
 Global Data Center Accelerator Market | 2026-2036
Global Data Center Accelerator Market Size, Share, and Industry Trends Forecast 2026-2036
Global Data Center Accelerator Market Foresight
The shift from CPU-centric to heterogeneous computing architectures is rewriting how data centers provision computational resources for AI workloads. NVIDIA Corporation dominates GPU-based training deployments through its CUDA software ecosystem and foundry partnerships. Intel Corporation competes in the accelerator segment with Gaudi processors and packaging innovations at its Arizona facilities. Advanced Micro Devices, Inc. positions its MI300 series as an alternative for inference and training workloads in enterprise data centers.
Data center accelerators are specialized co-processors designed to offload parallelizable computational tasks from general-purpose CPUs, typically manufactured on advanced nodes with high-bandwidth memory interfaces and interconnect fabrics exceeding 900 GB/s. These devices serve the primary commercial purpose of reducing time-to-result for machine learning model training, cryptographic operations, and media transcoding at scale. GPU-based accelerators anchor the largest revenue pool due to their maturity in training pipelines, while ASIC and TPU architectures represent the fastest-growing category as hyperscale operators pursue custom silicon for inference cost optimization. Machine learning applications absorb the dominant share of accelerator shipments, though network acceleration and encryption segments are expanding as zero-trust security mandates proliferate across cloud and edge deployments.
The US Department of Commerce's Bureau of Industry and Security export controls restrict advanced accelerator shipments to designated countries, compelling foundry investments in Singapore, Japan, and Ireland. The EU AI Act classifies certain high-risk AI training workloads under conformity assessment requirements that affect accelerator procurement specifications for European deployments. China's MIIT domestic substitution policies promote local ASIC and GPU development through GB standards compliance and state-backed semiconductor funds. Stakeholders must monitor how fragmentation in semiconductor equipment licensing reshapes the geographic distribution of advanced packaging capacity and foundry output.
Market Dynamics
Heterogeneous computing architectures are restructuring capital allocation across data center infrastructure as generative AI training workloads force rapid GPU and TPU procurement cycles. The shift from CPU-centric provisioning to accelerator-dense configurations is compressing equipment refresh timelines and reshaping supplier relationships.
Growth Catalysts
- Hyperscale AI Training Demand:Cloud operators are expanding accelerator deployments to support large language model development. This workload category now dominates procurement volumes for high-bandwidth memory devices.
- US Export Controls on Advanced Semiconductors:The Bureau of Industry and Security restrictions are accelerating foundry investments in Singapore, Japan, and Ireland as suppliers seek compliant manufacturing nodes.
- EU AI Act Conformity Requirements:High-risk AI training classifications under this framework are mandating documented accelerator specifications for European deployments, creating procurement standardization.
Market Restraints
- Advanced Node Supply Concentration:Leading-edge foundry capacity concentrates in Taiwan and South Korea, creating geographic vulnerability for accelerator manufacturing.
- High-Bandwidth Memory Input Costs:HBM3 and HBM3e supply tightness is elevating bill-of-materials pressure for GPU and ASIC vendors.
- Interconnect Bandwidth Limitations:Current 900 GB/s fabric standards constrain scaling efficiency for trillion-parameter model training across distributed accelerator clusters.
Strategic Opportunities
- Edge Inference Acceleration:Enterprise data centers in Germany and Japan are deploying lower-power ASICs for real-time inference, opening a channel distinct from hyperscale cloud procurement.
- Domestic Substitution in China:MIIT GB standards compliance programs are creating procurement preference for local GPU and ASIC designs through state-backed semiconductor funds.
- Optical Interconnect Convergence:Co-packaged optics with accelerator dies is enabling new system architectures that reduce power consumption for training workloads.
Industry Challenges
- Advanced Packaging Talent Scarcity:Chiplet-based accelerator designs require specialized 2.5D and 3D integration expertise that remains concentrated among a limited engineering pool.
- Multi-Vendor Software Stack Integration:CUDA ecosystem dominance creates friction for enterprises deploying AMD MI300 or Intel Gaudi alternatives alongside existing NVIDIA infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Data Center Accelerator Market |
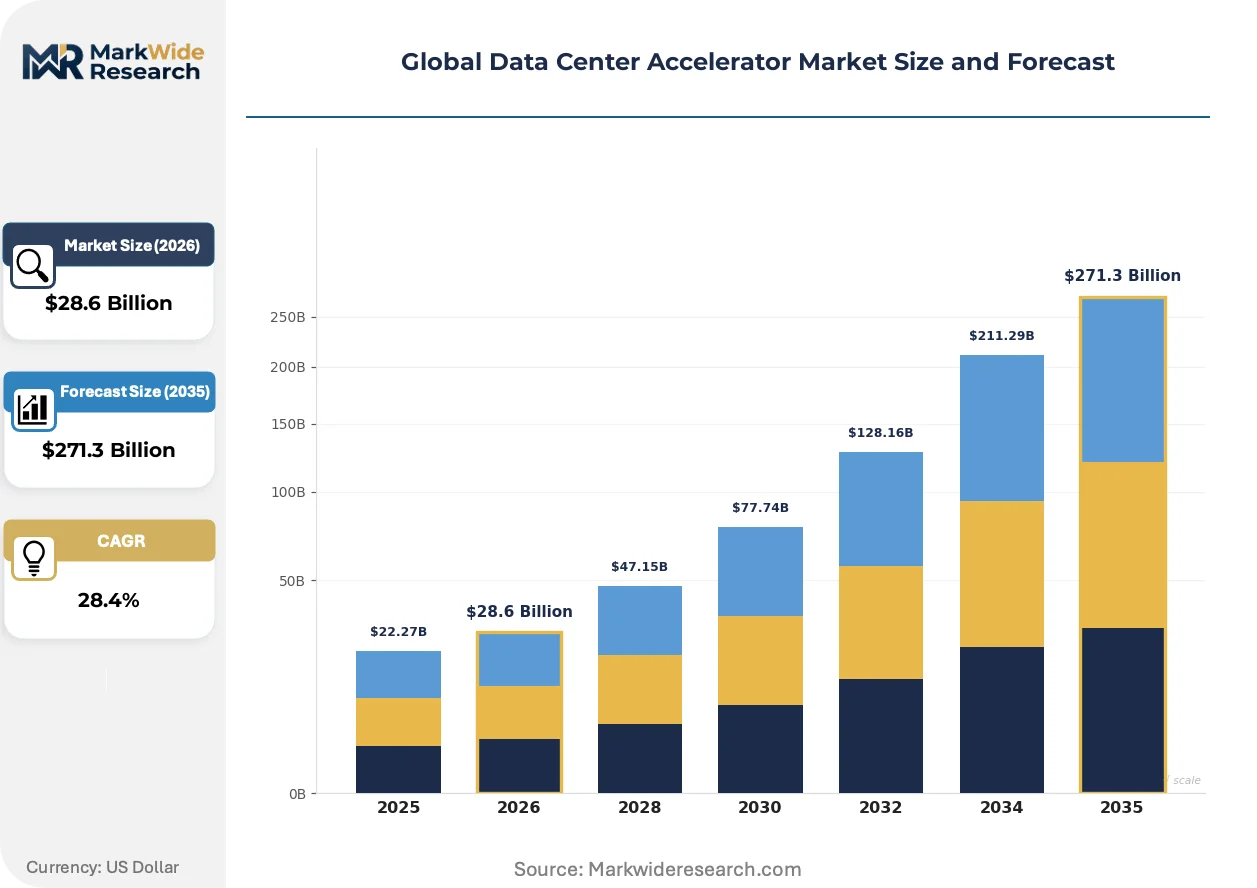
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $271.3 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: FPGA, ASIC, GPU, TPU, DPU Technology: Machine Learning, Encryption, Compression, Video Processing, Network Acceleration Application: Cloud Computing, High Performance Computing, Content Delivery, Data Analytics, Virtualization End User: Hyperscale Operators, Edge Computing Providers, Telecommunications, Financial Services, Research Institutions |
| Companies Covered | NVIDIA Corporation, Intel Corporation, Advanced Micro Devices, Inc., Alphabet, Inc., Amazon Web Services, Inc., IBM Corporation, Marvell Technology Inc., Qualcomm Incorporated, Dell Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Data Center Accelerator Market Shifts & Advancements
Computational virtualization is restructuring how data centers provision accelerator resources, with software-defined partitioning enabling shared access across multiple workloads. This architectural shift is compressing hardware utilization gaps and forcing vendor ecosystem adaptations.
Optical interconnect technology is virtualizing memory access patterns across distributed accelerator clusters. Hyperscale operators in the United States and China are deploying co-packaged photonics to extend effective bandwidth beyond electrical signaling limits. This approach is collapsing the physical constraints that previously governed training cluster scaling.
The EU AI Act's risk-based classification system is mandating conformity assessments for high-capacity training accelerators deployed in European facilities. Hardware vendors must now document thermal design power, interconnect specifications, and memory bandwidth to satisfy notified body requirements. German and French data center operators are adjusting procurement checklists to incorporate these technical disclosure obligations.
Consumption-based accelerator leasing is displacing capital purchase models among mid-sized enterprise data centers. Cloud-adjacent colocation providers in Singapore and Ireland are offering fractional GPU capacity with metered pricing. This pattern is most visible among financial services and pharmaceutical research organizations seeking training access without infrastructure ownership.
Global Data Center Accelerator Market Segmentation
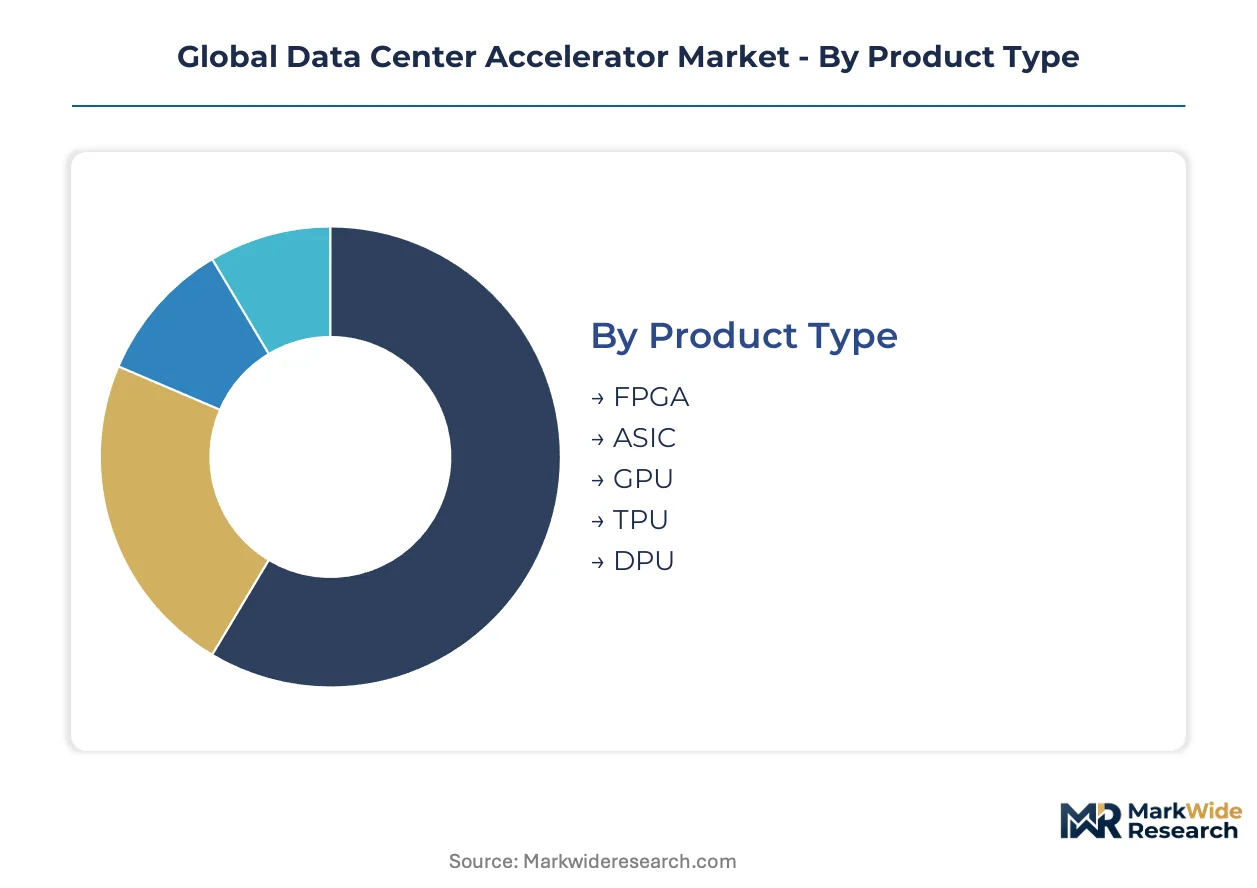
Accelerator segmentation reveals divergent procurement patterns across workload types and infrastructure scales. GPU-dense configurations dominate hyperscale training deployments, while FPGA and ASIC architectures carve distinct niches in latency-sensitive inference and specialized cryptographic operations.
Product Type:
GPU architectures anchor high-throughput training pipelines, while programmable logic devices address workload-specific optimization demands across the deployment spectrum.
- GPU:Parallel processing engines with high-bandwidth memory interfaces exceeding 900 GB/s dominate generative AI training clusters. Hyperscale operators in the United States and China are expanding procurement volumes for large language model development, constrained by HBM3 supply tightness and foundry capacity allocation.
- ASIC:Application-specific silicon delivers inference cost optimization through custom datapath designs. Edge computing providers in Germany and Japan are deploying lower-power variants for real-time inference, driven by EU AI Act conformity requirements and local energy efficiency mandates.
- FPGA:Reconfigurable logic arrays enable cryptographic acceleration and network function virtualization with field-updatable algorithms.
- TPU:Google-developed tensor processing units serve proprietary cloud training and inference workloads with matrix multiply-accumulate specialization.
- DPU:Data processing units offload networking, storage, and security virtualization from host CPUs in software-defined infrastructure.
Established volume favors GPU; emerging adoption favors ASIC.
Technology:
Workload-specific acceleration demands are fragmenting technology procurement across security, media, and analytics domains.
- Machine Learning:Training and inference acceleration absorbs the dominant share of high-bandwidth memory devices and advanced node wafer starts. Cloud operators are compressing refresh timelines to support trillion-parameter model development, with procurement concentrated in the United States and China.
- Network Acceleration:SmartNIC and DPU architectures virtualize data plane operations for zero-trust security mandates. Financial services organizations in Singapore and Ireland are deploying these for latency-sensitive trading infrastructure, compelled by SEC and Monetary Authority of Singapore disclosure requirements.
- Encryption:Hardware security modules and cryptographic accelerators address post-quantum cryptography transitions.
- Compression:Lossless and lossy codec acceleration reduces storage bandwidth for media archives and genomic datasets.
- Video Processing:Transcoding engines enable adaptive bitrate streaming at scale for content delivery networks.
Machine learning commands capital allocation; network acceleration is climbing the fastest.
Application:
Deployment context determines accelerator density, interconnect topology, and thermal design power specifications.
- Cloud Computing:Hyperscale facilities deploy accelerator-dense configurations with liquid cooling and optical interconnect fabrics. Operators are expanding capacity in Singapore and Ireland to navigate US export control restrictions on advanced semiconductor shipments.
- High Performance Computing:Government and academic research clusters integrate heterogeneous architectures for climate modeling and molecular simulation. Oak Ridge National Laboratory and Forschungszentrum Jülich are procuring mixed GPU-CPU systems for exascale transitions.
- Data Analytics:In-memory database acceleration reduces query latency for business intelligence platforms.
- Content Delivery:Edge-populated transcoding nodes optimize streaming quality across geographic distribution.
- Virtualization:Software-defined partitioning enables shared accelerator access across tenant workloads.
Cloud computing absorbs procurement volume; high performance computing shows steepest expansion trajectory.
End User:
Customer scale and regulatory exposure shape accelerator selection criteria and vendor engagement models.
- Hyperscale Operators:Amazon Web Services, Microsoft Azure, and Google Cloud Platform define accelerator roadmaps through custom silicon co-development and foundry partnerships. These operators are diversifying manufacturing geography to Singapore, Japan, and Ireland in response to Bureau of Industry and Security restrictions.
- Financial Services:Banks and trading venues deploy FPGA-based market data processing with deterministic latency guarantees. JPMorgan Chase and Deutsche Börse are expanding accelerator infrastructure for risk analytics and algorithmic execution, subject to SEC and BaFin operational resilience mandates.
- Edge Computing Providers:Distributed inference nodes serve manufacturing and retail computer vision applications.
- Telecommunications:5G core virtualization and RAN acceleration drive DPU and FPGA procurement.
- Research Institutions:National laboratories and universities access accelerator resources through cloud partnerships and dedicated allocations.
Hyperscale operators dictate technology roadmaps; financial services are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale cloud operators in the United States and China absorb the dominant share of accelerator procurement, while Germany and Singapore emerge as critical nodes for regulatory-compliant manufacturing and European AI infrastructure deployment.
United States
Amazon Web Services, Microsoft Azure, and Google Cloud Platform drive GPU and TPU procurement volumes for large language model training clusters. The Bureau of Industry and Security export controls restrict advanced accelerator shipments to designated countries, compelling domestic foundry partnerships and Arizona-based packaging investments. Northern Virginia and Dallas-Fort Worth data center corridors concentrate liquid-cooled accelerator deployments for trillion-parameter model development.
China
Domestic cloud operators and state-backed AI labs accelerate procurement despite import restrictions on advanced node devices. MIIT GB standards compliance programs promote local GPU and ASIC development through semiconductor industry funds. Beijing and Shanghai anchor design and verification activities, while Hefei and Wuhan foundry clusters expand mature-node accelerator production for inference workloads.
Germany
Forschungszentrum Jülich and industrial research consortia procure heterogeneous GPU-CPU systems for exascale computing transitions. The EU AI Act mandates conformity assessments for high-risk AI training accelerators, documented through notified body specifications. Bavaria and Baden-Württemberg concentrate data center construction for European sovereign AI infrastructure, with Frankfurt serving as the primary interconnection hub.
Singapore
Foundry investments from TSMC and GlobalFoundries establish advanced packaging capacity to navigate US export control restrictions. The Monetary Authority of Singapore and SEC-aligned disclosure requirements drive financial services accelerator deployment for latency-sensitive trading infrastructure. Tuas and Changi North data center zones attract cloud-adjacent colocation providers offering fractional GPU leasing to pharmaceutical and hedge fund clients.
Japan
METI semiconductor revitalization subsidies support domestic foundry investments in Kumamoto and Hokkaido for accelerator manufacturing. Kioxia and local memory vendors supply HBM components to reduce import dependency for GPU bill-of-materials. Tokyo and Osaka metro areas host edge inference deployments for manufacturing computer vision, driven by local energy efficiency mandates and real-time processing requirements.
Global Data Center Accelerator Market Competitive Landscape
Channel-controlling players compete with product-specialist players across accelerator procurement cycles, with hyperscale cloud operators and foundry partnerships determining technology roadmaps. The vendor base stratifies between CUDA-ecosystem incumbents, x86-heritage challengers, and custom silicon developers. Three archetypes dominate: GPU-dense training specialists, ASIC inference optimizers, and programmable logic generalists. Capacity expansion and strategic foundry partnerships constitute the primary competitive moves, with geographic manufacturing diversification accelerating in response to trade restrictions.
Within the GPU-dense training tier, NVIDIA Corporation anchors ecosystem control through software-hardware integration, while Intel Corporation and Advanced Micro Devices, Inc. occupy challenger positions with alternative accelerator architectures. These three US-based technology companies exemplify the competitive tension between incumbent platform dominance and heterogeneous computing alternatives, with each representing distinct approaches to high-bandwidth memory integration and interconnect scaling for distributed training clusters.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Intel Corporation |
| Advanced Micro Devices, Inc. |
| Alphabet, Inc. |
| Amazon Web Services, Inc. |
| IBM Corporation |
| Marvell Technology Inc. |
| Qualcomm Incorporated |
| Dell Inc. |
| Others |
Supply & Pricing Matrix
Single-source HBM3e dependency from SK Hynix and Samsung determines both accelerator pricing tier spreads and supply chain shape, compressing margins for GPU vendors while forcing hyperscale buyers into multi-year offtake commitments.
Pricing Analysis
Cost-plus contracts with quarterly indexation to DRAM spot markets dominate accelerator procurement between hyperscale operators and GPU vendors. Price differentiation rests on memory bandwidth tier and foundry node certification, with HBM3e-equipped SKUs commanding substantial premiums over HBM2e alternatives. Cost compression in mid-range inference accelerators is intensifying because Chinese ASIC vendors are undercutting NVIDIA A100-class pricing through domestic foundry partnerships. Financial services organizations exhibit highest price sensitivity due to SEC-mandated capital efficiency ratios, while sovereign AI labs in Germany and Saudi Arabia demonstrate lowest sensitivity given state-backed funding.
Supply Chain Analysis
TSMC, Samsung Foundry, and Intel Foundry Services hold captive capacity for advanced node accelerator manufacturing, with CoWoS packaging bottlenecked at TSMC's Taichung and Tainan facilities. Geographic supply concentration centers on Taiwan for leading-edge wafer fabrication, South Korea for HBM stack assembly, and the United States for Arizona-based advanced packaging investments. Raw material dependencies draw from neon gas suppliers in Ukraine and Russia, high-purity silicon from Hemlock Semiconductor, and photoresist from JSR and Tokyo Ohka Kogyo. Single-source vulnerability in CoWoS capacity creates acute supply chain risk for trillion-parameter training clusters. Distribution runs through direct OEM relationships with hyperscale operators, bypassing traditional channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across workload-specific acceleration architectures creates niche entry points, as the shift from general-purpose training to optimized inference workloads splinters procurement standards and opens vendor diversification.
For Market Incumbents: Harden software ecosystem lock-in through CUDA toolchain exclusivity and foundry partnership extensions into Singapore and Japan. Defensive moves must prioritize captive HBM supply agreements with SK Hynix and Samsung to neutralize memory shortage threats, alongside Arizona packaging capacity expansion to satisfy Bureau of Industry and Security compliance requirements for domestic manufacturing. For New Entrants and Emerging Players: Edge inference acceleration for manufacturing computer vision in Japan and Germany represents the most penetrable entry point, given METI energy efficiency mandates and EU AI Act conformity requirements that favor lower-power ASIC architectures over GPU density. Go-to-market positioning should emphasize software stack compatibility with existing Kubernetes orchestration layers to reduce enterprise integration friction. For Investors and Strategic Acquirers: The market sits at a technology transition phase that favors optical interconnect specialists and advanced packaging equipment vendors over pure-play silicon designers. Long-term viability across the next decade hinges on exposure to co-packaged photonics and chiplet integration capabilities. Acquisition targets should display foundry-agnostic design methodologies and existing partnerships with TSMC or Intel Foundry Services. The signal to watch is hyperscaler capex reallocation from training clusters to inference infrastructure as model deployment scales.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Partnership Expansion | TSMC and Intel Foundry Services commitments in Arizona and Japan secure compliant manufacturing nodes for export-controlled accelerators. |
| HBM Supply Captivation | Long-term offtake agreements with SK Hynix and Samsung neutralize memory bottleneck risks for GPU and ASIC bill-of-materials. |
| Optical Interconnect Integration | Co-packaged photonics with accelerator dies reduces power consumption for distributed training clusters beyond electrical signaling limits. |
| Software Ecosystem Hardening | CUDA toolchain exclusivity and container orchestration integration defend against AMD ROCm and Intel oneAPI competitive encroachment. |
| Edge Inference ASIC Development | Low-power tensor processing units for manufacturing computer vision address METI efficiency mandates and EU AI Act conformity requirements. |
Research Methodology
Operator-level perspectives from hyperscale cloud procurement officers, foundry capacity planners, semiconductor equipment vendors, and enterprise IT infrastructure directors anchored the qualitative base. Primary interviews combined with secondary validation from SEC 10-K filings, hyperscaler capex disclosures, Bureau of Industry and Security regulatory notices, and EU AI Act technical documentation. Bottom-up unit shipment estimates triangulated against top-down wafer start projections from TSMC, Samsung, and Intel Foundry Services.
Scenario-bracketing around foundry capacity constraints, export control enforcement intensity, and HBM supply tightness shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include accelerator architecture type, workload application, deployment scale tier, and regional regulatory cluster. CAGRs derived from unit economics analysis of GPU, ASIC, and FPGA bill-of-materials trajectories, with inputs from memory vendor pricing disclosures and advanced packaging yield curves.
Practitioners should monitor Bureau of Industry and Security license approval rates, CoWoS capacity expansion announcements, and hyperscaler training cluster deployment timelines for early signals of forecast revision. Quarterly review of foundry utilization rates, HBM spot pricing, and EU AI Act notified body certification volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Italy Data Center Rack Market
Data Center Infrastructure
Brazil Data Center Server Market
Data Center Infrastructure
Thailand Data Center Rack Market
Data Center Infrastructure
Malaysia Data Center Construction Market
Data Center Infrastructure
North America Data Center Infrastructure Management Market
Data Center Infrastructure
Data Center Blocks Market
Data Center Infrastructure
Australia Data Center Physical Security Market
Data Center Infrastructure
France Data Center Construction Market
Data Center Infrastructure
North America Data Center Server Market
Data Center Infrastructure
Israel Data Center Rack Market
Data Center Infrastructure
Ireland Data Center Rack Market
Data Center Infrastructure
China Data Center Power Market
Data Center Infrastructure
London Data Center Market
Data Center Infrastructure
Data Center Outsourcing and Infrastructure Utility Services Market
Data Center Infrastructure
Poland Data Center Construction Market
Data Center Infrastructure
Water Leak Detection System for Server Rooms and Data Centers Market