
 Global Data Center RFID Market | 2026-2036
Global Data Center RFID Market Size, Share, and Industry Trends Forecast 2026-2036
Global Data Center RFID Market Foresight
Asset-light leasing models for RFID infrastructure is rewriting competitive entry barriers for mid-sized data center operators. Zebra Technologies Corporation leverages its end-to-end printing and encoding portfolio to anchor enterprise deployments across North America and Europe. Impinj, Inc. sustains its position through RAIN RFID chip innovation that dominates high-volume item-level tracking. Honeywell International Inc. competes by integrating RFID with building automation systems for unified facility management.
Data center RFID encompasses radio frequency identification systems engineered for automatic identification and data capture within mission-critical IT environments, typically operating across UHF bands from 860 to 960 MHz to enable non-line-of-sight reading of server assets, cooling equipment, and network hardware. These systems serve the primary commercial purpose of eliminating manual inventory audits while providing real-time location visibility across distributed infrastructure footprints. Passive RFID tags hold mature volume leadership due to their minimal unit cost and battery-free operation, yet active RFID segments command superior margin pools where real-time environmental monitoring of temperature-sensitive server racks justifies higher expenditure. UHF RFID technology leads deployment scale among cloud service providers seeking rapid bulk-reading capabilities during mass server commissioning events.
The U.S. Federal Communications Commission governs spectrum allocation for RFID transmissions, while the EU REACH regulation imposes substance restrictions on tag adhesives and embedded electronics entering European data centers. India's BIS certification mandates electromagnetic compatibility testing for imported RFID hardware, creating compliance gates for foreign suppliers. Stakeholders must monitor evolving spectrum harmonization between the FCC and EU frameworks, as divergent UHF frequency bands complicate global rollout strategies for multinational operators.
Market Dynamics
Hyperscale cloud operators in the United States are compressing server commissioning cycles from months to weeks, forcing RFID infrastructure to scale from pilot deployments to enterprise-wide coverage without proportional cost escalation.
Growth Catalysts
- EU Ecodesign for Sustainable Products Regulation:Mandates automated asset tracking for circular economy compliance, pushing European operators toward RFID-enabled inventory systems for server lifecycle documentation.
- Server sprawl in hyperscale facilities:Amazon Web Services and Microsoft Azure campuses now track individual blade servers through commissioning to decommissioning, creating sustained hardware demand for UHF tag readers.
- India's data center construction acceleration:Mumbai, Hyderabad, and Chennai clusters are embedding RFID infrastructure into greenfield builds, treating asset visibility as foundational rather than retrofit.
Market Restraints
- Copper and silicon supply concentration:RAIN RFID chip fabrication depends on TSMC and Samsung foundries concentrated in Taiwan and South Korea, exposing tag supply to geopolitical friction.
- Metal interference in server racks:UHF signal attenuation from dense steel enclosures requires specialized tag antenna design, adding engineering cost per deployment.
- BIS electromagnetic compatibility certification:India's mandatory testing for imported RFID hardware creates 12-16 week entry delays for foreign suppliers targeting domestic data center builds.
Strategic Opportunities
- Environmental sensor convergence:Active RFID tags with integrated temperature and humidity monitoring capture premium pricing in liquid-cooled server deployments where thermal runaway risks dominate operator concern.
- Asset-light leasing models:Mid-sized colocation operators in Germany and France now subscribe to RFID infrastructure as operational expenditure, lowering competitive entry barriers.
- Indonesia and Vietnam data center pipelines:Southeast Asian markets with underpenetrated asset tracking present first-mover advantages for UHF reader vendors establishing local service partnerships.
Industry Challenges
- Legacy DCIM integration:Existing data center infrastructure management platforms from Schneider Electric and Nlyte Software use proprietary APIs, forcing RFID vendors to build custom middleware for each deployment.
- RAIN RFID protocol fragmentation:Competing chip implementations from Impinj, NXP Semiconductors, and Alien Technology create interoperability testing burdens for multi-vendor environments.
- RF engineer scarcity:Optimal antenna placement in multi-path metal environments requires specialized electromagnetic simulation expertise that system integrators struggle to staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Data Center RFID Market |
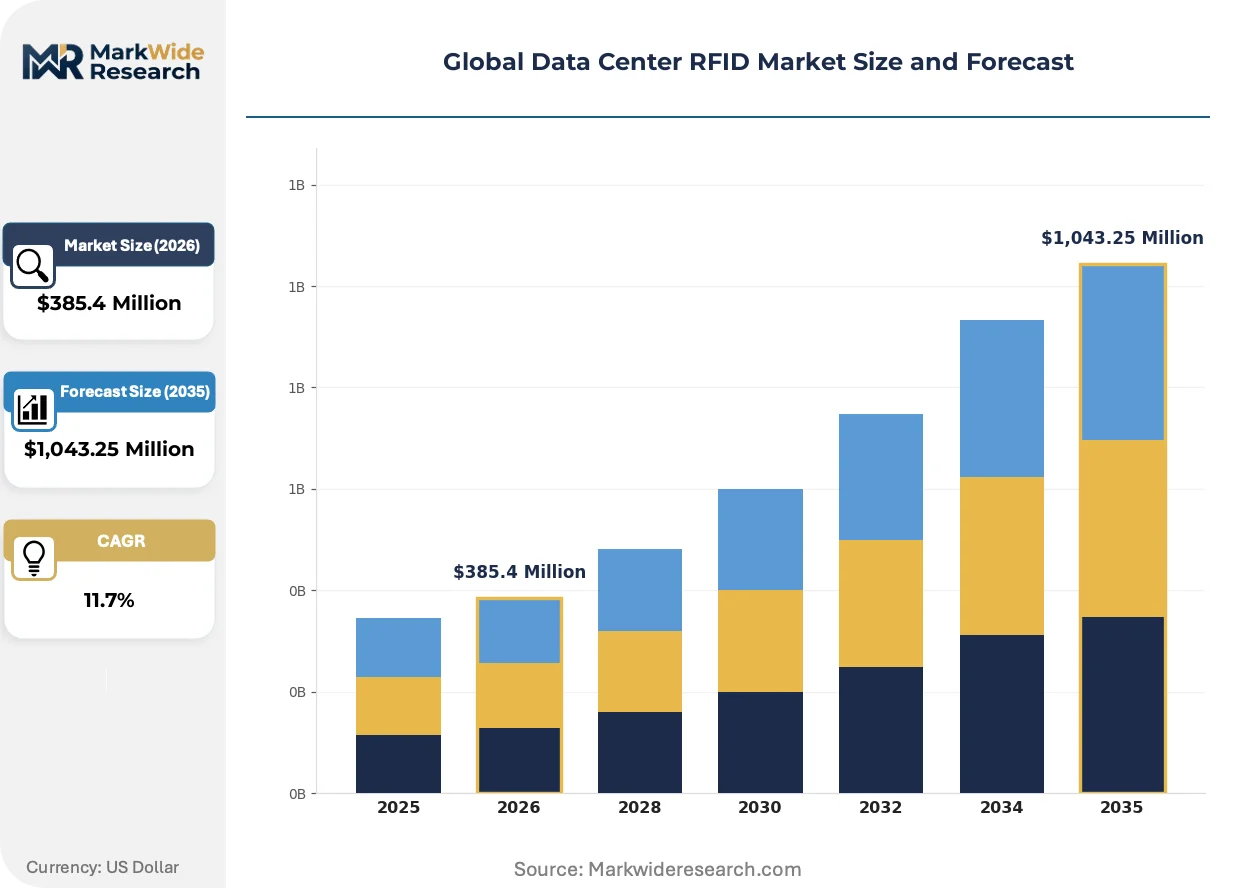
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,043.25 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Passive RFID, Active RFID, Semi-Passive RFID, NFC, UHF RFID Application: Asset Tracking, Access Control, Inventory Management, Environment Monitoring, Equipment Maintenance Deployment: On-Premises, Hybrid Cloud, Managed Services, Colocation Facilities, Virtualized Infrastructure End User: Cloud Service Providers, Telecommunication Companies, Data Storage Firms, Financial Institutions, Government Agencies |
| Companies Covered | Zebra Technologies Corporation, Impinj, Inc., Honeywell International Inc., Avery Dennison Corporation, Alien Technology, GAO Group, HID Global, NXP Semiconductors, Confidex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Data Center RFID Market Shifts & Advancements
Passive UHF RFID is migrating toward sensor-augmented architectures that transform tags from simple identifiers into distributed data collection nodes, compressing the boundary between asset tracking and environmental monitoring.
Sensor-integrated passive tags are migrating from identification-only functions to temperature and vibration sensing without battery power. Hyperscale operators in the United States are piloting these chips for thermal mapping of server intake zones. The technology is migrating from pilot validation to production deployment, compressing the need for separate wired sensor networks.
REACH substance restrictions on tag adhesives and embedded electronics are forcing European suppliers to reformulate antenna substrates and conductive inks. Industrial consequence includes accelerated qualification timelines for tag vendors seeking EU market access. German and Dutch data center operators are responding by pre-qualifying compliant tag suppliers before construction procurement.
Leasing models for RFID infrastructure are displacing capital purchase patterns among mid-sized colocation providers. Channel disruption favors managed service providers offering tag-as-a-service subscriptions over traditional hardware distributors. France and the United Kingdom exhibit the strongest contract velocity for this procurement shift, driven by private equity-backed data center rollups seeking operational expenditure treatment.
Global Data Center RFID Market Segmentation
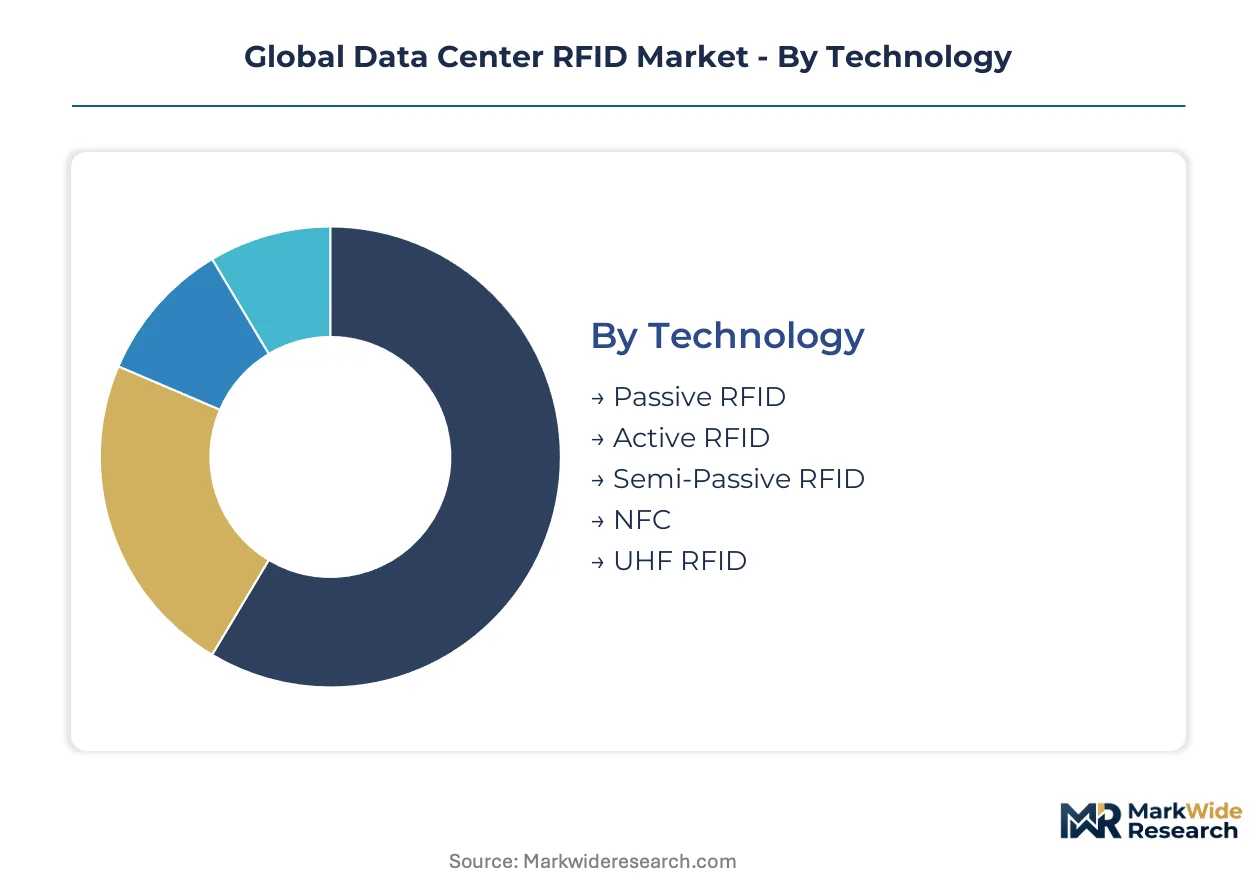
Segmentation in the data center RFID market reveals distinct procurement patterns across technology tiers and operational models. Cloud operators prioritize bulk-reading UHF systems while colocation providers favor hybrid deployment architectures. Understanding these splits enables vendors to align R&D investment with specific infrastructure upgrade cycles.
Technology:
Cost tier determines deployment scale and margin structure across RFID technology categories.
- Passive RFID:Battery-free tags operating via harvested RF energy dominate hyperscale server commissioning events where unit economics favor disposable identification. Amazon Web Services and Microsoft Azure campuses deploy millions annually for blade-level tracking across distributed footprints.
- Active RFID:Self-powered transmitters with integrated environmental sensors command premium positioning in liquid-cooled racks where thermal runaway monitoring justifies higher expenditure. Demand concentrates in Germany and the Netherlands where REACH-compliant tag substrates face mandatory pre-qualification.
- Semi-Passive RFID:Battery-assisted passive designs bridge cost-performance gaps for medium-density asset environments.
- NFC:Near-field protocols serve technician authentication and localized equipment configuration workflows.
- UHF RFID:Ultra-high frequency systems from 860-960 MHz anchor enterprise-wide coverage for rapid bulk-reading without line-of-sight constraints.
Passive RFID holds installed capacity. Active RFID is rotating up the share rankings.
Application:
Application focus shifts with facility maturity — greenfield builds embed tracking foundationally while retrofits prioritize high-ROI use cases.
- Asset Tracking:Real-time location systems for server, storage, and network hardware form the core commercial justification for RFID infrastructure in multi-tenant facilities. India's Mumbai and Hyderabad construction clusters treat this capability as foundational rather than retrofit.
- Environment Monitoring:Temperature, humidity, and vibration sensing tags capture expanding share in liquid-cooled deployments where thermal mapping replaces wired sensor networks. United States hyperscale operators pilot sensor-augmented passive chips for intake zone characterization.
- Access Control:Personnel and equipment authentication gates secure high-security zones within financial and government facilities.
- Inventory Management:Automated stock reconciliation eliminates manual audit labor across distributed spare parts depots.
- Equipment Maintenance:Lifecycle documentation links physical assets to service history for compliance and warranty management.
Asset Tracking commands current deployment share. Environment Monitoring is expanding most quickly as thermal density escalates.
Deployment:
Customer type and capital availability shape procurement model selection across deployment architectures.
- On-Premises:Fully owned infrastructure suits sovereign cloud operators and defense-adjacent facilities with data residency requirements. India's BIS certification mandates for imported hardware create 12-16 week procurement timelines that favor domestic system integrators.
- Managed Services:Subscription-based RFID infrastructure lowers entry barriers for mid-sized colocation operators in France and the United Kingdom seeking operational expenditure treatment. Private equity-backed data center rollups drive contract velocity for tag-as-a-service models.
- Hybrid Cloud:Mixed ownership structures balance control with flexibility for multi-cloud enterprises.
- Colocation Facilities:Multi-tenant environments demand tenant-isolated tracking domains with shared physical infrastructure.
- Virtualized Infrastructure:Software-defined overlays abstract physical asset location from logical resource allocation.
On-Premises retains legacy dominance. Managed Services is climbing the fastest as leasing models displace capital purchase patterns.
End User:
Volume concentration and procurement sophistication vary sharply across end user categories.
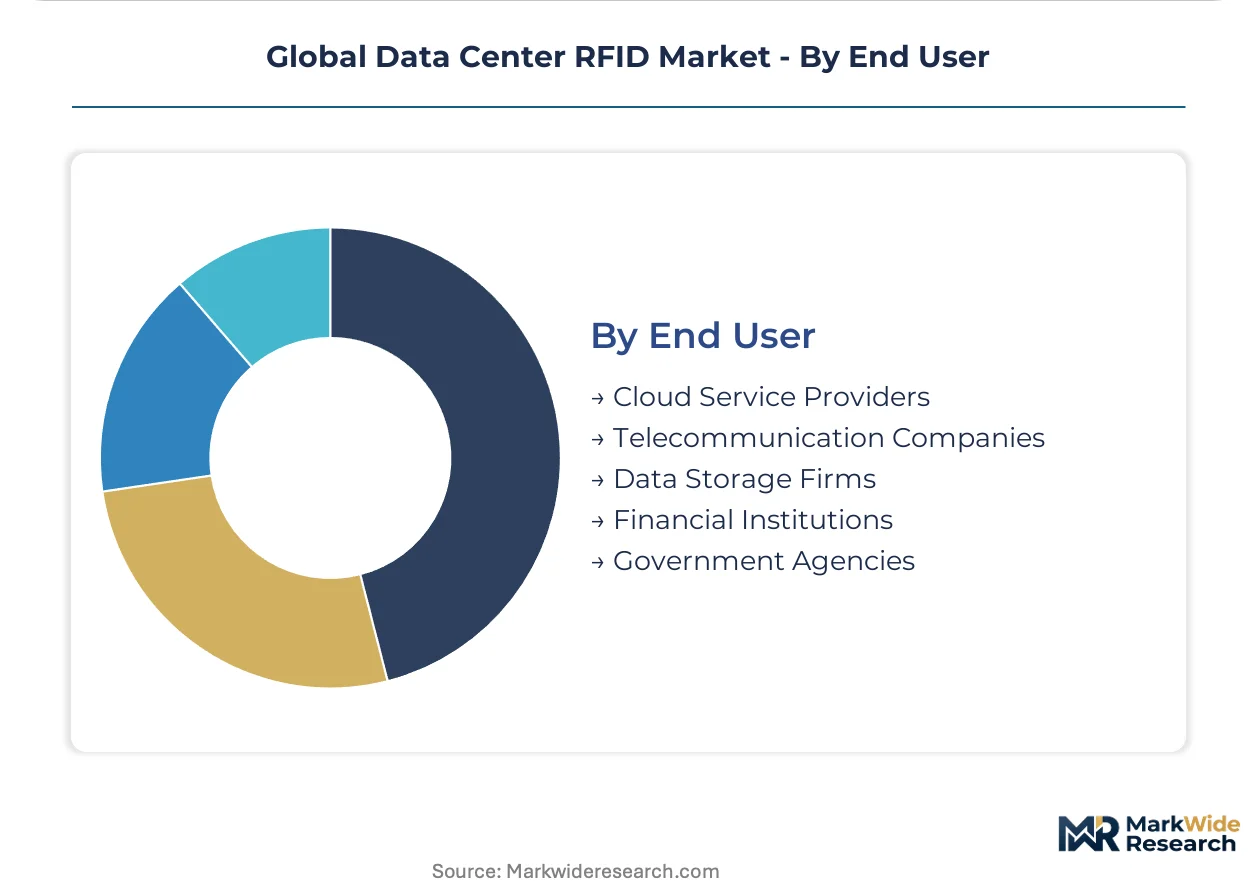
- Cloud Service Providers:Hyperscale operators compress server commissioning cycles from months to weeks, forcing RFID infrastructure to scale without proportional cost escalation. United States campuses now track individual blade servers from commissioning through decommissioning.
- Telecommunication Companies:Edge compute deployments and 5G infrastructure expansion drive distributed asset tracking requirements across cell tower and micro data center footprints.
- Data Storage Firms:Archive and cold storage operators prioritize inventory accuracy over real-time location for low-access media assets.
- Financial Institutions:Trading floor and core banking facilities demand sub-second location resolution for compliance and disaster recovery.
- Government Agencies:Classified and critical infrastructure deployments face additional supply chain security vetting for foreign-sourced tags.
Cloud Service Providers anchor current demand. Telecommunication Companies are gaining share fastest with edge infrastructure buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net RFID hardware trade flows from Taiwan and South Korea toward data center construction zones in the United States, Germany, and India. Import dependency for RAIN RFID chips creates supply vulnerability during geopolitical friction. Domestic system integrators in India and Southeast Asia capture value-add through BIS certification services and localized deployment support.
United States
Hyperscale cloud operators compress server commissioning cycles from months to weeks, forcing RFID infrastructure to scale without proportional cost escalation. The FCC governs spectrum allocation for UHF transmissions across 902-928 MHz bands. Northern Virginia and Dallas-Fort Worth data center clusters now track individual blade servers from commissioning through decommissioning.
Germany
REACH substance restrictions on tag adhesives and embedded electronics force European suppliers to reformulate antenna substrates and conductive inks. The EU Ecodesign for Sustainable Products Regulation mandates automated asset tracking for circular economy compliance. Frankfurt and Berlin data center operators pre-qualify compliant tag suppliers before construction procurement.
India
Mumbai, Hyderabad, and Chennai construction clusters embed RFID infrastructure into greenfield builds, treating asset visibility as foundational rather than retrofit. BIS certification mandates electromagnetic compatibility testing for imported RFID hardware, creating 12-16 week entry delays for foreign suppliers. Domestic system integrators capture deployment contracts through certification facilitation.
Netherlands
Liquid-cooled server deployments drive demand for active RFID tags with integrated temperature monitoring where thermal runaway risks dominate operator concern. The EU Green Deal accelerates automated inventory adoption for sustainability reporting. Amsterdam and Rotterdam data centers lead European deployment of sensor-augmented passive chips for intake zone thermal mapping.
Japan
Edge compute deployments and 5G infrastructure expansion drive distributed asset tracking requirements across micro data center footprints. METI standards govern electromagnetic compatibility for industrial RFID hardware. Tokyo and Osaka metropolitan areas prioritize inventory accuracy for disaster recovery compliance in financial and government facilities.
Global Data Center RFID Market Competitive Landscape
On the supply side, the industry is consolidating around integrated platform providers while fragmenting at the component tier. Tier-one vendors bundle hardware, software, and managed services into multi-year enterprise contracts. Tier-two specialists concentrate on RAIN RFID chip innovation and tag antenna engineering. Dominant competitive moves include strategic partnerships with data center infrastructure management platforms and geographic expansion through local system integrator networks.
Within the integrated platform tier, Zebra Technologies Corporation and Honeywell International Inc. represent end-to-end solution providers that anchor enterprise deployments across North America and Europe. Impinj, Inc. exemplifies the chip-specialist archetype, occupying a position defined by RAIN RFID innovation for high-volume item-level tracking. These three companies illustrate the market's bifurcation between breadth-oriented platform vendors and depth-focused component specialists.
| Leading Market Players |
|---|
| Zebra Technologies Corporation |
| Impinj, Inc. |
| Honeywell International Inc. |
| Avery Dennison Corporation |
| Alien Technology |
| GAO Group |
| HID Global |
| NXP Semiconductors |
| Confidex |
| Others |
Supply & Pricing Matrix
Overcapacity in RAIN RFID chip fabrication across Taiwan and South Korea is compressing tag margins while hyperscale buyers exploit volume leverage, creating divergent pricing postures between commodity passive tags and sensor-augmented active systems.
Pricing Analysis
Industrial OEM buyers anchor subscription-based SaaS pricing for managed RFID infrastructure, displacing capital purchase patterns among mid-sized colocation operators. Price differentiation stems from certification tier—BIS-compliant hardware for India versus standard CE-marked equipment for Europe—and volume scale with hyperscale cloud providers commanding steepest discounts. Cost compression in passive UHF tags is intensifying because TSMC and Samsung foundry overcapacity feeds component oversupply. Mid-sized colocation operators exhibit highest price sensitivity due to constrained IT budgets, while liquid-cooled hyperscale facilities show lowest sensitivity given thermal runaway risks.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for antenna substrate and conductive ink sourcing. RAIN RFID chip fabrication draws from Taiwan, South Korea, and China, with tag assembly concentrating in China and Vietnam. Copper antenna substrates, silicon wafers, and REACH-compliant adhesives constitute critical input dependencies. Single-source vulnerability around TSMC's advanced node capacity threatens supply continuity during geopolitical friction. Distribution runs through authorized system integrators in India and Germany who manage BIS and CE certification compliance before domestic deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The data center RFID market is cycling through a recovery phase as hyperscale capital expenditure rebounds from prior-year compression and greenfield construction accelerates across Mumbai, Hyderabad, and Chennai.
For Market Incumbents: Harden supply chain resilience by qualifying secondary foundry sources beyond TSMC and Samsung for RAIN RFID chip supply, insulating against Taiwan Strait disruption. Deepen backward integration into antenna substrate manufacturing to capture margin pools currently flowing to copper suppliers and hedge REACH substance restriction volatility. Prioritize certification pre-qualification workflows for India's BIS mandates to compress 12-16 week entry delays.
For New Entrants and Emerging Players: Pursue white-space opportunity in Indonesia and Vietnam data center pipelines where asset tracking penetration remains nascent and local service partnerships are unclaimed. Target mid-sized colocation operators in France and the United Kingdom seeking operational expenditure treatment through tag-as-a-service subscriptions. Lead with managed services positioning rather than hardware sales to bypass incumbent scale advantages in reader manufacturing.
For Investors and Strategic Acquirers: Capital is best deployed toward chip-specialist firms with proprietary RAIN RFID protocol implementations and established hyperscale customer relationships, as interoperability moats sustain pricing power. Long-term viability over a multi-year horizon rests on environmental sensor convergence capabilities that transform tags from identifiers into distributed data nodes. Monitor server commissioning cycle compression at AWS and Microsoft Azure campuses as the inflection signal—further acceleration validates RFID infrastructure as non-discretionary spend.
| Strategic Initiative | Industry Significance |
|---|---|
| Environmental Sensor Convergence | Active RFID tags with integrated temperature monitoring capture premium pricing in liquid-cooled server deployments. |
| Managed Services Transition | Subscription-based RFID infrastructure lowers entry barriers for mid-sized colocation operators in France and the United Kingdom. |
| Geographic Expansion Through Local Integrators | Domestic system integrators in India capture deployment contracts through BIS certification facilitation. |
| Backward Integration Into Antenna Substrates | In-house production of REACH-compliant antenna materials insulates against EU substance restriction volatility. |
| Strategic Partnership With DCIM Platforms | Integration with Schneider Electric and Nlyte Software reduces custom middleware burdens for enterprise deployments. |
Research Methodology
A spread of perspectives from data center infrastructure executives, RFID system integrators, procurement officers at hyperscale cloud operators, and regulatory compliance specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FCC spectrum allocation records, EU Ecodesign regulatory texts, India's BIS certification databases, and SEC filings from publicly traded RFID vendors. Bottom-up unit economics for tag deployments were triangulated against top-down market sizing from construction pipeline tracking across Mumbai, Hyderabad, Chennai, Northern Virginia, and Frankfurt.
Demand-supply balance modeling anchored the forecast framework, with segmentation across passive versus active RFID technology, asset tracking versus environment monitoring applications, on-premises versus managed services deployment models, and cloud service provider versus telecommunication company end users. CAGRs were derived from elasticity-adjusted adoption curves applied to verified greenfield construction timelines. Server commissioning cycle compression rates and REACH compliance cost trajectories served as industry-specific forecast inputs across the projection horizon.
Macroeconomic conditions sit as an overlay; deviation in hyperscale capital expenditure cycles, copper price volatility, or Taiwan Strait trade flows would shift the trajectory materially. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology substitution thresholds. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
China Data Center Rack Market
Data Center Infrastructure
Asia-Pacific Hyperscale Data Center Market
Data Center Infrastructure
IT Infrastructure Management Tools Market
Data Center Infrastructure
Poland Data Center Power Market
Data Center Infrastructure
Canada Data Center Construction Market
Data Center Infrastructure
Hong Kong Data Center Rack Market
Data Center Infrastructure
Ireland Data Center Physical Security Market
Data Center Infrastructure
Norway Data Center Power Market
Data Center Infrastructure
Airflow Management Equipment Market
Data Center Infrastructure
Mexico Data Center Power Market
Data Center Infrastructure
Italy Data Center Market
Data Center Infrastructure
Mini Data Center Market
Data Center Infrastructure
Middle East Data Center Rack Market
Data Center Infrastructure
Malaysia Data Center Networking Market
Data Center Infrastructure
Beijing Data Center Market
Data Center Infrastructure
Switzerland Data Center Server Market