
 Europe Managed Infrastructure Services Market | 2026-2036
Europe Managed Infrastructure Services Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Managed Infrastructure Services Market Foresight
The EU Green Deal is consolidating demand for energy-efficient data center operations across European enterprises. Accenture leverages its consulting-led infrastructure model to embed carbon reporting into client IT estates. IBM sustains a dominant position in mainframe and hybrid cloud managed services through decades of European banking relationships. Capgemini competes aggressively on price-to-performance in public sector infrastructure outsourcing across France and Benelux.
Europe Managed Infrastructure Services encompass the ongoing administration, optimization, and security of enterprise IT infrastructure—including servers, networks, storage, and cloud resources—delivered under multi-year contractual arrangements with defined service level agreements specifying uptime thresholds of 99.9% or higher. These services primarily reduce capital expenditure burdens while ensuring operational continuity for organizations lacking internal scale. Cloud Management services command the largest revenue share as enterprises accelerate workload migration, while Security Services represent the fastest-expanding margin pool amid escalating cyber insurance requirements. Hybrid deployment models dominate new contract value as regulated industries seek to retain sensitive data on-premises while bursting non-critical workloads to public cloud environments.
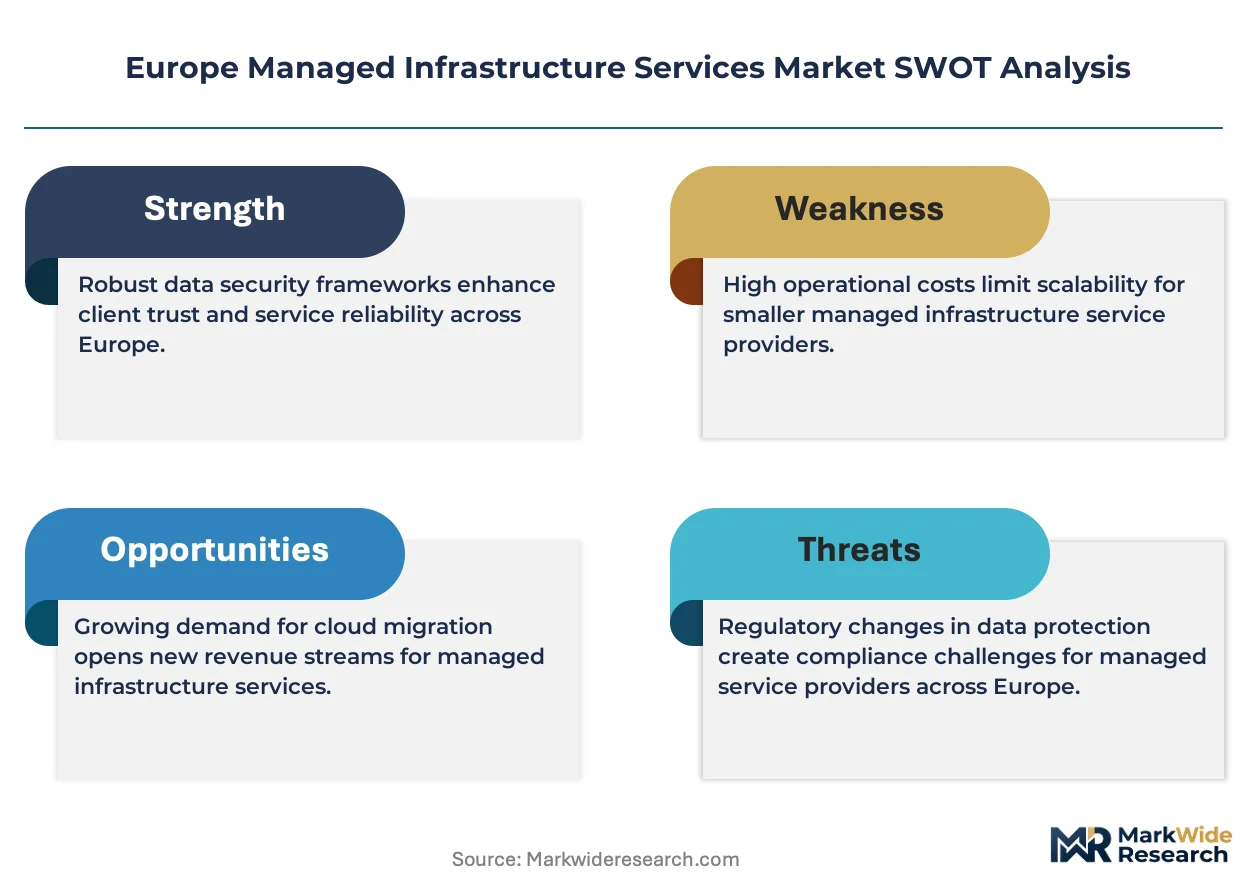
GDPR enforcement by national data protection authorities and the EU AI Act's risk-classification framework are reshaping vendor qualification criteria for infrastructure contracts involving automated decision-making systems. REACH and RoHS compliance obligations extend to hardware refresh cycles within managed data center engagements, compelling service providers to document supply chain chemical transparency. EMA guidelines on validated IT infrastructure for pharmaceutical manufacturing further segment the addressable market by certification intensity. Stakeholders must weigh the trade-off between standardization economies and vertical-specific compliance premiums when structuring service delivery models.
Market Dynamics
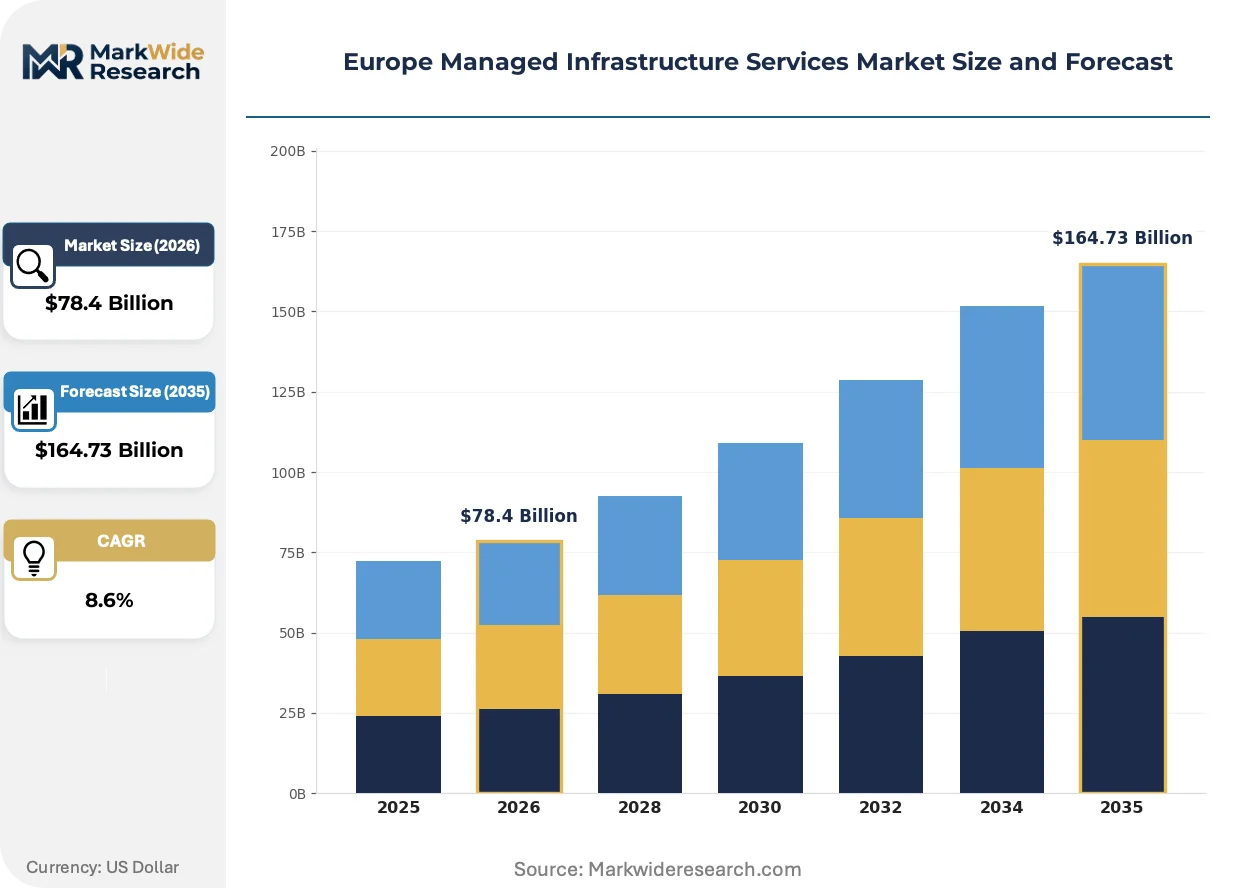
The EU Green Deal's digital sustainability mandates are compressing infrastructure refresh cycles across European enterprises, forcing service providers to reengineer data center operations around carbon transparency and energy efficiency metrics.
Growth Catalysts
- GDPR data residency requirements:Financial institutions in Germany and France must maintain sovereign data controls, driving demand for hybrid cloud managed services with localized infrastructure.
- EU AI Act risk classification:Automated infrastructure monitoring systems in healthcare and banking now require validated compliance frameworks, expanding specialized managed service contracts.
- Pharmaceutical manufacturing expansion:EMA guidelines on validated IT infrastructure are compelling drug makers to outsource GxP-compliant data center operations to certified providers.
Market Restraints
- Energy cost volatility:Electricity price spikes in Germany and the Netherlands are squeezing data center margins and forcing contract renegotiations with power purchase agreement exposure.
- Critical hardware concentration:Server and networking equipment supply chains concentrate in East Asian manufacturing clusters, creating delivery timeline vulnerability for European infrastructure rollouts.
- Legacy system technical debt:Decades-old mainframe estates in UK and Italian banking resist cloud-native migration, trapping capital in maintenance-heavy environments.
Strategic Opportunities
- Benelux public sector modernization:Belgian and Dutch government agencies are consolidating fragmented IT estates, creating large-scale infrastructure outsourcing tenders with decade-long terms.
- Carbon reporting as a service:CSRD disclosure requirements are enabling new revenue streams where providers embed Scope 3 emissions tracking into standard managed infrastructure contracts.
- Edge-to-cloud orchestration:Manufacturing and logistics firms are converging industrial IoT edge processing with centralized cloud analytics, requiring unified management platforms.
Industry Challenges
- Certified talent scarcity:Shortages of ITIL and ISO 27001 credentialed engineers in Poland and Romania are inflating wage costs for nearshore delivery centers.
- Multi-cloud integration complexity:Enterprises operating across AWS, Azure, and Google Cloud environments face operational fragmentation that managed service providers struggle to unify under single SLAs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Managed Infrastructure Services Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $164.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cloud Management, Network Management, Data Center Management, Security Services Deployment Model: On-Premises, Hybrid, Public Cloud, Private Cloud End User: SMEs, Large Enterprises, Government, Non-Profit Organizations Technology: Virtualization, Automation, AI-Driven Solutions, IoT Integration |
| Companies Covered | IBM, Accenture, Capgemini, Atos, Fujitsu, Dell Technologies, Hewlett Packard Enterprise, Bechtle AG, DXC Technology, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Managed Infrastructure Services Market Shifts & Advancements
Carbon-aware workload scheduling and AI-driven infrastructure automation are rewriting how European enterprises consume and pay for managed services. These shifts are compressing traditional procurement cycles and elevating sustainability metrics to contract-critical status.
Immersive liquid cooling systems are rewriting thermal management economics for high-density computing estates. Hyperscale data center operators in Frankfurt and Amsterdam are adopting these systems to support AI training clusters while containing energy consumption. The technology is rewriting facility design standards and enabling providers to meet PUE commitments under stricter EU energy efficiency directives.
REACH and RoHS compliance obligations now extend to hardware refresh cycles within managed engagements, compelling providers to document supply chain chemical transparency for every server and storage array deployed. ECHA enforcement actions against non-compliant electronics imports are tightening vendor qualification criteria. Pharmaceutical and medical device manufacturers face the steepest compliance premiums as EMA guidelines mandate validated infrastructure with full material traceability.
Enterprise buyers are unbundling infrastructure management from application support, creating discrete procurement categories with separate RFP processes. Large German automotive and industrial conglomerates now source managed infrastructure through centralized procurement functions while retaining application management with line-of-business IT teams. This pattern is most pronounced in the DACH region where procurement functions have professionalized technology category management.
Europe Managed Infrastructure Services Market Segmentation
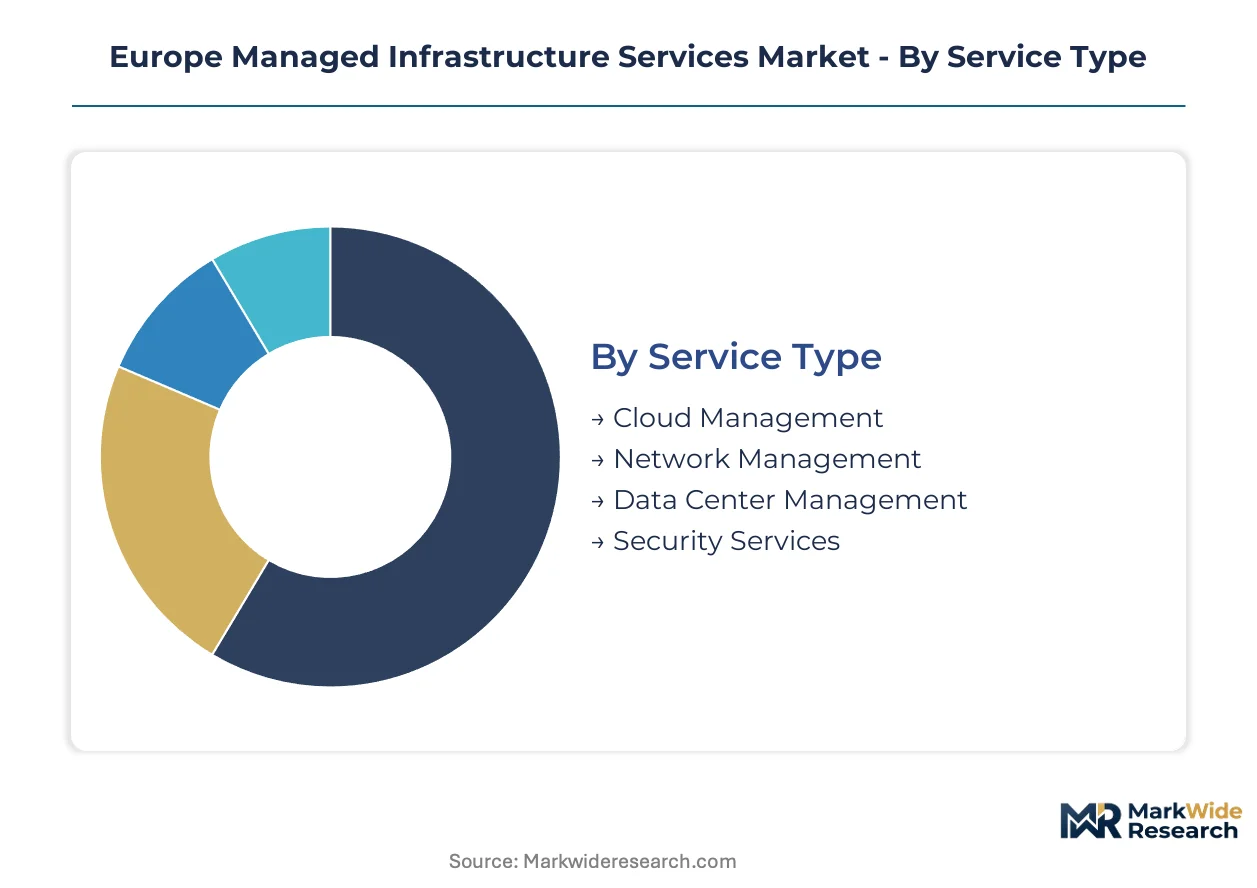
European enterprises structure managed infrastructure procurement around workload sensitivity, compliance exposure, and refresh cycle timing. Segmentation reveals how hybrid architectures and vertical-specific mandates reshape service packaging across the region.
Service Type:
Infrastructure refresh cycles in European banking and pharmaceutical sectors are compressing as energy efficiency mandates and GxP validation requirements force earlier hardware replacements.
- Cloud Management:Orchestrates multi-tenant workloads across AWS, Azure, and Google Cloud environments with automated provisioning and cost optimization. German automotive manufacturers and French insurers concentrate demand here as they burst non-critical analytics to public cloud while retaining sovereign controls.
- Security Services:Delivers managed detection and response, identity governance, and compliance monitoring under unified SLAs. Healthcare providers in the Netherlands and UK financial services firms drive expansion amid escalating cyber insurance requirements and GDPR breach notification pressures.
- Network Management:Administers SD-WAN, SASE, and core routing infrastructure with guaranteed latency thresholds. Manufacturing clusters in northern Italy and the Ruhr Valley source these services to support industrial IoT deployments.
- Data Center Management:Covers facility operations, hardware lifecycle management, and energy efficiency compliance for captive and colocation estates. EMA-validated contracts for pharmaceutical manufacturing command premium pricing due to material traceability documentation requirements.
Cloud Management sits at the top of the volume ranking, with Security Services climbing the fastest.
Deployment Model:
Cost tier differentiation separates sovereign-controlled deployments from commodity cloud consumption, with hybrid architectures capturing the margin premium.
- Hybrid:Combines on-premises infrastructure for sensitive data with public cloud bursting for variable workloads. Regulated industries across Germany, France, and Switzerland default to this model to satisfy GDPR data residency while gaining elasticity.
- On-Premises:Retains complete infrastructure control within client facilities or dedicated colocation. UK banking mainframe estates and Italian government data centers persist here due to legacy system interdependencies and national security classifications.
- Private Cloud:Delivers single-tenant cloud infrastructure with dedicated resource pools. Belgian and Dutch public sector agencies prefer this model for citizen data processing with defined jurisdictional boundaries.
- Public Cloud:Consumes shared infrastructure from hyperscale providers with standardized management overlays. Scandinavian startups and digital-native SMEs leverage this tier for speed-to-market without capital deployment.
Hybrid deployments command the steepest expansion trajectory as compliance complexity increases, while On-Premises contracts face gradual compression.
End User:
Customer type determines contract scale, with procurement centralization in large conglomerates creating discrete RFP categories separate from line-of-business application spending.
- Large Enterprises:Centralized procurement functions in DACH-region automotive and industrial conglomerates source multi-year infrastructure contracts with carbon reporting embedded. These engagements span thousands of servers across multiple countries with unified SLAs.
- Government:Benelux public sector modernization programs are consolidating fragmented IT estates into decade-long outsourcing tenders with strict EU public procurement directives. National security classifications limit vendor pools for defense and intelligence applications.
- SMEs:Mid-market manufacturers and professional services firms purchase standardized managed infrastructure packages through channel partners. Polish and Romanian nearshore delivery centers support these accounts with cost-optimized service tiers.
- Non-Profit Organizations:Research institutions and charitable foundations access subsidized or grant-funded infrastructure services with simplified compliance requirements. University computing clusters in the UK and Germany represent concentrated demand pockets.
Large Enterprises anchor contract value, with Government segments gaining share fastest through consolidation mandates.
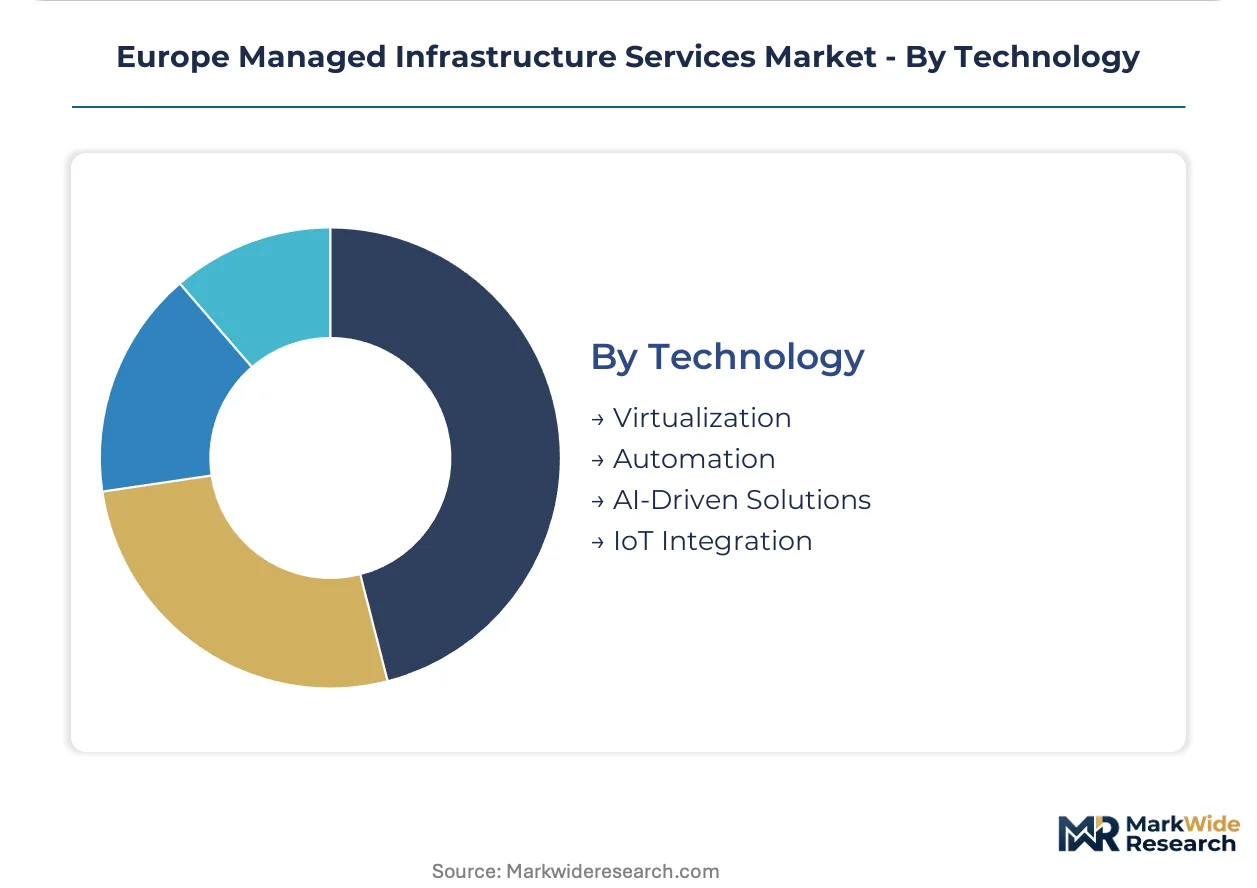
Technology:
Application maturity separates established virtualization stacks from emerging AI-driven automation, with integration complexity rising as technology layers accumulate.
- AI-Driven Solutions:Deploys machine learning for predictive capacity planning, anomaly detection, and autonomous remediation. Frankfurt and Amsterdam hyperscale data centers adopt these capabilities to optimize energy consumption under EU efficiency directives.
- Automation:Implements infrastructure-as-code, policy-driven orchestration, and self-healing workflows. Financial services institutions in London and Paris accelerate deployment velocity while reducing manual change errors.
- Virtualization:Abstracts compute, storage, and networking resources through VMware, Hyper-V, or KVM hypervisors. Established enterprise workloads across southern Europe continue relying on this foundation despite cloud migration pressures.
- IoT Integration:Connects industrial sensors, edge gateways, and centralized analytics platforms with unified management. Logistics hubs in Rotterdam and manufacturing plants in Bavaria drive demand for converged edge-to-cloud orchestration.
Virtualization retains the largest installed base, with AI-Driven Solutions expanding most quickly as energy cost pressures intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified infrastructure engineers concentrate in Poland and Romania, anchoring nearshore delivery capacity for Western European clients. Germany, France, and the United Kingdom concentrate the bulk of regional demand as enterprises migrate legacy systems to hybrid cloud architectures.
Germany
Automotive manufacturers and industrial conglomerates in the DACH region source multi-year infrastructure contracts with embedded carbon reporting. The EU Green Deal's digital sustainability mandates compress refresh cycles for energy-efficient data center operations. Frankfurt hyperscale clusters adopt immersive liquid cooling to support AI training workloads while meeting PUE commitments.
France
Public sector agencies consolidate fragmented IT estates into decade-long outsourcing tenders under strict EU public procurement directives. The CNIL enforces GDPR data residency requirements that compel financial institutions to maintain sovereign data controls. Paris-based banking relationships sustain demand for mainframe and hybrid cloud managed services.
United Kingdom
Financial services firms drive expansion in managed detection and response amid escalating cyber insurance requirements. Decades-old mainframe estates resist cloud-native migration, trapping capital in maintenance-heavy environments. London accelerates deployment velocity through infrastructure-as-code implementations while reducing manual change errors.
Netherlands
Electricity price spikes squeeze data center margins and force contract renegotiations with power purchase agreement exposure. The Dutch government consolidates citizen data processing through private cloud deployments with defined jurisdictional boundaries. Rotterdam logistics hubs demand converged edge-to-cloud orchestration for industrial IoT deployments.
Belgium
Benelux public sector modernization programs create large-scale infrastructure outsourcing opportunities with strict compliance frameworks. Belgian agencies prefer single-tenant cloud infrastructure for processing sensitive citizen data. Brussels-based institutions navigate REACH and RoHS compliance obligations extending to hardware refresh cycles with full material traceability.
Europe Managed Infrastructure Services Market Competitive Landscape
Capital-heavy producers compete with asset-light designers for infrastructure management contracts across European enterprises. The vendor base stratifies across three tiers: global systems integrators with consulting-led delivery models, hardware-centric providers leveraging captive equipment relationships, and regional specialists competing on price-to-performance in public sector tenders. Dominant competitive moves include carbon reporting service bundling and multi-cloud orchestration capability acquisition.
Within the global systems integrator tier, Accenture and Capgemini exemplify contrasting approaches to European market penetration. IBM anchors the hardware-heritage segment through decades of European banking relationships. These three entities represent the primary competitive archetypes shaping procurement outcomes across Germany, France, and the United Kingdom.
| Leading Market Players |
|---|
| IBM |
| Accenture |
| Capgemini |
| Atos |
| Fujitsu |
| Dell Technologies |
| Hewlett Packard Enterprise |
| Bechtle AG |
| DXC Technology |
| Others |
Supply & Pricing Matrix
Certified ITIL and ISO 27001 engineers concentrated in Poland and Romania create labor-cost differentials that widen pricing-tier spreads between premium EMA-validated contracts and standardized nearshore delivery packages. Energy price volatility in Germany and the Netherlands further compresses margins for data center operators, forcing providers to embed carbon reporting premiums into sovereign-controlled deployments while economy tiers absorb cost pressure through automation.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates European managed infrastructure procurement, with EMA-validated pharmaceutical contracts commanding certification premiums and nearshore Polish delivery centers competing on cost-optimized automation tiers. Price differentiation hinges on compliance grade and geographic delivery cost, with GDPR-sovereign deployments in Germany and France resisting downward pressure while commodity cloud management faces compression from hyperscale competition. Healthcare providers in the Netherlands exhibit acute price sensitivity amid cyber insurance inflation, whereas DACH-region automotive conglomerates prioritize carbon transparency over unit cost.
Supply Chain Analysis
Regional distribution centers in Frankfurt, Amsterdam, and London anchor hub-and-spoke patterns for critical server and networking hardware, with inventory buffers managed through power purchase agreement exposure clauses in Dutch and German contracts. Manufacturing concentration in Taiwan, South Korea, and China for semiconductor components and networking equipment creates single-source vulnerability for European infrastructure rollouts, while copper and rare earth dependencies for liquid cooling systems and high-density storage arrays compound material risk. Distribution runs through certified value-added resellers in the DACH region and direct hyperscale partnerships for public cloud bursting tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in European managed infrastructure services rests on carbon reporting service bundling and AI-driven automation compressing delivery costs for standardized workloads.
For Market Incumbents: Hedge against hyperscale encroachment by deepening captive mainframe relationships in UK banking and acquiring multi-cloud orchestration capabilities to unify fragmented AWS-Azure-Google Cloud environments. Defensive consolidation around EMA-validated pharmaceutical contracts and CSRD-compliant carbon reporting services protects premium positioning as compliance complexity intensifies. For New Entrants and Emerging Players: The mid-market price-point gap between premium sovereign-controlled deployments and economy-tier nearshore automation presents white-space opportunity in Benelux public sector modernization and Scandinavian SME cloud migration. Target Polish and Romanian certified talent pools for cost-optimized delivery, positioning through channel partnerships with hardware-centric providers lacking consulting-led transformation capabilities. For Investors and Strategic Acquirers: Hyperscale cloud providers are the most active acquirer in this space, seeking managed services capabilities to bridge enterprise hybrid adoption gaps. Long-term viability favors targets with validated healthcare or pharmaceutical infrastructure credentials and established carbon measurement toolkits. Watch for EU AI Act enforcement triggering specialized compliance service premiums as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Reporting Service Bundling | CSRD disclosure requirements enable new revenue streams embedding Scope 3 tracking into standard contracts. |
| Multi-Cloud Orchestration Acquisition | Unified management platforms resolve operational fragmentation across AWS, Azure, and Google Cloud environments. |
| EMA-Validated Infrastructure Certification | Pharmaceutical manufacturing expansion compels GxP-compliant data center outsourcing to certified providers. |
| Immersive Liquid Cooling Deployment | Frankfurt and Amsterdam hyperscale clusters adopt thermal management to meet PUE commitments under EU directives. |
| Nearshore Delivery Center Expansion | Polish and Romanian ITIL-credentialed engineer pools support cost-optimized service tiers for mid-market accounts. |
Research Methodology
Coverage spans Western Europe, Central Europe, and the Nordics, with primary inputs from each region combining structured interviews with CTOs, IT procurement officers, data center operations directors, and channel partners with secondary validation. Regulatory filings from EMA and ECHA, hyperscaler capex disclosures, EU public procurement databases, and national data protection authority enforcement records anchored source triangulation. Bottom-up contract value analysis across service type, deployment model, and end-user segments converged with top-down market sizing through industry association data.
Rate-of-change decomposition across the analysis window isolated volume drivers from price-mix effects, with segmentation modeling spanning service type, deployment architecture, organization size, vertical compliance intensity, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating infrastructure refresh cycle compression, energy cost trajectory assumptions, and certified talent supply elasticity. Forecast inputs included EU Green Deal implementation pacing and pharmaceutical manufacturing capacity expansion timelines.
Caveats apply where energy price volatility, hardware supply chain disruption, or regulatory enforcement intensity could materially shift the outlook. Forecasts reflect documented assumptions around cloud migration velocity and nearshore labor cost inflation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Enterprise Social Networks Market
Enterprise Services
Enterprise Portal Market
Enterprise Services
Europe Managed Services Market
Enterprise Services
Contingent Staffing Solutions Market
Enterprise Services
North America Managed Services Market
Enterprise Services
Shared Services Market
Enterprise Services
South-East Asia Consulting Services Market
Enterprise Services
Helpdesk Management Market
Enterprise Services
HR Tech Consulting Market
Enterprise Services
Mobile Enterprise Application Market
Enterprise Services
Asia-Pacific Contingent Workforce Management Market
Enterprise Services
United States Customer Technical Support Services Market
Enterprise Services
Digital Talent Acquisition Market
Enterprise Services
Enterprise Service Bus Software Market
Enterprise Services
United States Managed Services Market
Enterprise Services
Global Enterprise Content Collaboration Market