
 Global Cloud Computing Data Center IT Asset Disposition (ITAD) Market | 2026-2036
Global Cloud Computing Data Center IT Asset Disposition (ITAD) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cloud Computing Data Center IT Asset Disposition (ITAD) Market Foresight
The EU WEEE Directive is shifting compliance burdens upstream, forcing ITAD providers to certify full material traceability before processing retired cloud infrastructure. Iron Mountain leverages its archive-security heritage to dominate enterprise data-destruction contracts. Hewlett Packard Enterprise anchors its ITAD services through captive reverse-logistics networks tied to original server sales. Sims Lifecycle Services specializes in component harvesting from hyperscale decommissions, extracting value from semiconductors and rare-earth magnets before smelting.
Cloud computing data center IT asset disposition encompasses the secure decommissioning, data sanitization, refurbishment, and material recovery of retired server systems, storage systems, networking equipment, power supplies, cooling systems, and racks and enclosures, employing NIST 800-88 purge protocols and R2 or e-Stewards certification standards to eliminate residual data and redirect recoverable components into secondary markets. By service type, data destruction and secure recycling command premium pricing due to liability exposure, while refresh and remarketing competes on volume throughput and resale-channel depth. By asset type, server systems and storage systems generate the highest per-unit recovery values as hyperscale operators retire generations of NVMe-based and traditional spinning-disk infrastructure.
The EPA regulates hazardous-waste classifications for lithium battery and coolant recovery, while the EU REACH and RoHS frameworks restrict substance reuse in refurbished electronics circulating across member states. Japan's METI enforces strict domestic recycling quotas that limit cross-border material flows. Stakeholders must monitor evolving extended-producer-responsibility mandates that could obligate cloud service providers to contract only certified ITAD vendors with auditable chain-of-custody documentation.
Market Dynamics
Server refresh cycles at hyperscale facilities are compressing below 36 months, forcing cloud operators to decommission NVMe-based infrastructure before full depreciation and flooding secondary markets with recoverable semiconductors.
Growth Catalysts
- EU WEEE Directive chain-of-custody mandates:Extended producer responsibility rules now obligate cloud providers to document material flows from rack removal through final smelting, creating contracted demand for certified ITAD vendors.
- Hyperscale decommissioning volume:Amazon Web Services, Microsoft Azure, and Google Cloud are simultaneously retiring first-generation NVMe storage arrays and Skylake-era compute nodes.
- Rare-earth magnet recovery:Neodymium and dysprosium harvesting from retired server fans and hard drive actuators is electrifying component-level remarketing economics.
Market Restraints
- EPA hazardous-waste classification uncertainty:Lithium battery and coolant handling regulations vary by state, fragmenting processing economics for cross-border ITAD operators.
- Japan METI domestic recycling quotas:Strict material-flow restrictions prevent Japanese cloud operators from exporting retired assets to lower-cost Southeast Asian recovery facilities.
- Data sanitization labor intensity:NIST 800-88 purge protocol execution requires skilled technicians, creating throughput bottlenecks during hyperscale decommissioning surges.
Strategic Opportunities
- India's cloud infrastructure buildout:Domestic data center construction is accelerating, creating demand for ITAD services as legacy enterprise servers migrate to colocation facilities in Mumbai and Hyderabad.
- Blockchain-based chain-of-custody verification:Immutable asset-tracking ledgers are electrifying compliance documentation for EU WEEE and emerging US state e-waste laws.
- Component harvesting specialization:DRAM module testing and GPU refurbishment for secondary AI inference markets commands premium recovery values.
Industry Challenges
- R2 and e-Stewards certification timeline:Audit backlogs at accredited bodies delay vendor qualification for enterprise and hyperscale contracts by 8-14 months.
- Legacy spinning-disk data destruction:Degaussing equipment for HDD sanitization requires capital-intensive upgrades to handle helium-filled drives with glass substrates.
- Cross-border logistics coordination:Retired assets from German cloud facilities face complex Basel Convention documentation when routed to non-OECD recovery partners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cloud Computing Data Center IT Asset Disposition (ITAD) Market |
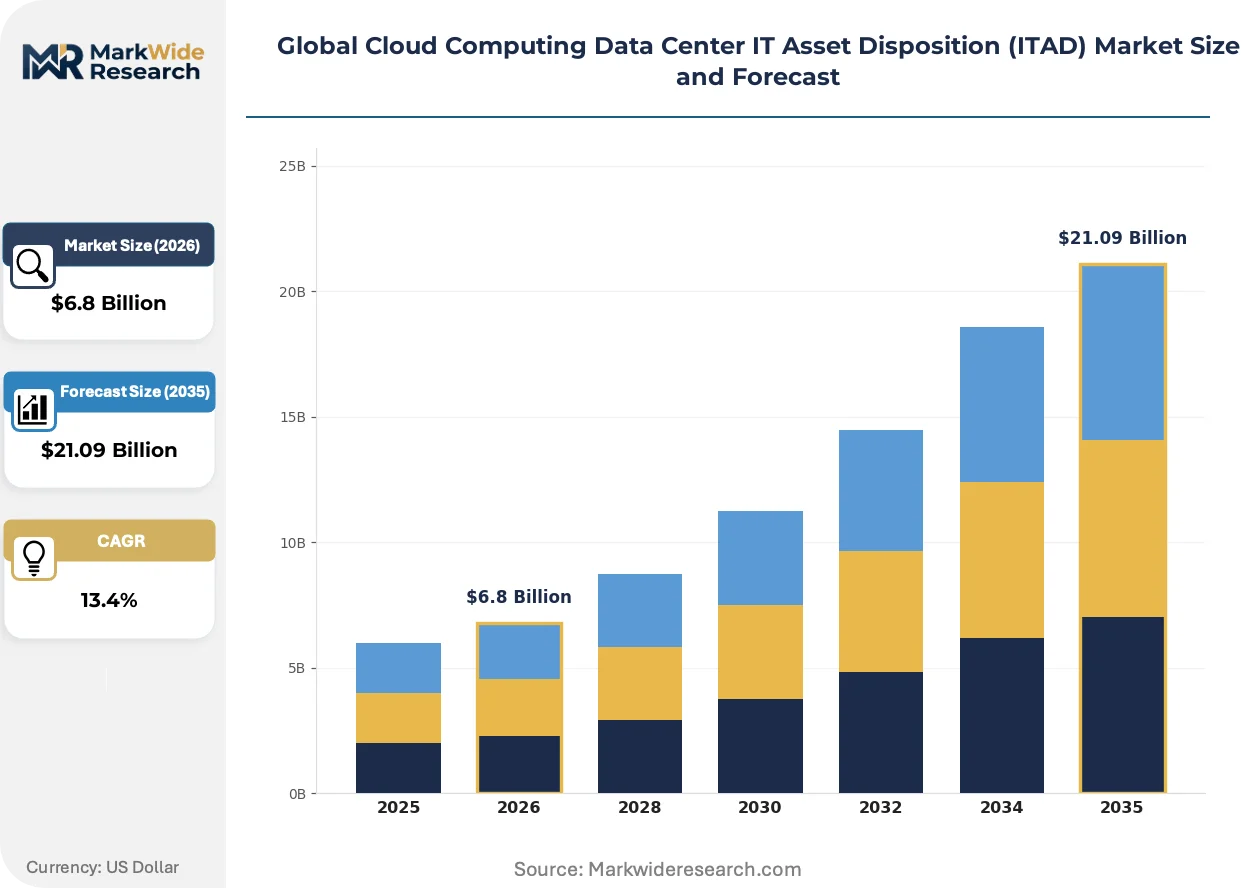
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $21.09 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Refresh & Remarketing, Data Destruction, Component Harvesting, Secure Recycling, Logistics Management, Diagnostics & Testing End User: Cloud Service Providers, Hyperscale Operators, Colocation Facilities, Managed Service Providers, Telecommunication Companies, Edge Data Centers Deployment Model: Private Cloud, Public Cloud, Hybrid Cloud, Multi-Cloud, Community Cloud Asset Type: Server Systems, Storage Systems, Networking Equipment, Power Supplies, Cooling Systems, Racks & Enclosures |
| Companies Covered | Iron Mountain, Hewlett Packard Enterprise, Sims Lifecycle Services, HOBI International, TES, Arrow Electronics, IBM, Dell, Atlantix Global Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cloud Computing Data Center IT Asset Disposition (ITAD) Market Shifts & Advancements
Automated material identification and AI-driven component grading are electrifying recovery yields, while regulatory pressure on embodied carbon is reshaping how cloud operators evaluate ITAD partners.
Robotic disassembly systems equipped with computer vision are electrifying server decommissioning throughput. Hyperscale operators in the United States and Germany are deploying these systems at dedicated reverse-logistics hubs. The technology is electrifying labor cost structures and enabling 24-hour processing windows that compress asset-to-resale cycles from weeks to days.
REACH and RoHS substance restrictions are tightening material reuse eligibility for refurbished electronics circulating across EU member states. Cloud providers must now certify that recovered components contain no restricted phthalates or flame retardants before redeployment. German and French operators are responding by segmenting ITAD vendor pools into REACH-compliant and non-compliant tiers.
Consumption-based service contracts are displacing traditional per-asset disposal agreements. Enterprise buyers now demand outcome-based pricing tied to verified data destruction certificates and recovered material value sharing. This shift is most visible in United States financial services and healthcare verticals, where liability exposure drives preference for bundled sanitization-plus-recovery services over transactional scrap arrangements.
Global Cloud Computing Data Center IT Asset Disposition (ITAD) Market Segmentation
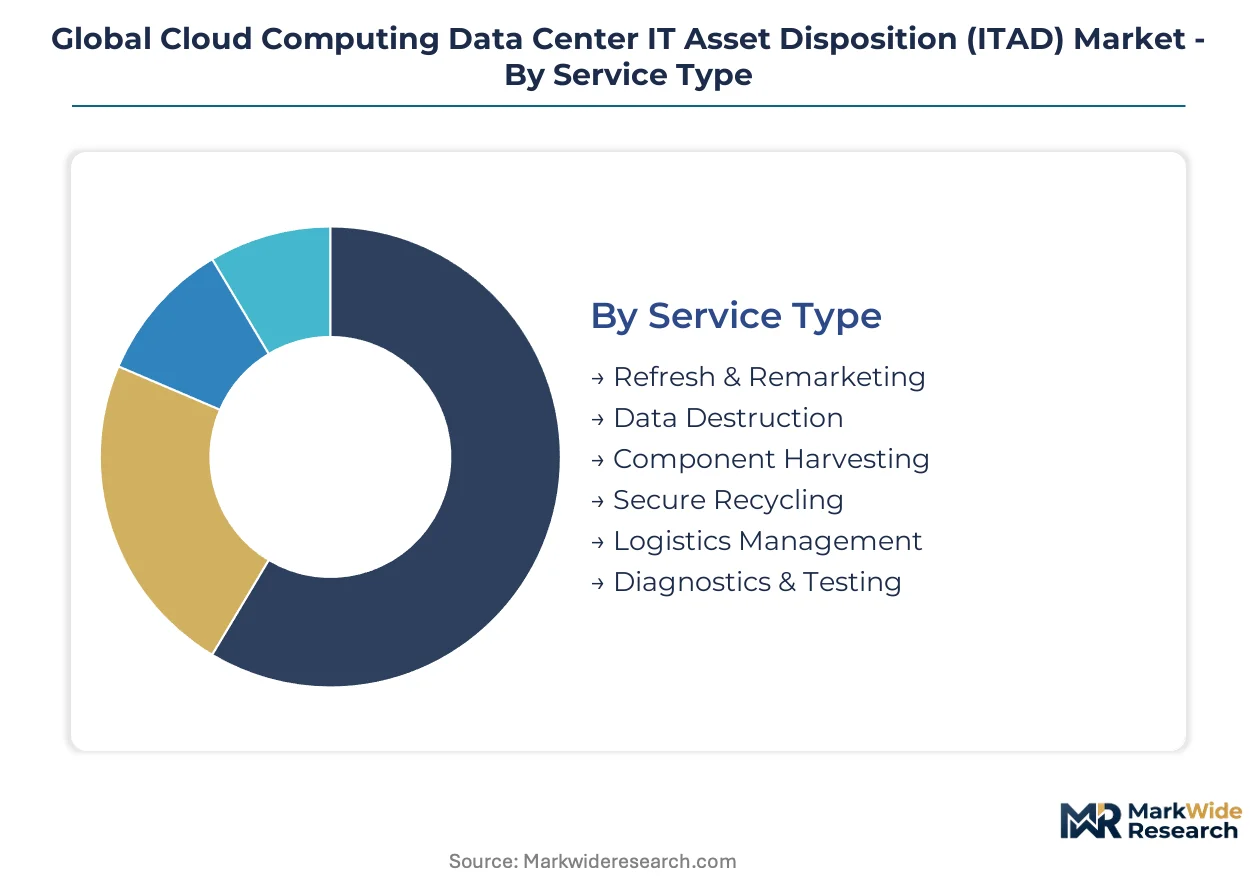
ITAD service differentiation separates premium liability-bearing offerings from high-volume commodity flows. Cloud operators select service tiers based on data sensitivity classification and residual asset value recovery targets.
Service Type:
Volume throughput dominates refresh and remarketing, while data destruction commands pricing premiums tied to liability exposure.
- Refresh & Remarketing:Server refurbishment and secondary-market resale of NVMe storage arrays and compute nodes. Hyperscale operators in Germany and the United States drive volume as Skylake-era infrastructure reaches end-of-life simultaneously.
- Data Destruction:NIST 800-88 purge protocol execution with certificate issuance for audit compliance. Financial services and healthcare verticals in the United States pay premiums for bundled sanitization-plus-documentation services.
- Component Harvesting:DRAM module extraction and GPU recovery for AI inference secondary markets.
- Secure Recycling:Smelter-directed material flows with full chain-of-custody documentation under EU WEEE mandates.
- Logistics Management:Reverse supply chain coordination from rack removal through final disposition.
- Diagnostics & Testing:Functional verification of retired assets prior to remarketing or harvesting decisions.
Today's leader: Data Destruction. Tomorrow's challenger: Component Harvesting.
End User:
Hyperscale operators generate the steepest decommissioning surges as refresh cycles compress below 36 months.
- Cloud Service Providers:Amazon Web Services, Microsoft Azure, and Google Cloud operate captive ITAD programs with dedicated reverse-logistics hubs.
- Hyperscale Operators:First-generation NVMe storage arrays and Skylake-era compute nodes are flooding secondary markets from simultaneous retirement programs across United States and German facilities.
- Colocation Facilities:Multi-tenant infrastructure in Mumbai and Hyderabad creates fragmented asset ownership complicating chain-of-custody documentation.
- Managed Service Providers:White-label ITAD coordination for enterprise clients lacking direct vendor relationships.
- Telecommunication Companies:Legacy central office equipment migration to cloud architectures generates mixed-vintage decommissioning volumes.
- Edge Data Centers:Distributed micro-facilities complicate logistics economics for consolidated processing.
Hyperscale concentration is forcing mid-tier providers toward specialization in edge and colocation segments.
Deployment Model:
Public cloud infrastructure generates standardized asset homogeneity that streamlines remarketing, while hybrid complexity fragments recovery economics.
- Private Cloud:Enterprise-owned infrastructure with customized configurations requiring individualized sanitization protocols.
- Public Cloud:Standardized server generations from Amazon Web Services, Microsoft Azure, and Google Cloud enable component harvesting at scale.
- Hybrid Cloud:Mixed ownership structures complicate liability allocation between enterprise and provider during decommissioning.
- Multi-Cloud:Cross-provider asset distribution fragments chain-of-custody documentation requirements.
- Community Cloud:Sector-specific infrastructure in healthcare and financial services demands specialized compliance certification.
Public cloud standardization is accelerating robotic disassembly adoption; hybrid complexity sustains demand for manual protocol execution.
Asset Type:
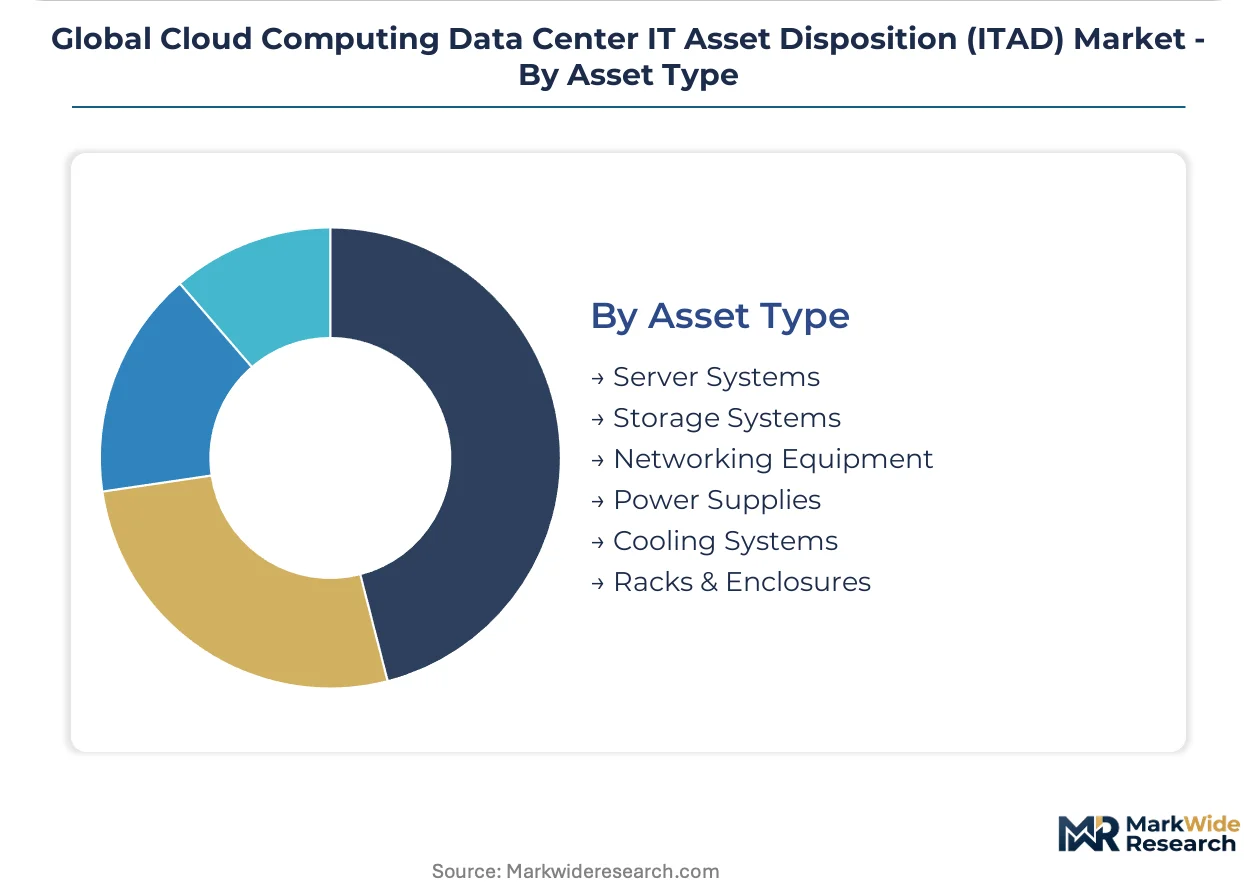
Server systems and storage systems concentrate recovery value, while power and cooling equipment face commodity scrap economics.
- Server Systems:Compute nodes with recoverable CPUs, DRAM modules, and GPUs. Rare-earth magnet extraction from fans and actuators commands premium component-level economics in German and Japanese processing facilities.
- Storage Systems:NVMe-based arrays and traditional spinning-disk infrastructure reaching simultaneous end-of-life. Helium-filled drives with glass substrates require capital-intensive degaussing equipment upgrades.
- Networking Equipment:Switch and router remarketing faces shorter technology obsolescence cycles than compute assets.
- Power Supplies:Lithium battery recovery triggers EPA hazardous-waste classification uncertainty fragmenting cross-border processing.
- Cooling Systems:Coolant handling regulations vary by United States state, complicating logistics for national operators.
- Racks & Enclosures:Structural steel and aluminum recovery with minimal data liability exposure.
Server systems dominate current recovery margins. Storage systems face technology transition pressure from helium-drive handling requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified ITAD technicians concentrate in Germany, Japan, and the United States, where hyperscale decommissioning volumes and regulatory stringency create specialized labor markets. These geographies anchor global capacity for secure data destruction and component recovery.
United States
Hyperscale operators in Northern Virginia and Dallas-Fort Worth metro areas are retiring first-generation NVMe arrays simultaneously. The EPA's state-fragmented hazardous-waste classifications for lithium batteries complicate cross-border logistics. Chicago and Phoenix host dedicated reverse-logistics hubs processing Skylake-era compute nodes at 24-hour throughput cycles.
Germany
Frankfurt's data center corridor generates concentrated decommissioning volumes as cloud infrastructure reaches end-of-life. The EU WEEE Directive mandates full material traceability from rack removal through smelting, forcing ITAD providers into certified vendor tiers. Bavarian processing facilities specialize in rare-earth magnet extraction from server fans and hard drive actuators.
Japan
Tokyo and Osaka cloud facilities face compressed refresh cycles below 36 months for AI inference infrastructure. METI enforces strict domestic recycling quotas that prevent export of retired assets to Southeast Asian recovery facilities. Kyushu-based smelters process neodymium and dysprosium harvested from hyperscale decommissions under closed-loop material controls.
India
Mumbai and Hyderabad colocation buildouts are creating ITAD demand as legacy enterprise servers migrate to cloud architectures. The country's national electronics regulator enforces extended producer responsibility frameworks for data center equipment. Bangalore technicians specialize in DRAM module testing and GPU refurbishment for secondary AI markets.
United Kingdom
London's financial services vertical drives premium pricing for bundled data destruction and documentation services. The country's data protection authority mandates NIST 800-88 purge protocol execution for cloud provider contracts. Slough and Manchester processing clusters handle mixed-vintage decommissioning from hybrid cloud migrations.
Global Cloud Computing Data Center IT Asset Disposition (ITAD) Market Competitive Landscape
The competitive structure tilts toward diversified industrials with captive reverse-logistics networks. Market concentration remains moderate, with three to five vertically integrated operators commanding hyperscale contracts while regional specialists fragment mid-tier enterprise accounts. Two strategic archetypes dominate: archive-security heritage firms leveraging compliance credibility, and original equipment manufacturers bundling ITAD with hardware refresh cycles. Competitive moves center on certification audit acceleration and robotic disassembly technology deployment.
Within the diversified industrial tier, Iron Mountain, Hewlett Packard Enterprise, and Sims Lifecycle Services exemplify contrasting positioning strategies. Iron Mountain represents the archive-security heritage archetype, extending document destruction credibility into electronic media. Hewlett Packard Enterprise occupies a position as an original equipment manufacturer with captive reverse-logistics infrastructure tied to server sales. Sims Lifecycle Services sits within the component harvesting specialization vector, focusing on semiconductor and rare-earth material recovery before smelting.
| Leading Market Players |
|---|
| Iron Mountain |
| Hewlett Packard Enterprise |
| Sims Lifecycle Services |
| HOBI International |
| TES |
| Arrow Electronics |
| IBM |
| Dell |
| Atlantix Global Systems |
| Others |
Supply & Pricing Matrix
Hyperscale cloud operators in Northern Virginia and Frankfurt concentrate procurement volume, forcing ITAD providers into bundled sanitization-plus-recovery contracts with outcome-based pricing tied to verified data destruction certificates and material value sharing.
Pricing Analysis
Bundled liability-bearing services versus unbundled transactional disposal splits the pricing landscape. Three-tier pricing structure across premium, standard, and economy levels separates R2-certified destruction with full documentation from basic recycling without chain-of-custody guarantees. Price differentiation hinges on certification grade and volume scale, with financial services verticals paying premiums for NIST 800-88 purge protocol execution. Pricing pressure stems from robotic disassembly technology deployment compressing labor cost structures. Mid-tier colocation facilities exhibit highest price sensitivity, while hyperscale operators prioritize compliance credibility over unit cost.
Supply Chain Analysis
Certification gating through R2 and e-Stewards audit backlogs delays vendor qualification by 8-14 months, concentrating supply among accredited incumbents. Geographic supply concentrates in Germany, Japan, and the United States where certified technicians cluster around hyperscale decommissioning hubs. Raw material flows draw from retired server systems, NVMe storage arrays, and rare-earth magnet harvesting from fans and actuators. Single-source vulnerability runs through lithium battery recovery facilities facing EPA state-fragmented hazardous-waste classifications. Distribution runs through captive reverse-logistics networks at dedicated processing hubs in Chicago, Phoenix, and Bavaria.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as EU WEEE Directive chain-of-custody mandates shift procurement toward certified vendors with auditable documentation capabilities.
For Market Incumbents: Acquire robotic disassembly technology assets to compress asset-to-resale cycles from weeks to days. Consolidate regional processing capacity in Germany and Japan where METI domestic recycling quotas and EU material traceability rules create captive demand. Certification investment serves as the primary defensive lever against mid-tier specialists. Channel control over hyperscale reverse-logistics contracts limits emerging entrant access. For New Entrants and Emerging Players: Blockchain-based chain-of-custody verification technology offers entry wedge into compliance documentation services for EU WEEE and emerging US state e-waste laws. White-space targets include India's colocation buildouts in Mumbai and Hyderabad where fragmented asset ownership complicates incumbent coordination. Component harvesting specialization in DRAM module testing and GPU refurbishment for secondary AI inference markets provides the most penetrable segment. Direct sales to edge data center operators bypasses hyperscale captive program saturation. For Investors and Strategic Acquirers: Original equipment manufacturers with server sales footprints are the most active acquirer in this space, seeking captive reverse-logistics integration. Long-term viability centers on regulatory compliance infrastructure rather than commodity scrap economics. Acquisition target archetype: regional specialists with R2 or e-Stewards certification and established hyperscale relationships. Monitor EU extended producer responsibility mandate expansion as inflection indicator for contracted demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Disassembly Deployment | Computer vision-enabled systems at Chicago and Phoenix hubs compress processing windows to 24-hour cycles. |
| R2 Certification Acceleration | Audit backlog reduction enables faster vendor qualification for hyperscale decommissioning contracts. |
| Component Harvesting Specialization | DRAM and GPU recovery for AI inference secondary markets commands premium recovery economics. |
| Blockchain Chain-of-Custody | Immutable ledgers satisfy EU WEEE material traceability mandates for cloud provider compliance. |
| India Colocation Partnership | Mumbai and Hyderabad facility relationships capture legacy enterprise server migration demand. |
Research Methodology
Direct dialogue with data center operations directors, IT procurement officers at hyperscale cloud providers, certified ITAD facility managers, and regulatory compliance leads at EU member state environmental agencies grounded the qualitative foundation. Secondary validation drew from EPA hazardous-waste classification filings, EU WEEE implementation reports, METI recycling quota disclosures, hyperscaler capex and decommissioning announcements, and R2/e-Stewards certification databases. Bottom-up service volume estimates triangulated against top-down cloud infrastructure depreciation schedules.
Segment-level projections across service type, asset category, deployment model, and end-user vertical fed into the analytical framework over the projection horizon. CAGR derivation incorporated server refresh cycle compression trends, regulatory mandate phase-in schedules, and secondary market component resale velocity. Industry-specific inputs included NVMe storage array retirement timing, rare-earth magnet recovery yield rates, and NIST 800-88 purge protocol labor intensity coefficients.
The model holds under stable regulatory enforcement intensity and continued hyperscale infrastructure buildout; deviation in EU extended producer responsibility expansion timing or EPA lithium battery classification harmonization would shift volume and value trajectories. A model refresh is warranted upon material change in hyperscale decommissioning program acceleration or certification audit backlog resolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
South America Data Center Server Market
Data Center Infrastructure
France Data Center Rack Market
Data Center Infrastructure
Nigeria Data Center Physical Security Market
Data Center Infrastructure
Brazil Data Center Power Market
Data Center Infrastructure
Canada Data Center Storage Market
Data Center Infrastructure
Denmark Data Center Server Market
Data Center Infrastructure
India Data Center Market
Data Center Infrastructure
Global Data Center Accelerator Market
Data Center Infrastructure
Taiwan Data Center Server Market
Data Center Infrastructure
Global Micro Mobile Data Center Market
Data Center Infrastructure
Belgium Data Center Physical Security Market
Data Center Infrastructure
Taiwan Data Center Power Market
Data Center Infrastructure
Singapore Data Center Server Market
Data Center Infrastructure
Hong Kong Data Center Rack Market
Data Center Infrastructure
Norway Data Center Server Market
Data Center Infrastructure
Multi-Tenant Data Center Market