
 Nigeria Data Center Market | 2026-2036
Nigeria Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Nigeria Data Center Market Insights
Enterprise buyer concentration across Nigerian banks and mobile network operators is restructuring procurement patterns for data center capacity. MTN Nigeria leverages its integrated telecom-to-cloud stack to capture captive demand from enterprise subsidiaries. MDXi anchors West African interconnection through its Lagos cable landing station adjacency. Africa Data Centres competes with hyperscale-ready designs targeting pan-African enterprise rollouts.
A data center constitutes a dedicated facility housing compute, storage, and networking equipment with controlled environmental parameters—typically maintaining temperatures between 18°C and 27°C and power usage effectiveness ratios below 1.5 for efficient operations—serving as the physical backbone for digital service delivery. Colocation services dominate current revenue as enterprises shed owned facilities for operational flexibility. Cloud services represent the fastest-expanding segment, though margin pools remain thinner than managed services where technical integration complexity sustains pricing power. Capacity segmentation shows enterprise-class deployments absorbing the majority of new power allocation in Lagos corridors.
The National Information Technology Development Agency enforces data localization mandates that restrict certain government and financial data from offshore hosting, directly stimulating domestic construction permits. The Central Bank of Nigeria's cashless policy and digital banking frameworks amplify BFSI sector capacity requirements. Stakeholders must monitor spectrum allocation timelines and diesel subsidy reforms, as backup power economics determine facility viability outside grid-stable zones.
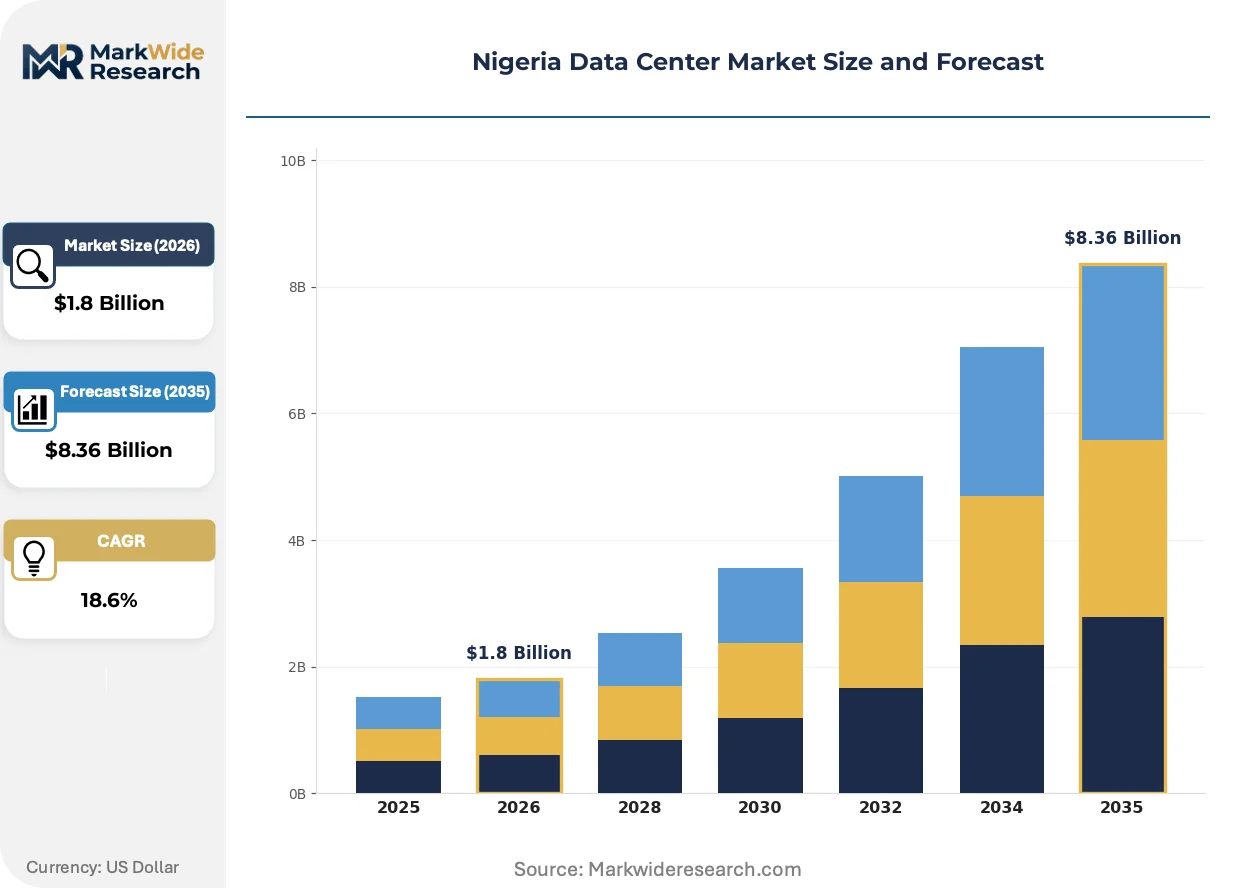
Market Dynamics
Nigeria's data center expansion hinges on the collision between NITDA's data sovereignty mandates and diesel-dependent backup power economics. Facility operators must absorb localization requirements while grid instability forces redundant generation investments.
Growth Catalysts
- Data Localization Mandates:NITDA's guidelines restrict offshore hosting of government and financial data, compelling domestic facility construction.
- Mobile Network Operator Cloud Migration:MTN Nigeria and Airtel Africa are migrating enterprise workloads from on-premise server rooms to colocation facilities.
- Lagos Cable Landing Concentration:Submarine cable landings at Lekki and Apapa create low-latency interconnection gravity for West African traffic.
Market Restraints
- Diesel Price Volatility:Backup generator economics consume 35-45% of operational expenditure as diesel subsidy reforms proceed.
- Grid Instability Outside Lagos:Power reliability in Kano, Port Harcourt, and Abuja corridors forces 2N or 2N+1 redundancy designs that inflate capex.
- Limited Domestic Fiber Backhaul:Last-mile fiber penetration outside Lagos metropolitan zones constrains edge deployment feasibility.
Strategic Opportunities
- Abuja Federal Data Center Consolidation:Government cloud migration programs create anchor tenancy demand for Tier III facilities in the Federal Capital Territory.
- Hyperscale-Ready Design Convergence:Liquid cooling and modular power architectures enable 30MW+ campus developments serving pan-African cloud providers.
- Financial Services Edge Computing:CBN's real-time payment systems drive sub-10ms latency requirements for bank transaction processing nodes.
Industry Challenges
- Certified Data Center Engineering Talent Scarcity:Uptime Institute and TIA-942 accredited design professionals remain concentrated in South Africa and Europe.
- Legacy Enterprise Server Room Integration:Nigerian banks face complex workload migration from aging on-premise infrastructure with custom core banking software dependencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nigeria Data Center Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Colocation, Managed Services, Cloud Services, Infrastructure as a Service End User: IT & Telecom, BFSI, Government, Healthcare Capacity: Small, Medium, Large, Enterprise Technology: Hyperconverged, Traditional, Open Source, Proprietary |
| Companies Covered | Africa Data Centres, MDXi (MainOne – an Equinix Company), Rack Centre, MTN Nigeria, Open Access Data Centres, Nxtra (Airtel Africa), 21st Century Technologies, Digital Realty, Equinix, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nigeria Data Center Market Trends and Innovations
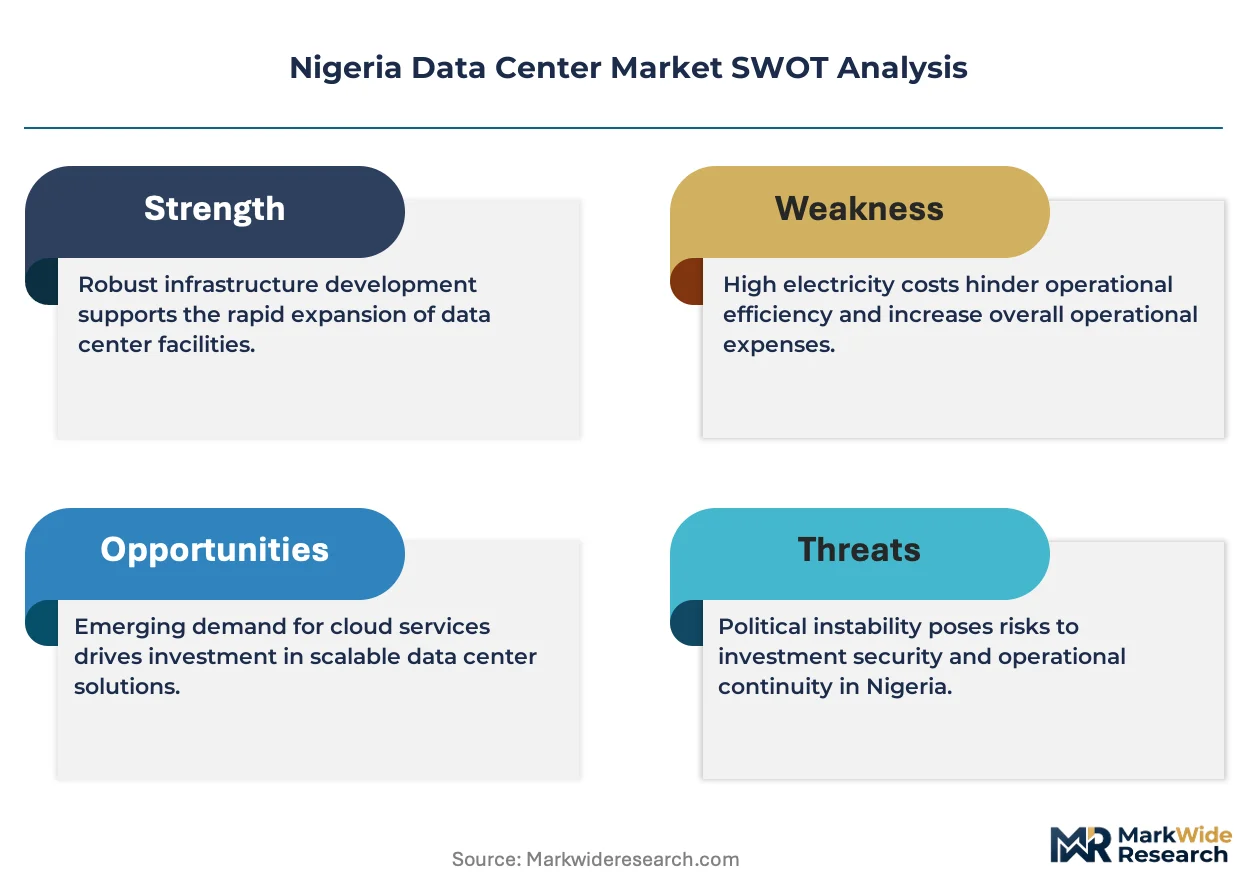
Modular construction techniques and software-defined power management are compressing facility deployment timelines. Operators now prioritize energy efficiency certifications as diesel costs escalate and ESG disclosure requirements tighten.
Liquid cooling systems are integrating into high-density compute environments to support GPU clusters for AI training workloads. Nigerian banks and fintechs deploying fraud detection models are adopting direct-to-chip cooling to manage 50kW+ rack densities. This technology is integrating with existing air-cooled infrastructure through hybrid designs that preserve capital in legacy white space.
NITDA's data center certification framework is mandating minimum Tier II resilience standards for facilities handling government cloud workloads. The regulation compresses market entry for uncertified operators while accelerating professional services demand for compliance consulting. Financial institutions represent the most affected segment, with tier-1 banks pre-certifying suppliers to accelerate procurement cycles.
Enterprise buyers are consolidating vendor relationships around integrated telecom-to-cloud stacks. Mobile network operators with captive fiber and tower portfolios are capturing data center contracts that previously flowed to pure-play colocation providers. This concentration is most visible in Lagos, where MTN's Y'ello Digital and Airtel's cloud services bundle connectivity with rack space.
Nigeria Data Center Market Segmentation
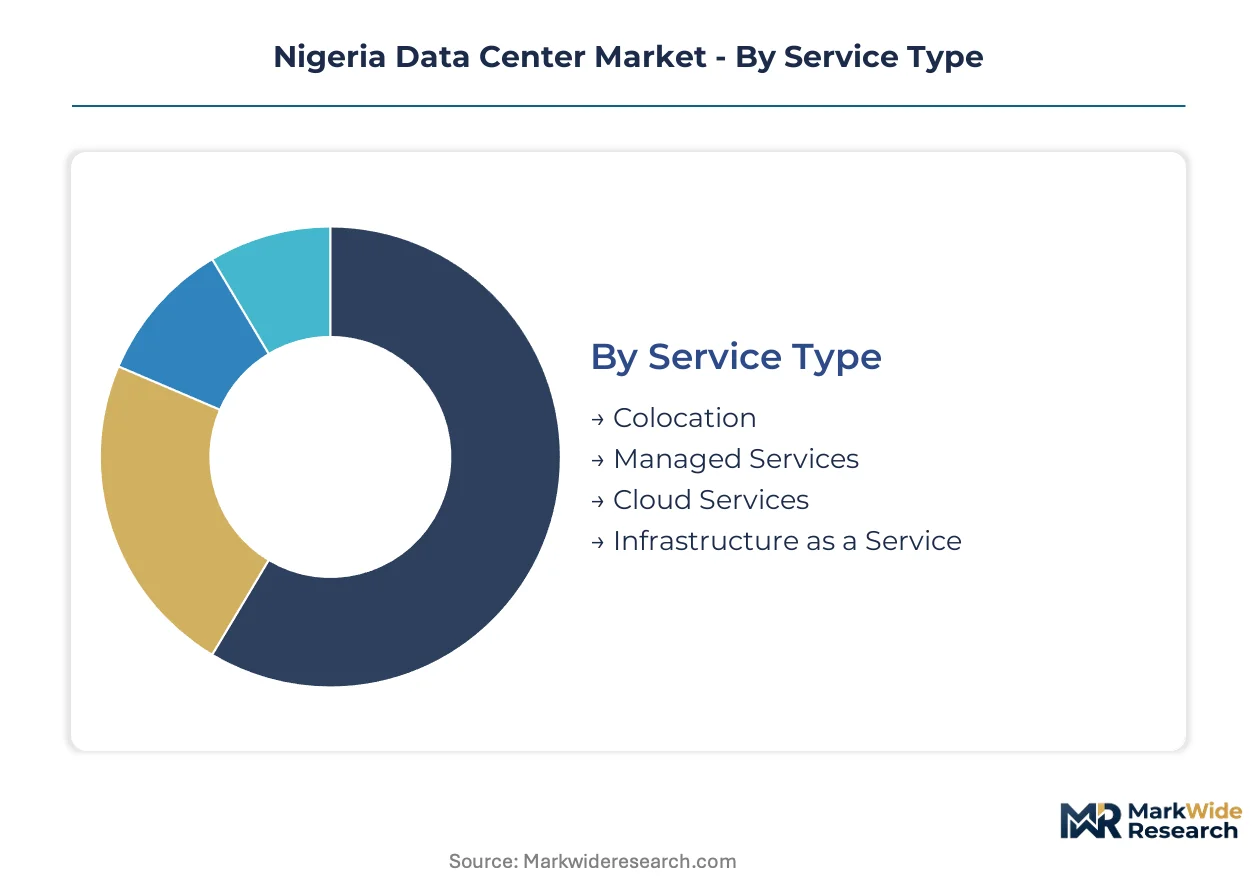
Segmentation reveals how Nigerian data center operators allocate capital across service tiers and capacity bands. Procurement patterns diverge sharply between financial institutions seeking managed sovereignty compliance and mobile operators optimizing for interconnection density.
Service Type:
Supply concentrates in colocation and managed services where facility operators capture recurring revenue through long-term enterprise contracts.
- Colocation:Rack space and power provisioning with shared facility infrastructure. Nigerian banks and mobile network operators dominate demand in Lagos corridors where submarine cable landings minimize latency. NITDA's data localization mandates compel domestic facility commitments over offshore alternatives.
- Managed Services:Technical integration covering migration, monitoring, and optimization. Tier-1 banks pre-certify suppliers to accelerate procurement cycles while navigating legacy core banking software dependencies. Margin pools remain thicker than commodity infrastructure due to complexity premiums.
- Cloud Services:Virtualized compute and storage delivered on-demand. MTN Nigeria and Airtel Africa bundle connectivity with cloud workloads, capturing contracts that previously flowed to pure-play providers.
- Infrastructure as a Service:Raw compute, storage, and networking resources provisioned programmatically. Hyperscale-ready designs in Lagos enable 30MW+ campus developments serving pan-African providers.
Today's leader: Colocation. Tomorrow's challenger: Cloud Services.
End User:
Cost tier differentiation separates premium compliance-driven buyers from standard infrastructure seekers.
- IT & Telecom:Mobile network operators and internet service providers requiring low-latency interconnection. MTN Nigeria leverages integrated telecom-to-cloud stacks for captive enterprise demand. Spectrum allocation timelines determine capacity expansion pacing.
- BFSI:Banks, insurance carriers, and fintechs subject to Central Bank of Nigeria cashless policy frameworks. Real-time payment systems drive sub-10ms latency requirements for transaction processing nodes in Lagos and Abuja.
- Government:Federal and state agencies migrating to certified facilities under NITDA Tier II minimum standards. Abuja Federal Data Center consolidation programs create anchor tenancy demand in the Federal Capital Territory.
- Healthcare:Hospital networks and health insurers adopting digital records infrastructure. Data sovereignty requirements restrict patient information from offshore hosting, stimulating domestic construction permits.
BFSI commands premium pricing. Government represents the steepest expansion trajectory.
Capacity:
Volume distribution favors enterprise-class deployments absorbing majority power allocation in grid-stable zones.
- Small:Facilities below 500kW serving edge workloads and branch office consolidation. Limited domestic fiber backhaul outside Lagos metropolitan zones constrains deployment feasibility.
- Medium:500kW to 2MW designs targeting regional enterprise clusters. Port Harcourt and Kano corridors force 2N redundancy designs that inflate capex due to grid instability.
- Large:2MW to 10MW campuses serving multi-tenant requirements. Diesel price volatility consumes 35-45% of operational expenditure as subsidy reforms proceed.
- Enterprise:10MW+ hyperscale-ready facilities with modular power architectures. Liquid cooling integration supports GPU clusters for AI training workloads in fraud detection applications.
Enterprise claims investment priority. Small capacity faces fiber penetration constraints.
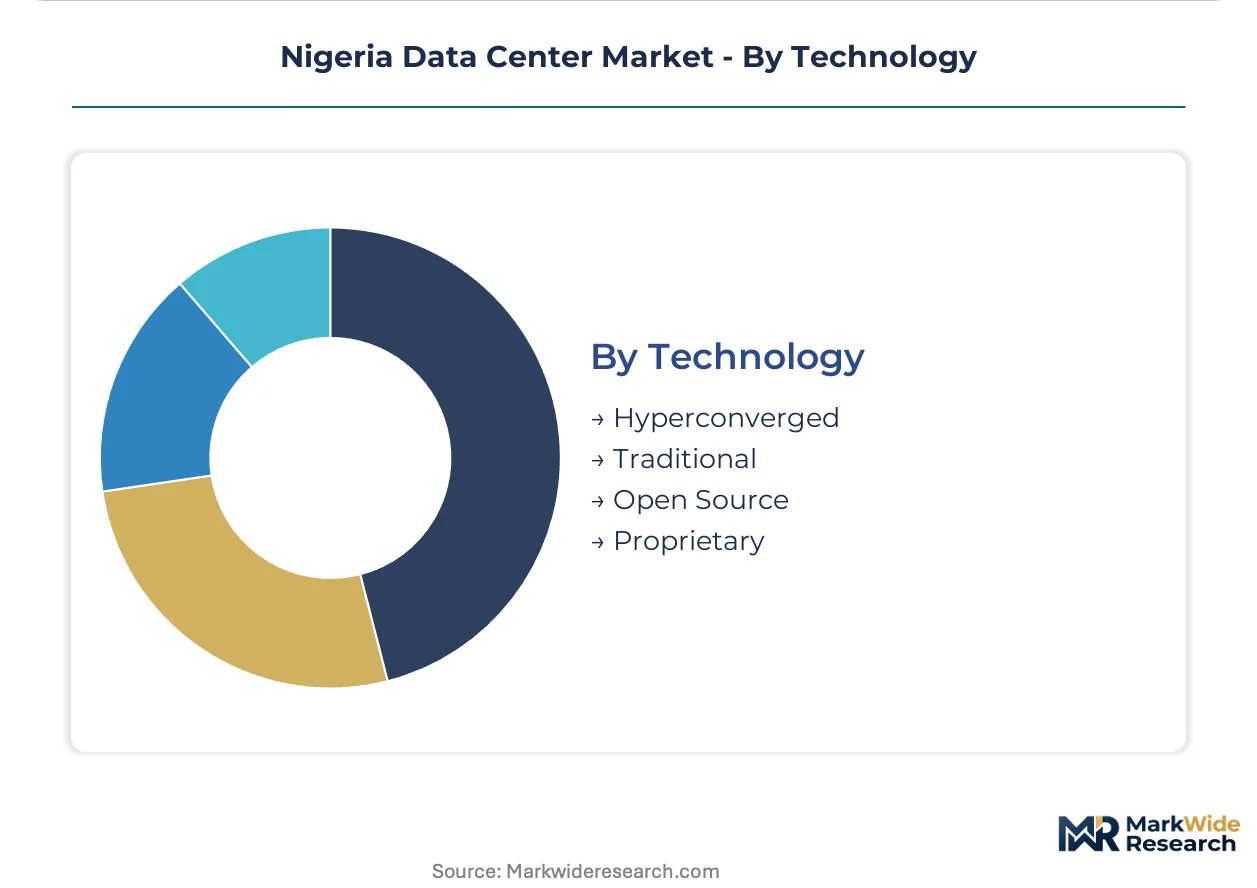
Technology:
Customer type splits between incumbent banks preserving legacy investments and cloud-native entrants adopting software-defined infrastructure.
- Hyperconverged:Integrated compute, storage, and networking through software-defined layers. Nigerian fintechs deploy direct-to-chip cooling to manage 50kW+ rack densities for AI model training.
- Traditional:Siloed three-tier architecture with discrete servers, storage arrays, and network switches. Tier-1 banks maintain custom core banking software dependencies that complicate workload migration.
- Open Source:Community-driven platforms reducing licensing overhead. Modular construction techniques compress deployment timelines for operators prioritizing capital efficiency.
- Proprietary:Vendor-locked systems with integrated hardware-software stacks. Enterprise buyers consolidate around integrated telecom-to-cloud bundles from mobile network operators with captive fiber portfolios.
Traditional architecture retains installed base. Hyperconverged is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified data center engineering talent concentrates in Lagos, where submarine cable landings and enterprise density create infrastructure gravity for Nigerian facility operators.
Lagos Metropolitan Corridor
Financial services institutions and mobile network operators drive capacity absorption in the Lekki and Apapa zones. NITDA's data localization mandates compel domestic hosting commitments from tier-1 banks. The Lagos cable landing station adjacency positions MDXi to anchor West African interconnection.
Abuja Federal Capital Territory
Government cloud migration programs generate anchor tenancy demand for Tier III facilities. The Central Bank of Nigeria's digital banking frameworks amplify real-time payment infrastructure requirements. Federal data center consolidation concentrates procurement in the city center and satellite districts.
Port Harcourt
Oil and gas sector digitalization creates enterprise workload demand from energy multinationals. Grid instability forces 2N redundancy designs that inflate operational expenditure. Limited domestic fiber backhaul constrains edge deployment feasibility outside core metropolitan zones.
Kano
Islamic banking institutions and agricultural commodity traders seek regional data residency for transaction processing. Diesel-dependent backup power economics consume 35-45% of facility budgets as subsidy reforms proceed. Northern corridor fiber penetration remains below Lagos benchmarks.
Ibadan
Educational institutions and healthcare networks adopt digital records infrastructure subject to data sovereignty requirements. State government cloud programs stimulate medium-capacity facility development. Proximity to Lagos fiber routes enables latency-sensitive workload distribution.
Nigeria Data Center Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Nigerian data center procurement. The market structure shows moderate concentration around integrated telecom operators and independent colocation providers. Three archetypes dominate: mobile network operators with captive fiber portfolios, pan-African facility specialists with hyperscale-ready designs, and regional pure-plays targeting compliance-driven financial services demand. Capacity expansion and strategic fiber partnerships constitute the dominant competitive moves.
Within the telecom-integrated tier, MTN Nigeria and Airtel Africa's Nxtra occupy positions leveraging captive tower and fiber assets to bundle connectivity with rack space. Africa Data Centres exemplifies the pan-African specialist archetype targeting enterprise-class deployments across multiple markets. MDXi represents the cable-landing adjacency model, anchoring interconnection gravity through Lagos submarine cable proximity. Rack Centre sits within the independent colocation segment serving financial institutions with certified facility commitments.
| Leading Market Players |
|---|
| Africa Data Centres |
| MDXi (MainOne – an Equinix Company) |
| Rack Centre |
| MTN Nigeria |
| Open Access Data Centres |
| Nxtra (Airtel Africa) |
| 21st Century Technologies |
| Digital Realty |
| Equinix |
| Others |
Pricing and Supply Chain Analysis
Financial services institutions concentrated in Lagos corridors anchor pricing power for Nigerian data center operators, with tier-1 banks accepting premium rack rates for Tier III certification compliance while smaller enterprises negotiate commodity colocation contracts. This buyer concentration bifurcates the market into bundled managed services with thick margins and unbundled infrastructure with thinner returns.
Pricing Analysis
Bundled connectivity-plus-compute packages from mobile network operators command 15-25% premiums over unbundled rack space from independent colocation providers. Price differentiation rests on certification grade—Uptime Institute Tier III facilities extract premiums from BFSI buyers—and volume scale, with hyperscale deployments securing long-term offtake pricing. Cost compression in standard colocation intensifies as diesel subsidy reforms inflate operational expenditure and force facility operators to absorb margin erosion. Small and medium enterprises exhibit highest price sensitivity, migrating workloads to cloud services bundles rather than certified Tier III facilities.
Supply Chain Analysis
Freight costs for critical infrastructure equipment—generators, switchgear, precision cooling units—consume disproportionate capex share given Nigeria's distance from manufacturing hubs in China, Germany, and the United States. Facility construction draws from Chinese electrical components, European power distribution equipment, and American cooling systems, creating multi-source procurement complexity. Single-source vulnerability concentrates in diesel generator supply, with limited domestic assembly capacity forcing dependency on imported Caterpillar and Cummins units. Distribution runs through Lagos port corridors, with Apapa congestion extending equipment lead times and inflating project timelines for Abuja and Port Harcourt deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nigeria's data center market functions as a geographic-arbitrage play where NITDA's data localization mandates create captive domestic demand unavailable to offshore competitors, while diesel-dependent backup power economics deter capital-light entrants lacking operational scale.
For Market Incumbents: Lock in long-term enterprise contracts with BFSI buyers before NITDA certification requirements harden procurement criteria and accelerate supplier consolidation. Defend against mobile network operator cloud bundles by deepening vertical integration into captive fiber backhaul and tower portfolios. Prioritize liquid cooling certification for AI-ready rack densities to capture fintech fraud-detection workload demand.
For New Entrants and Emerging Players: Islamic banking institutions in Kano and agricultural commodity traders represent underserved buyer archetypes seeking regional data residency with limited incumbent presence. Target medium-capacity facilities in northern corridors where grid instability has deterred hyperscale investment. Deploy modular construction techniques to compress deployment timelines and undercut established operators on project delivery speed.
For Investors and Strategic Acquirers: Pan-African telecom operators are the most active acquirer in this space, seeking integrated infrastructure stacks across West African markets. The 5-10 year viability window favors facilities with cable landing station adjacency and certified engineering talent pipelines. Monitor diesel subsidy reform implementation as the critical inflection signal determining operational expenditure trajectories and facility margin sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Tier III Certification Investment | NITDA mandates Tier II minimums, creating Tier III differentiation for BFSI procurement. |
| Cable Landing Station Adjacency | Lagos submarine cable proximity anchors West African interconnection gravity for latency-sensitive workloads. |
| Liquid Cooling Deployment | GPU clusters for AI fraud detection require direct-to-chip cooling at 50kW+ rack densities. |
| Modular Construction Adoption | Prefabricated facility components compress deployment timelines in diesel-cost-inflated environments. |
| Integrated Telecom-to-Cloud Bundling | MTN and Airtel capture enterprise contracts through captive fiber and tower portfolio leverage. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with data center facility operators, NITDA compliance officers, BFSI procurement leads, and hyperscale cloud architects with secondary validation from NITDA regulatory filings, Central Bank of Nigeria policy frameworks, submarine cable landing station disclosures, and Uptime Institute certification databases. Bottom-up facility capacity tallies triangulated against top-down enterprise IT spending estimates across the Nigerian economy.
Segment-weighting approaches distributed value and volume projections across service type tiers, end-user verticals, capacity bands, and technology architectures. CAGRs were derived from facility construction permit trajectories, enterprise cloud migration timelines, and diesel price elasticity modeling throughout the projection horizon. Forecast inputs incorporated NITDA enforcement intensity scenarios, spectrum allocation pacing for mobile network operators, and grid reliability improvement assumptions for secondary cities.
Underlying measurement precision varies by segment; Lagos metropolitan capacity figures carry tighter precision than northern corridor projections given disclosure concentration among certified operators. Forecasts reflect documented assumptions about regulatory enforcement timelines and infrastructure investment commitments. Stakeholders should weight assumptions against their own operating context, particularly diesel procurement strategies and grid backup redundancy designs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Ireland Data Center Market
Data Center Infrastructure
High Frequency Trading Server Market
Data Center Infrastructure
Server Station Market
Data Center Infrastructure
France Data Center Construction Market
Data Center Infrastructure
China Data Center Construction Market
Data Center Infrastructure
South Africa Data Center Power Market
Data Center Infrastructure
Europe Data Center Server Market
Data Center Infrastructure
Italy Data Center Market
Data Center Infrastructure
Brazil Data Center Power Market
Data Center Infrastructure
Israel Data Center Market
Data Center Infrastructure
Malaysia Data Center Rack Market
Data Center Infrastructure
North America Data Center Rack Market
Data Center Infrastructure
Chicago Data Center Market
Data Center Infrastructure
Asia-Pacific Data Center Market
Data Center Infrastructure
Asia-Pacific Data Center Infrastructure Management Market
Data Center Infrastructure
Australia Data Center Construction Market