
 Philippines Data Center Server Market | 2026-2036
Philippines Data Center Server Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Data Center Server Market Insights
Market Dynamics
Capital-intensity divergence between hyperscale-ready builders and legacy enterprise vendors is redrawing competitive boundaries in the Philippines. HP Enterprise leverages its global supply scale to serve multinational cloud operators establishing presence in Clark Freeport Zone. Super Micro Computer, Inc. differentiates through liquid-cooled server architectures suited to tropical ambient conditions. Dell Inc. anchors its position via channel partnerships with local systems integrators serving BPO and banking verticals.
Technical Landscape
Data center servers in the Philippines encompass rack-mounted, blade, and tower configurations engineered for compute densities exceeding 30 kW per rack, with redundant power and cooling architectures sustaining uptime above 99.99%. These systems process transactional workloads for financial services, host sovereign cloud instances for government agencies, and train AI models for telecommunications operators. Rack Servers dominate current procurement volumes among colocation providers expanding floor space in Cavite and Laguna. Blade Servers represent the fastest-growing product type as hyperscalers pursue space-efficient, high-throughput deployments. IT Services and Financial Services end users command the deepest margin pools due to compliance-driven refresh cycles and latency-sensitive application requirements.
Regulatory Environment
The Department of Information and Communications Technology, National Privacy Commission, and Bangko Sentral ng Pilipinas collectively shape server procurement through data localization mandates, cybersecurity certification requirements, and financial sector technology risk management rules. BIS-aligned standards for electromagnetic compatibility and energy efficiency filter import eligibility, while the National Broadband Plan directs subsidy flows toward domestic cloud infrastructure. Stakeholders must monitor evolving critical information infrastructure designations that could impose sovereign ownership conditions on server assets housed within Philippine territory.
Market Dynamics
Hyperscale cloud operators are compressing procurement cycles for tropical-grade server infrastructure, forcing legacy enterprise vendors to reconfigure supply chains around liquid-cooled architectures and modular power delivery systems suited to Metro Manila's grid constraints.
Growth Catalysts
- Real-time payment infrastructure:Filipino banks and fintech platforms are expanding server deployments to support instant settlement systems mandated by Bangko Sentral ng Pilipinas technology risk management rules.
- National Broadband Plan subsidies:The Department of Information and Communications Technology is directing public capital toward domestic cloud infrastructure buildout in Clark and Cavite corridors.
- AI model training demand:Telecommunications operators are procuring GPU-dense rack configurations for edge inference and centralized model development.
Market Restraints
- Import dependency for advanced cooling components:Liquid-cooled server subsystems rely on concentrated East Asian manufacturing bases, exposing buyers to shipping cost volatility and customs clearance friction.
- BIS electromagnetic compatibility certification:Alignment with BIS standards filters import eligibility for non-compliant server brands, narrowing vendor choice for price-sensitive colocation providers.
- Power grid instability in secondary provinces:Diesel generator redundancy requirements inflate total cost of ownership for facilities outside Luzon's transmission backbone.
Strategic Opportunities
- Subic Bay Freeport Zone expansion:Unused naval infrastructure offers submarine cable landing proximity and tax incentives for hyperscale campus development.
- Sovereign cloud mandates for government agencies:Critical information infrastructure designations under review by the National Privacy Commission could reserve server procurement for domestic-registered operators.
- Immersion cooling convergence with tropical ambient design:Integration of dielectric fluid systems with ambient air economizers reduces mechanical cooling load in Cavite's high-humidity climate.
Industry Challenges
- Datacenter engineering talent scarcity:Specialized skills in high-density power distribution and thermal management remain concentrated in Metro Manila, constraining provincial expansion timelines.
- Legacy BPO server refresh complexity:Financial services compliance mandates require uptime guarantees during hardware migration, extending procurement decision cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Data Center Server Market |
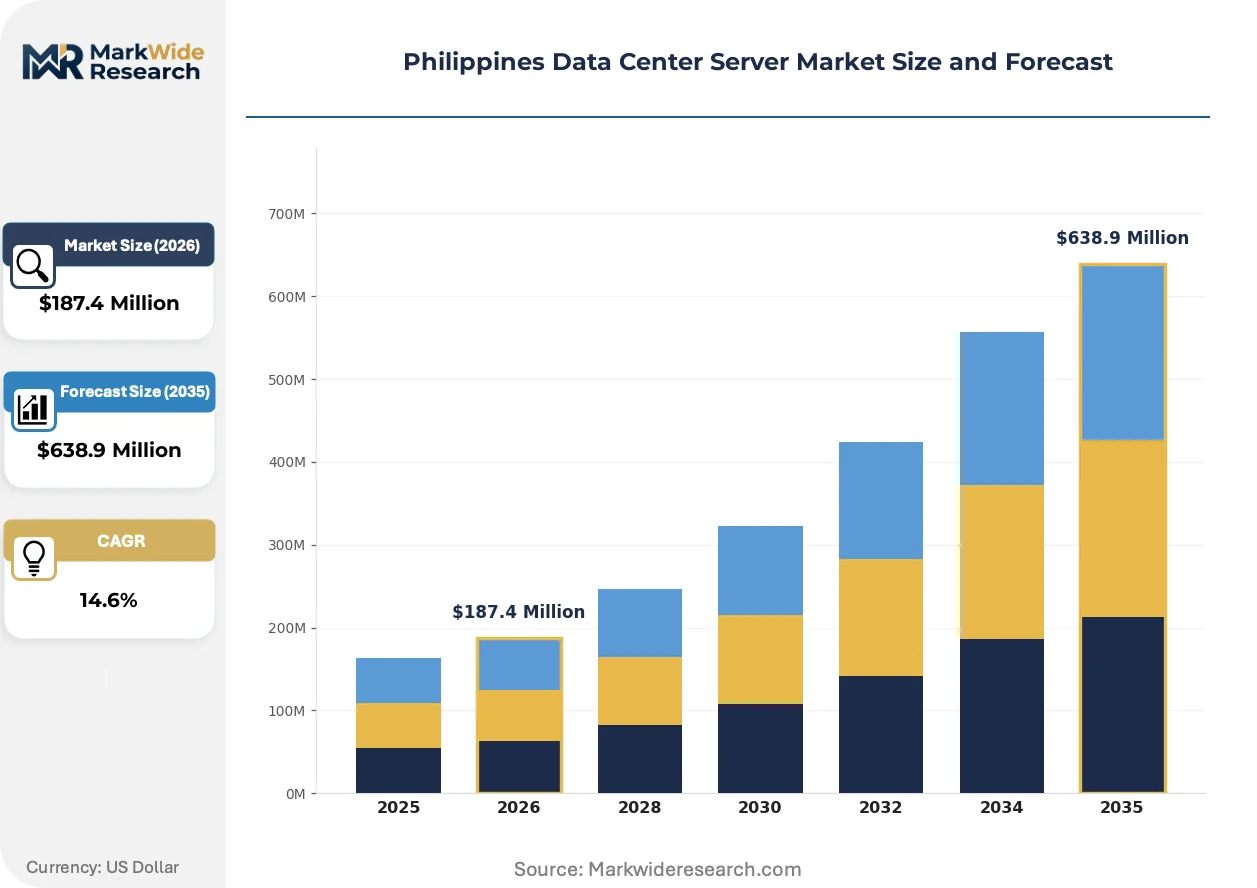
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blade Servers, Rack Servers, Tower Servers, Mainframe Servers End User: IT Services, Telecommunications, Government, Financial Services Installation: On-Premise, Colocation, Hybrid, Managed Service Type: Maintenance, Configuration, Cloud Services, Support |
| Companies Covered | HP Enterprise, Dell Inc., IBM Corporation, Fujitsu Limited, Huawei Technologies Co., Ltd., Lenovo Group Limited, Super Micro Computer, Inc., Oracle Corporation, Hitachi Asia Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Data Center Server Market Trends and Innovations
Liquid-cooled server architectures are displacing traditional air-cooled designs as the default specification for new hyperscale builds, while regulatory pressure on data localization accelerates sovereign infrastructure investment across Philippine economic zones.
Direct-to-chip liquid cooling is displacing perimeter CRAC units in rack densities above 30 kW. Hyperscalers deploying in Clark Freeport Zone are specifying cold plate and immersion variants for 100% of new capacity. This thermal architecture is displacing conventional raised-floor designs from procurement shortlists, compressing margins for air-cooled server specialists.
Bangko Sentral ng Pilipinas technology risk management guidelines are tightening data residency requirements for financial transaction processing. Banks must now maintain primary processing infrastructure within Philippine territory, with audit trails subject to central bank inspection. IT Services and Financial Services end users are responding by procuring sovereign-certified colocation space in Cavite and Laguna rather than regional hub alternatives.
Buyers are consolidating server procurement under long-term framework agreements with integrated facility operators. Channel partnerships with local systems integrators are losing share to direct hyperscale contracts. This concentration is most visible in Metro Manila, where BPO operators are bypassing traditional value-added resellers for volume commitments with campus developers offering bundled power, cooling, and compute.
Philippines Data Center Server Market Segmentation
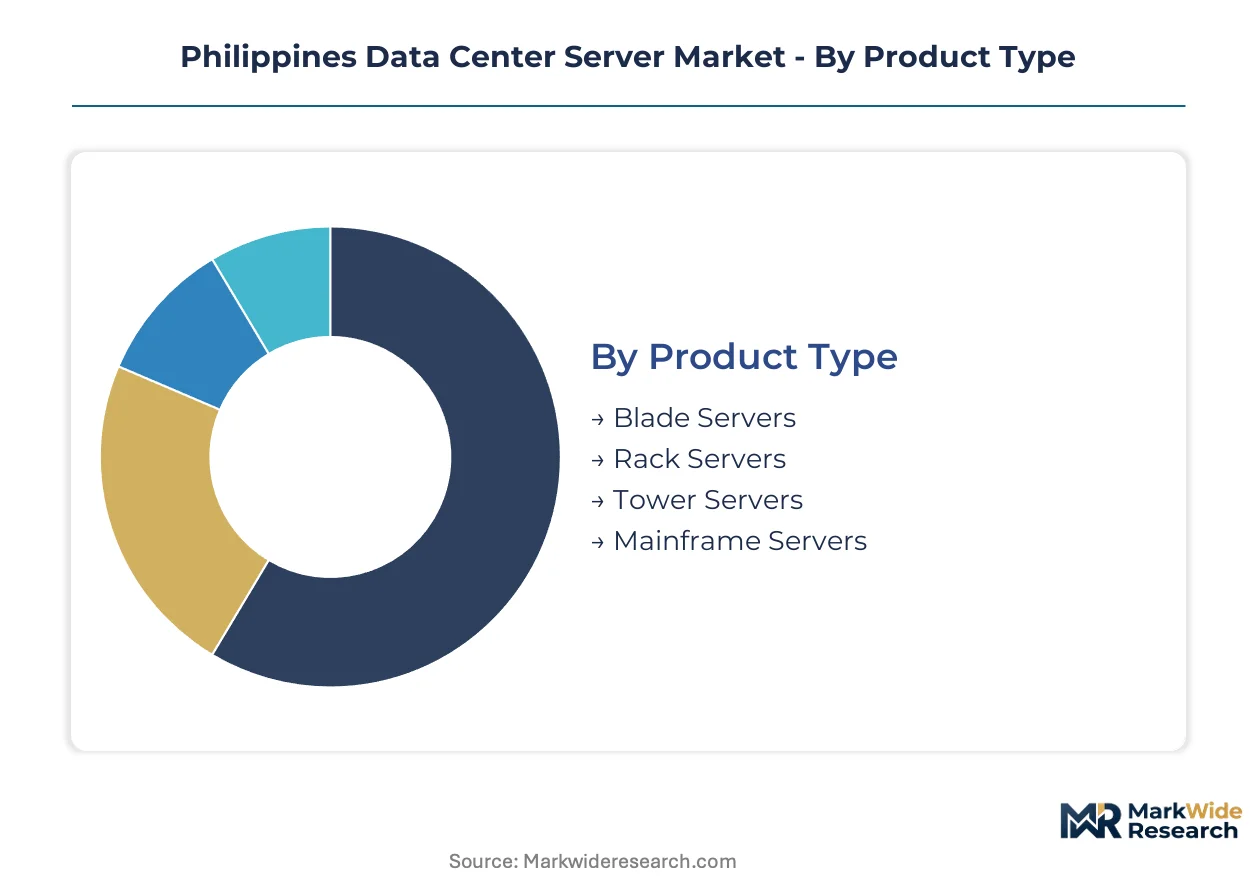
Server procurement patterns in the Philippines diverge sharply between hyperscale cloud operators and legacy enterprise buyers, with tropical climate constraints and sovereign data mandates reshaping how each segment sources compute infrastructure. Understanding these fault lines reveals where margin pools concentrate and which technical specifications command premium positioning.
Product Type:
Domestic demand concentrates on air-cooled rack configurations for BPO and banking verticals, while export-oriented hyperscale builds in Clark Freeport Zone specify liquid-cooled architectures engineered for tropical ambient conditions.
- Rack Servers:Standard 19-inch enclosures dominate procurement volumes among colocation providers expanding floor space in Cavite and Laguna. Filipino banks and fintech platforms specify these for real-time payment infrastructure mandated by Bangko Sentral ng Pilipinas technology risk management rules.
- Blade Servers:Space-efficient modular designs support high-throughput hyperscale deployments where compute density exceeds 30 kW per rack. Telecommunications operators procuring GPU-dense configurations for AI model training in Metro Manila corridors drive specification tightening.
- Tower Servers:Standalone vertical enclosures serve branch-office and small datacenter requirements in provincial banking networks outside Luzon's transmission backbone.
- Mainframe Servers:High-availability centralized systems process core banking workloads for established financial institutions maintaining legacy transaction architectures.
Rack Servers command the established base. The steepest expansion runs through Blade Servers.
End User:
Margin depth correlates directly with compliance burden and latency sensitivity, creating tiered pricing power across customer archetypes.
- Financial Services:Banks and insurance carriers operate under Bangko Sentral ng Pilipinas data residency mandates requiring primary processing infrastructure within Philippine territory. Compliance-driven refresh cycles and uptime guarantees during hardware migration extend procurement decision cycles.
- IT Services:BPO operators and systems integrators represent the deepest volume pool, consolidating server procurement under long-term framework agreements with integrated facility operators in Clark and Cavite corridors.
- Telecommunications:PLDT, Globe, and DITO Telecommunity procure GPU-dense rack configurations for edge inference and centralized AI model development.
- Government:National Privacy Commission critical information infrastructure designations under review could reserve server procurement for domestic-registered operators serving sovereign cloud mandates.
IT Services commands the established base. Financial Services exhibits the steepest margin expansion.
Installation:
Deployment model selection tracks power grid reliability and specialized engineering talent availability, with provincial expansion constrained by diesel generator redundancy requirements.
- Colocation:Third-party facility operators in Metro Manila's Clark and Cavite corridors bundle power, cooling, and compute under long-term volume commitments. Hyperscalers bypass traditional value-added resellers for direct campus developer contracts.
- On-Premise:Enterprise-owned facilities persist among financial services institutions requiring audit trail control for central bank inspection.
- Hybrid:Split workloads between owned infrastructure and colocation balance sovereignty requirements with capital efficiency.
- Managed:Outsourced operations and maintenance contracts address datacenter engineering talent scarcity concentrated in Metro Manila.
Colocation commands the established base. Hybrid deployments are climbing the fastest.
Service Type:
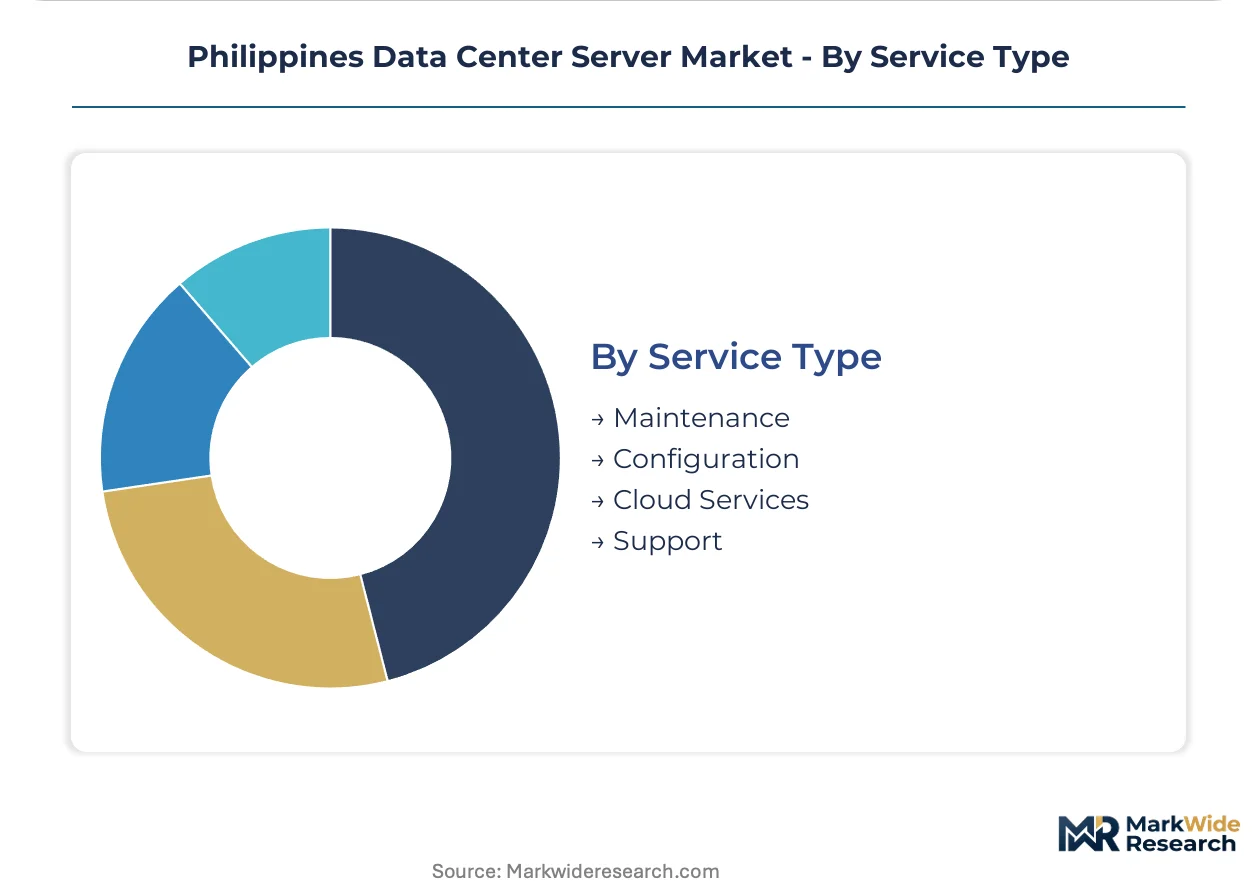
Revenue attachment rates vary by installation complexity and compliance certification requirements, with tropical climate conditions elevating maintenance premiums.
- Maintenance:Preventive and corrective service contracts sustain uptime above 99.99% in high-humidity Cavite operating environments.
- Configuration:Initial deployment and optimization services for liquid-cooled and air-cooled architectures.
- Cloud Services:Sovereign cloud instance provisioning for government agencies under National Broadband Plan subsidy flows.
- Support:Technical assistance and warranty extensions for BIS electromagnetic compatibility certified equipment.
Maintenance commands the established base. Cloud Services is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-sensitive provincial banking networks outside Luzon prioritize diesel generator redundancy over advanced cooling specifications, while Metro Manila hyperscalers absorb premium liquid-cooled premiums without volume elasticity.
Metro Manila
BPO operators and financial institutions dominate server procurement in the capital region, consolidating under long-term framework agreements with integrated facility operators. Bangko Sentral ng Pilipinas technology risk management rules mandate primary processing infrastructure within Philippine territory for audit trail compliance. Clark Freeport Zone and Cavite corridors concentrate hyperscale campus development with bundled power, cooling, and compute contracts.
Central Luzon
Subic Bay Freeport Zone offers unused naval infrastructure with submarine cable landing proximity and tax incentives for hyperscale expansion. The Department of Information and Communications Technology directs National Broadband Plan subsidy flows toward domestic cloud infrastructure buildout in this corridor. Liquid-cooled server deployments exceed 30 kW per rack density as telecommunications operators procure GPU-dense configurations for AI model training.
Calabarzon
Laguna and Cavite provinces host colocation providers expanding floor space with air-cooled rack configurations for BPO verticals. High-humidity ambient conditions drive immersion cooling convergence with dielectric fluid systems to reduce mechanical cooling load. Diesel generator redundancy requirements inflate total cost of ownership for facilities outside Luzon's transmission backbone.
Visayas
Provincial banking networks in Cebu and Iloilo maintain tower server deployments for branch-office transaction processing with limited high-density compute requirements. Power grid instability constrains hyperscale interest, extending refresh cycles for legacy enterprise infrastructure. Local systems integrators serve compliance-driven maintenance contracts sustaining uptime above 99.99%.
Mindanao
DITO Telecommunity and regional telecommunications operators drive modest GPU-dense rack procurement for edge inference in Davao and Cagayan de Oro. Datacenter engineering talent scarcity concentrates specialized skills in Metro Manila, constraining provincial expansion timelines. Sovereign cloud mandates under National Privacy Commission review could reserve future server procurement for domestic-registered operators.
Philippines Data Center Server Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Philippine data center server market. Hyperscale-ready builders with liquid-cooled expertise command premium positioning in Clark Freeport Zone, while legacy enterprise vendors compete on channel depth and local systems integrator relationships. Three archetypes dominate: tropical-optimized thermal specialists, global supply-scale multinationals, and channel-anchored domestic integrators. Competitive moves concentrate on direct hyperscale contracts bypassing traditional value-added resellers, and strategic partnerships with facility operators bundling power, cooling, and compute.
Within the global supply-scale tier, HP Enterprise and Dell Inc. occupy positions serving multinational cloud operators and BPO verticals respectively. Super Micro Computer, Inc. exemplifies the tropical-optimized specialist archetype with liquid-cooled architectures engineered for high-humidity ambient conditions. These three companies represent the competitive fault lines between hyperscale-direct procurement and channel-mediated enterprise sales.
| Leading Market Players |
|---|
| HP Enterprise |
| Dell Inc. |
| IBM Corporation |
| Fujitsu Limited |
| Huawei Technologies Co., Ltd. |
| Lenovo Group Limited |
| Super Micro Computer, Inc. |
| Oracle Corporation |
| Hitachi Asia Ltd. |
| Others |
Pricing and Supply Chain Analysis
Ninety-day lead times for liquid-cooled server subsystems from concentrated East Asian manufacturing bases concentrate pricing power among hyperscale-ready builders while compressing margins for air-cooled specialists serving price-sensitive provincial banking networks. This inventory-to-supply dynamic forces procurement officers to choose between premium thermal architectures for Clark Freeport Zone deployments or diesel-generator-burdened total cost of ownership for facilities outside Luzon's transmission backbone.
Pricing Analysis
Maintenance and extended service contracts drive lifetime value capture for server vendors serving Bangko Sentral ng Pilipinas compliance mandates. Pricing stratifies across liquid-cooled premium tiers for hyperscalers, standard air-cooled configurations for BPO operators, and economy tower deployments for provincial branch offices. Cost compression in the standard tier intensifies as channel partnerships with local systems integrators lose share to direct hyperscale contracts. Provincial banking networks exhibit highest price sensitivity due to diesel redundancy requirements, while hyperscalers in Metro Manila corridors absorb premium thermal specifications without volume elasticity.
Supply Chain Analysis
Strait of Malacca transit underwrites liquid-cooled component flows from Taiwan, South Korea, and Japan into Philippine economic zones. Cold plate assemblies, dielectric fluids, and GPU-dense rack configurations draw from concentrated East Asian manufacturing bases. Single-source vulnerability in advanced cooling subsystems exposes buyers to shipping cost volatility and customs clearance friction at the Port of Manila. Distribution runs through direct hyperscale contracts with integrated facility operators, bypassing traditional value-added resellers in Clark and Cavite corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity opens as sovereign cloud mandates and tropical thermal requirements split procurement patterns between hyperscale-direct and channel-mediated enterprise sales. Compliance-driven refresh cycles for financial services create defendable niches for vendors with Bangko Sentral ng Pilipinas certification pathways.
For Market Incumbents: Fortify channel control in Cavite and Laguna corridors by deepening partnerships with local systems integrators serving BPO verticals. Invest in BIS electromagnetic compatibility certification to filter import eligibility for non-compliant challengers. Anchor position through long-term framework agreements with integrated facility operators bundling power, cooling, and compute. For New Entrants and Emerging Players: Differentiate on immersion cooling convergence with tropical ambient design for high-humidity Cavite operating environments. Target provincial banking networks in Visayas and Mindanao where datacenter engineering talent scarcity constrains incumbent expansion timelines. Pursue managed services contracts addressing specialized skills gaps outside Metro Manila. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational server vendors divesting non-core air-cooled product lines under margin pressure from liquid-cooled hyperscale specifications. Long-term viability centers on tropical-optimized thermal expertise and sovereign certification capabilities. Watch National Privacy Commission critical information infrastructure designations as inflection signal for domestic-registered operator requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Hyperscale Contracting | Bypasses traditional resellers for bundled power-cooling-compute agreements with Clark campus developers. |
| Liquid-Cooled Architecture Investment | Captures premium positioning as 30+ kW rack densities displace air-cooled designs from procurement shortlists. |
| Sovereign Cloud Certification | Secures eligibility for National Broadband Plan subsidy flows and potential domestic-registered operator mandates. |
| Provincial Distribution Partnership | Addresses diesel generator redundancy requirements and talent scarcity constraining expansion outside Luzon. |
| Immersion Cooling Integration | Reduces mechanical cooling load in Cavite's high-humidity climate through dielectric fluid system deployment. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of hyperscaler capex disclosures, BIS certification databases, and Department of Information and Communications Technology policy filings. Interviews with data center facility operators, server procurement officers at BPO operators, thermal engineering specialists, and Bangko Sentral ng Pilipinas technology risk management officials combined with bottom-up shipment tracking and top-down infrastructure investment analysis.
Segmentation dimensions modeled include product type, end user vertical, installation model, and service attachment across the projection horizon. CAGRs were derived from triangulating vendor shipment data, facility expansion announcements, and regulatory compliance timeline assumptions. Tropical climate constraints and sovereign data localization mandates served as scenario-weighting inputs.
The analysis sits within stated boundaries; outcomes outside National Broadband Plan subsidy continuity or stable Strait of Malacca logistics corridors would require recalibration. Practitioners should keep alternative scenarios live as National Privacy Commission critical infrastructure designations and Bangko Sentral ng Pilipinas audit trail requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Global Data Colocation Market
Data Center Infrastructure
China Data Center Market
Data Center Infrastructure
Virtualized Data Center Market
Data Center Infrastructure
Data Center Transformation Market
Data Center Infrastructure
Server Station Market
Data Center Infrastructure
Malaysia Data Center Power Market
Data Center Infrastructure
Brazil Data Center Rack Market
Data Center Infrastructure
Composable Infrastructure Market
Data Center Infrastructure
Paris Data Center Market
Data Center Infrastructure
North America Green Data Center Market
Data Center Infrastructure
Spain Data Center Market
Data Center Infrastructure
Hong Kong Data Center Power Market
Data Center Infrastructure
Germany Data Center Power Market
Data Center Infrastructure
Mumbai Data Center Market
Data Center Infrastructure
GCC Data Center Market
Data Center Infrastructure
Saudi Arabia Data Center Market