
 Sweden Data Center Power Market | 2026-2036
Sweden Data Center Power Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden Data Center Power Market Insights
Hyperscale cloud deployments are recalibrating the buyer landscape as telecom providers cede share to IT companies and financial institutions building captive capacity. ABB Ltd leverages its Nordic grid integration heritage to dominate medium-voltage power distribution for greenfield campuses. Schneider Electric SE anchors the uninterruptible power supply segment through localized manufacturing and channel control across the Mälardalen region. Vertiv Group Corp. differentiates on thermal management integration, positioning its liquid cooling portfolios for direct-to-chip architectures in high-density halls.
Sweden data center power encompasses the generation, conditioning, distribution, and backup infrastructure that delivers continuous electrical energy to server halls, typically operating at 400/230 V three-phase with power usage effectiveness targets below 1.2 for new builds. The primary purpose centers on eliminating downtime while maximizing energy conversion efficiency from renewable sources to silicon loads. Renewable energy power sources lead structural investment as developers pursue 24/7 carbon-free matching under corporate sustainability commitments. Liquid cooling represents the fastest-growing thermal category, displacing air systems above 30 kW per rack. N+2 and 2N redundancy levels command premium pricing as financial institutions and healthcare facilities demand contractual uptime guarantees exceeding 99.999 percent.
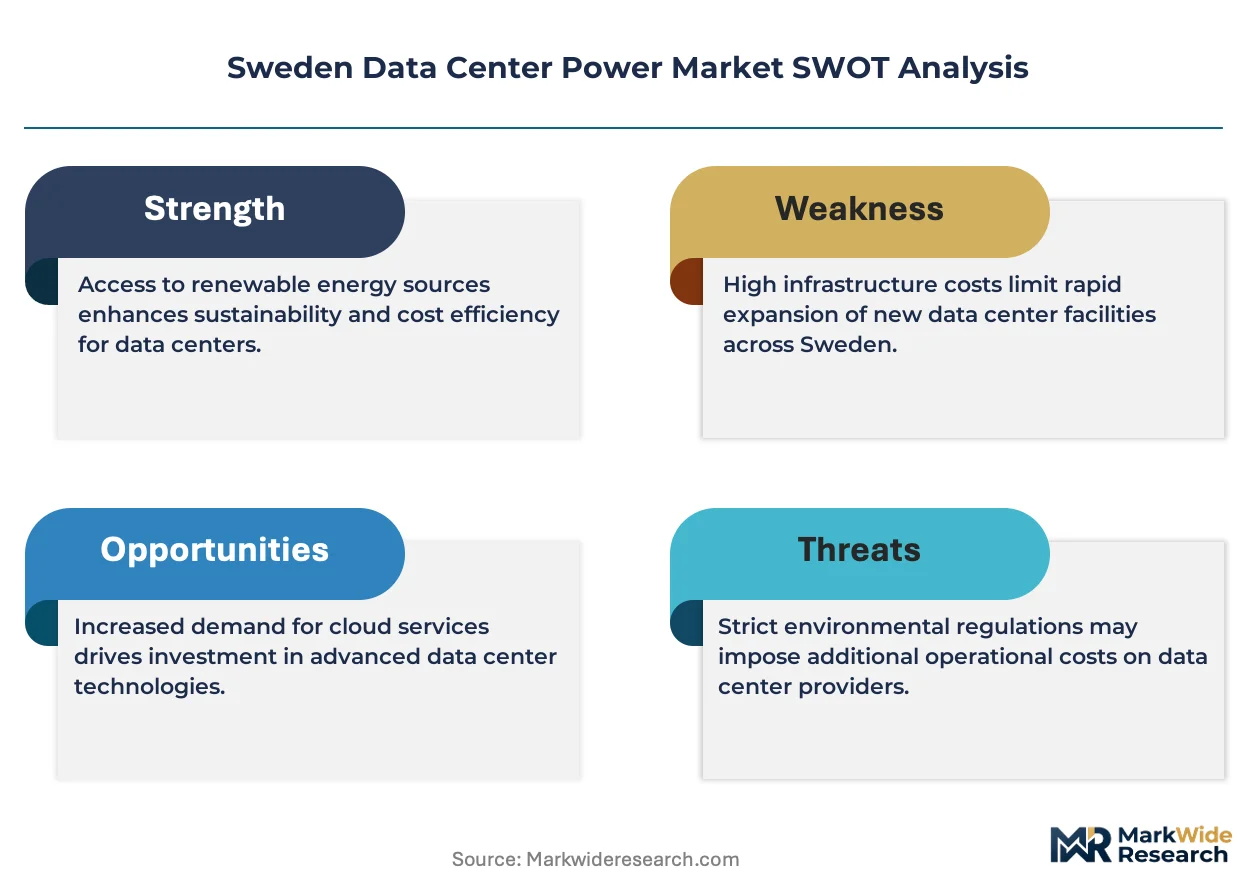
The Swedish Environmental Protection Agency enforces site-specific environmental permits that mandate waste heat recovery and limit diesel generator runtime, reshaping backup power architecture toward battery-hybrid designs. BIS-aligned electrical safety standards and EU Energy Efficiency Directive compliance requirements filter market access to vendors with certified European component traceability. The Swedish Energy Agency's capacity allocation rules for grid connection queue priority favor projects with firm renewable supply contracts, compressing timelines for developers without advance power purchase agreements. Stakeholders must monitor grid interconnection queue dynamics and district heating partnership terms to secure viable project economics.
Market Dynamics
Hyperscale cloud operators are compressing procurement cycles and mandating 24/7 carbon-free energy matching, forcing power infrastructure vendors to pre-certify equipment for Swedish grid codes and district heat recovery integration before qualification.
Growth Catalysts
- Swedish Environmental Protection Agency carbon-neutrality mandates:New facility permits require verified renewable supply and waste heat utilization, accelerating battery-hybrid backup adoption over diesel architectures.
- Liquid cooling systems:Direct-to-chip thermal management is displacing air systems above 30 kW per rack, enabling higher server density in Stockholm-Uppsala corridor builds.
- Stockholm-Uppsala corridor:Concentrated hyperscale clustering creates economies of scale for medium-voltage substation sharing and pooled renewable procurement.
Market Restraints
- Grid interconnection queue priority rules:The Swedish Energy Agency's capacity allocation favors projects with firm renewable supply contracts, compressing timelines for developers without advance power purchase agreements.
- Copper and rare earth magnet volatility:Medium-voltage transformer and high-efficiency motor costs fluctuate with commodity markets, pressuring fixed-price EPC contracts.
- N+2 redundancy capex premium:Financial institutions demanding 99.999 percent uptime contractual guarantees face 40-60 percent infrastructure cost premiums versus N+1 designs.
Strategic Opportunities
- Luleå data center cluster expansion:Northern Norrland's abundant hydropower and sub-Arctic cooling conditions offer untapped greenfield capacity for AI training workloads.
- District heating network partnerships:Waste heat recovery integration with municipal utilities creates secondary revenue streams and streamlines environmental permitting.
- Battery-hybrid plus fuel cell convergence:Solid-oxide fuel cells paired with lithium-ion buffers offer path to zero-diesel backup under tightening Swedish Environmental Protection Agency runtime limits.
Industry Challenges
- Medium-voltage power electronics specialization:Shortage of engineers qualified in 10-36 kV data center substation design extends project staffing timelines and inflates labor rates.
- BIS-aligned electrical safety certification:European component traceability requirements filter market access, delaying vendor qualification by 6-12 months for non-EU suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden Data Center Power Market |
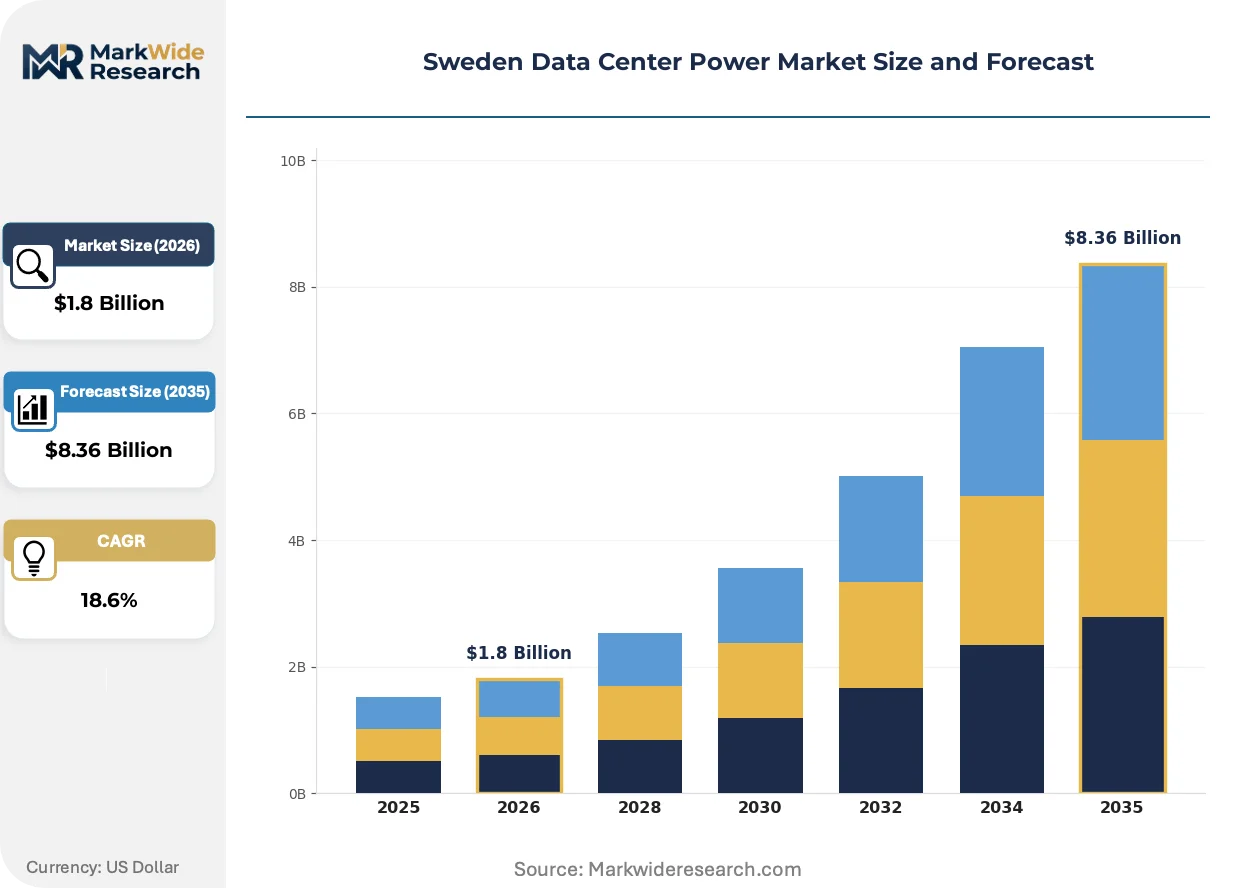
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Source: Renewable Energy, Grid Connection, Backup Generator, Uninterruptible Power Supply Cooling Technology: Air Cooling, Liquid Cooling, Hybrid Cooling, Evaporative Cooling End User: Telecom Providers, IT Companies, Financial Institutions, Healthcare Facilities Redundancy Level: N+1, N+2, 2N, 1+1 |
| Companies Covered | ABB Ltd, Schneider Electric SE, Vertiv Group Corp., Eaton Corp. plc, Cummins Inc., Hitachi Energy, FläktGroup, Socomec, Riello UPS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden Data Center Power Market Trends and Innovations
Liquid cooling architectures and battery-hybrid backup systems are reconfiguring power infrastructure specifications, while procurement models shift toward integrated energy-as-a-service contracts that bundle renewable supply with facility operations.
Direct-to-chip liquid cooling is integrating with medium-voltage power distribution to eliminate intermediate conversion losses. Hyperscale operators in the Stockholm-Uppsala corridor are specifying integrated thermal-electrical designs that route coolant and power through common busway infrastructure. This convergence is compressing vendor qualification lists to suppliers with certified combined offerings.
The Swedish Environmental Protection Agency's site-specific environmental permits mandate waste heat recovery and limit diesel generator runtime hours. Facility developers must now pre-negotiate district heating offtake agreements before construction permits issue. Northern Norrland clusters face particular scrutiny due to proximity to sensitive boreal forest ecosystems.
Enterprise buyers are consolidating vendor relationships under long-term power purchase agreements that bundle renewable supply, backup capacity, and thermal management. Financial institutions building captive capacity in Stockholm prefer single-counterparty contracts over fragmented equipment procurement. This concentration is visible in the Mälardalen region where three hyperscale operators now account for the majority of new substation interconnection requests.
Sweden Data Center Power Market Segmentation
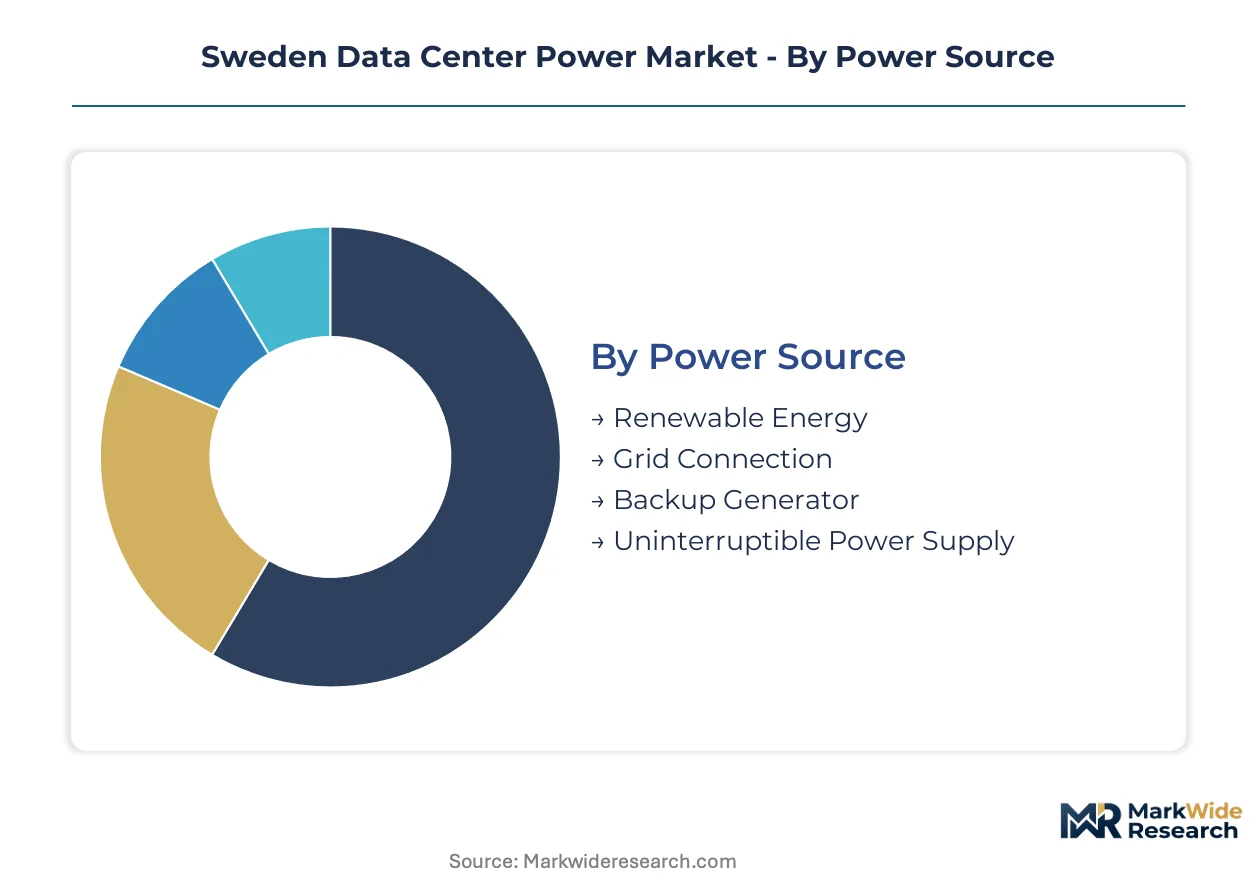
Power infrastructure segmentation in Sweden reflects the tension between hyperscale efficiency mandates and institutional uptime requirements. Each dimension shapes procurement patterns, vendor qualification, and project economics across Stockholm-Uppsala corridor builds and northern Norrland clusters.
Power Source:
Upgrade cycles for primary power infrastructure are accelerating as hyperscale operators replace legacy diesel architectures with battery-hybrid and renewable-matched systems.
- Renewable Energy:Hydropower purchase agreements dominate procurement, with developers securing 24/7 carbon-free matching through Swedish Energy Agency queue priority rules. Stockholm-Uppsala corridor projects cluster around pooled renewable procurement to compress interconnection timelines.
- Grid Connection:Medium-voltage substations at 10-36 kV integrate directly with Nordic grid codes, requiring pre-certified equipment for district heat recovery compatibility. Norrland clusters leverage abundant hydropower proximity to bypass transmission congestion.
- Backup Generator:Diesel runtime faces Swedish Environmental Protection Agency limits, restricting deployment to emergency-only scenarios. Battery-hybrid designs are displacing conventional gensets in new permits.
- Uninterruptible Power Supply:Lithium-ion buffers with solid-oxide fuel cell pairing offer path to zero-diesel backup under tightening environmental mandates.
Renewable Energy sits at the top of the volume ranking, with Backup Generator retrofit demand climbing the fastest as operators race to comply with runtime restrictions.
Cooling Technology:
Application requirements stratify sharply between AI training halls exceeding 30 kW per rack and enterprise workloads tolerating air-cooled densities.
- Liquid Cooling:Direct-to-chip architectures eliminate intermediate thermal losses, integrating coolant and power through common busway infrastructure. Hyperscale operators in Stockholm-Uppsala corridor specify combined thermal-electrical designs from qualified vendors.
- Air Cooling:Legacy enterprise facilities and sub-20 kW racks retain conventional precision HVAC, though retrofit demand is flattening as density requirements rise.
- Hybrid Cooling:Mixed environments combine liquid loops for high-density zones with air handling for standard racks, optimizing capital allocation across heterogeneous workloads.
- Evaporative Cooling:Sub-Arctic conditions in Luleå clusters enable free cooling economics, reducing mechanical refrigeration dependency for seasonal workload bursts.
Liquid Cooling commands premium pricing tiers, while Evaporative Cooling gains share fastest in greenfield northern developments.
End User:
Customer type determines redundancy specifications, contract structures, and vendor consolidation patterns across the procurement landscape.
- IT Companies:Hyperscale cloud operators compress vendor lists to single-counterparty agreements bundling renewable supply, backup capacity, and thermal management. Three operators now account for the majority of new substation interconnection requests in Mälardalen.
- Financial Institutions:Captive capacity builds in Stockholm demand 99.999 percent uptime guarantees with N+2 redundancy premiums, favoring integrated procurement over fragmented equipment sourcing.
- Telecom Providers:Legacy colocation operators are ceding share to cloud and financial buyers, with power infrastructure spend concentrating in wholesale leasing rather than owned builds.
- Healthcare Facilities:Regulatory compliance drives redundant architecture investment, though project scale remains smaller than hyperscale or financial deployments.
IT Companies anchor procurement volume, with Financial Institutions expanding most quickly as captive builds accelerate.
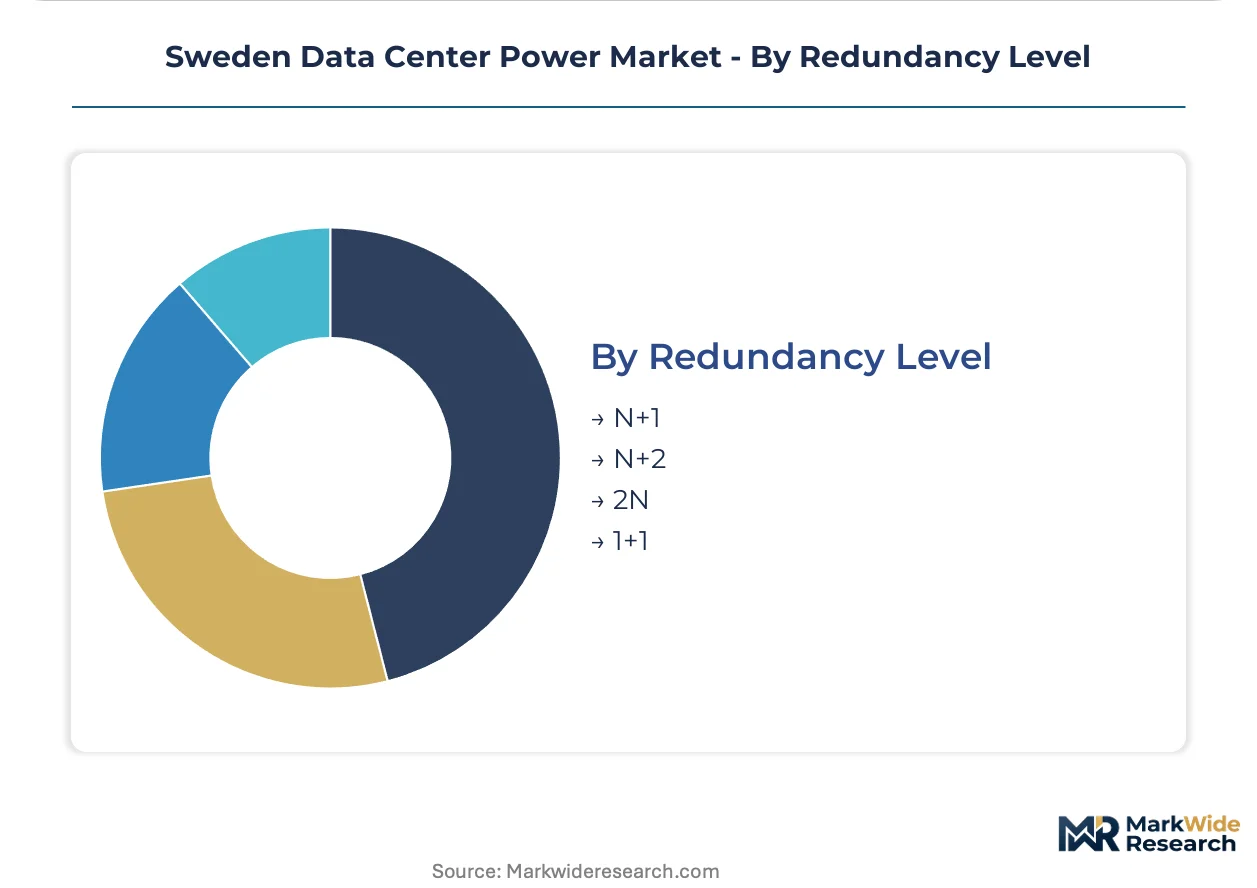
Redundancy Level:
Margin structures diverge dramatically across tiers, with premium uptime specifications commanding 40-60 percent infrastructure cost premiums.
- N+2:Parallel redundant paths with dual independent failure tolerance support financial trading floors and healthcare critical systems. Swedish Environmental Protection Agency permits for N+2 facilities require pre-negotiated district heating offtake agreements.
- 2N:Fully duplicated infrastructure delivers highest availability for payment processing and core banking platforms, with capital intensity limiting deployment to revenue-critical workloads.
- N+1:Single redundant component coverage serves standard enterprise cloud and development environments, balancing cost against acceptable downtime windows.
- 1+1:Active-active configurations for specific subsystems optimize utilization while maintaining failover capability for less critical applications.
N+1 retains the broadest installed base, with N+2 posting the steepest expansion trajectory as contractual uptime guarantees tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Stockholm-Uppsala corridor anchors Sweden's data center power infrastructure expansion, with hyperscale operators clustering around pooled renewable procurement and shared medium-voltage substation architectures.
Stockholm-Uppsala Corridor
Hyperscale cloud deployments and financial institution captive builds drive concentrated demand for N+2 redundancy and liquid cooling integration. The Swedish Environmental Protection Agency mandates waste heat recovery and carbon-neutral energy matching for all new facility permits. ABB Ltd and Schneider Electric SE dominate medium-voltage power distribution contracts across this corridor's greenfield campuses.
Luleå and Northern Norrland
Sub-Arctic free cooling conditions and abundant hydropower proximity attract AI training workload investments with power usage effectiveness targets below 1.2. The Swedish Energy Agency's grid connection queue priority rules favor projects with firm renewable supply contracts in this region. Facebook's earlier establishment created a vendor ecosystem now serving expanding hyperscale demand in the Luleå cluster.
Gothenburg and Western Sweden
Enterprise colocation and maritime industry digitalization sustain steady demand for standard redundancy configurations. BIS-aligned electrical safety standards and EU Energy Efficiency Directive compliance requirements govern equipment certification for this market. Vertiv Group Corp. positions its thermal management portfolios for hybrid cooling environments in Gothenburg's enterprise facilities.
Malmö and Southern Sweden
Cross-border connectivity to continental European markets and Copenhagen proximity attract latency-sensitive workload deployments. District heating network integration requirements from municipal utilities shape backup power architecture toward battery-hybrid designs. Eaton Corp. plc and Cummins Inc. compete for UPS and generator retrofit contracts in Malmö's legacy facility upgrades.
Sweden Data Center Power Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors pre-certify integrated thermal-electrical offerings before hyperscale qualification. The market exhibits tiered concentration with three global electrical infrastructure groups controlling medium-voltage distribution, two specialized thermal management firms anchoring liquid cooling integration, and a fragmented tier of regional UPS and generator service providers. Equipment vendors pursue backward integration into district heating partnerships while EPC contractors deepen captive supply relationships with certified component fabricators.
Among Nordic-heritage electrical specialists, ABB Ltd represents the grid integration archetype through its legacy in 10-36 kV substation design. Schneider Electric SE exemplifies the localized manufacturing approach with channel control across the Mälardalen region. Vertiv Group Corp. occupies the thermal-electrical convergence position, anchoring liquid cooling portfolios for direct-to-chip architectures in high-density Stockholm-Uppsala builds.
| Leading Market Players |
|---|
| ABB Ltd |
| Schneider Electric SE |
| Vertiv Group Corp. |
| Eaton Corp. plc |
| Cummins Inc. |
| Hitachi Energy |
| FläktGroup |
| Socomec |
| Riello UPS |
| Others |
Pricing and Supply Chain Analysis
Backward integration into district heating partnerships anchors supply position and pricing power for power infrastructure vendors serving Swedish data center developments. Pre-certified equipment bundling under Swedish Environmental Protection Agency mandates compresses vendor lists and concentrates margin capture among qualified suppliers.
Pricing Analysis
Copper and rare earth magnet cost pass-through dominates medium-voltage transformer and high-efficiency motor pricing, with commodity volatility pressuring fixed-price EPC contracts. Pricing stratifies across N+2 redundancy premiums, liquid cooling integration tiers, and district heat recovery bundling levels. Cost compression in standard N+1 configurations is intensifying as hyperscale operators consolidate procurement volumes. Financial institutions building captive Stockholm capacity show lowest price sensitivity due to contractual uptime guarantee requirements.
Supply Chain Analysis
Single-source vulnerability sits with Chinese rare earth processing and German precision electrical component manufacturing for medium-voltage switchgear. Power distribution hardware draws from Swedish domestic fabrication, Finnish transformer winding, and Polish cable assembly operations. Supply chain risk centers on EU Energy Efficiency Directive compliance certification delays for non-EU component suppliers. Distribution runs through ABB Ltd and Schneider Electric SE channel networks across the Mälardalen region, with Vertiv Group Corp. handling thermal-electrical bundled shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Swedish data center power market functions as a regulatory compounder where Swedish Environmental Protection Agency carbon-neutrality mandates for new facility permits continuously reshape infrastructure specifications and procurement patterns.
For Market Incumbents: Cement grid interconnection queue priority by securing firm renewable supply contracts before competitor project submissions. Lock in district heating partnership exclusives with municipal utilities to streamline environmental permitting and block rival facility developments. Battery-hybrid backup specialization represents the critical R&D lever against diesel runtime restriction tightening. For New Entrants and Emerging Players: Capture Luleå cluster expansion demand for AI training workload power infrastructure where Facebook's vendor ecosystem presence lowers qualification barriers. Target solid-oxide fuel cell integration partnerships as the most penetrable white-space segment under Swedish Environmental Protection Agency runtime limits. Lead with thermal-electrical bundled offerings to bypass incumbent channel control in Stockholm-Uppsala corridor builds. For Investors and Strategic Acquirers: Roll-up economics work for Nordic-heritage electrical specialists with certified 10-36 kV substation design capabilities because medium-voltage power electronics engineering scarcity extends project timelines and inflates labor rates. Platform consolidation across UPS, thermal management, and renewable procurement bundling offers five-to-ten year viability as hyperscale operators compress vendor relationships. Watch grid interconnection queue dynamics as the primary inflection signal for project viability and equipment demand timing.| Strategic Initiative | Industry Significance |
|---|---|
| District Heating Partnership | Waste heat recovery integration with municipal utilities creates secondary revenue streams and streamlines Swedish Environmental Protection Agency permitting. |
| Battery-Hybrid Backup Deployment | Lithium-ion buffer systems with fuel cell pairing eliminate diesel runtime under tightening environmental mandates. |
| Liquid Cooling Integration | Direct-to-chip thermal management enables server densities above 30 kW per rack in Stockholm-Uppsala corridor builds. |
| Medium-Voltage Pre-Certification | Swedish grid code and district heat recovery compatibility qualification compresses vendor lists before hyperscale procurement cycles. |
| Renewable Supply Contracting | Firm power purchase agreements secure Swedish Energy Agency queue priority and accelerate interconnection timelines. |
Research Methodology
Direct dialogue with data center developers, EPC contractors, utility interconnection planners, and power infrastructure procurement officers grounded qualitative findings, validated against Swedish Energy Agency grid queue databases, EU Energy Efficiency Directive compliance filings, hyperscaler capex disclosures, and Nordic electrical equipment trade flows. Bottom-up project pipeline aggregation and top-down market sizing triangulated volume estimates across the analysis window.
Segmentation outputs reflect power source, cooling technology, end user, and redundancy level dimensions modeled throughout the forecast period, with CAGRs derived from project-level interconnection request trajectories and equipment procurement cycle compression rates. Hydropower purchase agreement volumes, liquid cooling adoption curves above 30 kW rack densities, and N+2 redundancy specification premiums informed projection calibration.
Swedish Environmental Protection Agency permit issuance delays, copper and rare earth commodity volatility, and grid interconnection queue priority rule changes are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions about hyperscale expansion pacing and district heating network partnership formation rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Brazil Data Center Rack Market
Data Center Infrastructure
Data Center Substation Market
Data Center Infrastructure
Asia-Pacific Hyperscale Data Center Market
Data Center Infrastructure
UAE Data Center Construction Market
Data Center Infrastructure
Italy Data Center Physical Security Market
Data Center Infrastructure
Europe Data Center Construction Market
Data Center Infrastructure
China Data Center Server Market
Data Center Infrastructure
Australia Data Center Rack Market
Data Center Infrastructure
Data Center Asset Management Market
Data Center Infrastructure
Smart Data Center Market
Data Center Infrastructure
South Africa Data Center Rack Market
Data Center Infrastructure
Middle East Data Center Physical Security Market
Data Center Infrastructure
Next Generation Data Center Market
Data Center Infrastructure
New Zealand Data Center Market
Data Center Infrastructure
Mumbai Data Center Market
Data Center Infrastructure
APAC Data Center Server Market