
 Global Data Center Rack and Enclosure Market | 2026-2036
Global Data Center Rack and Enclosure Market Size, Share, and Industry Trends Forecast 2026-2036
Global Data Center Rack and Enclosure Market Foresight
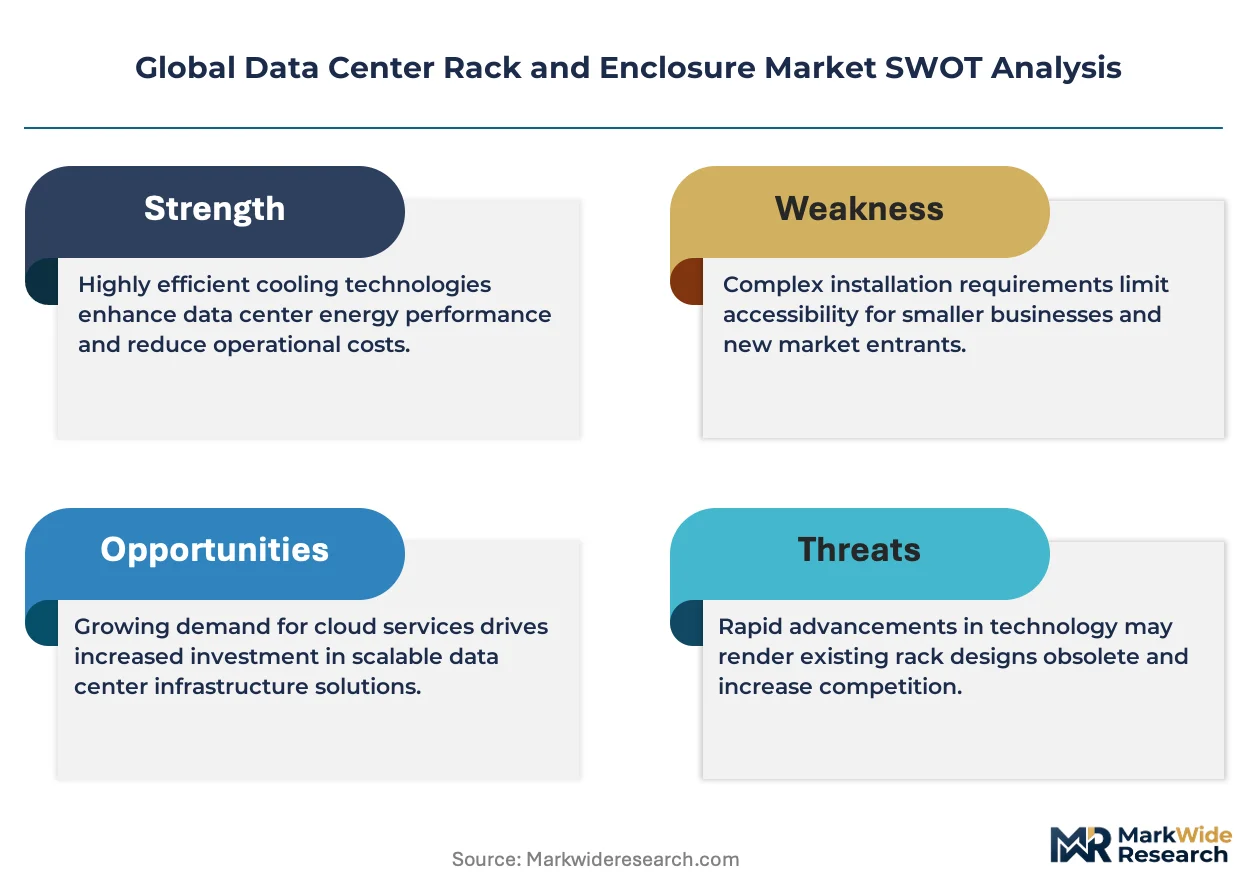
Buyer consolidation among hyperscale cloud operators is repositioning procurement leverage toward volume-contract frameworks. Schneider Electric leverages its integrated power and cooling portfolio to anchor large-scale deployment contracts. Vertiv competes through thermal management specialization that sustains premium positioning in high-density environments. Eaton differentiates via electrical infrastructure convergence, extending its reach beyond physical enclosures into power distribution units.
Data center racks and enclosures are engineered steel or aluminum frameworks designed to house, organize, and protect servers, networking equipment, and power infrastructure, typically conforming to 19-inch EIA standards for equipment mounting width. These structures incorporate cable management channels, grounding systems, and airflow baffles to maintain thermal stability and operational accessibility in mission-critical facilities. Rack cabinets dominate current revenue as the default specification for enterprise and hyperscale deployments, while open frame racks capture growing share in lab and development environments where cost sensitivity and rapid reconfiguration outweigh physical security requirements. Edge computing applications represent the fastest-expanding demand segment, driven by latency-sensitive workloads requiring distributed enclosure footprints closer to end users.
ISO 9001 quality management and IEC 61508 functional safety standards govern manufacturing consistency and electrical integration protocols for enclosure suppliers accessing multinational contracts. EPA Energy Star certification and EU Ecodesign Directive requirements are forcing thermal efficiency improvements that favor vendors with advanced airflow management and liquid-ready rack architectures. Stakeholders must monitor evolving carbon disclosure mandates under CSRD and emerging state-level efficiency regulations that will reshape supplier qualification criteria and retrofit obligations across installed base portfolios.
Market Dynamics
Hyperscale cloud operators are consolidating procurement power through multi-year volume frameworks, compressing supplier margins while demanding integrated thermal-electrical architectures that legacy vendors struggle to assemble.
Growth Catalysts
- Edge Computing Deployment:Latency-sensitive AI inference workloads are forcing rack installations into secondary cities and industrial zones, expanding addressable footprint beyond traditional hyperscale clusters.
- EU Ecodesign Directive:Thermal efficiency mandates for server and storage equipment are accelerating replacement cycles in European facilities, favoring liquid-ready rack architectures over air-cooled legacy stock.
- India PLI Scheme:Production-linked incentives for electronics manufacturing are attracting enclosure fabricators to establish domestic capacity, reducing import dependency for the country's data center buildout.
Market Restraints
- Steel and Aluminum Volatility:Input cost swings for cold-rolled steel and extruded aluminum profiles compress fabrication margins and complicate long-term contract pricing.
- China Supply Concentration:Sheet metal stamping and precision machining capacity clusters in Guangdong and Jiangsu provinces, exposing buyers to logistics disruption and tariff exposure.
- Air-Cooling Ceiling:Conventional forced-air thermal management hits physical limits above 30kW per rack, constraining deployment of next-generation GPU clusters without infrastructure overhaul.
Strategic Opportunities
- Sub-Saharan Africa:Underpenetrated data center infrastructure in Nigeria and Kenya offers first-mover positioning as submarine cable capacity expands and cloud demand localizes.
- Modular Edge Micro-Data Centers:Pre-integrated enclosure-power-cooling skids are capturing share in manufacturing and retail verticals requiring sub-100kW deployments with rapid commissioning.
- US IRA Clean Energy Credits:Tax incentives for energy-efficient equipment are improving project economics for thermal-optimized rack retrofits in enterprise colocation facilities.
Industry Challenges
- Thermal-Mechanical Integration:Converging liquid cooling plumbing with structural enclosure engineering demands cross-functional expertise scarce in traditional sheet metal fabricators.
- IEC 61508 Certification Timelines:Functional safety validation for power distribution integration extends product development cycles 8-14 months, delaying revenue recognition on integrated rack-PDU combinations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Data Center Rack and Enclosure Market |
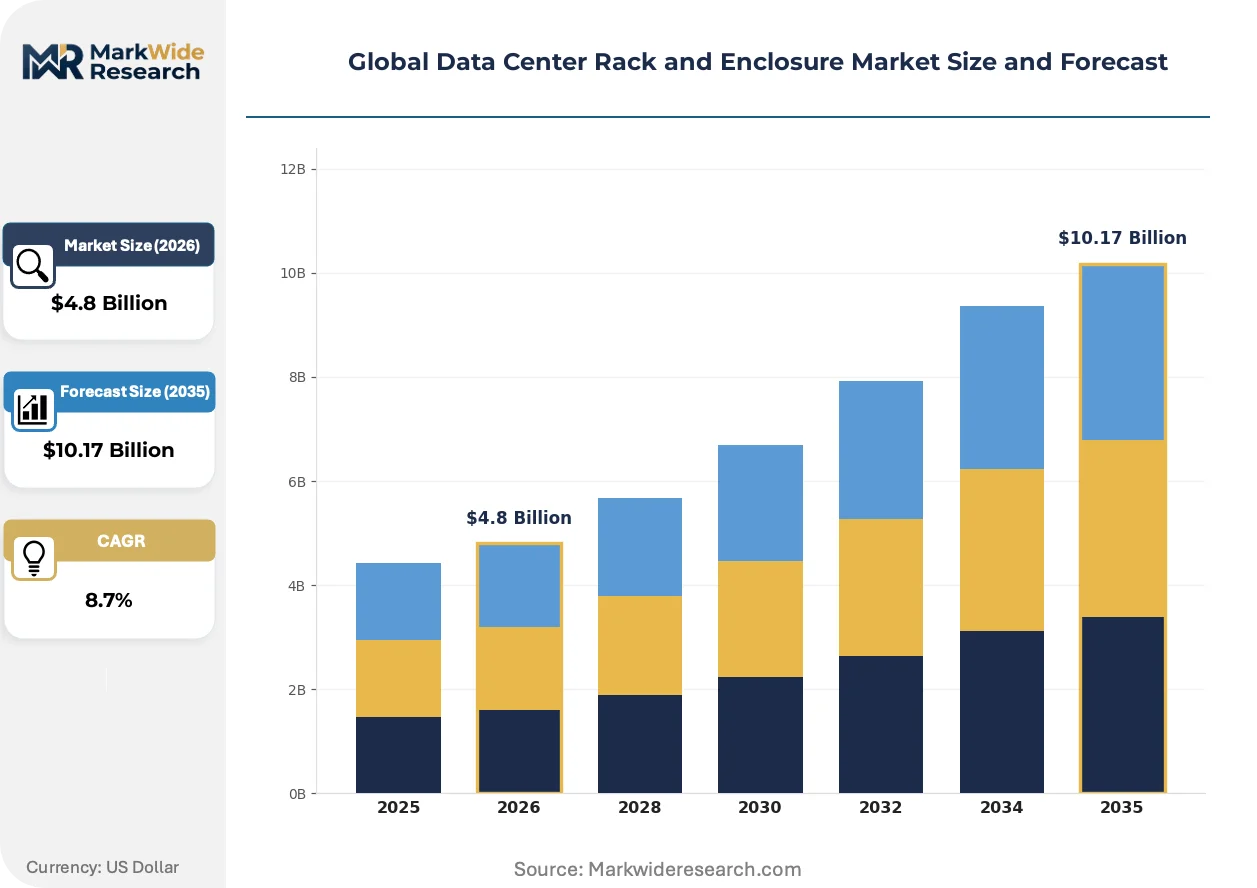
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rack Cabinets, Wall Mount Racks, Open Frame Racks, Enclosures Technology: Airflow Management, Power Distribution, Cable Management, Cooling Systems Application: Cloud Service Providers, Telecommunication, Colocation Facilities, Edge Computing End User: Data Center Operators, Managed Service Providers, Government Agencies, Research Institutions |
| Companies Covered | Schneider Electric, Vertiv, Eaton, Rittal, HPE, Fujitsu, Dell Technologies, Legrand, Panduit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Data Center Rack and Enclosure Market Shifts & Advancements
Liquid cooling infrastructure is overtaking conventional air management as the default specification for high-density deployments, rewiring supplier capabilities and buyer evaluation criteria simultaneously.
Direct-to-chip liquid cooling is overtaking rear-door heat exchangers as the thermal architecture of choice for AI training clusters. Hyperscale operators in the United States and Germany are specifying cold plate manifolds and coolant distribution units as standard rack subsystems. This shift is overtaking air-cooled designs in the 50-100kW density band, forcing enclosure vendors to engineer fluid sealing and quick-disconnect integration at scale.
The EU CSRD carbon disclosure mandate is tightening scope 3 reporting requirements for data center equipment suppliers. Enclosure manufacturers must now document embodied carbon in steel and aluminum inputs, driving sourcing shifts toward recycled content and regional fabrication. German and French operators are prioritizing vendors with verified Environmental Product Declarations, compressing qualification timelines for uncertified competitors.
Buyers are consolidating procurement through integrated infrastructure contracts that bundle racks, power distribution, and cooling into single-vendor frameworks. Colocation providers in India and the United States are abandoning component-level sourcing in favor of turnkey aisle deployments. This concentration is visible most acutely in hyperscale tenders, where electrical-mechanical-thermal integration capability outweighs standalone enclosure pricing.
Global Data Center Rack and Enclosure Market Segmentation
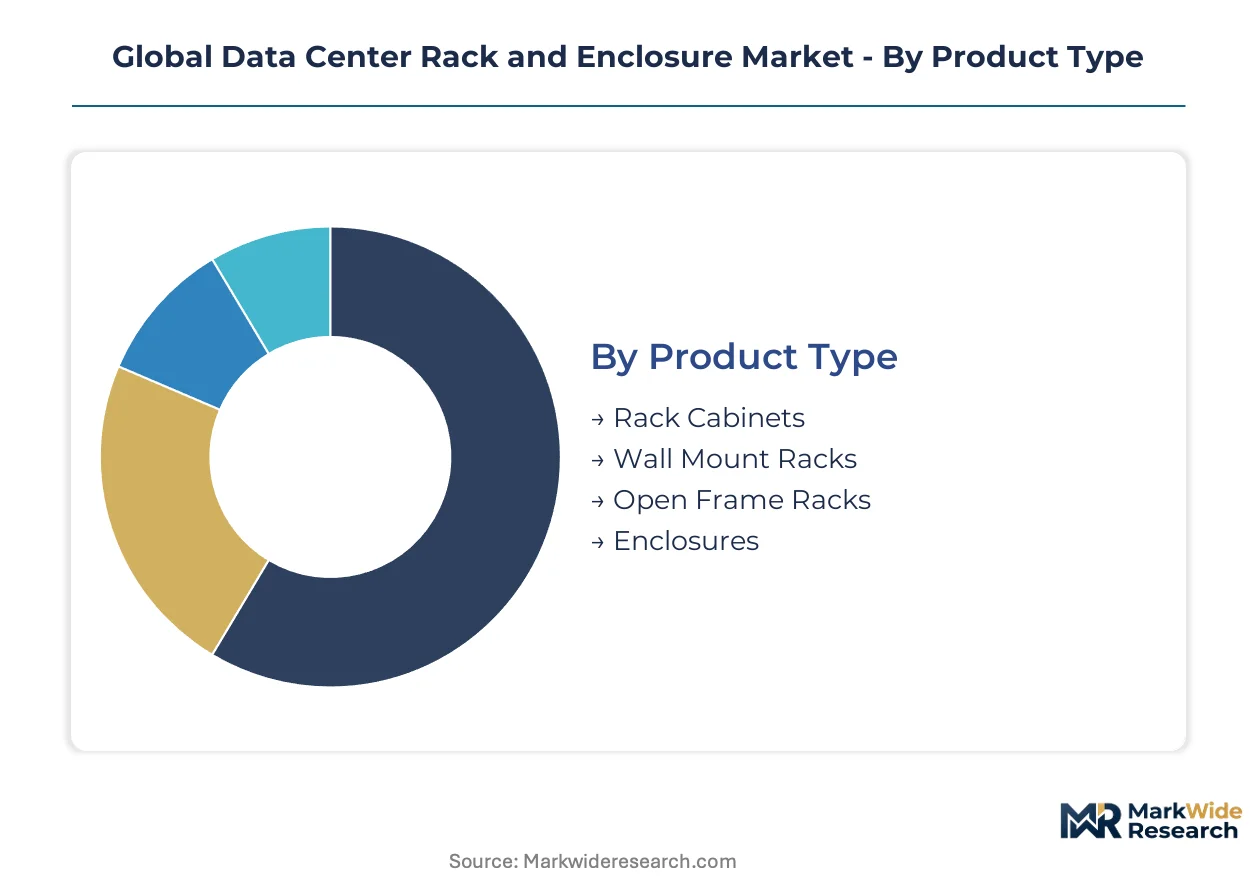
Segmentation in the data center rack and enclosure market reveals how procurement priorities diverge across deployment scales and thermal densities. Buyers optimize for fundamentally different constraints when selecting infrastructure for hyperscale cloud campuses versus distributed edge nodes.
Product Type:
Capital intensity varies sharply across physical form factors, with integrated cabinet systems demanding the highest upfront engineering investment.
- Rack Cabinets:Fully enclosed steel or aluminum housings with integrated doors, side panels, and locking mechanisms. Cloud service providers in the United States and Germany specify these as the default for hyperscale deployments, driven by physical security requirements and thermal containment needs.
- Open Frame Racks:Four-post skeletal frameworks without enclosing panels, prioritizing airflow accessibility and rapid equipment swaps. Development environments and lab facilities across India favor these configurations where cost sensitivity outweighs security concerns.
- Wall Mount Racks:Compact hinged or fixed enclosures designed for network closets and constrained floorplates.
- Enclosures:Sealed protective housings for outdoor or harsh-environment deployments.
Rack cabinets absorb the bulk of installed capacity; open frame racks are expanding most quickly.
Technology:
Margin profiles diverge based on whether the technology layer involves passive mechanical components or active thermal-electrical systems.
- Cooling Systems:Liquid cooling manifolds, rear-door heat exchangers, and coolant distribution units integrated at rack level. AI training clusters in Germany and the United States now specify liquid-ready architectures as standard, displacing air-cooled designs above 30kW densities.
- Power Distribution:Rack-mounted PDUs, busbars, and intelligent power monitoring subsystems. Colocation facilities in India prioritize metered power distribution for tenant billing accuracy, accelerating integrated rack-PDU procurement.
- Airflow Management:Passive baffles, blanking panels, and containment systems for thermal optimization.
- Cable Management:Organized routing channels for power and data cabling within rack structures.
Cooling systems command the highest technology premiums; power distribution integration is climbing fastest as a procurement priority.
Application:
Volume concentration aligns with deployment scale, with the largest facility types driving standardization and the smallest requiring customization.
- Cloud Service Providers:Hyperscale operators deploying standardized rack configurations across multi-megawatt facilities. Amazon Web Services, Microsoft Azure, and Google Cloud facilities in the United States specify 48U-52U cabinets with integrated busway connections, compressing supplier margins through multi-year volume frameworks.
- Edge Computing:Distributed micro-data centers and cell tower enclosures positioned closer to end users. Latency-sensitive AI inference workloads are forcing rack installations into secondary cities across India and Germany, expanding addressable footprint beyond traditional clusters.
- Colocation Facilities:Multi-tenant data centers offering rack space and power to enterprise customers.
- Telecommunication:Central offices, mobile switching centers, and 5G infrastructure housing.
Cloud service providers absorb the bulk of installed capacity; edge computing is gaining share fastest.
End User:
Procurement sophistication varies by organizational technical depth and regulatory exposure.
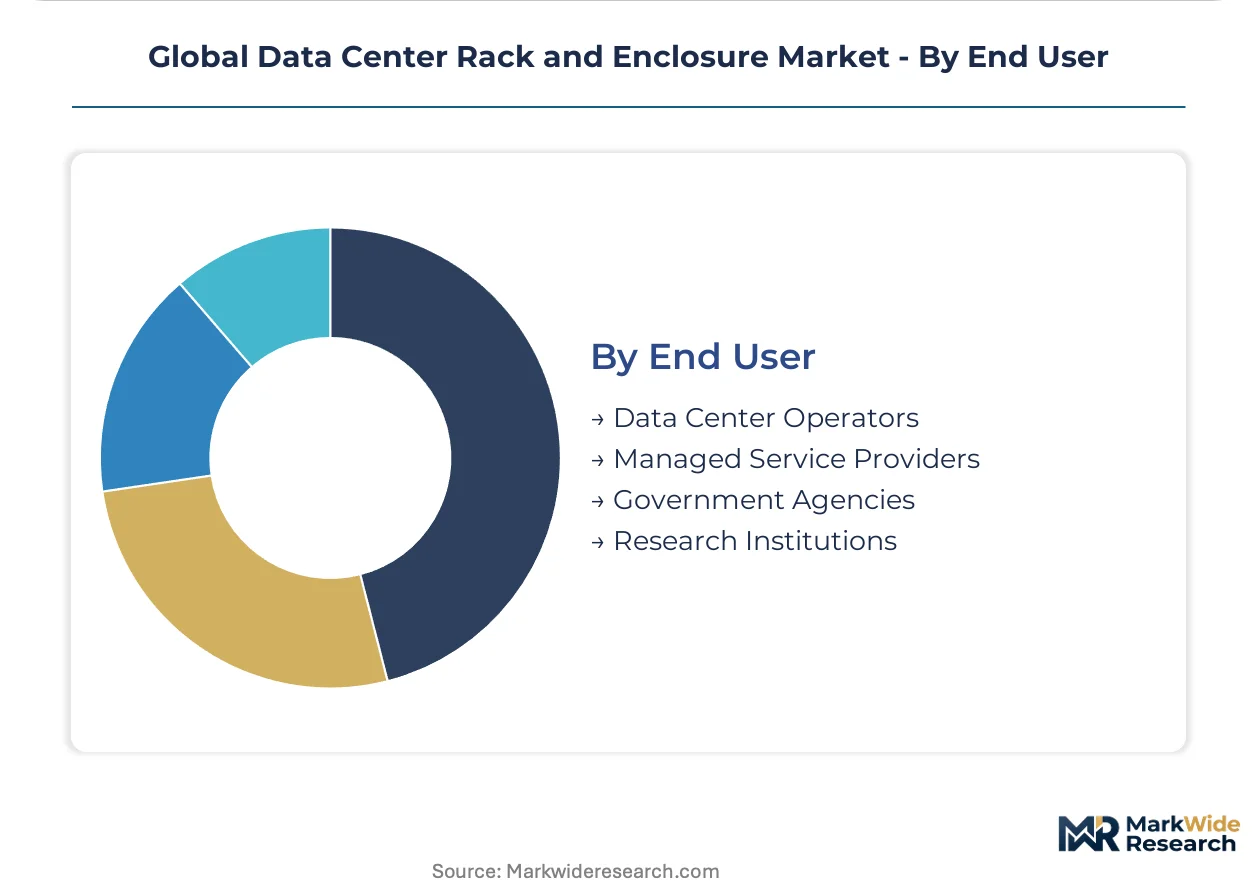
- Data Center Operators:Owner-operators of enterprise or hyperscale facilities managing full infrastructure stacks. Operators in Germany face EU CSRD carbon disclosure mandates requiring documented embodied carbon in steel and aluminum inputs, driving sourcing shifts toward recycled content.
- Government Agencies:Federal, state, and municipal entities with mission-critical security requirements. US federal data centers must comply with EPA Energy Star specifications and FISMA security protocols, restricting vendor qualification to certified suppliers.
- Managed Service Providers:Third-party operators delivering hosted IT services to enterprise clients.
- Research Institutions:Universities and national laboratories running high-performance computing workloads.
Data center operators absorb the bulk of installed capacity; government agencies are expanding procurement most quickly under infrastructure modernization programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale cloud operators concentrate procurement leverage across the United States, Germany, and India, driving standardization in rack specifications while edge computing deployments expand into secondary metros.
United States
Amazon Web Services, Microsoft Azure, and Google Cloud dominate hyperscale rack procurement through multi-year volume frameworks. EPA Energy Star specifications and FISMA security protocols restrict vendor qualification to certified suppliers. Northern Virginia's Data Center Alley and Dallas-Fort Worth anchor the densest concentration of rack deployments, with liquid-ready architectures now standard above 50kW densities.
Germany
EU Ecodesign Directive thermal efficiency mandates accelerate replacement cycles in Frankfurt and Munich hyperscale clusters. The country's national regulator enforces CSRD carbon disclosure requirements that demand documented embodied carbon in steel and aluminum inputs. Berlin-Brandenburg and Bavaria host the primary fabrication facilities serving Central European cloud buildouts.
India
Production-linked incentives for electronics manufacturing attract enclosure fabricators to establish domestic capacity in Maharashtra and Karnataka. TRAI and CEA regulations govern power infrastructure integration standards for multi-tenant facilities. Mumbai and Chennai emerge as the dominant deployment clusters as cloud demand localizes for latency-sensitive workloads.
China
Sheet metal stamping and precision machining capacity clusters in Guangdong and Jiangsu provinces supply global fabrication demand. MIIT and GB standards govern structural and electrical integration protocols for domestic hyperscale operators. Beijing-Tianjin-Hebei and the Yangtze River Delta concentrate the majority of manufacturing output despite logistics disruption exposure.
United Kingdom
London and the Southeast anchor colocation rack demand driven by financial services latency requirements. CE marking and REACH compliance obligations filter supplier qualification for European market access. Slough and the London Docklands maintain the highest density of installed enclosure capacity outside Germany.
Global Data Center Rack and Enclosure Market Competitive Landscape
North American producers anchor one tier; European specialists hold premium positioning through thermal-electrical integration capabilities. The vendor base stratifies across three tiers: integrated infrastructure conglomerates, thermal management specialists, and regional sheet metal fabricators. Strategic archetypes include full-stack power-cooling-rack integrators, liquid cooling subsystem specialists, and volume-scale commodity suppliers. Competitive moves concentrate on M&A for thermal-electrical convergence and capacity expansion into India under PLI incentives.
Among the integrated infrastructure tier, Schneider Electric, Vertiv, and Eaton occupy distinct positioning vectors. Schneider Electric exemplifies the full-stack archetype through its combined power and cooling portfolio. Vertiv represents thermal management specialization that sustains premium positioning in high-density environments. Eaton anchors electrical infrastructure convergence, extending reach beyond physical enclosures into power distribution units. These three companies collectively illustrate how procurement consolidation favors vendors with cross-domain integration capabilities over standalone enclosure fabricators.
| Leading Market Players |
|---|
| Schneider Electric |
| Vertiv |
| Eaton |
| Rittal |
| HPE |
| Fujitsu |
| Dell Technologies |
| Legrand |
| Panduit |
| Others |
Supply & Pricing Matrix
EU CSRD carbon disclosure mandates now gate qualified supply and premium-tier pricing access, forcing enclosure vendors to document embodied carbon in steel and aluminum inputs or forfeit contracts with German and French operators prioritizing Environmental Product Declarations.
Pricing Analysis
Volume-mass hyperscale frameworks compress margins on standard rack cabinets while liquid-ready thermal-electrical architectures sustain premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates certified integrated systems from commodity sheet metal. Cost compression in standard enclosures intensifies because buyer consolidation favors turnkey aisle deployments over component sourcing. Colocation providers in India exhibit highest price sensitivity; AI training clusters in Germany and the United States demonstrate lowest sensitivity due to thermal performance requirements.
Supply Chain Analysis
ISO 9001 and IEC 61508 certification requirements filter supplier qualification, concentrating qualified fabrication capacity in China, Germany, and India. Cold-rolled steel and extruded aluminum profiles anchor material costs, with sheet metal stamping capacity clustering in Guangdong and Jiangsu provinces. Single-source vulnerability in precision machining exposes buyers to logistics disruption and tariff exposure. Distribution runs through direct OEM contracts for hyperscale operators and regional distributors serving enterprise colocation facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Liquid cooling manifold fabrication capacity represents the binding constraint propping pricing for thermal-electrical integrated systems, as cross-functional engineering expertise remains scarce among traditional sheet metal vendors.
For Market Incumbents: Lock in multi-year volume frameworks with hyperscale cloud operators before emerging thermal specialists capture share. Acquire liquid cooling subsystem engineering capabilities to defend against pure-play thermal vendors displacing air-cooled legacy portfolios. Prioritize IEC 61508 certification investment to accelerate integrated rack-PDU revenue recognition timelines.
For New Entrants and Emerging Players: Direct-to-hyperscale digital procurement portals offer bypass routes around entrenched distributor relationships. Target modular edge micro-data centers in manufacturing and retail verticals requiring sub-100kW rapid-commissioning skids. Lead with pre-integrated enclosure-power-cooling bundles rather than standalone rack sales to penetrate procurement consolidation.
For Investors and Strategic Acquirers: First liquid cooling manifold order announcements from Indian PLI beneficiaries are the leading indicator that domestic thermal-electrical integration capacity is achieving scale. Five-to-ten year viability favors vendors with backward integration into precision machining and captive coolant distribution unit production. Watch for CSRD-aligned Environmental Product Declaration acceleration among German operators as inflection signal for carbon-transparent supply chain premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Manifold Integration | Captures AI training cluster contracts in Germany and the United States demanding 50-100kW densities. |
| Environmental Product Declaration Certification | Qualifies vendors for EU CSRD-mandated procurement by German and French data center operators. |
| India PLI Manufacturing Footprint | Reduces import dependency for domestic cloud buildouts in Maharashtra and Karnataka clusters. |
| Integrated Rack-PDU Development | Accelerates revenue recognition through IEC 61508 functional safety validation compression. |
| Recycled Content Steel Sourcing | Meets scope 3 carbon disclosure requirements under tightening EU Ecodesign Directive mandates. |
Research Methodology
Document review covered SEC filings from hyperscale cloud operators, EPA Energy Star certification databases, EU Ecodesign Directive implementation guidance, and India PLI scheme notifications, complemented by interviews with data center infrastructure procurement directors, thermal engineering leads at colocation facilities, sheet metal fabrication plant managers, and regulatory compliance officers at enclosure manufacturers. Secondary validation drew from IEC standards documentation, CSRD technical guidance, and customs trade data for steel and aluminum inputs. Bottom-up capacity estimates triangulated against top-down hyperscale capex deployment tracking.
Cross-referencing historical rack deployment patterns against expert panel input on liquid cooling adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, cooling technology tier, application scale, and end-user regulatory exposure. CAGRs were derived from slope analysis of hyperscale facility commissioning timelines and edge computing node proliferation rates. Forecast inputs incorporated India PLI capacity ramp schedules and EU Ecodesign replacement cycle acceleration assumptions.
Inputs from hyperscale operator procurement directors and India PLI beneficiary disclosures were available through the study window; gaps in real-time edge deployment tracking introduce uncertainty bands around distributed infrastructure estimates. Forecasts reflect assumptions on thermal density migration rates and carbon disclosure enforcement intensity. A model refresh is warranted upon material change in EU CSRD audit implementation timelines or India PLI capacity utilization thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Japan Data Center Construction Market
Data Center Infrastructure
Singapore Data Center Server Market
Data Center Infrastructure
Data Center Renovation Market
Data Center Infrastructure
Mexico Data Center Rack Market
Data Center Infrastructure
Malaysia Data Center Rack Market
Data Center Infrastructure
APAC Green Data Center Market
Data Center Infrastructure
France Data Center Power Market
Data Center Infrastructure
Poland Data Center Rack Market
Data Center Infrastructure
Middle East and Africa Data Center Infrastructure Management Market
Data Center Infrastructure
South America Data Center Server Market
Data Center Infrastructure
Switzerland Data Center Rack Market
Data Center Infrastructure
United States Data Center Market
Data Center Infrastructure
Russia Data Center Construction Market
Data Center Infrastructure
Russia Data Center Rack Market
Data Center Infrastructure
Data Center Rack Solutions Market
Data Center Infrastructure
Belgium Data Center Power Market