
 Flour Conditioner Market | 2026-2036
Flour Conditioner Market Size, Share, and Industry Trends Forecast 2026-2036
Flour Conditioner Market Foresight
The EU Green Deal and associated F-Gas Regulation is consolidating reformulation priorities across European milling and baking supply chains. Corbion leverages its biotechnology platform to specialize in enzyme-based conditioners that reduce chemical additive dependency. AB Mauri anchors its position through fermentation-derived solutions and deep bakery sector relationships across multiple continents.
Flour conditioners comprise functional additives and processing aids that modify gluten development, oxidation kinetics, and dough rheology through enzymatic or chemical action, typically dosed at 10–200 parts per million depending on flour protein content and desired end-product texture. Their primary commercial purpose is to standardize flour performance variations caused by wheat cultivar differences, harvest conditions, and storage parameters. Enzymes and emulsifiers capture the most significant margin pools due to clean-label premiums and patent-protected production methods, while oxidizing agents face gradual displacement as bakeries reformulate for simpler ingredient declarations. Bread applications dominate volume consumption, though pasta and noodle segments attract specialized conditioner blends as Asian wheat-processing capacity expands.
The FDA governs flour conditioner safety through GRAS determinations and food additive petitions, while the USDA oversees wheat quality standards that indirectly shape conditioner efficacy requirements across US milling operations. EFSA and EMA frameworks in Europe enforce stricter residue limits and novel food assessments, compelling suppliers to maintain dual regulatory dossiers for transatlantic product lines. Stakeholders must monitor evolving enzyme classification debates between processing aid and additive categories, as regulatory reclassification would trigger substantial reformulation costs and label disclosure obligations.
Market Dynamics
The EU Green Deal and F-Gas Regulation are forcing systematic reformulation across European milling supply chains, compressing demand for chemical oxidizers while accelerating enzyme-based conditioner adoption in industrial baking clusters.
Growth Catalysts
- Clean-label mandates:The EU Green Deal pushes commercial bakeries toward enzyme-based conditioners that eliminate chemical additive declarations from ingredient panels.
- Industrial baking concentration:High-volume operations in Germany's milling corridors standardize procurement around performance-guaranteed conditioner systems to reduce flour variability.
- Biotechnology maturation:Fermentation-derived processing aids now achieve cost parity with synthetic alternatives while delivering superior dough rheology control.
Market Restraints
- Wheat protein volatility:Harvest condition variation forces conditioner dosage recalibration, eroding margin predictability for millers operating on fixed-price contracts.
- Enzyme supply concentration:Production of patent-protected amylases and xylanases clusters among biotechnology specialists, creating single-source vulnerability for regional bakeries.
- Regulatory bifurcation:EFSA's novel food assessments impose dual dossier requirements that inflate compliance costs for transatlantic product lines versus single-territory competitors.
Strategic Opportunities
- Asian noodle processing expansion:Wheat-based pasta and noodle capacity growth in China and Southeast Asia creates demand for specialized gluten-strengthening conditioner blends formulated for alkaline dough systems.
- Processing aid reclassification:Pending EFSA determinations on enzyme classification could exempt certain biotechnologies from additive labeling, unlocking clean-label premiums.
- Direct-to-mill digital distribution:Conditioner suppliers bypass traditional ingredient distributors by deploying IoT-enabled dosing systems that integrate with mill automation infrastructure.
Industry Challenges
- Enzymology expertise scarcity:Formulation chemistry roles requiring simultaneous knowledge of protein biochemistry and bakery process engineering remain difficult to fill in European labor markets.
- Legacy equipment incompatibility:Precision enzyme dosing requires automated dispersion systems that many mid-capacity mills lack, forcing capital-intensive retrofit decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flour Conditioner Market |
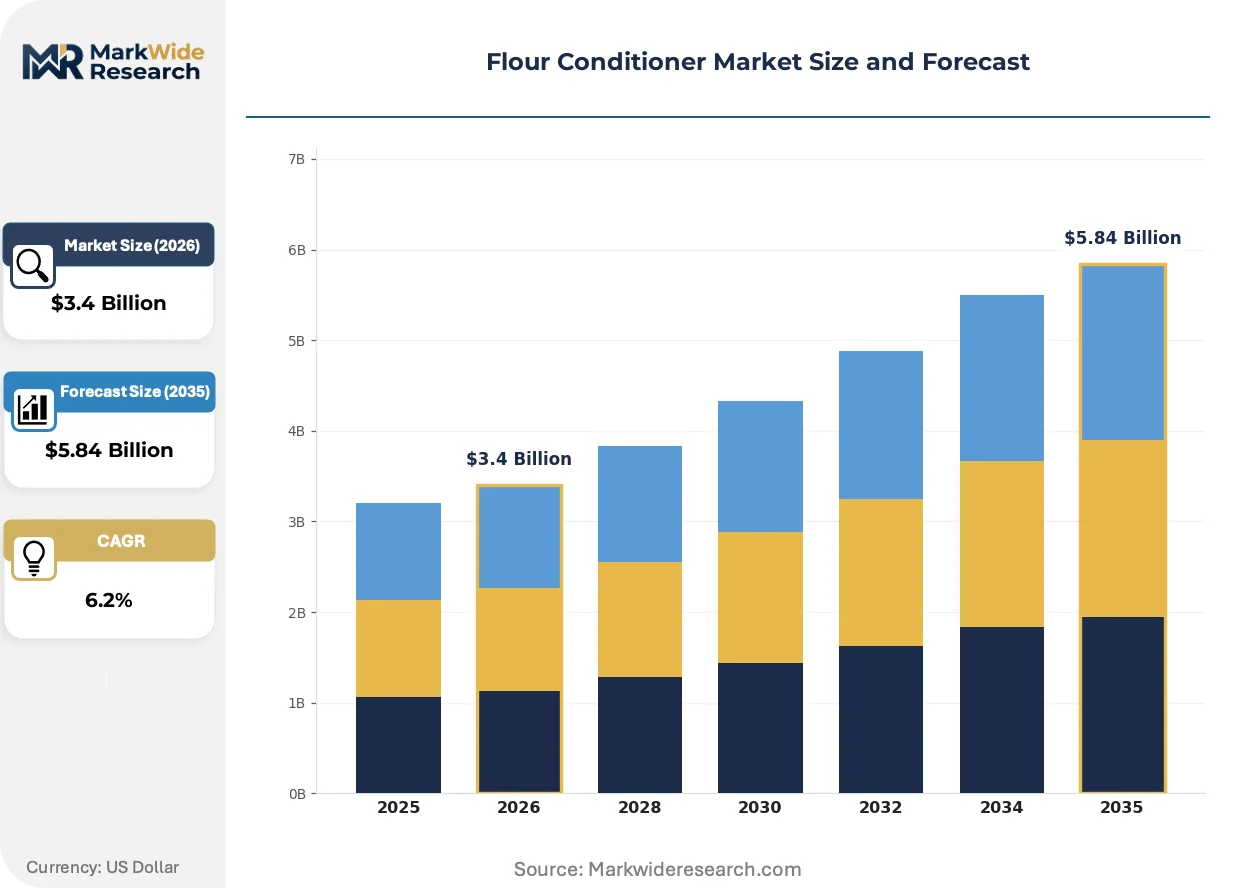
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.84 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzymes, Oxidizing Agents, Reducing Agents, Emulsifiers, Bleaching Agents, Dough Strengtheners Application: Bread, Cake, Biscuit, Pasta, Noodles, Pastries End User: Bakeries, Food Processing Units, Confectionery Manufacturers, Frozen Food Producers, Retailers Packaging Type: Bulk Bags, Paper Bags, Plastic Bags, Drums, Multi-layered Bags |
| Companies Covered | Ardent Mills, AB Mauri, Corbion, Lallemand, Archer Daniels Midland Company, Puratos Group, DuPont Nutrition & Biosciences, Watson Foods, RIBUS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flour Conditioner Market Shifts & Advancements
Biotechnology platforms are consolidating competitive advantage in flour conditioning, while regulatory pressure and procurement rationalization simultaneously reshape supplier relationships and product architectures across industrial baking.
Enzyme-based conditioners, particularly amylase and lipase blends, modify starch gelatinization and lipid emulsification to standardize dough performance across variable wheat harvests. Commercial bakeries in Germany and the Netherlands adopt these systems at accelerating rates as EFSA residue limits tighten. This transition is consolidating market share among biotechnology specialists with captive fermentation capacity, compressing margins for legacy chemical oxidizer suppliers dependent on commodity production economics.
The EU F-Gas Regulation and associated REACH amendments restrict peroxide-based oxidizing agents in food processing applications, triggering reformulation timelines across European milling operations. Industrial bakers face 18-24 month product redevelopment cycles to maintain certification under evolving EFSA processing aid classifications. Bread and viennoiserie segments absorb the highest compliance burden, with German industrial clusters investing most aggressively in enzyme transition programs to preempt enforcement actions.
Ingredient procurement is consolidating toward multi-year performance contracts that transfer flour variability risk from bakeries to conditioner suppliers. Large-scale commercial operations in France and Italy now specify guaranteed dough tolerance ranges rather than discrete additive purchases, forcing suppliers to embed analytical services and technical field support into core offerings. This model compresses distributor margins while rewarding vertically integrated biotechnology platforms with real-time milling data access.
Flour Conditioner Market Segmentation
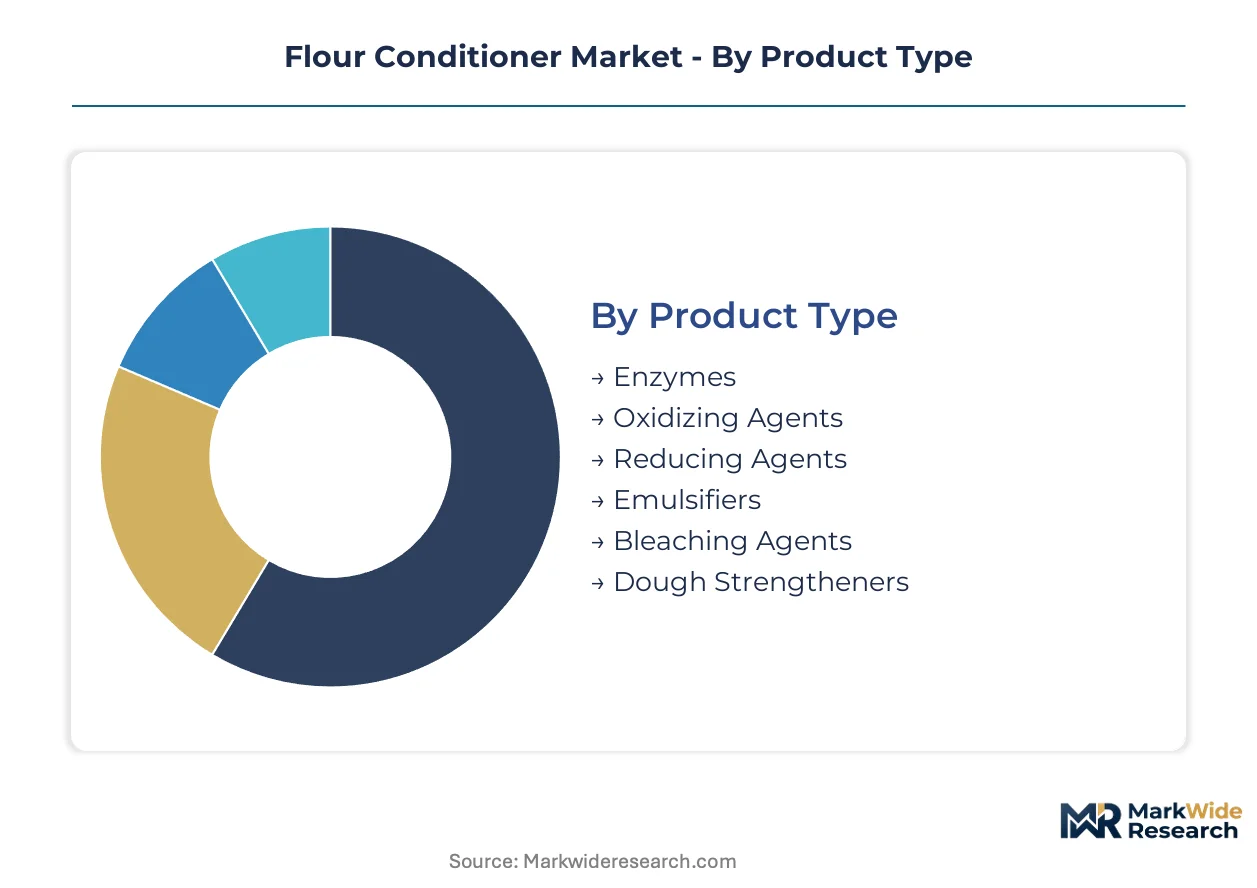
Segmentation in flour conditioning reveals how procurement patterns diverge between industrial-scale operators and artisanal producers. Reformulation pressures and equipment compatibility requirements create distinct upgrade cycles across product categories, reshaping supplier relationships and margin structures.
Product Type:
Replacement cycles accelerate as EFSA reclassifications and REACH amendments force systematic shifts from chemical oxidizers to enzyme-based systems, compressing legacy product lifecycles.
- Enzymes:Amylase, lipase, and xylanase blends modify starch gelatinization and gluten development through targeted biocatalysis. German industrial baking clusters standardize procurement around these systems to eliminate chemical additive declarations and preempt F-Gas enforcement actions.
- Oxidizing Agents:Peroxide-based conditioners strengthen gluten networks through oxidative cross-linking of sulfhydryl groups. Demand contracts across European milling corridors as the EU Green Deal mandates reformulation timelines, though residual volume persists in price-sensitive export markets.
- Reducing Agents:L-cysteine and sodium metabisulfite relax dough structure for cracker and biscuit applications. Asian noodle processors favor these for alkaline dough systems.
- Emulsifiers:DATEM and SSL improve crumb softness and shelf-life extension. Clean-label pressures limit growth in premium bread segments.
- Bleaching Agents:Benzoyl peroxide and chlorine dioxide whiten flour for aesthetic consistency. Regulatory restrictions constrain deployment in EU territories.
- Dough Strengtheners:Ascorbic acid and azodicarbonamide enhance mixing tolerance and gas retention. Replacement by enzyme alternatives proceeds fastest in high-volume operations.
Volume placements concentrate in Enzymes; the faster expansion belongs to Dough Strengtheners as bakers seek hybrid formulations during transition periods.
Application:
Cost tier differentiation separates commodity bread applications from specialized pasta and noodle segments, with premium pricing attaching to alkaline dough compatibility and extended frozen stability.
- Bread:Pan bread, artisan loaves, and flatbreads require gluten network optimization and fermentation control. Industrial bakeries in France and Italy specify guaranteed dough tolerance ranges rather than discrete additive purchases, embedding technical service into conditioner contracts.
- Cake:High-ratio formulations demand precise starch modification and emulsification to prevent structural collapse. Emulsifier-enzyme blends capture margin premiums in clean-label reformulations.
- Biscuit:Short dough systems require reduced gluten development for friable texture. Reducing agents dominate this segment with minimal regulatory pressure.
- Pasta:Durum wheat processing relies on oxidative conditioners for color stability and cooking tolerance. Italian milling infrastructure sustains concentrated demand.
- Noodles:Alkaline wheat noodles in China and Southeast Asia require specialized gluten-strengthening blends formulated for high-pH dough systems.
- Pastries:Laminated doughs need controlled gluten relaxation and fat emulsification for layer integrity. Viennoiserie segments absorb significant compliance burden from EFSA processing aid reclassifications.
Procurement scale peaks in Bread; Noodles climb the fastest as Asian wheat-processing capacity expands.
End User:
Customer type fragmentation creates divergent service models, with industrial bakeries demanding performance guarantees while retailers prioritize label simplicity and distributor consolidation.
- Bakeries:Commercial and artisanal operations require consistent dough performance across variable flour deliveries. Germany's industrial clusters invest most aggressively in enzyme transition programs.
- Food Processing Units:Integrated milling-baking operations seek direct-to-mill digital distribution with IoT-enabled dosing integration.
- Confectionery Manufacturers:Precise aeration and texture control drive specialized emulsifier demand.
- Frozen Food Producers:Extended shelf-life stability and freeze-thaw tolerance command premium conditioner blends.
- Retailers:Private-label programs specify clean-label ingredient panels, pushing reformulation downstream to suppliers.
Contract value concentrates in Bakeries; the steepest expansion trajectory belongs to Frozen Food Producers as prepared dough markets grow.
Packaging Type:
Supply concentration in automated handling systems favors bulk and multi-layered formats, while mid-capacity mills face capital-intensive retrofit decisions for precision enzyme dosing.
- Bulk Bags:One-tonne flexible intermediate bulk containers serve high-volume industrial mills with automated dispensing infrastructure. German milling corridors standardize around this format.
- Paper Bags:Kraft multi-wall construction suits traditional distribution channels and smaller bakery operations. Sustainability credentials support residual demand.
- Plastic Bags:Polyethylene liners provide moisture barrier protection for humidity-sensitive enzyme formulations.
- Drums:Steel and fiber containers handle liquid enzyme concentrates and specialized emulsifier pastes.
- Multi-layered Bags:Aluminum-laminated structures with oxygen barriers preserve oxidative conditioner potency through extended storage.
Shipment volumes concentrate in Bulk Bags; Multi-layered Bags gain share fastest as enzyme shelf-life requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Ruhr industrial corridor anchors European flour conditioner procurement, where concentrated milling infrastructure and commercial baking clusters generate sustained demand for enzyme-based processing aids.
Germany
Industrial baking clusters in North Rhine-Westphalia and Bavaria drive enzyme conditioner procurement at scale. The EU F-Gas Regulation mandates peroxide-based oxidizer phase-out timelines, compelling reformulation investments. Milling corridors around Hamburg and Stuttgart standardize on multi-year performance contracts that embed technical field support.
United States
Commercial bakeries across the Midwest and Southeast seek consistent dough performance across variable wheat harvests. FDA GRAS determinations govern enzyme safety classifications, while USDA wheat quality standards shape conditioner efficacy requirements. Kansas City milling infrastructure sustains concentrated procurement pull for high-volume bread operations.
China
Wheat-based noodle capacity expansion in Shandong and Henan provinces creates specialized demand for alkaline dough conditioners. SAMR food additive regulations enforce residue limits that diverge from Western frameworks. Yangtze River Delta baking clusters adopt precision enzyme dosing systems for frozen dough stability.
Italy
Durum wheat processing for pasta production sustains oxidative conditioner demand despite European reformulation pressures. EFSA novel food assessments impose stricter dossier requirements than transatlantic counterparts. Emilia-Romagna milling infrastructure maintains concentrated procurement for color-stable semolina conditioning.
India
Commercial bakery expansion in Maharashtra and Gujarat drives emulsifier and enzyme adoption for extended shelf-life bread. FSSAI food additive regulations govern maximum permissible limits for oxidizing agents. Mumbai-Pune industrial corridors standardize procurement around cost-optimized conditioner blends for mass-market pan bread.
Flour Conditioner Market Competitive Landscape
Premium-margin players sit above commodity-margin players across biotechnology specialization and regulatory compliance capabilities, creating a tiered competitive structure. The vendor base concentrates among fermentation-derived processing aid specialists with captive manufacturing capacity, while legacy chemical oxidizer suppliers face margin compression from reformulation mandates. Three archetypes dominate: biotechnology platforms with enzyme patent portfolios, diversified ingredient conglomerates with bakery sector relationships, and regional milling service providers with technical field presence. Capacity expansion and strategic partnerships represent the dominant competitive moves, as players secure fermentation capacity and integrate analytical services into core offerings.
Within the biotechnology platform tier, Corbion and AB Mauri exemplify archetypes built on fermentation-derived solutions and deep bakery sector integration. Lallemand occupies a position as a specialty fermentation company with inherent enzyme production capabilities. These three anchors demonstrate how patent-protected biocatalysis and multi-continental technical service networks create defensive positioning against commodity chemical alternatives.
| Leading Market Players |
|---|
| Ardent Mills |
| AB Mauri |
| Corbion |
| Lallemand |
| Archer Daniels Midland Company |
| Puratos Group |
| DuPont Nutrition & Biosciences |
| Watson Foods |
| RIBUS |
| Others |
Supply & Pricing Matrix
Patent-protected enzyme formulations command substantial premiums over commodity chemical oxidizers, with biotechnology specialists capturing margin pools through fermentation-derived production methods while legacy suppliers face compression from EFSA reclassification timelines. This tier divergence manifests in procurement patterns: industrial baking clusters in Germany negotiate multi-year performance contracts embedding technical field support, whereas mid-capacity mills confront capital-intensive retrofit decisions for precision dosing infrastructure.
Pricing Analysis
Outcome-guaranteed pricing anchors the flour conditioner market, with suppliers embedding analytical services and dough tolerance warranties into contract structures. Three-tier pricing structure across premium, standard, and economy levels separates patent-protected enzyme blends from fermentation-derived alternatives and commodity chemical oxidizers. Cost compression in chemical oxidizer tiers is intensifying because the EU F-Gas Regulation mandates systematic phase-out timelines. Artisanal bakeries exhibit highest price sensitivity due to limited volume scale, while frozen food producers absorb premium pricing for extended stability guarantees.
Supply Chain Analysis
EFSA novel food assessments and REACH compliance certifications gate supplier participation in European milling corridors, creating qualification barriers that concentrate procurement among dossier-capable biotechnology platforms. Production gravity centers on the Netherlands, Germany, and Denmark, where captive fermentation capacity and analytical service infrastructure co-locate with industrial baking demand. Raw material dependencies include wheat cultivar sourcing, microbial strain libraries, and specialized packaging substrates for oxygen-sensitive enzymes. Single-source vulnerability in patent-protected amylase supply creates structural risk for regional bakeries. Distribution runs through direct-to-mill digital channels and traditional ingredient distributors serving mid-capacity operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The flour conditioner market functions as a cost-of-compliance arena where the EU F-Gas Regulation and EFSA processing aid reclassifications erect substantial barrier-to-entry moats for biotechnology specialists with regulatory dossier capabilities.
For Market Incumbents: To counter margin compression from chemical oxidizer phase-out mandates, biotechnology platforms should secure captive fermentation capacity expansion in North Rhine-Westphalia and Bavaria while embedding IoT-enabled dosing systems into mill automation infrastructure. Backward integration into microbial strain development preserves biocatalysis advantages against emerging fermentation specialists. For New Entrants and Emerging Players: Mid-capacity mills lacking automated dispersion infrastructure represent an underserved buyer archetype requiring retrofit-compatible enzyme formulations and technical field support bundling. Asian noodle processors in Shandong and Henan provinces offer penetrable entry points through alkaline dough conditioner specialization. A go-to-market angle anchored in direct-to-mill digital distribution bypasses incumbent distributor relationships. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated biotechnology platforms given pending EFSA determinations on enzyme classification that could unlock clean-label premiums. Long-term viability over the coming decade hinges on regulatory dossier depth and multi-continental technical service networks. The signal to watch is EFSA processing aid reclassification timing, which would trigger substantial reformulation demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Captive production of patent-protected amylases secures supply security for German industrial baking clusters. |
| IoT-Enabled Dosing Integration | Direct-to-mill digital distribution bypasses traditional ingredient channels while embedding real-time technical support. |
| Regulatory Dossier Investment | Dual EFSA-FDA compliance capabilities unlock transatlantic product line premiums versus single-territory competitors. |
| Asian Noodle Processing Specialization | Alkaline dough conditioner formulations capture capacity expansion in China's Shandong and Henan provinces. |
| Performance Contract Structuring | Guaranteed dough tolerance ranges transfer flour variability risk from bakeries to conditioner suppliers. |
Research Methodology
Trade databases, EFSA regulatory filings, and milling industry association reports formed the secondary backbone, supplemented by primary interviews with fermentation technology directors, industrial bakery procurement leads, milling operations managers, and regulatory affairs specialists at biotechnology platforms. Bottom-up volume modeling triangulated against top-down value estimates derived from customs data and industry production statistics.
Historical trendline analysis across wheat harvest variability patterns and enzyme adoption curves established baseline growth parameters. The forecast framework segments by product type, application, end-user archetype, and regional regulatory cluster, with CAGRs derived from elasticity modeling against wheat protein content volatility and clean-label reformulation penetration rates. Industry-specific inputs include EFSA processing aid reclassification timelines and Asian noodle capacity expansion trajectories.
Revisions become necessary when EFSA regulatory determinations, wheat harvest disruption events, or biotechnology patent expirations materially alter competitive dynamics. Forecasts reflect documented assumptions regarding reformulation adoption rates and supply concentration stability. A model refresh is warranted upon material change in EU Green Deal enforcement intensity or enzyme classification frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Isoprenol Market
Food Enhancers and Additives
Enriched Yeast Extract Market
Food Enhancers and Additives
Australia Food Flavor and Enhancer Market
Food Enhancers and Additives
Anti-Sagging Agents Market
Food Enhancers and Additives
Flavonoid Phytogenic Feed Additive Market
Food Enhancers and Additives
Crumb Softener Market
Food Enhancers and Additives
Kaempferol Market
Food Enhancers and Additives
Cake Softener Market
Food Enhancers and Additives
South Korea Fat Replacers Market
Food Enhancers and Additives
Mexico Water Enhancer Market
Food Enhancers and Additives
Emulsion Stabilizer for Beverages Market
Food Enhancers and Additives
South Africa Water Enhancer Market
Food Enhancers and Additives
Vegetable Shortening Market
Food Enhancers and Additives
Yellow Fats Market
Food Enhancers and Additives
Australia Water Enhancer Market
Food Enhancers and Additives
Food Thickening Agents Market