
 Cholesterol API Market | 2026-2036
Cholesterol API Market Size, Share, and Industry Trends Forecast 2026-2036
Cholesterol API Market Outlook
Pharmaceutical companies is repositioning cholesterol API procurement toward contract manufacturers as in-house synthesis economics erode. Zhejiang Garden Biochemical leverages vertical integration from sterol extraction to finished API purification. Dishman Carbogen Amcis sustains specialized manufacturing capabilities for high-purity cholesterol derivatives used in liposomal drug delivery. Nippon Fine Chemical anchors supply relationships with Japanese pharmaceutical houses requiring JIS-standard material certification.
Cholesterol API refers to refined sterol compounds meeting pharmacopeial purity specifications, typically exceeding 95% assay with controlled oxidation and moisture parameters, produced through solvent extraction from wool grease or animal tissue followed by crystallization and chromatographic purification. The material serves as a critical starting material for statin synthesis and as an excipient in liposomal and nanoparticle formulations. Simvastatin and atorvastatin product types dominate current volume flows, though rosuvastatin-grade cholesterol commands margin premiums due to tighter impurity specifications. Oral delivery mode absorbs the majority of API offtake, while injectable-grade cholesterol for lipid nanoparticle applications exhibits the fastest structural expansion as mRNA therapeutic platforms multiply.
FDA maintains Current Good Manufacturing Practice oversight for cholesterol API through drug master file review, while EMA enforces ICH Q3D elemental impurity guidelines that constrain residual metal thresholds in sterol-derived APIs. India's CDSCO mandates active pharmaceutical ingredient registration for export-oriented facilities under its phased manufacturing program. Contract manufacturers must monitor evolving pharmacopeial harmonization between USP, EP and IP standards, as divergence in sterol-related substance testing creates compliance complexity for multi-destination supply chains.
Market Dynamics
Pharmaceutical outsourcing is compressing the cholesterol API value chain as contract manufacturers absorb synthesis stages previously retained in-house, while liposomal drug delivery platforms are electrifying demand for ultra-high-purity sterol grades that exceed standard pharmacopeial thresholds.
Growth Catalysts
- EMA ICH Q3D Guidelines:Tightened elemental impurity thresholds for sterol-derived APIs are filtering subscale producers and consolidating volume among certified manufacturers capable of validated metal control.
- Liposomal Formulation Expansion:mRNA therapeutic platforms require cholesterol excipients with oxidation specifications below 0.5%, creating a specialized demand tier with margin premiums.
- India CDSCO Registration:Export-oriented API facilities under the phased manufacturing program are securing locked supply relationships with generic statin producers in regulated markets.
Market Restraints
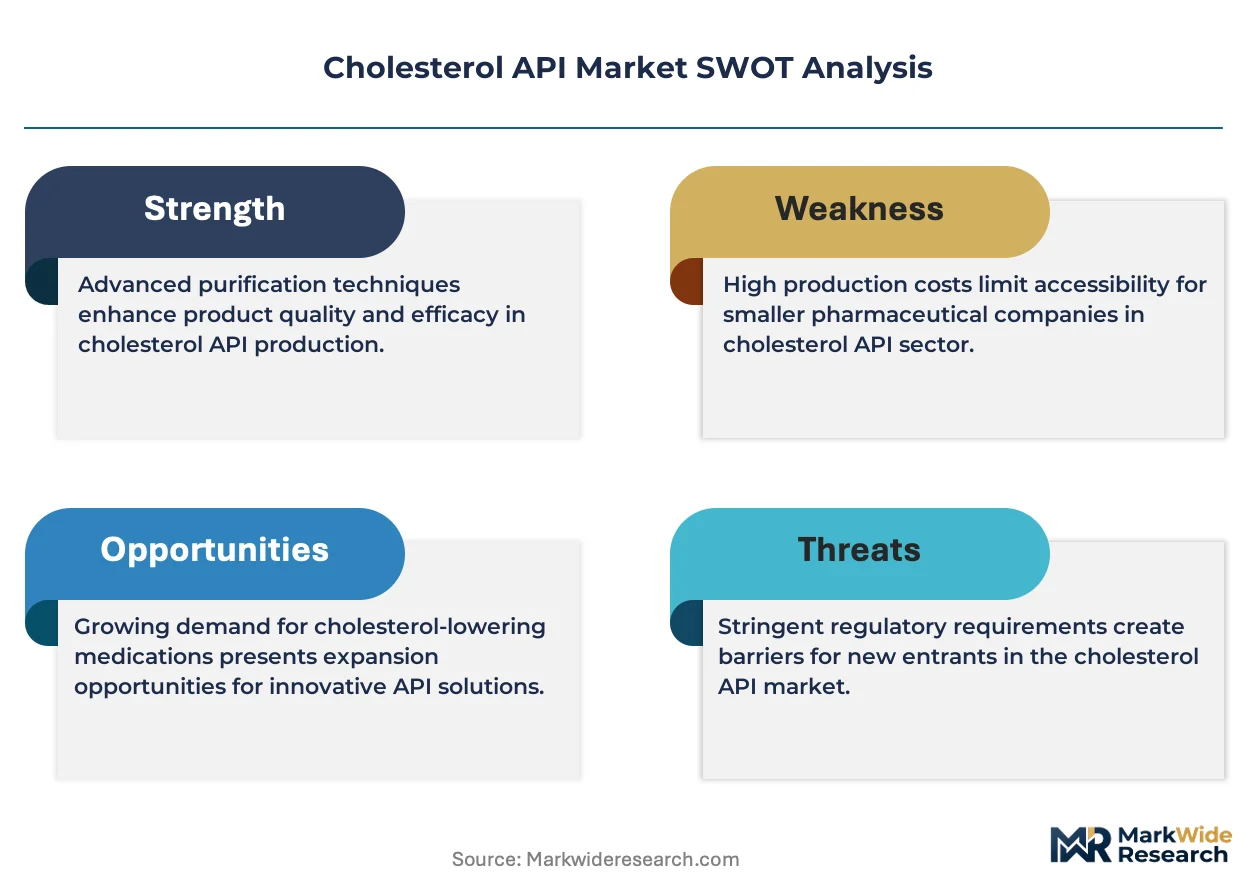
- Wool Grease Supply Volatility:Crude lanolin feedstock prices fluctuate with Australian and New Zealand wool production cycles, compressing margin predictability for non-integrated refiners.
- Single-Geography Concentration:Zhejiang province hosts over sixty percent of global sterol extraction capacity, exposing multi-destination supply chains to localized disruption risks.
- Biotechnological Substitution:Fermentation-derived phytosterols from engineered yeast strains are approaching pharmacopeial purity parity for non-statin applications.
Strategic Opportunities
- Saudi Arabia Local Production:SFDA import substitution incentives are attracting toll manufacturing partnerships for cholesterol API serving Middle East and North Africa generic markets.
- Continuous Chromatography Adoption:Simulated moving bed systems are reducing solvent consumption by forty percent versus batch crystallization, enabling cost-positioned entry into economy-grade statin supply.
- Japan PMDA Certification:JIS-standard material qualification opens direct supply relationships with domestic pharmaceutical houses that bypass trading company intermediaries.
Industry Challenges
- Analytical Method Harmonization:Divergent sterol-related substance testing between USP, EP and IP standards forces multi-destination manufacturers to maintain parallel validation protocols, extending release timelines.
- Specialized Purification Engineering:Liposomal-grade cholesterol production requires supercritical fluid extraction capabilities that demand capital commitments exceeding mid-scale API facility budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cholesterol API Market |
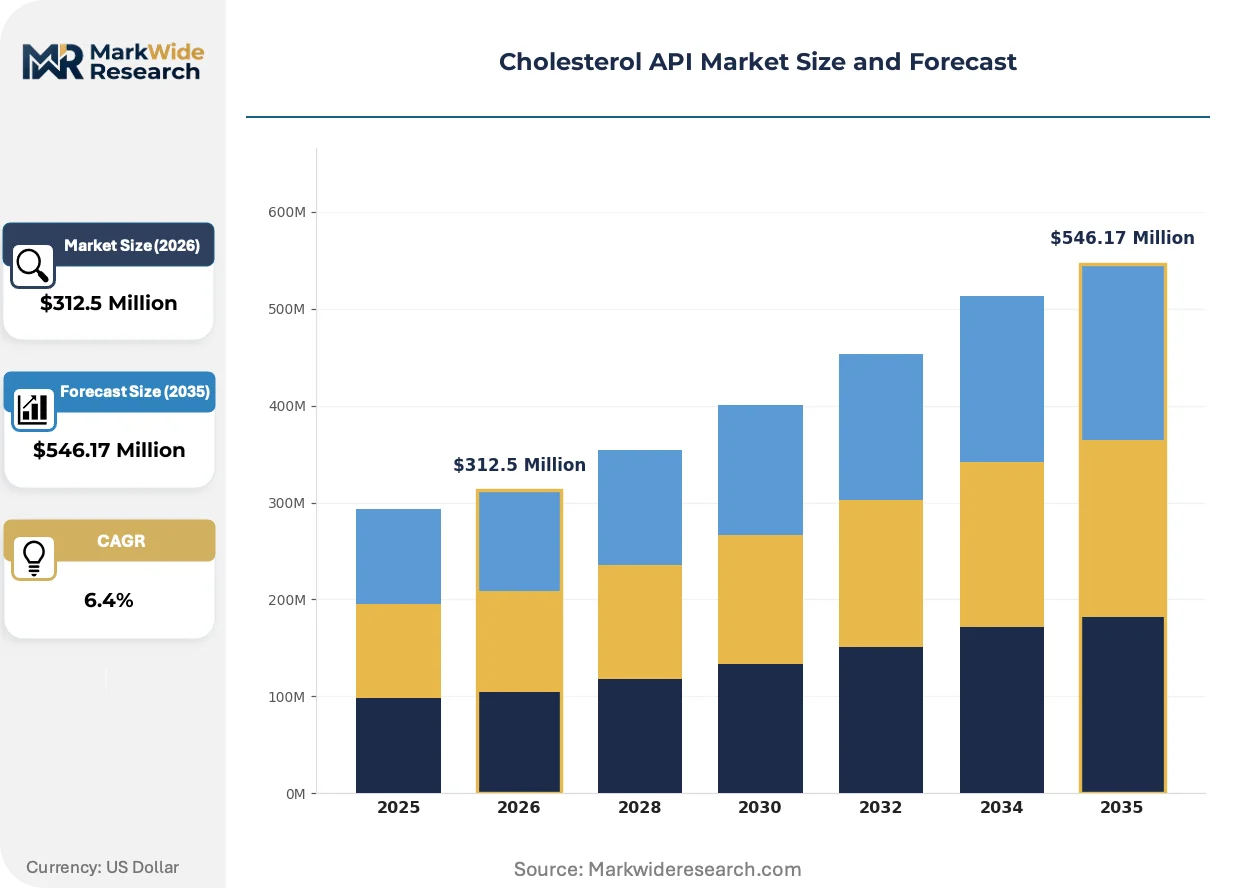
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Simvastatin, Atorvastatin, Rosuvastatin, Lovastatin End User: Pharmaceutical Companies, Research Institutions, Contract Manufacturers, Biotechnology Firms Delivery Mode: Oral, Injectable, Intravenous, Topical Application: Hyperlipidemia Treatment, Cardiovascular Disorders, Preventive Therapy, Research |
| Companies Covered | Zhejiang Garden Biochemical, Dishman Carbogen Amcis, Croda International, Nippon Fine Chemical, Merck KGaA, Anhui Chem-Bright Bioengineering, NOF Corporation, Tokyo Chemical Industry, Avanti Polar Lipids, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cholesterol API Market Strategic Shifts
Supercritical fluid extraction and continuous processing are displacing conventional solvent crystallization in cholesterol API manufacturing, while regulatory divergence between pharmacopeias is forcing investment in modular quality systems capable of rapid standard switching.
Supercritical carbon dioxide extraction is electrifying the purification of high-oxidation-sensitivity cholesterol grades for liposomal applications. Contract manufacturers serving mRNA platform developers are retrofitting batch facilities with continuous SFE trains. This technology compression is collapsing the historical three-month production cycle for pharmaceutical-grade sterols into sub-forty-day continuous operations.
REACH authorization requirements for residual solvent classifications are tightening disclosure obligations for European-sourced cholesterol APIs. ECHA's updated guidance on cyclic siloxane contaminants is forcing wool grease refiners to install dedicated distillation stages. German and Swiss generic producers are now mandating full supply chain solvent mapping from their Indian and Chinese API suppliers.
Buying patterns among statin generic houses are compressing supplier qualification cycles from twenty-four months to under twelve. Large-volume purchasers are unbundling technical qualification from commercial contracting, creating parallel-track procurement processes. This behavioral shift is most pronounced in India, where CDSCO-registered facilities are securing multi-year offtake agreements before completion of full pharmacopeial certification.
Cholesterol API Market Segmentation
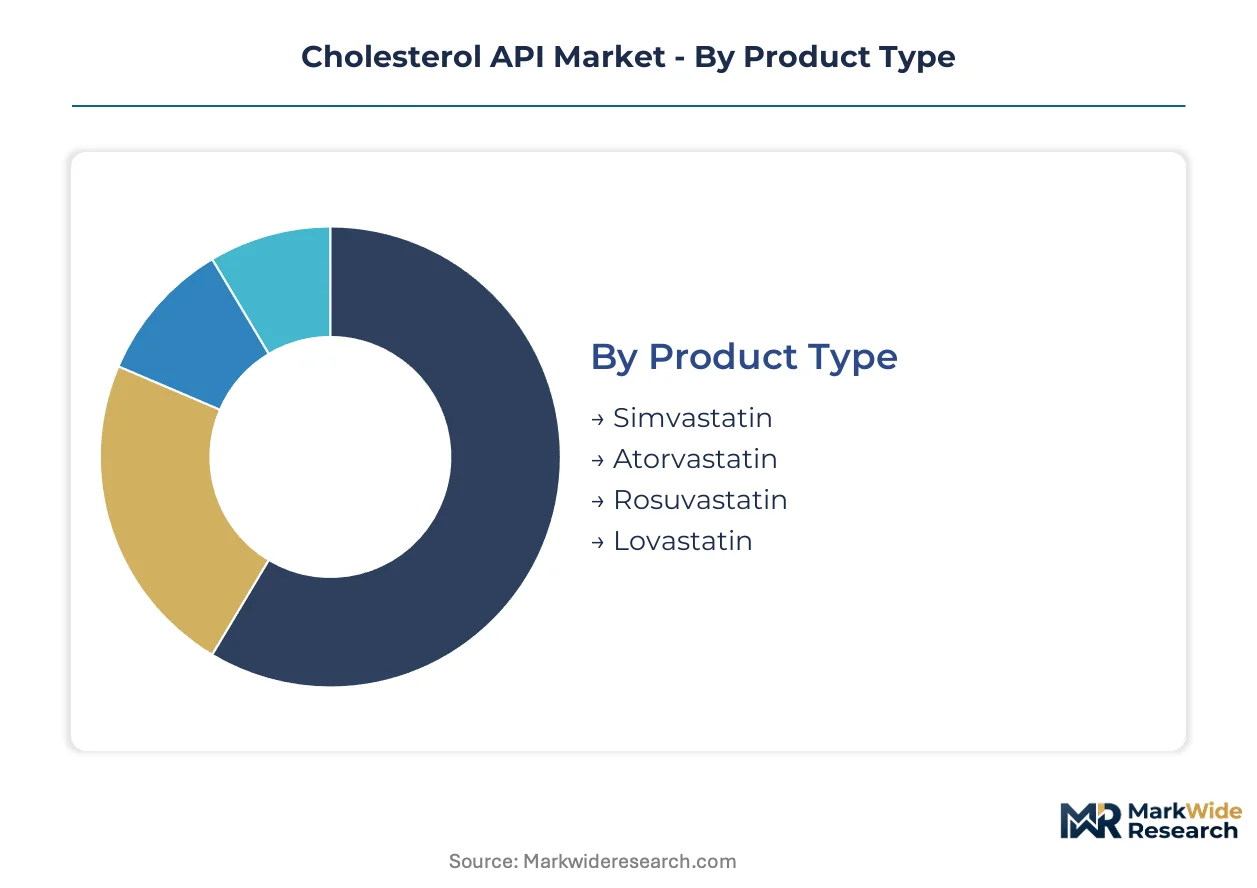
Cholesterol API demand fragments across statin synthesis pathways, end-user procurement models, and escalating purity requirements for liposomal drug delivery. Each segmentation axis reveals distinct margin structures and qualification barriers that shape supplier competitive position.
Product Type:
Integration depth varies sharply across statin grades, with some cholesterol APIs serving as standalone starting materials while others embed into complex multi-step synthesis chains.
- Simvastatin:Semi-synthetic lactone prodrug derived from lovastatin fermentation, requiring cholesterol API with standard USP-grade purity thresholds. Indian CDSCO-registered facilities in Hyderabad and Ahmedabad supply generic houses serving US and European markets under FDA and EMA drug master file pathways.
- Atorvastatin:Fully synthetic statin demanding pyrrole-substituted cholesterol intermediates with tighter oxidation specifications. Zhejiang province manufacturers dominate crystallization capacity, though Dishman Carbogen Amcis maintains European purification capabilities for regulated-market supply.
- Rosuvastatin:Super-statin grade commanding margin premiums for enantiomerically pure cholesterol derivatives. Japanese PMDA certification requirements filter supply to JIS-standard qualified producers.
- Lovastatin:Natural fermentation product from Aspergillus terreus cultures, now largely supplanted by semi-synthetic alternatives in volume markets.
Simvastatin leads volumes today; rosuvastatin is gaining share fastest.
End User:
Procurement concentration tracks outsourcing intensity, with in-house synthesis retreat fastest among mid-cap pharmaceutical developers.
- Pharmaceutical Companies:Vertically integrated statin producers retain cholesterol API production for proprietary process control, though large-cap firms increasingly toll-manufacture to Indian and Chinese contract specialists.
- Contract Manufacturers:Absorbing synthesis stages previously retained in-house as pharmaceutical outsourcing accelerates. CDSCO-registered Indian facilities secure multi-year offtake agreements before full pharmacopeial certification completion.
- Research Institutions:Academic and government laboratories procuring gram-to-kilogram quantities for mechanism-of-action studies and novel formulation development.
- Biotechnology Firms:mRNA platform developers sourcing liposomal-grade cholesterol with oxidation specifications below 0.5% for lipid nanoparticle formulations.
Contract manufacturers absorb the fastest volume expansion; pharmaceutical companies still anchor absolute consumption.
Delivery Mode:
Purity thresholds escalate with route sophistication, creating tiered qualification barriers that segment supplier capabilities.
- Oral:Standard pharmacopeial grades dominate statin tablet production, with moisture and oxidation parameters controlled through conventional crystallization.
- Injectable:Liposomal and nanoparticle applications demand supercritical fluid extraction capabilities and sub-0.5% oxidation specifications. mRNA therapeutic platforms multiply demand for this specialized tier.
- Intravenous:Hospital-administered lipid emulsions requiring endotoxin-controlled cholesterol API with validated pyrogen testing protocols.
- Topical:Dermal delivery formulations utilizing cholesterol as penetration enhancer in transdermal patches and dermatological preparations.
Oral delivery anchors current volumes; injectable grades climb the fastest.
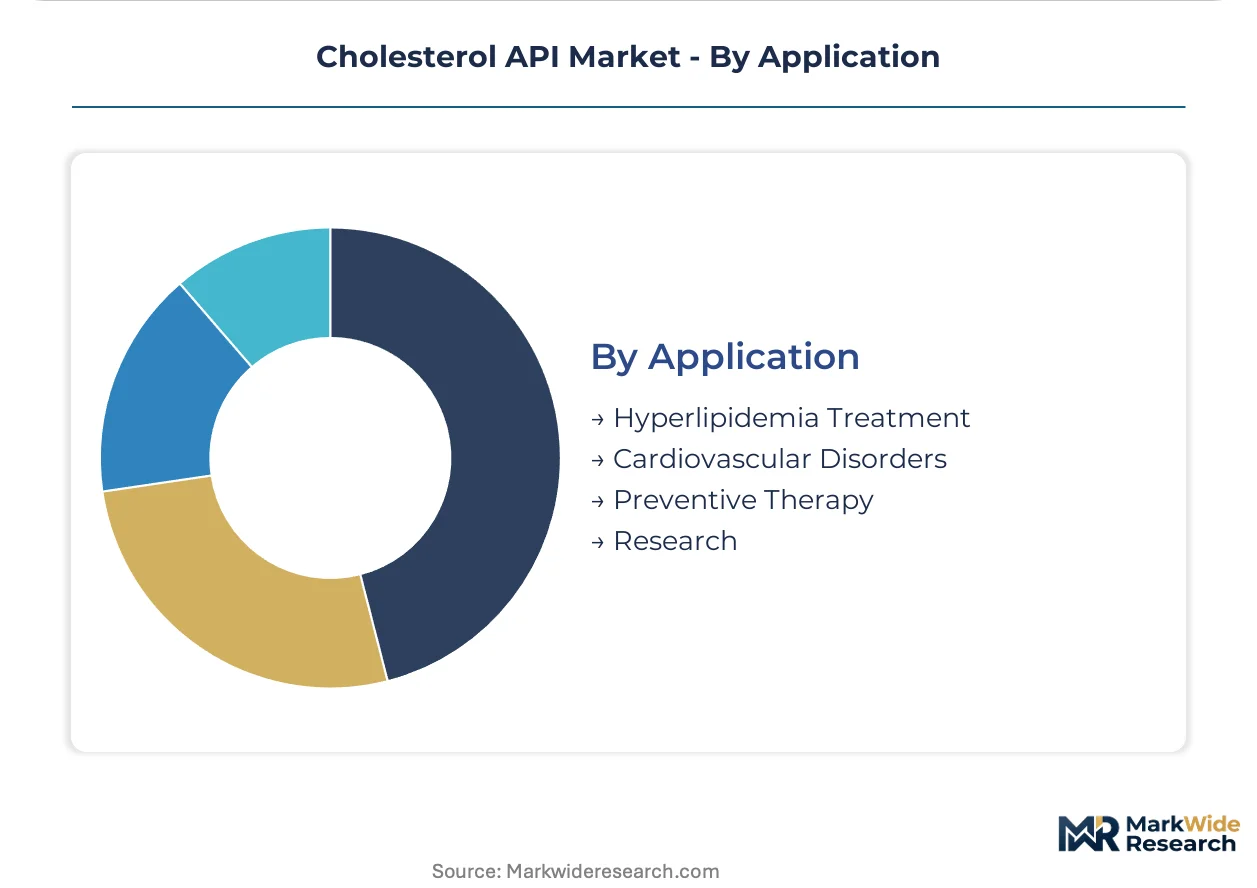
Application:
Clinical indication shapes regulatory pathway complexity and reimbursement pressure on API cost structures.
- Hyperlipidemia Treatment:Primary therapeutic indication driving bulk statin consumption, with generic price erosion compressing cholesterol API margins toward economy-grade supply.
- Cardiovascular Disorders:Secondary prevention protocols in post-myocardial infarction patients sustaining demand for high-dose atorvastatin and rosuvastatin formulations.
- Preventive Therapy:Primary prevention in high-risk populations expanding addressable patient pools, particularly in emerging markets with rising metabolic disease prevalence.
- Research:Preclinical and clinical investigation of novel cholesterol metabolism modulators requiring small-batch, high-characterization API grades.
Hyperlipidemia treatment leads absolute consumption; preventive therapy applications expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting cholesterol API production toward jurisdictions where compliance costs align with generic pricing pressure. Manufacturers migrate to regions offering streamlined pharmacopeial certification pathways without sacrificing access to regulated export markets.
China
Zhejiang province concentrates over sixty percent of global sterol extraction capacity, with Hangzhou and Ningbo clusters hosting integrated refiners serving statin generic houses. NMPA drug master file requirements align with USP and EP standards for export-oriented facilities. Local manufacturers are retrofitting batch plants with continuous processing trains to meet liposomal-grade oxidation specifications below 0.5%.
India
Hyderabad and Ahmedabad CDSCO-registered facilities supply generic statin producers under phased manufacturing program incentives. CDSCO mandates active pharmaceutical ingredient registration for export certification to regulated markets. Contract manufacturers in these clusters secure multi-year offtake agreements before completing full pharmacopeial qualification.
United States
FDA Current Good Manufacturing Practice oversight drives demand for validated metal control under ICH Q3D elemental impurity guidelines. New Jersey and Massachusetts biotech corridors source liposomal-grade cholesterol for mRNA lipid nanoparticle platforms. Domestic toll manufacturers specialize in supercritical fluid extraction for oxidation-sensitive applications.
Japan
PMDA certification requirements filter supply to JIS-standard qualified producers serving domestic pharmaceutical houses. Osaka and Tokyo pharmaceutical clusters require material certification that bypasses trading company intermediaries. Local manufacturers anchor supply relationships with super-statin developers demanding enantiomerically pure cholesterol derivatives.
Germany
EMA ICH Q3D enforcement tightens residual metal thresholds for sterol-derived APIs entering European markets. Frankfurt and Munich generic producers mandate full supply chain solvent mapping from Asian API suppliers. ECHA REACH authorization requirements for residual solvent classifications drive disclosure obligations for imported cholesterol grades.
Cholesterol API Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated refiners commanding statin-grade volumes while toll operators capture liposomal-grade premiums. The vendor base organizes around three archetypes: wool-grease-integrated extractors, synthetic-route specialists, and fermentation-derived phytosterol innovators. Consolidation pressure favors certified manufacturers capable of validated metal control under tightening pharmacopeial standards. Capacity expansion and continuous processing adoption represent the dominant competitive vectors.
Within the integrated extraction tier, Zhejiang Garden Biochemical exemplifies backward integration from sterol feedstock to finished API purification. Dishman Carbogen Amcis occupies a position among European toll manufacturers specializing in high-purity derivatives for regulated-market supply. Nippon Fine Chemical anchors Japanese domestic supply relationships through JIS-standard material qualification.
| Leading Market Players |
|---|
| Zhejiang Garden Biochemical |
| Dishman Carbogen Amcis |
| Croda International |
| Nippon Fine Chemical |
| Merck KGaA |
| Anhui Chem-Bright Bioengineering |
| NOF Corporation |
| Tokyo Chemical Industry |
| Avanti Polar Lipids |
| Others |
Value Chain & Pricing Dynamics
Generic statin producers concentrate procurement among CDSCO-registered Indian contract manufacturers, locking in contract-based long-term offtake pricing that insulates volume buyers from wool grease feedstock volatility. This buyer-archetype consolidation compresses margin capture for non-integrated refiners while rewarding certified manufacturers with validated metal control capabilities.
Pricing Analysis
Distributor margins collapse in direct-to-API-producer relationships, with contract manufacturers capturing value through three-tier pricing structure across liposomal-grade premium, standard pharmacopeial, and economy statin-feedstock levels. Price differentiation rests on oxidation specification thresholds and CDSCO registration status, with sub-0.5% oxidation grades commanding substantial premia. Pricing pressure stems from generic statin price erosion in hyperlipidemia treatment, forcing economy-grade suppliers toward continuous processing adoption. Large-volume Indian generic houses exhibit lowest price sensitivity; mRNA platform developers accept premium tiers for validated liposomal supply.
Supply Chain Analysis
Certification gating through FDA drug master file review, EMA ICH Q3D compliance, and CDSCO phased manufacturing registration fragments supply eligibility and creates tiered supplier pools. Geographic concentration centers on Zhejiang province, India, and Germany, with over sixty percent of sterol extraction capacity clustered in Chinese coastal cities. Raw material dependencies draw from Australian and New Zealand wool grease, chromatographic resins, and supercritical CO2 processing equipment. Single-geography concentration in Zhejiang exposes multi-destination chains to localized disruption risks. Distribution runs through direct manufacturer-to-contract-manufacturer relationships, bypassing traditional chemical distributor networks for qualified pharmaceutical supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in cholesterol API supply hinges on continuous chromatography adoption collapsing production cycle times and liposomal-grade demand multiplying premium-tier offtake.
For Market Incumbents: Cement supply relationships with mRNA platform developers before pharmacopeial certification divergence widens, while retrofitting batch facilities with supercritical fluid extraction trains to capture liposomal-grade premia. Fermentation-derived phytosterol substitution threatens non-statin applications, demanding backward integration into wool grease refining or synthetic route development to defend position. Capacity addition in Saudi Arabia toll manufacturing partnerships accesses SFDA import substitution incentives serving Middle East generic markets. For New Entrants and Emerging Players: Launch via continuous processing technology licensing to Indian CDSCO-registered facilities seeking cost-positioned entry into economy-grade statin supply. Liposomal-grade cholesterol for mRNA lipid nanoparticle applications represents the most penetrable white space, with validated oxidation specifications below 0.5% filtering incumbent competition. Target biotechnology firm direct procurement relationships, bypassing established pharmaceutical house supplier qualification cycles through platform-specific technical partnerships. For Investors and Strategic Acquirers: Contract manufacturers with validated metal control capabilities are the most active acquirer targets in this space, as EMA ICH Q3D enforcement consolidates volume among certified producers. Long-term viability favors facilities with modular quality systems capable of rapid USP-EP-IP standard switching. Watch ECHA REACH authorization requirements for residual solvent classifications as the inflection signal forcing capital deployment into dedicated distillation stages.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Chromatography Adoption | Simulated moving bed systems reduce solvent consumption versus batch crystallization, enabling cost-positioned supply to Indian generic statin producers. |
| Supercritical Fluid Extraction Retrofit | Continuous SFE trains collapse production cycles for liposomal-grade cholesterol serving mRNA platform developers. |
| CDSCO Registration Completion | Phased manufacturing program certification secures multi-year offtake agreements with export-oriented generic statin houses. |
| JIS-Standard Material Qualification | PMDA certification opens direct supply relationships with Japanese pharmaceutical houses bypassing trading intermediaries. |
| Backward Integration into Wool Grease | Captive feedstock supply insulates margin predictability from Australian and New Zealand wool production cycle volatility. |
Study Parameters
Bottom-up statin synthesis pathway modeling reconciled against top-down sterol extraction capacity tracking forms the analytical core of this study. Primary interviews with API facility plant managers, regulatory affairs leads at CDSCO-registered manufacturers, generic statin procurement directors, and liposomal formulation scientists combined with secondary validation against FDA drug master file databases, EMA submission records, CDSCO manufacturing program registrations, and customs trade data. Triangulation across these sources calibrated volume and value estimates.
Input-output matrices mapped cholesterol API consumption across product type, end-user procurement model, delivery mode purity tier, and geographic regulatory cluster. CAGRs were derived from segment-level growth rate reconciliation against aggregate market trajectory. Forecast inputs incorporated liposomal formulation expansion rates, statin generic substitution patterns, and pharmacopeial harmonization divergence timelines across the projection horizon.
Several conditions sit outside the modeled scope, including biotechnological substitution timelines for fermentation-derived phytosterols and geopolitical disruption scenarios affecting Zhejiang province production clusters. Forecasts reflect assumptions regarding sustained mRNA therapeutic platform expansion and stable wool grease feedstock availability. A model refresh is warranted upon material change in EMA ICH Q3D elemental impurity enforcement stringency or CDSCO phased manufacturing program eligibility criteria.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Egg Yolk Oil Market
Ingredients
Mastic Gum Market
Ingredients
Barley Malt Extract Market
Ingredients
Edible Fiber Market
Ingredients
Quark Powder Market
Ingredients
Peanut Ingredients Market
Ingredients
Industrial Sugar Market
Ingredients
Marine Hyaluronic Ingredients Market
Ingredients
China Cane Sugar Market
Ingredients
Rose Extract Market
Ingredients
Clean Label Flour Market
Ingredients
Cheese Cultures Market
Ingredients
Smoked Yeast Market
Ingredients
Eucalyptus Oil Market
Ingredients
Asia-Pacific Whey Protein Ingredients Market
Ingredients
Agarwood Oil Market