
 Global Malted Barley Market | 2026-2036
Global Malted Barley Market Size, Share, and Industry Trends Forecast 2026-2036
Global Malted Barley Market Outlook
Australia is fragmenting as new craft malt houses challenge legacy exporters. Malteurop Group leverages vertical integration from barley breeding to kilning across four continents. Cargill sustains ocean freight advantages through dedicated grain terminals on the US Gulf Coast. Soufflet Group anchors French agronomy networks to secure heritage barley varieties for premium brewing accounts.
Malted barley consists of germinated cereal grain dried in controlled kilning cycles to develop enzymatic diastatic power, typically achieving moisture content below six percent and soluble nitrogen ratios calibrated to brew specifications. The process converts starches into fermentable sugars for wort production in lager and ale systems. Pale malt and pilsner malt dominate volume throughput in commercial brewing, though roasted malt commands margin premiums from stout and porter specialists. Craft breweries as an end-user segment outpace commercial brewery growth rates, while direct sales channels capture share from distributor networks among large-scale distillers seeking batch consistency documentation.
EU Green Deal carbon accounting rules, US FDA food facility registration requirements, and Australia's CEA energy efficiency standards collectively shape kiln modernization timelines and cross-border shipment protocols. EMA-aligned food-grade certifications in Europe and FDA Good Manufacturing Practice audits in North America filter market access for smaller maltsters without laboratory infrastructure. Stakeholders must monitor brewing water chemistry trends and regenerative barley farming contracts as sustainability credentials displace price in procurement decisions.
Market Dynamics
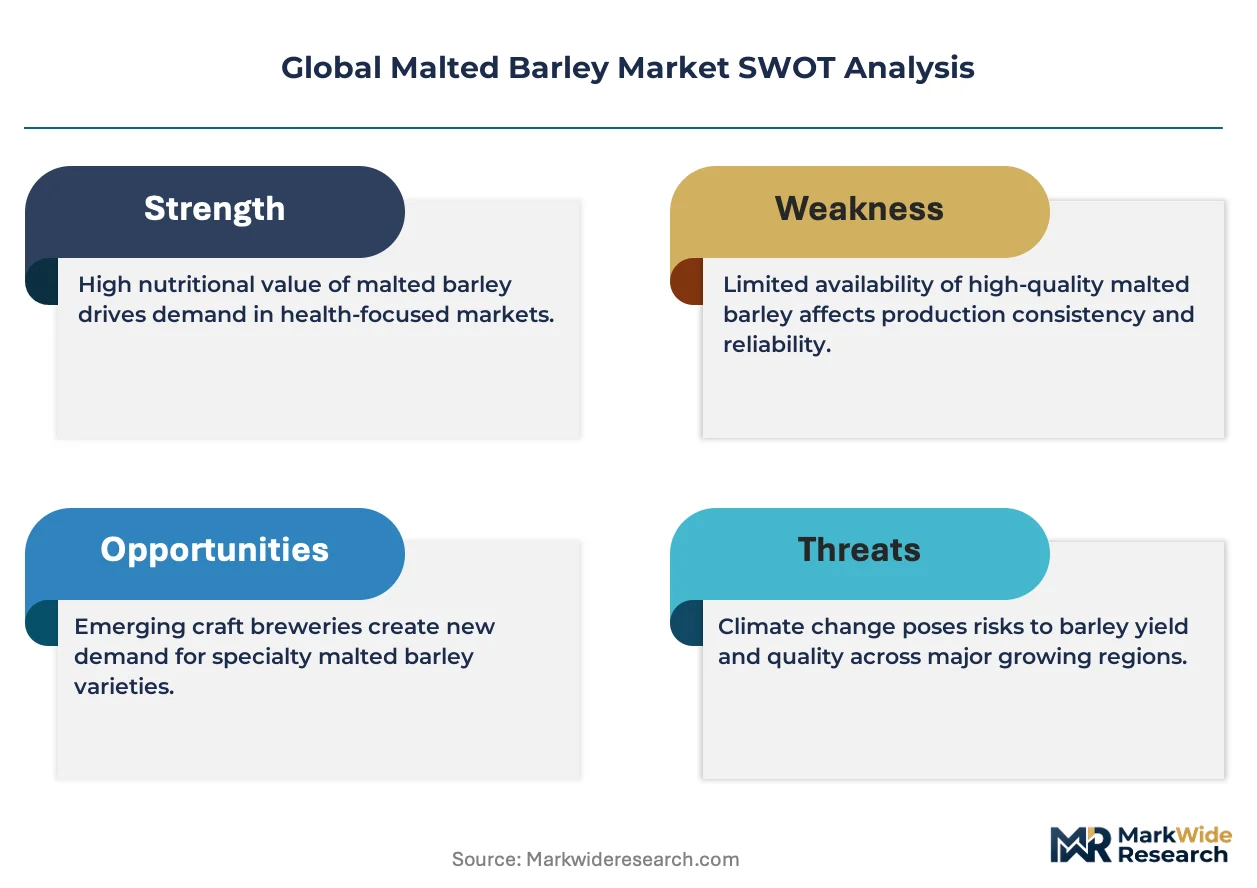
EU Green Deal carbon accounting rules and Australia's CEA energy efficiency standards are forcing simultaneous kiln modernization across malt houses, compressing capital deployment timelines while fragmenting competitive positioning between legacy exporters and craft malt specialists.
Growth Catalysts
- Craft brewery proliferation:Specialty pale and pilsner malt consumption accelerates as small-batch brewers in Germany and the United States expand capacity and demand batch-traceable sourcing.
- EU Green Deal mandates:Carbon-neutral kilning requirements create procurement pull for heritage barley varieties grown under regenerative farming contracts.
- Distiller direct channels:Large-scale whiskey and spirits producers bypass distributor networks to secure documentation consistency, reshaping maltster customer relationships.
Market Restraints
- Natural gas price volatility:Kiln fuel costs represent 35-45% of malt production economics, exposing margins to European and Australian energy market swings.
- Export concentration risk:Australian bulk malt shipments depend on United Malt Group and GrainCorp terminal capacity, creating single-point vulnerabilities for Asia-Pacific brewers.
- Barley variety lock-in:Brewing water chemistry specifications constrain switching between heritage and modern cultivars, limiting sourcing flexibility for premium accounts.
Strategic Opportunities
- Carbon credit monetization:EU Emissions Trading System compliance pathways allow maltsters to capture value from biogas kiln retrofits and regenerative barley contracts.
- Specialty roasted malt white space:Stout and porter specialists command margin premiums that pale malt commoditization cannot match, rewarding flavor-focused product development.
- Blockchain traceability integration:Batch documentation systems satisfy distiller audit requirements while opening direct-to-brewer subscription channels.
Industry Challenges
- Diastatic power calibration expertise:Soluble nitrogen ratio management requires skilled kiln operators, and talent scarcity constrains craft malt house scale-up.
- EMA and FDA audit timelines:Food-grade certification delays for smaller maltsters without captive laboratory infrastructure freeze market access for 12-18 months.
- Legacy ERP integration:Carbon accounting data capture for EU Green Deal reporting conflicts with existing batch management systems, forcing expensive middleware deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Malted Barley Market |
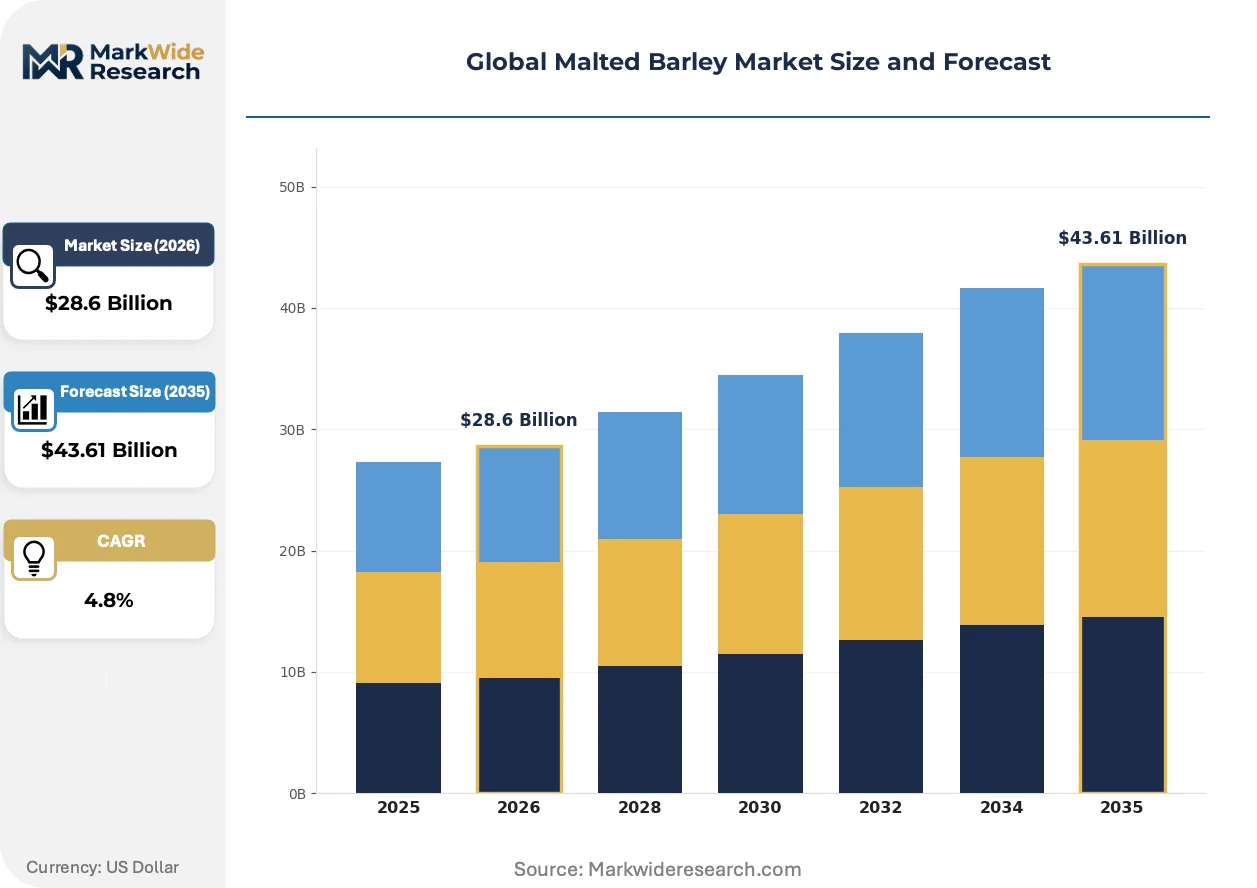
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.61 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pale Malt, Pilsner Malt, Roasted Malt, Amber Malt Application: Brewing, Distilling, Food Production, Snacks End User: Commercial Breweries, Craft Breweries, Distillers, Bakeries Distribution Channel: Direct Sales, Retail, Online Sales, Distributors |
| Companies Covered | Malteurop Group, Cargill, Soufflet Group, GrainCorp, Crisp Malting Group, Boortmalt, Muntons, Rahr Corporation, United Malt Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Malted Barley Market Strategic Shifts
Kiln control systems and barley breeding platforms are virtualizing traditional malting craftsmanship, compressing the expertise gap between industrial and craft production while enabling new entrants to challenge established export hierarchies.
Digital twin technology for kilning cycle optimization is virtualizing moisture content and enzymatic development control that previously required decades of operator experience. Mid-sized craft malt houses in Belgium and the Czech Republic deploy these systems to match consistency benchmarks of century-old industrial facilities. The technology is virtualizing quality assurance labor, allowing new entrants to bypass apprenticeship-based skill acquisition.
EU Green Deal carbon border adjustment mechanisms are reshaping cross-border malt shipment protocols, requiring embedded emissions documentation from germination through kilning. French and German maltsters retrofit biogas-fired kilns to maintain access to Nordic brewing accounts. Roasted malt categories face disproportionate compliance burden due to extended high-temperature energy intensity.
Brewing water chemistry transparency is displacing price as the primary procurement criterion for premium lager producers. German and Japanese brewers now require barley variety provenance and kilning fuel source disclosure before contract award. This specification creep favors maltsters with backward integration into barley breeding and captive regenerative farming networks.
Global Malted Barley Market Segmentation
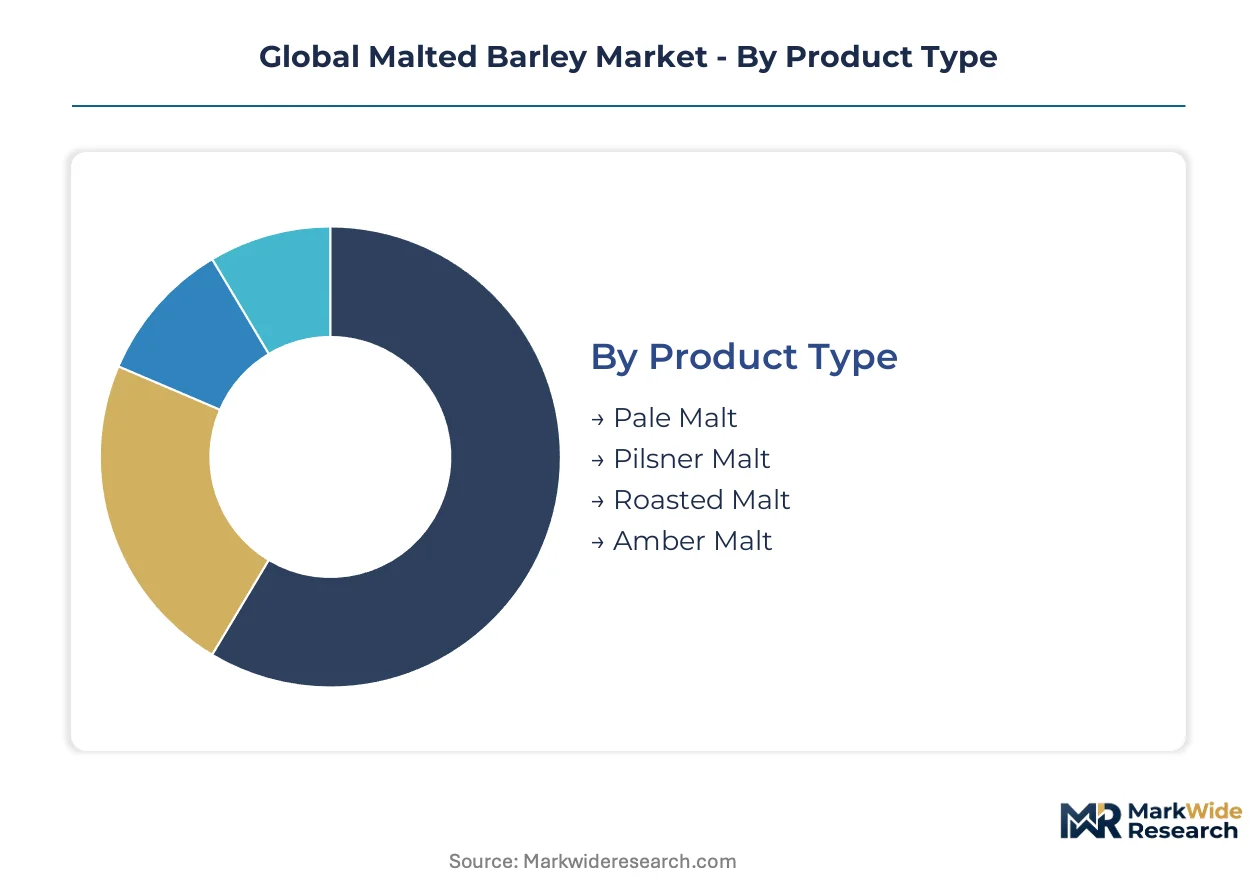
Maltsters calibrate production portfolios against divergent margin profiles across brewing, distilling, and food applications. Product specifications vary sharply between enzymatic base malts for lager systems and roasted specialties for color and flavor contribution. End-user scale determines whether batch traceability or volume throughput dominates procurement criteria.
Product Type:
Cost tier differentiation separates commodity base malts from premium roasted categories with distinct kilning economics and margin structures.
- Pale Malt:Standard two-row barley germinated under controlled moisture achieves diastatic power of 120-160 Lintner for wort conversion in lager and ale systems. Commercial breweries in Germany and the United States absorb volume through long-term supply agreements tied to brewing water chemistry specifications.
- Pilsner Malt:Extended low-temperature kilning below 85°C preserves delicate enzyme profiles and pale color for Bohemian-style lagers. Czech and Belgian craft breweries specify this grade for single-infusion mashing systems where protein rest flexibility matters.
- Roasted Malt:High-temperature finishing develops Maillard compounds for color and roasted flavor in stout and porter recipes.
- Amber Malt:Intermediate kilning caramelizes starches for biscuit and toffee notes in English ale traditions.
Pale Malt commands the established base. The steepest expansion runs through Roasted Malt.
Application:
Volume concentration in brewing contrasts with margin intensity in distilling and emerging food uses.
- Brewing:Wort production for lager, ale, and specialty beer styles consumes enzymatic base malts calibrated to brewhouse efficiency targets. German and Australian brewing clusters specify heritage barley varieties for premium positioning.
- Distilling:Whiskey and spirits producers require high-extract, low-nitrogen malts for fermentable sugar yield and congeners control. Scottish and Irish distillers enforce batch documentation standards that reshape maltster customer relationships.
- Food Production:Malt extracts and syrups supply bakery and confectionery applications for flavor and browning.
- Snacks:Malted barley flour and crisped grains enter cereal and energy bar formulations.
Brewing anchors volume throughput. Distilling is climbing the fastest on margin contribution.
End User:
Customer scale determines whether procurement prioritizes price efficiency or supply chain transparency.
- Commercial Breweries:Large-scale lager producers negotiate annual contracts with specification tolerance bands for moisture and protein. Brazilian and Mexican brewing facilities optimize for extract yield per tonne.
- Craft Breweries:Small-batch operators in the United States and Germany demand varietal provenance disclosure and regenerative farming credentials. These accounts tolerate premium pricing for batch-traceable specialty malts.
- Distillers:Whiskey producers require consistency documentation across multi-year aging programs.
- Bakeries:Artisan and industrial bakers use malt extracts for fermentation activation and crust color.
Commercial Breweries retain the volume base. Craft Breweries are gaining share fastest on specification creep.
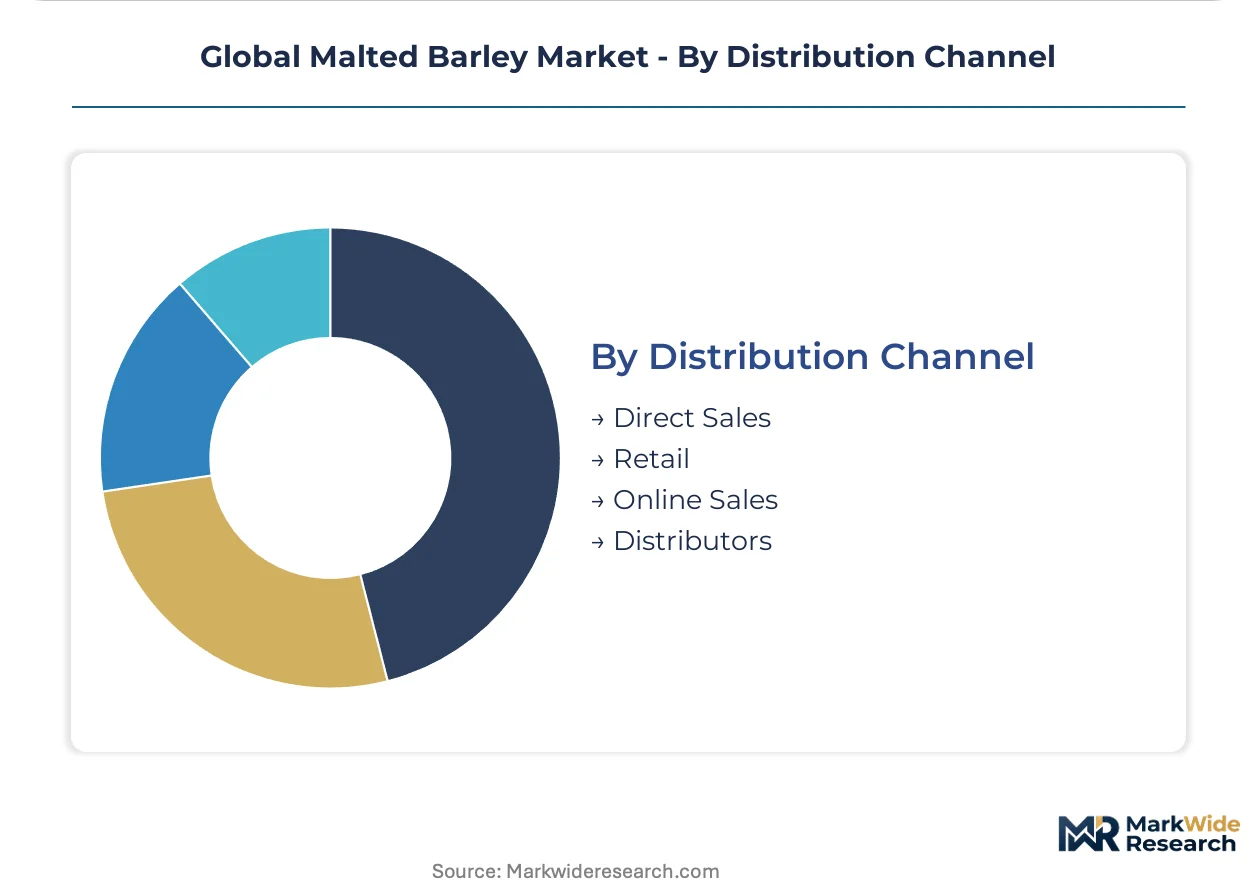
Distribution Channel:
Channel selection reflects end-user scale and documentation requirements for food-grade compliance.
- Direct Sales:Large distillers and multinational brewers bypass intermediaries to secure audit trails and volume commitments. Malteurop and Soufflet Group operate dedicated account teams for these relationships.
- Retail:Homebrew supply stores and specialty food retailers stock small-package malt for consumer brewing kits.
- Online Sales:Direct-to-brewer platforms serve craft malt houses with subscription models for rotating specialty releases.
- Distributors:Regional beverage supply houses aggregate fragmented craft brewery demand with consolidated logistics.
Direct Sales holds the contract value base. Online Sales is expanding most quickly among craft-focused maltsters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's bulk grain terminals underwrite German export dominance, while dedicated malt terminals on the US Gulf Coast anchor trans-Atlantic supply chains. Australian port infrastructure at Geelong and Newcastle concentrates Asia-Pacific shipment capacity.
Germany
Craft brewery clusters in Bavaria and Baden-Württemberg absorb specialty pale and pilsner malts at premium pricing. EU Green Deal carbon accounting rules force kiln modernization across Franconia malting facilities. Hamburg anchors northern export logistics, with Bremerhaven terminals handling bulk shipments to Nordic brewing accounts.
United States
Small-batch brewers in Colorado and Oregon drive specialty malt consumption with batch-traceable sourcing requirements. FDA food facility registration requirements shape laboratory infrastructure investments across Great Plains malt houses. Milwaukee and St. Louis brewing heritage clusters sustain technical specification dialogue between maltsters and brewhouse engineers.
Australia
Asia-Pacific brewing demand concentrates export throughput through Geelong and Newcastle terminal assets. CEA energy efficiency standards compress kiln retrofit timelines across Victoria and New South Wales production sites. United Malt Group and GrainCorp anchor terminal capacity, though craft malt houses in Adelaide challenge legacy export hierarchies.
France
Premium brewing accounts in Île-de-France and Hauts-de-France specify heritage barley varieties with regenerative farming credentials. ANSM and EU Green Deal compliance pathways favor maltsters with backward integration into captive agronomy networks. Lille and Strasbourg malting clusters leverage proximity to Belgian and German brewing customers.
United Kingdom
Scottish and Irish distillers enforce batch documentation standards that reshape maltster customer relationships. EMA-aligned food-grade certifications filter market access for smaller English maltsters without captive laboratory infrastructure. Edinburgh and Inverness distilling corridors concentrate high-extract, low-nitrogen malt demand for whiskey aging programs.
Global Malted Barley Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in breeding and agronomy. The vendor base stratifies between century-old industrial maltsters with captive terminal assets and craft-focused entrants deploying digital kiln control. Three archetypes dominate: vertically integrated grain-to-malt conglomerates, regional specialists with heritage variety portfolios, and technology-enabled craft houses. Capacity expansion and biogas kiln retrofits represent the dominant competitive vectors as carbon accounting rules harden.
Among French agronomy-anchored conglomerates, Soufflet Group exemplifies backward integration into heritage barley breeding. Malteurop Group occupies the multi-continent platform tier with breeding-to-kilning control across four continents. Cargill sits within the grain-trading-origin archetype, leveraging Gulf Coast terminal infrastructure for ocean freight positioning.
| Leading Market Players |
|---|
| Malteurop Group |
| Cargill |
| Soufflet Group |
| GrainCorp |
| Crisp Malting Group |
| Boortmalt |
| Muntons |
| Rahr Corporation |
| United Malt Group |
| Others |
Value Chain & Pricing Dynamics
The Hamburg-Bremerhaven bulk grain corridor anchors trans-Atlantic malt pricing, with ocean freight rate volatility transmitting directly into contract tiering for German export houses and Australian terminal operators while EU Green Deal carbon accounting forces kilning cost pass-throughs that widen spreads between heritage variety premiums and commodity base malt.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates batch-traceable heritage malts for craft distillers from commercial brewery contracts and spot-market commodity grades. Price differentiation rests on carbon-neutral kilning certification and brewing water chemistry documentation, with EU Emissions Trading System compliance costs intensifying margin compression in the standard tier. Craft breweries exhibit lowest price sensitivity, while Brazilian and Mexican commercial lager producers negotiate aggressively on extract yield per tonne.
Supply Chain Analysis
Malteurop Group and Cargill hold concentrated germination and kilning capacity across France, Germany, and the United States Gulf Coast. Raw material flows draw from Australian breeding programs, Canadian prairie barley, and French agronomy networks. Single-source vulnerability concentrates in Geelong and Newcastle terminal assets controlled by United Malt Group and GrainCorp. Distribution runs through direct sales contracts for multinational distillers and regional beverage distributors for fragmented craft brewery demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory entrenchment story where EU Green Deal carbon accounting and FDA food facility registration requirements create switching costs that cement incumbent positions while freezing out laboratory-deficient challengers for 12-18 month certification windows.
For Market Incumbents: Entrench through biogas kiln retrofits that capture EU Emissions Trading System credits while locking in Nordic brewing accounts with embedded emissions documentation. Add dedicated malt terminals on the US Gulf Coast to mirror Cargill's ocean freight positioning. Digital twin kiln control investments virtualize operator expertise scarcity that constrains craft malt house scale-up.
For New Entrants and Emerging Players: Specialty roasted malt for stout and porter specialists represents the most penetrable entry point, as extended high-temperature kilning faces disproportionate compliance burden that industrial incumbents avoid. Belgian and Czech craft malt houses deploying digital twin systems demonstrate viability. Subscription-based direct-to-brewer platforms bypass distributor margin capture.
For Investors and Strategic Acquirers: Regional specialists with captive heritage barley breeding programs and regenerative farming contract networks offer durable margin insulation. Long-term viability favors maltsters with backward integration into agronomy rather than pure toll-kilning operations. Watch brewing water chemistry specification creep as the inflection signal for premium procurement pull.
| Strategic Initiative | Industry Significance |
|---|---|
| Biogas Kiln Retrofit | EU Green Deal compliance secures Nordic brewing account access for French and German maltsters. |
| Heritage Barley Breeding Program | Captive agronomy networks supply regenerative farming credentials that displace price in procurement. |
| Blockchain Traceability Integration | Batch documentation satisfies Scottish and Irish distiller audit requirements for multi-year aging programs. |
| Digital Twin Kiln Deployment | Virtualized moisture control allows Belgian craft entrants to match century-old industrial consistency benchmarks. |
| Gulf Coast Terminal Expansion | Dedicated grain assets replicate Cargill's ocean freight advantages for trans-Atlantic malt shipments. |
Study Parameters
A standing panel of malt house operations directors, craft brewery head brewers, distiller procurement leads, and barley agronomists provided ongoing calibration throughout the study. Primary fieldwork combined structured interviews across German malting clusters, Australian export terminals, and US craft brewing corridors with secondary validation from EU ETS compliance filings, FDA food facility registration databases, and customs trade records. Bottom-up volume modeling across product type, application, and end-user segments triangulated against top-down macroeconomic drivers.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning pale/pilsner/roasted malt grades, brewing/distilling/food applications, and commercial versus craft end-user scale. CAGRs derived from historical shipment data through major port terminals and forward contract coverage ratios. Kiln modernization capex cycles and EU carbon border adjustment implementation timelines served as key forecast inputs.
Practitioners should monitor natural gas price volatility, EU ETS allowance auction dynamics, and brewing water chemistry specification announcements for early signals of forecast revision. Quarterly review of heritage barley variety adoption rates and regenerative farming contract penetration is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Global Premium Gin Market
Alcoholic Beverages
South America Beer Market
Alcoholic Beverages
South America Fermented Drinks Market
Alcoholic Beverages
UK Tequila Market
Alcoholic Beverages
Beer Line Cooling System Market
Alcoholic Beverages
Cognac Market
Alcoholic Beverages
Malaysia Alcohol E-Commerce Market
Alcoholic Beverages
Turkey Tequila Market
Alcoholic Beverages
Bahrain Alcoholic Beverages Market
Alcoholic Beverages
Wine Cork Market
Alcoholic Beverages
Gin Market
Alcoholic Beverages
Beer Adjuncts Market
Alcoholic Beverages
Pisco Market
Alcoholic Beverages
North America Alcoholic Beverages Market
Alcoholic Beverages
Asia Pacific Beer Market
Alcoholic Beverages
Low Alcohol Beverages Market