
 Anhydrous Caffeine Market | 2026-2036
Anhydrous Caffeine Market Size, Share, and Industry Trends Forecast 2026-2036
Anhydrous Caffeine Market Analysis
Synthetic caffeine derived from urea and chloroacetic acid is decoupling from natural coffee-based extraction on cost and purity metrics. CSPC Pharmaceutical Group Limited leverages backward integration into chloroacetic acid feedstock to control input costs. Shandong Xinhua Pharmaceutical Company Limited anchors its position through pharmaceutical-grade certification pipelines. BASF SE competes on fermentation-derived alkaloid platforms with European regulatory alignment.
Anhydrous caffeine is a dehydrated form of trimethylxanthine containing less than 0.5% water by weight, typically manufactured through sublimation or solvent crystallization to achieve USP-grade purity above 99%. Powder formulations dominate bulk ingredient procurement from contract manufacturers due to blending flexibility in energy drink and pre-workout formulations. Sports nutrition applications now outpace pharmaceutical demand growth as fitness-oriented retail consumers shift procurement toward direct-to-consumer channels. Tablet and capsule segments retain higher margin pools through pharmacy and specialty store distribution where medical professionals and regulated health claims sustain price premiums.
US FDA and EPA frameworks govern residual solvent limits and environmental discharge from caffeine synthesis facilities, while China's NMPA and MEE enforce dual carbon goals that elevate energy costs for coal-dependent sublimation plants. India's CDSCO and BIS standards for active pharmaceutical ingredients create compliance barriers for unregistered importers. Stakeholders must monitor regulatory divergence between pharmaceutical-grade and food-grade purity specifications as classification determines market access pathways.
Market Dynamics
Synthetic caffeine production is absorbing volume from natural extraction as urea-chloroacetic acid routes achieve cost parity at pharmaceutical purity thresholds. Contract manufacturers in China and India are consolidating procurement relationships with sports nutrition brands, compressing traditional pharmaceutical buyer dominance.
Growth Catalysts
- Sports nutrition procurement surge:Energy drink and pre-workout formulators now order bulk powder volumes exceeding legacy pharmaceutical contracts. Direct-to-consumer fitness brands bypass traditional distribution tiers.
- Dual carbon policy enforcement:China's MEE mandates are accelerating coal-to-gas conversions at sublimation facilities, improving process yields for export-grade anhydrous caffeine.
- USP-grade certification pipelines:Pharmaceutical-grade purity specifications above 99% are unlocking regulated markets where medical professionals sustain premium pricing for tablet and capsule formats.
Market Restraints
- Chloroacetic acid feedstock volatility:Petrochemical input costs fluctuate with crude derivatives, squeezing margins for non-integrated synthetic caffeine producers.
- Coal-dependent energy baselines:Sublimation plants in Shandong and Hebei provinces face elevated electricity costs under provincial carbon intensity caps.
- Natural extraction capacity constraints:Coffee decaffeination byproduct supply cannot scale to match synthetic route economics for cost-sensitive formulations.
Strategic Opportunities
- Fermentation-derived alkaloid platforms:BASF SE and European competitors are developing biotechnological routes that align with EMA sustainability criteria for pharmaceutical applications.
- India CDSCO registration pathways:Unregistered importers face compliance barriers that create first-mover advantages for API-certified domestic manufacturers.
- Specialty pharmacy distribution:Medical-grade tablet and capsule segments retain higher margin pools through regulated health claims and professional recommendation channels.
Industry Challenges
- Residual solvent compliance timelines:US FDA and EPA frameworks demand extended validation periods for solvent crystallization facilities seeking pharmaceutical-grade certification.
- Cross-grade specification divergence:Food-grade and pharmaceutical-grade purity thresholds create classification ambiguities that complicate multi-market registration strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anhydrous Caffeine Market |
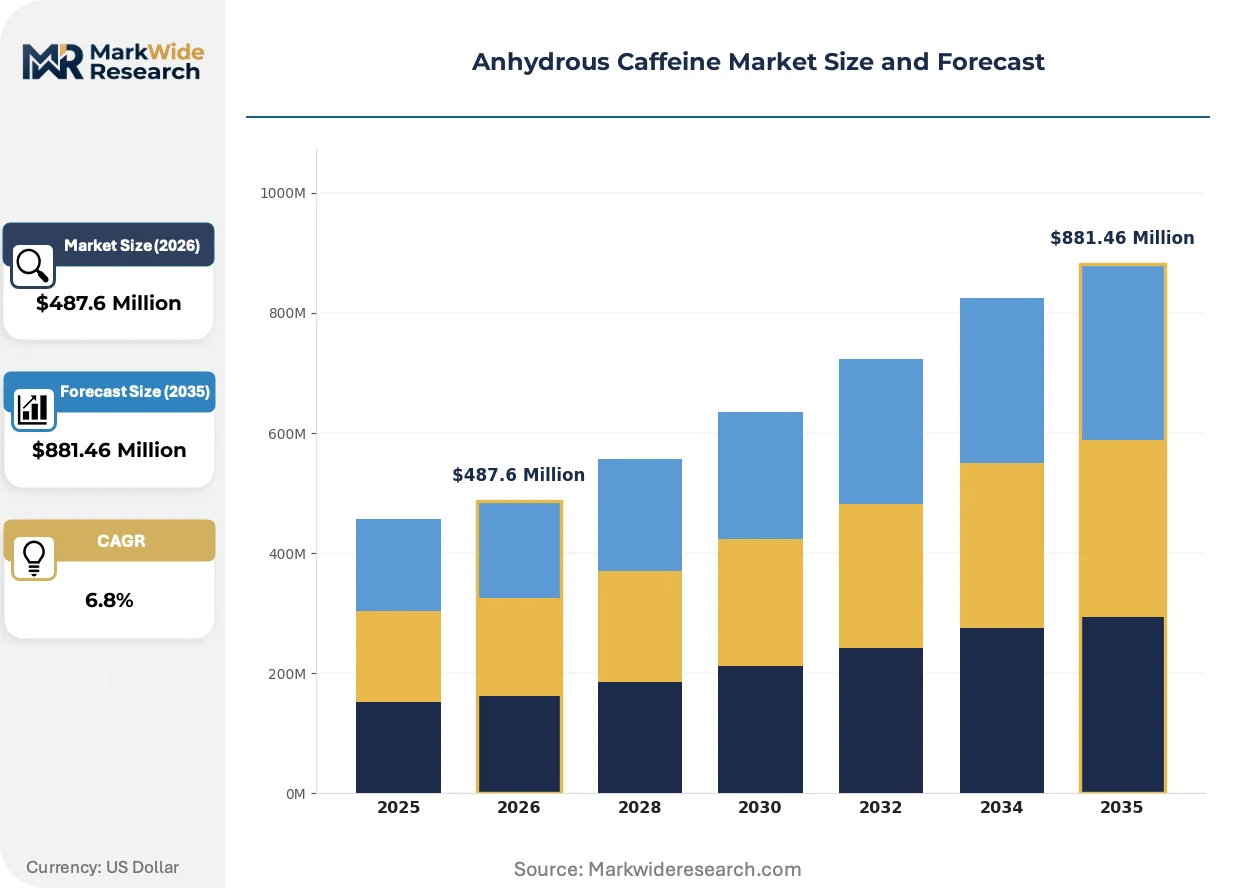
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablet, Powder, Capsule, Liquid Application: Dietary Supplements, Energy Drinks, Pharmaceuticals, Sports Nutrition End User: Retail Consumers, Fitness Enthusiasts, Medical Professionals, Manufacturers Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Supermarkets |
| Companies Covered | Archer Daniels Midland Company, Tate Lyle, BASF SE, Ajinomoto, Aarti Industries Limited, CSPC Pharmaceutical Group Limited, Cargill Inc, DuPont, Shandong Xinhua Pharmaceutical Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anhydrous Caffeine Market Emerging Trajectories
Manufacturing technology and regulatory classification are reshaping competitive boundaries in anhydrous caffeine supply. Process innovation, environmental compliance, and buyer channel evolution are compressing legacy procurement patterns.
Continuous sublimation systems with integrated solvent recovery are absorbing capital investment from batch crystallization infrastructure. Large-scale contract manufacturers in Shandong province are retrofitting facilities to meet NMPA dual carbon enforcement timelines. The technology is absorbing margin pressure from energy cost inflation while maintaining USP-grade output consistency.
REACH registration requirements for chloroacetic acid derivatives are tightening import documentation for European pharmaceutical formulators. ECHA substance evaluation protocols now demand expanded toxicological datasets for synthetic caffeine batches above 10-ton annual volumes. German and Swiss buyers are consolidating supplier relationships with backward-integrated producers possessing verified feedstock chain-of-custody records.
Direct-procurement contracts between sports nutrition brands and API manufacturers are disintermediating traditional chemical distributors. Fitness-oriented retail consumers are shifting volume toward private-label energy drink producers who blend at captive facilities. This channel compression is most visible in North American and Western European markets where vertically integrated contract manufacturers offer powder-to-finished-product services.
Anhydrous Caffeine Market Segmentation
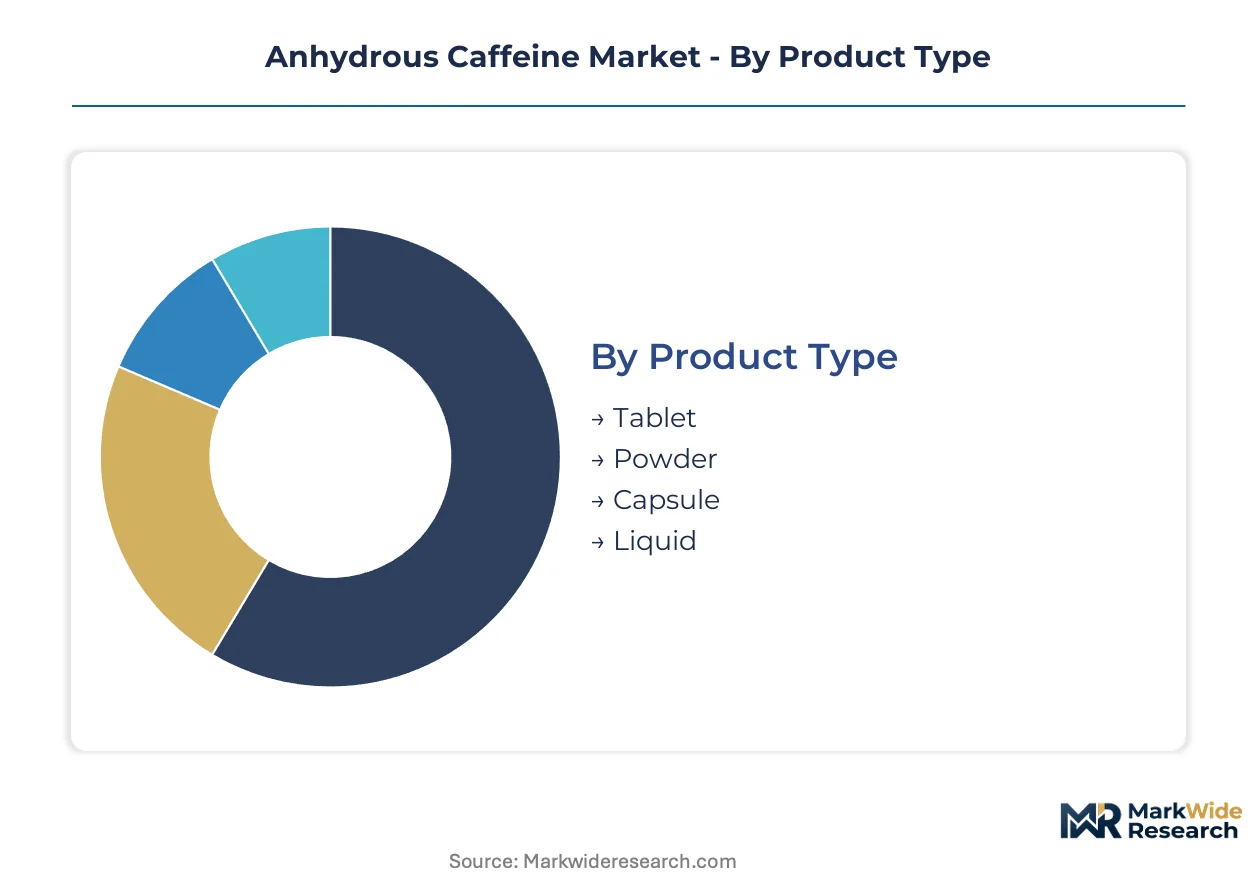
Anhydrous caffeine segmentation reveals divergent margin structures across physical formats and procurement channels. Powder formulations command bulk volume through contract manufacturing, while tablet and capsule formats sustain premium pricing in regulated distribution environments.
Product Type:
Procurement scale and blending flexibility determine buyer selection across physical formats, with manufacturing integration levels varying by segment.
- Powder:Dehydrated crystalline form with USP-grade purity above 99%, manufactured through sublimation or solvent crystallization. Bulk procurement from contract manufacturers in Shandong and Hebei provinces supplies energy drink and pre-workout formulators with blending flexibility.
- Tablet:Compressed dosage units with precise trimethylxanthine content, requiring pharmaceutical-grade certification and extended validation timelines under FDA residual solvent frameworks. Medical professionals and regulated health claims sustain price premiums through pharmacy distribution channels.
- Capsule:Gelatin or vegetable-derived shells containing measured anhydrous caffeine doses, positioned between powder convenience and tablet precision for specialty store placement.
- Liquid:Pre-dissolved formulations in aqueous or hydroalcoholic bases, serving ready-to-drink manufacturers seeking immediate incorporation without hydration steps.
Powder leads on scale; tablet leads on momentum.
Application:
End-use concentration patterns reflect shifting consumer procurement behaviors and channel disintermediation trends.
- Sports Nutrition:Pre-workout powders and energy gels targeting fitness-oriented retail consumers through direct-to-consumer channels. Direct-procurement contracts between brands and API manufacturers are compressing traditional distributor relationships.
- Energy Drinks:Carbonated and still beverages with standardized caffeine content, blending at captive facilities under private-label arrangements. North American and Western European markets show pronounced vertical integration between contract manufacturers and finished-product brands.
- Dietary Supplements:Standalone caffeine products and combination formulations with vitamins or amino acids, distributed through online retail and specialty stores with variable purity specifications.
- Pharmaceuticals:Analgesic combinations and respiratory stimulants requiring USP-grade certification above 99% purity, governed by FDA, EMA, and NMPA frameworks with extended compliance timelines.
Energy drinks lead on scale; sports nutrition climbs the fastest.
End User:
Channel control and recommendation authority create distinct pricing tiers across user categories.
- Manufacturers:Contract manufacturers and finished-product brands procuring bulk powder for captive blending operations, consolidating procurement relationships and compressing traditional pharmaceutical buyer dominance.
- Retail Consumers:Direct purchasers of finished products through online retail and supermarket channels, price-sensitive and brand-loyal with limited technical specification awareness.
- Medical Professionals:Prescribers and pharmacists selecting tablet and capsule formats through regulated pharmacy distribution, sustaining premium positioning through professional recommendation channels.
- Fitness Enthusiasts:Performance-oriented consumers seeking pre-workout and energy formulations, shifting volume toward direct-to-consumer sports nutrition brands with transparent sourcing claims.
Manufacturers lead on scale; fitness enthusiasts lead on momentum.
Distribution Channel:
Channel compression and regulatory classification determine market access pathways and margin retention.
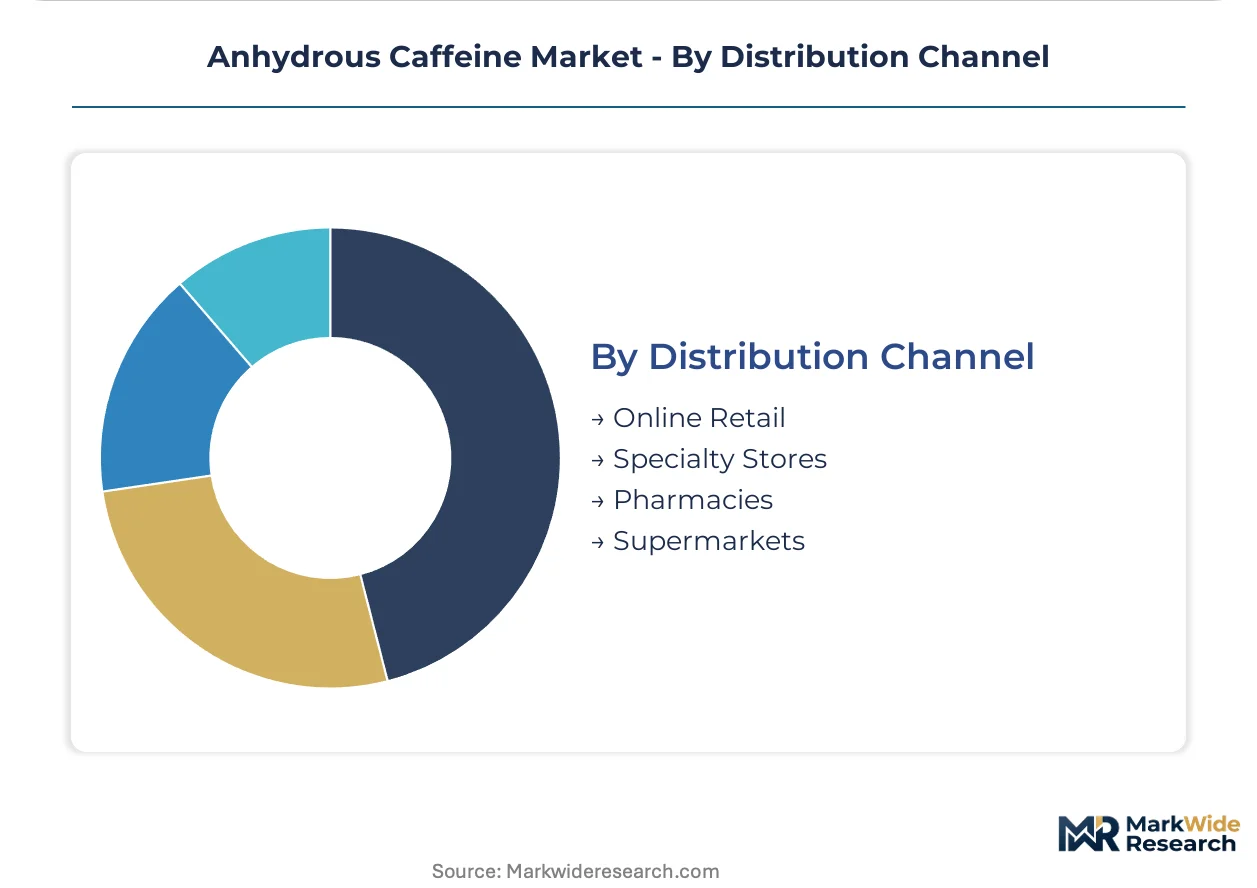
- Online Retail:Direct-to-consumer platforms serving sports nutrition and dietary supplement segments with private-label and branded offerings, disintermediating traditional chemical distributors.
- Pharmacies:Regulated distribution for pharmaceutical-grade tablet and capsule formats, requiring professional dispensing and sustaining price premiums through medical recommendation.
- Specialty Stores:Fitness and nutrition-focused retail with educated staff and curated product selection, bridging mass-market accessibility and premium positioning.
- Supermarkets:Mass-market placement for energy drinks and mainstream dietary supplements, volume-driven with compressed margins and high inventory turnover requirements.
Online retail leads on scale; pharmacies lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong province anchors global anhydrous caffeine manufacturing capacity, with sublimation facilities in Hebei and Jiangsu provinces feeding export demand across pharmaceutical and sports nutrition channels.
China
Sports nutrition procurement contracts and API manufacturing expansion drive volume concentration. NMPA dual carbon enforcement timelines and MEE energy intensity caps are accelerating coal-to-gas conversions at Hebei sublimation plants. Qingdao and Jinan industrial clusters host backward-integrated producers controlling chloroacetic acid feedstock costs.
India
Contract manufacturers are scaling active pharmaceutical ingredient capacity for energy drink and pre-workout formulators. CDSCO registration pathways and BIS purity standards create compliance barriers favoring domestic API-certified producers. Hyderabad and Ahmedabad pharmaceutical corridors concentrate fermentation-derived and synthetic caffeine output for regulated export markets.
United States
Direct-to-consumer sports nutrition brands are consolidating procurement relationships with API manufacturers, bypassing traditional chemical distributors. FDA residual solvent frameworks and EPA environmental discharge limits govern pharmaceutical-grade certification timelines. New Jersey and North Carolina chemical processing hubs blend bulk powder for captive energy drink and dietary supplement facilities.
Germany
REACH registration requirements for chloroacetic acid derivatives and ECHA substance evaluation protocols are tightening import documentation for pharmaceutical formulators. EMA sustainability criteria favor fermentation-derived alkaloid platforms. Ludwigshafen and Frankfurt chemical clusters anchor European pharmaceutical-grade caffeine formulation and distribution.
Switzerland
Swissmedic pharmaceutical certification and professional pharmacy distribution sustain premium pricing for tablet and capsule formats. Basel and Zurich life sciences corridors concentrate finished-dose manufacturing for regulated European and Middle Eastern markets. Swiss buyers consolidate supplier relationships with verified feedstock chain-of-custody documentation.
Anhydrous Caffeine Market Vendor Landscape
Backward integration into chloroacetic acid feedstock dominates the current landscape as the primary competitive maneuver. The vendor base separates into three functional tiers: multinational chemical conglomerates with fermentation platforms, Chinese pharmaceutical groups with coal-to-gas sublimation assets, and Indian API specialists with CDSCO-certified export pipelines. Capacity expansion and regulatory certification acceleration represent the two dominant competitive moves as producers seek pharmaceutical-grade purity thresholds.
Within the Chinese pharmaceutical tier, CSPC Pharmaceutical Group Limited and Shandong Xinhua Pharmaceutical Company Limited occupy positions defined by provincial industrial clustering and feedstock control. BASF SE represents the European fermentation-derived archetype, aligning with EMA sustainability criteria. These three anchors exemplify the geographic and technological bifurcation shaping procurement relationships with sports nutrition and pharmaceutical formulators.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Tate Lyle |
| BASF SE |
| Ajinomoto |
| Aarti Industries Limited |
| CSPC Pharmaceutical Group Limited |
| Cargill Inc |
| DuPont |
| Shandong Xinhua Pharmaceutical Company Limited |
| Others |
Supply Flow & Price Mechanics
Backward integration into chloroacetic acid feedstock anchors both supply position and pricing power for synthetic caffeine producers, creating cost advantages that compress margins for non-integrated competitors. Shandong province sublimation facilities leverage captive chloroacetic acid production to stabilize input costs against petrochemical volatility, while pharmaceutical-grade certification pipelines sustain premium positioning for tablet and capsule formats.
Pricing Analysis
Chloroacetic acid feedstock pass-through dominates synthetic caffeine cost structures, with petrochemical derivative volatility squeezing non-integrated producers. Three-tier pricing structure across pharmaceutical-grade, food-grade, and technical-grade levels separates USP-certified purity above 99% from lower-threshold formulations. Cost compression in food-grade powder runs through energy-intensive sublimation processes as China's MEE dual carbon enforcement elevates electricity costs. Contract manufacturers exhibit highest price sensitivity due to bulk procurement scales, while specialty pharmacy channels sustain lowest sensitivity through professional recommendation authority.
Supply Chain Analysis
Reverse-logistics flows for solvent recovery systems are absorbing capital investment as batch crystallization facilities retrofit for environmental compliance. Manufacturing concentrates in China, India, and Germany, with Shandong and Hebei provinces anchoring global sublimation capacity. Chloroacetic acid, urea, and coal-derived thermal energy constitute critical input dependencies. Single-source vulnerability concentrates in Hebei sublimation clusters facing provincial carbon intensity caps. Distribution runs through direct-procurement contracts between API manufacturers and sports nutrition brands, disintermediating traditional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Anhydrous caffeine represents a late-cycle quality story as sports nutrition procurement shifts toward USP-grade certification and transparent sourcing claims, elevating specification premiums over commodity spot pricing.
For Market Incumbents: Hedge against feedstock volatility by securing long-term chloroacetic acid supply agreements or acquiring backward-integrated production assets in Shandong industrial clusters. Defensive consolidation should prioritize CDSCO-registered Indian API manufacturers facing compliance barriers that protect first-mover positions. Certification investment in EMA-aligned fermentation platforms offers differentiation against coal-dependent sublimation competitors. For New Entrants and Emerging Players: India's CDSCO registration pathways open a window for domestic API-certified producers to capture energy drink and pre-workout formulator contracts bypassing unregistered importers. White-space targets include specialty pharmacy distribution for medical-grade tablet formats and direct-to-consumer sports nutrition channels seeking transparent supply chain documentation. Go-to-market positioning should emphasize verified feedstock chain-of-custody records for European REACH compliance. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented non-integrated producers face margin compression from chloroacetic acid cost volatility and energy transition compliance timelines. Long-term viability favors backward-integrated assets with pharmaceutical-grade certification pipelines and captive feedstock production. Acquisition target archetypes include Shandong-based sublimation facilities with NMPA dual carbon retrofit completion and established sports nutrition procurement relationships. Monitor CDSCO registration acceleration and REACH documentation tightening as inflection indicators for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chloroacetic Acid | Captive feedstock production insulates margins from petrochemical derivative volatility at Shandong facilities. |
| Pharmaceutical-Grade Certification Pipeline | FDA residual solvent validation unlocks regulated tablet and capsule markets with professional recommendation premiums. |
| Coal-to-Gas Sublimation Retrofit | MEE dual carbon compliance maintains export-grade output consistency under provincial energy intensity caps. |
| Direct-Procurement Contract Expansion | Bypassing chemical distributors captures margin compression from fitness-oriented retail channel disintermediation. |
| Fermentation-Derived Alkaloid Platform Development | EMA sustainability criteria alignment differentiates European supply for pharmaceutical applications. |
Methodological Framework
Multiple input streams — executive interviews with API manufacturing heads, procurement leads at sports nutrition brands, and regulatory affairs specialists — were reconciled against customs trade data, NMPA filing records, CDSCO registration databases, and SEC 10-K disclosures from listed chemical producers. Bottom-up volume estimates from individual facility capacities and top-down demand segmentation from end-use applications were triangulated to establish market sizing.
Data-stream reconciliation applied analytical frameworks across product type, application, and end-user dimensions, with additional modeling of certification-grade tier and regional production hub effects. CAGRs were derived through regression analysis of historical procurement patterns and forward projection of channel disintermediation trends. Forecast inputs incorporated energy transition compliance timelines and feedstock cost elasticity assumptions throughout the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated MEE enforcement or chloroacetic acid supply disruption scenarios. Practitioners should monitor CDSCO registration velocity, REACH documentation requirements, and sports nutrition direct-procurement contract announcements for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Soluble Fibers Market
Ingredients
Hydrolyzed Starch Market
Ingredients
Bay Leaf Oil Market
Ingredients
Low-Odor Fish Protein Hydrolysates from Med Species Market
Ingredients
Wheat Protein Concentrates Market
Ingredients
Global Distillers Grains Market
Ingredients
Low Calorie Olive Oil Market
Ingredients
Plant Based Premix Market
Ingredients
Banana Flour Market
Ingredients
South America Agar Market
Ingredients
Hops Derivative Market
Ingredients
Carob Powder Market
Ingredients
Ximenia Oil Market
Ingredients
Bakery Ingredients Market
Ingredients
South America Spirulina Extract Market
Ingredients
France Protein Market