
 Asia-Pacific Dairy Ingredients Market | 2026-2036
Asia-Pacific Dairy Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Dairy Ingredients Market Outlook
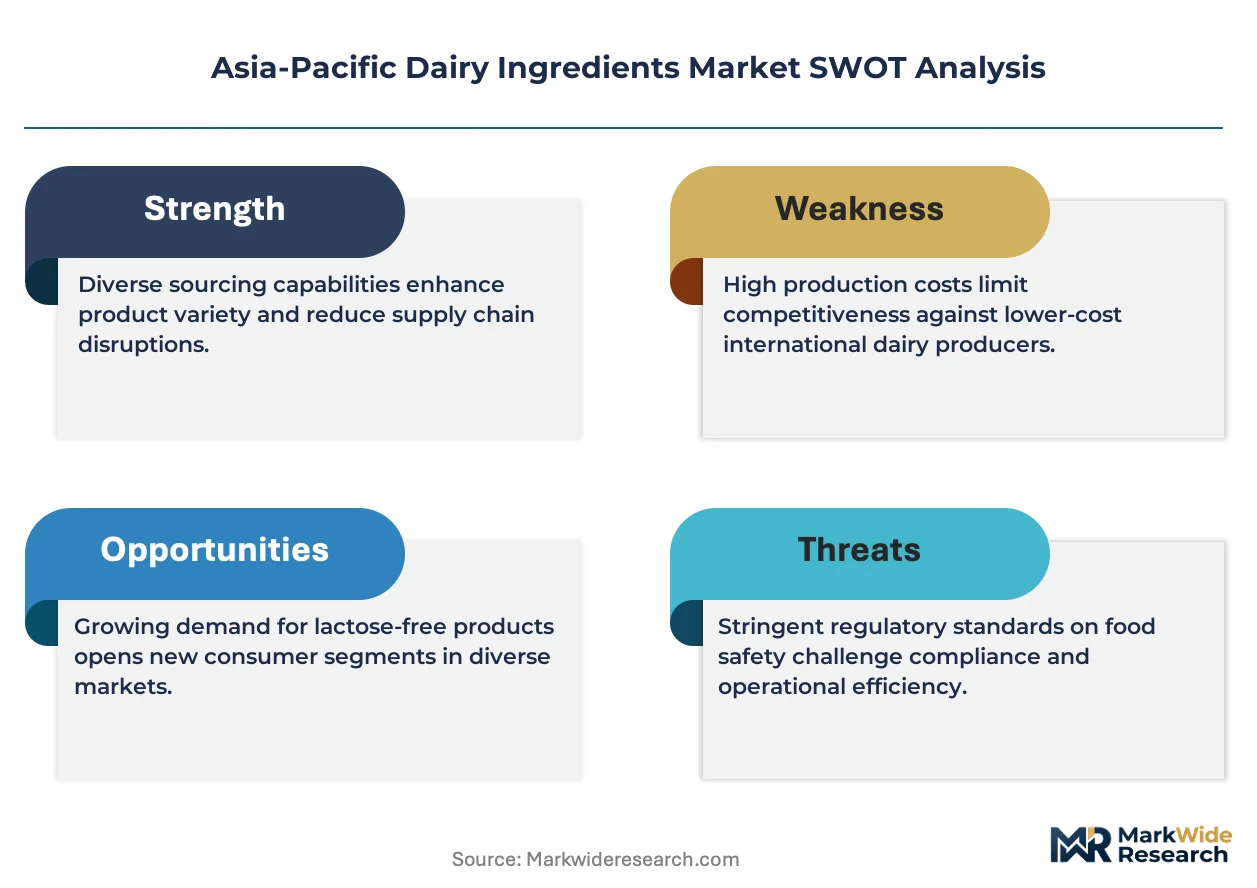
ISO 22000 certification for food safety management systems is redrawing competitive boundaries across the Asia-Pacific Dairy Ingredients Market. Fonterra Co-operative Group leverages its New Zealand-origin supply chain to anchor premium whey protein positions in Chinese infant nutrition channels. Arla Foods Ingredients Group differentiates through specialized milk fractionation capabilities that serve European-standard formulations exported into Southeast Asia. Gujarat Cooperative Milk Marketing Federation dominates domestic Indian procurement networks with backward integration into village-level dairy cooperatives.
Asia-Pacific dairy ingredients encompass dried, concentrated, or fractionated milk-derived components including protein-standardized milk powders with 26-34% protein content, whey protein isolates exceeding 90% protein purity, micellar casein concentrates, and anhydrous milk fat. These ingredients provide functional properties—emulsification, gelation, foaming, and nutritional fortification—to processed food, beverage, and specialized nutrition systems. Milk powder occupies the largest volume position across the region, sustained by reconstitution demand in tea and coffee applications across South Asia. Whey protein registers the fastest structural expansion, propelled by sports nutrition and clinical nutrition adoption in China's tier-one cities and Australia's fitness-oriented consumer base. Infant nutrition end-use commands premium margin pools, where cream and specialized fat blends concentrate value capture.
China's SAMR enforces stringent GB standards for dairy ingredient labeling and compositional claims, while India's FSSAI mandates micronutrient fortification in milk powders distributed through government nutrition programs. Australia's TGA and FSANZ jointly regulate novel dairy bioactive claims, creating dual compliance pathways for functional food exporters. Japan's Ministry of Health, Labour and Welfare maintains positive-list systems for dairy-derived food additives, constraining formulation flexibility for imported ingredients. Stakeholders must monitor divergence between China's evolving national standards and Codex Alimentarius benchmarks to anticipate reformulation costs and regional sourcing reconfigurations.
Market Dynamics
Specialized whey fractionation capabilities are concentrating procurement power among infant nutrition manufacturers in China's eastern seaboard processing clusters, where import dependency for protein-standardized ingredients creates supply security premiums.
Growth Catalysts
- GB Standards Enforcement:China's SAMR tightening of dairy ingredient labeling and compositional claims is forcing domestic reformulation toward higher-value specialized fractions.
- Sports Nutrition Adoption:Whey protein isolates exceeding 90% purity are accelerating in China's tier-one cities and Australia's fitness-oriented consumer base.
- FSSAI Fortification Mandates:India's micronutrient requirements for milk powders distributed through government nutrition programs are standardizing procurement specifications.
Market Restraints
- Import Concentration Risk:China's eastern seaboard clusters depend on New Zealand-origin whey protein supply chains vulnerable to climatic disruption and shipping constraints.
- Positive-List Constraints:Japan's Ministry of Health, Labour and Welfare additive approvals limit formulation flexibility for imported dairy-derived ingredients.
- Butterfat Price Volatility:Anhydrous milk fat production costs fluctuate with New Zealand and Australian pasture conditions and global commodity exchange movements.
Strategic Opportunities
- Clinical Nutrition Expansion:Micellar casein concentrates for medical nutrition applications remain underdeveloped across Southeast Asian hospital and aged-care channels.
- Village Cooperative Integration:Backward integration into India's village-level dairy cooperatives offers procurement scale without import dependency.
- Dual Carbon Alignment:China's MEE emissions frameworks favor domestic processing investments with lower carbon-intensity credentials for European-standard exports.
Industry Challenges
- ISO 22000 Certification Timelines:Food safety management system audits create 12-18 month qualification delays for new suppliers entering Chinese infant nutrition channels.
- Fractionation Skill Scarcity:Specialized milk protein separation expertise concentrates in European and New Zealand processing facilities, constraining regional capacity buildout.
- Codex Divergence Monitoring:Stakeholders must track evolving gaps between China's national standards and Codex Alimentarius benchmarks to anticipate reformulation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Dairy Ingredients Market |
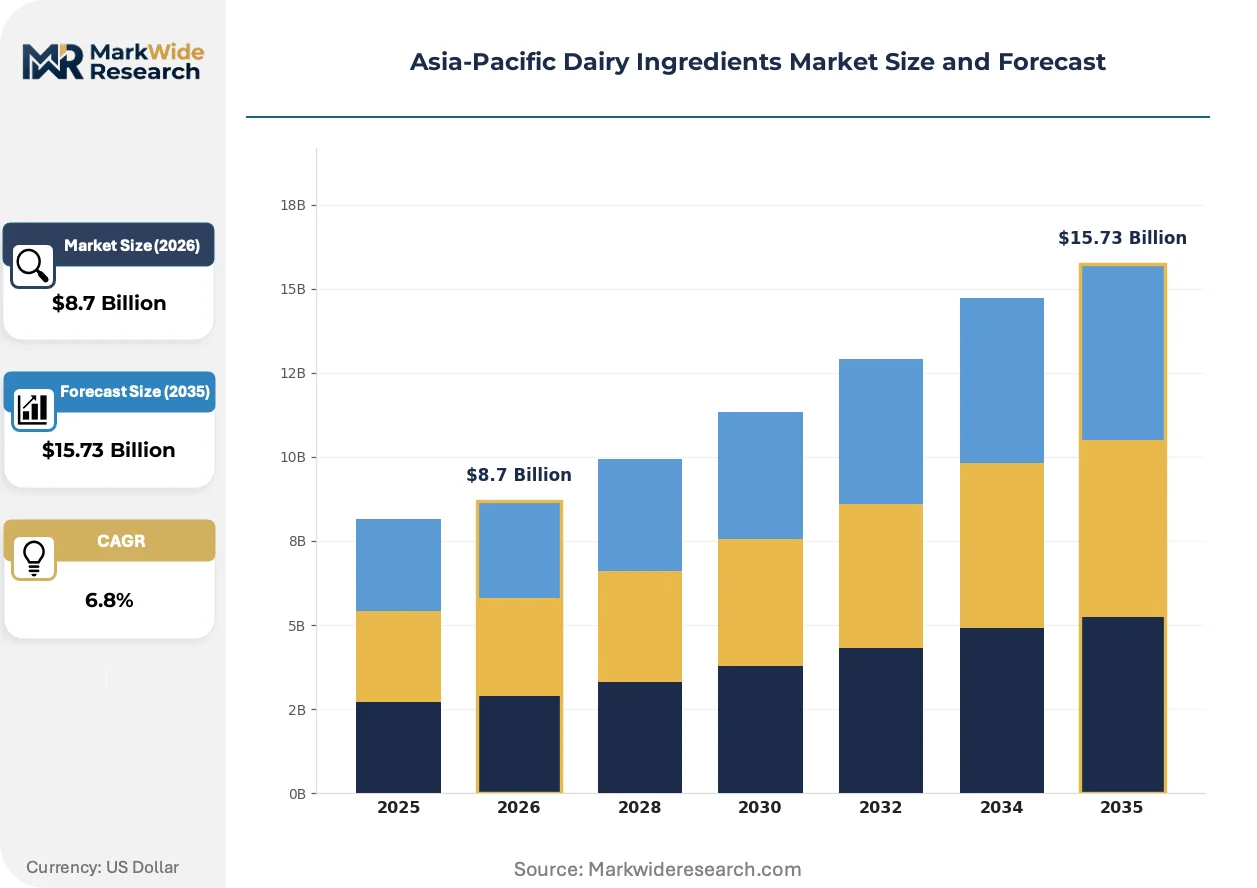
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk Powder, Whey Protein, Casein, Cream End User: Dairy Industry, Bakery, Confectionery, Infant Nutrition Application: Food & Beverage, Functional Foods, Sports Nutrition, Dietary Supplements Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | Euroserum SAS, Fonterra Co-operative Group, Lactalis Ingredients, Gujarat Cooperative Milk Marketing Federation, Saputo Inc, Hoogwegt Groep B V, Arla Foods Ingredients Group, Meiji Holdings Co., Ltd., Glanbia plc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Dairy Ingredients Market Strategic Shifts
Membrane filtration advances and precision fermentation are reshaping ingredient purity thresholds and functional property customization across Asia-Pacific dairy processing.
Membrane filtration technology is decomposing traditional cheese-making byproduct recovery into targeted whey protein isolate and micellar casein concentrate streams. Infant nutrition manufacturers in Shanghai and Guangzhou processing clusters are adopting ceramic membrane systems at accelerated replacement cycles. This capability compression is decomposing commodity whey powder positions into specialized fraction premiums.
India's FSSAI fortification mandates for iron, vitamin A, and vitamin D in milk powders are tightening compositional standards for government program suppliers. Domestic cooperatives and multinational ingredient blenders must reformulate to micronutrient premix specifications. Powder processors serving India's Integrated Child Development Services and Mid-Day Meal schemes face the steepest compliance recalibration.
Direct-procurement relationships between Southeast Asian sports nutrition brands and New Zealand fractionators are shortening traditional trader-mediated supply chains. E-commerce platforms and dedicated ingredient sourcing divisions at brands like Thailand's sports supplement distributors are replacing regional distributor networks. This channel compression is most visible in Bangkok and Jakarta metropolitan fulfillment zones.
Asia-Pacific Dairy Ingredients Market Segmentation
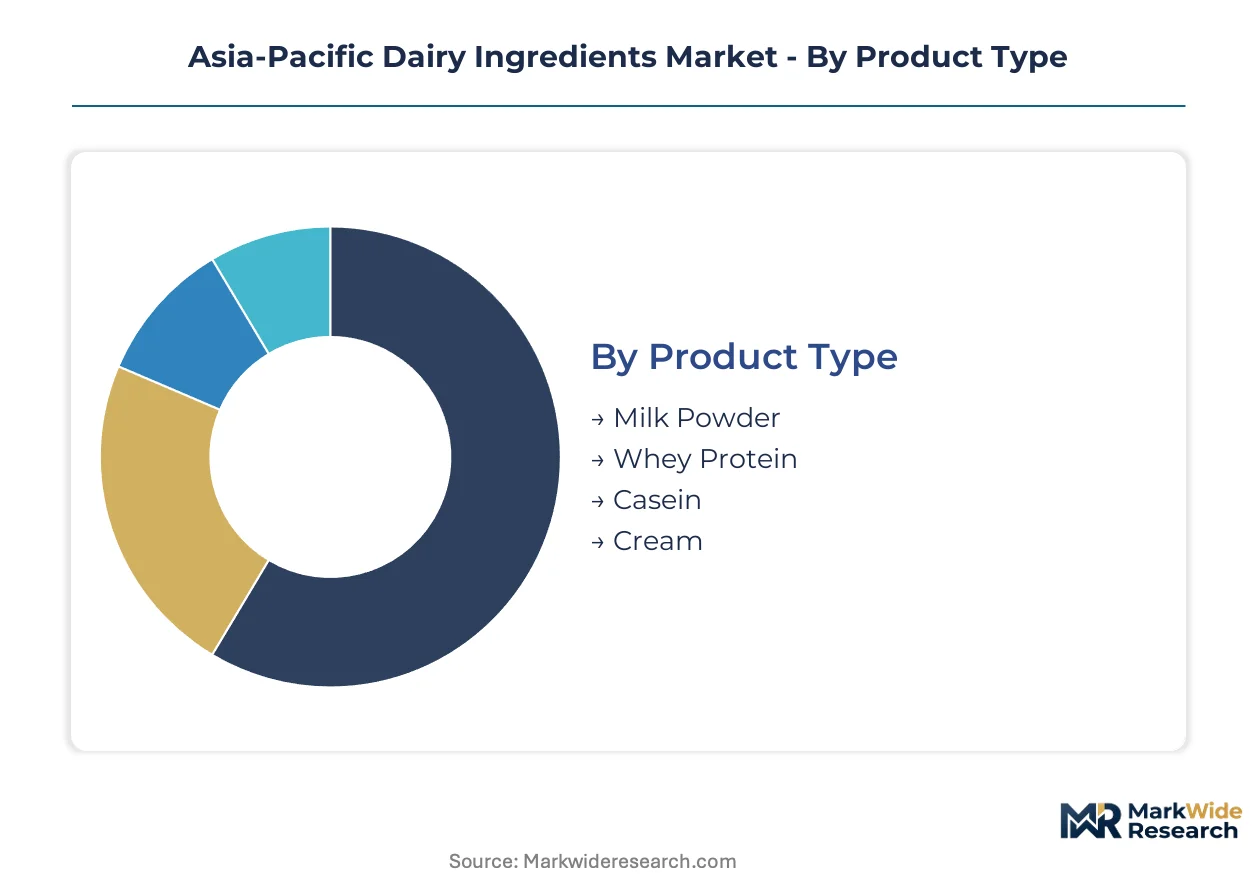
Ingredient specification tiers and channel fragmentation across the Asia-Pacific Dairy Ingredients Market create divergent margin structures. Procurement patterns in infant nutrition versus commodity food applications demand distinct segmentation lenses.
Product Type:
Milk powder anchors domestic consumption across South Asian tea markets, while whey protein isolates drive export-led premium capture.
- Milk Powder:Protein-standardized powders at 26-34% protein content serve reconstitution demand in India's government nutrition programs and Southeast Asian beverage manufacturing. Procurement concentrates in Gujarat Cooperative Milk Marketing Federation's village cooperative networks for domestic supply, with import dependency for specialized fractions in China's eastern seaboard clusters.
- Whey Protein:Isolates exceeding 90% purity command premium positioning in Chinese infant nutrition and Australian sports nutrition channels. Fonterra's New Zealand-origin supply chains anchor import procurement for Shanghai and Guangzhou processing clusters facing SAMR's tightened GB standards enforcement.
- Casein:Micellar casein concentrates for medical nutrition applications remain underdeveloped across Southeast Asian hospital channels.
- Cream:Specialized fat blends concentrate value capture in infant nutrition end-use with premium margin pools.
Milk powder holds the largest share; momentum sits with whey protein.
End User:
Cost tiers separate commodity food manufacturers from clinical nutrition formulators with specialized fraction requirements.
- Dairy Industry:Standardized milk powders and anhydrous milk fat supply recombined dairy product manufacturing across India's organized sector and China's domestic processors.
- Bakery:Emulsification-functional ingredients from whey protein concentrates serve industrial-scale production in Australia's commercial baking sector and Southeast Asian export-oriented facilities.
- Confectionery:Milk fat fractions and lactose specifications vary by end-market chocolate and confection manufacturing requirements.
- Infant Nutrition:Specialized whey fractions and cream blends command the steepest premium tier, with ISO 22000 certification creating 12-18 month supplier qualification delays for new entrants into Chinese channels.
Infant nutrition commands the highest margins; volume expansion is climbing the fastest in bakery applications.
Application:
Functional property requirements differentiate commodity food systems from bioactive-positioned health products.
- Food & Beverage:Reconstitution and emulsification applications dominate volume, with milk powder serving tea and coffee markets across India, Pakistan, and Bangladesh.
- Functional Foods:Japan's Ministry of Health, Labour and Welfare positive-list constraints limit formulation flexibility for imported dairy-derived bioactive ingredients in this channel.
- Sports Nutrition:Direct-procurement relationships between Southeast Asian brands and New Zealand fractionators are shortening traditional trader-mediated supply chains in Bangkok and Jakarta metropolitan zones.
- Dietary Supplements:Whey protein isolates and micellar casein concentrates serve Australia's fitness-oriented consumer base and China's tier-one city demand.
Food and beverage retains volume dominance; sports nutrition is gaining share fastest on channel compression.
Distribution Channel:
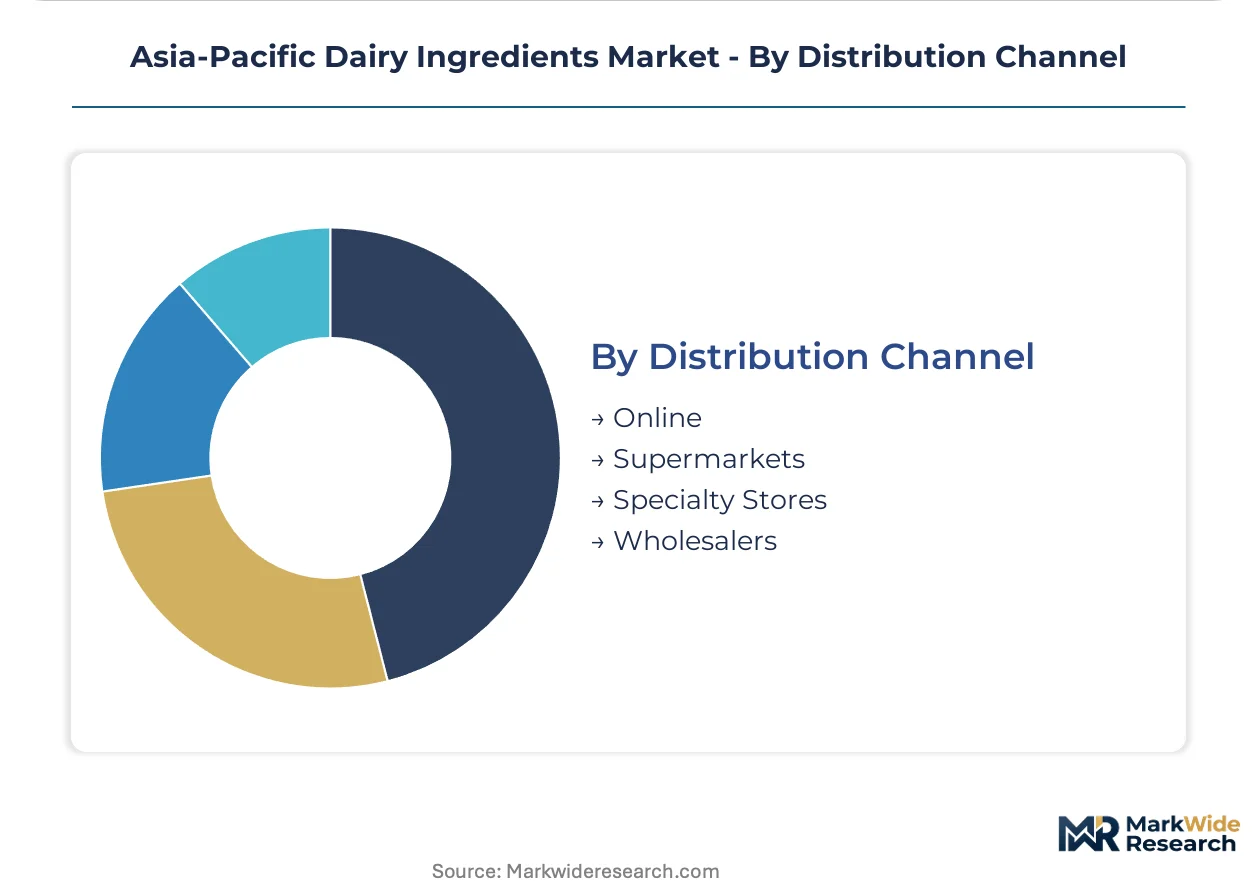
Customer type fragmentation separates bulk industrial procurement from fragmented retail and institutional pathways.
- Online:E-commerce platforms enable direct ingredient sourcing for Southeast Asian sports nutrition brands, bypassing regional distributor networks.
- Supermarkets:Packaged consumer-facing dairy ingredients serve Australia's retail-oriented market structure.
- Specialty Stores:Fitness and clinical nutrition channels in China's tier-one cities and Australian metropolitan areas stock premium whey isolates and casein products.
- Wholesalers:Traditional trader-mediated networks persist for commodity milk powders across South Asian bulk procurement systems.
Wholesalers retain the largest share; online channels are expanding most quickly on direct-procurement adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Infant nutrition manufacturers in China's eastern seaboard processing clusters anchor premium procurement, while India's government nutrition programs drive volume demand for standardized milk powders across South Asian reconstitution markets.
China
Shanghai and Guangzhou processing clusters import New Zealand-origin whey protein isolates for infant formula manufacturing. SAMR's tightened GB standards enforcement forces domestic reformulation toward specialized fractions exceeding 90% protein purity. Eastern seaboard facilities face 12-18 month ISO 22000 certification timelines that filter new supplier entry.
India
Gujarat Cooperative Milk Marketing Federation's village cooperative networks supply protein-standardized milk powders for government nutrition programs. FSSAI mandates iron, vitamin A, and vitamin D fortification in powders distributed through Integrated Child Development Services and Mid-Day Meal schemes. Domestic procurement concentrates in Anand and surrounding districts with backward integration into rural collection infrastructure.
Australia
TGA and FSANZ jointly regulate novel dairy bioactive claims, creating dual compliance pathways for functional food exporters targeting clinical nutrition channels. Sports nutrition demand from fitness-oriented consumers in Sydney and Melbourne metropolitan areas drives whey protein isolate consumption. Pasture conditions in Victoria and New South Wales influence anhydrous milk fat production costs.
Japan
Ministry of Health, Labour and Welfare maintains positive-list systems for dairy-derived food additives, constraining formulation flexibility for imported ingredients in functional food applications. Tokyo and Osaka metropolitan areas concentrate demand for premium whey fractions in clinical and sports nutrition. Domestic processors face limited regional whey fractionation capacity.
Vietnam
Ho Chi Minh City and Hanoi processing facilities import specialized milk fat blends for recombined dairy product manufacturing serving Southeast Asian export markets. Local beverage manufacturers drive milk powder demand for reconstitution applications. Regional distributors are shortening supply chains through direct relationships with New Zealand fractionators.
Asia-Pacific Dairy Ingredients Market Competitive Environment
Player mix skews toward cooperative structures and multinational dairy processors with integrated fractionation capabilities. Market structure concentrates procurement power among infant nutrition specialists and government program suppliers. Three archetypes dominate: New Zealand-origin exporters with premium whey positions, European fractionators with specialized separation technology, and Indian cooperatives with village-level backward integration. Competitive moves center on membrane filtration capacity expansion and direct-procurement relationship formation with Southeast Asian brands.
Within the premium-tier vector, Fonterra Co-operative Group represents New Zealand-origin supply chain anchoring, while Arla Foods Ingredients Group exemplifies European-standard fractionation capabilities. Gujarat Cooperative Milk Marketing Federation occupies a position as the dominant cooperative archetype in Indian domestic procurement. These three entities illustrate the geographic and structural segmentation that defines competitive positioning across infant nutrition, sports nutrition, and government program channels.
| Leading Market Players |
|---|
| Euroserum SAS |
| Fonterra Co-operative Group |
| Lactalis Ingredients |
| Gujarat Cooperative Milk Marketing Federation |
| Saputo Inc |
| Hoogwegt Groep B V |
| Arla Foods Ingredients Group |
| Meiji Holdings Co., Ltd. |
| Glanbia plc |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts with New Zealand-origin suppliers lock in both whey protein isolate access and forward price visibility for Chinese infant nutrition manufacturers facing SAMR's tightened GB standards enforcement. These arrangements transfer pasture-condition risk from processors to traders while securing 12-18 month qualification pipelines for ISO 22000 certification.
Pricing Analysis
Cost-plus contracts indexed to Global Dairy Trade auction settlements dominate whey protein isolate procurement for Chinese infant formula manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 22000-certified suppliers from commodity-grade traders and spot-market alternatives. Pricing pressure stems from FSSAI fortification mandates forcing micronutrient premix absorption by Indian domestic processors. Government nutrition program suppliers exhibit highest price sensitivity; infant nutrition channels show lowest elasticity due to qualification barriers.
Supply Chain Analysis
Strategic stockpiling of specialized whey fractions prevails among Shanghai and Guangzhou processing clusters confronting 12-18 month supplier qualification timelines. Supply concentrates in New Zealand, Australia, and European fractionation facilities with membrane filtration capabilities. Raw material dependencies include pasture-fed milk supply, ceramic membrane systems, and micronutrient premix formulations. Single-source vulnerability runs through New Zealand-origin whey protein channels exposed to climatic disruption. Distribution runs through direct-procurement relationships between Southeast Asian sports nutrition brands and fractionators, bypassing traditional trader networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane filtration technology is disrupting traditional whey fractionation economics, compressing commodity positions into specialized premium capture while regulatory divergence between China's GB standards and Codex Alimentarius benchmarks forces reformulation investment cycles.
For Market Incumbents: Secure ceramic membrane capacity expansion in China's eastern seaboard clusters ahead of competitor qualification timelines. Deepen backward integration into India's village-level dairy cooperatives to offset import dependency exposure. Fonterra and Arla must defend premium positioning against emerging European fractionators by accelerating ISO 22000 certification pipelines for secondary suppliers. For New Entrants and Emerging Players: ISO 22000 certification fast-track services offer service-layer entry into Chinese infant nutrition channels without capital-intensive fractionation investment. Clinical nutrition applications for micellar casein concentrates remain underdeveloped across Southeast Asian hospital channels. Direct-procurement platform development for Bangkok and Jakarta sports nutrition brands bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Capital is best deployed toward membrane filtration specialists with existing European or New Zealand processing footprints capable of serving dual carbon-aligned Chinese export demand. Long-term viability hinges on regulatory arbitrage capabilities between diverging national standards and Codex benchmarks. Watch for SAMR acceleration of GB standard harmonization as inflection indicator for reformulation cost recalibration.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Capacity Expansion | Ceramic system deployment in Shanghai clusters captures premium whey isolate positioning ahead of competitor qualification. |
| Village Cooperative Backward Integration | Gujarat Cooperative Milk Marketing Federation's rural collection infrastructure secures domestic Indian supply without import exposure. |
| ISO 22000 Certification Fast-Track | Accelerated audit pipelines filter new supplier entry into Chinese infant nutrition channels facing SAMR enforcement. |
| Direct-Procurement Platform Development | E-commerce sourcing relationships with New Zealand fractionators disintermediate traditional Bangkok and Jakarta distributor networks. |
| Micronutrient Premix Reformulation | FSSAI-compliant iron, vitamin A, and vitamin D fortification recalibration serves India's government nutrition program procurement. |
Study Parameters
A spread of perspectives from infant nutrition procurement managers, dairy cooperative operations directors, membrane filtration technology suppliers, and FSSAI regulatory affairs specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through customs trade data, Fonterra and Gujarat Cooperative Milk Marketing Federation annual disclosures, and SAMR regulatory filings. Bottom-up volume modeling from processing cluster capacities triangulated against top-down expenditure analysis across government nutrition programs and sports nutrition brand procurement.
Segmentation dimensions modeled include ingredient specification tier, end-use application, distribution channel structure, and regional regulatory cluster across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating FSSAI fortification mandate implementation timelines and SAMR GB standard enforcement trajectories. Forecast inputs incorporated pasture-condition variability indices and membrane filtration replacement cycle acceleration patterns observed in Shanghai and Guangzhou facilities.
Decision-makers should treat outputs as directional under assumptions of continued SAMR regulatory tightening and stable New Zealand-origin supply chain integrity; material deviation in either dimension would warrant model refresh. Practitioners should keep alternative scenarios live as Codex Alimentarius harmonization negotiations and China's dual carbon alignment frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Amaranth Oil Market
Ingredients
Volatile Fatty Acids Market
Ingredients
South America Spirulina Extract Market
Ingredients
Mastic Gum Market
Ingredients
Global Egg White Peptide Market
Ingredients
Soy Protein Ingredients Market
Ingredients
Hydrolyzed Vegetable Protein Market
Ingredients
MCT Oil Market
Ingredients
South America Fermented Ingredients Market
Ingredients
Vitamin C Ingredients Market
Ingredients
Sea Salt Market
Ingredients
Spain Fermentation Ingredients Market
Ingredients
Plant Based Thickener Market
Ingredients
Africa Soy Protein Ingredients Market
Ingredients
South America Protein Market
Ingredients
Fish Gelatin Market