
 Philippines Edible Oils & Fats Market | 2026-2036
Philippines Edible Oils & Fats Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Edible Oils & Fats Market Insights
The capital-intensity divergence between integrated refiners and toll-based processors is redrawing competitive boundaries in the Philippines edible oils sector. Universal Robina Corporation leverages its captive oleochemical and packaging infrastructure to sustain margin control across branded cooking oil and snack food supply chains. NutriAsia Inc. dominates the condiment-adjacent oil segment, while D&L Industries anchors industrial fat supply through its backward integration into specialty oil formulations.
Edible oils and fats comprise triglyceride-based lipid products refined to specific free fatty acid thresholds, iodine values, and smoke points for human consumption, serving as heat-transfer media, flavor carriers, and nutritional substrates in food systems. Coconut oil retains structural leadership in Philippine retail due to indigenous supply and cultural preference, though palm oil volumes in food processing applications are expanding fastest through cost-driven reformulation by pan-Asian fast-moving consumer goods manufacturers. Margarine production and snack food manufacturing represent concentrated margin pools where blended fat specifications command technical premiums over commodity cooking grades.
The Philippine Food and Drug Administration enforces Codex-aligned fat quality standards, while the Department of Agriculture's Bureau of Agricultural Research oversees coconut and oil palm varietal improvement programs that directly influence feedstock availability. The Department of Trade and Industry's mandatory product certification under Philippine National Standards shapes market access for imported and domestically refined oils alike. Stakeholders must monitor evolving biofuel feedstock competition for coconut oil and the Bureau of Customs' tariff administration on ASEAN-origin palm oil shipments.
Market Dynamics
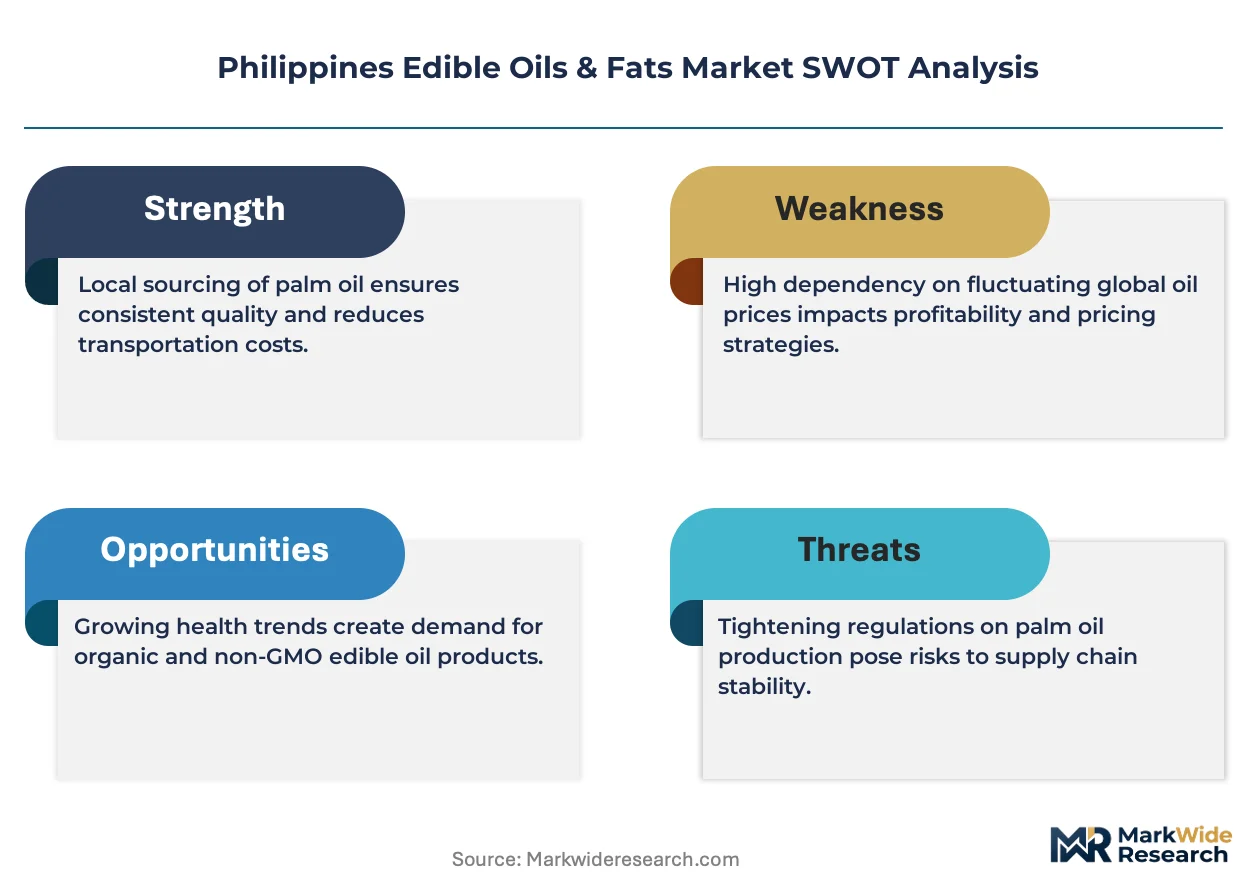
The Philippine Food and Drug Administration's trans fat labeling mandate is forcing systematic reformulation across the entire edible oils value chain, compressing margins for commodity processors while rewarding technical specialists capable of delivering tailored fat specifications.
Growth Catalysts
- Processed Food Manufacturing Expansion:Metro Manila and Cebu-based food manufacturers are scaling procurement of refined palm and coconut oils for snack and convenience food production.
- Department of Agriculture Varietal Programs:Bureau of Agricultural Research initiatives on high-yielding coconut and oil palm varieties are expanding domestic feedstock availability for downstream refiners.
- Foodservice Channel Density:The National Capital Region's concentrated restaurant and institutional catering corridor generates sustained bulk demand for cooking-grade oils.
Market Restraints
- Coconut Oil Price Volatility:Weather-driven yield fluctuations and competing biofuel feedstock demand create input cost instability for domestic refiners.
- ASEAN Palm Oil Import Concentration:Heavy reliance on Malaysian and Indonesian crude palm oil shipments exposes processors to Bureau of Customs tariff administration shifts.
- Technical Substitution Limits:Coconut oil's distinct fatty acid profile prevents full replacement in certain confectionery and infant formula applications where lauric acid specifications are non-negotiable.
Strategic Opportunities
- Visayas and Mindanao Industrial Corridors:Underpenetrated regions outside Luzon present greenfield opportunities for regional blending and distribution facilities.
- Specialty Fat Formulations:Margarine and shortening applications for bakery and foodservice command technical premiums over commodity cooking grades.
- Philippine National Standards Certification:Department of Trade and Industry mandatory product certification creates competitive moat for early-compliant domestic refiners against informal imports.
Industry Challenges
- Lipid Chemistry Technical Talent:Shortage of formulation chemists capable of designing trans fat-free blends while maintaining functional performance in industrial baking and frying.
- Refinery Retooling Capex:Hydrogenation equipment modification and interesterification system installation demand capital commitments that strain toll-based processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Edible Oils & Fats Market |
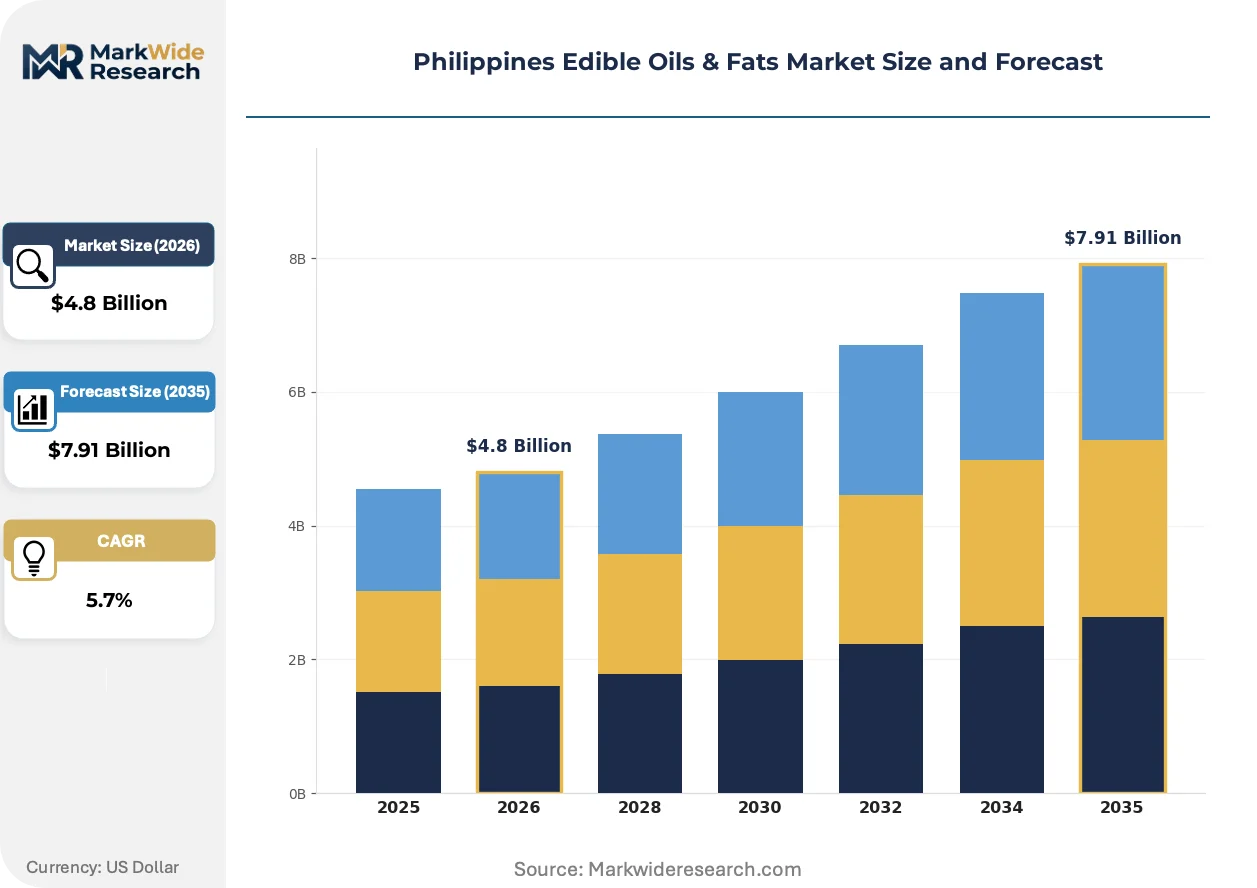
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Palm Oil, Coconut Oil, Soybean Oil, Olive Oil Application: Food Processing, Cooking Oil, Margarine Production, Snack Food Manufacturing Distribution Channel: Supermarkets, Online Retail, Foodservice, Wholesale Customer Type: Households, Restaurants, Food Manufacturers, Catering Services |
| Companies Covered | Universal Robina Corporation, CIIF Oils Mills Group, San Miguel Pure Foods, Minola Cooking Oil, Fly Ace Corporation, NutriAsia Inc., Oleo-Fats Incorporated, AgriPacific Corporation, D&L Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Edible Oils & Fats Market Trends and Innovations
Interesterification and enzymatic modification technologies are rewriting formulation possibilities for Philippine fat processors, enabling precise control over melting profiles and crystallization behavior without reliance on partial hydrogenation.
Enzymatic interesterification is decomposing the traditional technical advantage of chemical processing by enabling precise sn-2 positional specificity in triglyceride restructuring. Snack food manufacturers in Laguna and Cavite are piloting enzymatically modified palm fractions for improved shelf stability. This technology is decomposing the cost-performance trade-off that previously locked mid-tier processors out of premium fat specification markets.
The Philippine Food and Drug Administration's updated labeling standards for trans fat content are eliminating formulation flexibility for legacy hydrogenation-dependent producers. Industrial bakers and margarine compounders face compressed reformulation timelines to maintain product registration compliance. Packaged food manufacturers in the National Capital Region are accelerating supplier audits to verify non-hydrogenated oil sourcing.
Direct procurement relationships between food manufacturers and integrated refiners are displacing traditional distributor intermediaries in bulk oil supply. Large-scale processors in Bulacan and Pampanga are negotiating long-term offtake agreements with Universal Robina Corporation and D&L Industries for captive supply security. This pattern concentrates most visibly in the Luzon industrial belt where volume scale justifies dedicated logistics arrangements.
Philippines Edible Oils & Fats Market Segmentation
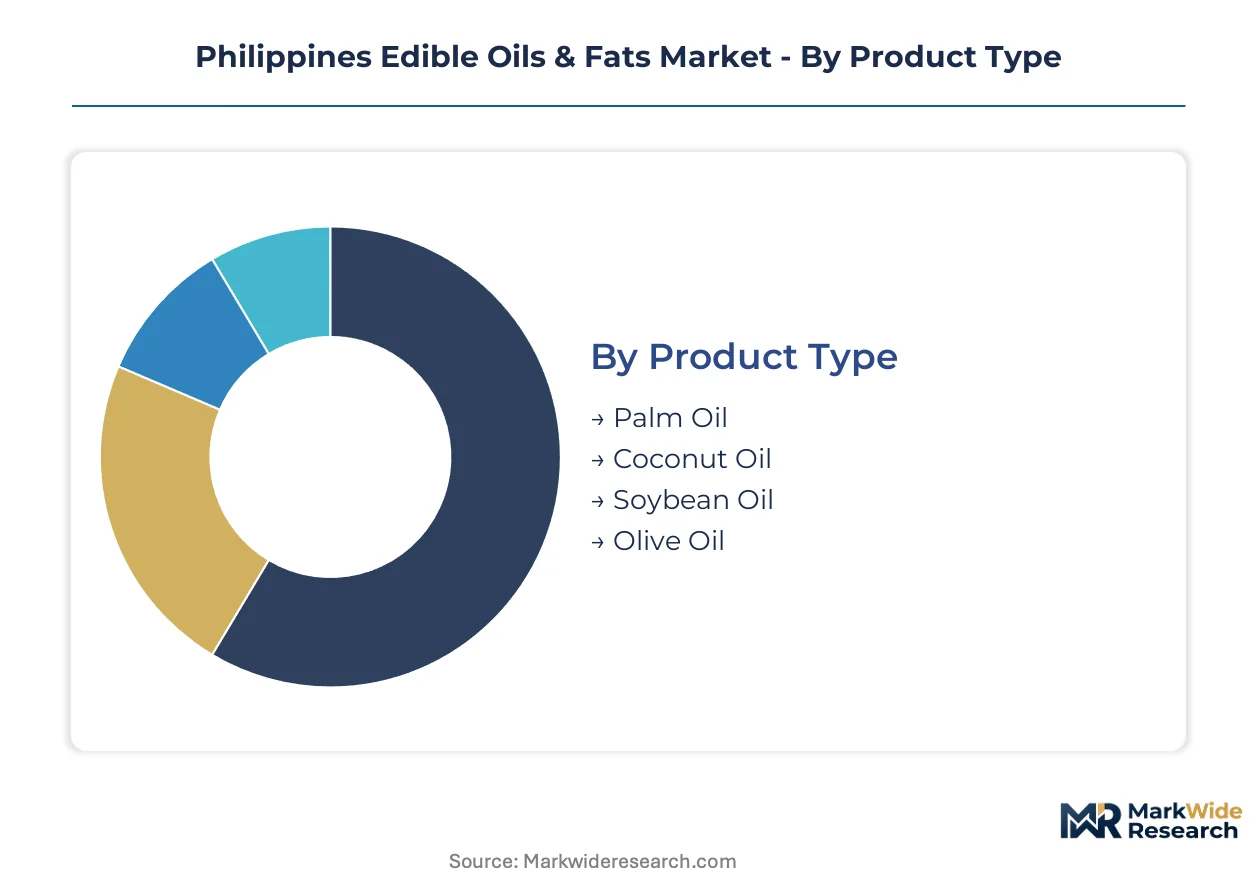
Segmentation in the Philippine edible oils sector reveals how procurement patterns diverge between commodity cooking grades and technical fat formulations. Understanding these divisions exposes where margin compression threatens toll-based processors and where specialty capabilities command pricing power.
Product Type:
Margin pools concentrate in oils offering functional specificity for industrial applications rather than generic cooking grades.
- Palm Oil:Refined, bleached, and deodorized palm olein dominates food processing applications through its cost efficiency and neutral flavor profile. Metro Manila snack manufacturers are expanding procurement of palm fractions for frying and shortening formulations as reformulation away from hydrogenated fats accelerates.
- Coconut Oil:Virgin and refined grades retain structural leadership in Philippine retail due to indigenous supply chains and lauric acid specifications valued in confectionery. Weather-driven yield volatility in Quezon and Bicol growing regions creates input cost instability that integrated refiners manage through backward integration into crushing assets.
- Soybean Oil:Imported crude shipments from Argentina and the United States supply refining capacity in Batangas and Cebu for institutional foodservice.
- Olive Oil:Premium import grades target affluent households in Makati and Taguig condominiums through specialty retail channels.
The dominant share belongs to Palm Oil, while Coconut Oil is closing the gap fastest through biodiesel feedstock competition and premium retail positioning.
Application:
Application segmentation tracks how technical specifications separate commodity volume from value-added formulations.
- Food Processing:Industrial bakeries and sauce manufacturers in Bulacan and Pampanga specify tailored fat blends for texture and shelf stability. The Philippine Food and Drug Administration's trans fat labeling mandate is forcing systematic reformulation across this segment, compressing margins for hydrogenation-dependent suppliers.
- Cooking Oil:Refined palm olein and coconut oil grades serve household and foodservice frying through sachet and bulk packaging formats. Luzon's National Capital Region corridor generates concentrated bulk demand from restaurant chains and institutional catering operations.
- Margarine Production:Compounders require precise solid fat content control for spreadability and baking performance.
- Snack Food Manufacturing:Laguna and Cavite processors pilot enzymatically modified palm fractions for improved oxidative stability in packaged goods.
Food Processing commands the largest volume position, with Snack Food Manufacturing expanding most quickly through foreign direct investment in Philippine convenience food production.
Distribution Channel:
Channel structure determines pricing transparency and customer captivity for oil suppliers.
- Supermarkets:Modern trade outlets in Metro Manila and Cebu stock branded cooking oils with Philippine National Standards certification marks. Shelf space negotiations favor suppliers with Department of Trade and Industry compliance documentation and national logistics coverage.
- Foodservice:Direct procurement relationships between large restaurant chains and integrated refiners are displacing traditional distributor intermediaries. Volume scale in the Luzon industrial belt justifies dedicated tanker logistics and long-term offtake agreements.
- Wholesale:Open market trading in Divisoria and regional agro-industrial supply hubs serves small-scale food manufacturers.
- Online Retail:E-commerce platforms aggregate specialty and imported oil demand from dispersed household segments.
Supermarkets retain the dominant channel position, while Foodservice is gaining share fastest through direct refiner-manufacturer relationships.
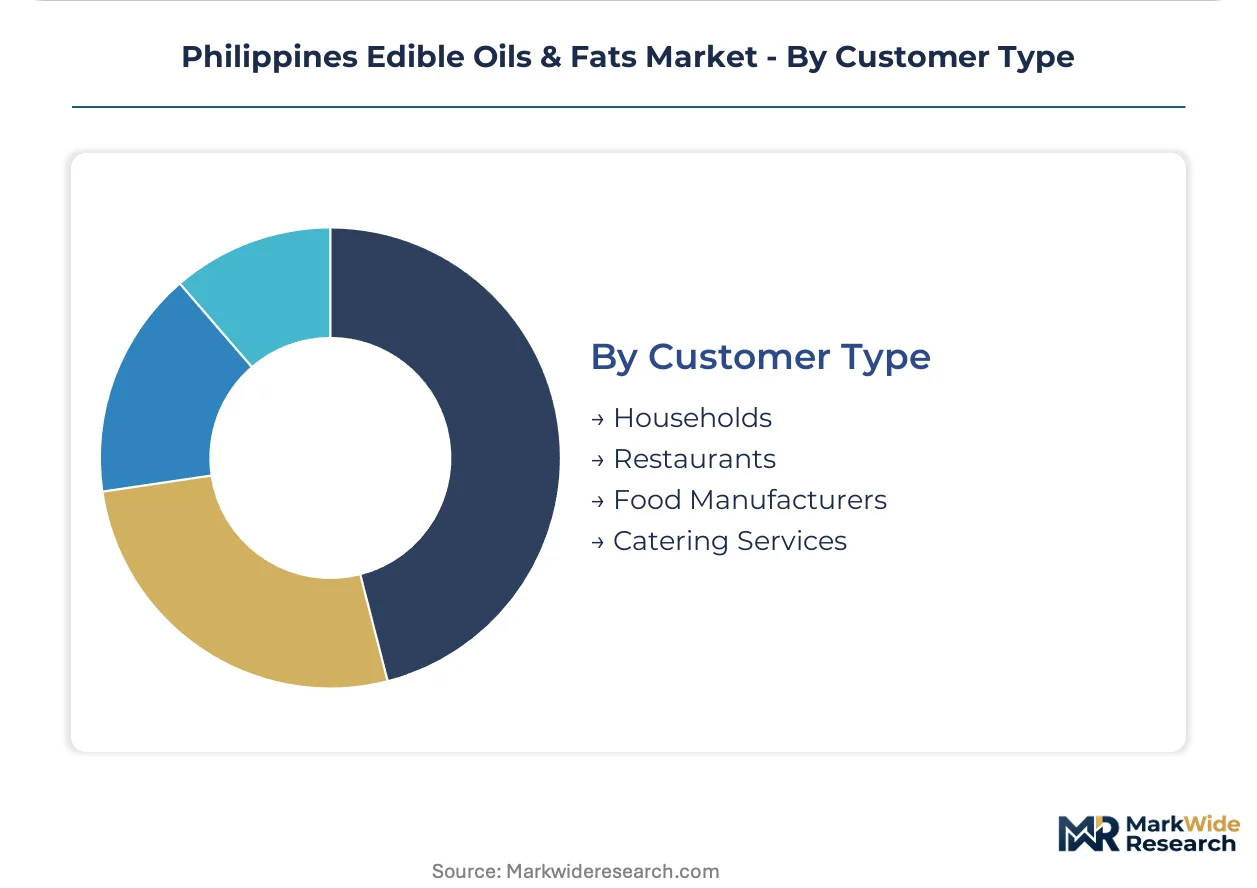
Customer Type:
Customer segmentation separates price-sensitive household consumption from specification-driven industrial procurement.
- Food Manufacturers:Large-scale processors negotiate formula-specific fat blends with technical service support from refiners like D&L Industries and Universal Robina Corporation. These relationships concentrate in Luzon where volume density supports captive supply arrangements and just-in-time delivery infrastructure.
- Households:Sachet and bottle formats dominate purchasing in provincial markets where coconut oil retains cultural preference over palm alternatives.
- Restaurants:Independent and chain foodservice operators source cooking grades through wholesale distributors or direct refiner contracts based on volume thresholds.
- Catering Services:Institutional feeding operations in schools, hospitals, and corporate facilities procure bulk oils through competitive bidding processes.
Food Manufacturers represent the largest revenue concentration, with Restaurants climbing fastest through quick-service chain expansion in secondary cities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Luzon commands pricing power through the National Capital Region's concentrated foodservice corridor, while Visayas and Mindanao processors absorb freight premiums on imported palm oil shipments from ASEAN origins.
Luzon
The National Capital Region's dense restaurant and institutional catering network generates sustained bulk demand for cooking-grade oils. The Philippine Food and Drug Administration's trans fat labeling mandate forces systematic reformulation across Bulacan and Pampanga industrial bakeries. Laguna and Cavite snack manufacturers pilot enzymatically modified palm fractions for improved shelf stability in packaged goods.
Visayas
Cebu-based food manufacturers are scaling procurement of refined palm and coconut oils for processed food production. The Department of Agriculture's Bureau of Agricultural Research varietal programs on high-yielding coconut varieties expand domestic feedstock availability for downstream refiners. Regional blending facilities remain underpenetrated relative to Luzon, creating greenfield opportunities for distribution infrastructure.
Mindanao
Oil palm plantation development in Bukidnon and North Cotabato supplies crude feedstock to regional crushing assets. The Department of Trade and Industry's Philippine National Standards certification shapes market access for domestically refined oils against informal imports. Davao City's emerging food processing corridor attracts direct procurement relationships with integrated refiners seeking captive supply security.
Bicol
Quezon Province's coconut-growing regions experience weather-driven yield volatility that creates input cost instability for domestic refiners. The Bureau of Customs' tariff administration on ASEAN-origin palm oil shipments exposes processors to administrative shifts. Integrated refiners manage supply risk through backward integration into crushing assets and long-term grower contracts.
Philippines Edible Oils & Fats Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Philippine edible oils sector. The market structure concentrates around integrated conglomerates with captive oleochemical infrastructure and toll-based processors serving commodity cooking grades. Strategic archetypes include backward-integrated refiners controlling feedstock through plantation assets, formulation specialists commanding technical premiums in margarine and shortening applications, and branded consumer goods players leveraging distribution density in modern trade. Dominant competitive moves span refinery retooling for interesterification capabilities and direct procurement relationships displacing distributor intermediaries.
Within the integrated conglomerate tier, Universal Robina Corporation and San Miguel Pure Foods exemplify players with captive supply chains spanning branded cooking oils through snack food production. D&L Industries anchors the industrial specialist archetype through its position in specialty oil formulations for food manufacturers. NutriAsia Inc. occupies a distinct position in condiment-adjacent oil segments where technical specifications intersect with brand equity in Philippine retail.
| Leading Market Players |
|---|
| Universal Robina Corporation |
| CIIF Oils Mills Group |
| San Miguel Pure Foods |
| Minola Cooking Oil |
| Fly Ace Corporation |
| NutriAsia Inc. |
| Oleo-Fats Incorporated |
| AgriPacific Corporation |
| D&L Industries |
| Others |
Pricing and Supply Chain Analysis
Forty-five to sixty-day inventory cycles for refined palm olein shipments from Malaysian and Indonesian ports directly determine margin capture for Philippine toll-based processors, concentrating pricing power among integrated refiners with backward integration into crushing assets and long-term grower contracts.
Pricing Analysis
The customization-premium spread between standard RBD palm olein and enzymatically modified specialty fat formulations exceeds commodity cooking grades by technical service bundling and Philippine National Standards certification tiers. Price differentiation rests on formulation chemist availability and trans fat-free compliance documentation. Pricing pressure intensifies in commodity cooking segments as direct refiner-manufacturer procurement relationships displace distributor markups. Small-scale food manufacturers in wholesale channels exhibit highest price sensitivity, while industrial bakers in Bulacan and Pampanga prioritize functional performance over unit cost.
Supply Chain Analysis
The Bureau of Customs' tariff administration chokepoint on ASEAN-origin crude palm oil shipments exposes processors to administrative delay and duty uncertainty. Feedstock supply concentrates in Malaysia, Indonesia, and domestic Quezon-Bicol coconut growing regions. Raw material dependencies span crude palm oil, copra, and imported soybean shipments from Argentina. Single-source vulnerability runs through the Strait of Malacca transit corridor for Indonesian crude. Distribution feeds from integrated refiner tanker fleets directly to Luzon industrial belt food manufacturers, bypassing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemistry expertise capable of designing trans fat-free blends while maintaining solid fat content specifications represents the critical capability gap constraining margin expansion for mid-tier processors.
For Market Incumbents: Compound technical service capabilities around enzymatic interesterification to defend against specialty fat formulation specialists encroaching on margarine and shortening applications. Secure captive coconut supply through long-term grower contracts in Quezon and Bicol to buffer weather-driven yield volatility. Expand Philippine National Standards certification coverage to create compliance moats against informal import competition. For New Entrants and Emerging Players: Technical service gaps in Visayas and Mindanao regional blending infrastructure present white-space targets where integrated refiners under-invest in localized formulation support. Davao City's emerging food processing corridor offers the most penetrable geography for direct procurement relationship building. Lead with just-in-time delivery capabilities and on-site lipid chemistry consultation to differentiate from commodity distributors. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across enzymatic modification equipment installations as hydrogenation retooling demands strain toll-based processor balance sheets. Long-term viability favors acquisition targets with existing interesterification capabilities and Department of Trade and Industry certification relationships. Monitor Bureau of Customs administrative shifts on ASEAN palm oil tariffs as the key inflection signal for integrated refiner margin expansion versus compression.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Interesterification Investment | Enables precise sn-2 positional specificity for premium margarine formulations without hydrogenation. |
| Backward Integration into Coconut Crushing | Universal Robina Corporation-style captive supply chains buffer Quezon-Bicol weather volatility. |
| Philippine National Standards Certification | Department of Trade and Industry compliance creates competitive moats against informal palm oil imports. |
| Direct Procurement Relationship Development | Bulacan and Pampanga industrial bakeries are displacing distributor intermediaries for volume security. |
| Visayas-Mindanao Distribution Infrastructure | Greenfield regional blending facilities capture underpenetrated Cebu and Davao food manufacturing demand. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Bureau of Customs import records, Philippine Food and Drug Administration product registration databases, and Department of Agriculture crop yield statistics. Primary interviews engaged refinery operations managers, food manufacturer procurement leads, lipid formulation chemists, and coconut plantation agronomists. Secondary validation drew from Philippine National Standards certification registries, ASEAN trade flow data, and integrated refiner SEC disclosures. Bottom-up volume modeling triangulates against top-down sectoral GDP contribution estimates.
Segmentation dimensions modeled span product type, application, distribution channel, and customer archetype across the projection horizon. Analytical framework incorporates coconut oil price volatility indices, palm oil import tariff schedules, and enzymatic modification technology adoption curves. CAGRs derive from time-series regression of historical volume data against macroeconomic consumption drivers and regulatory compliance timelines. Forecast inputs include Bureau of Agricultural Research varietal program yield projections and National Capital Region foodservice channel density metrics.
Underlying assumptions cover Philippine Food and Drug Administration enforcement consistency on trans fat labeling, Bureau of Customs tariff administration stability, and Department of Agriculture varietal program execution, with deviation risk concentrated in weather-driven coconut yield shocks and ASEAN-origin crude palm oil supply disruptions. Practitioners should keep alternative scenarios live as biofuel feedstock competition for coconut oil and Malaysian-Indonesian export policy shifts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Potato & Yam Derivatives Market
Ingredients
Indonesia Edible Oil Market
Ingredients
North America Vegetable Oils Market
Ingredients
Encapsulated Ingredients Market
Ingredients
Honey Powder Market
Ingredients
Fish Feed Ingredients Market
Ingredients
Dry Molasses Products Market
Ingredients
Durian Powder Market
Ingredients
Casein Market
Ingredients
Brazil Starch Derivatives Market
Ingredients
Custom Dry Ingredients Blends Market
Ingredients
Cheese Cultures Market
Ingredients
Dry Malt Products Market
Ingredients
Europe Fermented Ingredients Market
Ingredients
Jojoba Oil Market
Ingredients
Feed Premix Market