
 Outdoor Kitchen Appliances Market | 2026-2036
Outdoor Kitchen Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Outdoor Kitchen Appliances Market Analysis
Stainless steel is consolidating its position as the dominant housing material across premium grill and burner assemblies, displacing lower-grade coated metals that degrade under thermal cycling and coastal humidity. Weber-Stephen Products LLC leverages its foundry network to sustain domestic casting capacity for high-BTU burner manifolds. Napoleon anchors its competitive stance through vertical control over infrared sear technology and Canadian manufacturing scale. Kalamazoo Outdoor Gourmet differentiates via marine-grade stainless specifications that target waterfront residential installations.
Outdoor kitchen appliances comprise weather-resistant cooking, refrigeration, and cleanup equipment engineered for permanent exterior installation, typically featuring 304 or 316 stainless steel construction, insulated combustion chambers rated for sustained temperatures above 500°F, and sealed electrical components meeting IPX4 splash-resistance thresholds. The product category serves residential entertainment zones, commercial hospitality patios, and multifamily amenity spaces. Grills command the largest revenue pool within product type segmentation due to replacement frequency and burner complexity, while refrigerators gain share as outdoor beverage service expands beyond warm-climate markets. Built-in installation formats capture premium margin pools by requiring custom cabinetry and gas-line rough-ins, whereas portable configurations compete on seasonal mobility and lower entry price points.
The US EPA Energy Star program and state-level California Energy Commission Title 20 standards govern outdoor refrigerator efficiency thresholds and standby power draw, compelling manufacturers to redesign compressor systems and insulation packages. The National Fire Protection Association NFPA 54 fuel gas code and local municipal permitting authorities regulate propane and natural gas line routing for built-in grill installations, creating compliance barriers for unlicensed contractors and DIY assembly. Stakeholders must monitor evolving electrification mandates in coastal municipalities that could shift burner technology toward induction and infrared platforms while reshaping gas infrastructure dependencies.
Market Dynamics
Electrification mandates in coastal municipalities are forcing burner technology pivots toward induction and infrared platforms while simultaneously reshaping gas infrastructure dependencies across residential installation channels.
Growth Catalysts
- California Energy Commission Title 20 efficiency standards:These regulations compel compressor system redesigns that improve outdoor refrigerator performance ratings and drive replacement demand across Sun Belt states.
- Marine-grade stainless specifications:Waterfront residential installations in Florida and coastal California are specifying 316-grade housings that resist salt-air corrosion and thermal cycling degradation.
- Infrared sear technology adoption:Premium grill buyers are demanding high-BTU infrared burners that deliver restaurant-grade searing capabilities in residential outdoor kitchens.
Market Restraints
- NFPA 54 fuel gas code compliance:Municipal permitting authorities impose licensed contractor requirements that create barriers for DIY assembly and unlicensed installation services.
- Nickel and chromium price volatility:304 and 316 stainless steel input costs fluctuate with commodity markets, compressing margins on mid-tier grill housings and burner manifolds.
- Electrical infrastructure limitations:Legacy residential outdoor spaces lack 240V circuits required for induction cooktops, restricting electrification conversion in suburban developments built before 2010.
Strategic Opportunities
- Multifamily amenity space expansion:Apartment developers in Texas and Arizona are installing shared outdoor kitchen pods as competitive leasing amenities in Class-A properties.
- IPX4-rated smart control integration:Bluetooth-enabled temperature monitoring and automated ignition systems are converging with home automation platforms for seamless outdoor cooking management.
- US EPA Energy Star certification pathways:Manufacturers achieving standby power draw thresholds gain preferential specification in municipal green building incentive programs.
Industry Challenges
- Welding certification for marine-grade assemblies:Fabricators capable of 316 stainless TIG welding command premium wages, creating production bottlenecks for waterfront-targeted product lines.
- Cross-jurisdictional gas line inspection protocols:Installers face fragmented municipal requirements that delay project completion and increase compliance documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outdoor Kitchen Appliances Market |
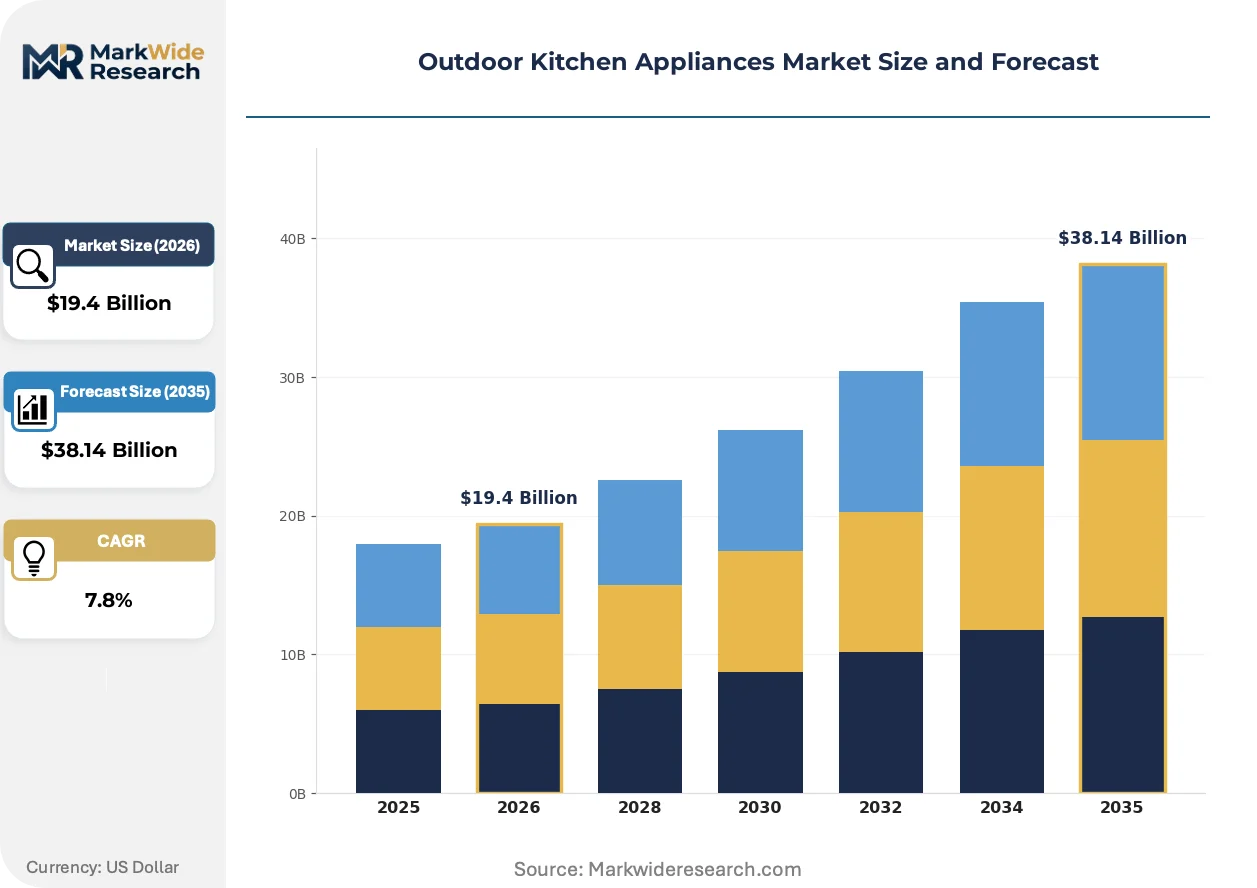
| Market Size in 2026 | $19.4 Billion |
| Market Size in 2035 | $38.14 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grills, Refrigerators, sinks, Burners Material: Stainless Steel, Aluminum, Wood, Stone Application: Residential, Commercial, Entertainment, Hospitality Installation: Built-in, Freestanding, Portable, Customizable |
| Companies Covered | Napoleon, Char-Broil LLC, Weber-Stephen Products LLC, Kalamazoo Outdoor Gourmet, Hestan Outdoor, The Middleby Corporation, Bull Outdoor Products, Inc., GE Appliances, Traeger Pellet Grills LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outdoor Kitchen Appliances Market Emerging Trajectories
Active redesign of combustion and control systems is compressing the performance gap between gas and electric outdoor cooking platforms while simultaneously embedding connectivity features that transform standalone appliances into integrated entertainment infrastructure.
Smart temperature management systems using probe-based feedback loops are automating cooking sequences for proteins and vegetables. High-end residential buyers in California and Florida are specifying these capabilities at accelerating rates. This automation is compressing the skill barrier for complex outdoor meal preparation while reducing operator attention requirements during entertaining.
The US EPA Energy Star program and parallel state-level efficiency codes are tightening standby power thresholds for outdoor refrigeration units. Compressor manufacturers are redesigning cooling systems with variable-speed drives and vacuum-insulated panels. Built-in refrigerator segments in coastal municipalities face the steepest compliance redesign cycles as electrification timelines accelerate.
Direct-to-consumer specification channels are displacing traditional contractor-mediated procurement for premium grill and refrigeration packages. Affluent homeowners in Sun Belt metropolitan areas are researching IP ratings, BTU outputs, and warranty terms independently before engaging installation services. This pattern concentrates in Arizona and Nevada markets where new construction volumes support owner-driven outdoor kitchen planning.
Outdoor Kitchen Appliances Market Segmentation
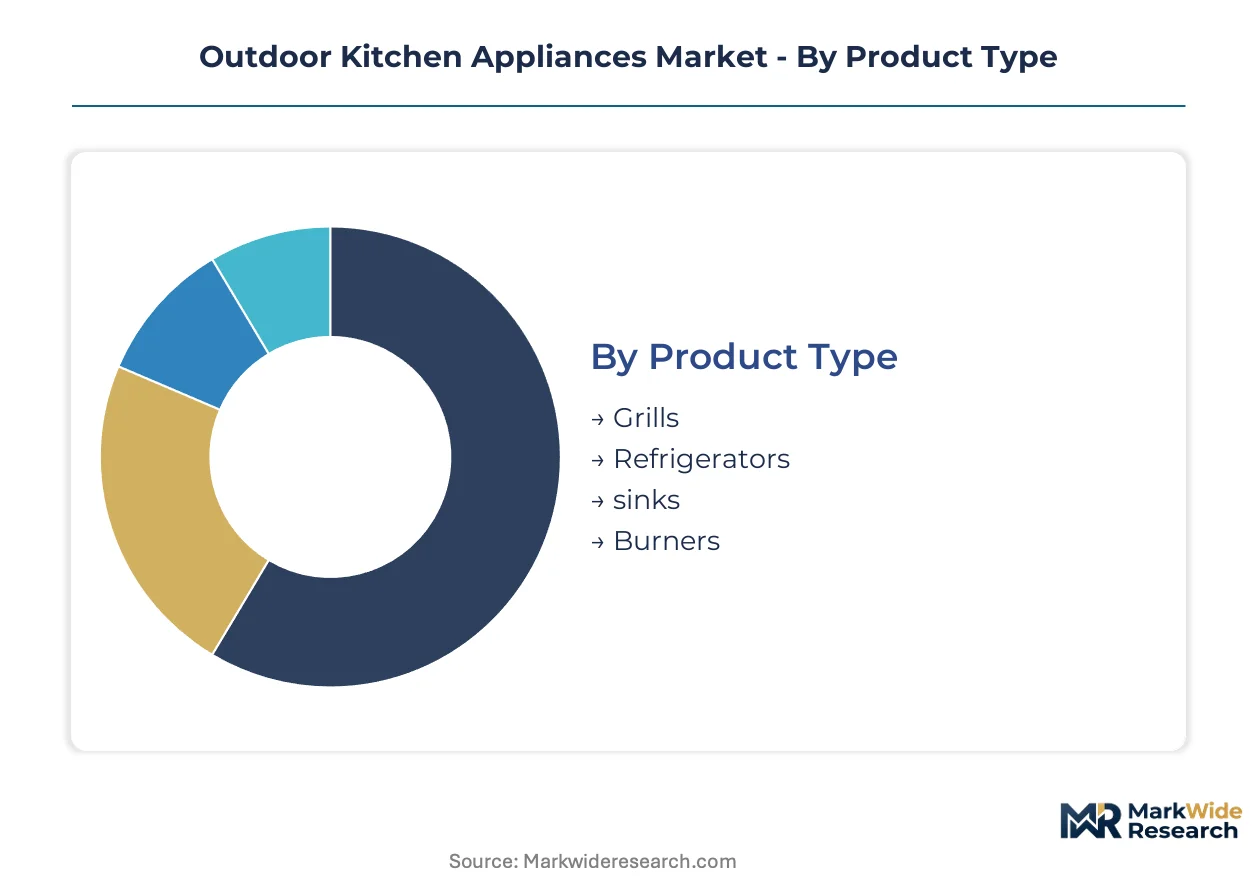
Outdoor kitchen purchasing decisions hinge on climate exposure, fuel infrastructure, and entertainment frequency. Segmentation reveals how material specifications and installation formats align with distinct upgrade cycles across suburban and waterfront properties.
Product Type:
Replacement cycles vary dramatically by combustion complexity and weather exposure, with high-BTU components driving earlier refresh timelines than passive storage units.
- Grills:Burner manifold assemblies and infrared sear plates require replacement every 5-7 years under intensive thermal cycling. Sun Belt metropolitan areas from Florida to California concentrate demand for premium configurations with rotisserie and smoker integration.
- Refrigerators:Compressor systems and vacuum-insulated panels engineered for ambient temperature operation above 90°F. California Energy Commission Title 20 efficiency standards are accelerating replacement of pre-2018 units across coastal municipalities.
- Sinks:Marine-grade 316 stainless basins with integrated cutting boards and drainage systems. Waterfront installations in Florida specify these for fish cleaning and prep station functionality.
- Burners:Side burner and power burner modules for wok cooking and stockpot heating. Texas and Arizona residential developments are specifying these at higher rates for multicultural cooking requirements.
Volume placements concentrate in grills; the faster expansion belongs to refrigerators.
Material:
Cost tiers separate waterfront specifications from inland suburban installations, with salt-air exposure dictating premium grade requirements.
- Stainless Steel:304-grade dominates inland markets; 316-grade commands waterfront premiums. Coastal California and Florida residential buyers specify marine-grade specifications for corrosion resistance under salt-air exposure.
- Aluminum:Cast and extruded housings for portable and entry-price configurations. Nevada and Arizona markets favor these for weight reduction in seasonal mobility applications.
- Wood:Teak and ipe cabinetry enclosures for custom island integration. High-end California markets specify these for aesthetic warmth in Mediterranean architectural styles.
- Stone:Granite and quartz composite countertops with integrated appliance cutouts. Texas custom installation channels specify these for heat resistance and permanent aesthetic anchoring.
Premium margin capture concentrates in stainless steel; aluminum maintains the broadest volume base.
Application:
Customer type determines specification complexity, with commercial operators prioritizing durability over residential buyers' emphasis on entertainment integration.
- Residential:Single-family suburban installations with permanent gas-line rough-ins. Sun Belt states from Florida through California dominate volume as outdoor living square footage expands.
- Commercial:Restaurant patio configurations requiring NSF certification and high-duty-cycle components. Coastal California municipalities are tightening health department inspection protocols for these installations.
- Entertainment:Integrated audio, lighting, and appliance control for hosting-centric layouts. Arizona and Nevada new construction specifications are rising for these bundled configurations.
- Hospitality:Hotel and resort poolside installations with centralized utility infrastructure. Florida hospitality developers specify these for competitive amenity differentiation in leisure markets.
Residential channels dominate absolute volume; hospitality is climbing the fastest.
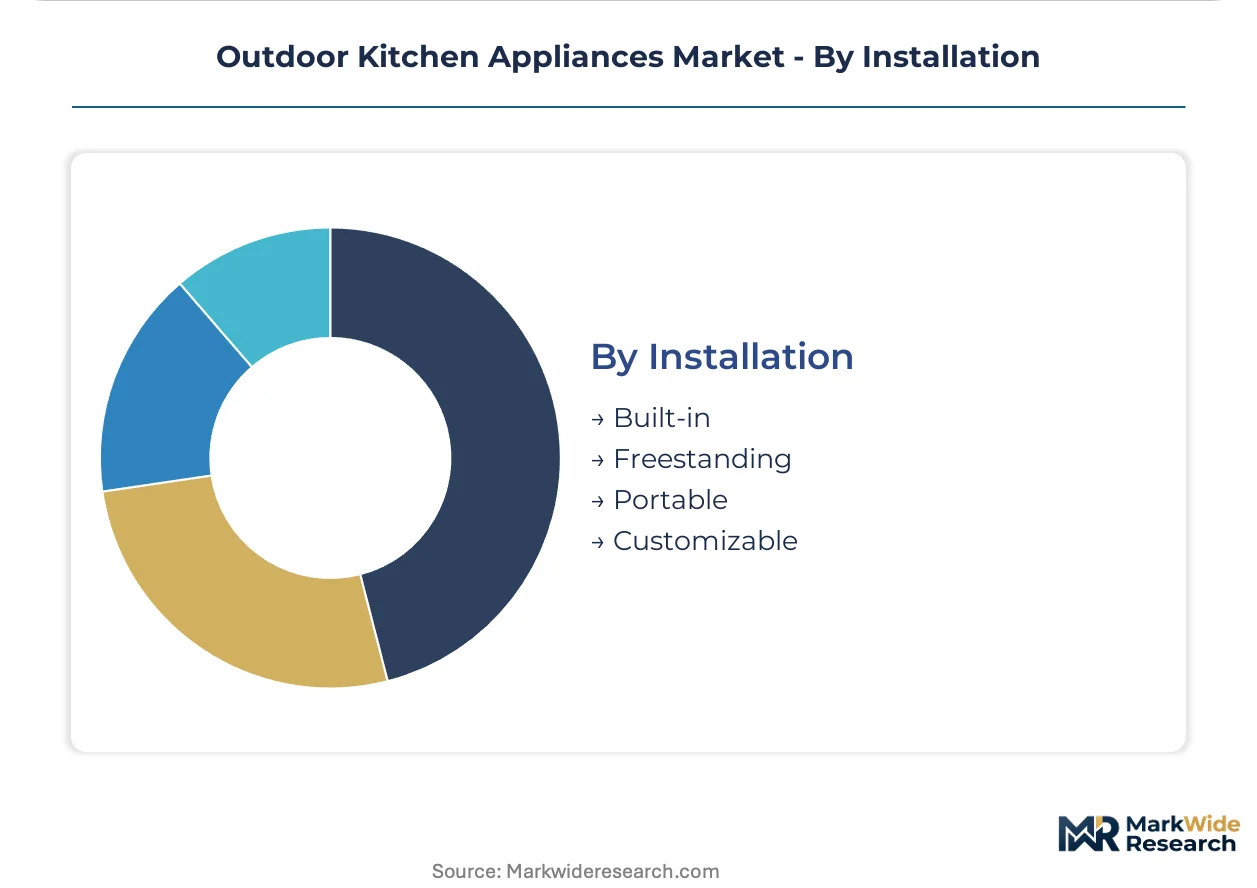
Installation:
Margin structures diverge sharply between permanent infrastructure requirements and seasonal mobility preferences.
- Built-in:Custom cabinetry with gas-line and electrical rough-ins requiring licensed contractor installation. California and Florida markets specify these for property value anchoring and permanent entertainment infrastructure.
- Freestanding:Modular island configurations with integrated utility connections. Texas and Arizona suburban buyers favor these for flexibility in open-plan outdoor spaces.
- Portable:Caster-mounted or lightweight configurations for seasonal storage. Nevada and inland California markets specify these for wildfire evacuation readiness and rental property restrictions.
- Customizable:Component-based systems allowing post-purchase reconfiguration. High-end California buyers specify these for phased outdoor kitchen buildouts.
Built-in formats command the steepest premium pricing; portable configurations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential demand concentrates in the United States, where suburban expansion across Sun Belt metropolitan areas from Florida to California drives replacement cycles and new installation volumes. Sub-regional variations in climate exposure, fuel infrastructure, and electrification timelines create distinct specification requirements across coastal and inland markets.
California
Coastal municipalities from San Diego to San Francisco are accelerating electrification mandates that reshape burner technology specifications toward induction and infrared platforms. The California Energy Commission Title 20 standards govern outdoor refrigerator efficiency thresholds and standby power draw, compelling compressor system redesigns. Los Angeles and Orange County residential developments specify marine-grade 316 stainless specifications for salt-air corrosion resistance.
Texas
Houston and Dallas-Fort Worth suburban developments are expanding outdoor living square footage at rates exceeding national averages, with Class-A multifamily properties installing shared kitchen pods as competitive leasing amenities. Municipal gas line permitting follows NFPA 54 fuel gas code requirements that create compliance barriers for unlicensed contractors. Austin and San Antonio markets favor freestanding modular island configurations for flexibility in open-plan outdoor spaces.
Florida
Waterfront residential installations from Miami to Tampa specify marine-grade 316 stainless housings that resist salt-air corrosion and thermal cycling degradation. The US EPA Energy Star program pathways influence municipal green building incentive programs across coastal counties. Orlando hospitality developers specify centralized outdoor kitchen infrastructure for competitive amenity differentiation in leisure markets.
Arizona
Phoenix and Tucson markets favor aluminum cast housings for weight reduction in seasonal mobility applications and wildfire evacuation readiness. New construction volumes support owner-driven outdoor kitchen planning with direct-to-consumer specification channels displacing traditional contractor-mediated procurement. Nevada-adjacent developments specify portable configurations for rental property restrictions.
Outdoor Kitchen Appliances Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium built-in formats consolidating around vertically integrated foundry operations while portable configurations sustain fragmented assembly networks. The competitive terrain separates into three strategic archetypes: domestic casting specialists controlling burner manifold supply, Canadian manufacturers leveraging scale advantages in infrared technology, and marine-grade fabricators targeting waterfront corrosion specifications. Dominant competitive moves include backward integration into stainless steel supply chains and strategic partnerships with compressor manufacturers for efficiency compliance.
Within the domestic casting tier, Weber-Stephen Products LLC exemplifies foundry network control for high-BTU burner manifolds. Napoleon occupies a position representing Canadian manufacturing scale advantages in infrared sear technology platforms. Kalamazoo Outdoor Gourmet anchors the marine-grade specialist archetype, with its name indicating Michigan-based fabrication targeting waterfront residential specifications.
| Leading Market Players |
|---|
| Napoleon |
| Char-Broil LLC |
| Weber-Stephen Products LLC |
| Kalamazoo Outdoor Gourmet |
| Hestan Outdoor |
| The Middleby Corporation |
| Bull Outdoor Products, Inc. |
| GE Appliances |
| Traeger Pellet Grills LLC |
| Others |
Supply Flow & Price Mechanics
London Metal Exchange nickel futures and chromium alloy benchmarks cascade through burner manifold and housing production, compressing margins on mid-tier grill assemblies while marine-grade 316 specifications sustain waterfront premiums. This commodity-cost architecture splits pricing power between foundry-integrated incumbents and assembly-dependent challengers.
Pricing Analysis
Volume concentrates in aluminum portable configurations at entry price points, while margin pools anchor in built-in stainless steel formats with custom cabinetry and gas-line rough-ins. Three-tier pricing structure across premium, standard, and economy levels reflects material grade, certification tier, and after-sales bundling differentiation. Cost compression in mid-tier 304-grade housings is intensifying because nickel price volatility feeds directly into burner manifold input costs. DIY residential buyers in inland Sun Belt markets exhibit highest price sensitivity; waterfront specification buyers in Florida and coastal California demonstrate lowest elasticity due to corrosion-performance requirements.
Supply Chain Analysis
Freight cost differentials between Canadian manufacturing hubs and US distribution centers favor Napoleon and other North American producers against Asian assembly competitors. Foundry capacity concentrates in the United States, Canada, and China, with domestic casting specialists controlling high-BTU burner manifold supply. Raw material dependencies center on Indonesian nickel ore, South African chromium, and Australian alumina. Single-source vulnerability runs through marine-grade 316 stainless supply from specialized mills. Distribution runs through contractor-mediated channels for built-in formats and direct-to-consumer platforms for portable configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where foundry control over burner manifold supply and captive stainless sourcing determine margin defense. Players are pursuing backward integration into alloy supply and compressor manufacturing to capture efficiency compliance premiums.
For Market Incumbents: Deploy foundry network expansion to secure domestic casting capacity for high-BTU components, insulating against nickel price volatility and electrification-driven burner redesign cycles. Deepen captive supply of 316-grade stainless through mill partnerships to defend waterfront specification margins against marine-grade fabricators. Counter the threat of induction platform mandates by accelerating infrared sear technology R&D partnerships. For New Entrants and Emerging Players: Direct-to-consumer specification channels offer the most penetrable route, displacing contractor-mediated procurement in Arizona and Nevada new construction markets. Target aluminum portable configurations for seasonal mobility applications where weight reduction and wildfire evacuation readiness drive specification. Pursue IPX4-rated smart control integration as a go-to-market angle, converging Bluetooth-enabled temperature monitoring with home automation platforms. For Investors and Strategic Acquirers: Distressed-cycle entries favor marine-grade fabrication specialists with 316 stainless TIG welding certification in Florida and coastal California waterfront markets. Long-term viability hinges on electrification compliance capabilities and infrared platform portfolios rather than pure gas-burner legacy. Watch California Energy Commission Title 20 enforcement acceleration as the inflection indicator for compressor system redesign investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Expansion | Domestic casting control insulates Weber-Stephen and peers from nickel alloy price volatility. |
| Infrared Technology Licensing | Napoleon's Canadian manufacturing scale enables premium sear-capability differentiation against gas-burner commoditization. |
| Marine-Grade Certification Investment | Kalamazoo's 316 stainless specifications capture waterfront corrosion-resistance premiums in Florida. |
| Direct-to-Consumer Channel Buildout | Arizona and Nevada owner-driven specification displaces traditional contractor procurement for portable configurations. |
| Energy Star Compliance Pathway | US EPA standby power thresholds unlock municipal green building incentive program preferential specification. |
Methodological Framework
Document review covered customs and trade data, SEC filings from publicly traded appliance manufacturers, and National Fire Protection Association code documentation, complemented by interviews with product development executives at grill and refrigeration OEMs, procurement managers at stainless steel distributors, and municipal permitting authorities in California and Florida. Secondary validation drew from EPA Energy Star certification databases, California Energy Commission Title 20 compliance filings, and LME nickel price archives. Bottom-up installation volume estimates triangulated against top-down manufacturer shipment data.
Historical shipment patterns cross-referenced against panel input from foundry operators and compressor manufacturers informed the analytical framework across the analysis window. Segmentation dimensions modeled include product type, material grade tier, installation format, and regional electrification timeline. CAGRs derived from regression-based trend extrapolation moderated by regulatory compliance cycle assumptions. Industry-specific forecast inputs incorporated NFPA 54 adoption trajectories and marine-grade specification penetration rates.
The model holds under stable nickel-chromium alloy pricing and incremental electrification mandate rollout; deviation in commodity volatility spikes or accelerated coastal municipality gas-ban timelines would shift replacement cycle and technology mix assumptions. Forecasts reflect documented assumptions regarding Sun Belt construction volume sustainability and efficiency code enforcement intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Built-In Kitchen Appliances Market
Kitchen Appliances
Capsule Coffee Machines Market
Kitchen Appliances
Cooktop Market
Kitchen Appliances
Europe Major Home Appliances Market
Kitchen Appliances
India Kitchen Appliances Market
Kitchen Appliances
South Korea Electric Hobs Market
Kitchen Appliances
Small Kitchen Appliances Market
Kitchen Appliances
Household Bread Machine Market
Kitchen Appliances
India Mixer Grinder Market
Kitchen Appliances
Electric Pressure Cooker Market
Kitchen Appliances
United Kingdom Kitchen Appliances Market
Kitchen Appliances
Portable Outdoor Pizza Oven Market
Kitchen Appliances
US Range Cooker Market
Kitchen Appliances
UK Cookware Market
Kitchen Appliances
Commercial Countertop Ranges Market
Kitchen Appliances
Switzerland Kitchen Appliances Product Market