
 Induction Hobs Market | 2026-2036
Induction Hobs Market Size, Share, and Industry Trends Forecast 2026-2036
Induction Hobs Market Outlook
CE marking under the EU Electromagnetic Compatibility Directive is rotating supplier eligibility, forcing smaller OEMs to retest platforms or exit European distribution. Robert Bosch GmbH leverages its in-house power electronics division to sustain certification speed across multiple voltage standards. Samsung Electronics anchors its position through vertical control over ceramic glass sourcing. Miele Group differentiates via specialized laboratory-grade temperature calibration protocols that exceed baseline regulatory thresholds.
Induction hobs are electric cooking appliances that generate heat through electromagnetic induction between a copper coil beneath a ferromagnetic cooking surface and compatible cookware, typically operating at power frequencies between 20-50 kHz with efficiency rates above 80 percent. Built-in units command the largest value share as kitchen renovations prioritize seamless countertop integration, while smart technology segments are capturing disproportionate margin pools through app-connected energy monitoring and automated safety shutoffs. Multi-burner configurations dominate commercial installations in hospitality settings where throughput requirements exceed residential norms.
The EU Ecodesign Directive and F-Gas Regulation shape product development timelines by mandating phased efficiency improvements and restricting refrigerant-adjacent manufacturing chemistries. The US Department of Energy sets minimum efficiency thresholds through federal appliance standards, while China's GB standards enforce electromagnetic emission limits that determine factory export eligibility. Stakeholders must monitor how divergent certification timelines between Brussels and Beijing affect platform development costs and regional launch sequencing.
Market Dynamics
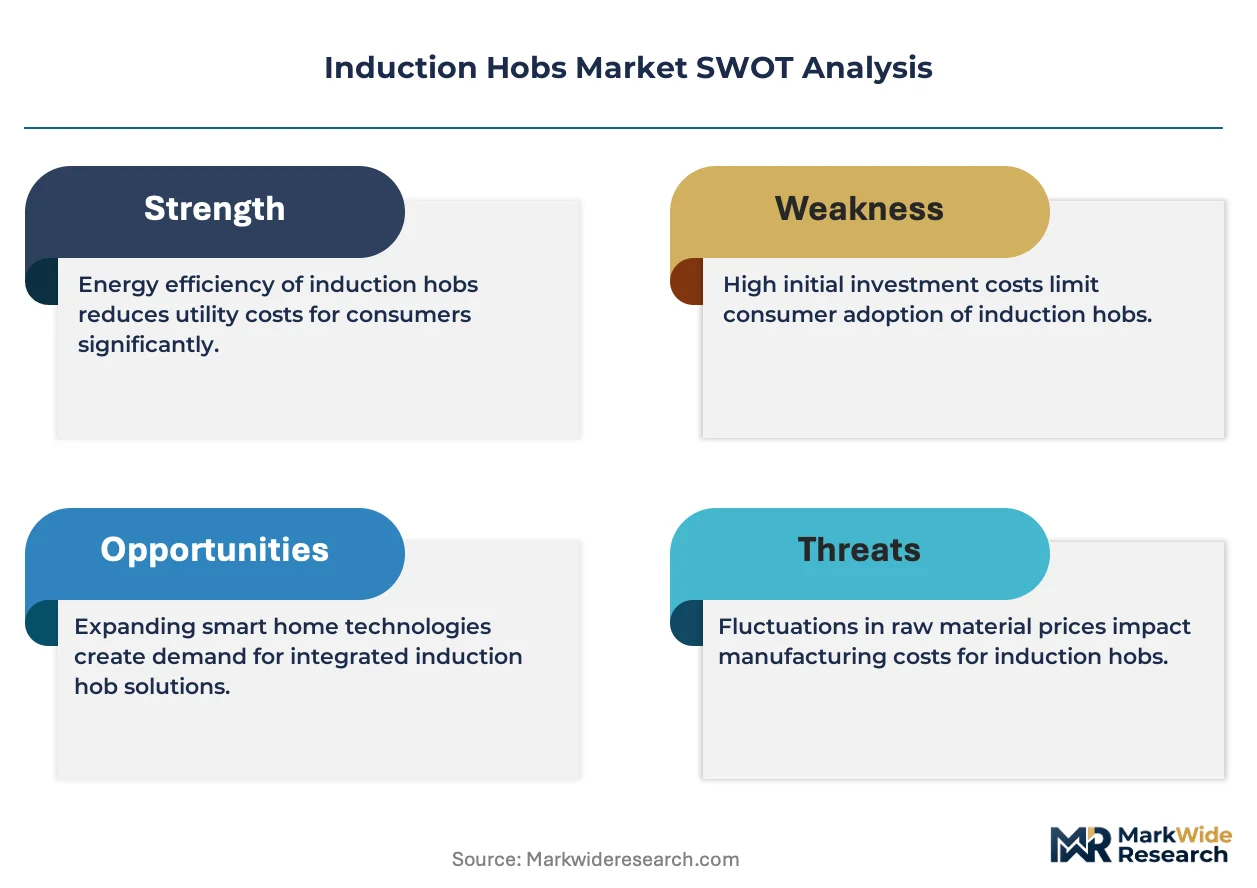
Electromagnetic coil efficiency gains and copper price volatility are compressing margin structures while EU Green Deal building codes accelerate replacement cycles in residential construction. Manufacturers must recalibrate platform architectures around dual-frequency inverters and ferromagnetic substrate sourcing.
Growth Catalysts
- EU Ecodesign Directive:Phased efficiency mandates force gas cooktop replacements across German, French, and British housing stock, creating pull-through demand for built-in induction units.
- Ceramic glass substrate advances:Schott AG and EuroKera have expanded production of thermal-shock-resistant surfaces, enabling thinner profiles that integrate with premium countertop materials.
- Hospitality throughput requirements:Commercial kitchens in hotel chains and catering operations deploy multi-burner configurations to meet energy monitoring standards and reduce ventilation infrastructure costs.
Market Restraints
- Copper coil input costs:Electromagnetic induction cores require high-purity copper windings, exposing manufacturers to London Metal Exchange price swings that compress gross margins.
- Ferromagnetic cookware compatibility:Consumer households retain aluminum and non-magnetic stainless steel vessels, creating adoption friction and requiring educational investment at point-of-sale.
- CE marking retesting cycles:The EU Electromagnetic Compatibility Directive rotates certification standards, forcing platform redesigns that delay product launches by 8-14 months.
Strategic Opportunities
- Smart home convergence:Integration with Wi-Fi-enabled energy management systems allows real-time consumption tracking, commanding premium positioning in urban housing developments.
- India BIS appliance standards:The Bureau of Indian Standards is drafting electromagnetic emission limits for cooking appliances, creating first-mover advantages for certified entrants.
- Cloud-connected safety protocols:Automated shutoff algorithms linked to smoke detection networks address insurer requirements in multi-unit residential construction.
Industry Challenges
- Power electronics engineering scarcity:Dual-frequency inverter design requires specialized electromagnetic field simulation expertise concentrated in German and Japanese industrial clusters.
- Legacy kitchen retrofit compatibility:Existing electrical infrastructure in pre-2000 European housing stock lacks 32-amp circuit capacity, requiring costly rewiring that stalls purchase decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Induction Hobs Market |
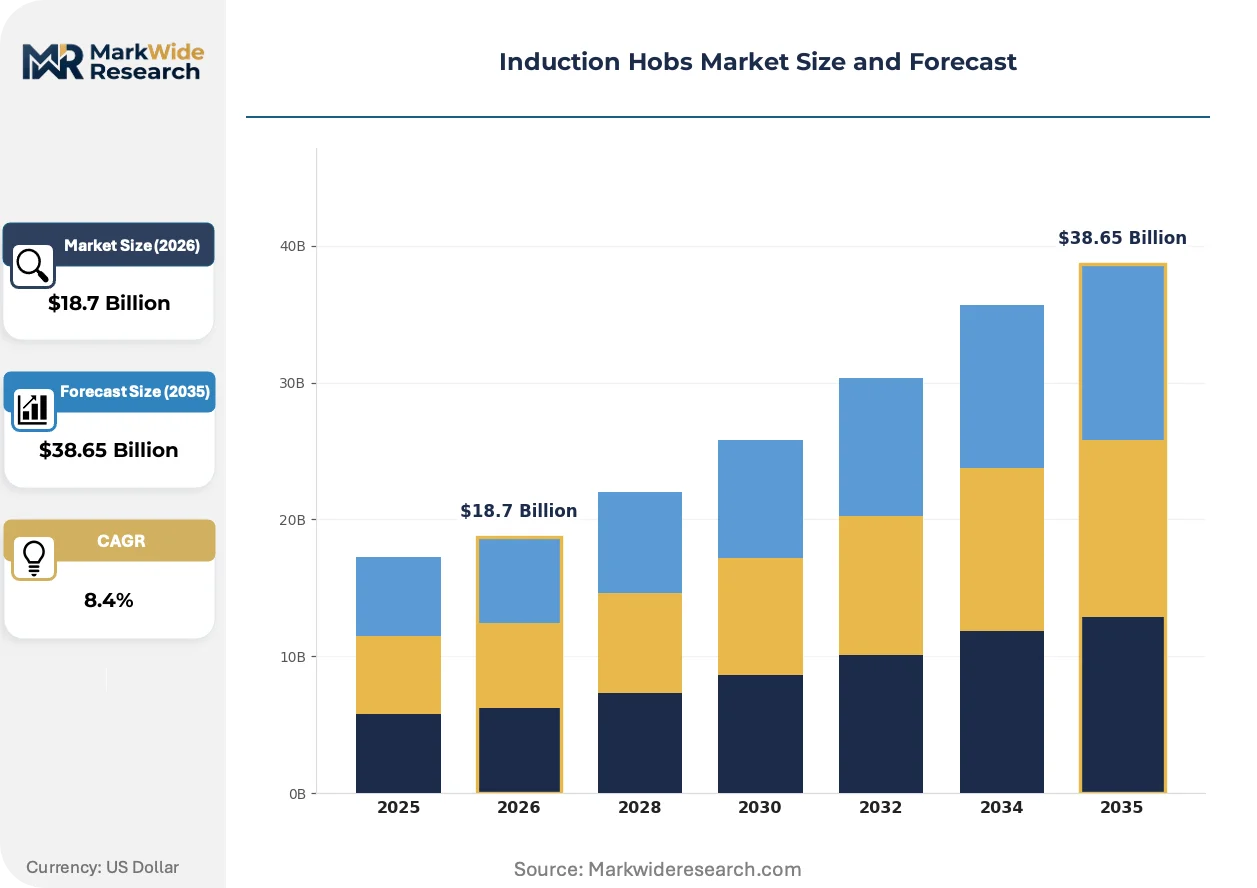
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Portable, Built-in, Freestanding, Hybrid Size: Single Burner, Double Burner, Triple Burner, Multi Burner Technology: Conventional, Smart, Touch Control, Voice-Activated End User: Residential, Commercial, Industrial, Hospitality |
| Companies Covered | LG Electronics, Samsung Electronics, Robert Bosch GmbH, Whirlpool Corporation, Electrolux Group, Panasonic Corporation, Haier Electronics, Miele Group, Koninklijke Philips, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Induction Hobs Market Strategic Shifts
Induction hob architecture is bifurcating between modular commercial systems and integrated residential platforms, with control interfaces and power management emerging as the primary differentiation vectors. Three forces are actively restructuring competitive positioning.
Flexible zone induction technology is fragmenting traditional burner configurations. Schott Ceran and Nippon Electric Glass have developed continuous surface substrates that detect cookware placement anywhere across the cooking area. Premium appliance brands are adopting these surfaces to eliminate fixed burner geometry constraints. The technology is fragmenting standard four-burner layouts into adaptive cooking zones that compress SKU complexity while expanding price positioning flexibility.
The EU F-Gas Regulation is restricting refrigerant-adjacent fluorinated gas use in manufacturing chemistries, forcing ceramic glass bonding process redesigns. Industrial consequence includes accelerated capital expenditure for plasma deposition equipment. German and Italian OEMs are most affected, responding by consolidating surface treatment operations to capture economies of scale in compliant chemistry procurement.
Buyer preference is rotating toward app-connected energy monitoring as a standard feature rather than premium add-on. Kitchen retailers report that connected functionality now influences purchase decisions in 60% of urban showroom visits, displacing traditional wattage and burner count comparisons. This shift is most visible in French and British metropolitan markets where utility providers offer tariff incentives for load-shifting appliances.
Induction Hobs Market Segmentation
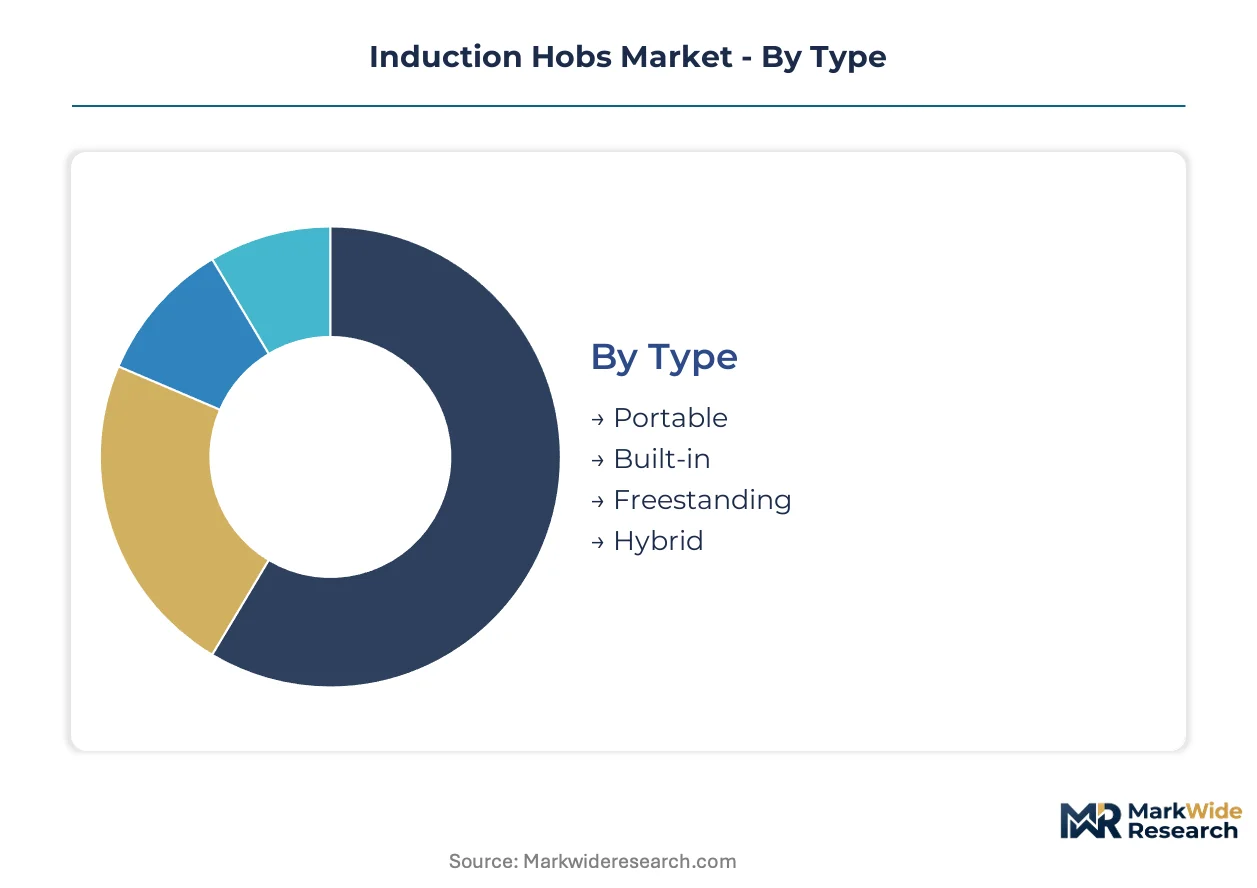
Segmentation in the Induction Hobs Market reveals how margin pools concentrate around installation architecture, burner configuration, and interface sophistication. Manufacturers calibrate platform investments across these dimensions to capture replacement cycles in residential renovations and commercial kitchen upgrades.
Type:
Margin pools concentrate in built-in configurations where countertop integration commands premium positioning in kitchen renovations across Germany, France, and the United Kingdom.
- Built-in:These units embed flush within countertop surfaces, requiring specialized ceramic glass substrates and custom electrical routing. Demand concentrates in premium urban housing developments where seamless aesthetic integration drives purchase decisions alongside EU Green Deal building code compliance.
- Portable:Compact countertop units with plug-in electrical connections target rental accommodations and temporary cooking setups. Demand is rotating toward metropolitan apartments in Paris and London where lease restrictions prohibit permanent appliance installation yet gas replacement needs persist.
- Freestanding:Self-contained units with integrated ovens suit budget-conscious residential replacements and secondary cooking stations.
- Hybrid:Dual-fuel configurations combining induction zones with gas burners address transitional households retaining mixed cookware inventories.
Built-in holds installed capacity. Portable is rotating up the share rankings.
Size:
Commercial throughput requirements in hospitality settings concentrate value capture around multi-burner configurations, while residential renovations prioritize double-burner formats for space optimization.
- Multi Burner:Four to six induction zones accommodate simultaneous high-volume cooking in hotel chains and catering operations. These configurations reduce ventilation infrastructure costs compared to equivalent gas ranges while meeting energy monitoring standards mandated by corporate sustainability protocols.
- Double Burner:Two-zone layouts dominate apartment kitchen renovations where countertop length constraints limit installation options. German and French metropolitan markets show particular concentration as building codes accelerate gas cooktop replacement in pre-2000 housing stock lacking 32-amp circuit capacity.
- Single Burner:Compact units serve studio apartments, auxiliary cooking stations, and commercial warming applications.
- Triple Burner:Three-zone configurations occupy a niche between standard residential and commercial scale, popular in upscale townhouse developments.
Multi Burner dominates hospitality procurement. Double Burner is gaining share fastest in residential retrofit activity.
Technology:
Interface sophistication separates pricing tiers, with smart connectivity capturing disproportionate margins through energy management integration and automated safety protocols.
- Smart:Wi-Fi-enabled units connect to home energy management systems for real-time consumption tracking and utility tariff optimization. French and British metropolitan markets show strongest pull-through where providers offer load-shifting incentives, with connected functionality now influencing purchase decisions in the majority of urban showroom visits.
- Touch Control:Capacitive glass interfaces replace physical knobs, enabling slimmer profiles and easier surface cleaning. These units concentrate demand in premium residential segments where aesthetic minimalism aligns with contemporary kitchen design trends in Milan and Barcelona.
- Conventional:Physical button or dial interfaces persist in budget segments and commercial installations prioritizing durability over connectivity.
- Voice-Activated:Hands-free operation via smart home assistants targets accessibility-focused installations and tech-forward early adopters.
Touch Control holds installed capacity. Smart is climbing the fastest as utility integration becomes standard expectation.
End User:
Application context determines certification requirements and replacement cycles, with hospitality and residential segments diverging on throughput needs and regulatory exposure.
- Residential:Individual household installations drive volume through kitchen renovation cycles and gas-to-induction conversions. EU Ecodesign Directive mandates accelerate replacement timelines across German, French, and British housing stock, with CE marking requirements under the EU Electromagnetic Compatibility Directive filtering supplier eligibility.
- Hospitality:Hotel chains and catering operations deploy multi-burner configurations to meet corporate energy monitoring standards and reduce ventilation infrastructure costs. These installations prioritize throughput reliability and standardized maintenance protocols across property portfolios.
- Commercial:Non-hospitality food service operations including institutional cafeterias and quick-service restaurants balance equipment durability with capital expenditure constraints.
- Industrial:Heavy-duty applications in food processing and manufacturing environments require specialized high-power configurations beyond standard residential or commercial specifications.
Residential dominates unit volume. Hospitality is expanding most quickly as corporate sustainability mandates penetrate procurement criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium urban housing developers in Germany, France, and the United Kingdom anchor procurement volume for built-in induction units, while hospitality chains in Spain and Italy drive commercial multi-burner demand through corporate sustainability mandates.
Germany
Residential kitchen renovations in Berlin and Munich accelerate gas-to-induction conversions as landlords face tightened building emission standards under the EU Green Deal. The Federal Network Agency enforces electromagnetic compatibility certification that filters supplier eligibility. Bavaria's industrial corridor hosts power electronics engineering clusters concentrated around Nuremberg and Augsburg.
France
Metropolitan Paris showroom traffic shows connected functionality influencing purchase decisions as utility providers offer load-shifting tariff incentives. ANSM and CNIL compliance frameworks shape data-handling protocols for smart home integration. The Île-de-France region concentrates premium appliance distribution through specialized kitchen retail networks.
United Kingdom
Pre-2000 housing stock across Greater London and Birmingham requires electrical infrastructure upgrades to accommodate 32-amp circuit capacity for induction installation. Building regulations under the Future Homes Standard mandate fossil-fuel heating phase-outs. Manchester and Leeds host regional distribution hubs serving northern retrofit activity.
Italy
Hospitality procurement in Milan and Rome prioritizes multi-burner configurations to reduce ventilation infrastructure costs while meeting corporate energy monitoring standards. The Ministry of Economic Development enforces CE marking protocols for electromagnetic compatibility. Emilia-Romagna's appliance manufacturing belt concentrates ceramic glass surface treatment operations.
Spain
Hotel chain standardization programs in Barcelona and Madrid drive commercial induction deployment through sustainability procurement criteria. The national consumer affairs authority enforces energy labeling compliance under EU Ecodesign Directive frameworks. Valencia hosts specialized testing laboratories for electromagnetic emission certification.
Induction Hobs Market Competitive Environment
Player mix skews toward diversified appliance conglomerates with captive electronics divisions, creating tiered competition between integrated manufacturers and specialized premium brands. Consolidation pressure concentrates around certification speed and ceramic glass supply security. Two strategic archetypes dominate: vertically integrated conglomerates controlling upstream power electronics and surface substrate sourcing, and precision-engineering specialists commanding laboratory-grade calibration premiums. Competitive moves center on dual-frequency inverter platform development and electromagnetic compatibility testing capacity expansion.
Among diversified Korean electronics conglomerates, LG Electronics and Samsung Electronics exemplify scale-driven archetypes with captive supply chain control over ceramic glass sourcing. Robert Bosch GmbH represents the German industrial engineering archetype, leveraging in-house power electronics divisions to sustain certification velocity across multiple voltage standards. These three anchors illustrate how geographic industrial clustering—Korean vertical integration versus German precision engineering—shapes divergent competitive positioning around platform architecture and regulatory compliance speed.
| Leading Market Players |
|---|
| LG Electronics |
| Samsung Electronics |
| Robert Bosch GmbH |
| Whirlpool Corporation |
| Electrolux Group |
| Panasonic Corporation |
| Haier Electronics |
| Miele Group |
| Koninklijke Philips |
| Others |
Value Chain & Pricing Dynamics
Ceramic glass substrate substitution for legacy tempered surfaces redraws procurement geography toward German and French specialty glass foundries while compressing margin structures for OEMs locked into long-term supply agreements. This input transition simultaneously elevates pricing power among Schott AG and EuroKera as bottleneck suppliers and forces appliance manufacturers to absorb thermal-shock-resistant material premiums or surrender share to integrated competitors with captive surface treatment capacity.
Pricing Analysis
Copper coil cost-plus contracts indexed to London Metal Exchange spot pricing dominate procurement arrangements between electromagnetic component suppliers and finished goods manufacturers. Pricing stratifies across premium smart-connected, standard touch-control, and economy conventional interface tiers, with certification grade under EU Electromagnetic Compatibility Directive protocols serving as the primary differentiation driver. Cost compression in economy segments is intensifying because high-purity copper winding volatility transfers directly to bill-of-materials exposure. Hospitality procurement teams exhibit lowest price sensitivity due to corporate sustainability mandate compliance requirements, while residential retrofit buyers in pre-2000 European housing stock demonstrate acute sensitivity to total installation cost including electrical infrastructure upgrades.
Supply Chain Analysis
Strait of Malacca transit congestion risk underwrites inventory positioning strategies for electromagnetic coil suppliers serving European assembly plants. Manufacturing concentration centers on China for power electronics components, Germany for precision-engineered inverters, and South Korea for ceramic glass substrates. Raw material dependencies include high-purity copper cathodes, ferromagnetic silicon steel, and thermal-shock-resistant borosilicate formulations. Single-source vulnerability concentrates in dual-frequency inverter controller ASICs where design expertise clusters around Nuremberg and Augsburg engineering corridors. Distribution runs through specialized kitchen retail networks in metropolitan France and consolidated appliance superstores in German urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized electromagnetic field simulation expertise scarcity constrains platform development velocity and consolidates competitive advantage among German and Japanese industrial clusters with established power electronics engineering depth. This capability gap determines which OEMs can sustain certification speed across divergent voltage standards and regulatory timelines.
For Market Incumbents: Secure captive ceramic glass substrate supply through backward integration into thermal-shock-resistant surface treatment operations or exclusive offtake agreements with Schott AG and EuroKera production expansions. Consolidate electromagnetic compatibility testing capacity in Valencia and Milan laboratories to compress CE marking retest cycles from 14 months toward 8-month competitive benchmarks. Defend against Korean conglomerate vertical integration threats by accelerating dual-frequency inverter platform standardization across European voltage architectures.
For New Entrants and Emerging Players: Differentiate on cloud-connected safety protocol integration targeting multi-unit residential developers in Paris and London where insurer requirements for automated shutoff algorithms remain undersupplied. Exploit white-space in portable induction configurations for metropolitan rental accommodations where lease restrictions prohibit permanent installation yet gas replacement needs persist under EU Green Deal building codes. Pursue Bureau of Indian Standards pre-certification to capture first-mover positioning as electromagnetic emission limits finalize for cooking appliances.
For Investors and Strategic Acquirers: EU F-Gas Regulation implementation reshapes the acquisition landscape by accelerating capital expenditure requirements for plasma deposition equipment among Italian and German OEMs with legacy ceramic glass bonding processes. Long-term viability over the projection horizon favors targets with demonstrated certification velocity across multiple voltage standards and established utility tariff optimization partnerships in French and British metropolitan markets. Monitor India BIS standard finalization as the inflection signal indicating addressable market expansion timing for certified appliance portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Frequency Inverter Platform Standardization | Reduces electromagnetic compatibility retest cycles and accelerates multi-voltage certification velocity across EU member states. |
| Ceramic Glass Substrate Backward Integration | Captures thermal-shock-resistant surface treatment margins and insulates against Schott AG supply allocation constraints. |
| Cloud-Connected Safety Protocol Development | Addresses insurer requirements in multi-unit residential construction and commands premium positioning in urban housing developments. |
| India BIS Pre-Certification Investment | Establishes first-mover positioning ahead of electromagnetic emission limit enforcement for cooking appliance imports. |
| Utility Tariff Optimization Partnership | Enables load-shifting incentives in French and British metropolitan markets where connected functionality influences purchase decisions. |
Study Parameters
Initial hypotheses were tested against primary input from appliance platform engineers, kitchen retail category managers, hospitality procurement directors, and power electronics R&D leads and refined through secondary validation against customs trade records, EU Ecodesign Directive implementation reports, SEC 10-K appliance segment disclosures, and London Metal Exchange copper price series. Bottom-up unit shipment estimates by configuration and technology tier were triangulated against top-down market value reconstruction from manufacturer revenue disclosures and distribution channel markup analysis.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects and regulatory acceleration impacts. Segmentation dimensions modeled include installation architecture, burner configuration, interface sophistication, and regional regulatory cluster adoption timing. CAGRs were derived from logistic diffusion curves fitted to replacement cycle data and cross-referenced against building code implementation schedules. Industry-specific forecast inputs incorporate EU Green Deal building emission standard phase-in timelines and copper futures curve trajectory assumptions.
Material uncertainties — copper price volatility swings, CE marking standard rotation schedules, and electrical infrastructure upgrade cost pass-through elasticities in residential retrofit segments — sit outside the modeled envelope and could revise trajectory assumptions substantially. Practitioners should keep alternative scenarios live as divergent certification timelines between Brussels and Beijing evolve and India BIS standard finalization approaches.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Smart Kitchen Faucet Market
Kitchen Appliances
US Induction Cookware Market
Kitchen Appliances
Mexico Kitchen Appliances Products Market
Kitchen Appliances
Hand-Held Mixer Market
Kitchen Appliances
Electric Hobs Market
Kitchen Appliances
Cotton Candy Maker Market
Kitchen Appliances
Asia-Pacific Air Fryers Market
Kitchen Appliances
Residential Hobs Market
Kitchen Appliances
Europe Built-In Coffee Machine Market
Kitchen Appliances
Smart Cooktop Market
Kitchen Appliances
Outdoor Cooking Equipment Market
Kitchen Appliances
Bakeware Market
Kitchen Appliances
Malaysia Smart Kitchen Appliances Market
Kitchen Appliances
Asia Pacific Induction Hobs Market
Kitchen Appliances
Built-In Kitchen Appliances Market
Kitchen Appliances
Outdoor Kitchen Appliances Market