
 Household Bread Machine Market | 2026-2036
Household Bread Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Household Bread Machine Market Foresight
Single-source component procurement is restructuring into multi-source strategies across the household bread machine supply chain. Panasonic Corporation leverages its vertical integration in heating element manufacturing to sustain cost advantages in premium segments. Midea Group anchors high-volume production through scale efficiencies in programmable and basic bread maker categories. Zojirushi America Corporation differentiates through specialized horizontal kneading technology that commands loyalty among baking enthusiasts.
A household bread machine is an electric countertop appliance that automates bread preparation through controlled mixing, kneading, rising, and baking cycles, typically operating at power ratings between 450 and 1650 watts with programmable crust and loaf-size settings. Its primary purpose is to enable consistent, repeatable home bread production without manual intervention or specialized culinary skill. Programmable bread makers and multi-functional bread makers capture the dominant margin pools as consumers trade up for scheduling flexibility and expanded recipe libraries. Gluten-free bread baking represents the fastest-growing application segment as dietary restriction awareness expands among health-conscious consumers and first-time users.
FDA guidelines for food-contact surfaces and electrical safety standards from UL shape material selection and heating system architecture in the United States market. The EU F-Gas Regulation and CE marking requirements constrain refrigerant-based cooling integrations and mandate specific energy efficiency disclosures for appliances sold across member states. Ecodesign directives from the European Commission progressively tighten standby power limits, forcing manufacturers to redesign control boards and display modules. Stakeholders must monitor evolving efficiency thresholds and material compliance timelines to preserve market access and avoid redesign costs.
Market Dynamics
Energy efficiency mandates from the European Commission are forcing redesign cycles across control board architectures, compressing development timelines while raising compliance costs for manufacturers serving multi-jurisdictional markets.
Growth Catalysts
- EU Ecodesign Directives:Progressive standby power limits accelerate replacement demand for older units and create upgrade cycles among efficiency-conscious residential buyers.
- Gluten-free recipe programming:Specialized baking cycles for dietary restrictions attract health-focused consumers and first-time appliance purchasers seeking dietary customization.
- Japan:Compact kitchen footprints and aging demographics sustain premium demand for programmable units with delayed-start functionality.
Market Restraints
- Heating element supply concentration:Dependence on specialized ceramic and metal alloy suppliers in East Asia creates input cost volatility and logistics vulnerability.
- Counter space competition:Multi-function appliances including combination pressure cookers and air fryers substitute dedicated bread machine purchases in space-constrained kitchens.
- F-Gas Regulation compliance costs:EU constraints on refrigerant-based cooling integrations limit product feature expansion and raise engineering overhead.
Strategic Opportunities
- Germany:Underpenetrated secondary household ownership and strong sustainability preferences create white space for certified efficient premium models.
- Smart home integration:Voice control and app-based recipe management converge with connected kitchen ecosystems to differentiate mid-tier offerings.
- Subscription ingredient services:Pre-portioned flour and yeast delivery partnerships create recurring revenue attachment to hardware sales.
Industry Challenges
- Firmware certification timelines:UL electrical safety validation and FDA food-contact material approvals extend product launch windows by six to twelve months.
- Legacy control board integration:Retrofitting existing production lines for reduced standby power draws requires capital-intensive manufacturing reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Household Bread Machine Market |
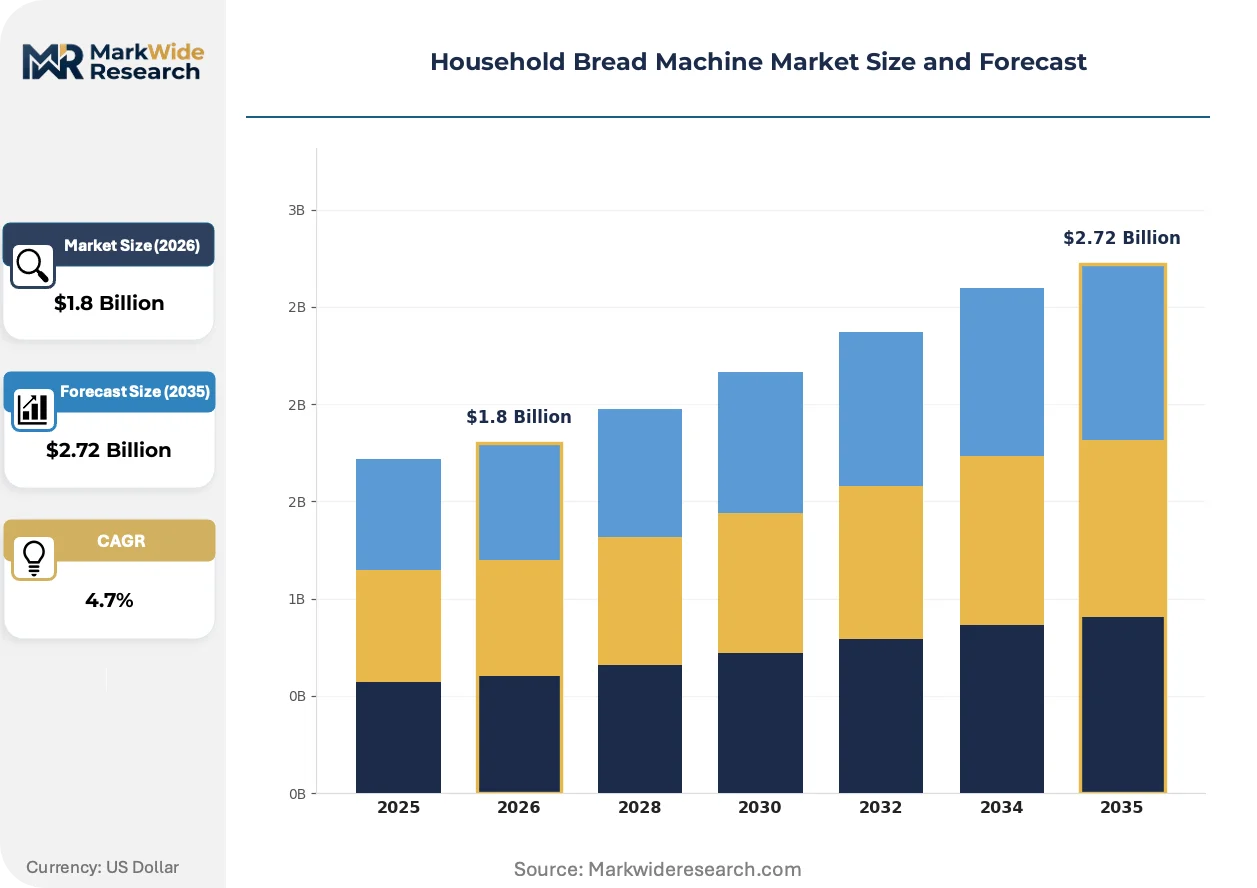
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Basic Bread Makers, Programmable Bread Makers, Automatic Bread Machines, Multi-Functional Bread Makers, Compact Bread Machines Technology: Rotary Kneading, Vertical Kneading, Horizontal Kneading, Convection Heating, Non-Stick Baking Pan Application: Home Baking, Small-Scale Baking, Custom Bread Preparation, Gluten-Free Bread Baking, Vegan Bread Making Customer Type: First-Time Users, Baking Enthusiasts, Health-Conscious Consumers, Gift Buyers, Culinary Professionals |
| Companies Covered | Midea Group, Panasonic Corporation, Xinbao Holding Group, Zojirushi America Corporation, Philips Domestic Appliances, Delonghi Group, Hamilton Beach Brands, Petrus Electrical Appliances, AUCMA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Household Bread Machine Market Shifts & Advancements
Connected functionality and automated ingredient dispensing are absorbing development resources across tier-one manufacturers, reshaping feature hierarchies and margin structures in residential kitchen appliances.
Inverter heating technology is absorbing precision temperature control requirements previously handled by mechanical thermostats. Premium segment buyers in Japan and Germany are adopting these units for sourdough and artisan bread programs. This shift is absorbing R&D investment from conventional fixed-wattage architectures and compressing price premiums for basic programmable models.
The EU F-Gas Regulation and companion Ecodesign directives are tightening standby power thresholds and refrigerant constraints for appliances with cooling features. Manufacturers serving European markets are redesigning control boards and eliminating compressor-based options. Programmable and multi-functional bread makers face the steepest compliance cost increases due to sophisticated electronics and display modules.
Direct-to-consumer ingredient subscription bundling is displacing traditional retail-only purchase patterns. Specialty flour mills and yeast suppliers are partnering with appliance brands to capture recurring revenue. This channel innovation is most visible in the United States and Germany where e-commerce penetration in kitchen appliances exceeds conventional electronics retail.
Household Bread Machine Market Segmentation
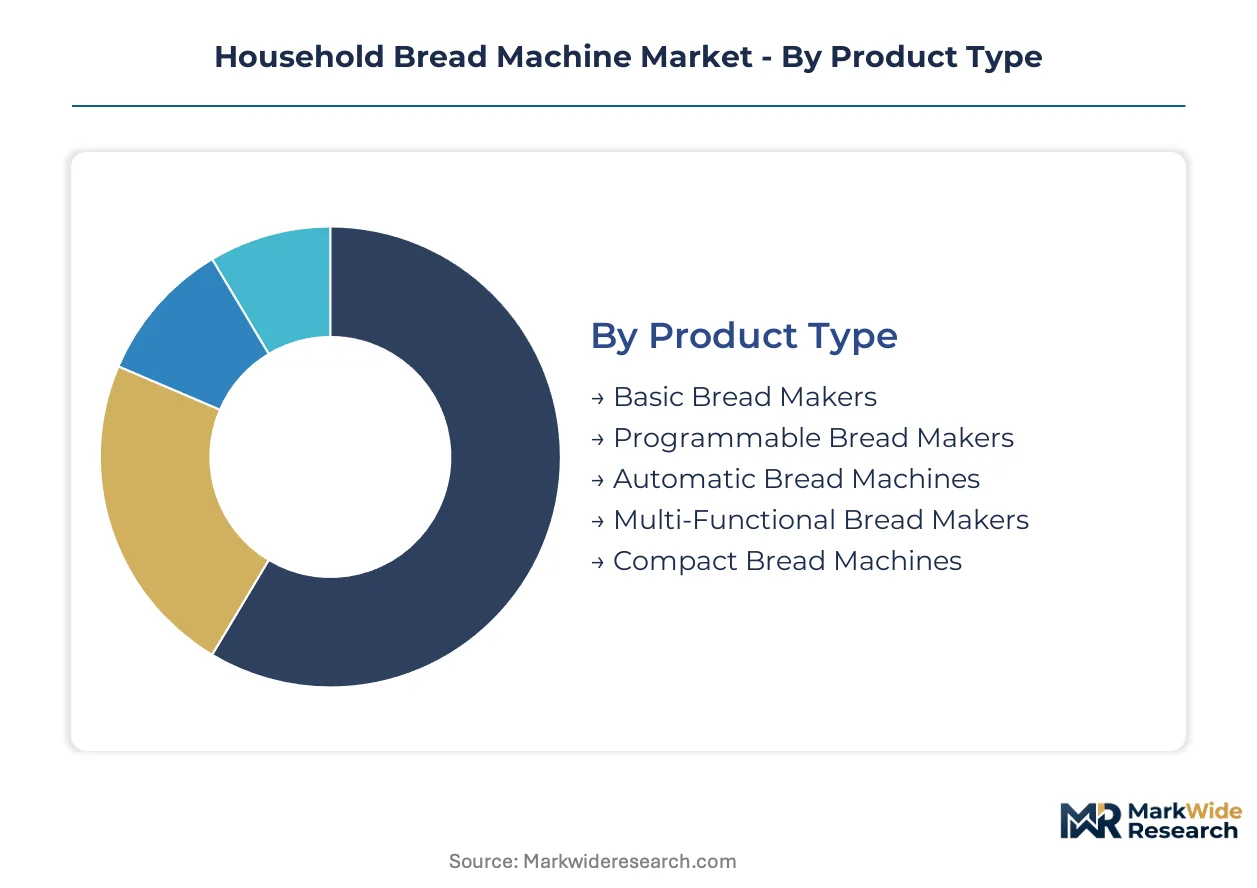
Segmentation in household bread machines reveals how capital allocation, technical complexity, and user sophistication split manufacturing priorities and margin structures across distinct product tiers. Understanding these divides clarifies where R&D investment concentrates and which buyer profiles sustain premium pricing.
Product Type:
Capital intensity escalates sharply from basic mechanical units to electronically dense multi-functional platforms, with programmable and connected variants demanding the heaviest upfront tooling and firmware development.
- Basic Bread Makers:Fixed-cycle mechanical systems with minimal electronics and single-knead paddle configurations. Demand concentrates in price-sensitive first-time buyers across Germany and the United States, constrained by substitution from multi-function kitchen appliances.
- Programmable Bread Makers:Microcontroller-driven units with delayed-start timers, crust selection, and recipe memory banks. Residential kitchens in Japan absorb the highest volumes, driven by compact-footprint requirements and aging demographics seeking scheduling flexibility.
- Automatic Bread Machines:Fully unattended operation from ingredient loading through cooling, typically integrating ingredient dispensers and yeast timers.
- Multi-Functional Bread Makers:Hybrid platforms combining bread cycles with jam, yogurt, and cake programs through swappable paddles and temperature profiles.
- Compact Bread Machines:Reduced-capacity units engineered for single-person households and urban apartments with severe counter-space constraints.
Programmable bread makers absorb the bulk of installed capacity; gluten-free-capable multi-functional units are expanding most quickly.
Technology:
Engineering differentiation clusters around kneading geometry and thermal management, with horizontal and convection systems commanding the steepest patent investment and supplier qualification hurdles.
- Rotary Kneading:Circular paddle motion in a cylindrical pan, the legacy standard for entry-level production with minimal mechanical complexity.
- Vertical Kneading:Top-down paddle drive producing denser crumb structures, dominant in East Asian market designs optimized for softer bread varieties.
- Horizontal Kneading:Dual-paddle side-drive system replicating commercial bakery knead patterns. Baking enthusiasts in the United States and Germany drive adoption, paying premiums for artisan-style crumb and crust development.
- Convection Heating:Fan-assisted forced-air circulation surrounding the baking chamber, enabling faster bake times and more uniform browning across loaf surfaces.
- Non-Stick Baking Pan:Ceramic and diamond-particle coatings reducing oil requirements and simplifying cleanup, now baseline across all tiers.
Horizontal kneading platforms capture the highest margin per unit; convection heating is climbing the fastest as efficiency regulations tighten thermal performance requirements.
Application:
Use-case segmentation tracks dietary restriction prevalence and occasion specificity, with health-driven applications reshaping feature roadmaps and ingredient compatibility testing.
- Home Baking:General-purpose residential bread production, the foundational use case spanning all product tiers and geographies.
- Small-Scale Baking:Supplementary production for home-based food businesses and farmers market sellers, requiring consistent output quality and durability.
- Custom Bread Preparation:User-defined recipes with variable hydration, fermentation time, and ingredient ratios, demanding programmable flexibility.
- Gluten-Free Bread Baking:Specialized cycles with extended mixing and single-rise protocols to compensate for absent gluten structure. Health-conscious consumers across the United States and Germany are accelerating purchases, forcing manufacturers to validate recipes and publish guaranteed results.
- Vegan Bread Making:Egg and dairy substitution compatibility with adjusted rise times and enriched dough handling.
Home baking retains the largest active installed base; gluten-free bread baking shows the steepest expansion trajectory as diagnostic rates and dietary awareness climb.
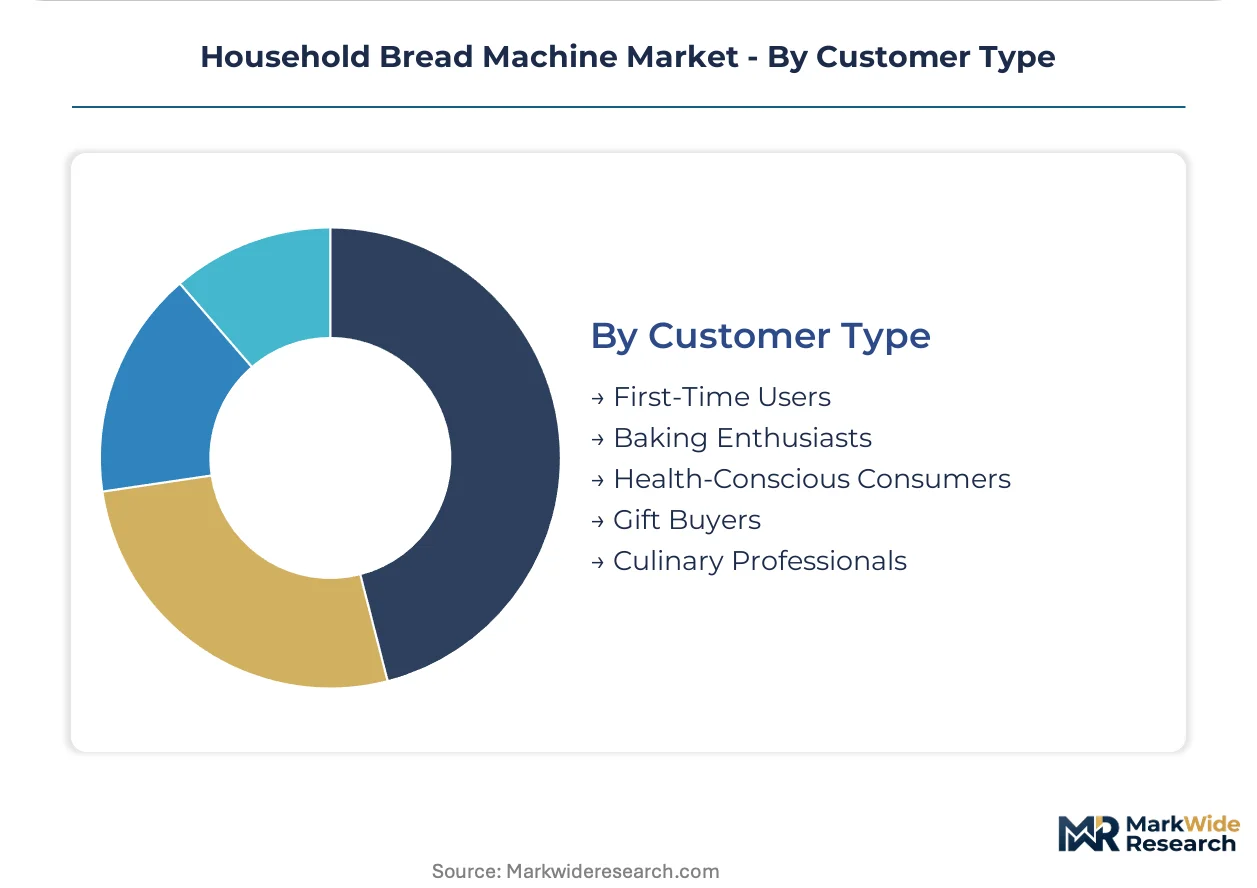
Customer Type:
Buyer sophistication determines pricing power and attachment rate for consumables, with enthusiasts and health-focused segments sustaining subscription ingredient services and premium replacement cycles.
- First-Time Users:Price-sensitive entrants seeking simplicity and reliability, heavily influenced by gift-giving occasions and online review aggregation.
- Baking Enthusiasts:Experienced home bakers with sourdough and artisan specialization, demanding horizontal kneading and precise temperature control. This cohort in Japan and Germany sustains premium tier viability and tolerates longer replacement cycles.
- Health-Conscious Consumers:Buyers prioritizing ingredient transparency and dietary restriction compliance, driving gluten-free and low-sodium program adoption.
- Gift Buyers:Seasonal purchasers responsive to packaging, brand recognition, and warranty terms rather than technical specifications.
- Culinary Professionals:Chefs and cooking instructors using bread machines for demonstration, recipe development, and small-batch testing.
Baking enthusiasts anchor premium pricing stability; health-conscious consumers are gaining share fastest as wellness expenditure displaces conventional appliance purchases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Heating element foundries in Guangdong and Zhejiang provinces anchor East Asian supply chains for bread machine components. Ceramic and metal alloy suppliers in this cluster feed assembly plants across Japan, South Korea, and Southeast Asia. Raw material proximity to manufacturing creates cost efficiencies that ripple through finished goods pricing in export markets.
United States
Health-conscious consumers in California and the Pacific Northwest drive gluten-free and programmable unit adoption. FDA food-contact surface guidelines and UL electrical safety standards constrain material selection and extend product certification timelines. Austin and Denver metro areas show concentrated demand for smart home-integrated bread makers with voice control compatibility.
Germany
Sustainability preferences in Bavaria and North Rhine-Westphalia sustain demand for energy-efficient premium models with Ecodesstandby power compliance. EU Ecodesign directives and F-Gas Regulation constrain refrigerant-based cooling integrations and mandate specific efficiency disclosures. Berlin-Brandenburg industrial clusters host control board redesign facilities serving pan-European distribution.
Japan
Compact kitchen footprints in Tokyo and Osaka metro areas sustain premium demand for programmable units with delayed-start functionality. METI appliance efficiency standards and JIS certification requirements shape heating system architecture and firmware development priorities. Nagoya-based manufacturers specialize in horizontal kneading platforms for artisan bread enthusiasts.
China
Scale manufacturing in the Yangtze River Delta and Pearl River Delta dominates basic and mid-tier bread maker production for domestic and export markets. GB standards and MIIT energy efficiency regulations progressively tighten standby power limits and material compliance requirements. Shenzhen industrial parks concentrate connected functionality development for smart home ecosystem integration.
South Korea
Seoul Capital Area households prioritize multi-functional bread makers combining jam, yogurt, and cake programs through swappable paddles. MFDS food safety regulations and KC marking requirements govern food-contact materials and electrical component certification. Busan-Ulsan manufacturing corridors supply non-stick ceramic coatings and diamond-particle baking pan finishes.
Household Bread Machine Market Competitive Landscape
Global majors compete with regional champions across technology tiers and price positioning. Market structure consolidates around three to four dominant players in premium programmable segments while fragmenting across basic mechanical units. Strategic archetypes include vertically integrated electronics conglomerates, specialized small-appliance manufacturers, and contract assemblers serving private-label brands. Competitive moves center on multi-source component procurement strategies and firmware certification acceleration to compress launch windows.
Among Asia-Pacific-based manufacturers, Midea Group, Panasonic Corporation, and Zojirushi America Corporation exemplify distinct competitive positions. Midea Group represents scale-driven contract manufacturing and private-label supply. Panasonic Corporation occupies a position within vertically integrated electronics conglomerates with captive heating element production. Zojirushi America Corporation anchors the specialized premium tier focused on horizontal kneading technology and enthusiast-grade functionality.
| Leading Market Players |
|---|
| Midea Group |
| Panasonic Corporation |
| Xinbao Holding Group |
| Zojirushi America Corporation |
| Philips Domestic Appliances |
| Delonghi Group |
| Hamilton Beach Brands |
| Petrus Electrical Appliances |
| AUCMA Group |
| Others |
Supply & Pricing Matrix
Inverter heating technology migration from mechanical thermostats simultaneously compresses cost structures for precision temperature control and concentrates supplier power among East Asian heating element foundries. This dual restructuring forces manufacturers to absorb upfront R&D outlays while negotiating input costs in a tightening supplier market.
Pricing Analysis
Warranty and service bundling separates premium programmable units with multi-year coverage from economy-tier products sold as-is. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service depth. Cost compression in basic mechanical segments is intensifying because multi-function appliance substitution erodes dedicated bread machine volumes. First-time users exhibit highest price sensitivity; baking enthusiasts tolerate premium positioning for horizontal kneading and artisan program validation.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore anchor hub-and-spoke patterns serving European and Asia-Pacific retail networks. Manufacturing concentrates in China, Japan, and South Korea, drawing from specialized ceramic heating elements, microcontroller assemblies, and non-stick coating chemistries. Single-source vulnerability in East Asian heating element supply creates exposure to logistics disruption. Distribution runs through big-box retail, e-commerce platforms, and direct-to-consumer subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The household bread machine market functions as a cost-of-compliance story where EU Ecodesign directives and F-Gas Regulation create barrier-to-entry moats for players with certified efficient platforms and pan-European distribution infrastructure.
For Market Incumbents: Lock in multi-source procurement strategies for heating elements to mitigate East Asian supplier concentration risk. Accelerate firmware certification pipelines to compress UL and FDA validation windows. Vertical integration into control board manufacturing defends margin position against Ecodesign-mandated redesign cycles.
For New Entrants and Emerging Players: Capture gluten-free-capable multi-functional segments in underpenetrated German secondary household ownership. Target health-conscious consumer archetypes in United States Pacific Northwest metro areas with subscription ingredient bundling. Direct-to-consumer channel entry bypasses incumbent retail slotting advantages.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized premium-tier manufacturers with horizontal kneading technology and enthusiast-grade brand equity. Long-term viability hinges on smart home ecosystem integration capabilities and recurring revenue attachment rates. Watch connected functionality adoption curves as inflection indicator for platform consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Source Procurement Restructuring | Diversified heating element sourcing reduces exposure to Guangdong-Zhejiang supplier concentration and logistics volatility. |
| Firmware Certification Acceleration | Compressed UL and FDA validation timelines enable faster product launches ahead of Ecodesign compliance deadlines. |
| Smart Home Ecosystem Integration | Voice control and app-based recipe management differentiate mid-tier offerings in Austin and Denver connected kitchen markets. |
| Subscription Ingredient Partnership | Pre-portioned flour and yeast delivery creates recurring revenue attachment to hardware sales in United States and Germany. |
| Horizontal Kneading Platform Investment | Dual-paddle side-drive systems command loyalty among artisan bread enthusiasts in Japan and Germany premium segments. |
Research Methodology
Independent corroboration across appliance manufacturing executives, retail category buyers, regulatory compliance officers, and component suppliers underwrites the qualitative findings. Primary interviews with product managers at tier-one manufacturers, procurement leads at heating element foundries, and channel partners in Germany, Japan, and the United States combined with secondary validation from EU Ecodesign directive filings, UL certification databases, and customs trade records. Bottom-up unit shipment estimates triangulate against top-down market value reconstructions.
Rate-of-change decomposition across the projection horizon segments volume and value by product type, technology tier, application use-case, and customer archetype. CAGRs derive from regression analysis of historical shipment patterns, replacement cycle assumptions, and regulatory-driven upgrade demand. Industry-specific forecast inputs include EU standby power threshold compliance timelines and gluten-free recipe program adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to multi-function appliance substitution rates and heating element supply disruptions. Outputs reflect documented assumptions around regulatory implementation schedules and consumer willingness-to-pay for connected functionality. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Built-In Coffee Machine Market
Kitchen Appliances
Europe Small Kitchen Appliances Market
Kitchen Appliances
Global Single Serve Coffee Maker Market
Kitchen Appliances
Outdoor Commercial Grills Market
Kitchen Appliances
Induction Stove Market
Kitchen Appliances
Cake Pans Market
Kitchen Appliances
US Induction Cookware Market
Kitchen Appliances
China Kitchen Appliances Market
Kitchen Appliances
Household Coffee Machine Market
Kitchen Appliances
Smart Kettle Market
Kitchen Appliances
South Korea Electric Hobs Market
Kitchen Appliances
Mexico Kitchen Appliances Products Market
Kitchen Appliances
Tabletop Kitchen Products Market
Kitchen Appliances
Pressure Cooker Market
Kitchen Appliances
Smart Kitchen System Market
Kitchen Appliances
Self-Heating Butter Knife Market