
 Air Fryer Accessories Market | 2026-2036
Air Fryer Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Air Fryer Accessories Market Insights
Silicone is expanding its share in air fryer accessories as manufacturers phase out perfluorinated non-stick coatings under tightening chemical safety rules. Groupe SEB S.A. leverages its European manufacturing footprint to supply BPA-free silicone mats across multiple continents. Instant Brands, Inc. anchors its accessory strategy on compatibility bundling with its core appliance lines. SharkNinja Operating LLC differentiates through rapid-release silicone designs that reduce consumer cleaning friction.
Air fryer accessories comprise supplementary implements designed to extend the functional range of convection-based countertop cooking appliances, typically constructed from food-grade silicone, anodized aluminum, or stainless steel rated for sustained temperatures above 400°F. These items enable baking, grilling, and dehydrating operations that exceed the native capability of standard fryer baskets. Silicone mats and baking trays occupy the largest volume position due to their low replacement cost and universal fit across brands. Stainless steel racks and grill pans represent the fastest-expanding material tier as consumers seek durability alternatives to disposable-coated options. The commercial kitchen end-user segment sustains premium pricing for heavy-gauge aluminum and copper-core accessories that withstand continuous cycling.
The United States FDA maintains active oversight of food-contact substances under 21 CFR 177, directly influencing coating formulations permitted in accessories sold to American households. The European Union REACH regulation and ECHA restrictions on per- and polyfluoroalkyl substances are accelerating material transitions across supply chains serving European consumers. China's national food safety standards and GB material specifications shape export compliance requirements for accessories manufactured in Shenzhen and Ningbo production clusters. Stakeholders must monitor evolving chemical substance restrictions and certification reciprocity agreements between major manufacturing hubs and their destination markets.
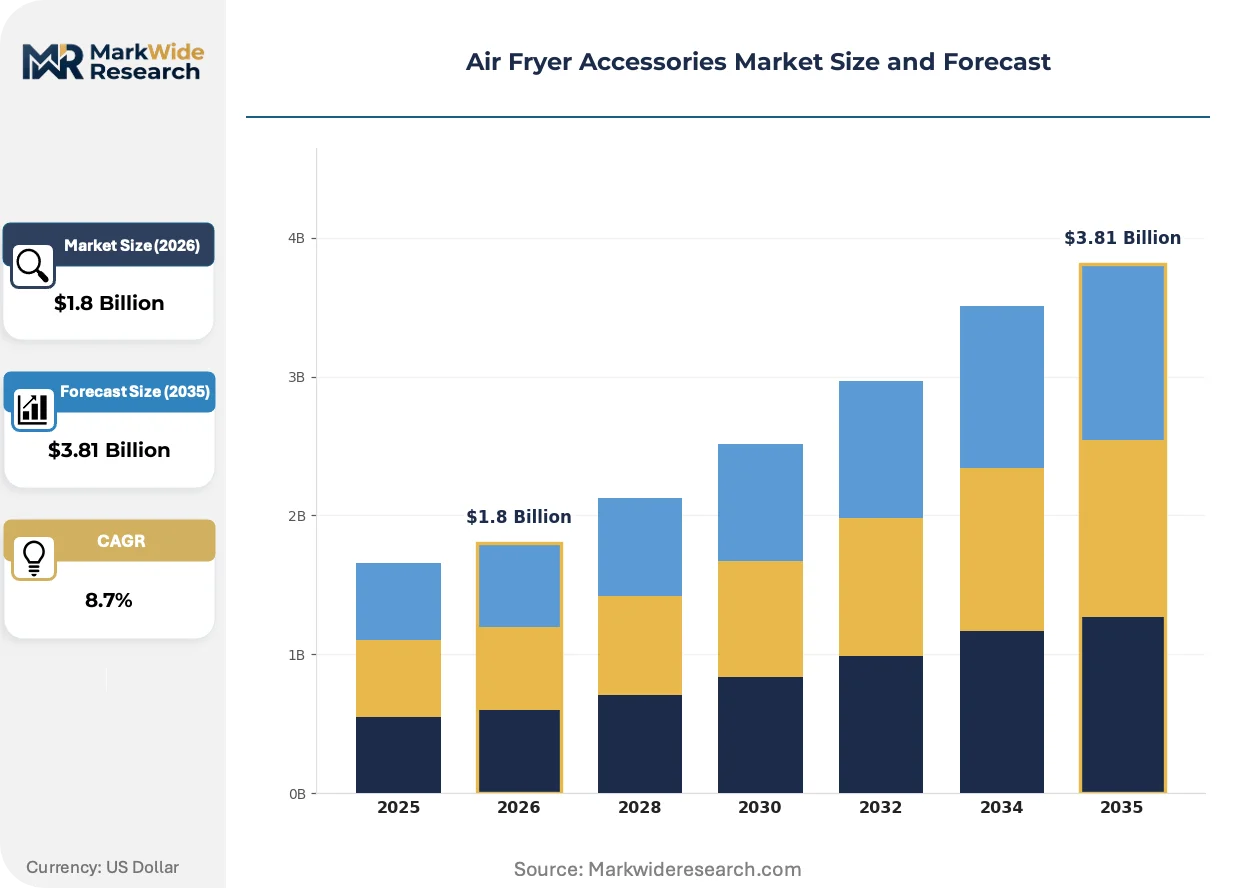
Market Dynamics
Material substitution away from perfluorinated coatings under REACH and FDA food-contact rules is compressing supplier margins while expanding silicone and ceramic alternatives across North American and European supply chains.
Growth Catalysts
- REACH PFAS restrictions:The European Union's accelerating bans on per- and polyfluoroalkyl substances are forcing coating reformulation, opening market share for compliant silicone and ceramic alternatives in accessories sold across Germany, France, and the Netherlands.
- Household accessory bundling:Appliance manufacturers are expanding attach rates of baking trays, grill pans, and silicone liners with new air fryer purchases, deepening per-unit revenue capture in the residential kitchen segment.
- Shenzhen-Ningbo manufacturing clusters:Concentrated production capacity in China's Pearl River Delta enables rapid tooling adjustments for material transitions, shortening product development cycles for export-bound accessory lines.
Market Restraints
- Silicone feedstock volatility:Specialized food-grade silicone rubber prices fluctuate with petrochemical inputs, squeezing margin stability for manufacturers dependent on continuous high-temperature formulations.
- Single-source coating dependency:Ceramic sol-gel alternatives remain concentrated among Japanese and German chemical suppliers, creating supply vulnerability during certification transitions.
- Interoperability limitations:Proprietary basket dimensions across Instant Brands, SharkNinja, and Groupe SEB appliance lines fragment accessory addressable markets, preventing universal fit standardization.
Strategic Opportunities
- India residential penetration:Air fryer ownership rates in Indian metropolitan households remain below fifteen percent, creating first-mover positioning for accessory bundling as appliance adoption accelerates in Mumbai and Bangalore.
- Commercial kitchen certification tiers:NSF International and ETL sanitation certifications for heavy-gauge aluminum accessories enable premium pricing in foodservice channels currently underserved by consumer-grade suppliers.
- Smart appliance integration:RFID-enabled baking trays that communicate cook times and temperatures to connected air fryers represent a convergence point between kitchen electronics and accessory hardware.
Industry Challenges
- Migration testing bottlenecks:FDA 21 CFR 177 compliance documentation for new coating chemistries requires eighteen-to-twenty-four month validation timelines, delaying product launches.
- Tooling amortization pressure:Stainless steel rack and grill pan production demands capital-intensive progressive die equipment, straining mid-tier manufacturers during material transition cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Fryer Accessories Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cooking Racks, Baking Trays, Silicone Mats, Grill Pans, Skewers, Drip Pans Material: Stainless Steel, Silicone, Aluminum, Non-stick Coating, Ceramic, Copper Application: Baking, Grilling, Roasting, Reheating, Dehydrating, Toasting End User: Households, Commercial Kitchens, Food Trucks, Catering Services, Restaurants, Cafés |
| Companies Covered | Versuni Holding B.V., SharkNinja Operating LLC, Instant Brands, Inc., Breville Group Limited, Groupe SEB S.A., Conair Corporation, VeSync Co., Ltd., Northland Aluminum Products, Inc., Hamilton Beach Brands Holding Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Fryer Accessories Market Trends and Innovations
Accessory design is fragmenting into modular, multi-functional components as consumers resist single-purpose kitchen implements. Three material and behavioral shifts are compressing traditional category boundaries.
Stackable stainless steel rack systems are modularizing interior air fryer configurations, enabling simultaneous multi-layer cooking that native baskets cannot accommodate. Premium residential buyers in the United States and Germany are adopting these systems at accelerating rates. The technology is modularizing accessory purchase decisions from replacement cycles to capability expansion events.
REACH Annex XVII restrictions on perfluorinated compounds are eliminating legacy non-stick coating options for European-bound accessories, forcing reformulation investments across Shenzhen export manufacturers. Industrial consequence includes accelerated R&D partnerships between Chinese molders and German ceramic coating specialists. Heavy-use segments including commercial kitchens are most affected, responding with premature replacement of compliant inventory ahead of enforcement deadlines.
Direct-to-consumer bundling is compressing traditional retail distribution for replacement accessories, with appliance OEMs capturing attach-rate economics previously lost to aftermarket suppliers. Amazon and dedicated kitchenware channels are losing share to manufacturer-direct subscription models for consumable liners and mats. This pattern is most visible in United States suburban households with established air fryer penetration and predictable replacement cadences.
Air Fryer Accessories Market Segmentation
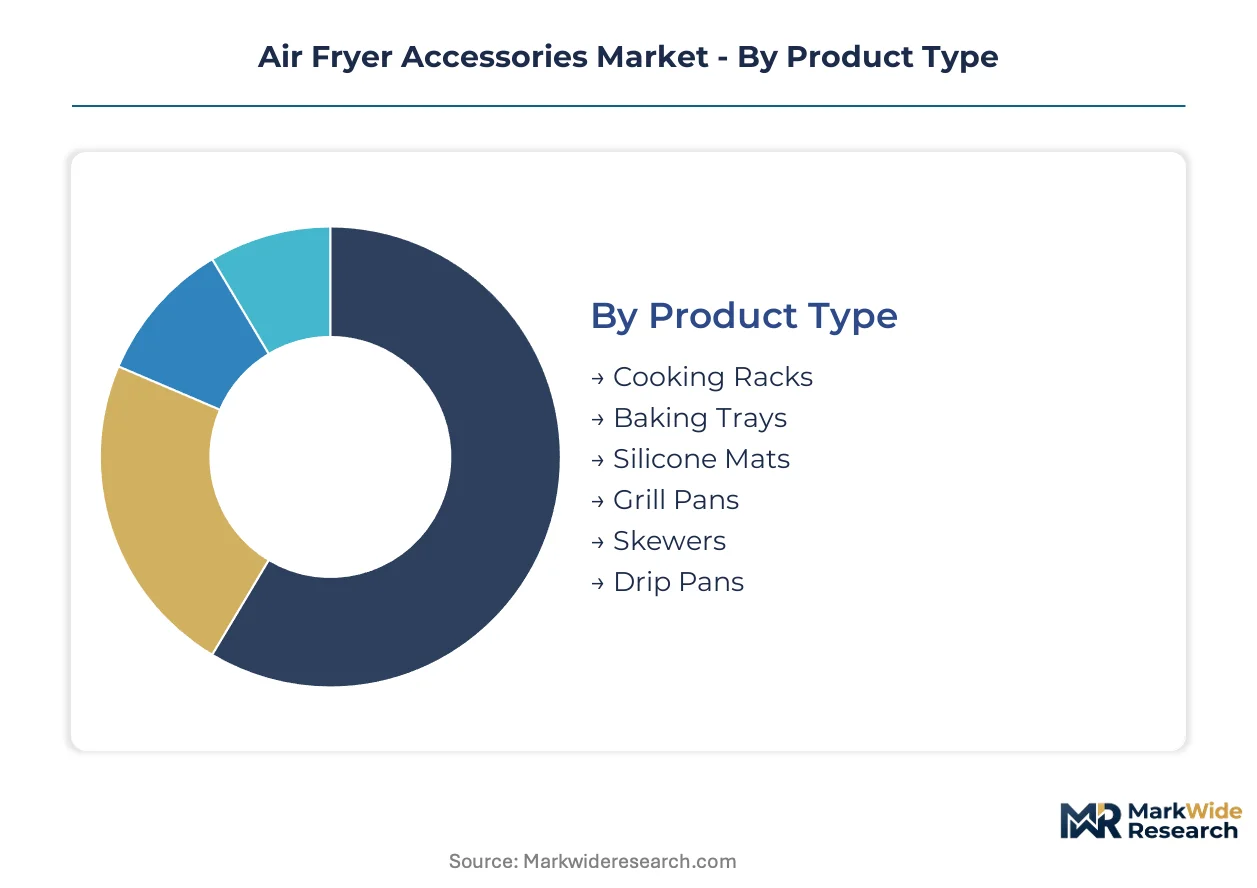
Accessory purchasing patterns in the air fryer market diverge sharply between replacement-driven consumables and capability-expanding durables. Material compliance costs and proprietary fit requirements reshape margin structures differently across each segment category.
Product Type:
Volume concentrates in low-cost consumables with rapid replacement cycles, while premium tiers capture margin through functional expansion.
- Silicone Mats:Food-grade silicone liners rated above 400°F dominate replacement purchases due to universal cross-brand compatibility and sub-$15 price points. Residential kitchens in the United States and Germany drive volume through quarterly replacement cadences tied to staining and odor accumulation.
- Baking Trays:Anodized aluminum and ceramic-coated rectangular platforms enable cake, bread, and pastry preparation beyond native fryer capabilities. Demand clusters among suburban United States households seeking to consolidate countertop appliances.
- Cooking Racks:Stainless steel multi-layer stacking systems for simultaneous food preparation.
- Grill Pans:Ridged cast-aluminum or steel surfaces for sear-mark generation and fat drainage.
- Skewers:Metal or bamboo implements for kebab and vegetable rotation cooking.
- Drip Pans:Disposable or reusable catchment trays for grease and crumb collection.
Today's leader: Silicone Mats. Tomorrow's challenger: Baking Trays.
Material:
Regulatory pressure on legacy coatings is accelerating supplier migration toward compliant alternatives with diverging cost structures.
- Silicone:Platinum-cured food-grade rubber formulations displace perfluorinated options under REACH Annex XVII and FDA 21 CFR 177 scrutiny. Shenzhen manufacturers are retooling extrusion lines to serve European and North American export requirements.
- Stainless Steel:304 and 430 grade alloys rated for sustained 450°F+ exposure gain share in durability-focused segments. German and United States premium buyers absorb 3-4x cost multiples versus coated alternatives for dishwasher-safe longevity.
- Aluminum:Lightweight anodized or bare metal substrates for heat-conductive tray applications.
- Non-stick Coating:Legacy PTFE and ceramic-sol-gel formulations facing phased elimination in EU-bound products.
- Ceramic:Sol-gel derived coatings from Japanese and German chemical suppliers as PFAS replacements.
- Copper:Heavy-gauge core materials for commercial kitchen thermal performance requirements.
Silicone commands current volume leadership. Stainless Steel is climbing the fastest as durability preferences harden among replacement-averse buyers.
Application:
Functional versatility determines attachment rates, with multi-use accessories outselling single-purpose implements by substantial margins.
- Baking:Cake, muffin, and bread preparation using trays and molds that convert air fryers into convection ovens. United States households with children show elevated attach rates for birthday cake and snack preparation.
- Grilling:High-heat searing and char-mark generation for proteins and vegetables. German consumers prioritize this function for year-round barbecue simulation despite seasonal climate constraints.
- Roasting:Whole poultry and large-cut meat preparation with rotation accessories.
- Reheating:Crisping and moisture restoration for leftover foods without microwave sogginess.
- Dehydrating:Low-temperature moisture removal for fruit, vegetable, and meat preservation.
- Toasting:Bread and pastry browning as toaster oven replacement functionality.
Current share leader: Baking. Steepest expansion trajectory: Dehydrating as preservation and snack-making trends converge.
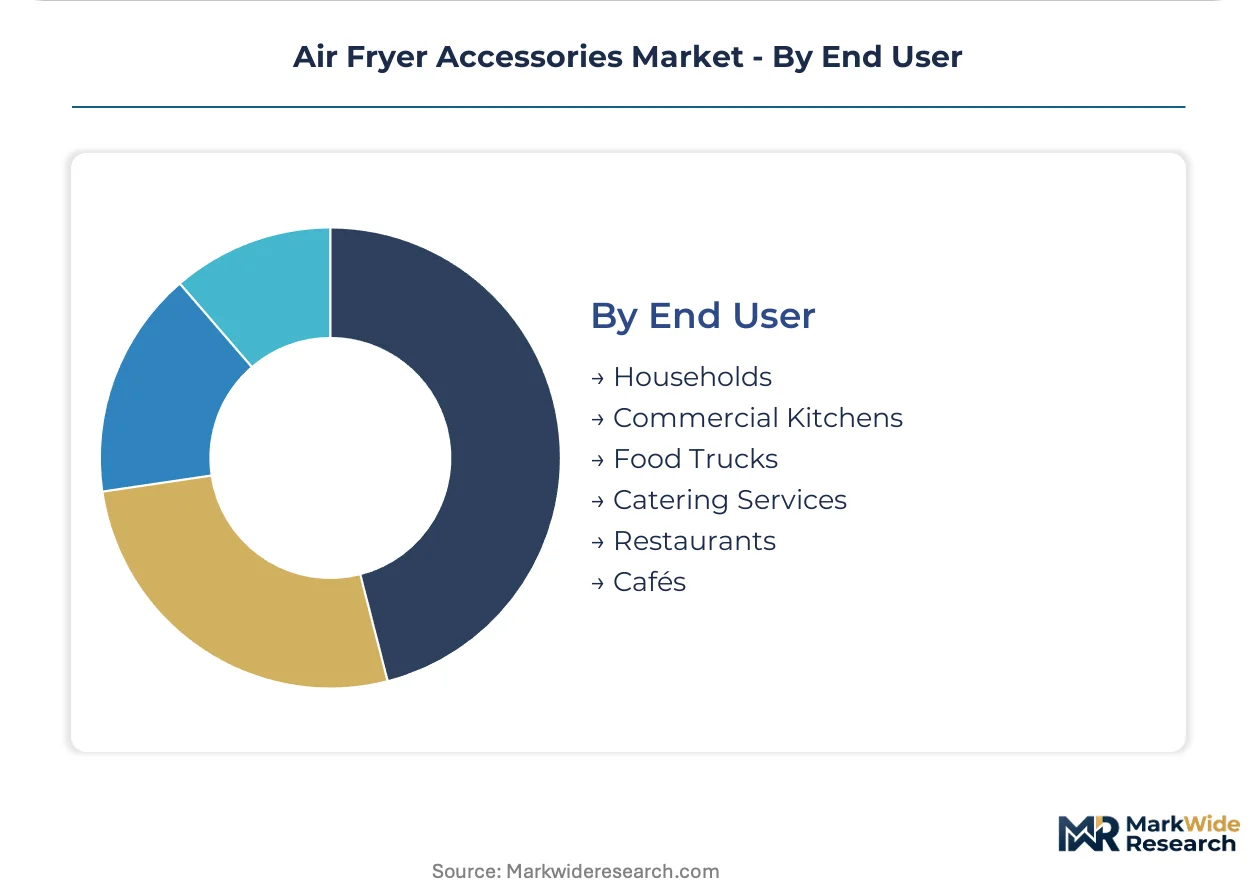
End User:
Price tolerance and certification requirements separate consumer-grade from commercial-grade procurement patterns.
- Households:Individual and family purchasers selecting accessories based on appliance brand compatibility and recipe aspiration. United States suburban markets show highest per-capita accessory accumulation as air fryer ownership exceeds 60% in middle-income demographics.
- Commercial Kitchens:Institutional foodservice operations requiring NSF International and ETL sanitation certifications for heavy-gauge aluminum and steel accessories. Premium pricing acceptance reflects durability requirements under continuous cycling conditions.
- Food Trucks:Mobile operators with space-constrained equipment needs and rapid turnover pressures.
- Catering Services:Event-based food preparation requiring portable, high-volume accessory sets.
- Restaurants:Full-service and quick-service establishments integrating air fryers into standardized menu execution.
- Cafés:Coffee-focused operations expanding into warmed pastry and light meal offerings.
Volume dominance sits with Households. Commercial Kitchens offer the most attractive margin expansion pathway for certified suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen-Ningbo manufacturing clusters anchor global air fryer accessory production, with export flows reaching residential kitchens across North America and Europe. Regulatory divergence between FDA and REACH frameworks fragments material compliance requirements across destination markets. Appliance ownership rates and replacement cycles for consumable accessories vary substantially by national income tier and kitchen culture.
United States
Suburban middle-income households drive silicone mat and baking tray replacement cycles, with air fryer penetration exceeding sixty percent in key demographics. FDA 21 CFR 177 food-contact substance rules directly shape coating formulations permitted in accessories sold to American consumers. Chicago and Dallas distribution hubs concentrate import logistics for Chinese-manufactured accessory lines serving mass-market retail channels.
Germany
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances accelerate material transitions toward ceramic and silicone alternatives in European-bound production. ECHA enforcement timelines compress supplier reformulation windows, creating premature replacement demand for compliant inventory. Bavarian industrial zones host German ceramic coating specialists partnering with Shenzhen molders on REACH-compliant export lines.
China
Domestic appliance adoption in Shanghai and Beijing metropolitan areas creates parallel demand for premium accessory bundling alongside export manufacturing. GB national food safety standards and SAMR oversight shape both domestic market requirements and export certification reciprocity protocols. Pearl River Delta production clusters enable rapid tooling adjustments for material transitions serving divergent regulatory destinations.
India
Metropolitan households in Mumbai and Bangalore show air fryer ownership rates below fifteen percent, creating first-mover positioning for accessory bundling as appliance adoption accelerates. FSSAI food safety standards and BIS certification requirements establish compliance baselines for import and domestic manufacture. Gujarat and Maharashtra industrial corridors attract component sourcing investments from established appliance brands seeking localized supply chains.
Japan
Compact kitchen configurations in Tokyo and Osaka metropolitan areas favor multi-functional accessories that consolidate countertop appliance roles. METI energy efficiency guidelines and JIS material standards influence accessory design specifications for domestic and regional export markets. Nagoya-area manufacturing maintains precision metalworking capabilities for stainless steel rack systems serving premium residential segments.
Air Fryer Accessories Market Competitive Landscape
Global majors compete with regional champions across material compliance and proprietary fit dimensions, producing a tiered structure where scale-driven appliance OEMs capture attach-rate economics while specialized fabricators serve aftermarket replacement cycles. Market concentration clusters around bundling relationships with core air fryer brands, fragmenting addressable markets by proprietary basket dimensions. Three archetypes dominate: integrated appliance-accessory bundlers, independent specialty manufacturers, and private-label contract producers. Competitive moves center on vertical integration into silicone compounding and strategic partnerships with Chinese molders for rapid tooling flexibility.
Among appliance-integrated bundlers, Groupe SEB S.A. and Instant Brands, Inc. exemplify the proprietary-fit strategy that locks accessory demand to core appliance lines. SharkNinja Operating LLC anchors the rapid-design-differentiation archetype through specialized silicone formulations. Versuni Holding B.V. occupies a position bridging European manufacturing heritage with Asian sourcing networks for cost-competitive material transitions.
| Leading Market Players |
|---|
| Versuni Holding B.V. |
| SharkNinja Operating LLC |
| Instant Brands, Inc. |
| Breville Group Limited |
| Groupe SEB S.A. |
| Conair Corporation |
| VeSync Co., Ltd. |
| Northland Aluminum Products, Inc. |
| Hamilton Beach Brands Holding Company |
| Others |
Pricing and Supply Chain Analysis
Appliance OEM bundling programs concentrate procurement power among Instant Brands, SharkNinja, and Groupe SEB, forcing aftermarket suppliers into transactional spot pricing for replacement silicone mats and baking trays. This buyer consolidation rewards direct-manufacturer subscription models while compressing margins for Amazon-dependent private-label sellers.
Pricing Analysis
Platinum-cured silicone feedstock pass-through dominates cost structures, with Shenzhen molders adjusting tray and liner quotations monthly against petrochemical indices. Three-tier pricing structure across premium, standard, and economy levels separates NSF-certified commercial-grade stainless steel from residential silicone and unbranded aluminum alternatives. Pricing pressure stems from REACH-driven coating reformulation costs absorbed by European-bound export lines. Household replacement buyers show highest price elasticity, while commercial kitchen procurement accepts 3-4x multiples for certified durability.
Supply Chain Analysis
Trans-Pacific container rates and Pearl River Delta port congestion directly impact landed costs for United States and German distribution hubs. Manufacturing concentrates in China, Vietnam, and India, with Shenzhen-Ningbo clusters anchoring food-grade silicone extrusion and anodized aluminum tray fabrication. Raw material sourcing draws from Japanese platinum catalyst suppliers, German ceramic sol-gel formulators, and Australian bauxite refiners. Single-source dependency on Japanese and German coating specialists creates vulnerability during FDA migration testing delays. Distribution runs through Chicago and Dallas logistics nodes for North American retail, Rotterdam for European REACH compliance staging.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The air fryer accessories market has entered late-cycle quality competition as residential buyers shift from entry-level consumables toward stainless steel durability and smart-enabled functionality. Premium specification demand now outpaces volume growth in established United States and German markets.
For Market Incumbents: Hedge coating transition risk by securing dual-source ceramic sol-gel supply from both Japanese and German chemical partners before REACH Annex XVII enforcement tightens. Backward integration into platinum-cured silicone compounding insulates margin compression from petrochemical volatility. Appliance OEMs must defend attach-rate economics against direct-to-consumer subscription challengers by embedding RFID-enabled trays into connected product ecosystems. For New Entrants and Emerging Players: Direct-to-Amazon storefronts offer the lowest friction entry path for REACH-compliant silicone mat specialists targeting United States suburban replacement cycles. White-space concentration sits with Indian metropolitan households below fifteen percent air fryer penetration, where accessory bundling with first-time appliance purchases captures lifetime value. Specialty stainless steel rack fabricators should pursue NSF International certification to access commercial kitchen premium pricing. For Investors and Strategic Acquirers: Appliance OEMs are the most active acquirer in this space, seeking captive accessory revenue streams to offset core hardware margin erosion. Long-term viability hinges on material compliance capabilities rather than brand equity alone, favoring targets with established FDA and REACH documentation pipelines. Watch for inflection when smart appliance integration shifts from novelty to standard feature expectation across premium tier launches.| Strategic Initiative | Industry Significance |
|---|---|
| Silicone Compounding Backward Integration | Captive supply of platinum-cured formulations insulates margin from petrochemical volatility. |
| NSF Commercial Certification Investment | Foodservice channel access unlocks premium pricing for heavy-gauge aluminum accessories. |
| Smart Tray RFID Development | Connected appliance integration shifts replacement purchases toward capability-expansion events. |
| India Localization Partnership | Gujarat and Maharashtra sourcing positions capture appliance adoption acceleration in Mumbai and Bangalore. |
| REACH-Compliant Coating R&D Alliance | German ceramic specialist partnerships secure European market access amid PFAS phase-out. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with appliance OEM product managers, Shenzhen contract manufacturer operations directors, United States retail category buyers, German ceramic coating R&D leads, and commercial kitchen procurement officers with secondary validation against FDA 21 CFR 177 filings, ECHA REACH restriction updates, Chinese customs export data, and Amazon bestseller trajectory databases. Bottom-up SKU-level demand modeling and top-down appliance penetration macro trends were cross-referenced for triangulation.
The forecast window anchored historical replacement cycle analysis against projected appliance install base expansion across the analysis window. Segmentation dimensions modeled include product type tier, material compliance grade, end-use application, and regional regulatory cluster. CAGRs were derived from material transition velocity curves and bundling attach-rate assumptions. Industry-specific inputs incorporated REACH enforcement timeline probability and silicone feedstock futures curve sensitivity.
The model assumes a particular technology adoption path; alternative pathways for smart appliance integration would alter the outlook if RFID-enabled tray communication fails to achieve standardization across Instant Brands, SharkNinja, and Groupe SEB ecosystems. Forecasts reflect assumptions about regulatory reciprocity between Chinese GB standards and FDA requirements. A model refresh is warranted upon material change in REACH Annex XVII enforcement acceleration or platinum group metal supply disruption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Smart Kitchen System Market
Kitchen Appliances
Electric Hobs Market
Kitchen Appliances
India Electric Vegetable Choppers Market
Kitchen Appliances
Smart Induction Cooktop Market
Kitchen Appliances
Hand-Held Mixer Market
Kitchen Appliances
Commercial Countertop Ranges Market
Kitchen Appliances
France Kitchen Appliances Market
Kitchen Appliances
Global Stainless Woks Market
Kitchen Appliances
India Kitchen Appliances Market
Kitchen Appliances
Europe Kitchen Appliances Market
Kitchen Appliances
Digital BBQ Tongs and Thermometer Market
Kitchen Appliances
Residential Induction Cooktops Market
Kitchen Appliances
Portable Outdoor Pizza Oven Market
Kitchen Appliances
Russia Household Electric Grill Market
Kitchen Appliances
Electric Lunch Box Market
Kitchen Appliances
Global Single Serve Coffee Maker Market