
 Brazil Kitchen Appliances Market | 2026-2036
Brazil Kitchen Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Kitchen Appliances Market Outlook
Urban residential demand is consolidating around connected cooking and refrigeration ecosystems. Whirlpool Corporation leverages its Brazilian manufacturing footprint to sustain cost-competitive refrigerator output for the mid-market. Mondial Eletrodomesticos anchors its position through deep penetration of budget-tier segments in the Northeast and Central-West regions. Electrolux AB differentiates via energy-efficient platform designs that align with INMETRO certification requirements.
Brazil kitchen appliances comprise electrically powered equipment designed for food storage, preparation, cooking, and cleaning in domestic and commercial environments, typically operating at 127V or 220V across Brazil's bifurcated electrical grid and subject to tropical climate durability standards for humidity and temperature cycling. Refrigerators command the largest product-type position due to universal household necessity and replacement-driven demand, while the premium price tier captures disproportionate margin pools as consumers trade up to inverter-compressor and smart-interface models. The residential customer type remains the volume foundation, though hospitality-sector procurement is accelerating as Brazil's food-service industry expands.
ANVISA governs material safety in food-contact appliance surfaces, while INMETRO administers mandatory energy-efficiency labeling and conformity assessment programs that determine market access for imported and domestically manufactured units. The National Institute of Metrology, Quality and Technology (INMETRO) also updates testing protocols periodically, forcing manufacturers to recalibrate product lines to maintain certification validity. Stakeholders must monitor impending efficiency-tier escalations and local-content requirements under Brazil's industrial policy framework to anticipate cost-structure shifts and sourcing decisions.
Market Dynamics
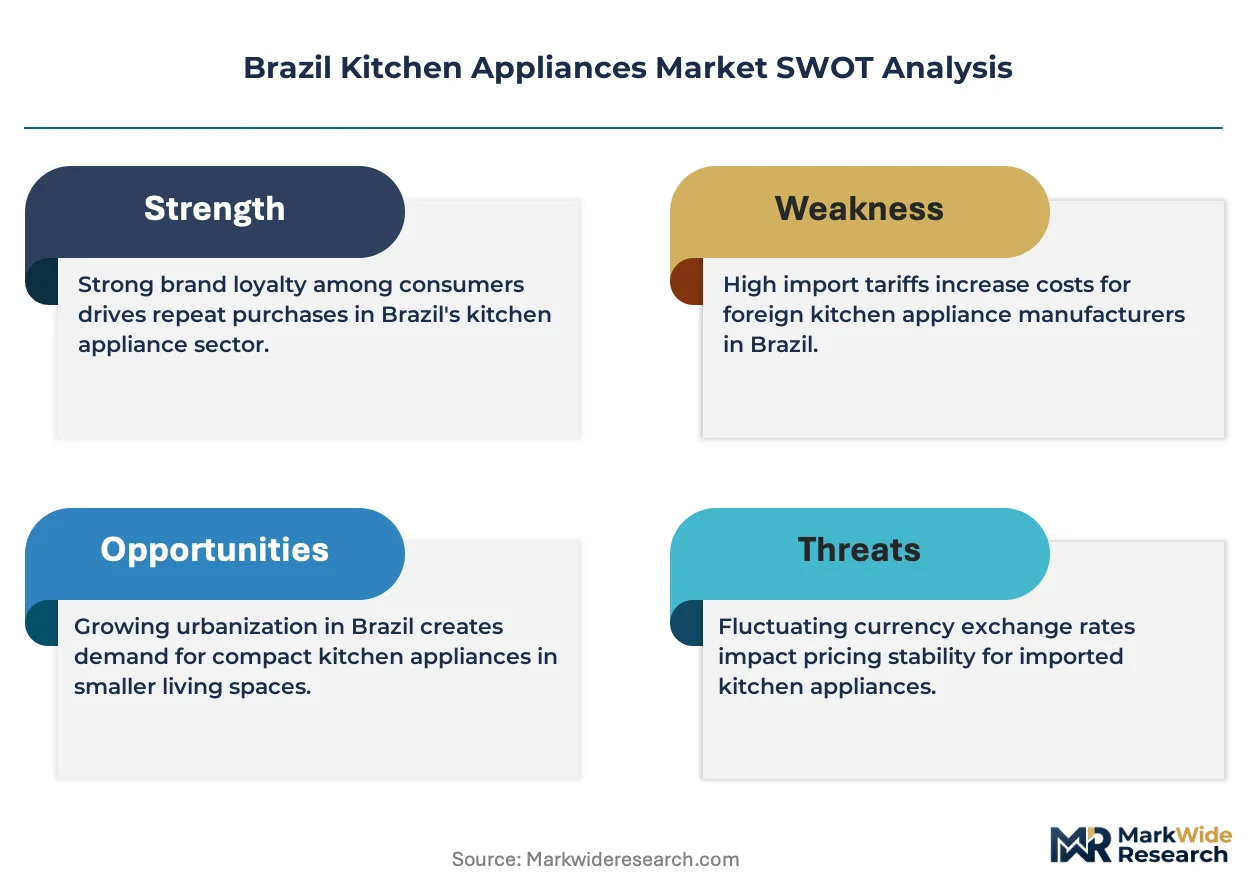
INMETRO's escalating energy-efficiency tiers are compressing manufacturer margins while forcing rapid product-line turnover across Brazil's appliance sector. The mandatory labeling program's 2024 recalibration eliminated entry-level compressor technologies from certified portfolios overnight.
Growth Catalysts
- INMETRO Labeling Escalation:Tighter efficiency bands under Portaria 553/2021 amendments are accelerating replacement demand as older stock loses retail authorization. Retailers face clearance pressure on non-compliant inventory.
- São Paulo Metropolitan Corridor:Urban density above ten thousand inhabitants per square kilometer concentrates replacement cycles and first-time purchases within a single logistics radius.
- Inverter-Compressor Technology:Variable-speed refrigeration systems are capturing premium-tier preference as electricity tariffs in the Southeast justify operational savings against higher upfront cost.
Market Restraints
- Copper-Alloy Input Volatility:Compressor and motor winding costs fluctuate with London Metal Exchange pricing, compressing margin predictability for domestic manufacturers.
- Southeast Manufacturing Concentration:Over seventy percent of certified production capacity clusters in São Paulo and Minas Gerais states, creating hurricane and logistics disruption exposure.
- 127V/220V Grid Bifurcation:Brazil's dual-voltage infrastructure forces SKU duplication, inflating inventory carrying costs and complicating national distribution planning.
Strategic Opportunities
- Northeast Regional Underpenetration:Pernambuco and Ceará states exhibit refrigerator ownership gaps against Southeast benchmarks, offering volume expansion for cost-optimized product lines.
- Food-Service Procurement Acceleration:Brazil's expanding hospitality sector is commercializing demand for high-cycle durability equipment with rapid-payback energy profiles.
- Connected-Appliance Convergence:Wi-Fi-enabled refrigeration and cooking ecosystems are creating service-revenue attachments and data-monetization pathways beyond hardware margins.
Industry Challenges
- INMETRO Recertification Timelines:Updated testing protocols require six-to-nine-month laboratory queues, delaying new product launches and compressing effective sales windows.
- Legacy 127V Infrastructure Integration:Smart-appliance power-management systems must accommodate voltage stabilizer dependencies in older residential wiring, complicating firmware architecture.
- Refrigerant Transition Complexity:The shift from R-134a to R-600a isobutane systems demands technician retraining and service network retooling across Brazil's dispersed maintenance infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Kitchen Appliances Market |
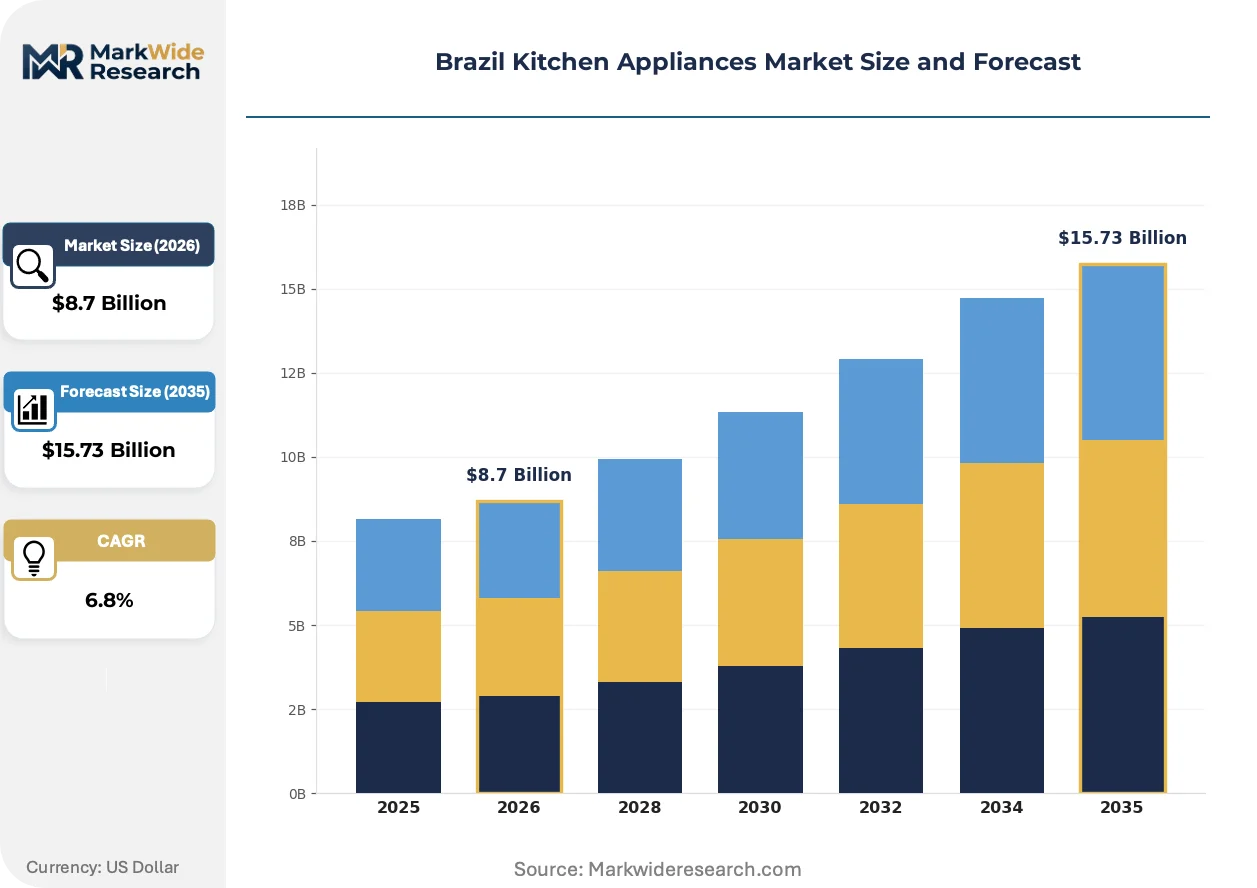
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Ovens, Microwaves, Dishwashers Price Tier: Premium, Mid-range, Budget, Luxury Customer Type: Residential, Commercial, Hospitality, Retail Distribution Channel: Online, Offline, Wholesalers, Retail Chains |
| Companies Covered | LG Electronics Inc., Midea Group, Whirlpool Corporation, Mondial Eletrodomesticos, Tramontina, Electrolux AB, Groupe SEB, Britânia Eletrodomésticos, Samsung Electronics Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Kitchen Appliances Market Strategic Shifts
Domestic appliance ecosystems are converging around predictive maintenance interfaces and energy-optimization algorithms. Brazilian manufacturers face pressure to integrate these capabilities while maintaining cost competitiveness against imported alternatives.
Inverter-driven compressor technology is expanding into mid-market refrigerator segments previously dominated by fixed-speed units. São Paulo's upper-middle households are adopting variable-speed systems at accelerated replacement cycles. This diffusion is compressing the premium-tier price umbrella and forcing standard-tier product repositioning.
ANVISA's updated food-contact surface regulations are mandating stainless-steel grade migrations in interior liner materials. Manufacturers must recalibrate stamping and welding processes to maintain certification validity. The commercial refrigeration segment faces the steepest compliance cost absorption as hygiene standards tighten.
Digital retail channels are capturing an expanding share of replacement-cycle purchases from traditional brick-and-mortar appliance specialists. São Paulo and Rio de Janeiro metropolitan buyers are completing high-consideration transactions through platform-enabled financing and installation scheduling. This disintermediation is compressing distributor margins and forcing brand-direct logistics investments.
Brazil Kitchen Appliances Market Segmentation
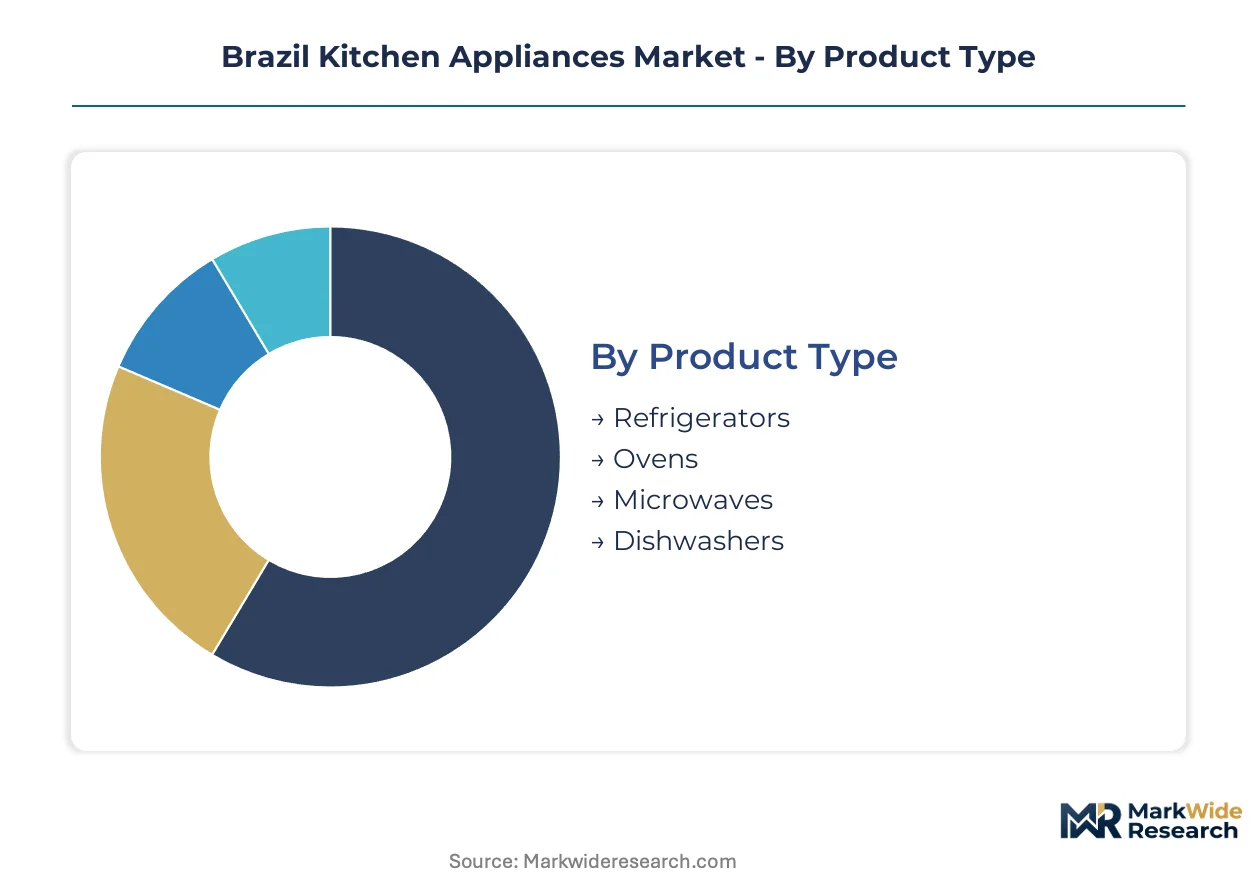
Brazil's kitchen appliance segmentation reflects divergent replacement rhythms across income tiers and voltage zones. Manufacturers calibrate SKU portfolios to São Paulo's inverter-compressor upgrades while defending volume in 127V legacy markets.
Product Type:
Replacement cycles vary dramatically by appliance category, with refrigeration commanding the shortest effective lifespan due to compressor duty stress under tropical conditions.
- Refrigerators:Inverter-compressor systems with variable-speed drives dominate Southeast replacement demand as electricity tariffs justify operational savings. São Paulo's upper-middle households are compressing replacement intervals to capture INMETRO A-grade efficiency ratings.
- Ovens:Built-in electric convection units are displacing freestanding gas alternatives in new São Paulo residential construction. Developers specify 220V pre-wiring to accommodate higher-wattage European-format designs.
- Microwaves:Solo-function countertop units retain volume leadership in Northeast budget-tier penetration.
- Dishwashers:Compact under-counter designs are gaining traction in Rio de Janeiro's renovated apartment stock where kitchen square footage constraints favor integrated solutions.
Volume placements concentrate in refrigerators; the faster expansion belongs to ovens.
Price Tier:
Cost stratification maps directly to voltage infrastructure maturity and regional income distribution across Brazil's bifurcated grid.
- Premium:Wi-Fi-enabled refrigeration ecosystems with predictive maintenance interfaces capture São Paulo's technology-forward households. These units integrate with home automation platforms to optimize compressor cycling during peak tariff windows.
- Mid-range:Inverter-compressor refrigerators without connectivity features anchor replacement demand in Minas Gerais and Paraná states. The segment balances upfront affordability against validated electricity savings.
- Budget:Fixed-speed compressor units dominate Northeast and Central-West first-time ownership curves.
- Luxury:Custom-panel refrigeration and professional-grade cooking suites serve Rio de Janeiro's high-rise penthouse renovations.
Mid-range shipments dominate unit volume; luxury is climbing the fastest as architect-specified kitchen renovations accelerate.
Customer Type:
End-use segmentation reveals divergent durability requirements and procurement decision structures across Brazil's appliance value chain.
- Residential:Replacement-driven demand concentrates in São Paulo's metropolitan corridor where household formation and income stability support accelerated upgrade cycles. INMETRO labeling mandates are forcing simultaneous fleet turnover across income tiers.
- Commercial:Food-service operators in Belo Horizonte and Curitiba are specifying high-cycle durability equipment with rapid-payback energy profiles. Procurement decisions prioritize total cost of ownership over upfront capital expenditure.
- Hospitality:Boutique hotel renovations in Rio de Janeiro's Zona Sul are driving demand for whisper-compressor refrigeration and European-format cooking suites.
- Retail:Appliance specialists and big-box formats maintain inventory exposure to clearance pressure from INMETRO recertification deadlines.
Residential channels absorb the highest unit placements; hospitality procurement is gaining share fastest as Brazil's tourism infrastructure expands.
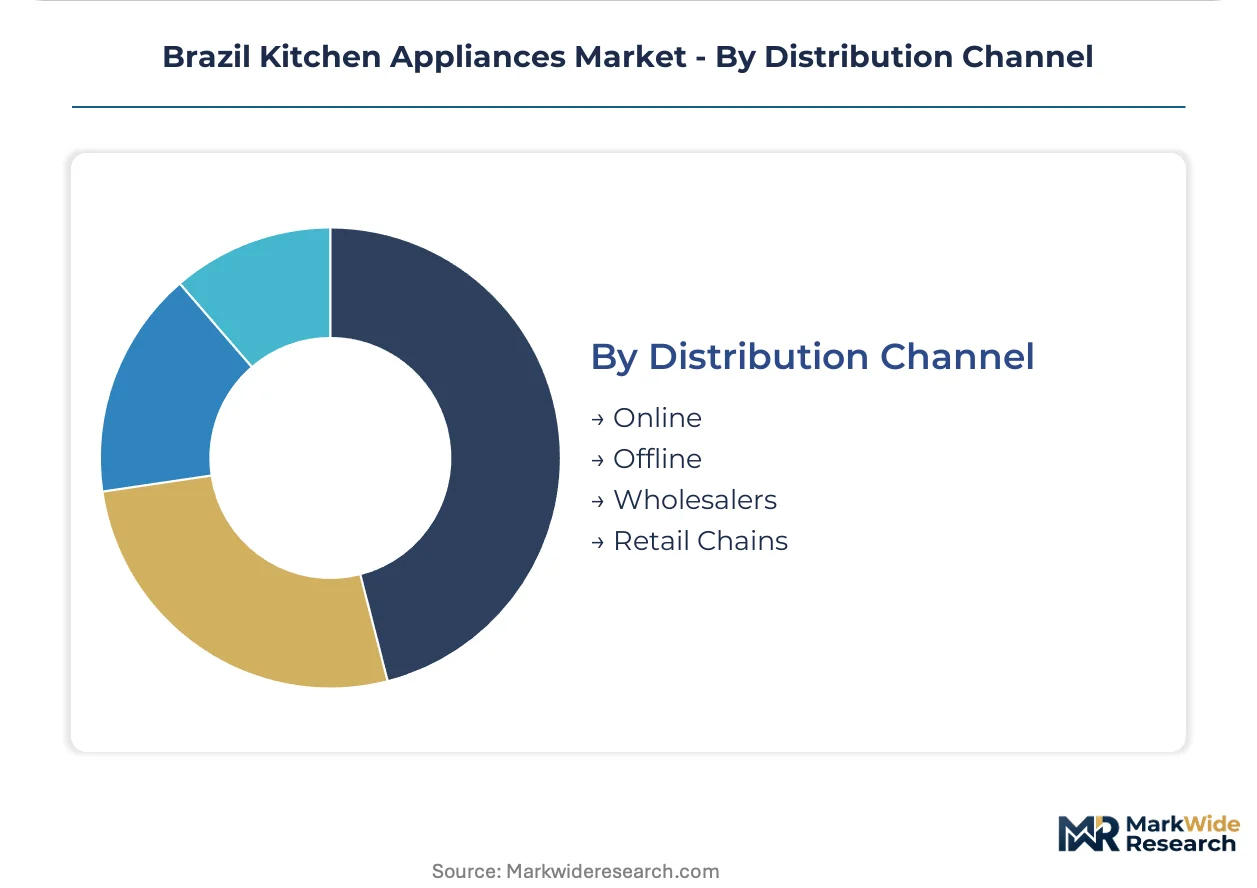
Distribution Channel:
Channel structure reflects last-mile complexity imposed by voltage bifurcation and installation service requirements.
- Online:Platform-enabled financing and installation scheduling are capturing São Paulo and Rio de Janeiro replacement cycles from traditional specialists. Digital channels excel at 220V SKU concentration where buyer sophistication reduces pre-sales consultation needs.
- Offline:Brick-and-mortar appliance specialists retain dominance in 127V markets where voltage stabilizer bundling and installation complexity demand face-to-face consultation.
- Wholesalers:Project channel distributors serve São Paulo's residential developers with volume pricing on uniform SKU specifications.
- Retail Chains:National big-box formats carry inventory risk from INMETRO recertification timelines and clearance pressure on non-compliant stock.
Offline retains the deepest volume footprint; online channels are expanding most quickly in Southeast metropolitan corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manaus Free Trade Zone tax incentives concentrate refrigerator and compressor manufacturing in Amazonas state, drawing assembly operations away from traditional Southeast industrial corridors.
São Paulo
São Paulo metropolitan households drive inverter-compressor replacement cycles as electricity tariffs justify operational savings against upfront premiums. INMETRO's Portaria 553/2021 amendments force simultaneous fleet turnover across income tiers. The ABC Paulista industrial belt hosts Whirlpool's Brazilian manufacturing footprint serving mid-market refrigerator demand.
Minas Gerais
Minas Gerais anchors Southeast production capacity with over seventy percent of certified manufacturing clustering alongside São Paulo state. The state's appliance assembly plants face hurricane and logistics disruption exposure from concentrated infrastructure. Belo Horizonte's food-service operators specify high-cycle durability equipment with rapid-payback energy profiles.
Rio de Janeiro
Rio de Janeiro's renovated apartment stock favors compact under-counter dishwasher designs where kitchen square footage constraints drive integrated solutions. ANVISA's updated food-contact surface regulations mandate stainless-steel grade migrations in interior liner materials. Zona Sul boutique hotel renovations demand whisper-compressor refrigeration and European-format cooking suites.
Rio Grande do Sul
Rio Grande do Sul's manufacturing base supplies fixed-speed compressor units for Northeast and Central-West first-time ownership curves. The state's industrial parks face copper-alloy input volatility from London Metal Exchange pricing fluctuations. Porto Alegre's distributor networks manage 127V SKU duplication for legacy grid infrastructure.
Bahia
Bahia exhibits refrigerator ownership gaps against Southeast benchmarks, offering volume expansion for cost-optimized product lines targeting underpenetrated Northeast demand. The state's retail channels retain brick-and-mortar dominance where voltage stabilizer bundling demands face-to-face consultation. Salvador's appliance specialists manage clearance pressure from INMETRO recertification deadlines.
Brazil Kitchen Appliances Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with consolidated multinational portfolios dominating premium-tier refrigeration while domestic fabricators defend volume in budget-tier penetration. The competitive structure tiers across three strategic archetypes: global appliance conglomerates with Brazilian manufacturing footprints, regional specialists anchored in Southeast industrial corridors, and domestic budget-tier producers with deep Northeast distribution. Capacity expansion and portfolio diversification represent the dominant competitive moves as players recalibrate for INMETRO efficiency escalations.
Within the global conglomerate tier, Whirlpool Corporation and Electrolux AB exemplify multinational positioning through Brazilian production scale. Midea Group represents Chinese-origin manufacturing diversification into Latin American appliance markets. LG Electronics Inc. and Samsung Electronics Co., Ltd. anchor the Korean-origin electronics conglomerate archetype competing on connected-appliance ecosystems.
| Leading Market Players |
|---|
| LG Electronics Inc. |
| Midea Group |
| Whirlpool Corporation |
| Mondial Eletrodomesticos |
| Tramontina |
| Electrolux AB |
| Groupe SEB |
| Britânia Eletrodomésticos |
| Samsung Electronics Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Compressor technician density in São Paulo's ABC Paulista industrial belt compresses labor-cost differentials between premium inverter systems and fixed-speed budget units, widening pricing-tier spreads as manufacturers pass skilled-wage premiums through to Southeast metropolitan buyers while defending margin in Northeast legacy markets.
Pricing Analysis
Lead-time-driven pricing angles dominate procurement negotiations, with São Paulo developers paying premiums for six-week delivery windows on INMETRO A-grade refrigerator fleets while Northeast distributors clear spot inventory at discounted rates. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and voltage infrastructure maturity. Price differentiation stems from INMETRO efficiency tier and after-sales service bundling. Cost compression in budget fixed-speed tiers is intensifying because copper-alloy input volatility feeds through compressor winding costs. Northeast first-time buyers exhibit highest price sensitivity; São Paulo's upper-middle replacement cycles show lowest.
Supply Chain Analysis
Freight cost inflation from Southeast manufacturing clusters to Northeast distribution centers absorbs margin on budget-tier shipments, forcing load consolidation and extended payment terms. Supply concentrates in Brazil's São Paulo and Minas Gerais states, with component sourcing from China and Mexico for electronic control systems. Raw material dependencies span copper-alloy compressor windings, cold-rolled steel for cabinet stampings, and ABS resin for interior liners. Single-source vulnerability sits with inverter-drive controller imports. Distribution runs through appliance specialists in 127V legacy markets and platform-enabled direct channels in 220V metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's kitchen appliance market reads as supply-constrained: INMETRO recertification laboratory queues stretching six-to-nine months prop pricing power for certified inventory holders.
For Market Incumbents: Cement dominance in São Paulo's inverter-compressor replacement corridor through captive technician training programs that lock in service-network loyalty. Deepen backward integration into compressor controller assembly to offset single-source import exposure. Electrolux AB and Whirlpool Corporation's Brazilian footprints demonstrate scale advantages that emerging entrants cannot replicate without certification backlog clearance. For New Entrants and Emerging Players: Begin with Pernambuco and Ceará refrigerator ownership gaps, where Southeast penetration benchmarks suggest volume expansion for cost-optimized fixed-speed lines. Target hospitality-sector procurement in Belo Horizonte and Curitiba, where food-service operators prioritize total cost of ownership over brand heritage. Deploy platform-enabled financing partnerships to bypass brick-and-mortar specialist gatekeeping in 127V legacy markets. For Investors and Strategic Acquirers: Re-rating potential sits with domestic fabricators possessing deep Northeast distribution and INMETRO certification pipeline clearance given efficiency-tier escalation catalysts. Long-term viability over a multi-year horizon favors regional specialists with captive production in Minas Gerais industrial corridors. Monitor INMETRO Portaria amendment timing as inflection indicator for inventory valuation swings.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Manufacturing | Captive production of variable-speed drives reduces exposure to London Metal Exchange copper volatility and import lead times. |
| INMETRO Certification Pipeline Investment | Laboratory queue priority access accelerates product launch windows ahead of regulatory tier escalations. |
| Northeast Distribution Network Expansion | Pernambuco and Ceará penetration captures first-time ownership curves outside Southeast replacement saturation. |
| Hospitality-Sector Specification Programs | Belo Horizonte and Curitiba food-service procurement prioritizes rapid-payback energy profiles over upfront capital. |
| Connected-Appliance Ecosystem Development | Wi-Fi-enabled refrigeration with predictive maintenance interfaces creates service-revenue attachments beyond hardware margins. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with appliance manufacturing plant managers, INMETRO certification laboratory directors, retail category buyers, and aftermarket service network heads. Secondary validation drew from ANVISA food-contact surface regulations, INMETRO Portaria amendments, and Brazilian customs import records for compressor components. Bottom-up unit shipment modeling triangulated against top-down household penetration benchmarks.
Data-stream reconciliation across manufacturer shipment disclosures, retail audit channels, and voltage-zone grid infrastructure maps informed the analytical framework. Segmentation dimensions spanned product type, price tier, customer type, and distribution channel across the analysis window. CAGRs derived from replacement cycle compression rates and income-tier penetration curves. Industry-specific forecast inputs incorporated electricity tariff trajectories in Southeast states and INMETRO efficiency-tier amendment schedules.
Underlying measurement precision varies by segment; São Paulo metropolitan replacement data carries tighter precision than dispersed Northeast first-time ownership estimates. Forecasts reflect assumptions regarding certification timeline adherence and copper-alloy price stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Global Baking Tools Market
Kitchen Appliances
Cookware Accessories Market
Kitchen Appliances
United States Small Kitchen Appliances Market
Kitchen Appliances
Hand-Held Mixer Market
Kitchen Appliances
Cotton Candy Maker Market
Kitchen Appliances
Electric Grill Market
Kitchen Appliances
Garlic Press Market
Kitchen Appliances
China Mixer Grinder Market
Kitchen Appliances
Australia Kitchen Appliances Market
Kitchen Appliances
Colombia Kitchen Appliances Market
Kitchen Appliances
Europe Kitchen Appliances Market
Kitchen Appliances
Europe Household Refrigerator Market
Kitchen Appliances
Built-In Kitchen Appliances Market
Kitchen Appliances
Electric Lunch Box Market
Kitchen Appliances
Air Fryer Accessories Market
Kitchen Appliances
Tabletop Kitchen Products Market