
 Capsule Coffee Machines Market | 2026-2036
Capsule Coffee Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Capsule Coffee Machines Market Analysis
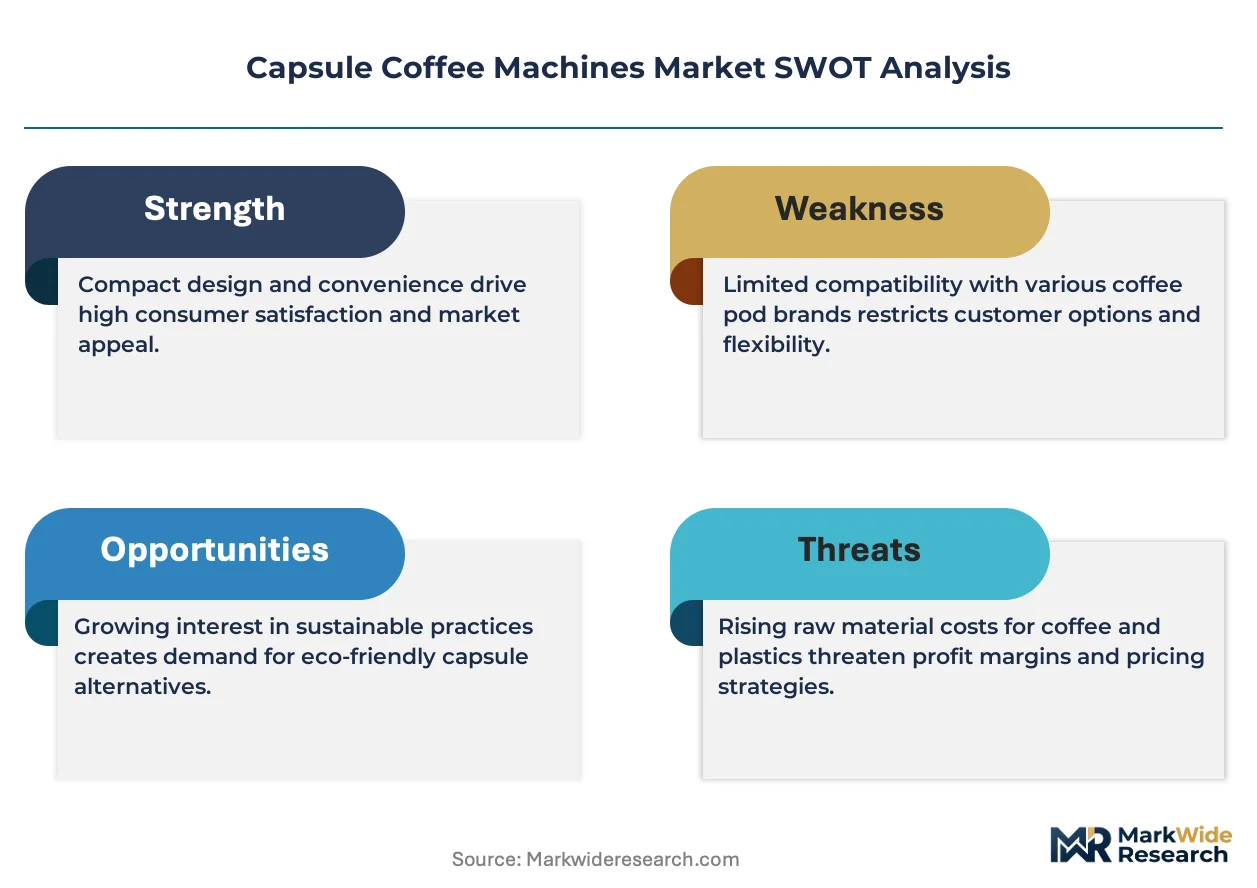
Subscription leasing and asset-light fleet models are reshaping competitive entry in capsule coffee machines, allowing hospitality groups and office service providers to deploy equipment without capital outlay. Nespresso leverages its direct-to-consumer channel control to anchor premium placement in European hotels. Keurig Dr Pepper sustains North American dominance through brewer placement density in commercial breakrooms. Breville differentiates via R&D intensity in manual and semi-automatic formats for enthusiast residential buyers.
A capsule coffee machine is an electric brewing appliance that punctures pre-portioned, sealed pods containing ground coffee, then forces pressurized heated water through the capsule at bars of pressure to extract a single serving. The device serves both consumer convenience and commercial consistency by eliminating grinding, dosing, and tamping variables. Single-serve formats lead residential volume due to space constraints and pod variety availability, while fully automatic systems command commercial margins through labor reduction and throughput speed. Cold brew technology represents the fastest-expanding segment as younger demographics shift toward chilled, lower-acidity preparations.
The EU Ecodesign Directive and REACH framework mandate energy efficiency thresholds and material recyclability for electrical appliances sold in Europe, compelling redesign of heating elements and pod composition. The US EPA and FDA jointly influence market access through appliance energy standards and food-contact material safety requirements for plastic and aluminum capsules. Stakeholders must monitor evolving extended producer responsibility laws in Germany and France, where deposit-return schemes for aluminum pods are restructuring cost allocation between manufacturers and consumers.
Market Dynamics
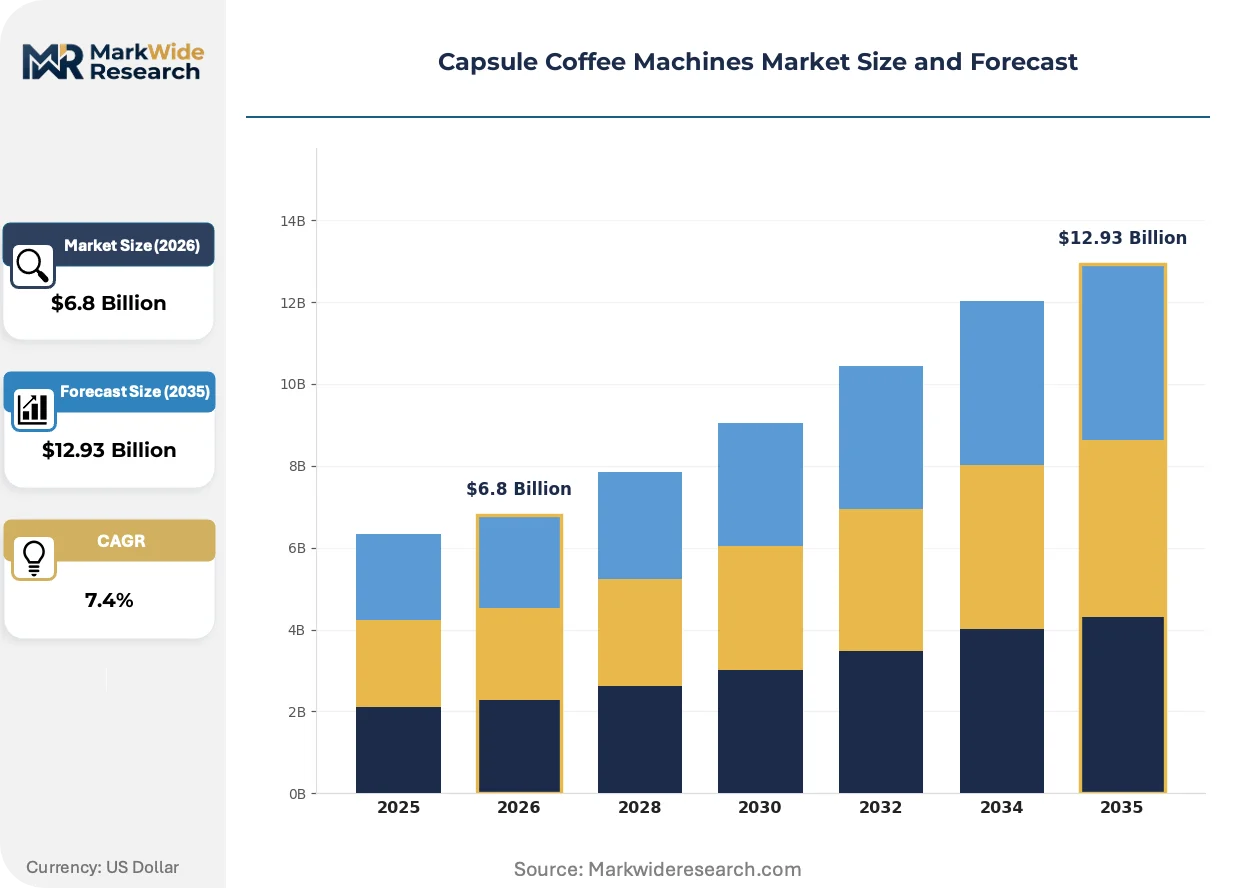
The EU Ecodesign Directive is forcing heating-element redesign across European manufacturers while hospitality labor costs accelerate fleet-model adoption. Subscription-based equipment deployment is compressing traditional capital-sales cycles and redistributing margin capture toward consumables.
Growth Catalysts
- REACH material mandates:Aluminum pod recyclability requirements in Germany are creating closed-loop infrastructure that reduces raw material input costs for compliant manufacturers.
- Hospitality labor inflation:European hotel chains are automating in-room beverage service to offset wage pressure, expanding commercial machine placement.
- Cold brew extraction systems:Chilled-brewing technology is capturing younger residential demographics seeking lower-acidity preparations.
Market Restraints
- Aluminum price volatility:Pod shell material costs fluctuate with energy-intensive smelting economics, compressing margin on economy-tier formats.
- Patent-thicket concentration:Brewing-system IP held by incumbent manufacturers blocks independent pod compatibility in key markets.
- Extended producer responsibility laws:France and Germany deposit-return schemes shift end-of-life costs onto producers, raising operational complexity.
Strategic Opportunities
- Office service provider channel:Asset-light leasing to facility management companies bypasses capital-budget constraints in commercial segments.
- Compostable polymer R&D:Plant-based barrier films meeting EN 13432 industrial-composting standards open premium positioning.
- Swiss hospitality density:Alpine hotel chains maintain above-average per-room coffee investment, supporting high-margin machine placement.
Industry Challenges
- Cross-border compliance talent:Interpreting divergent EPR implementations across German Länder and French regions requires specialized regulatory staffing.
- Legacy brewer fleet integration:New pod formats must maintain backward compatibility with installed base machines, constraining design freedom.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Capsule Coffee Machines Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Serve, Multi-Serve, Manual, Fully Automatic Technology: Espresso, Drip Brewing, Cold Brew, Pump Technology End User: Residential, Commercial, Office, Hospitality Distribution Channel: Online, Specialty Stores, Supermarkets, Wholesale |
| Companies Covered | De'Longhi, Illycaffe, Nespresso, Breville, Dualit, Keurig Dr Pepper, Philips, Ningbo AAA Group Electric Appliance, Lavazza, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Capsule Coffee Machines Market Emerging Trajectories
Heating technology and pod materials are undergoing simultaneous transformation as regulatory pressure intersects with operational cost reduction. Three distinct vectors are reshaping competitive positioning.
Induction heating elements are replacing traditional thermoblock systems in premium residential units. German and Swiss manufacturers are accelerating this transition to meet EU Ecodesign wattage thresholds. The technology is migrating from enthusiast-tier machines toward mid-market hospitality equipment, compressing the efficiency gap between segments.
REACH substance restrictions are compelling reformulation of pod sealing adhesives and barrier coatings. Manufacturers must validate alternative chemistries through ECHA notification procedures, extending product-development timelines. Commercial-grade aluminum pods face the tightest compliance windows, driving consolidation among European converter suppliers.
Corporate procurement departments are unbundling equipment ownership from beverage supply agreements. Facility management providers are displacing direct manufacturer relationships in mid-size office deployments. This pattern is most visible in German Mittelstand manufacturing facilities, where bundled service contracts now dominate new installations.
Capsule Coffee Machines Market Segmentation
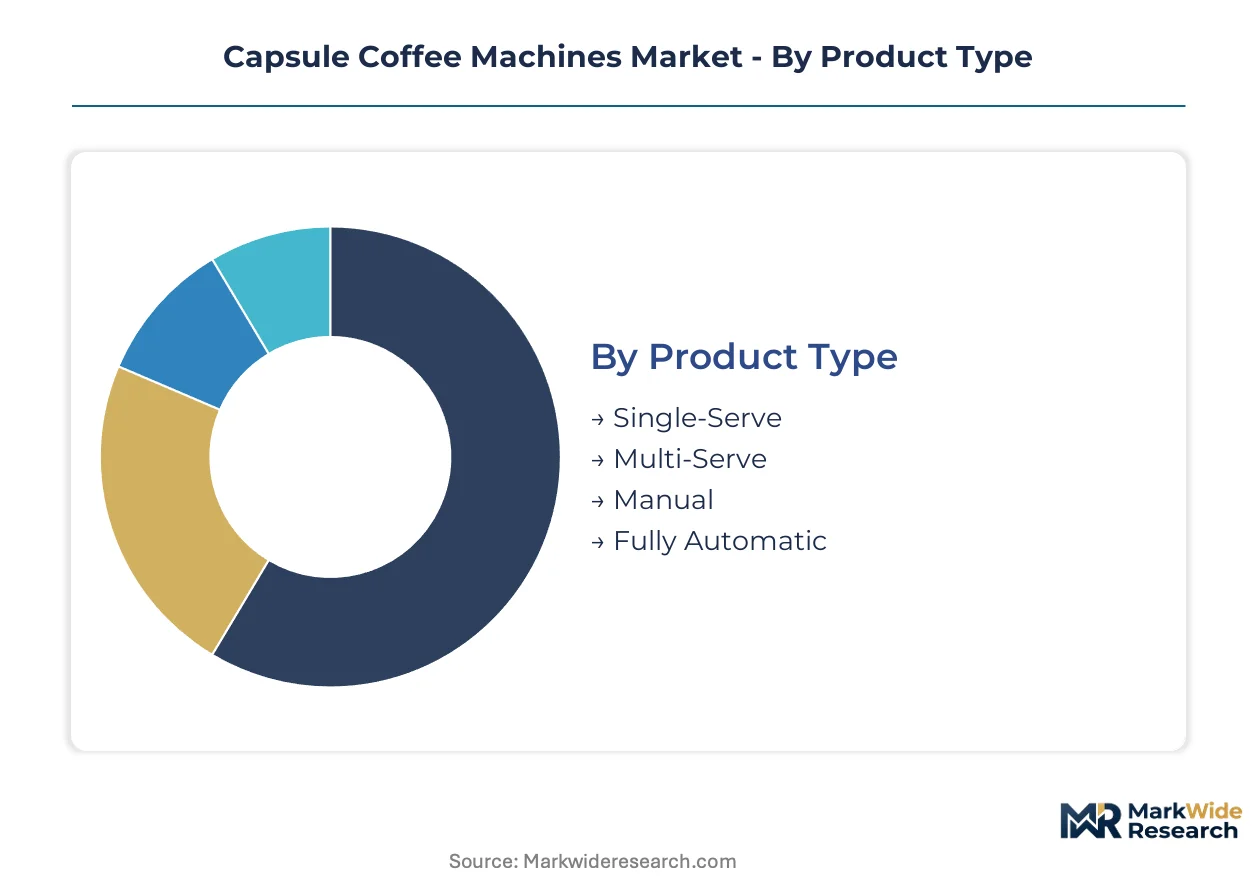
Segmentation in capsule coffee machines reflects divergent equipment economics across brewing formats and procurement channels. Technical specifications, end-use labor models, and distribution cost structures create distinct margin profiles that shape manufacturer portfolio priorities.
Product Type:
The use-case spectrum spans from countertop convenience to high-throughput commercial automation.
- Single-Serve:Compact units puncturing individual pods dominate residential kitchens where space constraints and variety-seeking behavior concentrate demand. German and Swiss households anchor volume due to premium pod availability and recycling infrastructure maturity.
- Fully Automatic:Integrated grinding, tamping, and milk-frothing systems command hospitality procurement budgets by eliminating barista labor. European hotel chains deploy these in lobby service areas to offset wage inflation while maintaining beverage consistency.
- Multi-Serve:Larger reservoir systems serve small offices and family households with elevated consumption patterns.
- Manual:Lever-operated and semi-automatic formats target enthusiast buyers seeking extraction control.
Established volume favors Single-Serve; emerging adoption favors Fully Automatic.
Technology:
Cost tier differentiation separates premium pressure systems from accessible drip alternatives.
- Espresso:High-pressure pump systems generating 9-15 bars extract concentrated shots with crema formation, commanding premium residential and hospitality placement. REACH compliance pressures are accelerating induction heating adoption in this tier.
- Cold Brew:Extended steeping or specialized chilling modules produce lower-acidity beverages capturing younger demographics. This segment is expanding most quickly as chilled coffee consumption displaces traditional hot formats in North American and European urban markets.
- Drip Brewing:Gravity-fed systems dominate economy positioning through simpler mechanics and reduced energy draw.
- Pump Technology:Electromagnetic and vibration pump variants balance cost against pressure consistency in mid-market units.
Margin concentration sits with Espresso; volume growth momentum sits with Cold Brew.
End User:
Application context determines equipment durability requirements and service contract structures.
- Residential:Individual households prioritize compact footprint and pod variety availability over throughput speed. German municipalities with established capsule collection programs show elevated replacement rates versus markets lacking recycling infrastructure.
- Hospitality:Hotels and serviced apartments demand 24-hour operational reliability and brand-compatible aesthetics. Swiss Alpine properties maintain above-average per-room coffee investment, supporting premium machine placement with bundled maintenance agreements.
- Commercial:Cafes and quick-service outlets require NSF-certified components and rapid recovery times.
- Office:Corporate breakrooms balance employee satisfaction against facilities management procurement constraints.
Replacement cycle stability favors Residential; fleet expansion rates favor Hospitality.
Distribution Channel:
Customer type and purchase urgency shape channel selection and margin retention.
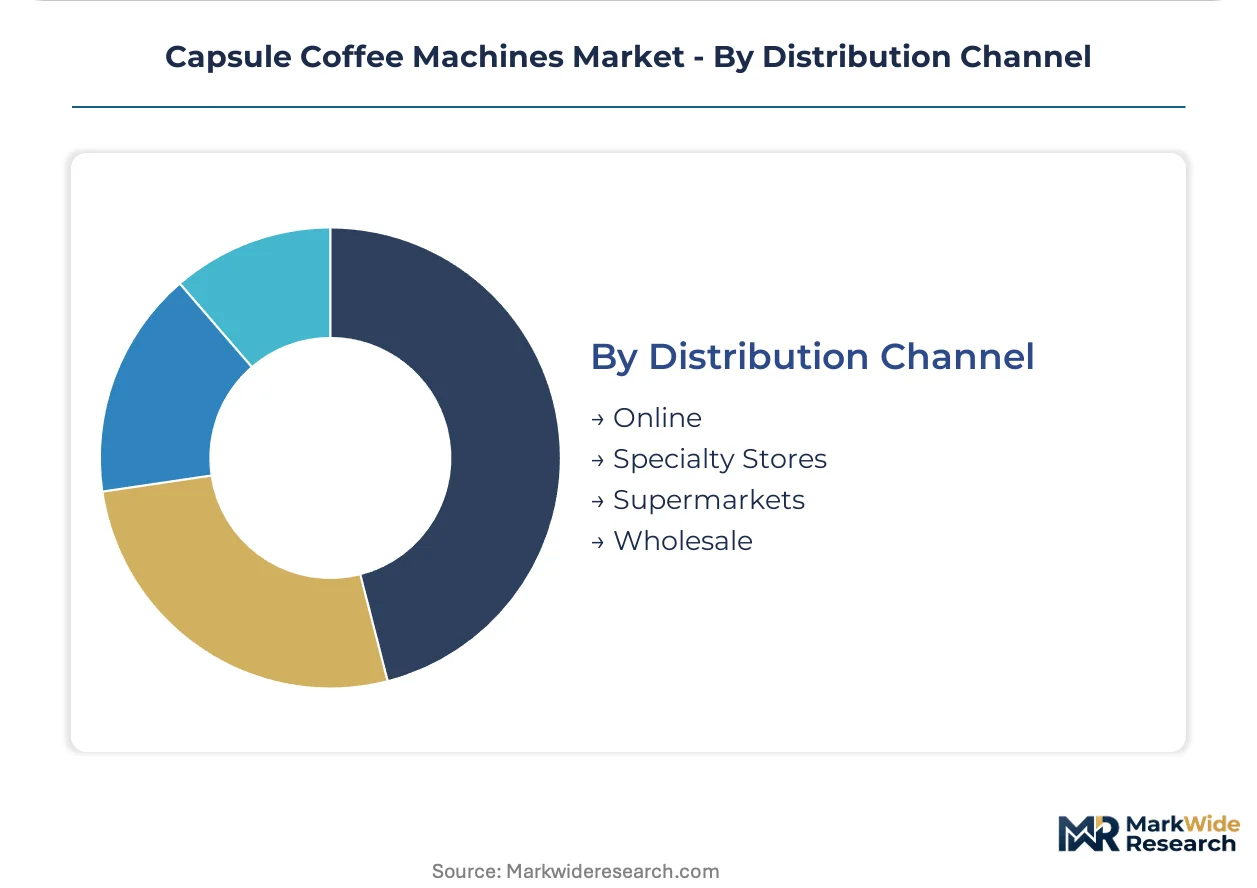
- Online:Direct-to-consumer platforms and marketplace listings capture subscription pod bundling and replacement part sales. Nespresso's proprietary channel control anchors premium European placement through locked-in brewer-pod ecosystems.
- Wholesale:Facility management providers and hospitality procurement consortia negotiate asset-light leasing arrangements. German Mittelstand manufacturing facilities increasingly source through bundled service contracts displacing direct manufacturer relationships.
- Specialty Stores:Curated retail environments support hands-on demonstration and enthusiast-tier conversion.
- Supermarkets:Mass retail placement drives impulse purchase and gift-market volume with compressed margins.
Recurring revenue attachment favors Online; contract scale favors Wholesale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Ecodesign Directive is accelerating equipment upgrades across European hospitality sectors while North American office service providers expand fleet leasing arrangements. Germany's deposit-return infrastructure and Switzerland's premium hotel density anchor continental demand patterns.
Germany
Hospitality automation and aluminum pod recycling infrastructure drive replacement cycles in German commercial installations. The national packaging ordinance mandates dual systems compliance for capsule producers, creating closed-loop cost advantages. Bavarian Mittelstand manufacturing clusters increasingly source through bundled service contracts rather than direct equipment purchase.
Switzerland
Alpine hotel chains maintain above-average per-room coffee investment, supporting premium machine placement with maintenance bundling. Swissmedic and federal environmental offices coordinate food-contact material standards with EU REACH alignment. The Zurich-Geneva hospitality corridor concentrates high-margin fully automatic deployments.
United States
Corporate breakroom consolidation and cold brew format expansion reshape procurement patterns across metropolitan office markets. EPA appliance energy standards and FDA food-contact regulations govern market access requirements. Pacific Northwest technology campuses pioneer subscription-based equipment deployment models.
France
Extended producer responsibility laws mandate producer-funded deposit-return schemes for aluminum capsules, restructuring cost allocation. ANSM oversight of food-contact materials intersects with EU Ecodesign compliance timelines. Parisian hospitality procurement consortia negotiate asset-light leasing at scale.
United Kingdom
Post-regulatory divergence creates dual compliance burdens for equipment serving both UK and EU markets. The Environment Agency administers packaging waste regulations affecting pod material choices. London financial district office service providers drive demand for multi-serve systems with rapid throughput.
Capsule Coffee Machines Market Vendor Landscape
Channel-controlling players compete with product-specialist players across divergent margin structures. The market exhibits tiered consolidation with premium pod-locked ecosystems at the top and unbranded equipment fabricators at the base. Two strategic archetypes dominate: direct-to-consumer platform operators and commercial fleet service providers. Competitive moves center on subscription model expansion and regulatory compliance certification rather than price-based confrontation.
Within the premium pod-locked tier, Nespresso exemplifies channel control through proprietary brewer-pod ecosystems, while Keurig Dr Pepper occupies a parallel position in North American commercial breakrooms. Among European equipment specialists, De'Longhi and Breville represent divergent approaches to enthusiast and semi-automatic residential segments.
| Leading Market Players |
|---|
| De'Longhi |
| Illycaffe |
| Nespresso |
| Breville |
| Dualit |
| Keurig Dr Pepper |
| Philips |
| Ningbo AAA Group Electric Appliance |
| Lavazza |
| Others |
Supply Flow & Price Mechanics
Guangdong province's electronics manufacturing clusters concentrate heating element and pump assembly capacity, creating asymmetric pricing power for OEMs serving European hospitality procurement. This concentration compresses margin capture for brands lacking direct component sourcing relationships or captive production.
Pricing Analysis
Certification level (CE marking plus Ecodesign compliance) creates the primary spread between premium and economy equipment tiers. Three-tier pricing structure across premium, standard, and economy levels reflects bundling intensity of after-sales service agreements and pod compatibility scope. Pricing pressure stems from aluminum pod material cost volatility and REACH compliance investment requirements. Mid-market hospitality buyers exhibit highest price sensitivity due to capital budget constraints, while Swiss Alpine hotel chains show lowest sensitivity where maintenance bundling dominates total cost of ownership.
Supply Chain Analysis
Flex, Jabil, and specialized EMS providers in Shenzhen and Dongguan hold dominant contract manufacturing capacity for heating modules and control systems. Component sourcing draws from Germany for precision pumps, China for induction coils and plastic housings, and Switzerland for temperature sensors. Single-source vulnerability concentrates in proprietary brewing chamber machining where incumbent IP holders restrict supplier diversification. Distribution runs through facility management providers in German Mittelstand clusters and direct-to-consumer platforms anchored by Nespresso's locked ecosystem.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Ecodesign Directive and REACH substance restrictions are accelerating equipment replacement cycles and pod material reformulation, creating high-growth disruption for compliance-ready manufacturers.
For Market Incumbents: Pre-empt regulatory fragmentation by securing ECHA pre-registration for alternative sealing adhesives before 2026 compliance windows tighten. Consolidate backward integration into aluminum pod converter relationships to offset extended producer responsibility cost shifts in France and Germany. Channel control through proprietary pod-locked ecosystems remains the priority defensive lever against unbranded equipment commoditization. For New Entrants and Emerging Players: Mid-market commercial buildings in German Mittelstand manufacturing clusters represent the most penetrable entry point where bundled service contracts are displacing direct manufacturer relationships. Asset-light leasing models to facility management providers bypass capital-budget gatekeeping that blocks equipment sales. Compostable polymer R&D partnerships with EN 13432-certified film suppliers enable premium positioning against incumbent aluminum formats. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors induction heating specialists with Ecodesign-compliant product pipelines over legacy thermoblock-dependent portfolios. Long-term viability rests on regulatory certification breadth across multiple EU member state implementations. Monitor ECHA substance restriction timelines as the critical inflection signal for pod material cost structure disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Induction Heating Module Development | Enables Ecodesign wattage compliance for German and Swiss hospitality procurement. |
| Compostable Pod Film Certification | Opens premium positioning through EN 13432 industrial-composting standard validation. |
| Facility Management Partnership | Captures German Mittelstand bundled service contract channel displacing direct sales. |
| Aluminum Converter Backward Integration | Secures closed-loop supply advantage under Germany's deposit-return packaging ordinance. |
| Cold Brew System Platform Launch | Captures younger residential demographics shifting toward lower-acidity chilled preparations. |
Methodological Framework
The analysis maps single-serve residential, fully automatic hospitality, and cold brew technology segments, each validated through facilities management procurement directors, hotel operations executives, and component supplier technical leads. Primary fieldwork combined structured interviews with heating element engineers, pod converter operations managers, and ECHA regulatory consultants. Secondary sources included EU Ecodesign implementing measure drafts, ECHA substance restriction notifications, German packaging ordinance compliance filings, and customs data for aluminum pod trade flows. Bottom-up equipment placement tracking and top-down consumables revenue triangulation anchored market sizing.
Assumptions held fixed include EU Ecodesign wattage thresholds and REACH substance restriction timelines, while aluminum price trajectories and hospitality labor inflation rates were varied across sensitivity scenarios. Segmentation modeling spanned product type, technology format, end-user application, and distribution channel across the analysis window. CAGRs were derived from installed base replacement cycle analysis and consumables attach rate projections. Forecast inputs incorporated induction heating adoption curves and deposit-return scheme participation rates by member state.
Macroeconomic conditions sit as an overlay; deviation in aluminum smelting energy costs or EU hospitality sector wage growth would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation schedules and pod recycling infrastructure buildout pace. Quarterly review of ECHA restriction proposal advancement and German Länder EPR enforcement intensity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Induction Stove Market
Kitchen Appliances
Air Fryer Accessories Market
Kitchen Appliances
Global Portable Blenders Market
Kitchen Appliances
Residential Hobs Market
Kitchen Appliances
Egg Boiler/Cooker Market
Kitchen Appliances
Pressure Cooker Market
Kitchen Appliances
Europe Small Kitchen Appliances Market
Kitchen Appliances
Cotton Candy Maker Market
Kitchen Appliances
North America Electric Kettle Market
Kitchen Appliances
Sandwich Maker Market
Kitchen Appliances
Kitchen Appliances Market
Kitchen Appliances
India Electric Vegetable Choppers Market
Kitchen Appliances
Induction Hobs Market
Kitchen Appliances
Global Baking Tools Market
Kitchen Appliances
Malaysia Smart Kitchen Appliances Market
Kitchen Appliances
Europe Household Side by Side Refrigerator Market