
 Belgium Data Center Power Market | 2026-2036
Belgium Data Center Power Market Size, Share, and Industry Trends Forecast 2026-2036
Belgium Data Center Power Market Insights
A capital-intensity divergence between integrated infrastructure providers and modular equipment specialists is reorganizing competitive dynamics in Belgium's data center power sector. Schneider Electric leverages its end-to-end power architecture portfolio to dominate turnkey deployments across the Brussels corridor. Vertiv sustains technology leadership in thermal-integrated power systems, while ABB competes through high-voltage direct current expertise for hyperscale campuses.
Belgium data center power encompasses electrical infrastructure engineered to deliver continuous, conditioned electricity to server environments, typically operating at voltages from 400V AC to 800V DC with redundancy tiers from N+1 to 2N+1. This infrastructure serves the fundamental purpose of eliminating downtime risk for digital asset hosting while optimizing energy conversion efficiency across cooling and compute loads. UPS systems and power distribution units concentrate margin pools due to their critical role in uptime assurance, whereas energy efficiency solutions represent the fastest-expanding segment as operators face mounting pressure from EU Green Deal compliance obligations. Generators retain structural importance for backup resilience but face gradual displacement in new builds where grid interconnection stability improves.
Belgian operators navigate overlapping requirements from the EU Green Deal's decarbonization timeline, CE marking for electrical safety conformity, and national building codes enforced by regional authorities in Flanders, Wallonia, and Brussels-Capital. These frameworks directly shape procurement specifications, mandating efficiency thresholds that filter vendor eligibility and elevate total cost-of-ownership calculations in sourcing decisions. Stakeholders must monitor how evolving grid capacity allocation rules from federal and regional energy regulators affect power availability timelines for planned data center expansions.
Market Dynamics
Belgian data center power procurement pivots on EU Green Deal compliance timelines that mandate 55% carbon reduction by 2030, forcing operators to abandon diesel-dependent backup architectures and requalify vendors against stricter efficiency thresholds.
Growth Catalysts
- EU Green Deal carbon mandates:Binding decarbonization targets for 2030 compel hyperscale operators to retrofit existing facilities with high-efficiency UPS and lithium-ion battery systems, creating sustained replacement demand across the Brussels corridor.
- Cloud capacity expansion:International cloud services providers are commissioning multi-megawatt campuses in the Brussels-Capital Region, directly lifting orders for medium-voltage switchgear and modular power skids.
- Liquid cooling integration:Direct-to-chip thermal architectures require redesigned power distribution topologies, pulling specialized PDU and busbar configurations into standard procurement specifications.
Market Restraints
- Copper and silicon carbide supply concentration:Power semiconductor fabrication concentrates in East Asian foundries, exposing Belgian integrators to lead time volatility for high-frequency switching components.
- Grid interconnection queuing:Federal and regional energy regulators in Belgium impose allocation rules that extend power availability timelines for new data center builds beyond typical construction schedules.
- Lithium-ion thermal runaway risk:Fire suppression requirements for battery energy storage systems add engineering complexity and insurance cost layers that nickel-cadmium alternatives avoid.
Strategic Opportunities
- Wallonia and Flanders secondary hub development:Land and power availability outside Brussels-Capital creates greenfield deployment opportunities for edge and regional cloud facilities requiring localized power infrastructure.
- High-voltage direct current distribution:800V DC architectures eliminate AC-DC conversion losses at the rack level, offering efficiency gains that hyperscale operators will premium-price against conventional 400V AC systems.
- CE marking plus BREEAM certification bundling:Vendors who pre-validate integrated power and building efficiency packages accelerate permitting timelines for developers targeting dual compliance.
Industry Challenges
- Medium-voltage engineering talent scarcity:Specialized expertise in 10-35kV switchgear design and commissioning remains concentrated among aging technical workforces, constraining deployment velocity for large campuses.
- Legacy 400V AC infrastructure retrofit complexity:Existing facilities face stranded asset risk as 800V DC and liquid cooling requirements demand complete electrical topology redesign rather than incremental upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Belgium Data Center Power Market |
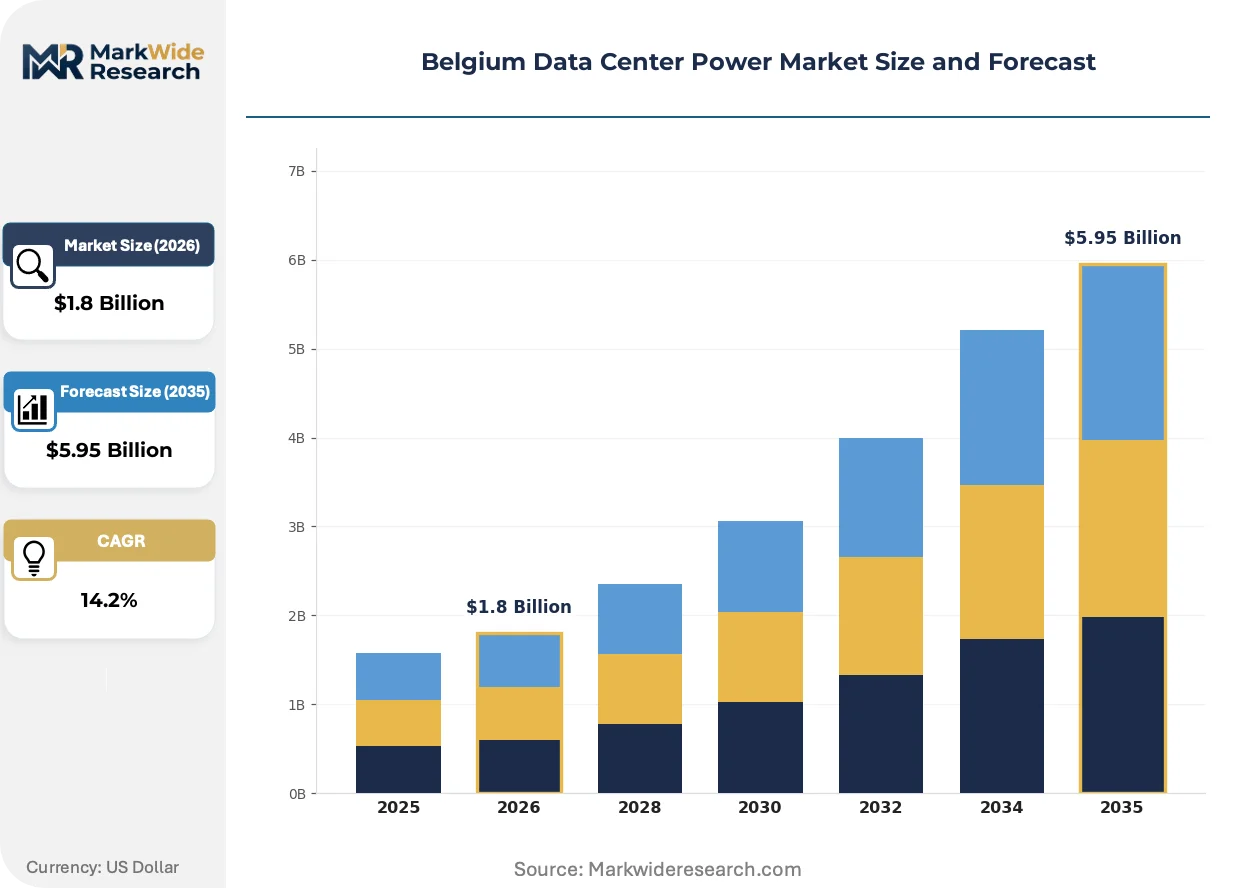
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Type: UPS Systems, Generators, Power Distribution Units, Power Cables Application: Colocation Centers, Cloud Services, Managed Hosting, Enterprise Data Centers Technology: DC Power, AC Power, Power Monitoring Systems, Energy Efficiency Solutions End User: IT Services, Telecommunications, Financial Services, Media |
| Companies Covered | Schneider Electric, Vertiv, ABB, Eaton, Delta Electronics, Digital Realty, LCL Data Centers, Datacenter United, Proximus, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Belgium Data Center Power Market Trends and Innovations
Belgium's data center power landscape is compressing around three vectors: voltage architecture migration, regulatory compliance automation, and procurement model restructuring that favors integrated performance guarantees over component-centric sourcing.
Solid-state transformer technology is supplanting conventional magnetic transformers in hyperscale designs. These semiconductor-based units enable direct medium-voltage to 800V DC conversion, eliminating multiple conversion stages. Colocation operators in the Brussels corridor are piloting deployments to reduce footprint and cooling loads. The technology is compressing total cost-of-ownership calculations for new builds despite higher capital outlays.
EU Green Deal implementation through national building codes enforced by Flanders, Wallonia, and Brussels-Capital regional authorities now mandates real-time power usage effectiveness reporting. This regulatory architecture forces operators to deploy sub-metering infrastructure at the rack level. Compliance automation software is becoming a bundled requirement in power infrastructure RFPs, particularly for facilities targeting BREEAM certification.
Performance-based contracting is displacing traditional equipment procurement in large deployments. Hyperscale operators now require vendors to guarantee energy efficiency outcomes over five-to-seven-year terms, transferring operational risk to integrators. This model concentrates vendor selection among firms with captive service networks. Wallonia-based edge facilities are adopting this structure fastest due to limited in-house engineering resources.
Belgium Data Center Power Market Segmentation
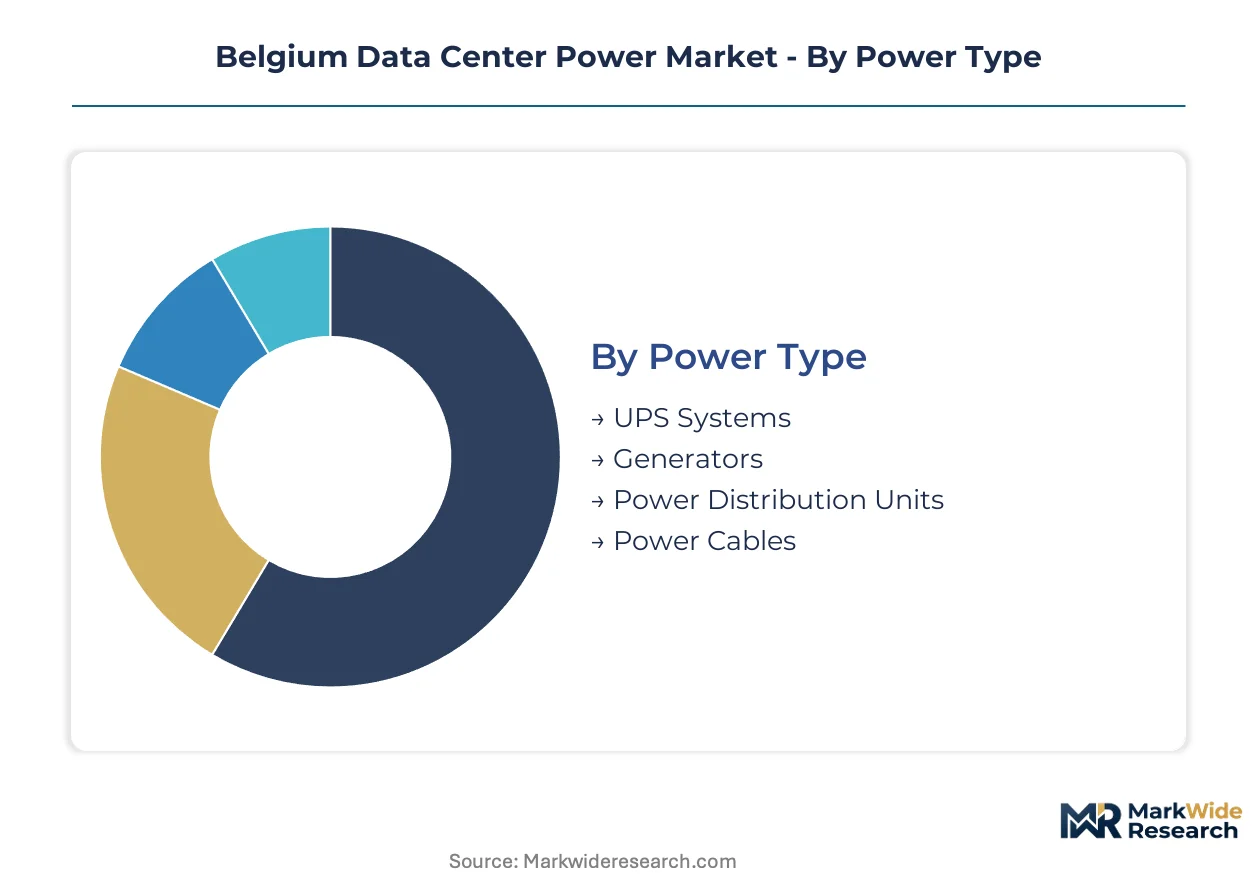
Belgium's data center power market segments along four critical dimensions that determine procurement patterns and vendor selection criteria. Each category reflects distinct technical requirements, compliance obligations, and channel dynamics that shape how power infrastructure flows from manufacturers to facility operators across Brussels-Capital, Flanders, and Wallonia.
Power Type:
Channel mix varies sharply by power type, with UPS systems and generators flowing through specialized electrical distributors while power cables and PDUs move via direct OEM relationships with large integrators.
- UPS Systems:Double-conversion online UPS units with lithium-ion battery integration dominate hyperscale procurement in the Brussels corridor. Demand concentrates among cloud services providers retrofitting facilities to meet EU Green Deal efficiency mandates, with vendors bundling real-time power monitoring to satisfy regional building code requirements.
- Generators:Diesel and natural gas backup systems face declining new-build orders as grid stability improves, though they retain structural importance for Tier IV facilities. Financial services operators in Brussels-Capital sustain replacement demand for existing diesel architectures despite carbon reduction pressures.
- Power Distribution Units:Rack-mounted and floor-standing PDUs with intelligent metering capabilities serve colocation operators seeking granular tenant billing accuracy.
- Power Cables:Medium-voltage and low-voltage cabling infrastructure connects switchgear to server halls, with copper pricing volatility affecting procurement timing.
By volume, power cables lead due to universal infrastructure requirements. By growth pace, UPS systems with lithium-ion integration are expanding most quickly.
Application:
Cost tier stratification separates premium hyperscale deployments from economy-grade edge facilities, with each application demanding distinct power architecture redundancy levels and efficiency specifications.
- Colocation Centers:Multi-tenant facilities require N+1 to 2N+1 redundant power architectures with sub-metering capabilities for individual client billing. Brussels-Capital operators prioritize CE-marked equipment bundles that accelerate permitting through BREEAM certification alignment.
- Cloud Services:Hyperscale campuses demand medium-voltage switchgear and modular power skids at multi-megawatt scale. Wallonia and Flanders greenfield developments attract cloud provider investment where land and interconnection capacity exceed Brussels constraints.
- Managed Hosting:Mid-tier facilities balance reliability against capital efficiency, typically specifying N+1 redundancy with shorter equipment lifecycles.
- Enterprise Data Centers:Corporate-owned facilities show heterogeneous requirements based on industry vertical, with financial services mandating the highest tier resilience.
Cloud services command the highest absolute spending per facility. Colocation centers are gaining share fastest as enterprises exit owned infrastructure.
Technology:
Customer maturity divides this category, with early-adopter hyperscalers piloting 800V DC architectures while conservative operators maintain 400V AC standards.
- DC Power:400V and 800V direct current distribution eliminates conversion losses for high-density compute loads. Hyperscale operators in the Brussels corridor premium-price DC architectures against conventional AC systems, particularly for liquid-cooled server deployments.
- AC Power:Traditional 400V alternating current infrastructure retains dominance in legacy facilities and smaller edge deployments. Flanders-based regional facilities specify AC power due to available technical expertise and established maintenance networks.
- Power Monitoring Systems:Real-time PUE reporting hardware satisfies EU Green Deal implementation through national building codes enforced by regional authorities.
- Energy Efficiency Solutions:Integrated hardware-software packages optimize power usage effectiveness across cooling and compute loads.
AC power retains volume leadership through installed base scale. DC power shows the steepest expansion trajectory as new hyperscale campuses commission.
End User:
Geography shapes end-user demand patterns, with Brussels-Capital concentrating financial services and telecommunications while Wallonia attracts media and regional IT services.
- IT Services:Outsourced infrastructure providers and systems integrators specify standardized power modules for rapid deployment across client sites. Demand clusters in Brussels-Capital where proximity to European institutions and corporate headquarters drives latency-sensitive hosting requirements.
- Telecommunications:5G edge computing and core network facilities require power systems with extreme reliability for uninterrupted service delivery. Operators prioritize solid-state transformer technology to reduce footprint in constrained urban locations.
- Financial Services:Banks and insurance carriers mandate Tier IV resilience with 2N+1 redundancy for trading and transaction processing infrastructure.
- Media:Content delivery and streaming platforms seek cost-optimized power architectures for cache and origin server deployments.
IT services generates the highest equipment volume through outsourcing growth. Telecommunications is climbing fastest on 5G infrastructure buildout.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgium's data center power infrastructure exhibits limited import dependence for specialized electrical components, with domestic integrators sourcing medium-voltage switchgear and power semiconductors from neighboring EU manufacturing hubs while exporting engineering expertise to Luxembourg and Netherlands facilities.
Brussels-Capital Region
Hyperscale cloud campuses from international providers drive concentrated demand for modular power skids and lithium-ion UPS systems. EU Green Deal implementation through Brussels-Capital regional building codes mandates real-time PUE reporting, forcing operators to deploy sub-metering infrastructure. The Brussels corridor anchors Belgium's primary data center cluster, with Digital Realty and colocation operators commissioning multi-megawatt facilities requiring 2N+1 redundant architectures.
Flanders
Edge computing and regional cloud facilities expand across Antwerp and Ghent where land availability exceeds Brussels constraints. Flemish regional authorities enforce CE marking and BREEAM certification requirements that filter vendor eligibility for power infrastructure procurement. The Port of Antwerp area attracts media content delivery networks seeking cost-optimized power architectures for cache server deployments.
Wallonia
Secondary hub development accelerates around Liège and Namur as operators seek greenfield sites with favorable grid interconnection timelines. Walloon regional energy regulators impose allocation rules that, while still demanding, offer shorter queues than Brussels-Capital for new data center power connections. Performance-based contracting spreads fastest here due to limited in-house engineering resources among regional facility developers.
Belgium Data Center Power Market Competitive Landscape
Concentration sits with integrated electrical infrastructure providers who control turnkey deployment channels across Belgium's three regions. The vendor base stratifies between end-to-end power architecture specialists and modular equipment fabricators focused on discrete components like UPS systems or intelligent PDUs. Two archetypes dominate: diversified industrial conglomerates leveraging high-voltage expertise, and pure-play data center power specialists with captive service networks. Competitive dynamics center on strategic partnerships with hyperscale operators and geographic expansion into Wallonia's emerging secondary hubs.
Within the integrated infrastructure tier, Schneider Electric anchors Belgian market presence through its end-to-end power architecture portfolio, while Vertiv exemplifies thermal-integrated power system specialization. ABB occupies a position among high-voltage direct current experts targeting hyperscale campus requirements. These three firms collectively represent the competitive core that smaller modular specialists and regional integrators must navigate around in RFP processes across Flanders, Wallonia, and Brussels-Capital.
| Leading Market Players |
|---|
| Schneider Electric |
| Vertiv |
| ABB |
| Eaton |
| Delta Electronics |
| Digital Realty |
| LCL Data Centers |
| Datacenter United |
| Proximus |
| Others |
Pricing and Supply Chain Analysis
Multi-megawatt hyperscale deployments in the Brussels corridor concentrate procurement volume among cloud services providers, compressing price floors for modular power skids while elevating premium capture for vendors bundling CE marking with BREEAM certification compliance. Scale economies at this tier reshape supplier selection criteria, forcing mid-tier integrators toward Wallonia and Flanders edge facilities where smaller lot sizes sustain price differentiation.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing with performance guarantees dominating hyperscale procurement in the Brussels corridor. Three-tier pricing structure across premium, standard, and economy levels separates Tier IV 2N+1 redundant architectures from N+1 colocation specifications and basic edge deployments. Cost compression in standard-tier UPS systems is intensifying because lithium-ion battery supply concentrates among East Asian cell manufacturers. Managed hosting operators exhibit highest price sensitivity, while financial services buyers premium-price resilience guarantees regardless of capital outlay.
Supply Chain Analysis
Germany and the Netherlands anchor medium-voltage switchgear fabrication for Belgian data center integrators, while Taiwan and South Korea feed power semiconductor wafer supply. Copper cabling and silicon carbide switching components draw from concentrated East Asian foundries, exposing lead time volatility. Single-source vulnerability in lithium-ion cell supply creates procurement risk for UPS system integrators targeting EU Green Deal compliance timelines. Distribution runs through specialized electrical distributors for standardized components and direct OEM relationships for custom power skids.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among hyperscale cloud operators commissioning multi-megawatt campuses, fragmenting vendor margins and forcing integrators toward performance-based contracting models that transfer operational risk.
For Market Incumbents: Consolidate control over medium-voltage engineering talent pools to defend deployment velocity against emerging specialists targeting Wallonia greenfield sites. Deepen backward integration into lithium-ion battery system assembly to capture margin pools shifting from diesel generators. Channel control through captive service networks remains essential as hyperscale operators demand five-to-seven-year efficiency guarantees. For New Entrants and Emerging Players: Lead with liquid cooling-integrated power distribution architectures targeting underpenetrated edge computing facilities in Flanders where established vendors lack localized technical support. Wallonia secondary hub development offers the most penetrable geography given limited in-house engineering resources among regional developers. Partner with solid-state transformer technology licensors to bypass incumbent patent positions in 800V DC conversion. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors modular equipment specialists with demonstrated EU Green Deal compliance automation capabilities over legacy diesel-generator incumbents facing stranded asset risk. Acquisition targets should exhibit captive lithium-ion integration expertise and regional permitting relationships across Brussels-Capital, Flanders, and Wallonia. Watch hyperscale operator capital allocation shifts toward 800V DC architectures as the signal indicating voltage architecture inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Contracting Adoption | Hyperscale operators now require five-to-seven-year efficiency guarantees from integrators. |
| Liquid Cooling Power Topology Redesign | Direct-to-chip thermal architectures pull specialized PDU configurations into standard specifications. |
| CE Marking Plus BREEAM Bundling | Pre-validated packages accelerate permitting timelines for developers targeting dual compliance. |
| Solid-State Transformer Pilot Deployment | Colocation operators in Brussels corridor test medium-voltage to 800V DC conversion technology. |
| Wallonia Secondary Hub Development | Greenfield sites near Liège offer favorable grid interconnection timelines versus Brussels constraints. |
Research Methodology
Operator-level perspectives from data center facility directors, electrical infrastructure procurement managers, regional energy regulator officials, and EPC contractor project leads anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation against FERC-equivalent Belgian federal energy filings, EU Green Deal implementation documents, regional building code enforcement records, and hyperscaler capital expenditure disclosures. Bottom-up equipment shipment analysis triangulated with top-down facility construction pipeline tracking across Brussels-Capital, Flanders, and Wallonia.
Sensitivity analysis tested forecast robustness across grid interconnection timeline scenarios, copper price volatility bands, and lithium-ion supply disruption assumptions over the projection horizon. Segmentation modeling incorporated power type, application tier, voltage architecture technology, and end-user vertical with geographic disaggregation by regional regulatory jurisdiction. CAGRs derived from facility commissioning schedules, equipment replacement cycles tied to EU Green Deal mandates, and hyperscale operator expansion announcements.
The analysis sits within stated boundaries; outcomes outside sustained cloud capacity expansion, stable grid interconnection allocation rules, or continued EU Green Deal enforcement would require recalibration. Forecasts reflect documented assumptions regarding lithium-ion cost curves and solid-state transformer commercialization timelines. Recalibration cycles align with material shifts in hyperscale operator voltage architecture decisions and regional energy regulator queue management policies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Singapore Data Center Physical Security Market
Data Center Infrastructure
Saudi Arabia Data Center Power Market
Data Center Infrastructure
Data Center Blade Server Market
Data Center Infrastructure
Global Cloud Infrastructure Service Market
Data Center Infrastructure
France Data Center Rack Market
Data Center Infrastructure
United States Data Center Server Market
Data Center Infrastructure
Ireland Data Center Market
Data Center Infrastructure
Poland Data Center Construction Market
Data Center Infrastructure
Hyperscale Data Center Market
Data Center Infrastructure
Australia Data Center Construction Market
Data Center Infrastructure
Japan Data Center Rack Market
Data Center Infrastructure
South America Data Center Rack Market
Data Center Infrastructure
Malaysia Data Center Rack Market
Data Center Infrastructure
Denmark Data Center Server Market
Data Center Infrastructure
Brazil Data Center Rack Market
Data Center Infrastructure
Blade Server Market