
 Malaysia Data Center Construction Market | 2026-2036
Malaysia Data Center Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Data Center Construction Market Insights
Green Building Index certification is bifurcating the competitive landscape between qualified and unqualified contractors. Gamuda Berhad leverages its integrated engineering capabilities to dominate large-scale hyperscale builds. YTL Data Center Holdings anchors its position through captive power infrastructure and land banking in Johor. EdgeConneX competes by specializing in rapid-deploy modular configurations for cloud tenants.
Data center construction encompasses the design, engineering, and physical build-out of facilities housing compute, storage, and networking infrastructure, typically requiring power densities exceeding 150 watts per square foot and precision cooling to maintain 18-27°C operating ranges. The primary purpose is creating mission-critical environments that guarantee 99.999% uptime for digital service delivery. Modular data centers are capturing accelerated investment cycles as hyperscalers prioritize speed-to-market over bespoke builds. Cooling systems represent the fastest-growing technology segment as tropical climates drive liquid cooling adoption. Cloud service providers command the dominant share of end-user demand, though managed service providers are expanding fastest among mid-tier capacity tiers.
The Green Building Index and Malaysia's Sustainable Energy Development Authority shape facility efficiency mandates, while the Communications and Multimedia Commission governs data sovereignty and cross-border connectivity standards. Compliance with these frameworks determines project approval timelines and operational licensing eligibility. Stakeholders must monitor how Johor's state-level investment incentives interact with federal digital infrastructure policy to identify optimal development sequencing.
Market Dynamics
Hyperscale cloud tenants are compressing construction timelines from 24 months to 12-14 months, forcing contractors to abandon traditional design-bid-build models in favor of integrated delivery frameworks that compress procurement and engineering phases.
Growth Catalysts
- Johor Investment Incentives:State-level tax holidays and import duty exemptions for critical infrastructure equipment are accelerating land acquisition decisions by foreign operators.
- Liquid Cooling Mandates:Tropical ambient temperatures above 30°C year-round are forcing adoption of direct-to-chip cooling systems as standard specification rather than premium upgrade.
- Green Building Index Certification:Federal procurement preferences for GBI-rated facilities are creating compliance-driven demand that locks out uncertified contractors from premium project tiers.
Market Restraints
- Copper and Aluminum Price Volatility:Busbar and cabling materials constitute 18-22% of electrical infrastructure costs, exposing fixed-price contracts to margin erosion when commodity markets spike.
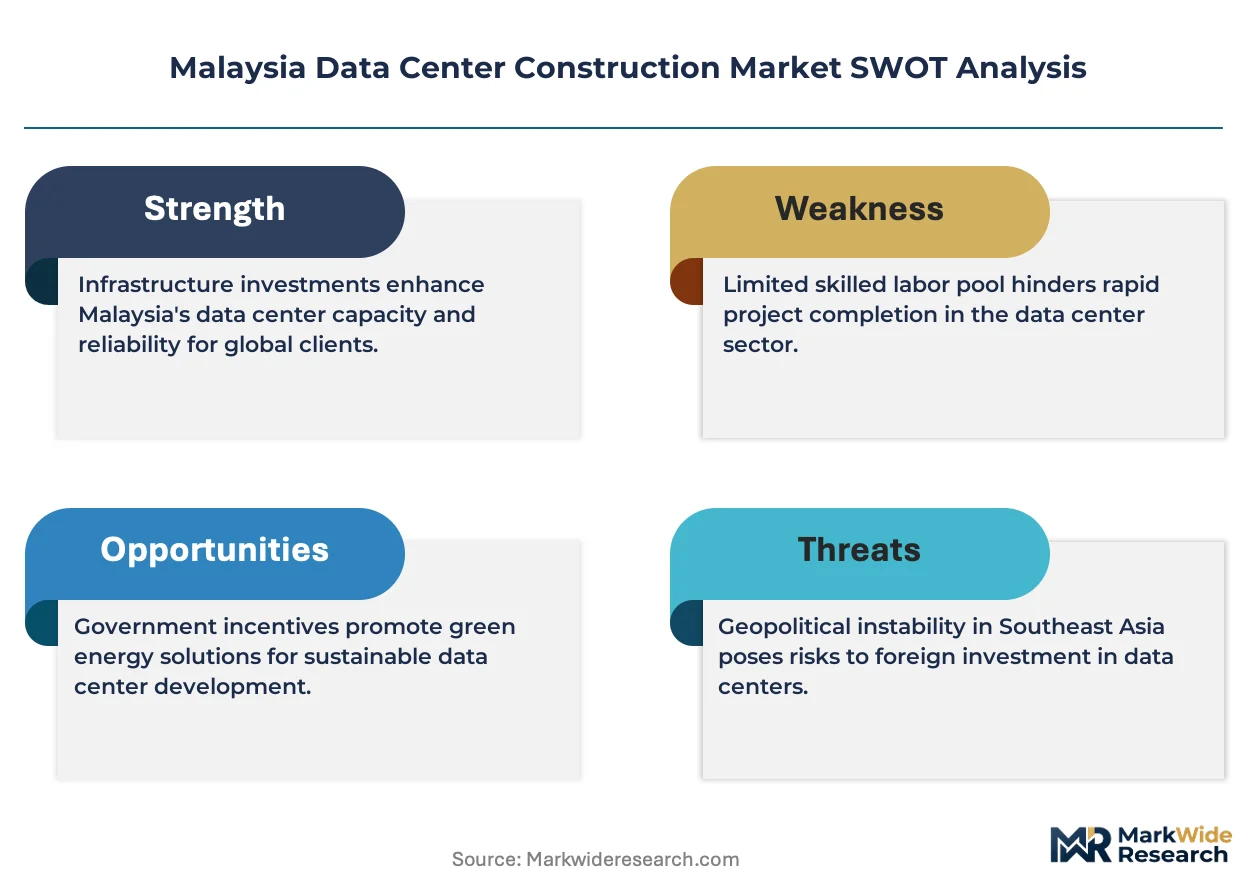
- Specialized Contractor Concentration:Only four Malaysian firms possess simultaneous GBI accreditation and hyperscale delivery track records, creating bottleneck risk for concurrent project ramp-ups.
- Grid Interconnection Queues:Tenaga Nasional Berhad's 18-24 month transmission upgrade timelines routinely extend project completion beyond tenant move-in commitments.
Strategic Opportunities
- Iskandar Puteri Corridor Expansion:State-backed land reclamation projects are releasing 800+ hectares of contiguous development parcels with pre-approved industrial zoning.
- AI Training Workload Migration:Southeast Asian financial institutions are relocating GPU-intensive compute from Singapore to Johor to exploit 40% lower land and power costs.
- Renewable Energy Certificate Arbitrage:Malaysia's net metering framework allows facility operators to monetize rooftop solar generation through virtual power purchase agreements with tenants.
Industry Challenges
- Mission-Critical MEP Coordination:Simultaneous commissioning of redundant electrical, mechanical, and fire suppression systems requires specialized technicians that Malaysian technical institutes currently produce at insufficient rates.
- Cross-Border Data Sovereignty Alignment:Operators must reconcile Malaysia's Personal Data Protection Act with tenant requirements for ASEAN-wide workload portability, complicating legal structuring and compliance documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Data Center Construction Market |
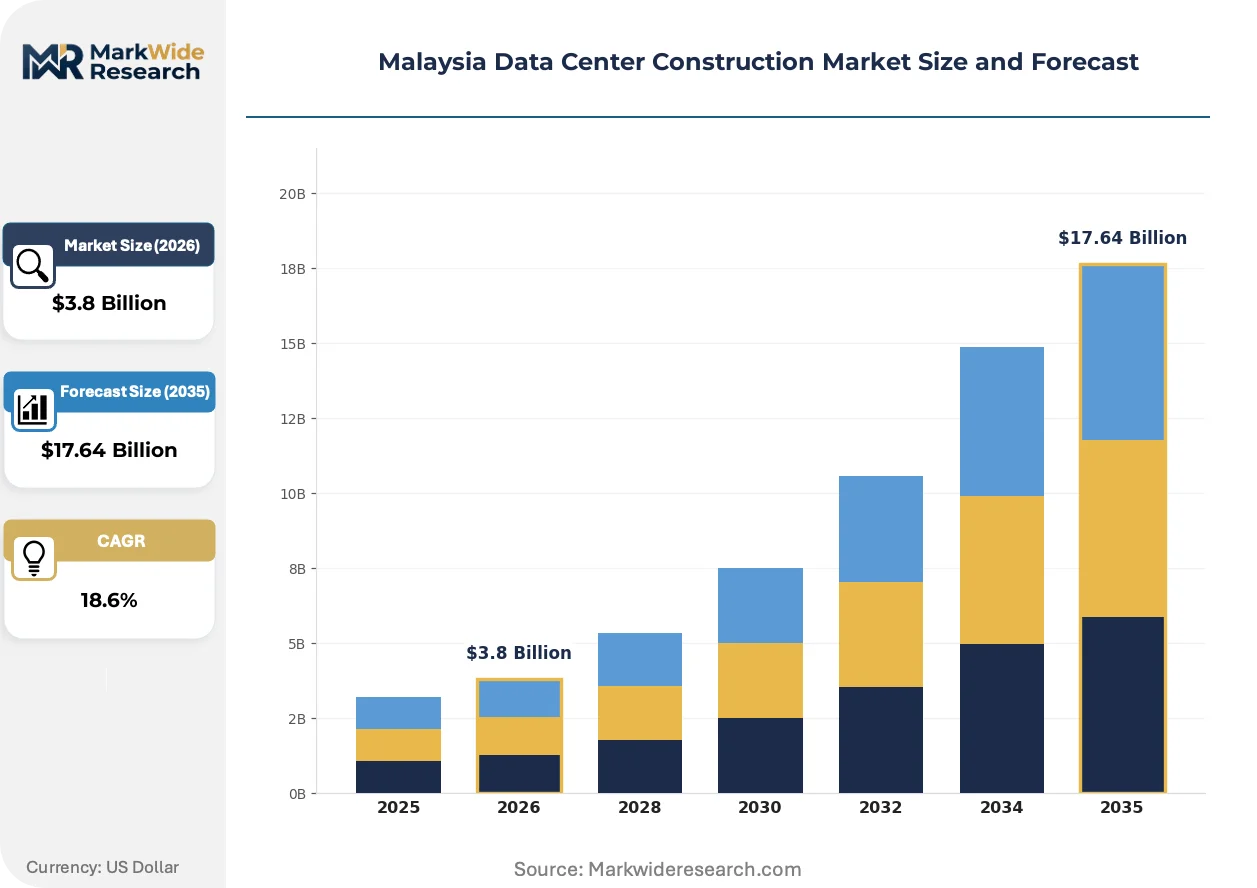
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Data Centers, Traditional Data Centers, Hybrid Data Centers, Edge Data Centers Technology: Cooling Systems, Power Infrastructure, Fire Protection, Security Systems End User: Telecom Providers, Cloud Service Providers, Managed Service Providers, Enterprises Capacity: Small Scale, Medium Scale, Large Scale, Exascale |
| Companies Covered | Gamuda Berhad, Bridge Data Centres, YTL Data Center Holdings, EdgeConneX, MN Holdings Bhd, K2 Strategic, AirTrunk, Exyte, Princeton Digital Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Data Center Construction Market Trends and Innovations
Construction methodology is fragmenting into two divergent paths: bespoke hyperscale builds for cloud operators versus prefabricated modular deployments for enterprise and colocation tenants. This bifurcation is compressing traditional engineering cycles and redrawing contractor specialization boundaries.
Modular data center architecture is decomposing the conventional construction value chain. Prefabricated power modules, cooling skids, and IT containers arrive site-ready from factory floors in Penang and Kulim. Hyperscalers including Microsoft and Amazon Web Services are specifying 70-80% factory completion rates to compress on-site integration to 90-120 days. This shift is decomposing the role of general contractors into logistics coordinators and foundation specialists, stripping margin from traditional civil and MEP trades.
Malaysia's Sustainable Energy Development Authority has tightened renewable energy utilization requirements for new data center approvals. Facilities must now demonstrate 30% clean power sourcing through on-site generation, green tariffs, or renewable energy certificates to secure operating licenses. This mandate is accelerating solar-plus-storage hybrid designs and forcing operators into long-term power purchase agreements with domestic renewable developers rather than relying solely on grid supply.
Enterprise procurement patterns are fragmenting away from single-source general contracting toward multi-contractor frameworks. Large tenants now separately tender civil works, MEP systems, and IT fit-out to capture specialized expertise and price transparency. This unbundling is most visible in Greater Kuala Lumpur, where financial services and telecommunications firms are driving demand for boutique commissioning agents who coordinate disparate contractor workstreams rather than traditional single-point-responsibility models.
Malaysia Data Center Construction Market Segmentation
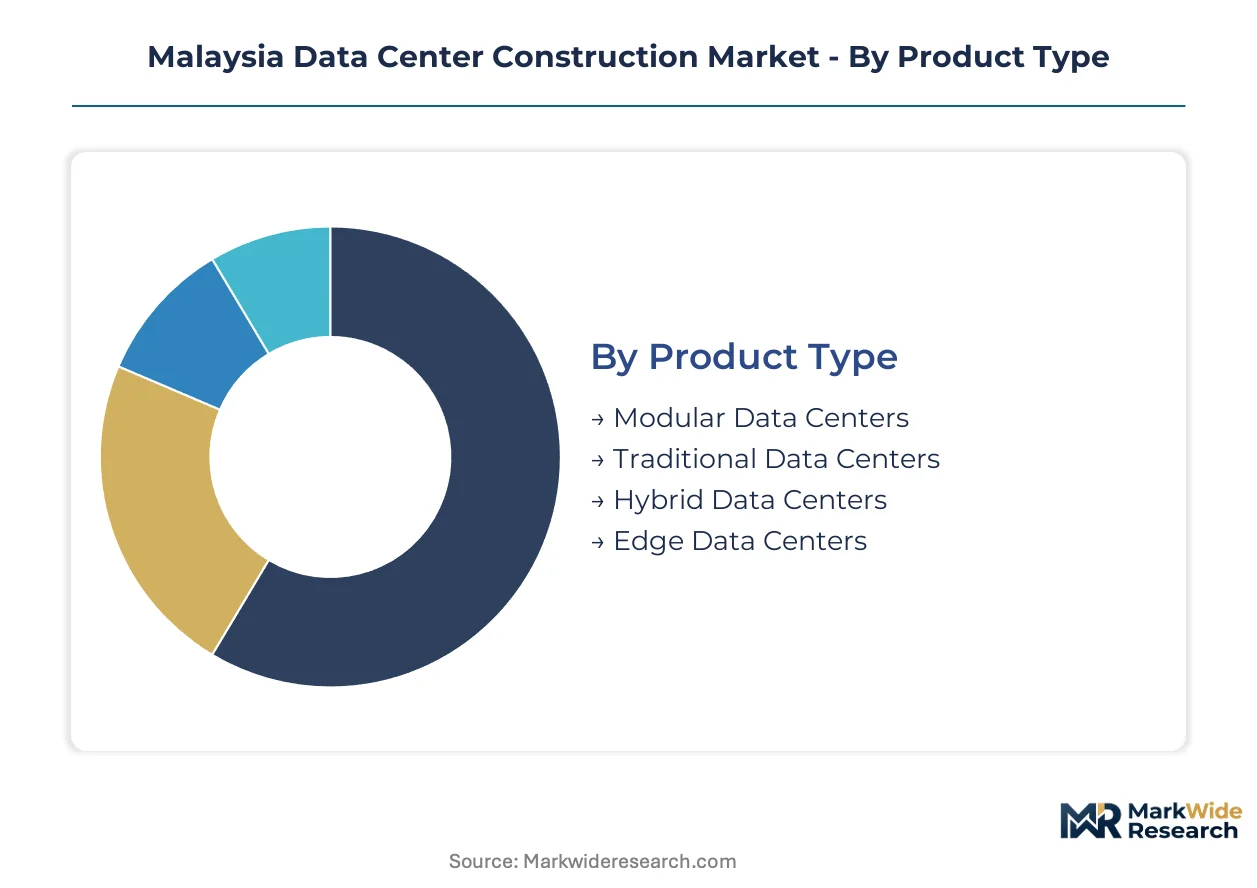
Construction methodology fragmentation in Malaysia reflects divergent tenant priorities: hyperscalers demand speed-to-market while enterprises prioritize operational flexibility. Segmentation reveals where contractor capabilities align with workload-specific infrastructure requirements.
Product Type:
Modular configurations face the strongest substitution pressure from prefabricated alternatives that compress deployment timelines by 60-70%.
- Modular Data Centers:Factory-integrated power, cooling, and IT containers arrive site-ready from Penang and Kulim manufacturing hubs. Hyperscalers including Microsoft and Amazon Web Services specify 70-80% factory completion rates to limit on-site integration to 90-120 days in Iskandar Puteri.
- Traditional Data Centers:Bespoke concrete-and-steel builds with custom MEP engineering dominate financial services procurement in Greater Kuala Lumpur. Extended 24-month timelines persist where tenants require specialized redundancy configurations and legacy system integration.
- Hybrid Data Centers:Blended architecture combining permanent core infrastructure with modular expansion pods serves managed service providers seeking staged capacity growth.
- Edge Data Centers:Sub-500kW distributed facilities target latency-sensitive applications in secondary Malaysian cities including Penang and Malacca.
Traditional builds retain volume leadership; modular deployments hold the steepest expansion curve.
Technology:
Cost tier differentiation separates premium liquid cooling from standard air-cooled baselines as tropical thermal loads intensify.
- Cooling Systems:Direct-to-chip liquid cooling and immersion technologies are displacing conventional CRAC units as ambient temperatures above 30°C year-round force specification upgrades. SEDA mandates now require 30% renewable integration for cooling energy sourcing.
- Power Infrastructure:Medium-voltage switchgear, UPS arrays, and busbar distribution constitute 18-22% of total project cost exposure to copper and aluminum commodity volatility.
- Fire Protection:Clean agent suppression and early warning smoke detection systems protect high-value compute assets.
- Security Systems:Biometric access control and perimeter monitoring satisfy MCMC data sovereignty compliance requirements.
Power infrastructure commands the largest capital allocation; cooling systems are climbing the fastest as efficiency mandates tighten.
End User:
Customer type concentration determines contractor selection criteria, with cloud providers imposing the most aggressive delivery timelines.
- Cloud Service Providers:Hyperscale tenants compress construction cycles to 12-14 months through integrated delivery frameworks, abandoning design-bid-build models for single-point accountability.
- Telecom Providers:Domestic carriers including Maxis and CelcomDigi drive edge facility deployment to support 5G network densification and low-latency service delivery.
- Managed Service Providers:Regional colocation operators expand fastest among mid-tier capacity tiers as ASEAN financial institutions migrate GPU-intensive workloads from Singapore.
- Enterprises:Banking and insurance sectors in Greater Kuala Lumpur favor boutique commissioning agents over general contractors for mission-critical builds.
Cloud providers dominate absolute capacity absorption; managed service providers are gaining share fastest as workload migration accelerates.
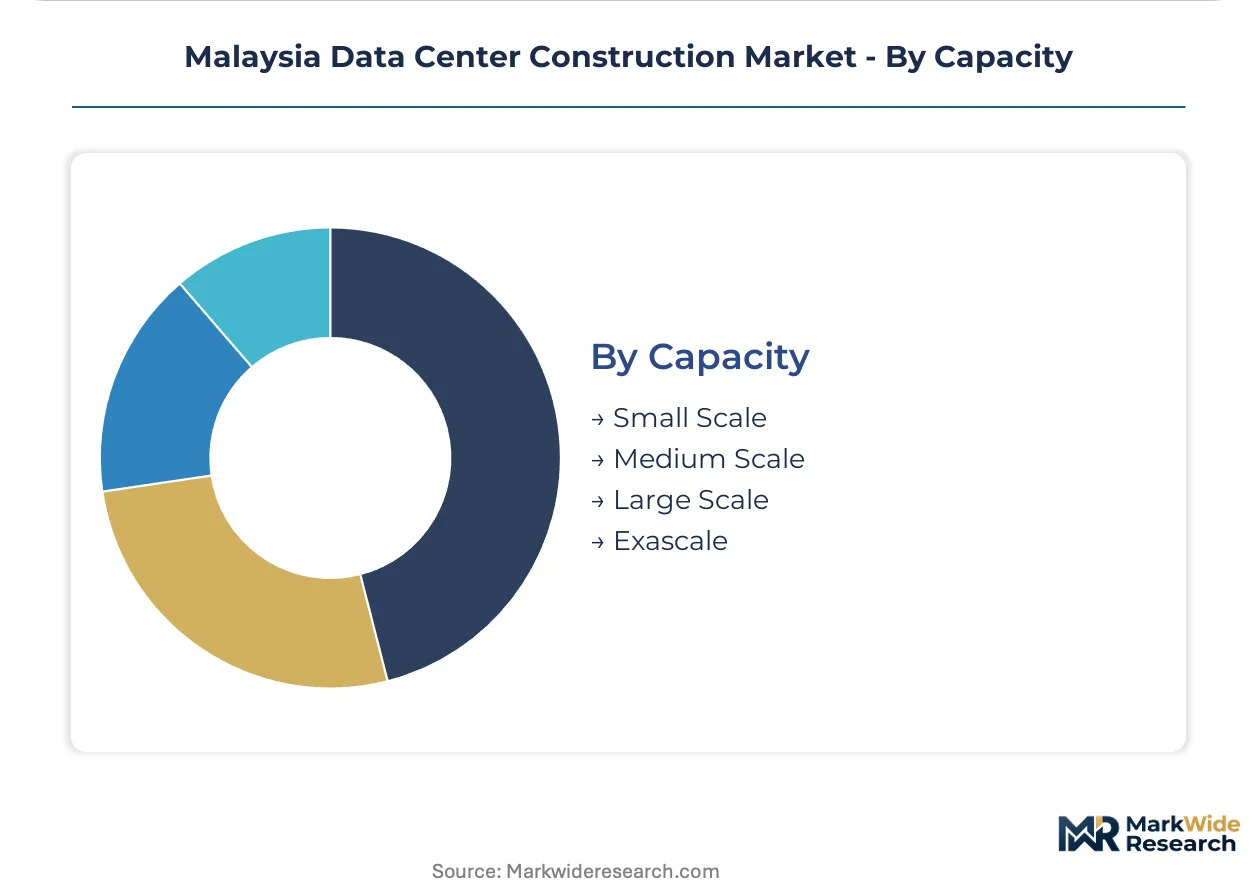
Capacity:
Scale tier alignment with land and power availability shapes geographic clustering across Malaysian development corridors.
- Exascale:Single-tenant facilities exceeding 100MW require contiguous land parcels and dedicated substations, concentrating in Johor's 800-hectare state-backed reclamation zones with pre-approved industrial zoning.
- Large Scale:20-100MW deployments serve regional cloud availability zones and multi-tenant colocation campuses.
- Medium Scale:5-20MW facilities address enterprise disaster recovery and secondary market penetration in Penang and Malacca.
- Small Scale:Sub-5MW edge nodes support latency-critical applications and rural connectivity initiatives.
Large scale deployments retain volume leadership; exascale projects are expanding most quickly as foreign operators exploit Johor investment incentives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-level tax holidays and import duty exemptions for critical infrastructure equipment are accelerating land acquisition decisions by foreign operators across Malaysian development corridors. Federal renewable energy mandates and Green Building Index certification requirements are reshaping facility standards and contractor qualification thresholds.
Johor
Iskandar Puteri anchors exascale facility development through state-backed land reclamation releasing 800-plus hectares of contiguous parcels with pre-approved industrial zoning. SEDA mandates require 30 percent clean power sourcing for new operating licenses. Direct-to-chip liquid cooling systems are becoming standard specification as tropical ambient temperatures force thermal management upgrades.
Greater Kuala Lumpur
Financial services and telecommunications firms drive demand for bespoke concrete-and-steel builds with specialized redundancy configurations. The Green Building Index creates compliance-driven procurement preferences that lock out uncertified contractors from premium project tiers. Boutique commissioning agents are displacing traditional general contractors as enterprise procurement fragments toward multi-contractor frameworks.
Penang
Factory-integrated power modules and cooling skids from Penang manufacturing hubs supply modular data center deployments across Southeast Asia. The state's electronics manufacturing ecosystem supports 70-80 percent factory completion rates for hyperscale specifications. Medium-scale 5-20MW facilities address enterprise disaster recovery requirements for regional banking clients.
Malacca
Secondary market penetration by managed service providers concentrates in sub-500kW edge facilities targeting latency-sensitive applications. State investment promotion agencies compete with Johor for mid-tier colocation operators through customized incentive packages. Grid interconnection timelines from Tenaga Nasional Berhad extend project completion schedules beyond tenant move-in commitments.
Selangor
Telecommunications infrastructure densification for 5G network deployment drives edge node construction in peri-urban corridors. The Communications and Multimedia Commission governs data sovereignty requirements that complicate legal structuring for cross-border workload portability. Domestic carriers including Maxis and CelcomDigi anchor demand for distributed facility deployment.
Malaysia Data Center Construction Market Competitive Landscape
Listed leaders compete with private specialists across integrated delivery capability and captive infrastructure control. The market structure concentrates around four Malaysian firms possessing simultaneous GBI accreditation and hyperscale delivery track records, creating bottleneck risk for concurrent project ramp-ups. Two strategic archetypes dominate: engineering conglomerates with civil and MEP integration capabilities, and infrastructure specialists leveraging land banking and power assets. Competitive moves center on integrated delivery framework adoption and renewable energy certificate arbitrage through rooftop solar monetization.
Among Malaysian engineering conglomerates, Gamuda Berhad occupies a position representing integrated civil and mechanical-electrical coordination capabilities for large-scale builds. YTL Data Center Holdings exemplifies the infrastructure specialist archetype through captive power infrastructure and strategic land positions. EdgeConneX represents the international operator model specializing in rapid-deploy modular configurations for cloud tenant requirements.
| Leading Market Players |
|---|
| Gamuda Berhad |
| Bridge Data Centres |
| YTL Data Center Holdings |
| EdgeConneX |
| MN Holdings Bhd |
| K2 Strategic |
| AirTrunk |
| Exyte |
| Princeton Digital Group |
| Others |
Pricing and Supply Chain Analysis
Exascale facility concentration in Johor's 800-hectare reclamation zones generates procurement leverage that compresses contractor margins while elevating price floors for uncertified competitors. Scale economies from contiguous land parcels with pre-approved industrial zoning allow hyperscalers to dictate integrated delivery terms, forcing traditional design-bid-build contractors into cost-absorbing position or market exit.
Pricing Analysis
Green Building Index certification level creates the primary spread between qualified and unqualified contractor tiers, with GBI-accredited firms commanding 15-25% construction cost premiums over non-certified competitors. Three-tier pricing structure separates hyperscale integrated delivery from boutique commissioning agent frameworks from traditional general contracting. Cost compression in mid-tier modular deployments intensifies as Penang factory-integrated power modules standardize specifications. Cloud service providers exhibit lowest price sensitivity due to speed-to-market imperatives, while regional managed service providers face acute margin pressure from concurrent project ramp-ups.
Supply Chain Analysis
Malaysia and China anchor electrical infrastructure component manufacturing, with Penang and Kulim factory hubs supplying 70-80% factory-completion power modules and cooling skids. Copper busbar, aluminum cabling, and medium-voltage switchgear constitute critical input dependencies. Single-source vulnerability concentrates in liquid cooling system supply as tropical ambient temperatures force direct-to-chip specification upgrades. Distribution runs through Tenaga Nasional Berhad grid interconnection queues that extend 18-24 months, creating downstream bottleneck risk for concurrent project completions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysia's data center construction market represents high-growth infrastructure disruption as SEDA's 30% renewable energy mandate and Green Building Index certification requirements reshape contractor qualification thresholds and procurement patterns.
For Market Incumbents: Shield integrated delivery capabilities through captive power infrastructure investment and GBI accreditation maintenance against modular specialist encroachment. Deepen backward integration into renewable energy certificate arbitrage through rooftop solar monetization. Prioritize land banking in Iskandar Puteri corridor to defend position against state-backed reclamation parcel releases.
For New Entrants and Emerging Players: Anchor in boutique commissioning agent roles within Greater Kuala Lumpur financial services procurement, where multi-contractor frameworks fragment away from single-source general contracting. Target medium-scale 5-20MW enterprise disaster recovery segments in Penang and Malacca with factory-integrated modular configurations. Exploit grid interconnection queue delays through rapid-deploy 90-120 day on-site integration capabilities.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors infrastructure specialists with captive power assets and strategic land positions over pure-play engineering conglomerates. Long-term viability hinges on renewable energy sourcing capabilities and hyperscale delivery track records. Monitor SEDA mandate enforcement intensity as signal for regulatory-driven consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Delivery Framework Adoption | Compresses 24-month timelines to 12-14 months for hyperscale cloud tenants. |
| Renewable Energy Certificate Arbitrage | Monetizes rooftop solar through virtual power purchase agreements under SEDA net metering. |
| Land Banking in Johor Corridor | Secures contiguous parcels with pre-approved industrial zoning for exascale facility development. |
| Liquid Cooling System Specialization | Addresses tropical ambient temperatures above 30°C through direct-to-chip specification dominance. |
| GBI Certification Investment | Unlocks federal procurement preferences and locks out uncertified competitors from premium tiers. |
Research Methodology
Desk research of construction industry databases, regulatory filings with SEDA and MCMC, and hyperscaler capital expenditure disclosures preceded structured interviews with data center project directors, MEP engineering leads, contractor procurement managers, and renewable energy developers. Primary fieldwork validated secondary estimates through bottom-up project pipeline enumeration and top-down market sizing triangulation.
Variance decomposition across construction methodology, cooling technology, and end-user segments shaped analytical framework development over the projection horizon. Modeled dimensions encompass facility scale tier, power density specification, certification status, and geographic corridor clustering. CAGRs derived from project-level capacity absorption rates and investment incentive utilization trajectories, with sensitivity analysis around grid interconnection timeline assumptions and commodity price volatility bands.
Decision-makers should treat outputs as directional under sustained Johor investment incentive availability and SEDA mandate enforcement; material deviation would warrant model refresh. Recalibration cycles align with material shifts in renewable energy utilization thresholds and hyperscale tenant migration patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Global Data Center Accelerator Market
Data Center Infrastructure
Iaas/Hosting Infrastructure Services Market
Data Center Infrastructure
Global Micro Mobile Data Center Market
Data Center Infrastructure
Data Terminal Market
Data Center Infrastructure
Malaysia Data Center Power Market
Data Center Infrastructure
Global Datacenter Deployment Spending Market
Data Center Infrastructure
Next Generation Data Center Market
Data Center Infrastructure
Cloud Network Infrastructure Market
Data Center Infrastructure
South America Data Center Power Market
Data Center Infrastructure
Airflow Management Equipment Market
Data Center Infrastructure
Belgium Data Center Rack Market
Data Center Infrastructure
Italy Data Center Server Market
Data Center Infrastructure
China Data Center Server Market
Data Center Infrastructure
Brazil Data Center Rack Market
Data Center Infrastructure
North America Data Center Power Market
Data Center Infrastructure
Data Center Power Solutions Market