
 Norway Data Center Rack Market | 2026-2036
Norway Data Center Rack Market Size, Share, and Industry Trends Forecast 2026-2036
Norway Data Center Rack Market Insights
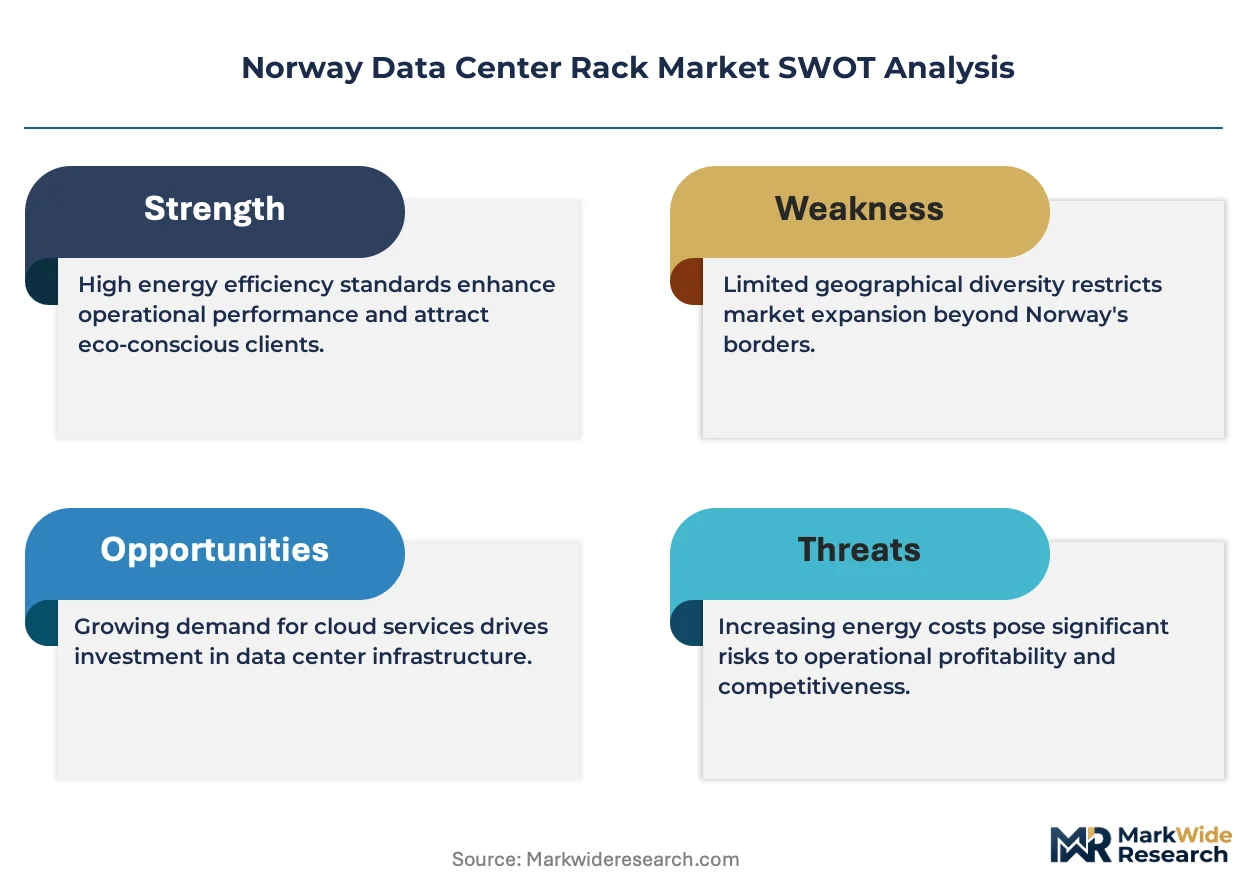
The premium rack tier is consolidating around liquid-cooled and high-density configurations, while commodity open-frame units face margin compression from standardized sourcing. Schneider Electric SE leverages its integrated power and cooling portfolio to dominate enterprise retrofit projects in Bergen and Stavanger. Eaton Corporation anchors its position through advanced power distribution units that bundle with rack enclosures. Rittal GMBH & Co.KG differentiates via modular enclosure systems engineered for Nordic climate extremes.
A data center rack is a standardized metal framework designed to house servers, networking equipment, and power distribution hardware, typically conforming to 19-inch EIA width specifications and supporting static loads exceeding 1,500 kilograms in heavy-duty configurations. Its primary purpose is to optimize spatial density, cable management, and thermal airflow within controlled facility environments. Enclosed rack and heavy-duty rack categories capture the strongest margin pools as hyperscale operators prioritize containment efficiency and load-bearing capacity for GPU-intensive workloads. Cloud service providers and telecom operators represent the fastest-growing end-user segments, driven by submarine cable expansion landing in Lofoten and Vestland corridors.
Norwegian building codes, EU Energy Efficiency Directive transpositions, and Datacenter Energy Efficiency Code of Conduct compliance shape procurement specifications for thermal performance and power usage effectiveness thresholds. The country's national data center strategy aligns with GDPR sovereignty requirements, restricting cross-border data flow infrastructure to certified domestic rack deployments. Stakeholders must monitor evolving carbon disclosure mandates and their impact on material sourcing decisions for aluminum and steel enclosures.
Market Dynamics
Hydropower abundance and submarine cable landings are restructuring procurement geography across Norway's data center rack market, concentrating capital deployment in corridors where renewable baseload intersects with trans-Atlantic fiber capacity.
Growth Catalysts
- EU Energy Efficiency Directive transposition:Norway's building codes now mandate power usage effectiveness thresholds that favor advanced containment rack systems over open-frame alternatives.
- Hyperscale cloud expansion:Submarine cable landings in Lofoten and Vestland corridors are pulling rack demand toward GPU-intensive configurations with liquid-cooling compatibility.
- Hydropower cost arbitrage:Foreign direct investment flows into Oslo metropolitan facilities where renewable electricity rates undercut continental European pricing by significant margins.
Market Restraints
- Aluminum and steel input volatility:Enclosure material costs fluctuate with Nordic metal exchange pricing, compressing margins on standardized open-frame units.
- GDPR sovereignty compliance:Cross-border data flow restrictions mandate certified domestic rack deployments, lengthening procurement cycles for international operators.
- Liquid cooling retrofit complexity:Legacy air-cooled facilities face technical barriers when upgrading to high-density configurations, limiting addressable market for advanced rack tiers.
Strategic Opportunities
- Stavanger-Bergen enterprise retrofit corridor:Oil and gas sector data centers present untapped demand for modular enclosure systems engineered for North Sea climate extremes.
- Carbon disclosure mandate alignment:The EU Green Deal's embodied carbon reporting requirements favor aluminum suppliers with verified low-carbon smelting processes.
- Edge computing convergence:5G infrastructure rollout is unifying telecom and cloud rack specifications, creating hybrid procurement channels for multi-tenant facilities.
Industry Challenges
- Thermal engineering talent scarcity:Liquid-cooling system design expertise concentrates among a limited pool of Nordic specialists, constraining deployment velocity.
- Datacenter Energy Efficiency Code certification timelines:Third-party validation for rack-level power usage effectiveness adds 8-14 weeks to project schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norway Data Center Rack Market |
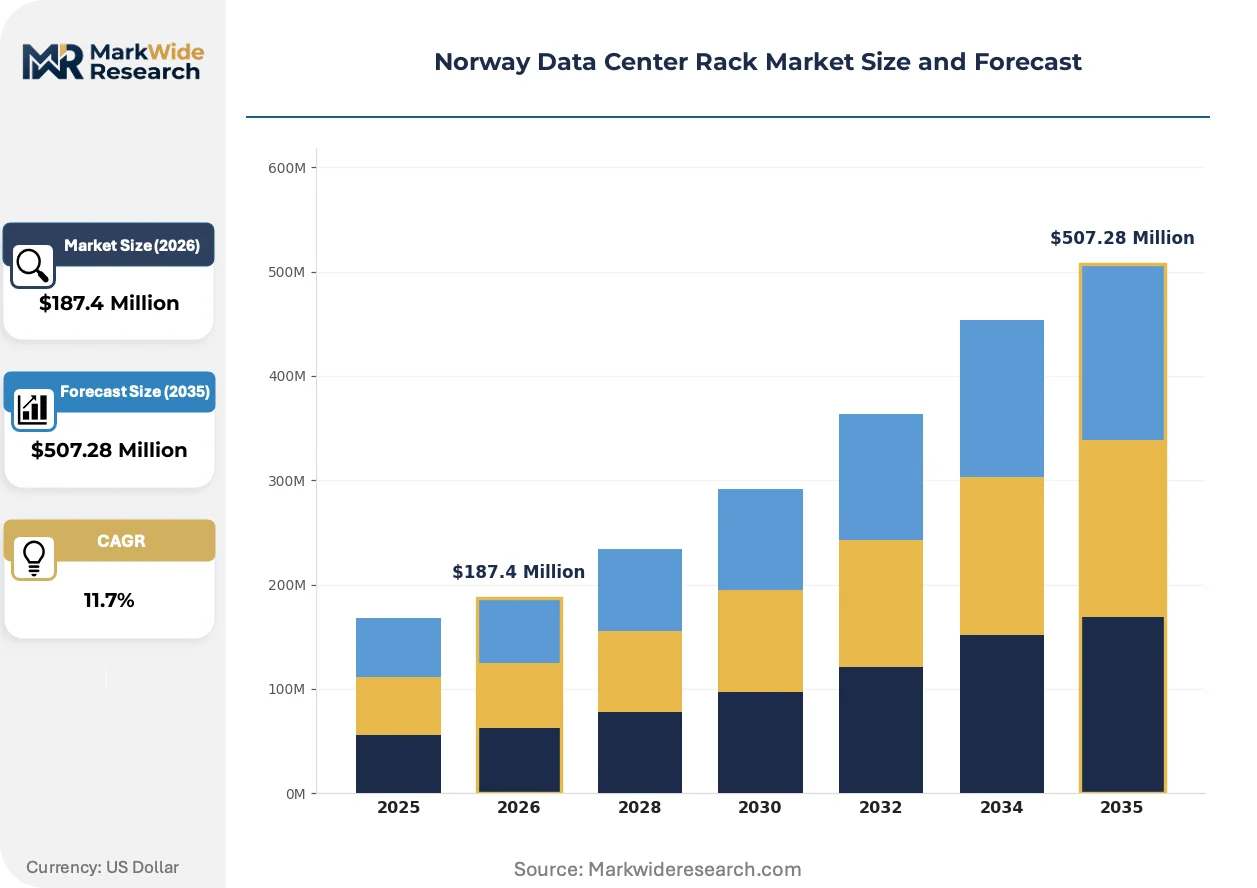
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Frame, Enclosed Rack, Wall-Mount Rack, Heavy-Duty Rack End User: Cloud Service Providers, Telecom Operators, Enterprises, Government Agencies Application: Data Storage, Network Management, Server Hosting, IT Infrastructure Installation: On-Premises, Co-Location, Modular, Hybrid |
| Companies Covered | Schneider Electric SE, Eaton Corporation, Rittal GMBH & Co.KG, Black Box Corporation, Hewlett Packard Enterprise (HPE), Vertiv Group Corp., Legrand, Panduit Corp., Tripp Lite, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norway Data Center Rack Market Trends and Innovations
Rack-level infrastructure is converging with facility-wide thermal and power management systems, eroding the boundary between enclosure hardware and building automation. This integration is compressing vendor margins while elevating specification complexity.
Immersion-ready rack architectures are unifying compute and cooling infrastructure into single-envelope designs. Hyperscale operators in the Oslo corridor are adopting these systems at accelerated pace to support GPU clusters exceeding 50kW per rack. The technology is unifying what were previously separate procurement categories—enclosure, power distribution, and thermal management—into consolidated vendor relationships that favor integrated suppliers.
Norway's transposition of the EU Energy Efficiency Directive into national building codes is mandating real-time power usage effectiveness monitoring at the rack level. Industrial consequence includes mandatory sensor integration in all new deployments above 500kW facility capacity. Enterprise retrofit projects in Bergen and Stavanger face the steepest compliance costs, driving preference toward pre-certified modular enclosure systems that bundle monitoring hardware.
Specification authority is migrating from facility engineering teams to sustainability procurement functions within cloud and telecom operators. Rack vendors now compete on embodied carbon documentation and circular material passports rather than purely on load-bearing metrics. This shift is most visible among hyperscale operators landing capacity in Vestland, where environmental disclosure requirements feature prominently in request-for-proposal scoring matrices.
Norway Data Center Rack Market Segmentation
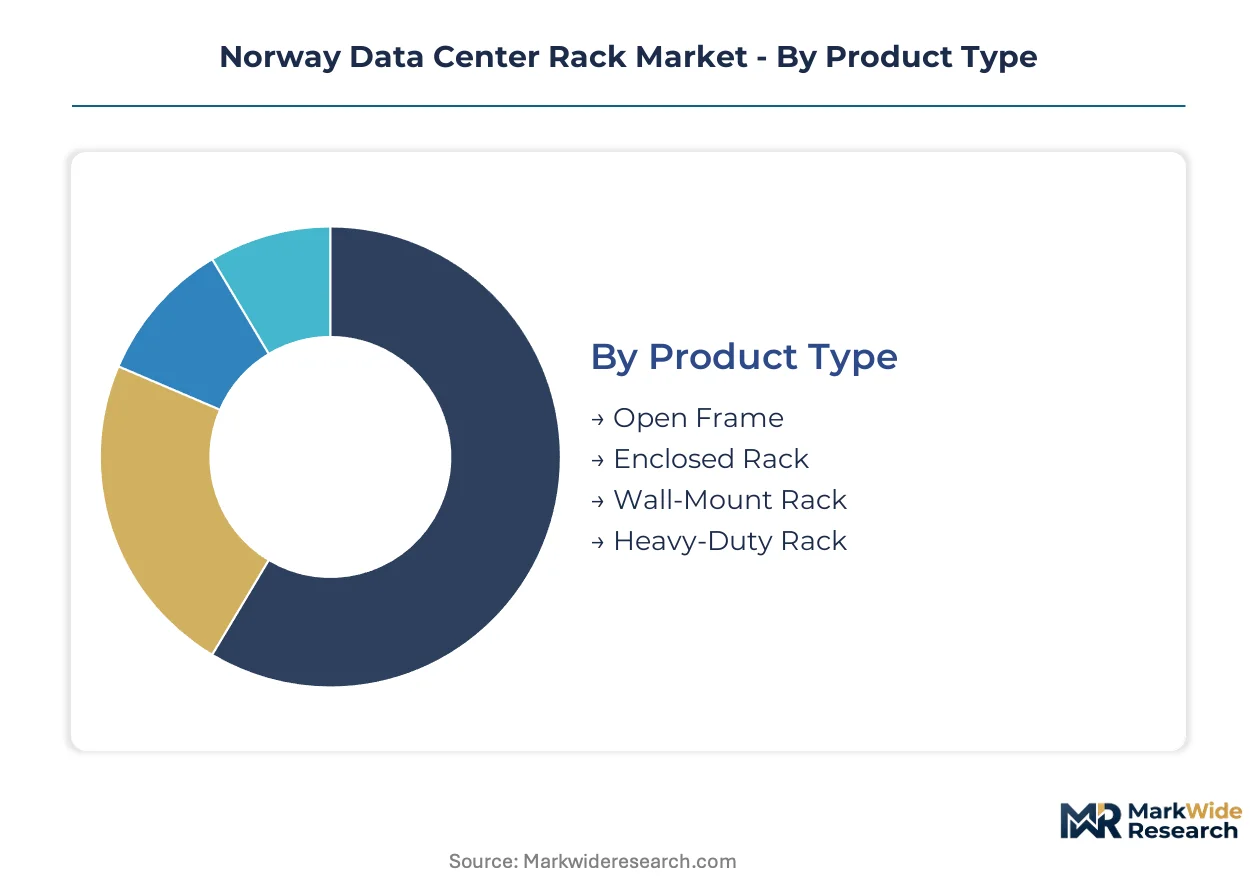
Norwegian data center rack procurement diverges sharply across deployment contexts, with hyperscale cloud facilities demanding liquid-cooled heavy-duty configurations while enterprise retrofits prioritize modular retrofit compatibility. Segmentation patterns reflect the tension between Oslo corridor hyperscale standardization and Stavanger-Bergen legacy infrastructure constraints.
Product Type:
Standardization pressure from hyperscale procurement dominates open-frame and enclosed rack specifications, while heavy-duty and wall-mount variants retain customization flexibility for specialized thermal and spatial requirements.
- Enclosed Rack:Fully sealed metal enclosures with integrated thermal containment and cable management systems support power usage effectiveness mandates under Norway's EU Energy Efficiency Directive transposition. Hyperscale operators in the Oslo metropolitan corridor specify these units for GPU-intensive workloads exceeding 50kW per rack, driven by liquid-cooling compatibility requirements and submarine cable landing proximity.
- Heavy-Duty Rack:Reinforced steel frameworks engineered for static loads surpassing 1,500 kilograms accommodate dense server configurations and battery backup systems. Demand concentrates in Vestland hyperscale facilities where renewable hydropower availability attracts foreign direct investment into sustainable data infrastructure with extended equipment lifecycles.
- Open Frame:Four-post skeletal structures without side panels prioritize airflow and cost efficiency for low-density deployments.
- Wall-Mount Rack:Compact hinged or fixed enclosures designed for edge computing nodes and constrained facility footprints.
Leading the category by volume: Enclosed Rack. Growing fastest: Heavy-Duty Rack.
End User:
Procurement authority varies dramatically across buyer types, with cloud service providers consolidating specifications through centralized sustainability procurement functions while government agencies navigate GDPR sovereignty compliance delays.
- Cloud Service Providers:Hyperscale operators drive specification convergence through consolidated vendor relationships bundling enclosure, power distribution, and thermal management. These buyers dominate rack demand in the Lofoten and Vestland corridors, prioritizing embodied carbon documentation and circular material passports over pure load-bearing metrics.
- Telecom Operators:5G infrastructure rollout is unifying cloud and telecom rack specifications, creating hybrid procurement channels for multi-tenant facilities. Telenor and regional carriers concentrate deployment in Oslo metropolitan edge nodes where submarine cable landings intersect with renewable energy availability.
- Enterprises:Oil and gas sector data centers in the Stavanger-Bergen corridor present retrofit demand for modular enclosure systems engineered for North Sea climate extremes.
- Government Agencies:National data center strategy alignment with GDPR sovereignty requirements restricts cross-border data flow infrastructure to certified domestic rack deployments, lengthening procurement cycles.
Cloud Service Providers command the largest procurement volume. Telecom Operators are expanding most quickly through 5G-edge convergence.
Application:
Application-driven segmentation reflects workload thermal profiles, with server hosting and data storage commanding premium containment configurations while network management tolerates open-frame economics.
- Server Hosting:GPU-intensive artificial intelligence and high-performance computing clusters demand liquid-cooling-ready rack architectures with real-time power usage effectiveness monitoring. Oslo corridor facilities lead deployment volume, mandated by national building codes for installations above 500kW capacity.
- Data Storage:Mass storage arrays prioritize vibration isolation and extended load-bearing specifications for disk-heavy configurations. Enterprise retrofits in Bergen and Stavanger favor pre-certified modular systems that bundle monitoring hardware to minimize compliance costs.
- Network Management:Switch and router housing emphasizes cable density and front-to-rear airflow optimization over thermal containment.
- IT Infrastructure:Mixed compute environments require flexible mounting rails and tool-less component access for operational agility.
Server Hosting leads application volume. Data Storage shows the steepest expansion trajectory as sovereign cloud requirements intensify.
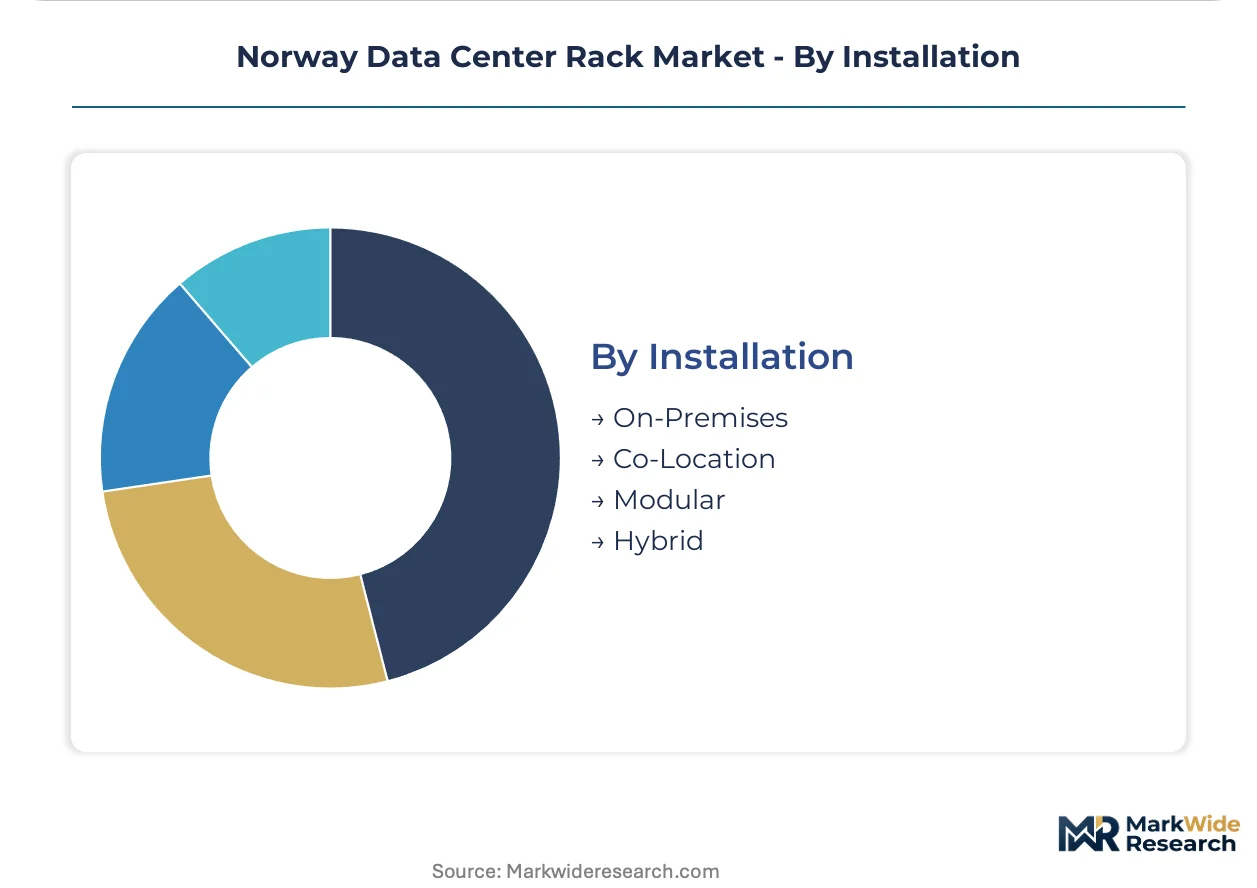
Installation:
Deployment mode selection determines rack specification flexibility, with co-location and hybrid installations standardizing around multi-tenant compatibility while on-premises retains customization scope.
- Co-Location:Multi-tenant facilities mandate standardized rack footprints and power density tiers to enable tenant mobility and cross-connect flexibility. Oslo metropolitan providers dominate this segment, leveraging submarine cable landings and hydropower cost arbitrage to attract international operators.
- Modular:Prefabricated data center modules require rack systems engineered for transport vibration tolerance and rapid field assembly. North Sea oil and gas sector adoption in the Stavanger-Bergen corridor drives demand for climate-extreme rated enclosure systems.
- On-Premises:Enterprise-owned facilities retain specification autonomy for specialized workload optimization.
- Hybrid:Split deployments combining owned and leased capacity demand rack compatibility across facility types.
Co-Location captures the largest installation volume. Modular deployment is gaining share fastest through prefabricated facility adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oslo metropolitan corridor concentrates Norway's data center rack demand through submarine cable landings and renewable hydropower convergence. Foreign direct investment flows into this corridor where electricity rates undercut continental European pricing. The national data center strategy shapes deployment patterns across five distinct sub-regions.
Oslo Metropolitan Corridor
Hyperscale cloud operators drive liquid-cooled rack specifications exceeding 50kW per rack for GPU-intensive workloads. EU Energy Efficiency Directive transposition mandates real-time power usage effectiveness monitoring for facilities above 500kW capacity. Lofoten and Vestland cable landings pull procurement toward high-density configurations with liquid-cooling compatibility.
Stavanger-Bergen Corridor
Oil and gas sector data centers generate retrofit demand for modular enclosure systems engineered for North Sea climate extremes. Datacenter Energy Efficiency Code certification timelines add 8-14 weeks to project schedules in this legacy infrastructure zone. Enterprise facilities here favor pre-certified modular systems that bundle monitoring hardware to minimize compliance costs.
Vestland Region
Foreign direct investment concentrates in facilities where renewable hydropower availability supports sustainable data infrastructure with extended equipment lifecycles. GDPR sovereignty requirements restrict cross-border data flow infrastructure to certified domestic rack deployments. Hyperscale operators landing capacity here prioritize embodied carbon documentation and circular material passports over pure load-bearing metrics.
Trøndelag
Edge computing nodes for 5G infrastructure rollout create hybrid procurement channels unifying telecom and cloud rack specifications. Telenor and regional carriers concentrate deployment where submarine cable landings intersect with renewable energy availability. Modular prefabricated data center modules require rack systems engineered for transport vibration tolerance and rapid field assembly.
Northern Norway
Arctic climate conditions drive specification requirements for thermal containment efficiency in enclosed rack categories. National building codes mandate power usage effectiveness thresholds that favor advanced containment systems over open-frame alternatives. Limited thermal engineering talent scarcity for liquid-cooling system design constrains deployment velocity in this emerging corridor.
Norway Data Center Rack Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Norway's data center rack market. Integrated power and cooling portfolio vendors dominate enterprise retrofit projects, while specialized enclosure fabricators capture modular deployment niches. Three archetypes define competitive positioning: integrated infrastructure conglomerates, modular enclosure specialists, and power distribution-focused suppliers. Capacity expansion into liquid-cooling-ready architectures and strategic partnerships for carbon disclosure compliance represent dominant competitive moves.
Within the integrated infrastructure tier, Schneider Electric SE anchors positioning through bundled power, cooling, and enclosure solutions. Eaton Corporation occupies a position among power distribution-focused suppliers, exemplifying the archetype of vendors leveraging advanced PDU technology to secure rack enclosure relationships. Rittal GMBH & Co.KG represents modular enclosure specialists, sitting within the tier of fabricators engineering systems for extreme climate applications. These three entities collectively illustrate how vendor consolidation around liquid-cooled and high-density configurations is compressing margins for standardized open-frame alternatives.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Eaton Corporation |
| Rittal GMBH & Co.KG |
| Black Box Corporation |
| Hewlett Packard Enterprise (HPE) |
| Vertiv Group Corp. |
| Legrand |
| Panduit Corp. |
| Tripp Lite |
| Others |
Pricing and Supply Chain Analysis
Liquid-cooling system design expertise concentrated among Nordic thermal engineering specialists in Oslo and Trondheim creates labor-cost differentials that widen pricing-tier spreads between premium liquid-cooled rack configurations and commodity open-frame alternatives. Norway's EU Energy Efficiency Directive transposition intensifies this spread by mandating power usage effectiveness monitoring that only advanced containment systems satisfy.
Pricing Analysis
Value-based pricing anchored to guaranteed power usage effectiveness outcomes dominates the Norwegian data center rack market. Three-tier pricing structure across premium, standard, and economy levels separates liquid-cooled heavy-duty enclosures with real-time monitoring from basic open-frame units. Price differentiation rests on certification grade under the Datacenter Energy Efficiency Code and embodied carbon documentation for aluminum enclosures. Pricing pressure stems from aluminum and steel input volatility on Nordic metal exchanges. Enterprise retrofit buyers in Stavanger-Bergen exhibit highest price sensitivity, while hyperscale cloud operators in Vestland prioritize thermal performance over unit cost.
Supply Chain Analysis
Reverse-logistics flows for rack refurbishment and component remanufacturing are emerging as supply chain differentiators in Norway's sustainability-mandated procurement environment. Manufacturing concentration draws from Germany, China, and domestic Nordic fabricators for enclosure steel and aluminum. Raw material dependencies center on low-carbon aluminum from Norwegian hydropower smelters, specialized cooling-grade copper tubing, and power distribution unit semiconductors. Single-source vulnerability concentrates in liquid-cooling component suppliers with limited Nordic representation. Distribution runs through direct hyperscale vendor relationships and regional system integrators serving enterprise retrofit corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Norway's data center rack market functions as a cost-of-compliance story where EU Energy Efficiency Directive transposition and GDPR sovereignty requirements create barrier-to-entry moats favoring vendors with pre-certified modular systems and domestic manufacturing footprints.
For Market Incumbents: To counter margin compression from standardized open-frame sourcing, Schneider Electric and Eaton should deepen backward integration into low-carbon aluminum smelting partnerships and expand liquid-cooling engineering capacity in the Oslo corridor. Certification investment under the Datacenter Energy Efficiency Code of Conduct represents the critical defensive lever for maintaining specification authority in hyperscale procurement. For New Entrants and Emerging Players: Direct-to-hyperscale digital sales channels bypass entrenched distributor relationships and enable rapid specification capture. Stavanger-Bergen enterprise retrofits present the most penetrable white-space, where oil and gas sector data centers demand modular enclosure systems engineered for North Sea climate extremes. A go-to-market angle bundling pre-certified monitoring hardware with climate-extreme rated enclosures minimizes compliance friction for legacy facility upgrades. For Investors and Strategic Acquirers: The window for entry favors modular enclosure specialists with verified low-carbon material passports and liquid-cooling system integration capabilities. Long-term viability over the next decade hinges on carbon disclosure mandate alignment as the EU Green Deal's embodied carbon reporting requirements intensify. The signal to watch is hyperscale operator request-for-proposal scoring matrices elevating environmental disclosure above pure load-bearing metrics.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid-Cooling System Integration | Unifies enclosure, power distribution, and thermal management into single-vendor relationships for hyperscale operators. |
| Low-Carbon Aluminum Sourcing Partnership | Aligns with EU Green Deal embodied carbon reporting requirements for rack-level environmental disclosure. |
| Datacenter Energy Efficiency Code Certification | Accelerates procurement cycles by pre-validating power usage effectiveness compliance for Norwegian deployments. |
| Stavanger-Bergen Retrofit Channel Development | Captures oil and gas sector demand for modular systems engineered to North Sea climate extremes. |
| Real-Time Monitoring Hardware Bundling | Addresses national building code mandates for rack-level power usage effectiveness tracking above 500kW facilities. |
Research Methodology
Trade association filings, Nordic metal exchange pricing data, and EU regulatory transposition documents formed the secondary backbone for this analysis. Primary interviews with data center facility engineering directors, hyperscale sustainability procurement leads, thermal system design specialists, and modular enclosure fabricators triangulated against secondary validation. Bottom-up rack deployment counts by corridor and top-down facility capacity estimates were cross-referenced to establish market sizing boundaries.
Historical trendline analysis of hyperscale capex disclosures and submarine cable landing timelines informed the projection framework. Segmentation modeling across product type, end user, application, and installation mode captured divergent procurement patterns between Oslo corridor hyperscale standardization and Stavanger-Bergen legacy constraints. CAGRs were derived from facility pipeline analysis and foreign direct investment flow trajectories. Key forecast inputs included hydropower electricity rate differentials and liquid-cooling adoption curves for GPU-intensive workloads.
The model holds under continued EU Energy Efficiency Directive enforcement and stable hydropower pricing; deviation in aluminum tariff regimes or liquid-cooling component supply disruptions would shift deployment velocity and vendor market share. Practitioners should monitor hyperscale operator embodied carbon scoring matrix weightings and Nordic thermal engineering talent migration patterns for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
France Data Center Rack Market
Data Center Infrastructure
Server Operating Environments Market
Data Center Infrastructure
Europe Containerized Data Center Market
Data Center Infrastructure
New Zealand Data Center Physical Security Market
Data Center Infrastructure
Vietnam Data Center Rack Market
Data Center Infrastructure
Asia-Pacific Data Center Power Market
Data Center Infrastructure
Blade Server Market
Data Center Infrastructure
Singapore Data Center Rack Market
Data Center Infrastructure
United Arab Emirates Data Center Market
Data Center Infrastructure
Ireland Data Center Rack Market
Data Center Infrastructure
DC Powered Servers Market
Data Center Infrastructure
Canada Data Center Storage Market
Data Center Infrastructure
Poland Data Center Rack Market
Data Center Infrastructure
France Data Center Storage Market
Data Center Infrastructure
Poland Data Center Construction Market
Data Center Infrastructure
Denmark Data Center Market