
 Thailand Data Center Rack Market | 2026-2036
Thailand Data Center Rack Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Data Center Rack Market Insights
High-density liquid cooling integration is reshaping rack architecture across Thai facilities. Schneider Electric SE leverages its regional manufacturing footprint to supply modular enclosures for tropical climates. Delta Electronics (Thailand) PCL anchors domestic production with localized sheet metal fabrication and power distribution integration. Rittal GmbH & Co. KG competes through precision thermal management systems designed for ambient temperatures exceeding thirty-five degrees Celsius.
A data center rack is a standardized metal framework that houses servers, networking equipment, and power distribution units, typically conforming to nineteen-inch mounting widths and load ratings up to fifteen hundred kilograms per cabinet. Its primary purpose is to optimize spatial efficiency, cable management, and cooling airflow within controlled facility environments. Enclosed rack configurations command premium positioning due to enhanced physical security and dust filtration requirements in Thailand's tropical conditions. Steel remains the dominant material category, though aluminum gains traction in edge deployments where weight reduction supports rapid site establishment. Colocation application demand outpaces enterprise-owned facilities as operators pursue operational flexibility.
Thailand's Board of Investment coordinates digital infrastructure incentives with the National Broadcasting and Telecommunications Commission licensing frameworks for data localization compliance. The Ministry of Digital Economy and Society enforces cybersecurity standards that mandate physical access controls, directly influencing rack-level biometric and surveillance specifications. Facility planners must evaluate cooling redundancy against evolving tropical design standards while monitoring Eastern Economic Corridor land allocation policies for expansion timing.
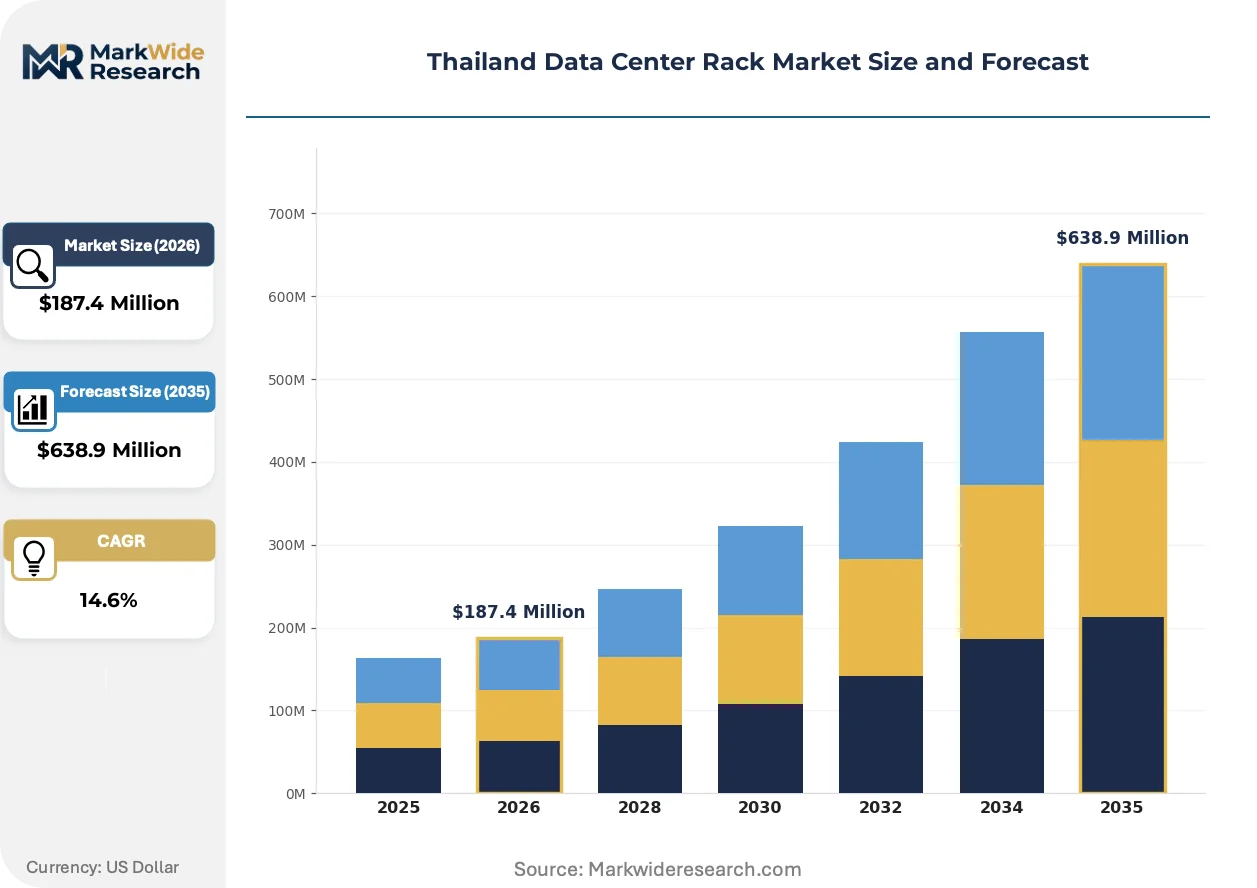
Market Dynamics
Hyperscale cloud expansion across Bangkok and the Eastern Economic Corridor is compressing deployment timelines and forcing rack suppliers to localize thermal engineering for tropical ambient conditions exceeding thirty-five degrees Celsius.
Growth Catalysts
- Board of Investment Incentives:Thailand's BOI digital infrastructure tax holidays and import duty exemptions for data center equipment are accelerating foreign direct investment into hyperscale facilities.
- Data Localization Mandates:The National Broadcasting and Telecommunications Commission licensing frameworks require domestic data storage, compelling financial services and e-commerce platforms to expand colocation footprints.
- Liquid Cooling Integration:High-density GPU deployments for AI workloads are driving rack architecture redesigns with integrated coolant distribution units and rear-door heat exchangers.
Market Restraints
- Steel Price Volatility:Cold-rolled steel sheet input costs fluctuate with regional commodity markets, compressing margins for domestic sheet metal fabricators serving rack enclosure production.
- Concentrated Component Supply:Intelligent power distribution unit controllers and precision cooling valves depend on concentrated East Asian semiconductor foundry output, creating single-source vulnerability.
- Tropical Design Standards Gap:Absence of unified ASHRAE-equivalent thermal guidelines for ambient humidity and particulate filtration forces redundant engineering across facility projects.
Strategic Opportunities
- Edge Micro-Data Centers:5G network densification across secondary Thai provinces creates demand for aluminum-framed, lightweight rack systems enabling rapid outdoor deployment.
- Biometric Access Integration:Ministry of Digital Economy and Society cybersecurity standards mandating physical access controls create attach-rate opportunities for rack-level fingerprint and facial recognition modules.
- Modular Factory Integration:Schneider Electric's regional manufacturing footprint demonstrates pathway for competitors to co-locate enclosure fabrication with power distribution assembly, compressing logistics costs.
Industry Challenges
- Thermal Engineering Talent Scarcity:Computational fluid dynamics modeling for tropical climate rack layouts requires specialized skill sets concentrated among Bangkok-based consulting firms, limiting facility design velocity.
- Legacy DCIM Integration Friction:New intelligent rack power monitoring systems must interoperate with existing data center infrastructure management platforms deployed by established colocation operators, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Data Center Rack Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Open Rack, Enclosed Rack, Static Rack, Mobile Rack Material: Steel, Aluminum, Composite, Plastic Application: Telecommunication, Cloud Computing, Colocation, Enterprise End User: SMBs, Large Enterprises, Government, Research Institutions |
| Companies Covered | Eaton Corporation plc, Dell Technologies Inc., Schneider Electric SE, nVent Electric plc, Hewlett Packard Enterprise Co., Rittal GmbH & Co. KG, Delta Electronics (Thailand) PCL, Legrand SA, Vertiv Group Corp., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Data Center Rack Market Trends and Innovations
Rack architecture in Thai facilities is converging around three vectors: thermal engineering for tropical extremes, embedded intelligence for remote operations, and procurement flexibility for hyperscale deployment cycles.
Immersive and direct-to-chip liquid cooling systems are digitizing rack-level thermal management by replacing perimeter CRAC dependency with precision coolant routing. Hyperscale operators in the Eastern Economic Corridor are specifying these systems for AI training clusters, compressing power usage effectiveness targets below industry legacy benchmarks.
Thailand's Ministry of Digital Economy and Society cybersecurity standards are mandating biometric access logging and environmental monitoring at the rack level. Colocation providers must retrofit existing enclosures or specify new builds with integrated surveillance and access control modules, accelerating supplier partnerships with security technology vendors.
Colocation buyers are compressing contract cycles from traditional five-year terms toward two-year agreements with expansion options. This flexibility demand forces rack suppliers to standardize modular configurations enabling rapid reconfiguration between single-tenant and multi-tenant layouts, with Bangkok financial services firms driving the shift.
Thailand Data Center Rack Market Segmentation
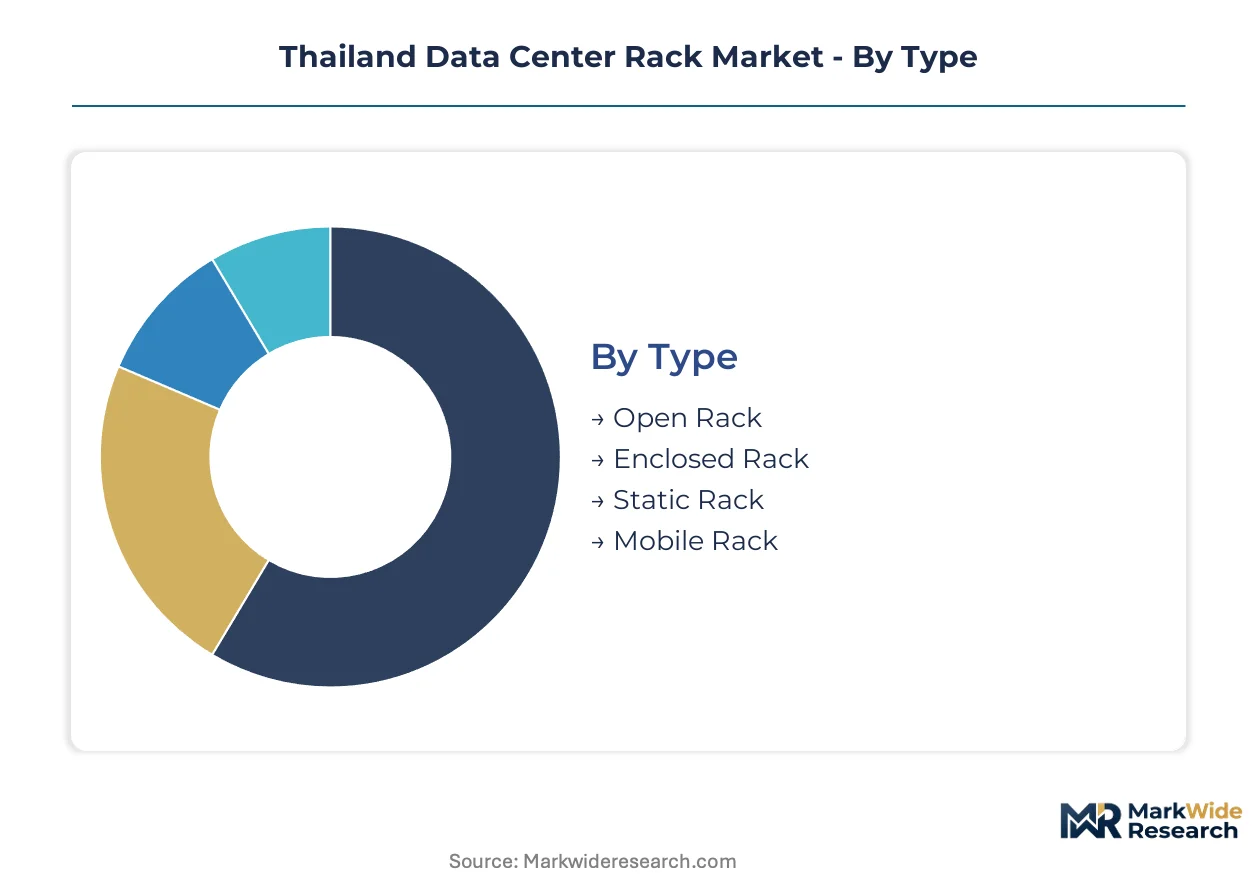
Segmentation reveals how rack specifications diverge across deployment contexts in Thailand's tropical climate. Material choices and enclosure types respond directly to cooling loads, security mandates, and facility ownership models.
Type:
Mature open-frame designs coexist with emerging intelligent enclosures as density requirements split the market.
- Open Rack:Four-post frameworks without side panels maximize airflow for standard-density server deployments. Demand concentrates in enterprise-owned facilities across Bangkok's industrial zones where perimeter cooling systems handle thermal loads.
- Enclosed Rack:Lockable cabinets with integrated cable management and dust filtration address tropical particulate concerns. Eastern Economic Corridor hyperscale operators specify these for multi-tenant security partitioning driven by Ministry of Digital Economy and Society compliance mandates.
- Static Rack:Fixed-position frameworks anchor traditional raised-floor data halls with load ratings up to fifteen hundred kilograms. These serve established colocation providers in central Bangkok.
- Mobile Rack:Castor-mounted enclosures enable rapid reconfiguration for edge micro-data centers. 5G infrastructure rollout across secondary Thai provinces drives specification.
Enclosed Rack retains volume leadership; Mobile Rack holds the steepest expansion curve.
Material:
Cost tiers separate commodity metals from performance alloys as weight and corrosion resistance trade off against unit economics.
- Steel:Cold-rolled carbon steel dominates through Delta Electronics' domestic sheet metal fabrication capacity. Bangkok-area fabricators supply standardized enclosures for cost-sensitive enterprise deployments.
- Aluminum:Lightweight extruded frames reduce shipping costs and enable rooftop or modular outdoor installations. Edge computing sites across Thailand's secondary cities favor these for rapid deployment timelines.
- Composite:Glass-reinforced polymer panels offer electromagnetic interference shielding with reduced thermal mass. Niche adoption appears in research institutions with specialized equipment isolation requirements.
- Plastic:Polycarbonate and ABS housings serve low-density networking closets and temporary installations. SMBs in provincial commercial centers specify these for budget-constrained refresh cycles.
Steel commands the largest installed base; Aluminum gains share fastest in new construction.
Application:
Customer type determines rack intelligence requirements and procurement flexibility terms.
- Telecommunication:Nineteen-inch standard frames house baseband units and radio access network equipment. National Broadcasting and Telecommunications Commission licensing frameworks mandate domestic infrastructure deployment.
- Cloud Computing:Hyperscale operators in the Eastern Economic Corridor specify liquid-cooling-ready enclosures with integrated coolant distribution. AI training cluster density requirements drive thermal engineering specifications.
- Colocation:Multi-tenant facilities demand biometric-access-equipped cabinets with remote environmental monitoring. Financial services firms in Bangkok compress contract terms toward two-year agreements with expansion options.
- Enterprise:Single-organization facilities prioritize operational control over flexibility. Manufacturing and logistics conglomerates maintain owned infrastructure in Bangkok metropolitan area industrial parks.
Colocation absorbs the greatest deployment volume; Cloud Computing climbs the fastest.
End User:
Volume scale and compliance sensitivity segment procurement behavior across organizational categories.
- SMBs:Small and medium businesses prioritize capital expenditure minimization through standardized open-frame racks. Provincial commercial centers outside Bangkok concentrate this demand.
- Large Enterprises:Banking and e-commerce platforms expand colocation footprints to satisfy data localization requirements. These buyers negotiate modular configurations enabling rapid reconfiguration.
- Government:Ministry of Digital Economy and Society cybersecurity standards mandate physical access controls and environmental logging. Government data centers specify integrated surveillance modules.
- Research Institutions:Universities and national laboratories deploy high-density liquid-cooled enclosures for computational research. Specialized thermal engineering requirements limit supplier options.
Large Enterprises drive the majority of current procurement; Government segment shows the steepest specification upgrade trajectory.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand exports data center rack systems and thermal engineering expertise to neighboring Southeast Asian markets while importing precision cooling components and intelligent power distribution controllers from East Asian semiconductor foundries. Cross-border supply chains link Bangkok fabricators with Vietnamese and Indonesian facility developers seeking tropical-climate rack specifications.
Bangkok Metropolitan Region
Financial services and e-commerce platforms drive colocation demand across central Bangkok industrial zones. The Ministry of Digital Economy and Society enforces cybersecurity standards mandating biometric rack-level access controls. Lat Phrao and Ratchada districts concentrate hyperscale cloud deployments with liquid-cooling-ready enclosures.
Eastern Economic Corridor
Hyperscale operators compress deployment timelines for AI training clusters requiring high-density thermal management. Thailand's Board of Investment coordinates tax holidays and import duty exemptions for data center equipment. Chonburi and Rayong provinces anchor foreign direct investment flows into modular factory-integrated rack production.
Northern Thailand
Edge computing sites for 5G network densification create demand for lightweight aluminum-framed rack systems. Provincial commercial centers outside the capital prioritize capital expenditure minimization through standardized open-frame configurations. Chiang Mai and Chiang Rai serve as logistics hubs for secondary city micro-data center rollouts.
Central Plains Industrial Zone
Manufacturing and logistics conglomerates maintain enterprise-owned facilities with operational control priorities over procurement flexibility. Ayutthaya and Pathum Thani host established colocation providers serving supply chain digitization requirements. Delta Electronics anchors domestic sheet metal fabrication capacity for steel enclosure production.
Southern Coastal Provinces
Telecommunications infrastructure deployment concentrates in Songkhla and Phuket for submarine cable landing station resilience. National Broadcasting and Telecommunications Commission licensing frameworks mandate domestic data storage for regional connectivity nodes. Baseband unit housing demands standard nineteen-inch frames for radio access network equipment.
Thailand Data Center Rack Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Thailand's data center rack supply base. The market exhibits moderate concentration with multinational industrial conglomerates holding premium-tier positions alongside domestic fabricators serving cost-sensitive segments. Three archetypes dominate: integrated power and thermal infrastructure providers, precision enclosure specialists, and regional sheet metal fabricators with localized assembly capacity. Competitive moves center on co-located manufacturing investments and modular configuration standardization for rapid reconfiguration between deployment contexts.
Among multinational infrastructure providers, Schneider Electric SE and Eaton Corporation plc occupy positions emphasizing integrated power distribution and thermal management systems. Delta Electronics (Thailand) PCL exemplifies the domestic fabrication archetype with captive sheet metal processing and localized supply chain integration. Rittal GmbH & Co. KG represents precision thermal engineering specialization for tropical ambient conditions exceeding standard temperate-zone specifications. These three anchors illustrate the competitive spectrum from global integrated solutions to regional manufacturing depth and climate-specific engineering focus.
| Leading Market Players |
|---|
| Eaton Corporation plc |
| Dell Technologies Inc. |
| Schneider Electric SE |
| nVent Electric plc |
| Hewlett Packard Enterprise Co. |
| Rittal GmbH & Co. KG |
| Delta Electronics (Thailand) PCL |
| Legrand SA |
| Vertiv Group Corp. |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in domestic sheet metal fabrication across Thailand's Central Plains is compressing supplier margins while forcing hyperscale buyers toward premium-tier liquid-cooling-ready enclosures. Board of Investment tax holidays for imported precision cooling components are shifting procurement calculus toward hybrid sourcing models that blend local steel enclosure assembly with East Asian semiconductor controller imports.
Pricing Analysis
Current-generation liquid-cooling-ready rack systems command substantial premiums over prior-generation air-cooled frameworks and next-generation immersive cooling prototypes still in pilot deployment. Pricing stratifies across premium, standard, and economy tiers where premium positioning reflects integrated biometric access modules and tropical-grade thermal engineering certification. Cost compression in the standard tier is intensifying because Delta Electronics' captive sheet metal capacity is flooding Bangkok industrial zones with commoditized steel enclosures. Small and medium businesses in provincial commercial centers exhibit the highest price sensitivity, while Eastern Economic Corridor hyperscale operators prioritize thermal performance over unit economics.
Supply Chain Analysis
Tariff exposure between Thailand and China dominates supply chain risk calculus for intelligent power distribution unit controllers and precision cooling valves. Manufacturing concentration centers on Thailand for steel enclosure fabrication, Taiwan for semiconductor foundry output, and Japan for precision thermal management components. Raw material dependencies rest on cold-rolled carbon steel sheet, aluminum extrusion billets, and glass-reinforced polymer composites. Single-source vulnerability in East Asian semiconductor controller supply creates procurement fragility for rack-level intelligence modules. Distribution runs through direct OEM relationships for hyperscale deployments and tiered distributor networks for enterprise and SMB segments.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's data center rack market operates as a defensive-moat story where regulatory entrenchment through Board of Investment licensing frameworks and Ministry of Digital Economy and Society cybersecurity mandates creates substantial switching costs for established facility operators.
For Market Incumbents: Build regulatory compliance moats by deepening certification investments for tropical-grade thermal engineering standards and biometric access integration. Incumbent suppliers should anchor capacity addition in Chonburi and Rayong provinces to compress logistics costs for Eastern Economic Corridor hyperscale deployments. The emergence of lightweight aluminum-framed edge systems from regional competitors threatens premium positioning in secondary city micro-data center segments. Vertical integration into localized power distribution assembly, demonstrated by Schneider Electric's regional manufacturing footprint, remains the critical lever for margin defense against domestic fabricators. For New Entrants and Emerging Players: Pursue white-space capture in Northern Thailand's 5G edge computing sites where aluminum-framed mobile rack demand is outpacing incumbent supply capacity. The most penetrable segment lies in provincial commercial centers outside Bangkok where SMBs prioritize capital expenditure minimization through standardized open-frame configurations. A direct-to-facility-developer go-to-market angle, bypassing established distributor networks, enables rapid site establishment and specification capture before incumbent relationships solidify. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among colocation operators with multi-tenant biometric-equipped cabinet deployments and compressed two-year contract cycles with expansion options. Long-term viability across the analysis window hinges on thermal engineering talent scarcity resolution and liquid cooling integration attach rates. Acquisition targets should emphasize domestic fabricators with captive sheet metal processing and localized supply chain integration. The signal to watch is hyperscale operator specification shifts toward factory-integrated modular rack systems with embedded coolant distribution units.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Factory Integration | Co-located enclosure fabrication with power distribution assembly compresses logistics costs for Eastern Economic Corridor deployments. |
| Liquid Cooling Partnership | Collaboration with precision cooling valve suppliers addresses single-source vulnerability in East Asian semiconductor foundry dependency. |
| Biometric Access Certification | Ministry of Digital Economy and Society compliance investment creates attach-rate expansion for rack-level security module suppliers. |
| Aluminum Framing Capacity Expansion | Lightweight extrusion capability enables rapid deployment timelines for 5G edge micro-data centers across secondary Thai provinces. |
| Thermal Engineering Talent Development | Computational fluid dynamics training programs address Bangkok-based consulting firm concentration limiting facility design velocity. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with data center facility planners, thermal engineering consultants, colocation procurement officers, and Board of Investment licensing officials; and secondary validation against customs records, National Broadcasting and Telecommunications Commission licensing databases, hyperscaler capital expenditure disclosures, and Ministry of Digital Economy and Society regulatory filings. Bottom-up triangulation across facility deployment counts and rack-level specification data was cross-checked against top-down market sizing derived from steel and aluminum input material flows.
Forecast inputs incorporated rack density evolution, liquid cooling penetration curves, and hyperscale contract cycle compression patterns across the projection horizon. Segmentation dimensions modeled include enclosure type, material category, application context, and end-user organizational scale. CAGRs were derived from regression analysis against facility investment timelines and Board of Investment incentive uptake rates. Industry-specific inputs encompassed tropical climate thermal engineering standards evolution and data localization mandate enforcement intensity.
Sensitivities concentrate around steel price volatility, East Asian semiconductor supply disruption, and Board of Investment incentive renewal schedules. Forecasts reflect documented assumptions regarding hyperscale deployment velocity and edge computing infrastructure rollout timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Israel Data Center Server Market
Data Center Infrastructure
Paris Data Center Market
Data Center Infrastructure
Brazil Data Center Rack Market
Data Center Infrastructure
US Multi-Tenant (Colocation) Data Center Market
Data Center Infrastructure
Japan Data Center Market
Data Center Infrastructure
Chicago Data Center Market
Data Center Infrastructure
Data Center Containment Solution Market
Data Center Infrastructure
Middle East and Africa Containerized Data Center Market
Data Center Infrastructure
South America Data Center Power Market
Data Center Infrastructure
Mini Data Center Market
Data Center Infrastructure
Data Center Transfer Switches and Switchgears Market
Data Center Infrastructure
Middle East Data Center Power Market
Data Center Infrastructure
Server Station Market
Data Center Infrastructure
Europe Automated Storage and Retrieval System Market
Data Center Infrastructure
Public Cloud System Infrastructure Service Market
Data Center Infrastructure
Data Center Modeling and Simulation Tools Market