
 North America Green Data Center Market | 2026-2036
North America Green Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
North America Green Data Center Market Foresight
Green bond issuance and power purchase agreement financing is rewriting capital access for data center developers without utility-scale balance sheets. Microsoft Corporation leverages long-term renewable energy contracts to lock in zero-carbon power across its hyperscale fleet. Vantage Data Centers anchors its expansion strategy through pre-leased, build-to-suit facilities backed by infrastructure fund commitments. Equinix Inc. differentiates via interconnection density combined with 100% renewable energy coverage across its metro platform.
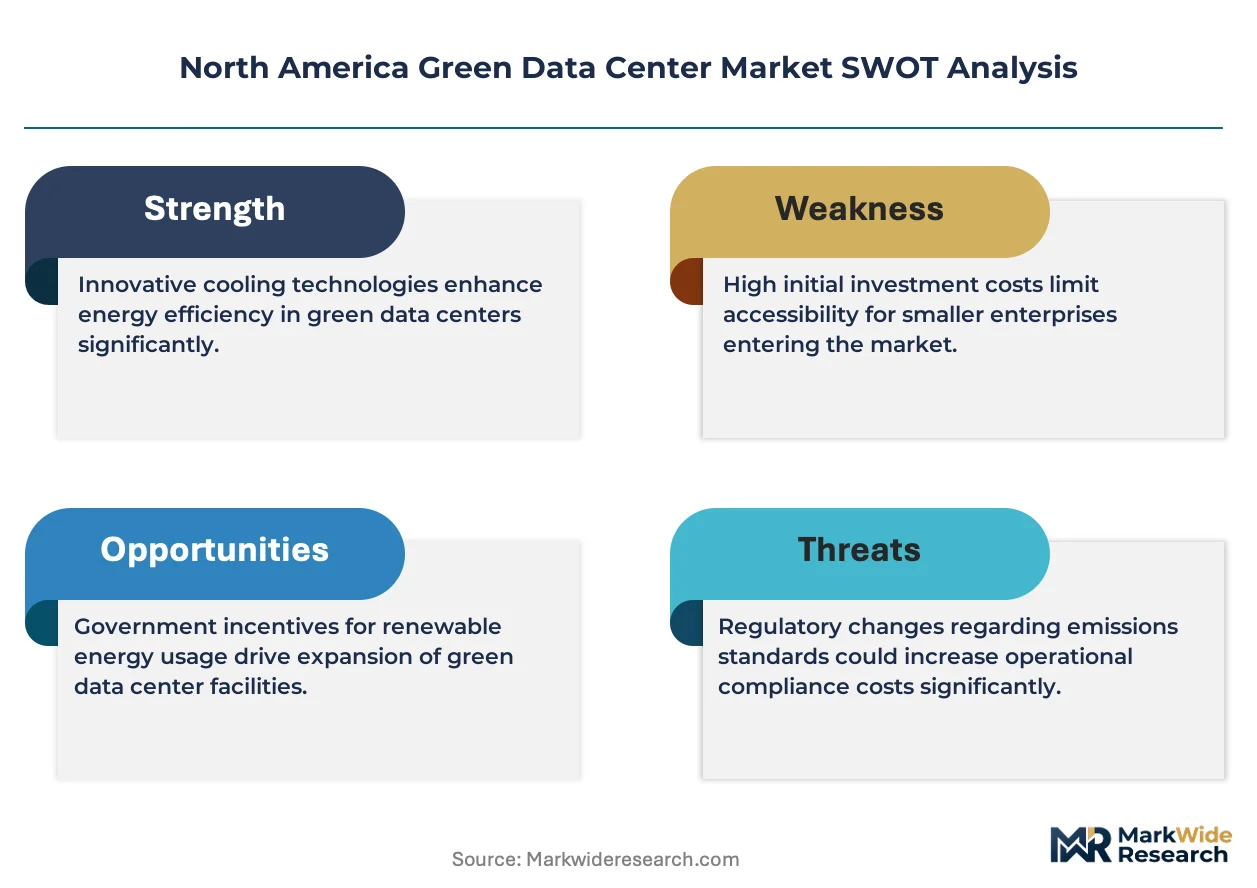
A green data center designates a facility engineered to minimize environmental impact through energy-efficient infrastructure, renewable power sourcing, and reduced water consumption, typically operating at power usage effectiveness ratios below 1.4 while deploying liquid cooling or free air exchange systems to manage thermal loads for high-density computing. Cooling Solutions technology leads capital deployment as chip thermal design power crosses 500 watts per processor, forcing abandonment of traditional raised-floor air conditioning. Colocation deployment occupies the fastest expansion track as enterprises exit owned facilities to meet carbon neutrality timelines without direct capital outlay.
EPA Energy Star certification and DOE Better Buildings Challenge establish efficiency benchmarks that filter market access for facility operators across the United States. FERC Order 2222 and state-level interconnection rules in Texas and California shape how behind-the-meter solar and battery storage integrate with data center loads. CSA Group standards in Canada add a second compliance layer for cross-border operators. Stakeholders must monitor whether proposed EPA greenhouse gas performance standards for existing power plants survive judicial review, as this determines the economic viability of on-site natural gas generation versus full grid-electrification strategies.
Market Dynamics
Hyperscale cloud procurement is concentrating sustainable colocation demand into pre-leased build-to-suit facilities, compressing development timelines and forcing traditional wholesale operators to restructure their capital stacks around green bond and power purchase agreement financing.
Growth Catalysts
- EPA Energy Star certification:Federal efficiency benchmarks filter market access for facility operators across the United States, accelerating retrofit investments in legacy server farms.
- Enterprise carbon neutrality timelines:Colocation deployment expands fastest as corporations exit owned facilities to meet Scope 3 emission targets without direct capital outlay.
- Dominion Energy clean power commitments:Northern Virginia's data center corridor benefits from utility-scale renewable procurement supporting massive server farm expansion.
Market Restraints
- Copper and electrical steel price volatility:Transformer and busbar input costs swing with commodity markets, squeezing margin on electrification retrofits.
- Liquid cooling equipment supply concentration:Precision cooling component manufacturing clusters in East Asian supplier networks, creating lead time vulnerability for North American projects.
- FERC interconnection queue delays:Behind-the-meter solar and battery storage projects face multi-year grid connection timelines in Texas and California ISO territories.
Strategic Opportunities
- Canadian hydroelectric zones:Quebec and British Columbia offer stranded clean power for hyperscale expansion with lower cooling loads from northern climate.
- AI training cluster demand:GPU-intensive workloads drive liquid cooling retrofit opportunities in existing air-cooled facilities.
- State renewable portfolio standards:California and Texas mandates create guaranteed offtake for data center-sited clean generation.
Industry Challenges
- Thermal engineering talent scarcity:Liquid cooling system design and computational fluid dynamics expertise concentrates among semiconductor and aerospace veterans.
- EPA greenhouse gas performance standard uncertainty:Judicial review of proposed existing power plant rules clouds economic viability of on-site natural gas versus full grid-electrification strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Green Data Center Market |
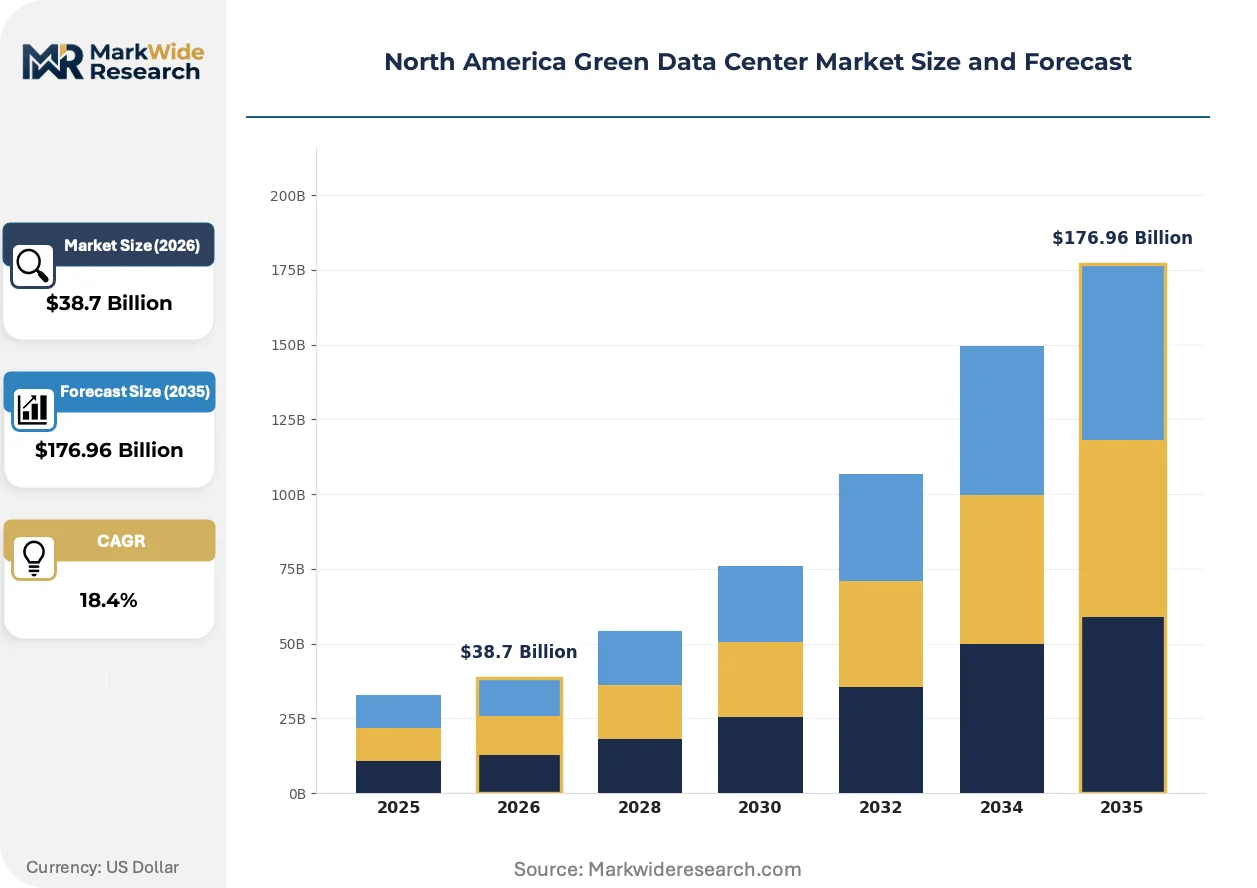
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $176.96 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Implementation, Maintenance, Management Technology: Virtualization, Cooling Solutions, Renewable Energy, Energy Management End User: IT, BFSI, Retail, Healthcare Deployment: On-premises, Cloud-based, Hybrid, Colocation |
| Companies Covered | Microsoft Corporation, Schneider Electric SE, Equinix Inc., Vantage Data Centers, Iron Mountain, Digital Realty Trust Inc., Google, IBM Corporation, Amazon Web Services, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Green Data Center Market Shifts & Advancements
Cooling architecture is migrating from air-based to liquid-based thermal management as chip thermal design power crosses thresholds incompatible with traditional raised-floor infrastructure. This shift compresses facility design cycles and rewires supplier relationships.
Immersion cooling is migrating from niche cryptocurrency mining to mainstream hyperscale deployment. Microsoft Corporation and Amazon Web Services pilot two-phase dielectric fluid systems for AI training clusters. The technology is migrating from experimental validation to pre-leased facility specifications, forcing traditional mechanical contractors to acquire new installation certifications.
California's Title 24 building energy efficiency standards now mandate solar readiness and battery storage pre-wiring for new data center construction. The regulation compresses permitting timelines for facilities that comply versus those requiring variance applications. Northern Virginia and Dallas-Fort Worth developers report accelerated entitlement processes for projects meeting these standards.
Enterprise buyers now require 100% renewable energy coverage and hourly carbon matching in colocation contracts, displacing annual renewable energy certificate purchases. Financial services and pharmaceutical verticals lead this specification. Texas ERCOT and California CAISO markets show the sharpest contract structure evolution toward time-matched clean power.
North America Green Data Center Market Segmentation
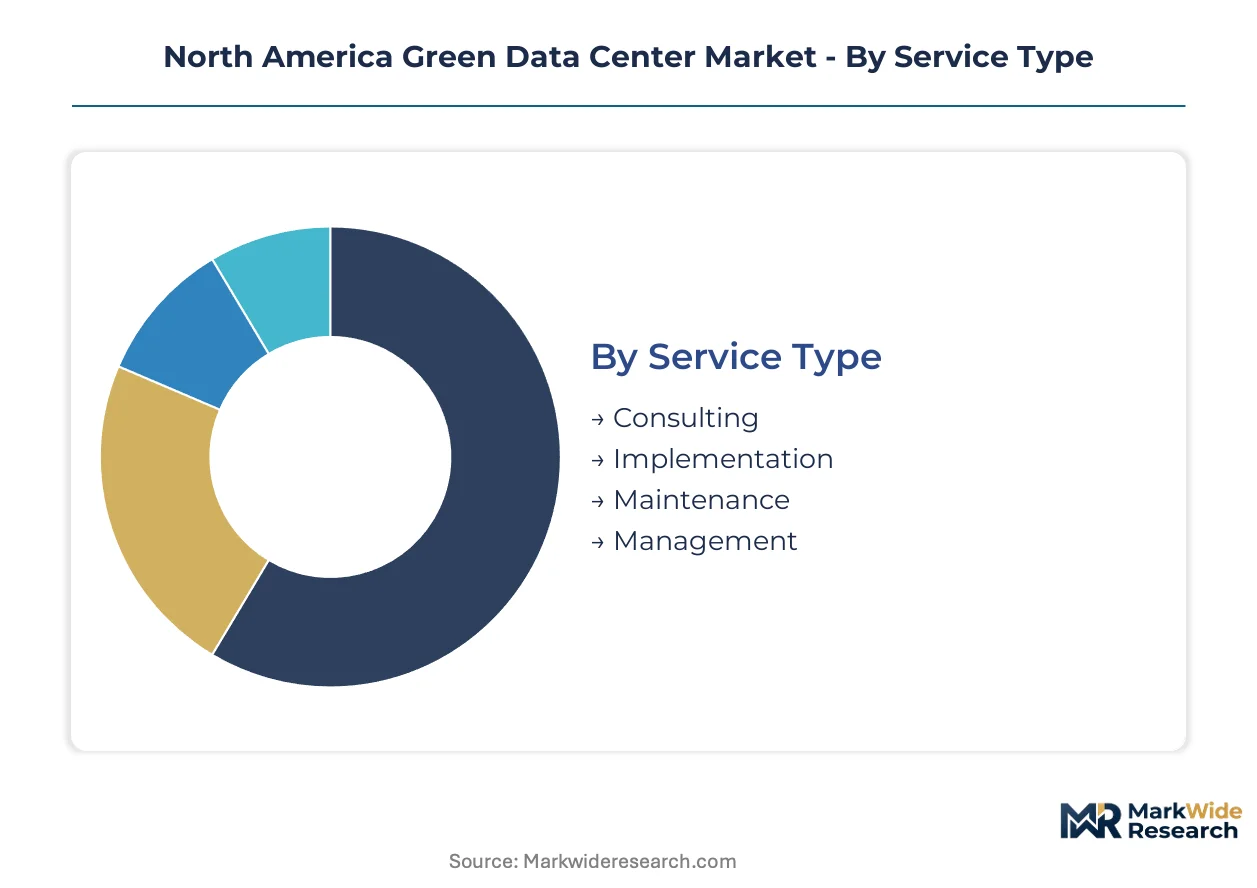
Green data center procurement patterns diverge sharply across service models and infrastructure types. Technology selection determines capital intensity and payback horizons. Deployment architecture dictates whether sustainability targets hit balance sheets directly or shift to third-party operators.
Service Type:
Implementation cycles compress from eighteen months for ground-up construction to six weeks for retrofit assessments, while management contracts stretch across decade-long terms with renewal escalators.
- Consulting:Energy audits and sustainability roadmapping dominate early-stage engagements. Financial services firms in New York and Toronto drive demand for Scope 3 emission baselining ahead of SEC and CSA Group disclosure mandates.
- Implementation:Physical infrastructure deployment including cooling retrofits, electrical upgrades, and renewable interconnection. Northern Virginia and Dallas-Fort Worth concentrate project volume as hyperscale pre-leasing accelerates construction timelines.
- Maintenance:Predictive thermal monitoring and equipment lifecycle management. EPA Energy Star certification compliance requires continuous commissioning protocols.
- Management:Full operational control including workload optimization and carbon accounting. Enterprise carbon neutrality timelines push outsourcing of facility operations to specialized operators.
Management dominates installed base. Implementation is where expansion concentrates.
Technology:
Capital allocation tilts toward thermal infrastructure as chip power densities render legacy air-cooling obsolete, while renewable energy procurement shifts from annual certificates to hourly carbon matching.
- Cooling Solutions:Liquid cooling systems and free air exchange architectures replace raised-floor air conditioning. GPU-intensive AI training clusters in California and Texas force abandonment of traditional mechanical infrastructure.
- Renewable Energy:Power purchase agreements and behind-the-meter solar plus storage. Dominion Energy clean power commitments in Virginia and ERCOT market structures in Texas shape offtake contract design.
- Virtualization:Software-defined infrastructure and container orchestration. IT and BFSI verticals deploy workload consolidation to compress server counts.
- Energy Management:Real-time monitoring platforms and demand response integration. FERC Order 2222 enables data center participation in wholesale ancillary service markets.
Cooling Solutions commands the largest capital draw. Renewable Energy is climbing the fastest as hourly matching requirements harden.
End User:
Procurement urgency varies by regulatory exposure and Scope 3 liability concentration.
- IT:Hyperscale cloud providers and SaaS operators. Carbon disclosure mandates and customer procurement requirements drive 100% renewable coverage specifications.
- BFSI:Banks, insurers, and asset managers. SEC climate disclosure rules and European CSRD alignment pressure accelerate colocation migration.
- Healthcare:Hospital systems and health insurers. HIPAA compliance constraints limit cloud migration, sustaining on-premises green retrofit demand.
- Retail:E-commerce platforms and brick-and-mortar chains. Seasonal demand volatility favors hybrid deployment with burst capacity into carbon-matched colocation.
IT anchors volume commitment. BFSI is gaining share fastest as disclosure rules tighten.
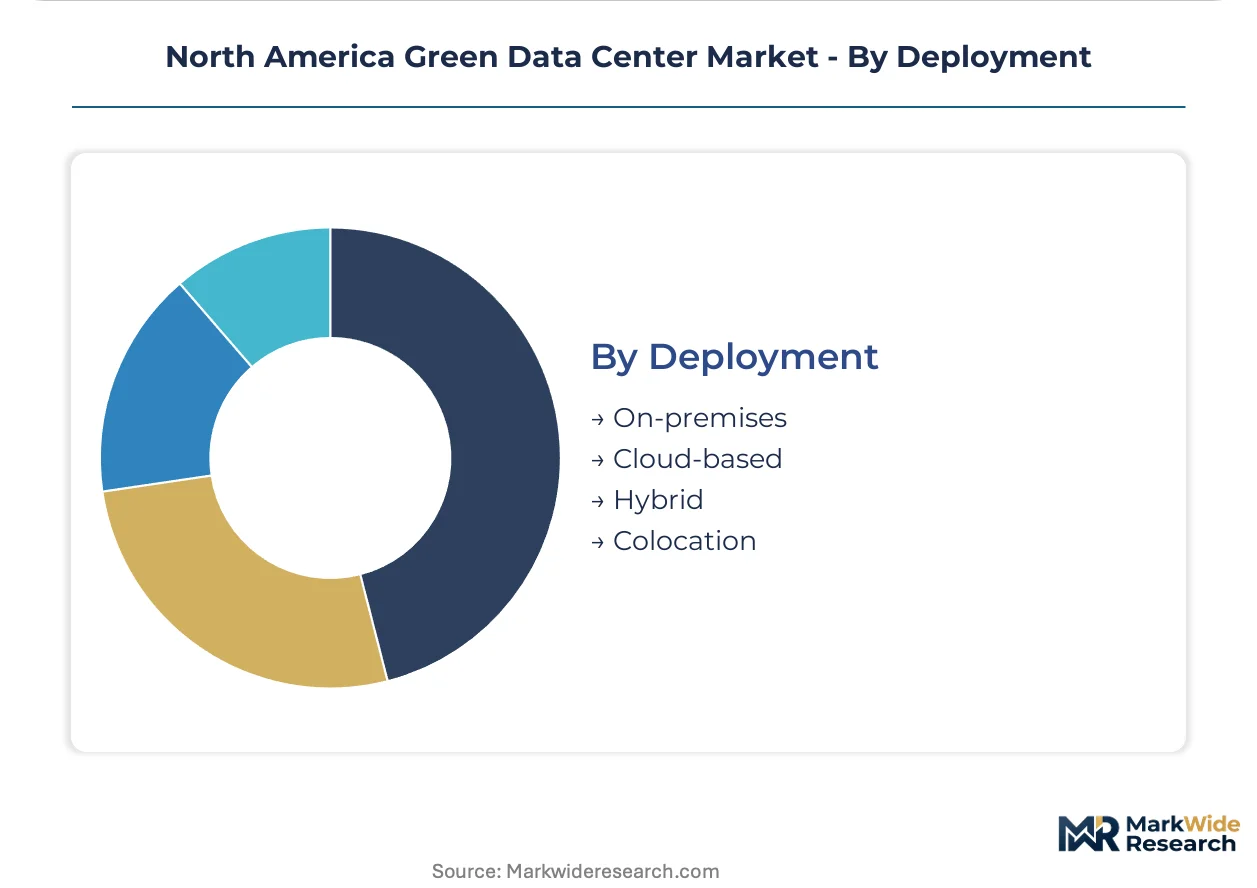
Deployment:
Balance sheet treatment and carbon accounting responsibility shift dramatically across architecture choices.
- Colocation:Third-party facility leasing with renewable energy pass-through. Enterprises exit owned assets to meet neutrality timelines without capital outlay.
- Cloud-based:Hyperscale provider infrastructure with shared sustainability attributes. Microsoft Corporation and Amazon Web Services compete on hourly carbon matching granularity.
- Hybrid:Split workloads across on-premises and cloud with unified carbon accounting. Pharmaceutical verticals deploy this architecture for regulatory data sovereignty.
- On-premises:Enterprise-owned facilities with direct retrofit investment. Legacy financial services and defense-adjacent workloads remain here due to security requirements.
On-premises retains the largest installed footprint. Colocation is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net import dependence for precision cooling equipment and electrical infrastructure shapes procurement strategies across North American data center corridors. Domestic manufacturing of liquid cooling components remains limited, forcing developers to manage East Asian supply chain exposure. Regional demand clusters around three primary jurisdictions with divergent regulatory and power market structures.
United States
Hyperscale cloud procurement concentrates in Northern Virginia, Dallas-Fort Worth, and Phoenix markets where Dominion Energy and ERCOT utilities offer renewable-heavy generation mixes. EPA Energy Star certification and DOE Better Buildings Challenge establish federal efficiency benchmarks that filter facility operator access. State renewable portfolio standards in California and Texas mandate clean power procurement, accelerating behind-the-meter solar plus storage deployment in Santa Clara and Austin metro corridors.
Canada
Quebec and British Columbia hydroelectric zones attract hyperscale expansion seeking stranded clean power with reduced cooling loads from northern climate conditions. CSA Group standards add compliance layering for cross-border operators serving US enterprise customers. Toronto and Montreal financial services clusters drive colocation demand for Scope 3 emission reporting aligned with CSA Group disclosure mandates and European CSRD alignment pressures.
Mexico
Querétaro and Mexico City metro areas emerge as nearshore alternatives for US enterprises seeking carbon-matched capacity with lower land and labor costs. Federal electricity commission restructuring and renewable energy auction mechanisms shape power procurement economics for foreign operators. Monterrey industrial corridor hosts initial hyperscale pilot projects leveraging existing manufacturing infrastructure and cross-border fiber connectivity.
North America Green Data Center Market Competitive Landscape
On the supply side, the industry is consolidating around hyperscale cloud operators and specialized colocation platforms with capital access through green bond and infrastructure fund channels. Tiered competitive structure separates vertically integrated cloud providers from wholesale colocation specialists and equipment system integrators. Dominant competitive moves include pre-leased build-to-suit development compression and renewable energy contract structuring for hourly carbon matching.
Within the hyperscale cloud tier, Microsoft Corporation and Amazon Web Services exemplify operators leveraging long-term renewable power purchase agreements to lock zero-carbon coverage across continental fleets. Equinix Inc. occupies a position representing interconnection-dense metro platforms with renewable energy pass-through structures. These three anchors demonstrate divergent capital deployment models: captive infrastructure development versus third-party facility leasing with sustainability attribute guarantees.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Schneider Electric SE |
| Equinix Inc. |
| Vantage Data Centers |
| Iron Mountain |
| Digital Realty Trust Inc. |
| IBM Corporation |
| Amazon Web Services |
| Others |
Supply & Pricing Matrix
Taiwan's precision cooling component manufacturing clusters anchor global liquid cooling supply, concentrating pricing power among East Asian suppliers and forcing North American developers to absorb freight premiums or accept extended lead times for thermal management infrastructure.
Pricing Analysis
Hyperscale cloud providers anchor contract-based long-term offtake pricing for renewable energy and colocation capacity, with differentiation driven by hourly carbon matching granularity and EPA Energy Star certification tier. Cost compression in air-cooled retrofit tiers is intensifying because GPU thermal loads render legacy mechanical infrastructure obsolete. Enterprise buyers in financial services show least price sensitivity, prioritizing Scope 3 emission compliance over per-kilowatt procurement costs.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for electrical steel and precision cooling components. Manufacturing concentrates in China, South Korea, and Taiwan for liquid cooling manifolds, dielectric fluids, and high-density busbar systems. Copper and electrical steel price volatility feeds into transformer and switchgear procurement timelines. Distribution runs through direct OEM relationships with hyperscale developers and tier-one mechanical contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Liquid cooling infrastructure migration represents a high-growth disruption as chip thermal design power crosses 500 watts, with FERC Order 2222 enabling new revenue streams from grid-interactive battery storage reshaping facility economics.
For Market Incumbents: Insulate market position through backward integration into precision cooling component supply and captive renewable energy development in Dominion Energy and ERCOT territories. Liquid cooling equipment supply concentration from East Asian sources threatens margin stability. Pre-leased build-to-suit development compression in Northern Virginia and Dallas-Fort Worth anchors volume commitment. For New Entrants and Emerging Players: Canadian hydroelectric zones in Quebec and British Columbia represent the most penetrable entry point for hyperscale capacity seeking stranded clean power with reduced cooling loads. AI training cluster retrofits in existing air-cooled facilities offer second white-space target. Hourly carbon matching expertise provides differentiated go-to-market positioning against annual renewable energy certificate competitors. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized colocation platforms with green bond capital access and interconnection-dense metro footprints. Long-term viability rests on hourly matching contract structures displacing legacy certificate procurement. The signal to monitor is EPA greenhouse gas performance standard judicial review outcomes determining on-site generation versus full electrification economics.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Structuring | Dominion Energy and ERCOT utilities enable hourly carbon matching for hyperscale cloud procurement. |
| Liquid Cooling Retrofit Deployment | GPU-intensive AI training clusters in California and Texas force abandonment of raised-floor air conditioning. |
| Green Bond Capital Raising | Infrastructure fund commitments support pre-leased build-to-suit facility compression in Northern Virginia. |
| Behind-the-Meter Solar Plus Storage | FERC Order 2222 enables data center participation in wholesale ancillary service markets. |
| Canadian Hydroelectric Expansion | Quebec and British Columbia stranded clean power offers lower cooling loads from northern climate conditions. |
Research Methodology
The analysis maps cooling solutions, renewable energy procurement, colocation deployment, and enterprise carbon accounting segments, each validated through data center facility operators, utility renewable energy planners, hyperscale cloud procurement officers, and thermal engineering specialists. Primary interview insights combined with secondary validation from EIA power market data, FERC interconnection filings, EPA Energy Star certification databases, and utility integrated resource plans. Bottom-up facility deployment tracking and top-down market sizing triangulate volume estimates.
Assumptions held fixed include state renewable portfolio standard enforcement trajectories in California and Texas, copper and electrical steel commodity price bands, and FERC Order 2222 implementation timelines across ISO territories. Modeled segmentation dimensions span service type, cooling technology tier, deployment architecture, and end-user vertical. CAGRs derive from facility pipeline tracking and utility interconnection queue analysis. Hyperscale pre-leasing velocity and liquid cooling adoption curves feed forecast sensitivity testing.
Stress conditions across EPA regulatory survival probability, East Asian supply chain disruption severity, and enterprise carbon neutrality deadline acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions with revision triggers tied to judicial review outcomes and commodity price regime shifts. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Norway Data Center Server Market
Data Center Infrastructure
Sweden Data Center Power Market
Data Center Infrastructure
Data Center Colocation and Managed Hosting Services Market
Data Center Infrastructure
Global Software Defined Infrastructure (SDI) Market
Data Center Infrastructure
Colocation Edge Data Center Market
Data Center Infrastructure
Data Center Containment Solution Market
Data Center Infrastructure
India Data Center Server Market
Data Center Infrastructure
New York Data Center Market
Data Center Infrastructure
Hong Kong Data Center Power Market
Data Center Infrastructure
Global Mega Data Center Market
Data Center Infrastructure
Thailand Data Center Market
Data Center Infrastructure
Sweden Data Center Physical Security Market
Data Center Infrastructure
Mexico Data Center Market
Data Center Infrastructure
Europe Data Center Colocation Market
Data Center Infrastructure
Hong Kong Data Center Server Market
Data Center Infrastructure
South Korea Data Center Market