
 Israel Data Center Rack Market | 2026-2036
Israel Data Center Rack Market Size, Share, and Industry Trends Forecast 2026-2036
Israel Data Center Rack Market Insights
Israel's National Cyber Directorate guidelines is consolidating physical security mandates for data center infrastructure, raising baseline compliance costs for new entrants. Schneider Electric leverages its integrated power and cooling portfolio to anchor premium rack deployments across Tel Aviv and Haifa corridors. Rittal competes through its modular enclosure systems designed for high-density Israeli climate conditions. Bynet Data Communications dominates local distribution channels with deep installer relationships and government contracting access.
Data center racks are standardized metal frameworks engineered to house servers, networking equipment, and power distribution units, typically conforming to 19-inch EIA-310 specifications for mounting rail spacing. These structures organize airflow management, cable routing, and load-bearing capacity up to 3,000 pounds per cabinet in enterprise configurations. Enclosed racks with integrated thermal containment lead product type demand as Israeli operators combat ambient temperature extremes. Edge computing deployment configurations represent the fastest-expanding segment as telecommunications providers distribute infrastructure toward cellular base stations and remote enterprise sites. Colocation deployments sustain mature growth patterns with established margin pools concentrated in Tel Aviv's central business district.
The Israel Standards Institute enforces structural and electrical safety certifications for rack-mounted equipment, while the National Cyber Directorate mandates physical access logging and biometric controls for critical infrastructure facilities. These overlapping requirements push buyers toward integrated rack-security systems rather than commodity frames. Stakeholders must monitor whether proposed amendments to national data localization rules will force additional domestic rack capacity commitments from multinational cloud operators.
Market Dynamics
Israel's National Cyber Directorate physical security mandates are compressing procurement timelines and elevating rack-security integration requirements for all new data center builds. This regulatory pressure is restructuring supplier qualification criteria and shifting buyer preference toward certified integrated systems over commodity enclosures.
Growth Catalysts
- Cloud Hyperscale Expansion:Amazon Web Services, Microsoft Azure, and Google Cloud are commissioning dedicated facilities in the Tel Aviv corridor, generating concentrated demand for high-density rack configurations with integrated power and cooling.
- 5G Edge Infrastructure Mandate:The Ministry of Communications is requiring cellular operators to deploy distributed compute nodes at base station locations, creating a new rack category for outdoor-hardened, thermally managed edge enclosures.
- National Cyber Directorate Physical Security Directives:Mandatory biometric access logging and intrusion detection integration for critical infrastructure facilities is forcing rack upgrades across existing colocation assets.
Market Restraints
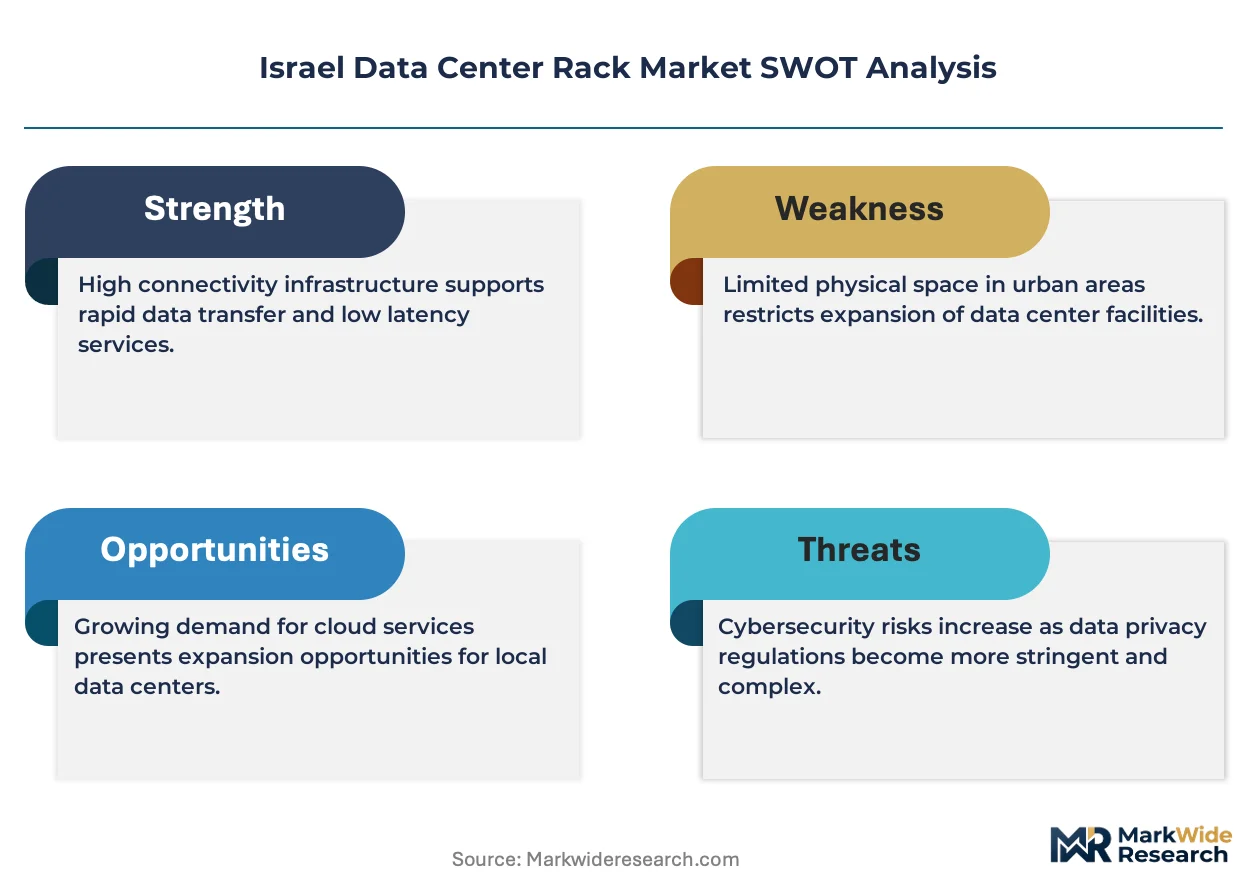
- Steel and Aluminum Input Volatility:Rack enclosure manufacturing depends on imported rolled steel and extruded aluminum, exposing Israeli fabricators to Mediterranean shipping cost fluctuations and currency hedge requirements.
- Concentrated Domestic Fabrication:Local metalworking capacity for precision enclosure manufacturing clusters in Haifa Bay industrial zones, creating single-point vulnerability for just-in-time delivery to Tel Aviv construction sites.
- Limited Local Cooling Component Supply:Precision air conditioning and liquid cooling manifolds for high-density racks rely on European and Asian component suppliers, extending lead times for integrated rack-cooling systems.
Strategic Opportunities
- Negev Desert Solar-Powered Facilities:The Israel Land Authority is allocating parcels near Be'er Sheva for renewable-powered data centers, creating demand for racks engineered for extreme thermal cycling and dust-sealed operation.
- Defense and Intelligence Contracting:Ministry of Defense classified facility construction is accelerating, requiring rack systems with electromagnetic shielding and tamper-evident mechanical designs unavailable from standard commercial catalogs.
- Modular Prefabricated Data Centers:Containerized and skid-mounted facility designs are overtaking traditional stick-built construction, favoring rack vendors with integrated modular enclosure and power distribution capabilities.
Industry Challenges
- Certified Security Integration Skill Gap:Rack deployment teams require cross-training in physical access control systems, biometric sensor calibration, and National Cyber Directorate audit documentation, extending project commissioning timelines.
- Legacy Copper Infrastructure Retrofit Complexity:Established Tel Aviv financial district facilities operate on outdated power and grounding architectures, complicating high-density rack deployments without full electrical infrastructure replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Israel Data Center Rack Market |
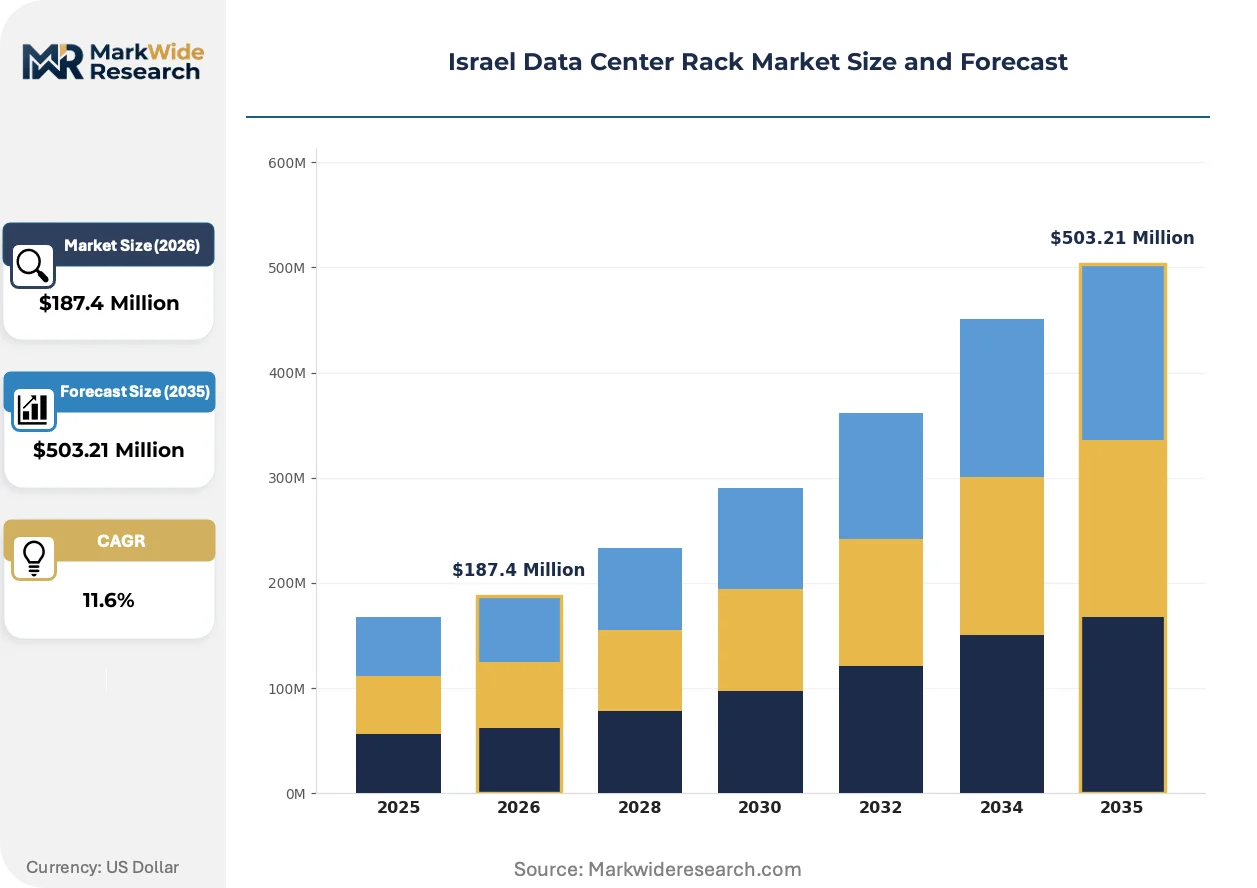
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Frame Racks, Enclosed Racks, Wall-Mounted Racks, Specialty Racks End User: Telecommunications, IT Services, Government, Education Deployment: On-Premises, Colocation, Edge Computing, Hybrid Service Type: Installation, Maintenance, Consulting, Monitoring |
| Companies Covered | Hewlett Packard Enterprise, Schneider Electric, Rittal, Eaton Corporation, Fujitsu, Vertiv, Dell, Legrand, Bynet Data Communications, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Israel Data Center Rack Market Trends and Innovations
Israeli data center architecture is pivoting toward thermal resilience and security integration as baseline requirements rather than premium options. Rack vendors are responding with enclosure designs that embed cooling distribution and access control as standard configurations.
Liquid cooling distribution manifolds integrated directly into rack frames are overtaking traditional rear-door heat exchangers as the preferred thermal management architecture for deployments exceeding 30 kW per cabinet. Israeli hyperscale operators are specifying these designs for AI training clusters in Tel Aviv metro facilities. The shift is compressing demand for standalone cooling units and elevating rack-level thermal engineering to a primary procurement criterion.
National Cyber Directorate amendments to critical infrastructure protection guidelines are mandating redundant biometric authentication and continuous access logging for all rack-mounted systems in designated facilities. Colocation operators must retrofit existing halls or risk contract disqualification from government and defense tenants. The regulation is accelerating replacement cycles for legacy open-frame racks across the Tel Aviv central business district.
Enterprise buyers are consolidating vendor relationships to capture integrated rack-power-cooling-security packages rather than sourcing components separately. This pattern is most pronounced among Israeli healthcare and financial institutions preparing for Ministry of Health and Bank of Israel data localization audits. Single-source procurement is compressing the addressable market for standalone enclosure vendors while expanding contract values for integrated system providers with local installation capabilities.
Israel Data Center Rack Market Segmentation
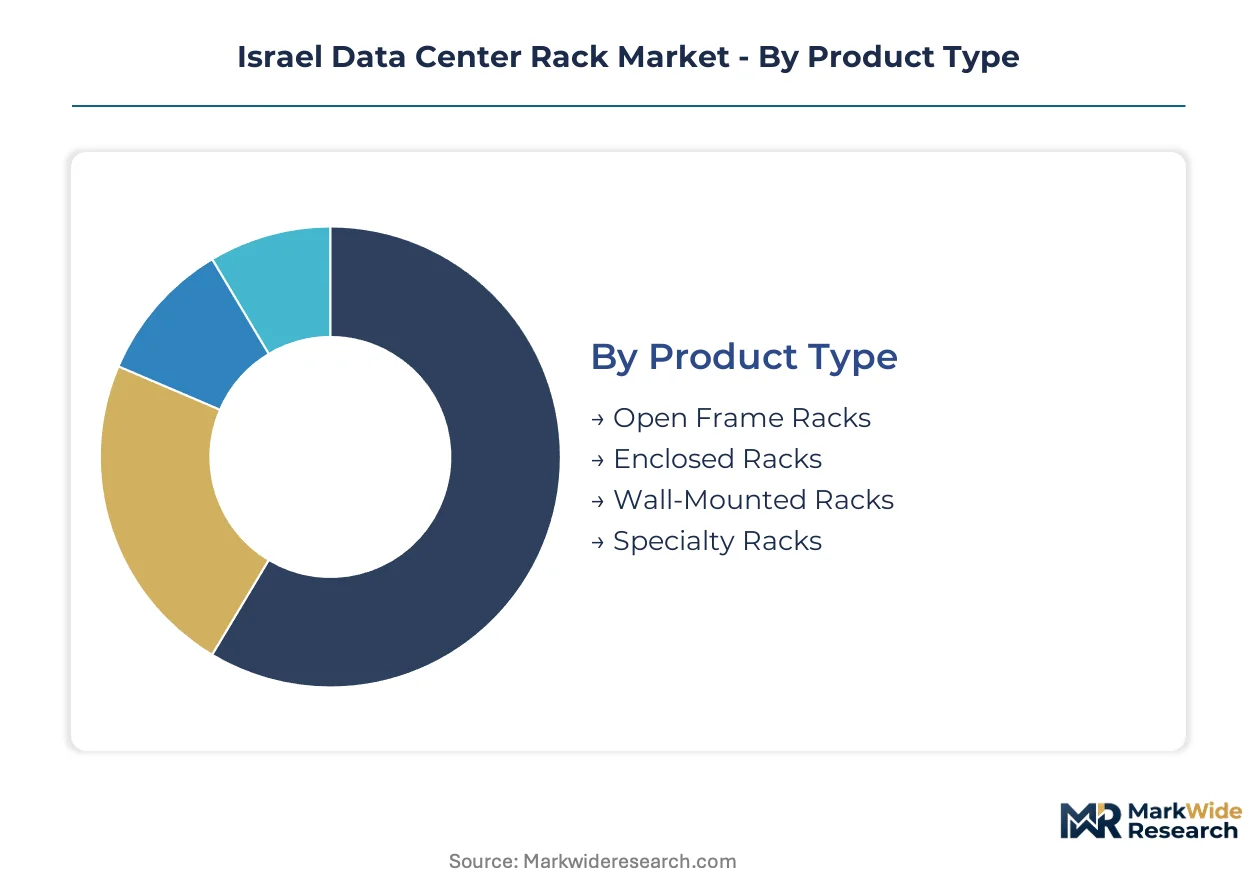
Segmentation in Israel's data center rack market reveals how regulatory mandates reshape procurement patterns across product categories and customer types. The National Cyber Directorate's physical security requirements create divergent compliance burdens that stratify demand by deployment complexity and certification depth.
Product Type:
The Israel Standards Institute certifies structural load ratings and electrical grounding for all rack enclosures, while the National Cyber Directorate imposes additional biometric integration mandates on enclosed configurations deployed in critical infrastructure facilities.
- Enclosed Racks:Fully sealed metal cabinets with integrated thermal containment and lockable side panels dominate Tel Aviv hyperscale builds. These units command premium positioning as Israeli operators combat ambient temperature extremes while satisfying mandatory access logging requirements for government and financial tenants.
- Open Frame Racks:Four-post frameworks without side panels or doors serve legacy enterprise server rooms and development environments. Demand concentrates in established Haifa industrial facilities where retrofit budgets limit full enclosure replacement and thermal loads remain below regulated thresholds.
- Wall-Mounted Racks:Compact swing-out enclosures secure networking equipment in space-constrained branch offices and retail banking locations.
- Specialty Racks:Custom-engineered frames with electromagnetic shielding or tamper-evident designs serve Ministry of Defense classified facilities.
Enclosed Racks sits at the top of the volume ranking, with Specialty Racks climbing the fastest.
End User:
Procurement patterns diverge sharply by buyer sophistication, with defense and government contracts demanding integrated security systems while commercial segments prioritize cost-optimized thermal performance.
- Telecommunications:Cellular operators deploying 5G distributed compute nodes drive demand for outdoor-hardened edge enclosures. The Ministry of Communications mandate for base station infrastructure is accelerating specification of thermally managed cabinets with extended temperature operating ranges across the Tel Aviv metropolitan corridor.
- Government:National Cyber Directorate classified facility designations require biometric authentication integration and continuous access logging for all rack-mounted systems. This segment sources exclusively through certified vendors with documented installer training and audit documentation capabilities.
- IT Services:Colocation providers and managed hosting operators balance density optimization against multi-tenant security separation requirements.
- Education:University research computing clusters and campus data centers prioritize standard enterprise configurations with modular expansion paths.
Telecommunications captures the largest procurement volumes, with Government expanding most quickly under security directive enforcement.
Deployment:
Physical infrastructure location determines which regulatory frameworks apply, with edge and hybrid configurations navigating overlapping compliance obligations from multiple oversight bodies.
- Colocation:Multi-tenant facilities in Tel Aviv's central business district sustain mature demand patterns with established margin pools. Operators here face accelerated replacement cycles as legacy open-frame racks must retrofit to meet National Cyber Directorate biometric access mandates or risk contract disqualification from government tenants.
- Edge Computing:Distributed compute nodes at cellular base stations and remote enterprise sites represent the steepest expansion trajectory. The Ministry of Communications infrastructure mandate is creating a new rack category purpose-built for outdoor deployment, thermal cycling resilience, and minimal on-site maintenance access.
- On-Premises:Enterprise-owned facilities in Jerusalem and Haifa maintain steady replacement demand for standardized enclosures.
- Hybrid:Split workload architectures combining cloud and local infrastructure drive specification of compatible rack form factors across environments.
Colocation maintains the highest installed base, with Edge Computing gaining share fastest under telecommunications infrastructure mandates.
Service Type:
Revenue attachment rates vary by deployment complexity, with integrated security systems requiring specialized commissioning expertise that standalone enclosure vendors cannot supply.
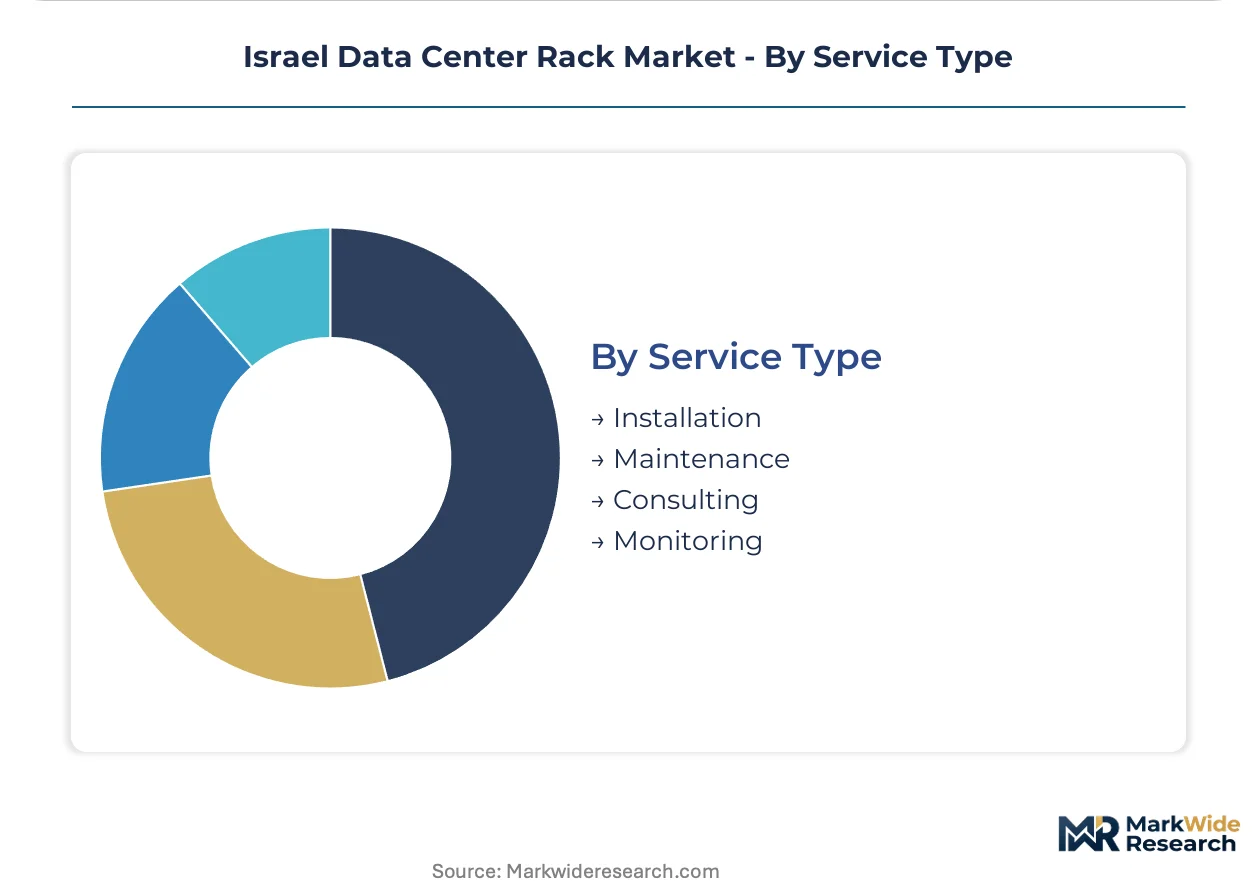
- Installation:Rack deployment teams require cross-training in physical access control systems, biometric sensor calibration, and National Cyber Directorate audit documentation. This skill scarcity extends project commissioning timelines and elevates contract values for qualified integrators with government contracting experience.
- Maintenance:Preventive service contracts covering thermal management components and security system firmware updates generate recurring revenue streams. Israeli healthcare and financial institutions preparing for Ministry of Health and Bank of Israel data localization audits are consolidating vendor relationships to capture integrated support packages.
- Consulting:Design-phase advisory on rack density, power distribution, and cooling integration supports new construction projects.
- Monitoring:Remote environmental and security status surveillance services attach to premium colocation contracts.
Installation commands the largest service revenue share, with Maintenance climbing fastest as retrofit mandates extend replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israel's dense concentration of cybersecurity talent and military technology expertise anchors its data center infrastructure development. The country's National Cyber Directorate workforce sets regulatory standards that cascade through regional deployment patterns.
Tel Aviv Metropolitan Corridor
Hyperscale cloud builds and colocation clusters concentrate rack demand along the Ayalon corridor and Herzliya Pituach technology park. The National Cyber Directorate's physical security mandates drive specification of biometric-integrated enclosures across all new facilities. Amazon Web Services, Microsoft Azure, and Google Cloud commissioning activity generates the steepest procurement volumes for high-density configurations.
Haifa Bay Industrial Zone
Precision metalworking capacity for rack enclosure fabrication clusters around this northern port region, creating a single-point vulnerability for just-in-time delivery. The Israel Standards Institute certifies structural load ratings and electrical grounding for locally manufactured units. Established industrial facilities here maintain steady replacement demand for open-frame racks where thermal loads remain below regulated thresholds.
Be'er Sheva and Negev Desert
The Israel Land Authority is allocating renewable energy parcels near this southern city for solar-powered data center construction. Rack deployments here require engineering for extreme thermal cycling and dust-sealed operation. Ministry of Defense classified facility construction accelerates demand for electromagnetic shielding and tamper-evident mechanical designs.
Jerusalem
Government and institutional data center operations sustain mature demand patterns for standardized enterprise enclosures. The National Cyber Directorate's critical infrastructure designations apply broadly across facilities serving national security and administrative functions. Financial district proximity drives hybrid cloud connectivity requirements.
Eilat and Southern Border Region
Submarine cable landing stations and cross-border connectivity infrastructure create specialized edge deployment opportunities. The Ministry of Communications mandate for distributed compute nodes extends to this corridor for redundancy and latency optimization. Outdoor-hardened edge enclosures face salt-air corrosion and thermal management challenges.
Israel Data Center Rack Market Competitive Landscape
The competitive structure tilts toward integrated systems providers over commodity enclosure fabricators. Two distinct tiers operate: multinational industrial conglomerates with power-cooling-security portfolios, and regional specialists with government contracting access. Dominant competitive moves include portfolio diversification into modular prefabricated systems and strategic partnerships with local installation integrators.
Among integrated infrastructure providers, Schneider Electric and Rittal exemplify the premium-tier archetype with thermal-engineered enclosure systems. Bynet Data Communications anchors the regional specialist position through distribution channel depth and installer relationships. Hewlett Packard Enterprise and Dell occupy the scale-driven compute-integrated rack segment, while Eaton Corporation and Vertiv represent power distribution specialists extending into enclosure offerings.
| Leading Market Players |
|---|
| Hewlett Packard Enterprise |
| Schneider Electric |
| Rittal |
| Eaton Corporation |
| Fujitsu |
| Vertiv |
| Dell |
| Legrand |
| Bynet Data Communications |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between National Cyber Directorate-compliant integrated systems and commodity open-frame enclosures manifests in divergent pricing architectures and procurement channel configurations across Israeli rack deployments. Premium-tier vendors capture bundled power-cooling-security packages through direct specification relationships with hyperscale cloud operators, while standard-tier fabricators compete on landed cost through Haifa Bay metalworking clusters serving price-sensitive enterprise retrofits.
Pricing Analysis
Bundled installation-commissioning services versus unbundled equipment-only procurement defines the dominant pricing split across Israeli data center rack transactions. Project-based contracting with multi-year maintenance attachments commands premium positioning for government and defense facilities requiring biometric integration and audit documentation. Price differentiation hinges on National Cyber Directorate certification depth and local installer qualification rather than raw material specifications alone. Cost compression in open-frame commodity tiers intensifies as Haifa fabricators absorb Mediterranean shipping volatility for imported rolled steel. Financial sector buyers exhibit lowest price sensitivity given regulatory audit exposure, while education and mid-market enterprise segments prioritize capital expenditure minimization.
Supply Chain Analysis
Reverse-logistics flows for rack refurbishment and component recovery remain underdeveloped in Israel, creating stranded asset risk for legacy open-frame installations displaced by security mandate retrofits. Primary manufacturing draws from China, Germany, and Italy for precision enclosure fabrication, with Israel's Haifa Bay industrial zone providing final assembly and certification integration. Rolled steel and extruded aluminum feedstocks, precision air conditioning manifolds, and biometric access control modules constitute critical input dependencies. Single-source vulnerability concentrates in European liquid cooling component suppliers, extending lead times for high-density integrated systems. Distribution runs through Bynet Data Communications' installer network for government contracts, while hyperscale operators source direct from Schneider Electric and Rittal regional offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Israel's data center rack market represents a late-cycle quality story as National Cyber Directorate physical security mandates force replacement cycles toward premium integrated specifications. Buyers now consolidate vendor relationships around certified systems rather than optimizing for standalone enclosure cost.
For Market Incumbents: Deploy certification investment as the primary defensive lever. Deepen backward integration into precision metalworking capacity within Haifa Bay industrial zones to compress delivery timelines for Tel Aviv hyperscale builds. Accelerate installer training programs in biometric sensor calibration and National Cyber Directorate audit documentation to capture maintenance contract renewals threatened by European specialist entrants.
For New Entrants and Emerging Players: National Cyber Directorate amendments to critical infrastructure protection guidelines in Israel open a window for modular prefabricated data center specialists with integrated rack-power-cooling capabilities. Target the Negev Desert solar-powered facility segment where extreme thermal cycling specifications create barrier-to-entry insulation against commodity enclosure vendors. Pursue Ministry of Defense electromagnetic shielding certifications as the definitive go-to-market credential for classified facility contracting.
For Investors and Strategic Acquirers: Asymmetric upside sits with regional installation integrators possessing documented government contracting relationships and cross-trained commissioning teams. Five-to-ten year viability depends on capturing recurring maintenance revenue streams from retrofit mandates rather than one-time equipment sales. Monitor National Cyber Directorate data localization rule amendments as the critical inflection signal for domestic capacity commitment timing from multinational cloud operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Security Integration | National Cyber Directorate mandates force rack-level access control retrofit across Tel Aviv colocation assets. |
| Liquid Cooling Manifold Development | AI training cluster density requirements displace rear-door heat exchangers in hyperscale specifications. |
| Negev Desert Facility Engineering | Israel Land Authority renewable parcels demand dust-sealed racks for extreme thermal cycling. |
| Defense Electromagnetic Shielding Certification | Ministry of Defense classified construction requires tamper-evident mechanical designs unavailable commercially. |
| Modular Prefabricated Data Center Partnership | Containerized facility designs favor vendors with integrated enclosure and power distribution capabilities. |
Research Methodology
Direct dialogue with data center construction directors, National Cyber Directorate compliance officers, colocation procurement managers, and precision metalworking plant supervisors in Haifa Bay grounded qualitative insights. Secondary validation drew from Israel Standards Institute certification databases, Ministry of Communications 5G infrastructure filings, Ministry of Defense procurement notices, and customs records for rolled steel and aluminum imports. Bottom-up rack deployment tallies triangulated against top-down facility construction pipeline estimates.
Bottom-up unit economics modeled rack shipments by product type, end-user vertical, and deployment configuration across the analysis window. Segmentation dimensions included enclosure specification tier, thermal management architecture, security integration depth, and regional delivery cluster. CAGRs derived from facility commissioning timelines, replacement cycle compression under regulatory mandates, and hyperscale cloud operator capacity expansion announcements. Forecast inputs incorporated National Cyber Directorate guideline amendment probabilities and Ministry of Communications edge infrastructure mandate enforcement schedules.
Revisions become necessary when National Cyber Directorate data localization amendments, Ministry of Defense classified facility budget reallocations, or Mediterranean shipping cost volatility materialize outside modeled ranges. Practitioners should monitor hyperscale cloud operator land acquisition filings in the Tel Aviv corridor and Negev Desert renewable energy parcel allocations for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Sweden Data Center Construction Market
Data Center Infrastructure
Converged Data Center Infrastructure Market
Data Center Infrastructure
Data Quality Management Market
Data Center Infrastructure
Global Cloud Infrastructure Service Market
Data Center Infrastructure
Data Center Colocation and Managed Hosting Services Market
Data Center Infrastructure
Canada Data Center Rack Market
Data Center Infrastructure
Russia Data Center Rack Market
Data Center Infrastructure
Global Telecommunication Equipment Cabinet and Racks Market
Data Center Infrastructure
India Data Center Rack Market
Data Center Infrastructure
Global Data Center Accelerator Market
Data Center Infrastructure
Server Station Market
Data Center Infrastructure
LAMEA Virtual Desktop Infrastructure Market
Data Center Infrastructure
Asia-Pacific Containerized Data Center Market
Data Center Infrastructure
Rugged Servers Market
Data Center Infrastructure
United States (US) Data Center Construction Market
Data Center Infrastructure
Virtualized Data Center Market