
 Data Terminal Market | 2026-2036
Data Terminal Market Size, Share, and Industry Trends Forecast 2026-2036
Data Terminal Market Analysis
Healthcare payment processing is pivoting toward integrated point-of-care terminals. Diebold Nixdorf leverages its ATM-to-terminal technology bridge to capture hospital network contracts. Verifone Systems anchors its position through cloud-connected device management platforms. PAX Technology competes aggressively on manufacturing scale across Asian supply chains.
A data terminal is an electronic device that captures, processes, and transmits transaction data through encrypted communication protocols, typically featuring PCI-compliant hardware, touchscreen interfaces, and modular connectivity ports for peripheral integration. Its primary purpose is to facilitate secure payment authorization and data exchange in commercial environments. Desktop terminals lead revenue contribution in mature retail markets where counter space permits dedicated installations. Mobile terminals represent the fastest-expanding product type as pop-up commerce and curbside pickup formats proliferate. Handheld terminals concentrate margin pools in logistics applications where ruggedized durability commands premium positioning.
FCC certification requirements govern wireless data terminal deployment across the United States, while PCI DSS standards enforce encryption and tokenization protocols globally. The EU AI Act and GDPR frameworks increasingly shape terminal software architecture for biometric authentication and transaction data storage. Stakeholders must monitor evolving central bank digital currency pilots and their hardware compatibility implications for next-generation terminal specifications.
Market Dynamics
EMV compliance deadlines and contactless payment mandates are compressing terminal replacement cycles across retail and hospitality networks, forcing merchants to absorb hardware refresh costs ahead of planned capital cycles.
Growth Catalysts
- PCI DSS 4.0 encryption standards:Mandates for end-to-end tokenization are compelling merchants to upgrade legacy terminals, creating replacement demand across United States retail chains.
- Curbside pickup infrastructure:Grocery and quick-service restaurant formats are deploying handheld terminals for parking lot transaction completion, expanding addressable unit volumes.
- China's digital yuan pilots:Hardware compatibility requirements for central bank digital currency acceptance are driving next-generation terminal specifications in Shanghai and Shenzhen payment corridors.
Market Restraints
- Semiconductor supply concentration:Secure element chip fabrication concentrates in Taiwan and South Korea foundries, exposing terminal manufacturers to allocation delays.
- FCC certification timelines:Wireless terminal approvals average 14-18 months in the United States, constraining product launch velocity for new connectivity protocols.
- Smartphone-based soft terminals:Tap-to-pay functionality on iOS and Android devices threatens dedicated hardware demand in micro-merchant segments.
Strategic Opportunities
- Healthcare point-of-care billing:Hospital networks in Germany and the United States are integrating payment terminals into patient registration workflows, creating vertical-specific demand.
- EU AI Act biometric provisions:Facial authentication-enabled terminals qualify for streamlined compliance pathways, incentivizing premium feature development.
- Logistics last-mile delivery:Ruggedized handheld terminals for proof-of-delivery and payment collection remain underpenetrated in Indian and Brazilian courier networks.
Industry Challenges
- EMV kernel certification backlog:Laboratory testing queues for contactless compliance extend 6-9 months, delaying product releases.
- Legacy POS integration complexity:Merchants operating 15-20 year-old retail management systems face middleware development costs to connect modern terminals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Terminal Market |
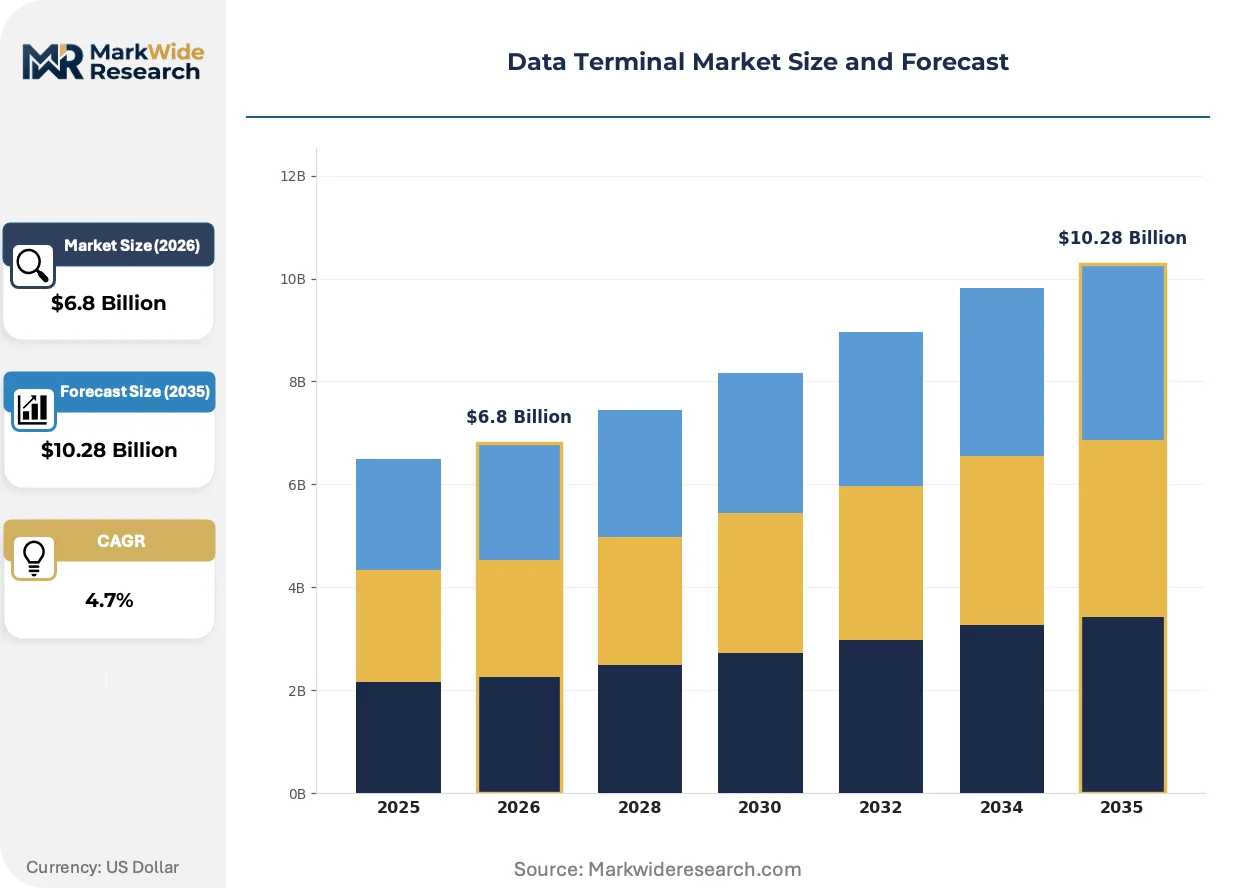
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop Terminals, Handheld Terminals, Mobile Terminals, Fixed Station Terminals Connectivity: Wired, Wireless, Bluetooth, NFC Application: Retail, Transportation, Healthcare, Logistics End User: Small Businesses, Large Enterprises, Government Agencies, Educational Institutions |
| Companies Covered | Newland Payment Technology, Diebold Nixdorf, Verifone Systems, Worldpay, Elavon, Ingenico Group, NCR Voyix, First Data, PAX Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Terminal Market Emerging Trajectories
Cloud-native terminal architectures are displacing on-device software stacks, enabling real-time transaction routing and remote configuration management across distributed merchant fleets.
Android-based open operating systems are overtaking proprietary embedded platforms in new terminal deployments. Large-format retailers in the United States and Germany are standardizing on Android terminals to run loyalty applications alongside payment functions. This convergence is compressing margins for closed-system hardware vendors while expanding software monetization opportunities for platform providers.
The EU AI Act's biometric authentication provisions are reshaping terminal camera and sensor integration requirements. Vendors must now document algorithmic transparency for facial recognition features sold into European markets. Germany's retail banking sector has responded by demanding hardware-level data isolation to satisfy GDPR and AI Act overlapping compliance obligations.
Merchant acquisition models are fragmenting as independent software vendors bundle payment acceptance into vertical-specific SaaS platforms. Restaurant management systems in the United States now embed terminal provisioning as a contracted service rather than a hardware purchase. This shift compresses upfront equipment revenue while elongating customer lifetime value through recurring software fees.
Data Terminal Market Segmentation
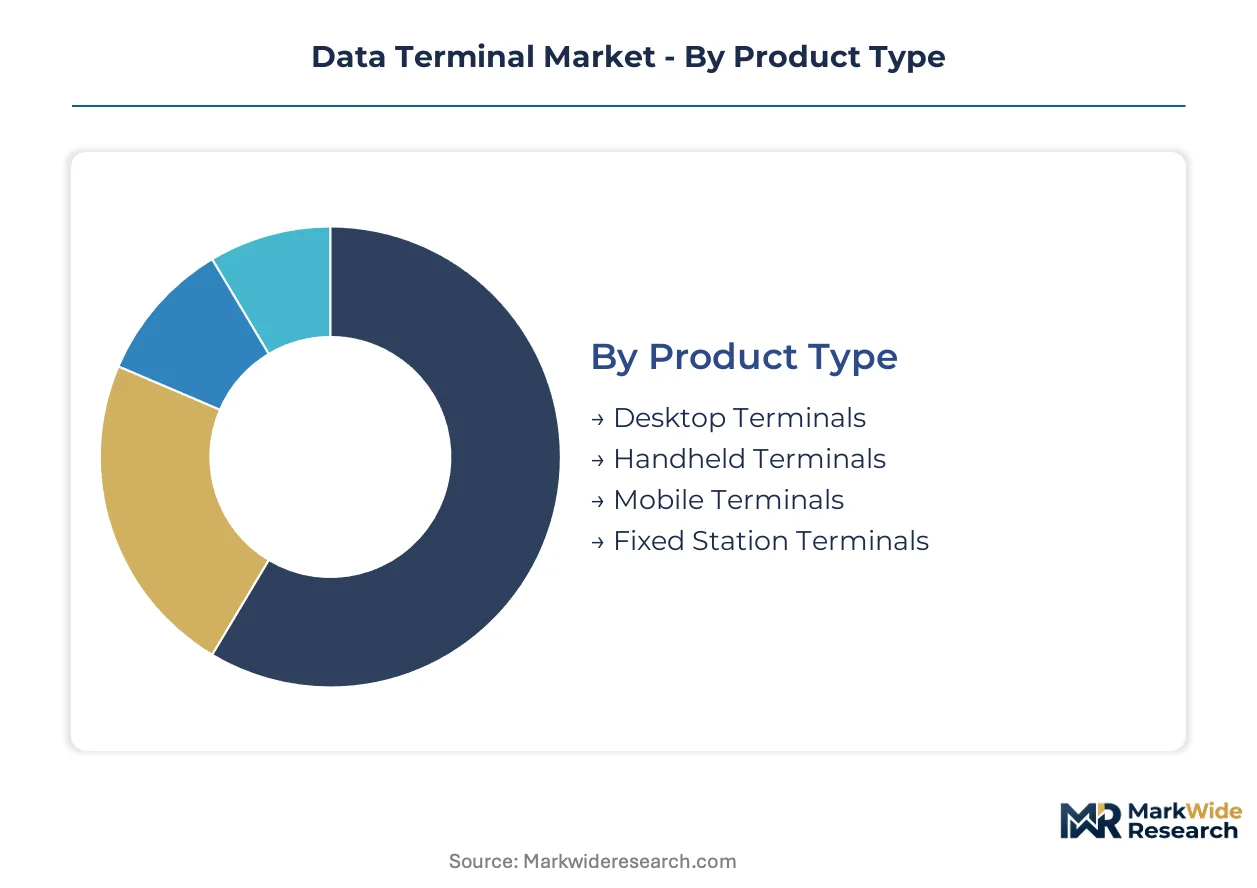
Terminal procurement decisions in this market pivot on infrastructure refresh cycles, compliance mandates, and operational mobility requirements. Each segmentation dimension reveals distinct upgrade pathways that reshape vendor positioning and margin capture across merchant categories.
Product Type:
Hardware replacement cycles vary dramatically by installation footprint and portability requirements, with countertop permanence versus field mobility driving divergent specification priorities.
- Desktop Terminals:Stationary units with integrated thermal printers, barcode scanners, and multiple peripheral ports dominate mature retail environments where counter space permits dedicated installations. Demand concentrates in United States grocery chains and German department stores refreshing EMV-compliant fleets ahead of contactless mandates.
- Mobile Terminals:Battery-powered devices with cellular or Wi-Fi connectivity enable transaction completion beyond fixed checkout locations. Curbside pickup proliferation across quick-service restaurants and parking lot commerce in the United States is accelerating unit deployment fastest.
- Handheld Terminals:Ruggedized form factors with IP65+ sealing and drop resistance serve field service applications.
- Fixed Station Terminals:Wall-mounted or kiosk-integrated units support self-service checkout and ticketing workflows.
Volume placements concentrate in Desktop Terminals; the faster expansion belongs to Mobile Terminals.
Connectivity:
Communication protocol selection directly determines certification burden, deployment flexibility, and recurring connectivity costs across merchant segments.
- Wired:Ethernet-connected terminals with stable power delivery and deterministic latency serve high-volume transaction environments. Large United States retail chains standardize on wired infrastructure for reliability, though installation constraints limit greenfield expansion.
- Wireless:Cellular-enabled terminals with 4G/5G modems eliminate infrastructure dependency for temporary or remote locations. German logistics networks and United States pop-up commerce operators are driving the steepest expansion trajectory.
- Bluetooth:Short-range pairing with smartphones and tablets supports soft terminal architectures.
- NFC:Contactless-only modules for tap-to-pay acceptance without full payment terminal functionality.
Merchant procurement currently favors Wired for volume; Wireless gains share fastest in logistics and temporary retail formats.
Application:
Vertical-specific compliance requirements and transaction workflows create divergent hardware specification demands that fragment vendor addressable markets.
- Retail:Checkout-optimized terminals with high-speed printers, customer-facing displays, and loyalty program integration handle the highest transaction volumes. United States and German large-format merchants anchor replacement demand through EMV and contactless upgrades.
- Healthcare:HIPAA-compliant terminals with encrypted data isolation and patient registration system integration are penetrating hospital networks. Point-of-care billing adoption in the United States and Germany is creating vertical-specific procurement channels.
- Transportation:Fare collection terminals with rapid tap-and-go processing for transit systems.
- Logistics:Proof-of-delivery and payment collection devices for courier and last-mile operations.
Retail captures the largest installed base; Healthcare applications are climbing the fastest as hospital networks integrate payment into registration workflows.
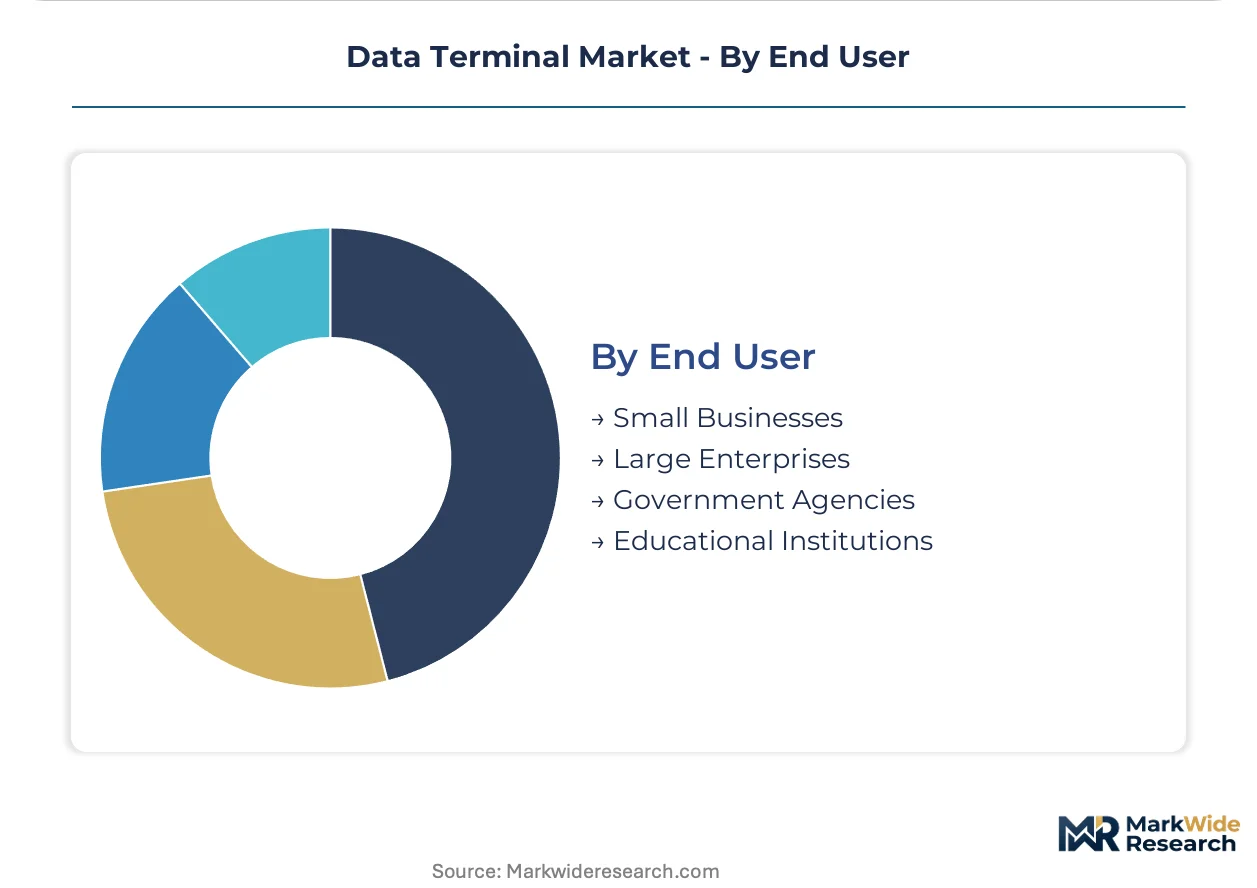
End User:
Scale-driven procurement patterns separate price-sensitive small merchant segments from enterprise buyers prioritizing fleet management and security certification.
- Large Enterprises:Multi-location merchants with centralized IT procurement demand cloud-connected terminal fleets with remote configuration and unified reporting. United States retail chains and German banking networks specify PCI DSS 4.0 compliance and Android-based open platforms for application flexibility.
- Small Businesses:Independent merchants with limited technical staff prioritize all-in-one solutions with minimal setup complexity. Smartphone-based soft terminal threats concentrate most heavily in this segment.
- Government Agencies:Public sector procurement with extended security vetting and domestic content requirements.
- Educational Institutions:Campus payment systems for tuition, dining, and retail services with student credential integration.
Large Enterprises drive premium-tier volume; Small Businesses represent the most contested segment as soft terminal alternatives erode dedicated hardware demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Shanghai concentrate terminal manufacturing capacity, while tax incentives in Bavaria and Texas anchor regional assembly operations for North American and European demand.
United States
EMV compliance deadlines and contactless payment mandates drive terminal refresh cycles across grocery chains and quick-service restaurants. FCC certification requirements govern wireless terminal deployment, with approval timelines averaging 14-18 months. Silicon Valley fintech clusters and Atlanta payment processing hubs shape procurement specifications for cloud-connected device fleets.
China
Digital yuan pilots in Shanghai and Shenzhen payment corridors require next-generation hardware compatibility, accelerating domestic terminal specifications. MIIT standards and SAMR regulations enforce encryption protocols for financial data terminals. Pearl River Delta manufacturing clusters in Guangdong Province supply secure element chip integration for Asian and export markets.
Germany
Hospital networks integrate point-of-care billing terminals into patient registration workflows, creating vertical-specific demand. GDPR and EU AI Act frameworks shape biometric authentication hardware requirements for facial recognition features. Bavaria's industrial automation corridor and Frankfurt's financial services cluster anchor enterprise procurement decisions.
India
RBI payment system directives and digital infrastructure investments expand terminal deployment across banking and retail networks. BIS certification requirements govern hardware security standards for domestic market entry. Mumbai-Pune manufacturing belt and Bangalore technology corridors concentrate assembly operations for South Asian distribution.
Brazil
Logistics networks and last-mile courier operations drive demand for ruggedized handheld terminals with proof-of-delivery functionality. ANVISA and central bank regulations enforce data encryption for payment processing hardware. São Paulo industrial districts anchor regional distribution for Latin American merchant acquisition networks.
Data Terminal Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated solution providers capturing enterprise accounts while OEM fabricators serve price-sensitive merchant tiers. The vendor base concentrates around three strategic archetypes: ATM-to-terminal technology bridges, cloud-connected platform operators, and manufacturing-scale Asian suppliers. Competitive positioning hardens through M&A consolidation of payment software stacks and strategic partnerships between terminal hardware vendors and merchant acquiring networks.
Within the technology bridge archetype, Diebold Nixdorf leverages ATM infrastructure relationships to capture hospital and banking network contracts. Verifone Systems anchors the cloud-connected platform tier through device management and remote configuration capabilities. PAX Technology occupies the manufacturing-scale position, competing on production volume across Asian supply chains for global distribution.
| Leading Market Players |
|---|
| Newland Payment Technology |
| Diebold Nixdorf |
| Verifone Systems |
| Worldpay |
| Elavon |
| Ingenico Group |
| NCR Voyix |
| First Data |
| PAX Technology |
| Others |
Supply Flow & Price Mechanics
PCI DSS 4.0 compliance mandates across United States retail chains are compressing procurement timelines and forcing terminal manufacturers to absorb certification acceleration costs while maintaining margin discipline on legacy product lines.
Pricing Analysis
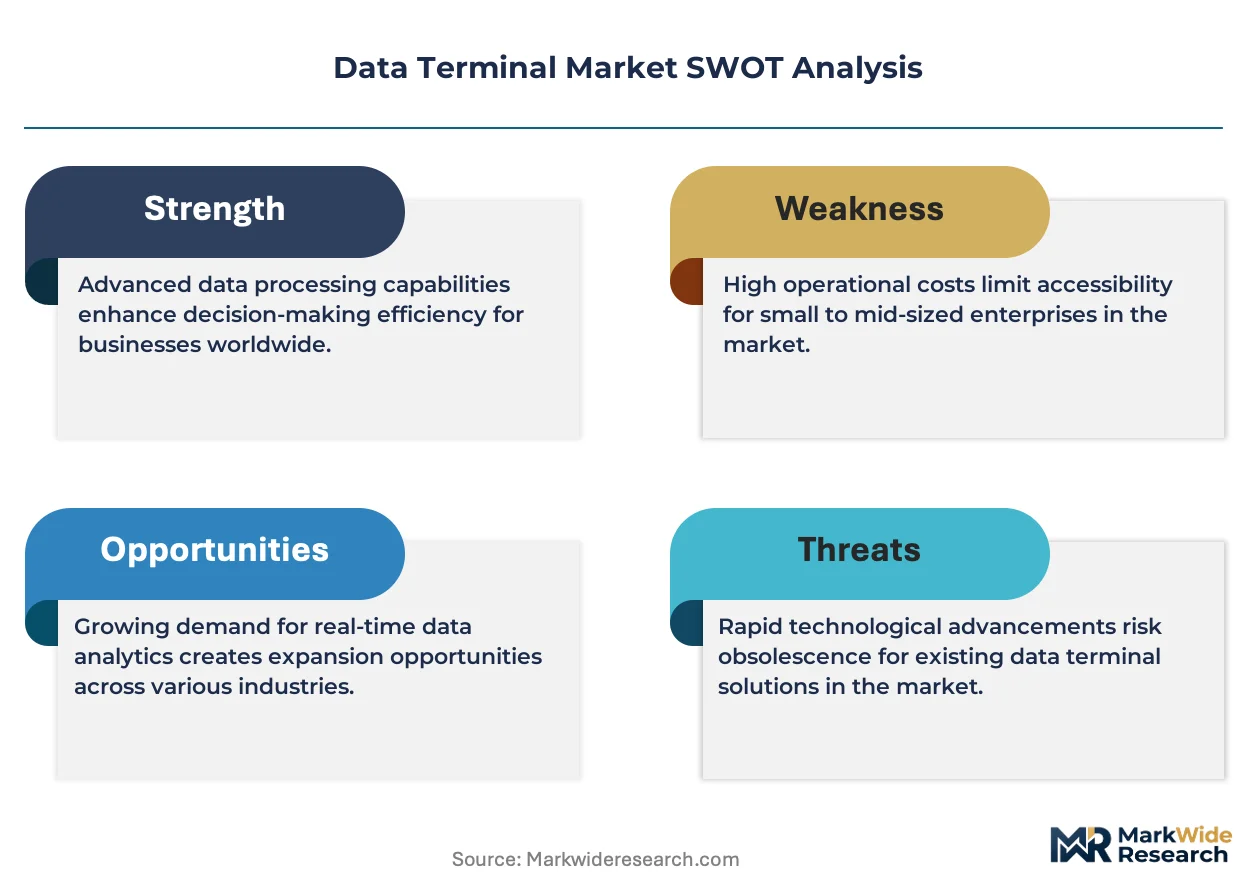
Lead-time premiums now dominate contract negotiations, with expedited FCC certification timelines commanding fifteen to twenty percent markups over standard-queue deliveries. Three-tier pricing structure across premium, standard, and economy levels segments the market: premium tiers bundle cloud-management platforms and biometric-ready hardware, standard tiers cover EMV-compliant countertop units, and economy tiers serve price-sensitive small merchants with stripped-down functionality. Price differentiation rests on certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because smartphone-based soft terminals erode dedicated hardware demand. Small businesses exhibit highest price sensitivity, while large enterprises prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Secure element chip fabrication rests on Taiwan and South Korea foundries, with back-end assembly concentrating in Guangdong Province and test facilities anchoring in Penang, Malaysia. Raw material dependencies span silicon wafers, cryptographic co-processors, and tamper-resistant enclosures. Single-source vulnerability in TSMC's advanced node capacity exposes terminal manufacturers to allocation delays during semiconductor demand surges. Distribution runs through merchant acquiring networks and independent software vendor platforms rather than direct hardware sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The data terminal market sits in a platform-transition phase as Android-based open operating systems displace proprietary embedded stacks, compressing margins for closed-system vendors while expanding software monetization opportunities.
For Market Incumbents: Deepen cloud-native platform investments to capture recurring software revenue as hardware margins compress. Prioritize EMV kernel certification pipeline expansion to reduce laboratory testing queue exposure. Strengthen hospital network relationships in Germany and the United States where point-of-care billing integration creates vertical-specific switching costs against smartphone-based alternatives.
For New Entrants and Emerging Players: Begin with ruggedized handheld terminals for Indian and Brazilian logistics networks, where proof-of-delivery functionality remains underpenetrated and price sensitivity is lower than retail segments. Target quick-service restaurant curbside pickup formats in the United States where mobile terminal deployment velocity outstrips incumbent fulfillment capacity. Pursue independent software vendor partnership routes rather than direct merchant acquisition channel builds.
For Investors and Strategic Acquirers: The window for entry favors cloud-connected platform operators with device management capabilities and healthcare vertical penetration. Long-term viability hinges on software recurring revenue ratios exceeding hardware dependency. Watch central bank digital currency pilot expansions in China and prospective European implementations as hardware refresh inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Enables real-time transaction routing and remote fleet management for distributed merchants. |
| Healthcare Vertical Integration | Captures hospital network contracts through HIPAA-compliant terminal and patient registration system integration. |
| Biometric Authentication Certification | Qualifies terminals for streamlined EU AI Act compliance pathways in German retail banking. |
| Android Open System Standardization | Supports loyalty application convergence alongside payment functions for large-format United States retailers. |
| Logistics Handheld Expansion | Addresses underpenetrated Indian and Brazilian courier networks with ruggedized proof-of-delivery devices. |
Methodological Framework
Multi-period observation of terminal deployment volumes, certification queue lengths, and merchant refresh cycles anchored the trend analysis, supplemented by interviews with payment technology executives, hospital procurement managers, logistics fleet operators, and retail IT directors. Secondary validation drew from FCC equipment authorization databases, PCI SSC compliance listings, central bank digital currency pilot disclosures, and SEC filings of publicly traded terminal manufacturers. Bottom-up unit shipment modeling triangulated against top-down payment transaction growth projections.
Segment-weighting approaches distributed value estimates across product type, connectivity protocol, application vertical, and end-user scale dimensions. CAGRs were derived from installed base replacement modeling and greenfield deployment trajectories across the analysis window. Forecast inputs incorporated EMV compliance deadline schedules, contactless payment mandate timelines, and healthcare point-of-care billing adoption curves.
Underlying measurement precision varies by segment; mobile terminal forecasts carry tighter precision than emerging biometric-enabled categories due to established deployment patterns. Forecasts reflect assumptions about certification timeline normalization and semiconductor supply stabilization. Central bank digital currency hardware mandate announcements and FCC regulatory processing rate changes warrant ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Data Center Rack Market
Data Center Infrastructure
China Data Center Server Market
Data Center Infrastructure
North America Data Center Rack Market
Data Center Infrastructure
Data Center Colocation Market
Data Center Infrastructure
Poland Data Center Rack Market
Data Center Infrastructure
Indonesia Enterprise Network Infrastructure Market
Data Center Infrastructure
Sweden Data Center Physical Security Market
Data Center Infrastructure
Saudi Arabia Data Center Market
Data Center Infrastructure
Data Center Monitoring Systems Market
Data Center Infrastructure
Data Center Transformation Market
Data Center Infrastructure
Hong Kong Data Center Server Market
Data Center Infrastructure
Europe Automated Storage and Retrieval System Market
Data Center Infrastructure
Nigeria Data Center Market
Data Center Infrastructure
Switzerland Data Center Rack Market
Data Center Infrastructure
Chile Data Center Processor Market
Data Center Infrastructure
Japan Data Center Construction Market