
 Malaysia Courier, Express, and Parcel (CEP) Market | 2026-2036
Malaysia Courier, Express, and Parcel (CEP) Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Courier, Express, and Parcel (CEP) Market Insights
Real-time tracking infrastructure is fragmenting traditional last-mile operations across the Malaysian CEP landscape. J&T Express leverages its extensive regional sorting hub network to sustain delivery density in Peninsular Malaysia. POS Malaysia Bhd anchors universal service obligations through its postal heritage infrastructure. Ninja Van competes aggressively on cross-border parcel consolidation into Singapore and Thailand.
Courier, Express, and Parcel services constitute integrated logistics solutions encompassing document transmission, time-definite freight, and standard parcel distribution through multimodal networks. These services rely on automated sorting systems, barcode tracking protocols, and dynamic route optimization to achieve delivery windows ranging from same-day to international deferred transit. Same-day service commands premium positioning within the service type architecture, while ground delivery mode dominates domestic cost structures due to Malaysia's peninsular geography. E-commerce customer type segments absorb the majority of volume growth, though B2B healthcare logistics generates disproportionate margin capture through temperature-controlled handling requirements.
Malaysian Communications and Multimedia Commission postal regulations govern licensing thresholds and service quality benchmarks for domestic operators. Customs Department procedures and ASEAN single window protocols shape cross-border clearance efficiency for international express shipments. Stakeholders must monitor evolving drone delivery pilot zones and carbon accounting mandates as these frameworks crystallize operational compliance requirements.
Market Dynamics
E-commerce parcel volumes are compressing delivery density economics across Peninsular Malaysia's logistics networks. Real-time tracking infrastructure and automated sorting systems are redrawing operational boundaries between express and standard parcel tiers.
Growth Catalysts
- ASEAN Single Window protocols:Cross-border clearance acceleration through harmonized customs documentation is reducing dwell times at Malaysia-Thailand and Malaysia-Singapore corridors.
- Temperature-controlled healthcare logistics:Cold chain infrastructure expansion for biologics and vaccines is creating premium service tier demand within B2B customer segments.
- Klang Valley urban density:Concentrated e-commerce consumption across Kuala Lumpur and Selangor is enabling same-day delivery network economics at scale.
Market Restraints
- Diesel price volatility:Ground transportation cost exposure constrains margin expansion for domestic last-mile operators dependent on road freight.
- Sorting hub concentration:Capital-intensive automated facilities cluster in Shah Alam and Petaling Jaya, creating regional capacity bottlenecks during peak seasons.
- Drone delivery airspace restrictions:Malaysian Civil Aviation Authority unmanned aircraft regulations limit autonomous last-mile deployment in urban zones.
Strategic Opportunities
- East Malaysia connectivity gaps:Sarawak and Sabah remain underserved for express delivery services, offering first-mover network establishment potential.
- Carbon accounting mandates:Malaysian Communications and Multimedia Commission sustainability reporting requirements favor operators with electric vehicle fleet transition plans.
- Blockchain-tracked cross-border consolidation:Immutable shipment documentation convergence with IoT sensors is enabling trust-minimized ASEAN parcel pooling.
Industry Challenges
- Last-mile driver retention:Gig economy platform competition is destabilizing courier workforce stability for established parcel networks.
- Legacy IT integration:ERP system modernization for route optimization APIs demands substantial capital deployment without immediate revenue uplift.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Courier, Express, and Parcel (CEP) Market |
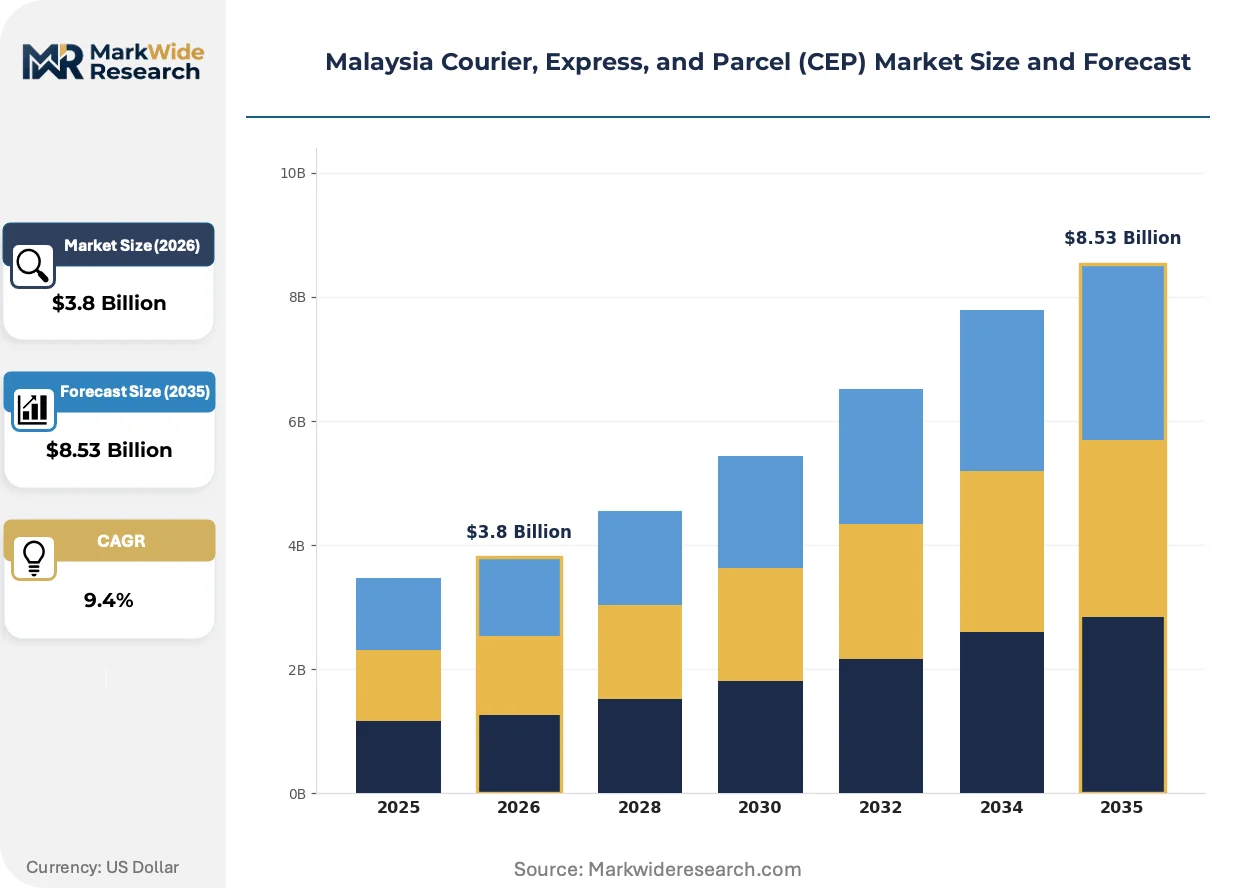
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Same Day, Next Day, International, Standard Delivery Mode: Ground, Air, Sea, Rail Customer Type: Retail, E-commerce, B2B, Healthcare Package Size: Document, Small, Medium, Large |
| Companies Covered | J&T Express, Ninja Van, POS Malaysia Bhd, DHL Group, FedEx, City-Link Express, GDEX Group, SF Express, United Parcel Service of America Inc (UPS), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Courier, Express, and Parcel (CEP) Market Trends and Innovations
Digital freight platforms are fragmenting traditional carrier-shipper relationships across Malaysian logistics corridors. Technology convergence and regulatory pressure are compressing legacy operational models.
Automated parcel sorting systems utilizing machine vision and robotic arm induction are collapsing manual labor requirements at regional distribution hubs. E-commerce fulfillment centers in Selangor are deploying these systems at accelerated replacement cycles. Labor cost compression is enabling 24-hour sortation throughput without shift rotation penalties.
Malaysian Communications and Multimedia Commission postal licensing revisions are tightening service quality benchmarks for domestic operators. Compliance costs are rising for tier-2 carriers lacking real-time tracking infrastructure. Smaller operators are consolidating or exiting rather than absorbing mandatory technology investments.
Buyer procurement patterns are compressing delivery window expectations from next-day to same-day service tiers. B2C e-commerce platforms are unbundling logistics from marketplace fees, forcing direct carrier relationships. This shift concentrates volume with operators possessing urban micro-fulfillment node density in the Klang Valley corridor.
Malaysia Courier, Express, and Parcel (CEP) Market Segmentation
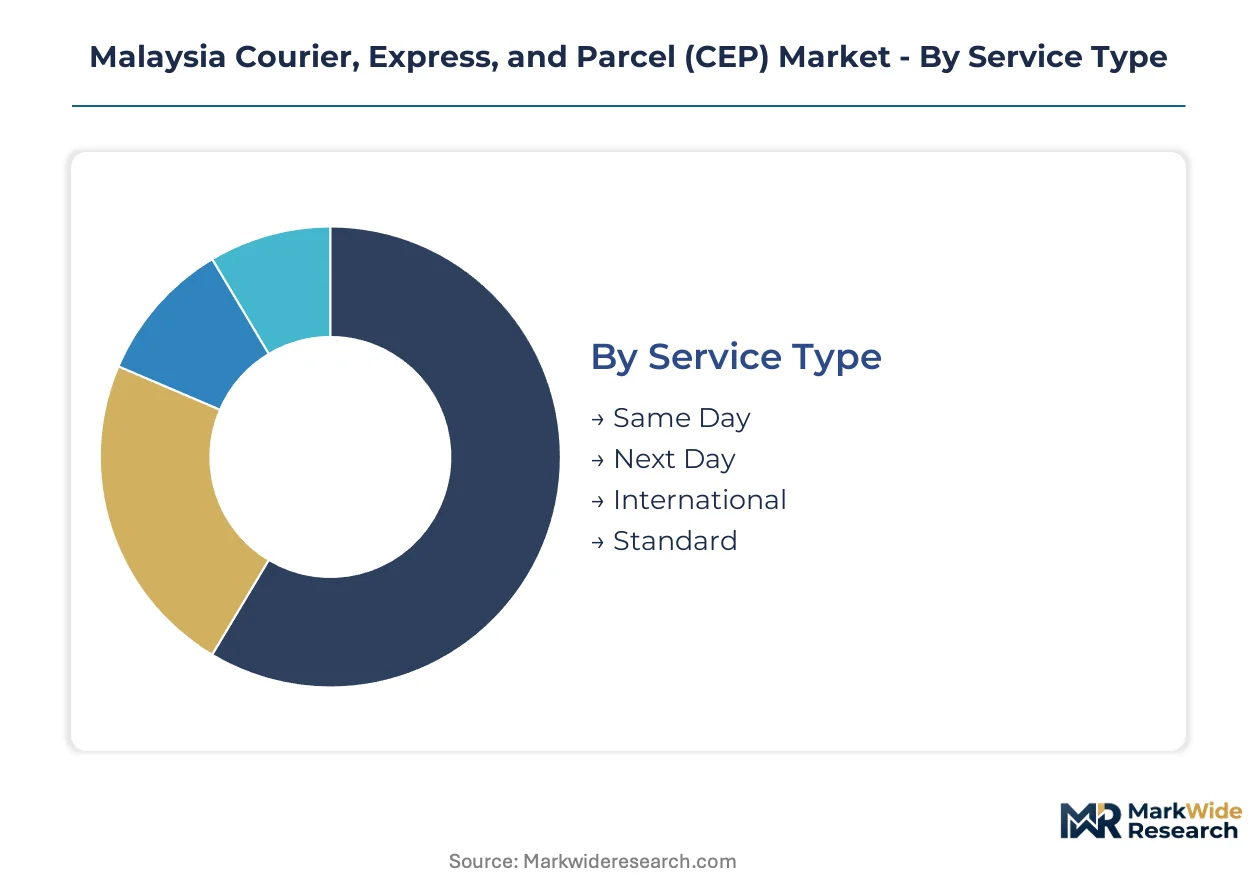
Service tier differentiation determines pricing power and network investment priorities across Malaysian CEP operations. Customer type concentration in e-commerce channels is compressing margin structures while creating volume scale advantages for operators with automated sorting infrastructure.
Service Type:
Cost tier positioning separates premium time-definite offerings from deferred economy services, with each tier demanding distinct operational capabilities and capital deployment profiles.
- Same Day:Ultra-time-critical deliveries within metropolitan boundaries requiring dedicated courier fleets and micro-fulfillment node density. Klang Valley urban concentration enables route optimization algorithms to achieve sub-six-hour windows for high-value electronics and perishable goods.
- Next Day:Deferred express service leveraging overnight sortation at Shah Alam and Petaling Jaya hubs for Peninsular Malaysia coverage. E-commerce platform procurement is compressing this tier toward same-day expectations in Greater Kuala Lumpur.
- International:Cross-border express and deferred parcel services through ASEAN Single Window corridors into Singapore and Thailand. Malaysian Customs Department clearance protocols and air freight slot access determine competitive positioning.
- Standard:Economy ground-based delivery with extended transit windows for non-urgent parcel flows. Cost-sensitive SME shippers and marketplace sellers dominate volume intake.
Standard service commands the established base. The steepest expansion runs through Same Day.
Delivery Mode:
Transport modality selection traces Malaysia's peninsular geography and the infrastructure gaps separating West from East Malaysia.
- Ground:Road freight networks dominate domestic cost structures across Peninsular Malaysia's highway corridor linking Johor Bahru through Kuala Lumpur to Penang. Diesel price volatility constrains margin stability for fleet-dependent operators.
- Air:Time-critical express shipments through Kuala Lumpur International Airport and Subang cargo terminals. Cross-border ASEAN connectivity depends on belly-hold capacity and dedicated freighter schedules.
- Sea:Inter-island ferry consolidation for East Malaysia connectivity to Sarawak and Sabah. Port Klang transshipment delays create dwell time penalties for non-urgent freight.
- Rail:Emerging multimodal option through KTM freight corridors for bulk parcel consolidation between distribution hubs. Track gauge limitations restrict direct container throughput.
Ground transport anchors operational scale. Air freight is gaining share fastest in premium express tiers.
Customer Type:
End-use application diversity creates divergent service requirements from temperature-controlled handling to bulk B2B scheduling.
- Retail:Traditional brick-and-mortar replenishment with fixed delivery windows and palletized freight requirements. Department store chains and franchise networks maintain contracted carrier relationships.
- E-commerce:Explosive parcel volume growth from marketplace platforms and direct-to-consumer brands. Real-time tracking infrastructure and returns processing capability determine carrier selection.
- B2B:Industrial parts, documents, and contract logistics for manufacturing and financial services. Scheduled route density and proof-of-delivery compliance outweigh speed premiums.
- Healthcare:Temperature-controlled biologics, vaccines, and medical device distribution requiring GDP compliance and cold chain validation. Malaysian Medical Device Authority regulations govern handling protocols.
E-commerce absorbs the volume surge. Healthcare generates the highest margin capture per shipment.
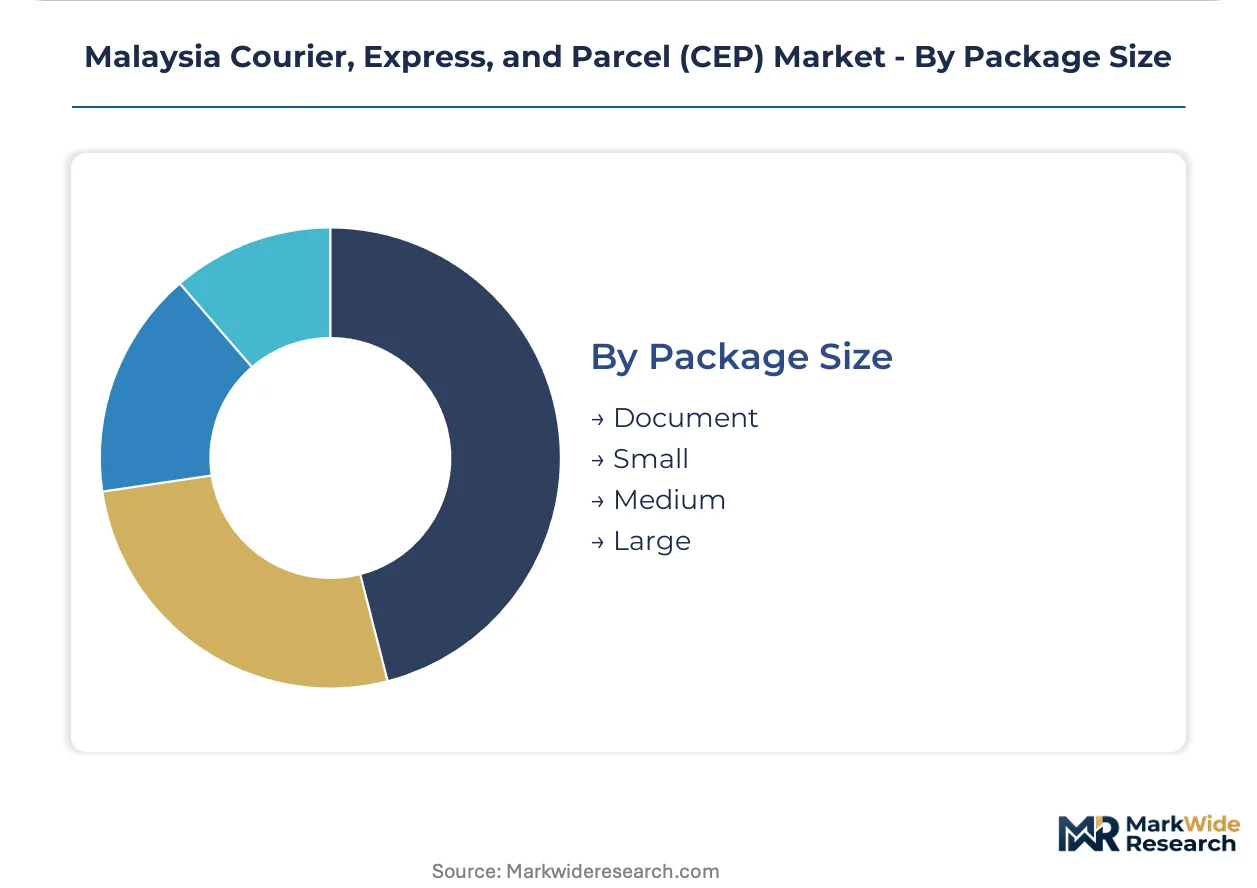
Package Size:
Physical dimension and weight classification sort parcels into distinct handling infrastructure and pricing brackets.
- Document:Lightweight envelope shipments under one kilogram requiring minimal sortation handling. Financial services and legal sectors sustain demand despite digital displacement.
- Small:Individual e-commerce parcels fitting standard polybag and small carton profiles. Automated sortation systems at Selangor hubs process these at highest throughput rates.
- Medium:Multi-item orders and SME B2B shipments requiring manual handling intervention. Dimensional weight pricing creates cost optimization incentives.
- Large:Bulky freight exceeding standard parcel dimensions, often requiring dedicated vehicle allocation. Furniture and appliance e-commerce is expanding this tier's relevance.
Small parcels dominate throughput volume. Large format is expanding most quickly with home delivery furniture growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
E-commerce platform procurement teams in Southeast Asia are consolidating carrier relationships around operators with ASEAN Single Window clearance capabilities. Malaysia's CEP demand concentrates in the Klang Valley corridor where same-day delivery density economics favor automated sortation infrastructure.
Indonesia
Marketplace giants Tokopedia and Shopee Indonesia are driving parcel volume surges through Jakarta-Bandung-Surabaya logistics triangles. The Ministry of Communication and Informatics postal licensing framework governs last-mile operator permits and service quality mandates. Bekasi and Bogor satellite cities host automated fulfillment centers where 24-hour sortation throughput is compressing delivery windows toward same-day service tiers.
Singapore
Cross-border consolidation hubs serving Malaysian e-commerce exporters depend on Changi cargo terminal belly-hold capacity and dedicated freighter schedules. The Infocomm Media Development Authority regulates postal service standards and data localization requirements for tracking platforms. Jurong logistics clusters anchor ASEAN parcel pooling operations where blockchain-tracked documentation is reducing trust friction in multimodal handoffs.
Thailand
Bangkok metropolitan consumption density enables route optimization algorithms to achieve sub-six-hour delivery windows for high-value electronics. The Ministry of Digital Economy and Society postal regulatory revisions are tightening real-time tracking infrastructure requirements for domestic operators. Samut Prakan and Pathum Thani distribution zones concentrate automated sorting systems where labor cost compression supports 24-hour operations without shift rotation penalties.
Vietnam
Ho Chi Minh City and Hanoi e-commerce penetration is accelerating parcel volume growth through Lazada and Tiki platform procurement. The Ministry of Information and Communications governs postal licensing thresholds and service quality benchmarks for express operators. Binh Duong and Bac Ninh industrial provinces host fulfillment centers where temperature-controlled healthcare logistics infrastructure is expanding for biologics distribution.
Philippines
Metro Manila logistics networks are fragmenting traditional carrier-shipper relationships through digital freight platform intermediation. The Department of Information and Communications Technology postal regulatory framework shapes market entry conditions and universal service obligations. Cavite and Laguna logistics corridors concentrate automated sortation hubs where diesel price volatility is constraining margin stability for fleet-dependent operators.
Malaysia Courier, Express, and Parcel (CEP) Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered service architectures where automated sortation infrastructure determines pricing power. The vendor base clusters around three strategic archetypes: regional network operators with ASEAN hub density, postal heritage incumbents anchoring universal service obligations, and cross-border specialists leveraging customs clearance integration. Consolidation pressure favors operators with electric vehicle fleet transition plans aligned to emerging carbon accounting mandates. Competitive moves concentrate on micro-fulfillment node density expansion in urban corridors and blockchain-tracked documentation convergence with IoT sensors.
Within the regional network operator tier, J&T Express and Ninja Van exemplify archetypes competing on delivery density across Peninsular Malaysia. POS Malaysia Bhd occupies a position representing postal heritage infrastructure anchoring universal service coverage. These three entities sit within competitive dynamics where real-time tracking capability and cross-border clearance efficiency determine procurement team carrier selection.
| Leading Market Players |
|---|
| J&T Express |
| Ninja Van |
| POS Malaysia Bhd |
| DHL Group |
| FedEx |
| City-Link Express |
| GDEX Group |
| SF Express |
| United Parcel Service of America Inc (UPS) |
| Others |
Pricing and Supply Chain Analysis
Automated sorting hub concentration in Shah Alam and Petaling Jaya anchors upstream capital intensity, directing margin pools toward operators with 24-hour throughput capability and real-time tracking infrastructure. Diesel price volatility across Peninsular Malaysia's highway corridors feeds back into fleet composition choices, accelerating electric vehicle transition timelines among tier-1 carriers.
Pricing Analysis
Cost-plus contracts with diesel price indexation dominate ground freight arrangements between e-commerce platforms and last-mile operators. Three-tier pricing structure across same-day, next-day, and standard service levels separates premium time-definite offerings from deferred economy tiers. Cost compression in standard parcel services is intensifying because e-commerce marketplace procurement teams are unbundling logistics fees and forcing direct carrier negotiations. SME marketplace sellers exhibit highest price sensitivity, while healthcare B2B shippers accept premium positioning for GDP-compliant cold chain handling.
Supply Chain Analysis
Extended payment terms from e-commerce platforms to last-mile operators have normalized 60-90 day receivables cycles, straining working capital for tier-2 carriers lacking supply-chain finance facilities. Sorting equipment and tracking hardware draws from China, South Korea, and Taiwan, while diesel and electric vehicle fleets rest on Malaysian petroleum distribution networks and regional battery supply chains. Single-source vulnerability concentrates in automated sortation system providers, with Shah Alam and Petaling Jaya hub capacity creating regional chokepoints during peak seasons. Distribution runs through hub-and-spoke networks anchored by Selangor sorting facilities and radiating via ground freight to Peninsular Malaysia nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
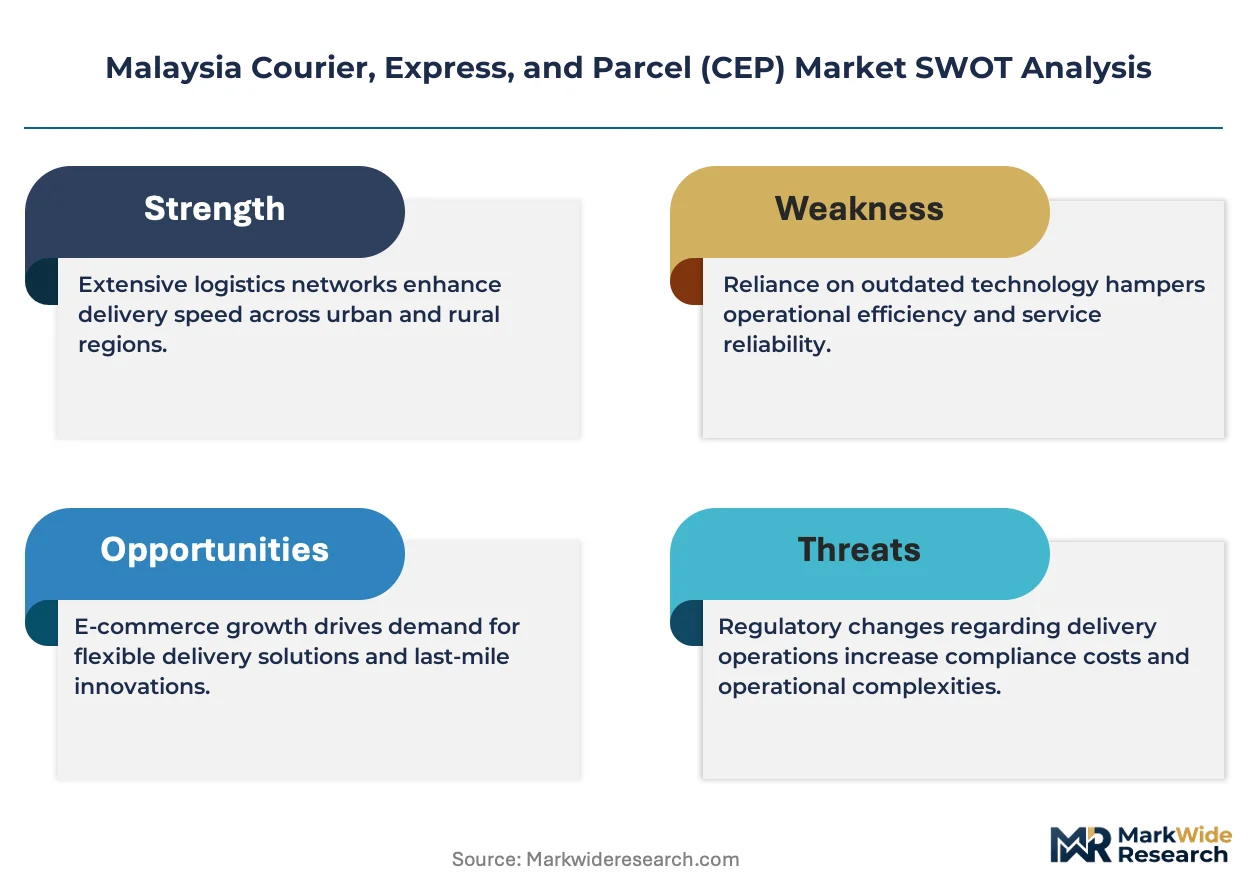
Malaysia's CEP market sits at a platform-economics inflection where e-commerce marketplace unbundling of logistics fees is forcing direct carrier-shipper relationships and compressing intermediary margins. Interoperability shifts around ASEAN Single Window customs documentation and blockchain-tracked cross-border consolidation are redrawing competitive boundaries between express and standard parcel tiers.
For Market Incumbents: Pre-empt platform disintermediation by securing exclusive same-day delivery contracts with high-volume e-commerce marketplaces in the Klang Valley corridor. Defend against Ninja Van and J&T Express density advantages through micro-fulfillment node expansion in Kuala Lumpur and Selangor urban zones. Anchor retention via electric vehicle fleet transition plans aligned to Malaysian Communications and Multimedia Commission carbon accounting mandates.
For New Entrants and Emerging Players: Establish a beachhead in East Malaysia express delivery services where Sarawak and Sabah remain underserved for time-definite offerings. Target temperature-controlled healthcare logistics for biologics distribution, leveraging GDP compliance gaps among established carriers. Penetrate via partnerships with Malaysian Medical Device Authority-certified cold chain facilities rather than asset-heavy hub construction.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier carriers possessing ASEAN Single Window clearance integration and scalable tracking infrastructure but lacking balance sheet depth for automated sorting hub investments. Long-term viability hinges on network density in the Klang Valley corridor and cross-border consolidation capabilities into Singapore and Thailand. Watch drone delivery pilot zone approvals by the Malaysian Civil Aviation Authority as signal for autonomous last-mile inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Micro-Fulfillment Node Expansion | Densifies same-day delivery coverage across Kuala Lumpur and Selangor urban corridors. |
| Electric Vehicle Fleet Transition | Aligns operational compliance with Malaysian Communications and Multimedia Commission carbon reporting mandates. |
| ASEAN Single Window Integration | Accelerates cross-border clearance efficiency for Malaysia-Singapore and Malaysia-Thailand parcel corridors. |
| Blockchain-Tracked Documentation | Enables trust-minimized parcel pooling through immutable shipment records converged with IoT sensors. |
| Cold Chain Infrastructure Buildout | Captures premium margin tiers in GDP-compliant biologics and vaccine distribution for healthcare B2B segments. |
Research Methodology
Cross-validation between primary interviews with logistics operations directors, e-commerce procurement leads, fleet managers, and customs brokerage specialists and secondary validation through Malaysian Communications and Multimedia Commission postal licensing records, ASEAN Single Window protocol documentation, and Malaysian Customs Department clearance statistics anchors the qualitative findings. Bottom-up parcel volume modeling across service type, delivery mode, customer type, and package size dimensions triangulates against top-down macroeconomic consumption indicators and e-commerce penetration benchmarks.
Calibration against historical volume trajectories and regulatory implementation timelines shapes the analytical framework across the analysis window. Segmentation dimensions modeled include service tier architecture, transport modality mix, end-use application concentration, and physical parcel profile distribution. CAGRs were derived from elasticity-adjusted demand projections incorporating e-commerce platform growth curves, automated sortation capacity deployment schedules, and cross-border trade corridor expansion patterns.
Sensitivities concentrate around diesel price volatility trajectories, drone delivery regulatory liberalization pacing, and e-commerce marketplace logistics unbundling acceleration. Forecasts reflect documented assumptions regarding infrastructure deployment timelines and regulatory enforcement intensity. Macroeconomic contraction, accelerated carbon mandate implementation, or autonomous delivery technology breakthroughs would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Germany Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
North America Automotive Logistics Market
Logistics and Shipping
Water Hauling Services Market
Logistics and Shipping
ISO Shipping Container Market
Logistics and Shipping
Japan Third-Party Logistics (3PL) Market
Logistics and Shipping
Smart Container Market
Logistics and Shipping
Fine Art Logistics Market
Logistics and Shipping
US Hazardous Goods Logistics Market
Logistics and Shipping
Germany Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Germany Automotive 3PL Market
Logistics and Shipping
Sweden Freight and Logistics Market
Logistics and Shipping
Car Carrier Market
Logistics and Shipping
Turkey Freight and Logistics Market
Logistics and Shipping
Armenia Freight and Logistics Market
Logistics and Shipping
Egypt Third Party Logistics (3PL) Market
Logistics and Shipping
Europe Automotive Logistics Market