
 GCC International Express Service Market | 2026-2036
GCC International Express Service Market Size, Share, and Industry Trends Forecast 2026-2036
GCC International Express Service Market Insights
Modular service bundling is repositioning buyer choice in the GCC express landscape, as carriers unbundle customs brokerage from core transport to create configurable procurement packages. Aramex leverages its regional hub infrastructure to anchor last-mile density across secondary Gulf cities. DHL Group sustains premium positioning through controlled temperature-chain capabilities for pharmaceutical shippers. FedEx competes on intercontinental lane breadth, connecting Gulf origins to North American and Asian gateways.
GCC international express service encompasses time-definite cross-border shipment solutions combining air cargo uplift, customs facilitation, and destination delivery within contracted transit windows, typically operating on 24–96 hour service commitments depending on lane distance and clearance complexity. Standard Express and Next-Day Delivery command the dominant revenue share, while Same-Day Delivery concentrates margin pools around high-value electronics and urgent industrial parts movements from Dubai and Doha. E-commerce Retailers represent the fastest-expanding customer type, pressuring carriers to integrate real-time tracking APIs and flexible delivery windows into platform checkout flows.
SFDA and Saudi Customs Authority frameworks govern pharmaceutical and controlled-goods express movements into the Kingdom, while UAE Federal Customs Authority regulations shape duty-de minimis thresholds that directly determine e-commerce parcel economics. Stakeholders must monitor evolving national data-localization requirements for shipment manifests, as Gulf regulators tighten cross-border information governance without harmonizing protocols across member states.
Market Dynamics
Modular unbundling of express service components is restructuring carrier-buyer relationships across Gulf markets, as customs brokerage separates from core transport to create configurable procurement architectures. This fragmentation is accelerating price transparency and compressing margin pools for bundled incumbents.
Growth Catalysts
- UAE Federal Customs Authority modernization:Streamlined clearance protocols reduce dwell times at Dubai International Airport, enabling tighter service commitments for e-commerce retailers.
- Pharmaceutical cold-chain infrastructure:Temperature-controlled express corridors expand as SFDA frameworks mandate validated distribution for biologics entering Saudi Arabia.
- Riyadh-Jeddah volume concentration:Premium delivery tiers concentrate demand in Saudi Arabia's two largest metropolitan clusters, supporting route density investments.
Market Restraints
- Jet fuel price volatility:Fuel represents the largest variable cost component for air cargo uplift, with Gulf carriers exposed to regional refinery capacity constraints.
- Data-localization fragmentation:Non-harmonized manifest requirements across GCC member states force redundant compliance systems without unified protocols.
- Last-mile labor scarcity:Secondary Gulf cities face driver recruitment bottlenecks that limit expansion of guaranteed delivery windows.
Strategic Opportunities
- Oman and Kuwait underpenetration:Express network density remains below UAE and Saudi levels, creating first-mover advantages for localized hub investments.
- Real-time tracking API convergence:Integration of carrier systems with e-commerce checkout flows enables dynamic delivery option presentation at point of purchase.
- Same-day industrial parts:Urgent manufacturing components from Doha's free zones represent an emerging premium segment with limited current competition.
Industry Challenges
- Customs broker licensing timelines:Saudi Customs Authority certification delays for foreign operators compress implementation schedules for cross-border launches.
- Legacy warehouse management integration:Port community systems in older Gulf facilities require middleware development to connect with modern tracking platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC International Express Service Market |
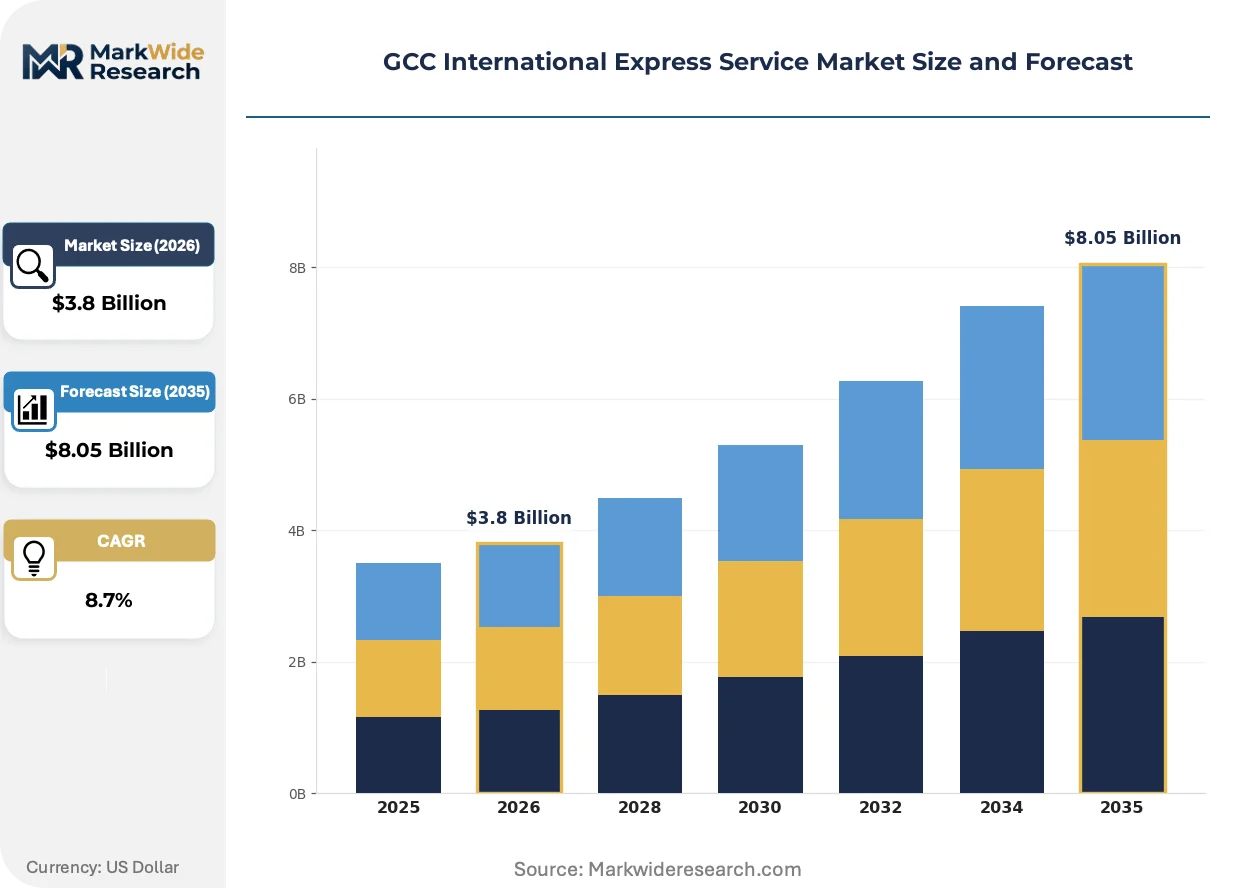
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Standard Express, Same-Day Delivery, Next-Day Delivery, International Freight Delivery Mode: Air Freight, Ground Shipping, Ocean Freight, Rail Transport Customer Type: Small Businesses, E-commerce Retailers, Corporations, Individuals Pricing Model: Flat Rate, Variable Rate, Subscription, Pay Per Use |
| Companies Covered | Postaplus, Emirates Post, Aramex, SMSA Express, Saudi Post-SPL, DHL Group, United Parcel Service of America, Inc. (UPS), Qatar Post, FedEx, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC International Express Service Market Trends and Innovations
Digital infrastructure investments are compressing information asymmetries between carriers and shippers across Gulf express markets. Real-time visibility platforms and automated customs pre-clearance are converging to redefine service-level benchmarks.
Blockchain-enabled shipment documentation is integrating with UAE Federal Customs Authority pre-arrival processing systems. Pharmaceutical shippers and high-value electronics retailers are adopting these verified data corridors fastest. This integration is compressing clearance uncertainty and enabling shorter quoted transit windows without buffer provisions.
SFDA serialization mandates for pharmaceutical imports are tightening track-and-trace requirements across Saudi entry points. Manufacturers must now embed unique identifiers at unit level before express uplift. Temperature-sensitive biologics and controlled substances face the steepest compliance ramps, with carriers investing in validated thermal packaging and chain-of-custody documentation.
E-commerce checkout flows are embedding carrier selection interfaces directly into retailer platforms. Fashion and consumer electronics marketplaces in Dubai and Riyadh now surface real-time rate and delivery window comparisons. This disintermediation of traditional freight forwarding relationships is most advanced among digitally native retailers with captive logistics development teams.
GCC International Express Service Market Segmentation
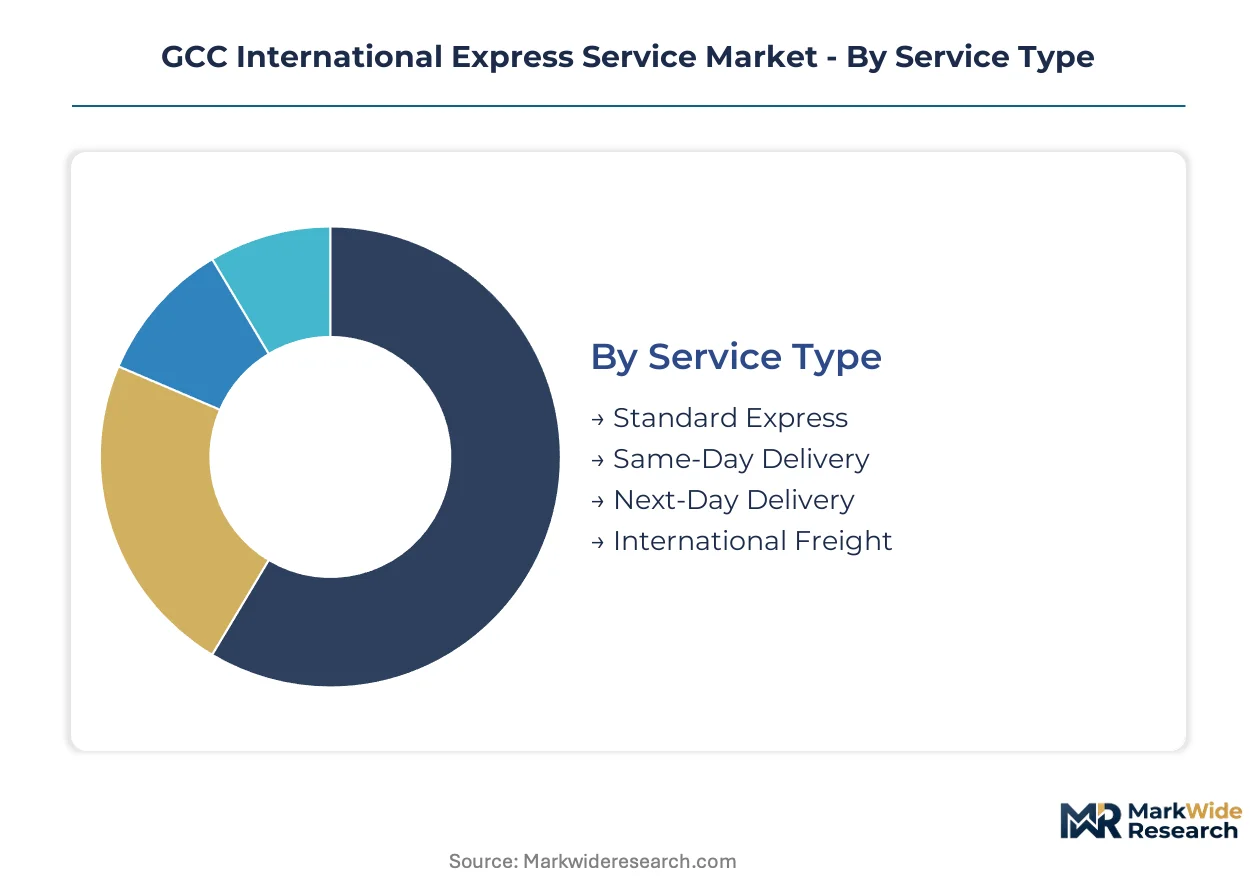
Express service segmentation in the Gulf Cooperation Council reflects divergent operational economics across service tiers and customer procurement patterns. Carrier network investments concentrate where margin structures justify dedicated capacity, creating distinct competitive arenas within each dimension.
Service Type:
Supply concentration in premium time-definite corridors shapes carrier fleet deployment and customs brokerage specialization across the GCC.
- Standard Express:Operates on 48–96 hour committed windows with consolidated air cargo uplift and deferred customs processing. Riyadh and Jeddah absorb the highest shipment volumes for this tier, driven by corporate procurement contracts seeking predictable cost structures over velocity.
- Next-Day Delivery:Demands dedicated air cargo capacity and pre-arrival customs clearance with 24-hour service commitments. Dubai International Airport anchors regional volume for this segment, where UAE Federal Customs Authority modernization programs compress dwell times to enable tighter quoted windows.
- Same-Day Delivery:Requires courier networks with immediate pickup capability and direct airport injection for morning departures. Doha's free zones and Dubai's e-commerce fulfillment clusters generate concentrated demand for urgent industrial parts and high-value electronics movements.
- International Freight:Encompasses deferred ocean-air combinations and consolidated LTL solutions for non-urgent cross-border movements. Secondary Gulf cities rely on this tier for cost-sensitive commercial shipments lacking time-critical requirements.
Standard Express absorbs the bulk of installed capacity; Same-Day Delivery is expanding most quickly.
Delivery Mode:
Cost tier differentiation across transport modes determines which corridors sustain dedicated versus shared capacity economics in Gulf markets.
- Air Freight:Dominates time-definite express with controlled temperature-chain capabilities for pharmaceutical shippers under SFDA frameworks. Dubai International and King Abdulaziz International anchor regional air cargo infrastructure.
- Ground Shipping:Connects UAE-Saudi corridor with dedicated fleet investments, leveraging Riyadh-Jeddah route density for premium road feeder services. Border modernization reduces transit friction on this lane.
- Ocean Freight:Serves deferred express segments with sea-air combinations through Jebel Ali and Dammam port corridors. E-commerce retailers utilize this mode for pre-positioned inventory flows.
- Rail Transport:Emerging as Etihad Rail infrastructure expands UAE-Saudi connectivity, though current express utilization remains limited to select bulk commodity movements.
Air Freight commands the dominant share of premium express value; Ground Shipping is climbing the fastest as corridor investments mature.
Customer Type:
Procurement sophistication varies sharply across buyer categories, dictating API integration requirements and contract structure complexity.
- E-commerce Retailers:Demand real-time tracking API convergence with checkout flow integration for dynamic delivery option presentation. Fashion and consumer electronics marketplaces in Dubai and Riyadh drive platform standardization pressures.
- Corporations:Negotiate annual contracts with modular unbundling of customs brokerage from core transport, creating configurable procurement architectures with dedicated account management.
- Small Businesses:Rely on self-service digital platforms with flat-rate simplicity, though customs documentation support requirements vary by shipment complexity.
- Individuals:Represent fragmented demand concentrated around gift shipments and personal effects, with limited price elasticity for documented delivery certainty.
Corporations anchor contracted revenue stability; E-commerce Retailers are gaining share fastest through volume expansion.
Pricing Model:
Margin structure transparency accelerates as digital platforms disintermediate traditional freight forwarding relationships across Gulf express markets.
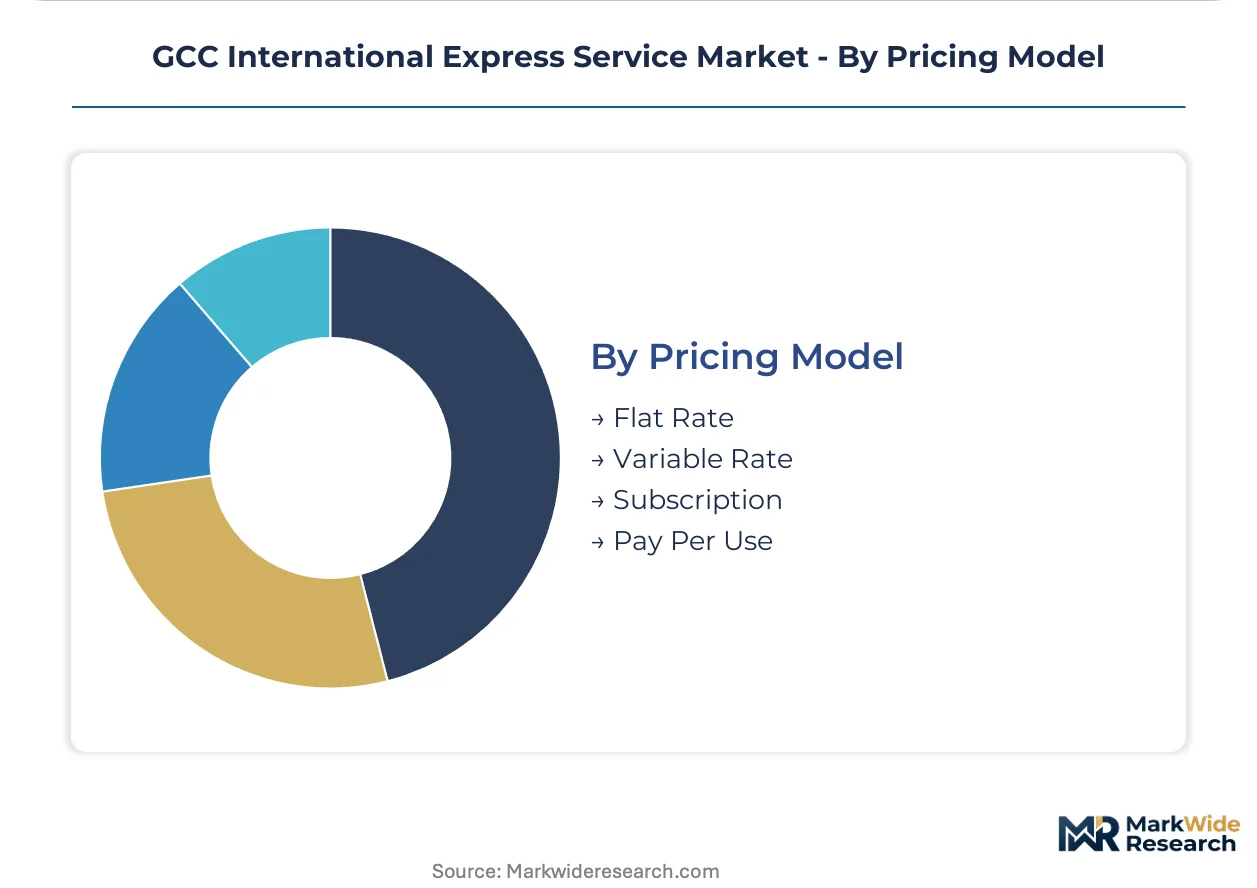
- Flat Rate:Simplifies procurement for standardized lane pairs with predictable weight breaks, dominating small business and individual segments where administrative simplicity outweighs optimization.
- Variable Rate:Ties pricing to fuel indices, capacity utilization, and seasonal demand swings, reflecting true cost volatility in air cargo corridors. Corporate contracts increasingly adopt this structure.
- Subscription:Offers committed volume discounts with monthly minimums, appealing to e-commerce retailers with predictable shipment frequencies and platform-native logistics teams.
- Pay Per Use:Eliminates commitment requirements for intermittent shippers, though per-shipment premiums reflect higher carrier risk allocation and administrative overhead.
Flat Rate retains the largest transaction volume base; Subscription is expanding most quickly among digitally mature retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's free zones and Saudi Arabia's logistics cities concentrate GCC express infrastructure investment. Tax incentives in Jebel Ali Free Zone and King Abdullah Economic City anchor carrier hub strategies. Regulatory modernization across member states reshapes clearance economics.
United Arab Emirates
E-commerce fulfillment clusters in Dubai generate concentrated express demand for fashion and electronics movements. UAE Federal Customs Authority pre-arrival processing systems compress dwell times at Dubai International Airport. Jebel Ali Free Zone serves as the primary consolidation point for Gulf air cargo uplift.
Saudi Arabia
SFDA serialization mandates for pharmaceutical imports tighten track-and-trace requirements across Saudi entry points. King Abdullah Economic City attracts carrier investments with bonded warehouse incentives and streamlined licensing. Riyadh and Jeddah metropolitan clusters generate the highest shipment volumes for premium delivery tiers.
Qatar
Industrial free zones in Doha produce urgent manufacturing components requiring same-day express corridors. The country's national customs authority maintains strict manifest documentation standards for cross-border movements. Ras Laffan industrial cluster generates specialized demand for time-critical energy sector logistics.
Oman
Express network density remains below UAE and Saudi levels, creating first-mover advantages for localized hub investments. Port community systems in Sohar require middleware development to connect with modern tracking platforms. Muscat metropolitan area shows emerging demand concentration from retail sector expansion.
Kuwait
Secondary city logistics infrastructure lags primary Gulf markets in last-mile density and delivery window guarantees. The country's national customs administration operates independent protocols from neighboring member states. Kuwait City commercial district generates consolidated demand for corporate procurement contracts.
GCC International Express Service Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Gulf express corridors. The vendor base spans global integrators, regional champions, and national postal operators with varying degrees of network control. Three archetypes dominate: global network integrators with intercontinental lane breadth, regional hub operators with last-mile density in secondary cities, and state-affiliated postal services with last-mile coverage obligations. Competitive moves concentrate on customs brokerage licensing acquisitions and real-time tracking API development partnerships.
Within the regional hub operator tier, Aramex exemplifies infrastructure-led positioning through Gulf secondary city penetration. Among global integrators, DHL Group and FedEx occupy positions differentiated by temperature-chain capabilities versus intercontinental lane breadth. Emirates Post and Saudi Post-SPL represent state-affiliated archetypes with mandated universal service obligations and domestic coverage advantages.
| Leading Market Players |
|---|
| Postaplus |
| Emirates Post |
| Aramex |
| SMSA Express |
| Saudi Post-SPL |
| DHL Group |
| United Parcel Service of America, Inc. (UPS) |
| Qatar Post |
| FedEx |
| Others |
Pricing and Supply Chain Analysis
SFDA serialization mandates for pharmaceutical imports gate both qualified supply and premium-tier pricing access, as carriers must embed validated thermal packaging and chain-of-custody documentation to serve Saudi biologics shippers. This compliance threshold stratifies the market between certified cold-chain operators commanding rate premiums and generalist providers competing on commoditized lanes.
Pricing Analysis
Margin tightening in standard express reflects jet fuel price volatility and e-commerce retailer procurement sophistication. Three-tier pricing structure across premium, standard, and economy levels differentiates service commitments, with temperature-chain certification and real-time API integration as primary price drivers. Cost-down pressure accelerates as digital platforms disintermediate traditional freight forwarding relationships. Small businesses exhibit highest price sensitivity, while pharmaceutical shippers accept premiums for validated distribution.
Supply Chain Analysis
Reverse logistics flows for e-commerce returns concentrate processing capacity in Dubai's Jebel Ali Free Zone and Riyadh's logistics cities. Supply draws from UAE and Saudi Arabia for air cargo uplift infrastructure, with secondary sourcing from Qatar's Doha free zones for urgent industrial parts. Jet fuel and validated thermal packaging constitute critical input dependencies. Single-source vulnerability around Dubai International Airport capacity creates chokepoint exposure. Distribution runs through bonded warehouse networks with pre-arrival customs processing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story, where SFDA serialization mandates and UAE Federal Customs Authority modernization programs erect barrier-to-entry moats favoring carriers with captive regulatory affairs capabilities.
For Market Incumbents: Anchor hub infrastructure investments in Riyadh-Jeddah corridor density to defend against modular unbundling pressures from digital-native competitors. Deepen backward integration into customs brokerage licensing to preserve margin pools, while accelerating real-time tracking API partnerships with e-commerce platforms to lock in platform-native retailers.
For New Entrants and Emerging Players: Begin with Oman and Kuwait underpenetration, where express network density remains below UAE and Saudi levels and localized hub investments yield first-mover advantages. Target urgent manufacturing components from Doha's free zones as the most penetrable premium segment, utilizing same-day industrial parts specialization as the go-to-market angle.
For Investors and Strategic Acquirers: Customs broker licensing acquisition announcements by regional hub operators are the leading indicator that consolidation momentum is accelerating. Long-term viability centers on carriers controlling both physical infrastructure and digital integration layers. Target mid-cap specialists with validated cold-chain capabilities and existing SFDA compliance frameworks. Monitor blockchain-enabled shipment documentation adoption rates for early signals of clearance economics transformation.
| Strategic Initiative | Industry Significance |
|---|---|
| Customs Brokerage Licensing Acquisition | SFDA certification timelines compress implementation schedules for cross-border launches. |
| Cold-Chain Infrastructure Expansion | Validated thermal packaging investments enable biologics distribution under Saudi pharmaceutical frameworks. |
| Real-Time Tracking API Development | Integration with Dubai and Riyadh e-commerce checkout flows locks in platform-native retailers. |
| Secondary City Hub Investment | Oman and Kuwait network density gaps create first-mover advantages for localized capacity. |
| Blockchain Documentation Integration | UAE Federal Customs Authority pre-arrival processing systems compress clearance uncertainty windows. |
Research Methodology
Independent corroboration across carrier network operations directors, e-commerce logistics procurement leads, and customs brokerage specialists underwrites the qualitative findings. Primary interviews with pharmaceutical supply chain managers and free zone authority planners combined with secondary validation from UAE Federal Customs Authority regulatory filings, SFDA serialization mandate documentation, and Dubai International Airport throughput disclosures. Bottom-up shipment volume modeling and top-down market sizing triangulation anchored the analysis.
Rate-of-change decomposition across service tiers, customer procurement patterns, and corridor-specific capacity investments structured the analytical framework. Segmentation dimensions modeled include service type commitment windows, delivery mode cost tiers, customer API integration requirements, and pricing model contract structures. CAGRs derived from corridor-level volume trajectories and lane-specific yield evolution, with jet fuel indices and customs modernization implementation timelines as industry-specific forecast inputs.
Regulatory harmonization delays, jet fuel price volatility spikes, and e-commerce platform insourcing decisions are the dominant revision risks. Forecasts reflect assumptions around SFDA enforcement consistency and UAE customs modernization pace. Practitioners should monitor blockchain documentation adoption rates and carrier-customs API integration announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
ASEAN Cold Chain Logistics Market
Transportation & Logistics
Slovakia Road Freight Transport Market
Transportation & Logistics
Europe Reverse Logistic Market
Transportation & Logistics
Ride-Hailing and Taxi Market
Transportation & Logistics
Germany Road Freight Transport Market
Transportation & Logistics
Japan Cold Chain Logistics Market
Transportation & Logistics
Poland Road Freight Transport Market
Transportation & Logistics
Reverse Logistics Market
Transportation & Logistics
Canada Customs Brokerage Market
Transportation & Logistics
Transport Refrigeration Unit (TRU) Market
Transportation & Logistics
Middle-East and North Africa Taxi Market
Transportation & Logistics
Rental and Subscription Product Logistics Orchestration Platforms Market
Transportation & Logistics
Malaysia Refrigerated Trailer Market
Transportation & Logistics
North America Road Freight Transportation Market
Transportation & Logistics
Global Automotive 3PL Market
Transportation & Logistics
Refrigerated Road Transportation Market