
 Turkey Freight and Logistics Market | 2026-2036
Turkey Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Turkey Freight and Logistics Market Analytics
E-commerce shippers is unwinding traditional wholesale freight patterns as Turkey's consumer delivery expectations tighten. Borusan Logistics leverages its captive rail and port assets to control east-west cargo corridors. Ekol Logistics sustains cross-border dominance through integrated European-Turkish road networks. BARSAN Global Logistics anchors automotive just-in-time supply chains with specialized flatbed and containerized services.
Turkey Freight and Logistics encompasses the physical movement, storage, and customs facilitation of goods across domestic and international corridors, typically operating through multimodal chains combining road haulage with rail, maritime, and air feeder links. The sector functions as the circulatory infrastructure for manufacturing exports, retail distribution, and port-to-hinterland container evacuation. Transportation and freight forwarding command the largest revenue pools, while warehousing margins expand fastest near Istanbul's Gebze-Tuzla industrial belt and the Ankara-Sivas rail axis. Blockchain and IoT deployments in customs clearance and fleet tracking represent the fastest-growing technology segment, though AI-driven demand forecasting remains nascent outside the largest integrators.
Turkey's Ministry of Transport and Infrastructure shapes corridor development through the Middle Corridor initiative and port privatization frameworks, while the Turkish Standards Institution enforces vehicle emissions and cargo securing protocols that filter fleet renewal decisions. The Customs Administration's digitalization mandates under the Trade Facilitation Agreement are accelerating single-window adoption and reducing dwell times at border crossings. Stakeholders must monitor how EU Carbon Border Adjustment Mechanism alignment pressures reshape Turkish exporter logistics contracts and modal choices.
Market Dynamics
The Middle Corridor rail initiative is compressing transit times between China and Europe, forcing Turkish logistics operators to reposition warehousing assets along the Ankara-Sivas-Kars axis or lose east-west cargo flows to competing Black Sea routes.
Growth Catalysts
- E-commerce fulfillment density:Consumer delivery expectations in Istanbul, Izmir, and Ankara are pulling inventory closer to population centers, expanding cold-chain and last-mile depot networks across Anatolia.
- EU Carbon Border Adjustment Mechanism alignment:Turkish exporters face new documentation requirements for embedded emissions, creating demand for certified green logistics providers and modal shift incentives toward rail.
- Port privatization frameworks:The Ministry of Transport and Infrastructure's concession models at Mersin and Izmir are attracting terminal automation investments that accelerate vessel turnaround.
Market Restraints
- Diesel price volatility:Road haulage operators absorb fuel cost swings directly, compressing margins on Istanbul-Ankara corridors where rail alternatives remain underdeveloped.
- Customs digitization gaps:The Customs Administration's single-window platform faces interoperability failures with Bulgarian and Greek border systems, extending dwell times at Kapikule and Ipsala.
- Driver shortage concentration:Long-haul trucking pools are aging without replacement inflows, particularly acute on the Edirne-Silopi transit axis serving Iraqi and Iranian markets.
Strategic Opportunities
- Southeast Anatolia manufacturing zones:Gaziantep and Sanliurfa textile exporters lack integrated logistics parks, presenting first-mover advantages for bonded warehousing and cross-dock facilities.
- Blockchain-IoT customs convergence:Real-time container tracking combined with immutable documentation streams can preempt disputes at Georgian and Azerbaijani transit points.
- Automotive EV supply chain reconfiguration:Battery component imports through Mersin require specialized hazmat handling infrastructure that existing terminals have not deployed.
Industry Challenges
- Warehouse management system fragmentation:Mid-tier 3PLs operate disconnected inventory platforms that block end-to-end visibility for multinational shippers.
- Rail-yard synchronization complexity:State railway scheduling protocols do not align with private operator container release windows, forcing costly buffer stock accumulation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turkey Freight and Logistics Market |
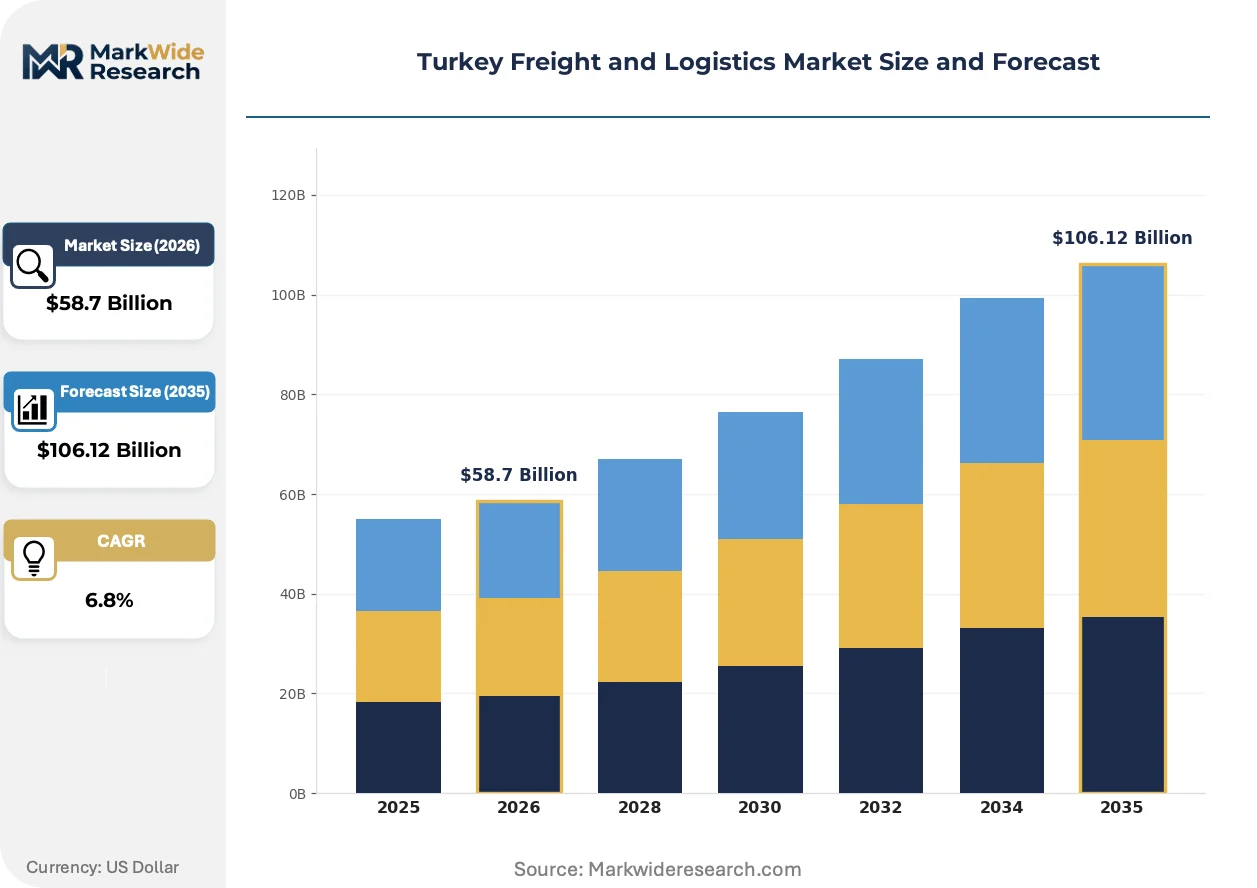
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $106.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Customs Brokerage End User: Manufacturing, Retail, E-commerce, Automotive Technology: Blockchain, IoT, AI, Automation Mode: Air, Road, Rail, Sea |
| Companies Covered | Borusan Logistics, Ekol Logistics, BARSAN Global Logistics, DHL, DFDS, Netlog Logistics, MARS Logistics, CMA CGM, Arkas Holding, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turkey Freight and Logistics Market Evolving Landscape
Digital freight matching platforms are compressing spot-market transaction cycles, while automation investments concentrate at container terminals where labor costs and vessel size escalation intersect.
Telematics-enabled fleet management is bifurcating the road haulage sector. Large operators deploy real-time fuel optimization and predictive maintenance across captive tractor fleets. Smaller owner-drivers lack capital for retrofitting, widening the efficiency gap on Istanbul-Izmir and Adana-Mersin corridors. This technology is bifurcating service tiers, with integrated telematics becoming a bidding prerequisite for automotive and pharmaceutical contracts.
The Turkish Standards Institution's emissions certification mandates for commercial vehicles are accelerating Euro 6 engine replacements. Fleet operators face compressed compliance timelines as older trucks face exclusion from municipal low-emission zones in Istanbul and Ankara. Heavy-duty segments serving construction materials and bulk agriculture are most affected, with many deferring purchases until secondhand Euro 6 supply expands.
Shippers are unbundling long-term forwarding contracts in favor of modular service procurement. Automotive manufacturers now separately tender port handling, customs brokerage, and final-mile delivery rather than awarding integrated contracts. This pattern is most visible among German and Korean OEMs operating from Gebze-Tuzla industrial clusters, where competitive bidding for each leg has compressed forwarder margins by forcing asset specialization.
Turkey Freight and Logistics Market Segmentation
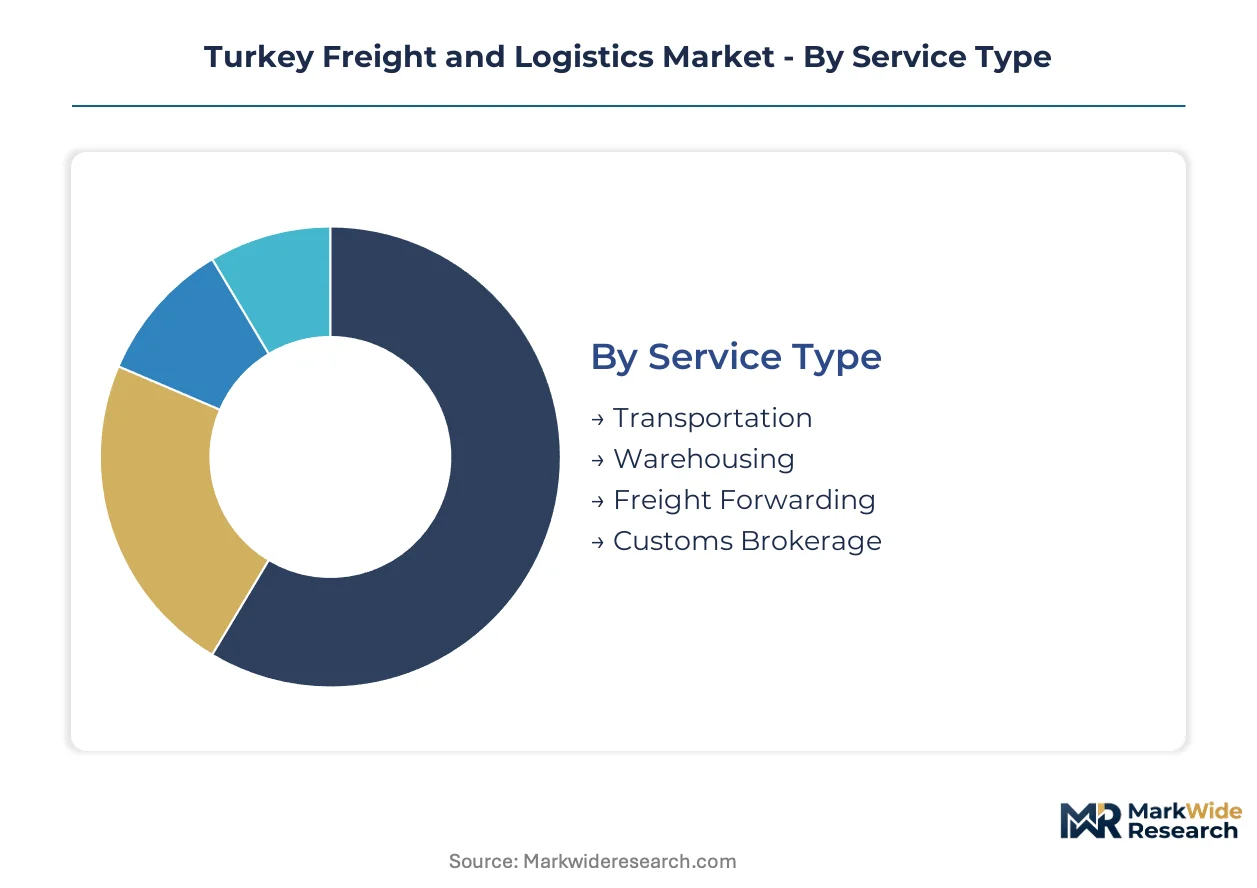
Segmentation reveals how margin pools concentrate across service layers and technology tiers in Turkey's logistics infrastructure. Distinct operational models govern each slice, from asset-heavy rail yards to software-driven customs platforms.
Service Type:
Margin density clusters around control points in the cargo journey rather than pure movement economics.
- Transportation:Road haulage dominates tonnage flows on the Edirne-Silopi corridor and Istanbul-Ankara axis. Diesel price volatility erodes fleet operator margins, accelerating interest in rail intermodal alternatives along the Middle Corridor.
- Warehousing:Cold-chain and e-commerce fulfillment facilities command premium rents in Gebze-Tuzla and near Mersin port. Inventory positioning closer to Istanbul, Izmir, and Ankara population centers drives speculative development.
- Freight Forwarding:Customs brokerage and documentation services generate fee income with limited asset exposure. Forwarders unbundle from integrated contracts as automotive OEMs separately tender each logistics leg.
- Customs Brokerage:Digital single-window mandates from the Customs Administration compress processing times. Blockchain-IoT convergence at Kapikule and Ipsala border crossings creates differentiation for tech-enabled brokers.
The dominant share belongs to Transportation, while Warehousing is closing the gap fastest.
End User:
Customer procurement patterns split between long-term contracted volumes and spot-market flexibility.
- Manufacturing:Textile exporters in Gaziantep and Sanliurfa lack integrated logistics parks, forcing reliance on fragmented trucking networks. Bonded warehousing demand concentrates near southeast Anatolia production zones.
- Retail:Big-box distributors maintain regional distribution centers serving Anatolian store networks. Inventory turns accelerate as consumer delivery windows tighten.
- E-commerce:Last-mile depot expansion across Anatolia pulls inventory closer to population centers. Same-day delivery expectations in Istanbul reshape fulfillment network topology.
- Automotive:German and Korean OEMs operating from Gebze-Tuzla clusters demand just-in-time sequencing with flatbed and containerized services. Battery component imports through Mersin require hazmat infrastructure that terminals have not deployed.
Automotive anchors contracted revenue stability, though e-commerce is expanding most quickly.
Technology:
Adoption curves diverge sharply between large integrators and mid-tier operators lacking capital for retrofit.
- Blockchain:Immutable documentation streams preempt disputes at Georgian and Azerbaijani transit points. Customs Administration digitization mandates accelerate single-window adoption.
- IoT:Real-time container tracking combines with fleet telematics to compress dwell times. Large operators deploy predictive maintenance across captive tractor fleets while owner-drivers lag.
- AI:Demand forecasting remains nascent outside the largest integrators. Route optimization algorithms penetrate slowly due to fragmented warehouse management systems.
- Automation:Terminal automation investments concentrate at Mersin and Izmir where labor costs and vessel size escalation intersect. Mid-tier 3PLs operate disconnected inventory platforms blocking end-to-end visibility.
IoT holds the installed base lead, while Blockchain is gaining share fastest.
Mode:
Modal economics shift as EU Carbon Border Adjustment Mechanism documentation requirements favor rail.
- Air:Express cargo and high-value electronics move through Istanbul's cargo terminals. Limited domestic feeder networks constrain hinterland reach.
- Road:Aging driver pools on the Edirne-Silopi axis serving Iraqi and Iranian markets face replacement shortfalls. Euro 6 engine mandates from the Turkish Standards Institution accelerate fleet renewal.
- Rail:State railway scheduling protocols misalign with private operator container release windows, forcing buffer stock accumulation. Middle Corridor transit time compression threatens Turkish operators who fail to reposition warehousing assets.
- Sea:Mersin port gateway handles bulk agriculture and construction materials alongside container flows. Privatization frameworks attract terminal automation investments accelerating vessel turnaround.
Road retains volume dominance, yet Rail shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Logistics infrastructure clusters around three distinct geographies that channel east-west trade corridors. Each sub-region commands different modal advantages and regulatory frameworks that reshape freight economics across Anatolia.
Marmara Region
Istanbul's Gebze-Tuzla industrial belt generates dense container flows through Mersin port gateway. The Ministry of Transport and Infrastructure's port privatization frameworks accelerate terminal automation investments. E-commerce fulfillment depots multiply across the metropolitan periphery as same-day delivery expectations tighten inventory positioning.
Central Anatolia
Ankara-Sivas rail axis anchors Middle Corridor transit corridors linking China-Europe flows. State railway scheduling protocols misalign with private operator container release windows, forcing costly buffer stock accumulation. The Turkish Standards Institution enforces vehicle emissions protocols that filter fleet renewal decisions for road haulage alternatives.
Aegean Region
Izmir port privatization attracts terminal automation investments competing with Mersin for Mediterranean container traffic. The Customs Administration's single-window platform faces interoperability failures with Greek border systems at Ipsala. Textile exporters in surrounding provinces lack integrated logistics parks, fragmenting trucking networks.
Southeast Anatolia
Gaziantep and Sanliurfa manufacturing zones drive bonded warehousing demand for textile exports. The Edirne-Silopi transit axis serving Iraqi and Iranian markets suffers acute driver shortage concentration. The Ministry of Transport and Infrastructure's Middle Corridor investments have not yet extended specialized hazmat infrastructure for battery component flows.
Black Sea Region
Samsun and Trabzon ports handle bulk agriculture and construction materials with limited container terminal depth. Euro 6 engine mandates from the Turkish Standards Institution accelerate fleet renewal for heavy-duty segments serving regional construction materials demand. Rail intermodal alternatives remain underdeveloped compared to southern corridors.
Turkey Freight and Logistics Market Competitive Landscape
Concentration sits with diversified logistics holding groups that combine captive rail assets, port terminals, and road fleets. The vendor base spans three tiers: integrated multimodal operators controlling corridor infrastructure, specialized automotive and cold-chain forwarders, and digital freight platforms compressing spot-market cycles. Strategic moves center on warehousing asset repositioning along the Ankara-Sivas-Kars axis and blockchain-IoT customs convergence at border crossings.
Among Turkey-based integrated operators, Borusan Logistics, Ekol Logistics, and BARSAN Global Logistics exemplify distinct archetypes. Borusan occupies a position anchored to captive rail and port assets that control east-west cargo corridors. Ekol sits within the cross-border dominance tier through integrated European-Turkish road network coverage. BARSAN represents specialized automotive logistics, anchoring just-in-time supply chains with flatbed and containerized service configurations. These three structures illustrate how asset control, geographic coverage, and vertical specialization segment competitive positioning.
| Leading Market Players |
|---|
| Borusan Logistics |
| Ekol Logistics |
| BARSAN Global Logistics |
| DHL |
| DFDS |
| Netlog Logistics |
| MARS Logistics |
| CMA CGM |
| Arkas Holding |
| Others |
Value Network & Pricing Analysis
Turkish Standards Institution Euro 6 emissions certification gates fleet operator market access while simultaneously stratifying contract rates across certified and non-certified carrier tiers. This dual-gate mechanism compresses margins for non-compliant hauliers on Istanbul-Ankara corridors while granting pricing premiums to operators who completed early engine renewal cycles.
Pricing Analysis
EU Carbon Border Adjustment Mechanism documentation requirements dictate the pricing tier structure across Turkish freight forwarding contracts. Three-tier pricing separates premium green-certified logistics providers from standard compliance-tier operators and economy-grade conventional hauliers. Price differentiation rests on emissions certification level and modal choice, with rail-intermodal contracts commanding premiums over pure road haulage. Cost compression in economy-tier road segments is intensifying because diesel price volatility absorbs directly into operator margins. Automotive OEMs operating from Gebze-Tuzla clusters exhibit least price sensitivity, while textile exporters in Gaziantep demonstrate highest sensitivity due to fragmented trucking alternatives.
Supply Chain Analysis
Automotive manufacturers favor just-in-time sequencing with minimal buffer inventory, while bulk agriculture and construction materials operators maintain strategic stockpiles near Mersin port to hedge vessel scheduling uncertainty. Geographic supply concentration for commercial vehicle fleets draws from Germany, Italy, and domestic Turkish assembly plants. Diesel fuel, tires, and telematics hardware constitute critical input dependencies. Single-source vulnerability runs through European engine component suppliers for Euro 6 retrofit kits. Distribution runs through captive rail yards controlled by integrated logistics holding groups and independent owner-driver networks serving last-mile corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Turkey's freight and logistics sector presents a defensive-moat structure anchored in regulatory entrenchment. The Turkish Standards Institution's emissions mandates and Customs Administration digitization protocols create switching costs that protect incumbent positions against unqualified challengers.
For Market Incumbents: Shield corridor control by accelerating warehousing asset repositioning along the Ankara-Sivas-Kars rail axis before Middle Corridor transit time compression redirects east-west flows toward competing Black Sea routes. Deepen backward integration into captive port terminal operations at Mersin to capture automation-driven vessel turnaround premiums. Counter the threat from digital freight matching platforms by embedding blockchain-IoT customs convergence into service contracts. For New Entrants and Emerging Players: Anchor in Southeast Anatolia's bonded warehousing white space, where Gaziantep and Sanliurfa textile exporters lack integrated logistics parks and depend on fragmented trucking networks. Target cold-chain depot expansion across Anatolian population centers as e-commerce fulfillment density pulls inventory closer to Izmir and Ankara consumer markets. Pursue a go-to-market angle centered on hazmat infrastructure for battery component flows that existing Mersin terminals have not deployed. For Investors and Strategic Acquirers: EU Carbon Border Adjustment Mechanism alignment deadlines reshape the acquisition landscape toward certified green logistics providers with modal shift capabilities. Long-term viability across the analysis window favors operators controlling captive rail assets and automated port terminals. Acquisition target archetype: mid-tier 3PLs with disconnected warehouse management systems that strategic buyers can integrate for end-to-end visibility. Signal to monitor: Customs Administration single-window interoperability fixes at Kapikule and Ipsala border crossings.| Strategic Initiative | Industry Significance |
|---|---|
| Warehousing Asset Repositioning | Ankara-Sivas-Kars axis capture secures Middle Corridor east-west cargo flows against Black Sea route competition. |
| Terminal Automation Investment | Mersin and Izmir privatization frameworks attract concession bids accelerating vessel turnaround metrics. |
| Blockchain-IoT Customs Convergence | Real-time container tracking at Georgian and Azerbaijani transit points preempts documentation disputes. |
| Hazmat Infrastructure Deployment | Battery component handling capabilities at Mersin unlock automotive EV supply chain reconfiguration contracts. |
| Telematics Fleet Integration | Predictive maintenance across captive tractor fleets satisfies automotive and pharmaceutical contract bidding prerequisites. |
Research Methodology
A standing panel of fleet operations directors, customs brokerage managers, port terminal executives, and e-commerce fulfillment planners provided ongoing calibration across the research cycle. Primary interviews with these stakeholders combined with secondary validation against Turkish Customs Administration trade statistics, Ministry of Transport and Infrastructure corridor investment disclosures, Turkish Standards Institution certification registries, and EU Carbon Border Adjustment Mechanism implementation guidance. Bottom-up service-type segmentation triangulated against top-down macroeconomic freight volume indicators.
Consistency checks validated volume and value outputs against external benchmarks including state railway cargo tonnage reports, container terminal throughput disclosures, and cross-border trucking permit issuance data. The analytical framework modeled service type, end user vertical, technology adoption tier, and modal choice across the projection horizon. CAGRs derived from segment-level growth drivers rather than aggregate extrapolation. Industry-specific forecast inputs included Middle Corridor transit time compression schedules and Euro 6 fleet renewal compliance curves.
Decision-makers should treat outputs as directional under assumptions of continued Customs Administration digitization momentum and sustained EU Carbon Border Adjustment Mechanism implementation; material deviation would warrant model refresh. Specific risk factors include diesel price volatility spikes, driver shortage acceleration on the Edirne-Silopi axis, and single-window platform interoperability failures extending dwell times. Revision becomes warranted when rail-yard synchronization protocols materially misalign with private operator container release windows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Mexico Logistics Market
Logistics and Shipping
Vietnam Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Spain 3PL Market
Logistics and Shipping
Saudi Arabia Integrated Cold Chain Logistics Market
Logistics and Shipping
Mexico 3PL Market
Logistics and Shipping
Shipping Container Market
Logistics and Shipping
Internet of Things (IoT) in Logistics Market
Logistics and Shipping
Shipping Supplies Market
Logistics and Shipping
United States Chartered Air Freight Transport Market
Logistics and Shipping
Central and Eastern Europe Freight and Logistics Market
Logistics and Shipping
GCC Air Freight Transport Market
Logistics and Shipping
Asia-Pacific Container Drayage Market
Logistics and Shipping
Qatar Freight and Logistics Market
Logistics and Shipping
North America Freight Forwarding Market
Logistics and Shipping
India Freight and Logistics Market
Logistics and Shipping
Bangladesh Contract Logistics Market