
 Armenia Freight and Logistics Market | 2026-2036
Armenia Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Armenia Freight and Logistics Market Outlook
Multi-source freight procurement is rebalancing Armenia's logistics landscape as shippers diversify beyond traditional Black Sea routes. DHL Group leverages its regional hub architecture to anchor pharmaceutical and electronics flows through Tbilisi corridors. Hellmann Worldwide Logistics competes on temperature-controlled capacity for Armenian agricultural exports. Unitrans Ltd. specializes in heavy-haul project cargo serving mining and energy infrastructure clients.
Armenia freight and logistics encompasses the planning, execution, and control of goods movement across road, rail, air, and multimodal corridors, typically involving cargo consolidation, customs documentation, and last-mile distribution within a landlocked operational environment. The primary purpose centers on overcoming geographic isolation by connecting Armenian producers to Black Sea ports, Iranian rail terminals, and European trade lanes. Transportation services dominate current revenue flows, particularly road freight along the North-South highway corridor, while warehousing gains structural importance as e-commerce fulfillment demands cold storage and bonded facilities near Zvartnots International Airport. Customs brokerage retains margin concentration due to complex transit documentation requirements across multiple jurisdictions.
The State Revenue Committee of Armenia enforces customs modernization protocols that mandate electronic declaration systems, directly shaping broker productivity benchmarks and technology procurement cycles. The country's national standards body aligns vehicle weight regulations with EAEU technical regulations, influencing fleet replacement timelines for domestic carriers. Stakeholders must monitor Iran-Armenia rail interoperability investments and their capacity to redirect Caspian-originated cargo away from congested Georgian transit corridors.
Market Dynamics
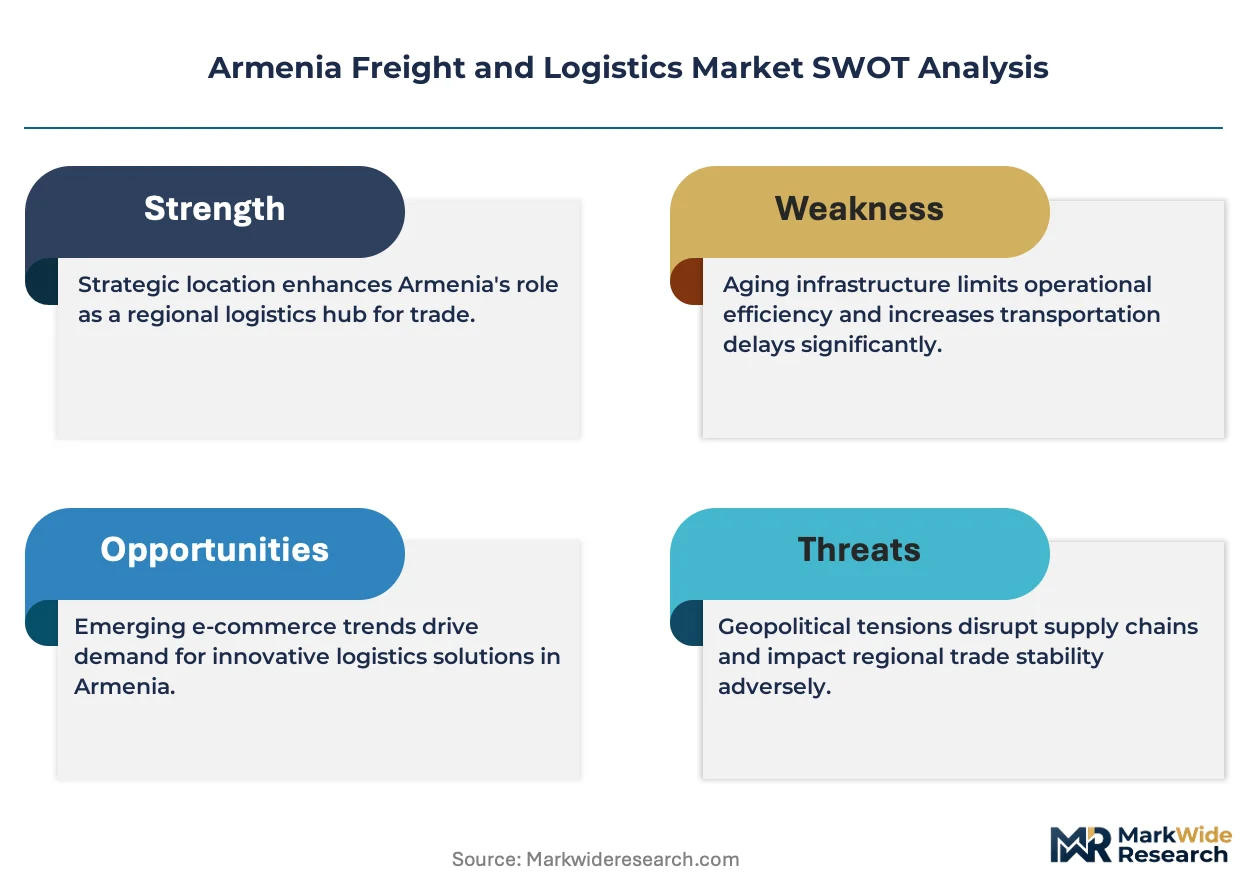
Armenia's landlocked geography forces freight operators to optimize multimodal handoffs across competing transit corridors, with the State Revenue Committee's customs modernization program now mandating electronic declarations that compress clearance timelines at the Iranian and Georgian borders.
Growth Catalysts
- Meghri Free Economic Zone:Armenian manufacturers of machinery and processed food are expanding outsourced logistics partnerships as trade integration with Iran deepens through this southern corridor facility.
- EAEU Technical Regulations:Alignment of vehicle weight standards with Eurasian Economic Union protocols is accelerating fleet replacement cycles among domestic road carriers serving cross-border routes.
- E-commerce Fulfillment:Demand for cold storage and bonded warehousing near Zvartnots International Airport is pulling investment into temperature-controlled infrastructure clusters along Yerevan's industrial corridor.
Market Restraints
- Georgian Transit Bottlenecks:Concentration of Black Sea-bound cargo through Poti and Batumi ports creates vulnerability to seasonal congestion and infrastructure capacity constraints.
- Fuel Cost Volatility:Diesel price fluctuations directly compress margins for road-dominant operators along the North-South highway corridor where rail alternatives remain underdeveloped.
- Complex Transit Documentation:Multi-jurisdictional customs brokerage requirements across Armenia, Georgia, and Iran sustain elevated compliance costs and extend shipment planning cycles.
Strategic Opportunities
- Iran-Armenia Rail Interoperability:Planned gauge standardization investments could redirect Caspian-originated project cargo away from congested Georgian corridors toward southern rail terminals.
- Pharmaceutical Cold Chain:Temperature-controlled capacity expansion presents white space for operators serving regional pharmaceutical distribution networks requiring GDP-compliant handling.
- Digital Freight Platforms:Real-time cargo matching and dynamic pricing tools remain underpenetrated among small and mid-sized Armenian trucking fleets operating fragmented spot markets.
Industry Challenges
- Customs Broker Talent Scarcity:Specialized expertise in EAEU, Iranian, and Georgian transit documentation remains concentrated among aging practitioner cohorts with limited training pipeline replenishment.
- Warehouse Automation Capex:E-commerce fulfillment demands for automated sortation and inventory management systems require capital outlays that strain family-owned logistics operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Armenia Freight and Logistics Market |
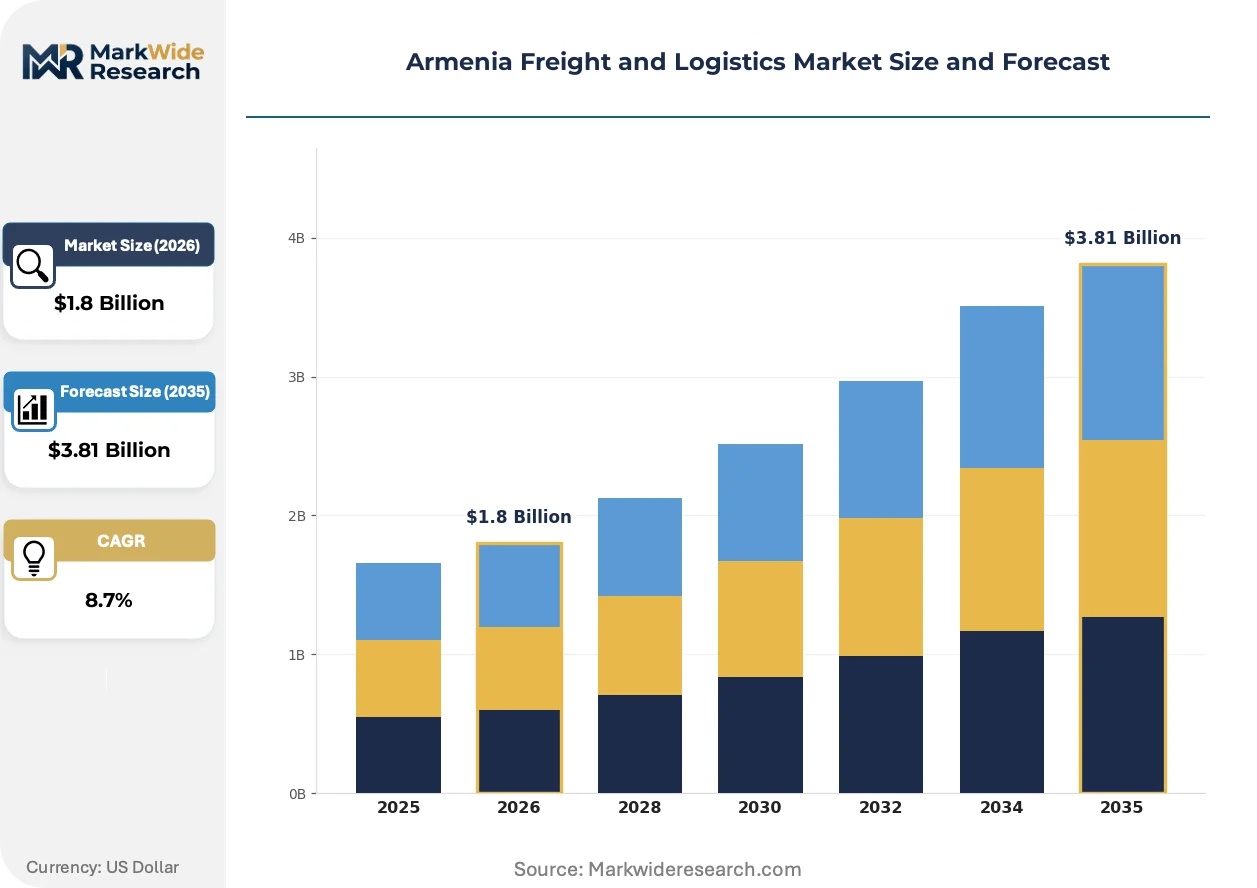
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Customs Brokerage, Freight Forwarding End User: Manufacturers, Retailers, E-commerce, Importers Technology: Automation, Tracking Systems, IoT Solutions, ERP Solutions Delivery Mode: Road, Rail, Air, Sea |
| Companies Covered | Unitrans Ltd., The MSC Group, DHL Group, PRIME LOGISTIC SERVICES LLC, NT Logistics, Hellmann Worldwide Logistics, Mira Trans LLC, Spinnaker Logistics, CEVA Logistics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Armenia Freight and Logistics Market Strategic Shifts
Digital infrastructure investments are compressing transaction friction across Armenia's logistics value chain, with technology adoption patterns diverging sharply between multinational operators and domestic carriers.
Blockchain-enabled cargo documentation is decentralizing trust architectures across multimodal shipments. Armenian customs brokers and freight forwarders serving pharmaceutical and electronics flows are piloting distributed ledger systems for immutable transit records. This technology is decentralizing document verification away from centralized customs authorities toward consortia of shippers, carriers, and banks.
The State Revenue Committee's electronic declaration mandate is restructuring broker productivity benchmarks. Operators must now integrate directly with centralized customs platforms, forcing technology procurement cycles and marginalizing paper-dependent competitors. Small and mid-sized freight forwarders in Yerevan's industrial corridor face the steepest adaptation curves as compliance deadlines compress.
Shippers are unbundling transportation from warehousing contracts, preferring modular procurement of specific corridor segments. Armenian agricultural exporters now separately negotiate temperature-controlled trucking to Georgian ports and ocean freight bookings, bypassing traditional freight forwarder bundles. This pattern is most visible among processed food manufacturers seeking direct control over Black Sea transit timing.
Armenia Freight and Logistics Market Segmentation
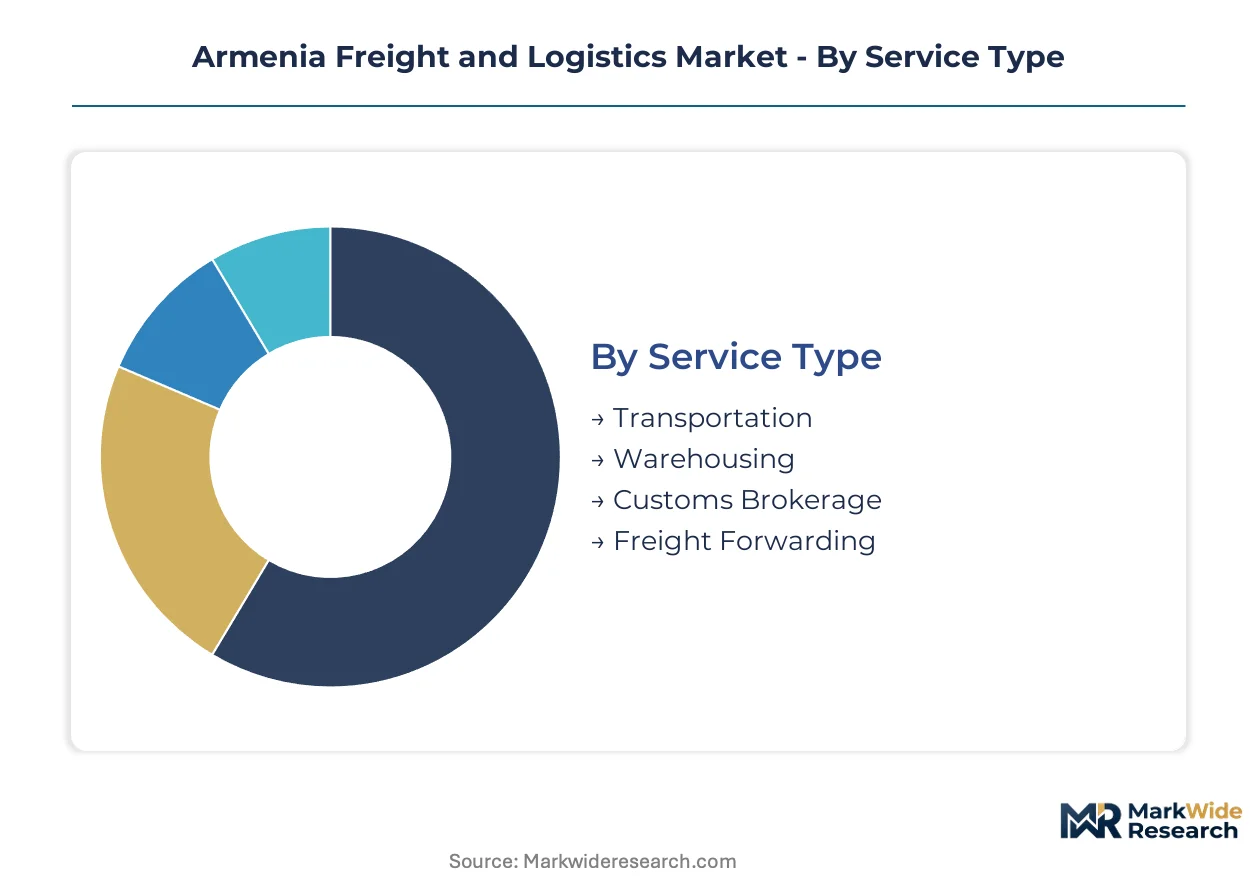
Armenia's landlocked geography forces shippers to optimize across service tiers that balance speed against corridor constraints. Segmentation patterns reveal how pharmaceutical cold chain demands and e-commerce fulfillment pressures are reshaping procurement priorities across Yerevan's industrial corridor.
Service Type:
Shippers select service tiers based on cargo value density and customs complexity rather than pure transport economics.
- Transportation:Road freight along the North-South highway corridor handles machinery and processed food volumes to Georgian Black Sea ports. Diesel cost volatility compresses margins for domestic carriers serving cross-border routes to Poti and Batumi.
- Warehousing:Temperature-controlled facilities near Zvartnots International Airport support pharmaceutical GDP compliance and e-commerce cold storage. Bonded warehouse demand concentrates in Yerevan's industrial corridor serving re-export flows to Iran through the Meghri Free Economic Zone.
- Customs Brokerage:Specialized EAEU transit documentation expertise commands premium pricing. The State Revenue Committee's electronic declaration mandate is marginalizing paper-dependent practitioners.
- Freight Forwarding:Corridor-specific bundling of trucking, documentation, and port coordination. Agricultural exporters increasingly unbundle transportation from warehousing contracts to control Black Sea transit timing directly.
Volume sits with Transportation; growth tilts toward Warehousing.
End User:
Customer procurement sophistication varies sharply across value chain position and export orientation.
- Manufacturers:Machinery and processed food producers dominate outsourced logistics spending. These shippers prioritize corridor reliability over unit cost when serving Iranian rail terminal destinations.
- Retailers:Inventory velocity requirements drive consolidation center investments. Distribution networks concentrate replenishment flows through Yerevan warehousing clusters serving domestic store networks.
- E-commerce:Last-mile density challenges and cold chain SKU expansion are pulling automation capital into fulfillment infrastructure. Customer delivery expectations compress acceptable fulfillment windows.
- Importers:Containerized consumer goods flows through Georgian ports require customs brokerage specialization across multiple jurisdictions. Documentation complexity sustains elevated compliance spending.
Manufacturers anchor current revenue; e-commerce is climbing the fastest.
Technology:
Technology adoption splits between multinational compliance requirements and domestic carrier cost constraints.
- Automation:Automated sortation and inventory management systems address e-commerce throughput pressures. Family-owned operators face capital barriers to warehouse robotics deployment.
- Tracking Systems:Real-time cargo visibility across Georgian and Iranian transit corridors. Pharmaceutical shippers mandate GPS-enabled cold chain monitoring for GDP compliance.
- IoT Solutions:Sensor networks for temperature monitoring and predictive maintenance. Mining and energy infrastructure project cargo uses heavy-haul telemetry for route optimization.
- ERP Solutions:Integration with State Revenue Committee electronic declaration platforms. Customs brokers must modernize legacy systems to meet centralized filing deadlines.
Tracking Systems dominate current penetration; ERP Solutions are gaining share fastest.
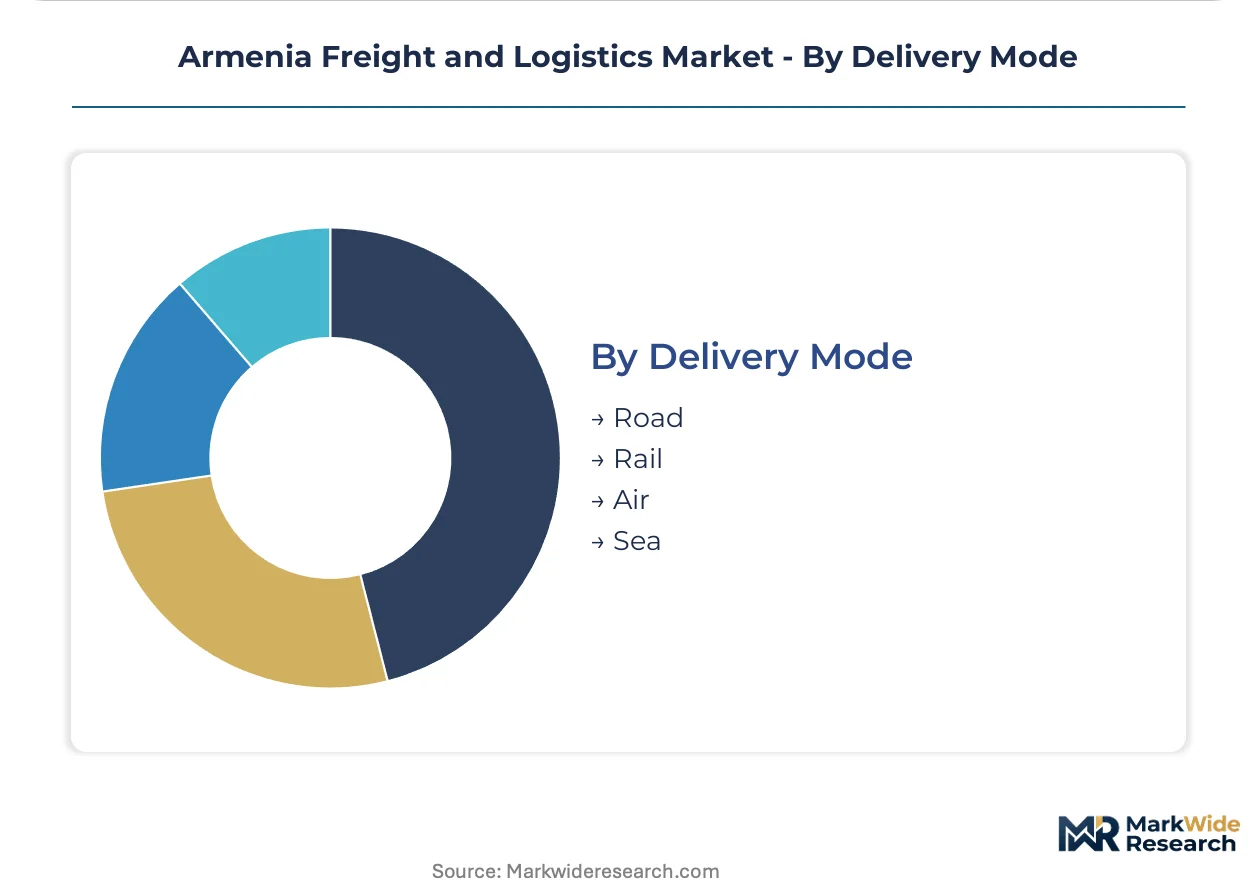
Delivery Mode:
Modal selection reflects permanent geographic constraints and intermittent infrastructure investments.
- Road:Dominant mode for North-South corridor flows to Georgian ports and Iranian border crossings. Fleet replacement cycles accelerate under EAEU vehicle weight standard alignment.
- Rail:Underdeveloped capacity limits current share despite Iran-Armenia gauge standardization plans. Caspian-originated project cargo could redirect from congested Georgian corridors upon interoperability completion.
- Air:Zvartnots International Airport handles high-value pharmaceutical and electronics flows. Temperature-controlled air freight capacity serves regional distribution network requirements.
- Sea:Virtual mode dependent on Georgian port access; no direct maritime infrastructure. Containerized agricultural exports rely on Poti and Batumi transshipment.
Road commands absolute volume; Rail holds the steepest expansion trajectory contingent on southern corridor completion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper concentrate deposits in Armenia's Syunik Province anchor heavy-haul logistics demand through the Meghri corridor. The country's landlocked position forces cargo flows through neighboring transit states with varying customs protocols. Regional logistics patterns concentrate around three dominant corridor configurations serving Black Sea, Iranian, and emerging Caspian routes.
Georgia
Poti and Batumi ports handle containerized Armenian agricultural exports and machinery imports. The Georgian Revenue Service enforces electronic pre-arrival declaration systems that compress border clearance timelines at the Bagratashen-Sadakhlo crossing. Warehousing clusters in Tbilisi's Dighomi district serve as consolidation hubs for Armenian shippers seeking Black Sea connectivity.
Iran
Bandar Abbas port access drives southern corridor investment through the Meghri Free Economic Zone. The Islamic Republic of Iran Customs Administration maintains distinct documentation protocols for transit cargo that sustain specialized broker expertise requirements. Rail terminals in Tabriz and Tehran receive Armenian machinery exports via the Jolfa-Norduz border crossing.
Turkey
Igdir province logistics facilities capture cross-border trade from Armenia's northwestern Shirak region. The Turkish Ministry of Trade enforces Eurasian Economic Union alignment protocols at the Margara-Alican crossing that complicate customs brokerage workflows. Trucking terminals in Kars province serve as alternative routing options during Georgian corridor disruptions.
Russia
North Caucasus rail connections via the Upper Lars crossing handle Armenian mineral exports and energy equipment imports. Russian Federal Customs Service regulations mandate EAEU-compliant documentation that domestic Armenian brokers must maintain. Volgograd logistics parks serve as consolidation points for Armenian cargo entering Russian distribution networks.
Azerbaijan
Caspian Sea port infrastructure at Alat presents potential rail-sea intermodal alternatives to Georgian transit. The State Customs Committee of Azerbaijan maintains separate regulatory frameworks for Armenian-originated cargo that limit current corridor utilization. Baku's Heydar Aliyev International Airport offers air freight capacity for high-value Armenian electronics and pharmaceutical shipments.
Armenia Freight and Logistics Market Competitive Environment
Global majors compete with regional champions across corridor specialization and customs brokerage depth. The Armenian freight market structures around three tiers: multinational integrators with Tbilisi hub architectures, regional specialists with temperature-controlled fleet assets, and domestic operators with heavy-haul project cargo capabilities. Strategic moves concentrate on customs technology integration and southern corridor capacity positioning ahead of Iran-Armenia rail completion.
Within the multinational integrator tier, DHL Group and CEVA Logistics exemplify hub-and-spoke architectures leveraging Georgian corridor connectivity. Hellmann Worldwide Logistics and The MSC Group represent regional specialists with maritime and temperature-controlled competencies. Unitrans Ltd. anchors the domestic heavy-haul segment serving mining infrastructure clients. These three archetypes—integrators, regional specialists, and domestic project operators—occupy distinct competitive positions based on corridor access and asset specialization.
| Leading Market Players |
|---|
| Unitrans Ltd. |
| The MSC Group |
| DHL Group |
| PRIME LOGISTIC SERVICES LLC |
| NT Logistics |
| Hellmann Worldwide Logistics |
| Mira Trans LLC |
| Spinnaker Logistics |
| CEVA Logistics |
| Others |
Value Chain & Pricing Dynamics
EAEU vehicle emissions alignment mandates gate qualified fleet supply and premium-tier pricing access for temperature-controlled and bonded logistics services, compressing margins for non-compliant operators while elevating certified carriers serving pharmaceutical GDP corridors through Zvartnots International Airport.
Pricing Analysis
Warranty and customs-clearance bundling separates full-service freight forwarders from unbundled transportation-only providers, with Armenian agricultural exporters increasingly breaking contracts to control Black Sea transit timing directly. Three-tier pricing structure across premium cold-chain, standard dry-cargo, and economy spot-market levels reflects certification grade and corridor reliability rather than pure distance economics. Price differentiation hinges on EAEU transit documentation expertise and GPS-enabled temperature monitoring compliance. Cost compression in standard road freight is intensifying because diesel volatility and Georgian port congestion squeeze asset utilization rates. Small domestic trucking fleets exhibit highest price sensitivity, while pharmaceutical shippers prioritize GDP-compliant handling over unit cost.
Supply Chain Analysis
Direct-to-manufacturer contracts anchor heavy-haul mining equipment flows through the Meghri corridor, bypassing traditional freight forwarder markups. Supply concentration rests on Georgia for Black Sea port access, Iran for southern rail terminal connectivity, and Russia for EAEU-compliant fleet assets. Raw material dependencies include diesel fuel subject to regional price volatility, refrigerated container equipment leased through Tbilisi hubs, and customs brokerage software integrating with State Revenue Committee platforms. Single-source vulnerability through Poti and Batumi ports creates structural risk during seasonal congestion or geopolitical disruptions. Distribution runs through Yerevan's industrial corridor warehousing clusters serving cross-border consolidation to all three transit corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Armenia's freight and logistics sector sits in a technology-transition phase, with blockchain-enabled cargo documentation and electronic customs declaration mandates displacing paper-dependent brokerage workflows and reshaping competitive viability across operator tiers.
For Market Incumbents: Anchor corridor-specific technology investments in the Georgian and Iranian transit routes to defend against digital-native freight platforms capturing fragmented spot-market volumes. Prioritize backward integration into temperature-controlled warehousing near Zvartnots International Airport to capture pharmaceutical GDP compliance premiums. Accelerate ERP system modernization to meet State Revenue Committee electronic filing deadlines and marginalize paper-dependent competitors. For New Entrants and Emerging Players: Launch via digital freight matching platforms targeting small and mid-sized Armenian trucking fleets operating unconsolidated spot markets between Yerevan and Georgian ports. White-space targets include real-time cargo visibility tools for cross-border pharmaceutical shipments and automated customs documentation services for agricultural exporters unbundling transportation contracts. The most penetrable segment is family-owned operators lacking capital for warehouse automation capex. For Investors and Strategic Acquirers: Iran-Armenia rail interoperability completion is the leading indicator that southern corridor capacity will redirect Caspian-originated project cargo and reshape modal share economics. Long-term viability favors operators with dual-corridor capability across Georgian and Iranian routes rather than single-corridor dependence. Target acquisition archetypes are domestic heavy-haul specialists with mining infrastructure relationships and technology-enabled customs brokers with EAEU certification expertise.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Customs Platform Integration | State Revenue Committee mandates force broker technology procurement cycles and marginalize paper-dependent competitors. |
| Temperature-Controlled Warehouse Expansion | Pharmaceutical GDP compliance requirements pull investment into cold storage clusters near Zvartnots International Airport. |
| Iran-Armenia Rail Interoperability Investment | Gauge standardization projects redirect Caspian project cargo from congested Georgian corridors to southern terminals. |
| Blockchain Cargo Documentation Pilot | Distributed ledger systems decentralize trust architectures for pharmaceutical and electronics transit records. |
| Heavy-Haul Fleet Modernization | EAEU vehicle weight alignment accelerates replacement cycles for domestic carriers serving cross-border mining routes. |
Study Parameters
Document review covered customs modernization protocols from the State Revenue Committee of Armenia, EAEU technical regulation filings, and Iranian rail infrastructure investment disclosures, complemented by interviews with fleet operations managers at domestic road carriers, customs brokerage principals in Yerevan's industrial corridor, pharmaceutical logistics directors managing GDP-compliant cold chains, and procurement leads at machinery exporters utilizing the Meghri Free Economic Zone. Secondary validation drew from trade corridor utilization statistics, port throughput data from Poti and Batumi, and airline cargo manifests from Zvartnots International Airport. Bottom-up carrier capacity assessments and top-down trade flow estimates were triangulated against customs declaration volume trends.
Historical volume trajectories were cross-referenced against panel input from corridor specialists and infrastructure planners to construct analytical frameworks across service type, end user, technology adoption tier, and delivery mode segmentation dimensions. Modeled variables included fleet replacement cycles under EAEU alignment, e-commerce fulfillment infrastructure buildout rates, and rail interoperability completion impacts on modal shift economics. CAGRs were derived from elasticity-adjusted corridor capacity projections and documented trade integration commitments.
Geopolitical corridor disruptions, fuel price volatility spikes, and customs modernization implementation delays are the dominant revision risks that could compress or extend forecast trajectories. Forecasts reflect documented infrastructure investment schedules and regulatory compliance timelines without contingency for accelerated or delayed execution. Periodic stress-testing of base assumptions against actual customs clearance time reductions and rail freight volume shifts is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Nigeria Air Freight Market
Logistics and Shipping
Sea Freight Forwarding Market
Logistics and Shipping
Europe Refrigerated Container Shipping Market
Logistics and Shipping
WAN Connected Returnable Transport Asset Tracking Market
Logistics and Shipping
Spain 3PL Market
Logistics and Shipping
Romania Freight and Logistics Market
Logistics and Shipping
ASEAN Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Logistics Visualization System Market
Logistics and Shipping
Vietnam Logistics Market
Logistics and Shipping
China Cold Chain Logistics Market
Logistics and Shipping
Manufacturing Logistics Market
Logistics and Shipping
Digital Freight Forwarding Market
Logistics and Shipping
Freight Transport Management Market
Logistics and Shipping
Morocco Freight and Logistics Market
Logistics and Shipping
Halal Logistics Market
Logistics and Shipping
Spain Third-Party Logistics (3PL) Market