
 Germany Courier, Express, and Parcel (CEP) Market | 2026-2036
Germany Courier, Express, and Parcel (CEP) Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Courier, Express, and Parcel (CEP) Market Insights
Real-time route optimization and predictive logistics software is fragmenting traditional hub-and-spoke network economics into dynamic, node-flexible architectures. DHL Group leverages its integrated air and ground infrastructure to sustain next-day coverage across all federal states. Hermes Germany competes through dense locker networks and independent courier partnerships that minimize fixed labor costs. Otto Group anchors significant B2C parcel flow through its captive e-commerce platforms, giving it upstream control over dispatch timing and packaging standards.
Germany Courier, Express, and Parcel (CEP) services encompass time-definite transportation of documents and goods weighing from envelope-scale to palletized freight, utilizing multimodal networks with tracking granularity at the individual package level. Same-day delivery and next-day delivery segments lead revenue contribution as consumer tolerance for transit time compresses, while locker systems and pick-up points represent the fastest-growing delivery mode as recipients seek flexible receipt options outside residential hours. B2C and e-commerce customer types now drive the majority of volume growth, though B2B non-document pallet shipping retains superior margin density due to contract stability and lower per-unit handling overhead.
The Kraftfahrt-Bundesamt (KBA) enforces commercial vehicle emissions standards that directly shape fleet procurement decisions, while the EU Green Deal's transport decarbonization targets pressure operators to phase diesel delivery vans. Germany's Packaging Act, administered by the Central Agency Packaging Register, mandates minimum recycled content thresholds that increase operational material costs. Stakeholders must monitor whether battery-electric van range constraints in rural postal codes will sustain hybrid fleet configurations or force network redesigns with intermediate micro-depots.
Market Dynamics
Fleet electrification mandates under the EU Green Deal and Germany's national emissions trading system are forcing capital reallocation toward battery-electric vans and charging infrastructure, compressing operating margins while reshaping depot location strategy around grid capacity.
Growth Catalysts
- E-commerce fulfillment density:Fashion and electronics retailers are pulling volume through automated sortation hubs in the Rhine-Ruhr corridor, creating network effects that reduce per-unit handling costs.
- EU Green Deal transport decarbonization targets:Regulatory pressure is accelerating fleet replacement cycles and opening public funding pools for charging infrastructure deployment.
- Micro-fulfillment center deployment:Last-mile density in metropolitan zones enables sub-30-minute delivery windows that capture premium pricing from time-sensitive consumers.
Market Restraints
- Battery-electric range constraints:Rural postal codes in Mecklenburg-Vorpommern and Saxony-Anhalt exceed single-charge operating radii, forcing hybrid fleet retention or depot network fragmentation.
- Recycled content mandates:Germany's Packaging Act administered by the Central Agency Packaging Register imposes minimum thresholds that raise material costs above Eastern European competitor benchmarks.
- Labor cost rigidity:Collective bargaining agreements with Ver.di limit flexible staffing models during peak season surges, constraining volume elasticity.
Strategic Opportunities
- Parcel locker network expansion:Dense locker installations in Bavaria and Baden-Württemberg reduce failed delivery rates and enable 24/7 recipient access outside residential hours.
- Predictive logistics software convergence:Integration of real-time traffic data with warehouse management systems is digitizing traditional hub-and-spoke network economics into dynamic node-flexible architectures.
- Same-day delivery white space:Grocery and pharmaceutical verticals remain underpenetrated relative to fashion, offering first-mover advantage in temperature-controlled rapid fulfillment.
Industry Challenges
- Grid infrastructure synchronization:Depot electrification timelines depend on municipal utility expansion schedules that lag fleet procurement cycles by 18-36 months.
- Legacy system integration:Predictive routing algorithms require data architecture overhauls that conflict with decades-old parcel tracking databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Courier, Express, and Parcel (CEP) Market |
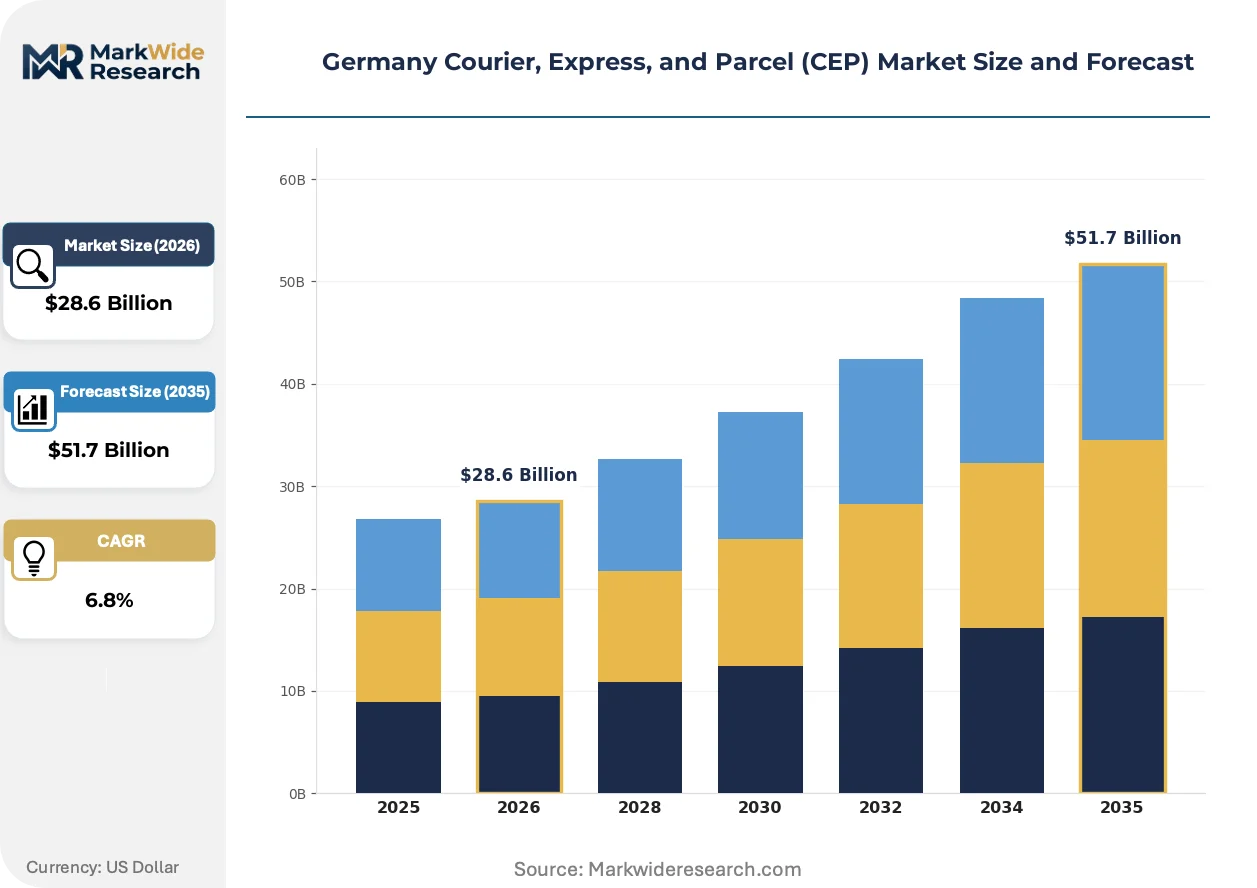
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Standard Delivery, Same-Day Delivery, Next-Day Delivery, International Shipping Delivery Mode: Door-to-Door, Drop Shipping, Pick-Up Points, Locker Systems Customer Type: B2B, B2C, E-Commerce, Retail Package Type: Document, Non-Document, Pallet, Oversized Items |
| Companies Covered | DHL Group, Otto Group, International Distributions Services, United Parcel Service, FedEx, DPD, GLS, DSV, Hermes Germany, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Courier, Express, and Parcel (CEP) Market Trends and Innovations
Operational technology stacks are converging around real-time visibility and autonomous decision-making, compressing the gap between demand signal and fulfillment execution while raising the capital threshold for competitive participation.
Autonomous mobile robots in sortation hubs are digitizing parcel handling workflows through machine-vision-guided picking and dynamic slotting algorithms. Mid-sized operators in North Rhine-Westphalia are piloting these systems to offset wage pressure during peak volumes. The technology is digitizing labor allocation models that previously relied on seasonal hiring surges.
The EU Green Deal's transport decarbonization targets are mandating progressive diesel van phase-outs through 2035, with intermediate benchmarks tightening each compliance period. Fleet operators must now coordinate vehicle procurement with charging infrastructure deployment across federal states. Heavy-goods segments face the steepest cost curves due to battery weight penalties on payload capacity.
Recipient preference is shifting toward flexible receipt options that bypass residential presence requirements, with locker systems and retail pick-up points displacing home delivery as the default expectation. Urban consumers in Berlin and Hamburg now select alternative delivery locations for over half of e-commerce orders. This behavioral pivot is forcing retailers to cede last-mile control to CEP operators with established locker density.
Germany Courier, Express, and Parcel (CEP) Market Segmentation
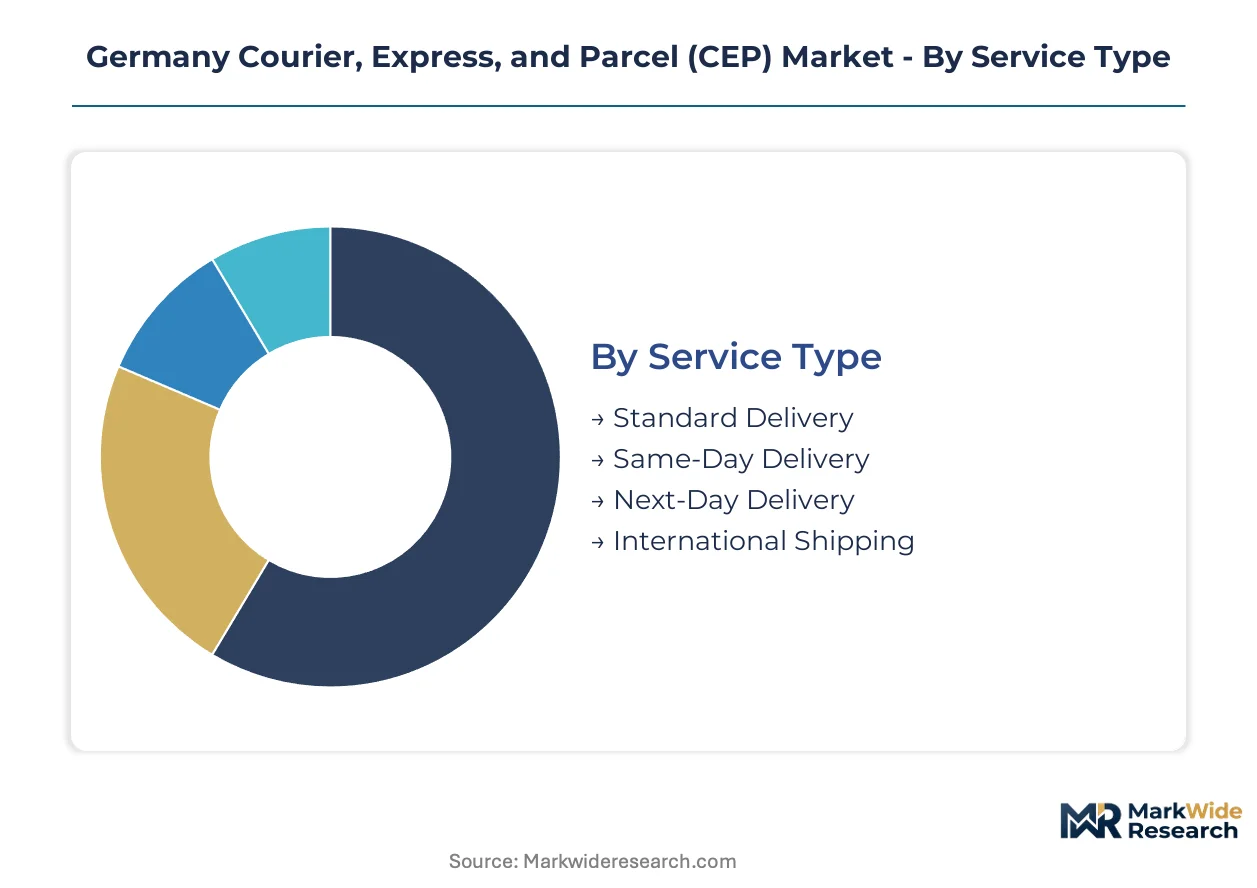
Segmentation in the Germany CEP market reveals how service velocity, delivery infrastructure, and customer economics interact. Understanding these dimensions exposes where capital deploys most efficiently and where regulatory pressure reshapes competitive boundaries.
Service Type:
Cycle times compress from five-day international transit to sub-two-hour same-day fulfillment, creating distinct capital intensity and margin profiles across the service spectrum.
- Same-Day Delivery:Ultra-rapid fulfillment requiring urban micro-depots and dynamic courier pooling. Berlin and Munich density supports 90-minute windows for pharmaceuticals and groceries, though battery-electric range constraints limit rural penetration.
- Next-Day Delivery:Premium time-definite service leveraging automated sortation hubs in the Rhine-Ruhr corridor. Fashion and electronics retailers anchor volume, with DHL Group's integrated air-ground network sustaining federal-state coverage.
- Standard Delivery:Cost-optimized ground transport with 2-3 day transit windows. E-commerce platforms absorb volume during promotional surges, though Ver.di collective agreements constrain peak-season staffing elasticity.
- International Shipping:Cross-border parcel and document flows governed by EU customs protocols and the EU Green Deal's aviation emission benchmarks. Heavy-goods segments face payload penalties from battery weight in electric freighter transitions.
Next-day delivery dominates installed base. Same-day delivery is where expansion concentrates.
Delivery Mode:
Recipient control over receipt timing varies from passive home delivery to active self-service retrieval, shifting last-mile cost structures and failed-delivery rates.
- Locker Systems:Automated parcel terminals enabling 24/7 retrieval without residential presence. Hermes Germany deploys dense networks in Bavaria and Baden-Württemberg to minimize redelivery costs and driver dwell time.
- Pick-Up Points:Retail-integrated collection locations including petrol stations and convenience stores. Urban consumers in Hamburg now select alternative delivery locations for over half of e-commerce orders.
- Door-to-Door:Traditional residential delivery requiring recipient presence. Labor cost rigidity under collective bargaining agreements pressures operators to shift volume toward lower-touch modes.
- Drop Shipping:Direct-to-consumer fulfillment bypassing retailer inventory holding. Otto Group's captive e-commerce platforms leverage upstream dispatch timing control to compress delivery windows.
Door-to-door retains volume leadership. Locker systems are climbing the fastest.
Customer Type:
Contract stability and per-unit handling economics diverge sharply between enterprise procurement and fragmented consumer demand.
- B2B:Non-document pallet shipping with long-term contracts and superior margin density. Manufacturing supply chains in Baden-Württemberg generate predictable freight flows with lower per-unit handling overhead.
- E-Commerce:Platform-aggregated consumer demand driving majority volume growth. Fashion and electronics verticals pull parcels through automated hubs, though peak-season surges strain fixed-cost infrastructure.
- B2C:Direct consumer shipments outside platform intermediation. Smaller parcel sizes and residential delivery requirements elevate last-mile cost per unit relative to commercial destinations.
- Retail:Store-based distribution and click-and-collect fulfillment. Brick-and-mortar networks in North Rhine-Westphalia convert foot traffic into parcel pick-up density.
B2B anchors margin stability. E-commerce is gaining share fastest.
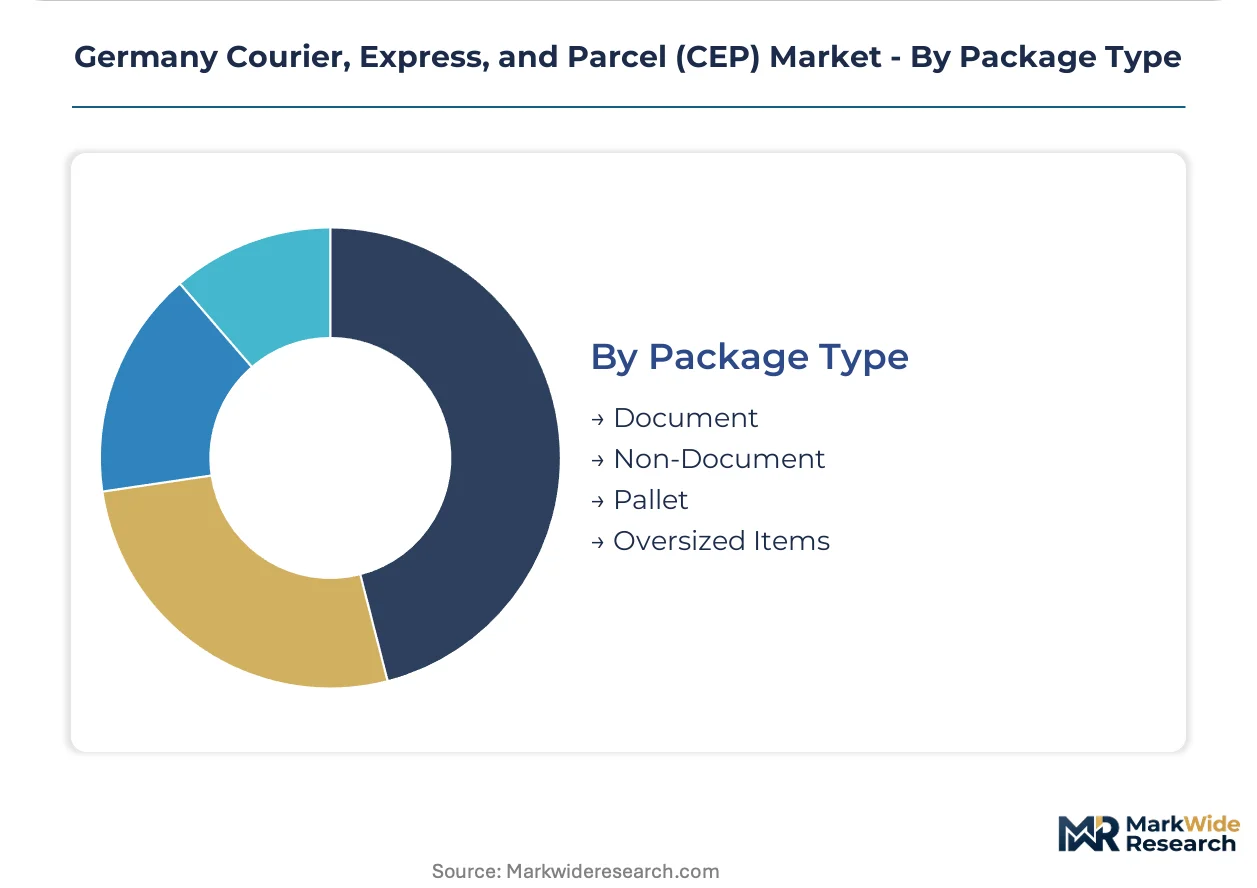
Package Type:
Physical characteristics determine sortation automation compatibility, vehicle payload optimization, and regulatory compliance scope.
- Non-Document:Parcel-scale goods requiring dimensional weight pricing and automated handling. Central Agency Packaging Register mandates on recycled content thresholds elevate material costs above Eastern European competitor benchmarks.
- Pallet:Unitized freight moving through hub-and-spoke networks with forklift-based transfer. B2B contract stability sustains superior margin density despite lower velocity.
- Document:Envelope-scale items with declining volume as digitization displaces paper workflows. Remaining demand concentrates in legal and financial services requiring original signatures.
- Oversized Items:Furniture and appliance freight requiring specialized handling equipment and two-person delivery crews. Limited automation compatibility preserves labor intensity.
Non-document parcels dominate throughput. Pallet shipping anchors contract value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's export-import intensity generates substantial cross-border parcel flows, with industrial clusters in the south and west driving B2B freight demand while e-commerce platforms concentrate fulfillment capacity around urban consumption centers.
North Rhine-Westphalia
The Rhine-Ruhr metropolitan corridor anchors automated sortation hub deployment, with fashion and electronics retailers pulling volume through dense logistics infrastructure. KBA commercial vehicle emissions standards shape fleet procurement timelines for operators serving the region. Cologne and Düsseldorf host micro-fulfillment centers targeting sub-30-minute delivery windows in high-density zones.
Bavaria
Munich's affluence supports premium same-day delivery penetration in pharmaceuticals and groceries, though battery-electric range constraints limit rural coverage in Alpine foothills. The EU Green Deal's transport decarbonization targets accelerate depot electrification schedules. Nuremberg functions as a distribution node for northern Bavaria's manufacturing supply chains.
Baden-Württemberg
Automotive and machinery exporters generate stable B2B pallet shipping demand with superior margin density. Germany's Packaging Act administered by the Central Agency Packaging Register elevates material costs for parcel operations. Stuttgart and Mannheim concentrate locker network installations to reduce failed delivery rates.
Berlin-Brandenburg
Urban consumer density enables dynamic courier pooling for rapid fulfillment, with over half of e-commerce orders now directed to alternative delivery locations. Ver.di collective bargaining agreements constrain flexible staffing during peak surges. Berlin's startup ecosystem pilots predictive logistics software integration.
Hamburg
The port city's container throughput feeds international shipping segments governed by EU customs protocols and aviation emission benchmarks. Grid infrastructure synchronization challenges delay depot electrification timelines. Urban consumers in Hamburg metro select pick-up points for the majority of online purchases.
Germany Courier, Express, and Parcel (CEP) Market Competitive Landscape
On the supply side, the industry is consolidating around integrated operators with captive air-ground networks and independent parcel specialists with asset-light locker strategies. Three archetypes dominate: postal incumbents with universal service obligations, e-commerce-platform-affiliated carriers with upstream dispatch control, and independent couriers leveraging gig-economy labor pools. Capacity expansion in automated sortation and strategic partnerships for last-mile density represent the primary competitive vectors.
Within the integrated infrastructure tier, DHL Group and Otto Group occupy positions that exemplify divergent strategic approaches—DHL Group through federal-state coverage density and Otto Group through captive e-commerce platform control over dispatch timing. Hermes Germany sits within the independent specialist archetype, deploying dense locker networks to minimize fixed labor exposure. These three entities collectively represent the competitive spectrum from universal service obligation to platform-captive fulfillment to asset-light last-mile specialization.
| Leading Market Players |
|---|
| DHL Group |
| Otto Group |
| International Distributions Services |
| United Parcel Service |
| FedEx |
| DPD |
| GLS |
| DSV |
| Hermes Germany |
| Others |
Pricing and Supply Chain Analysis
The Rhine-Ruhr metropolitan corridor's automated sortation hub concentration concentrates network-scale efficiencies that downstream operators convert into pricing leverage across same-day and next-day delivery tiers. DHL Group's integrated air-ground infrastructure and Hermes Germany's locker density create divergent cost-to-serve profiles that stratify competitive pricing floors.
Pricing Analysis
Diesel-to-electric fleet transition costs widen the pricing gap between legacy diesel-dependent operators and next-generation battery-electric networks, with charging infrastructure deployment timelines determining who captures premium positioning. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation hinging on delivery velocity and recipient control over receipt timing. Pricing pressure stems from Ver.di collective bargaining agreements that fix labor costs above flexible gig-economy alternatives. E-commerce platforms exhibit highest price sensitivity, while pharmaceutical and grocery verticals tolerate premium rates for temperature-controlled rapid fulfillment.
Supply Chain Analysis
Contract manufacturing concentration in the Netherlands and Poland for automated sortation equipment, combined with Chinese dominance in battery-electric van production, shapes procurement timelines for depot modernization. Lithium-ion battery cells, charging hardware, and machine-vision sorting components draw from East Asian supply chains vulnerable to maritime logistics chokepoints. Distribution runs through hub-and-spoke networks anchored in North Rhine-Westphalia, with micro-fulfillment nodes proliferating in Bavaria and Baden-Württemberg to compress last-mile radii.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in rural postal codes where battery-electric range constraints and locker network gaps create service vacuums for agile entrants. E-commerce fulfillment demand from fashion and electronics retailers is splintering volume across specialized operators rather than consolidating under universal carriers.
For Market Incumbents: Pre-empt locker network saturation in Bavaria and Baden-Württemberg by accelerating automated terminal deployment ahead of Hermes Germany's independent courier partnerships. Lock in grid capacity reservations for depot electrification before municipal utility expansion lags fleet procurement cycles. Vertical integration into predictive logistics software reduces exposure to legacy system integration failures that stall dynamic routing adoption. For New Entrants and Emerging Players: Rural pharmaceutical delivery in Mecklenburg-Vorpommern and Saxony-Anhalt represents the most penetrable entry point, where hybrid fleet configurations and temperature-controlled micro-depots address incumbent battery-electric range gaps. Grocery same-day fulfillment in Alpine foothill zones offers white-space expansion with premium pricing tolerance. Go-to-market leverage should anchor on independent courier partnerships that minimize fixed labor exposure under Ver.di collective agreements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among locker network operators with dense Bavaria and Baden-Württemberg footprints, where 24/7 recipient access locks in platform-aggregated e-commerce volume. Long-term viability favors asset-light specialists with established last-mile density over capital-heavy integrated carriers facing diesel fleet stranding risk. Watch battery-electric van range extension breakthroughs as the inflection signal for rural network redesign economics.| Strategic Initiative | Industry Significance |
|---|---|
| Locker Network Saturation | Dense Bavaria and Baden-Württemberg installations reduce failed delivery rates below door-to-door economics. |
| Depot Electrification Partnership | Municipal utility coordination in North Rhine-Westphalia accelerates grid capacity ahead of KBA compliance deadlines. |
| Predictive Logistics Acquisition | Machine-vision sortation hubs in the Rhine-Ruhr corridor digitize labor allocation away from seasonal hiring surges. |
| Rural Hybrid Fleet Retention | Mecklenburg-Vorpommern and Saxony-Anhalt coverage sustains service where battery-electric range falls short. |
| Pharmaceutical Same-Day Certification | Temperature-controlled rapid fulfillment captures grocery and pharmaceutical verticals underpenetrated by fashion-focused operators. |
Research Methodology
Cross-validation between primary interviews with CEP operations directors, fleet procurement managers, and e-commerce platform logistics leads and secondary validation through KBA commercial vehicle registration data, Central Agency Packaging Register filings, and EU Green Deal transport decarbonization benchmarks anchors the qualitative findings. Bottom-up volume modeling from postal code-level delivery density triangulates against top-down federal-state consumption projections.
Calibration against historical CEP volume trajectories and e-commerce penetration curves shapes the analytical framework across the projection horizon. Segmentation dimensions include service velocity tier, delivery mode infrastructure, customer contract type, and package physical characteristics. CAGRs derive from elasticity modeling of delivery time compression tolerance and fleet electrification cost pass-through assumptions, with battery-electric van adoption curves and locker network deployment rates as key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending on fashion and electronics would shift the trajectory. Forecasts reflect documented assumptions on regulatory compliance timelines and technology cost curves. Quarterly review of KBA fleet registration data and municipal utility grid expansion announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Brazil 3PL Market
Logistics and Shipping
United States Apparel Logistics Market
Logistics and Shipping
Global Freight Broker Software Market
Logistics and Shipping
Peru Road Freight Transport Market
Logistics and Shipping
Nigeria Freight and Logistics Market
Logistics and Shipping
US International Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Global Courier Market
Logistics and Shipping
Singapore Freight and Logistics Market
Logistics and Shipping
South America Freight and Logistics Market
Logistics and Shipping
United States Chartered Air Freight Transport Market
Logistics and Shipping
Europe Logistics Automation Market
Logistics and Shipping
Italy Courier Market
Logistics and Shipping
Event Logistics Market
Logistics and Shipping
Latin America Stevedoring and Marine Cargo Handling Market
Logistics and Shipping
Roll Trailer Market
Logistics and Shipping
Iraq Air Freight Transport Market