
 Germany Domestic Courier, Express, and Parcel (CEP) Market | 2026-2036
Germany Domestic Courier, Express, and Parcel (CEP) Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Domestic Courier, Express, and Parcel (CEP) Market Insights
Real-time route optimization and automated sortation is narrowing the cost gap between express and standard delivery tiers in Germany. Deutsche Post AG leverages its nationwide Packstation network to sustain last-mile density. DPD anchors urban same-day coverage through micro-fulfillment nodes. GLS competes on cross-border parcel consolidation into Eastern European corridors.
The Germany Domestic Courier, Express, and Parcel sector encompasses time-definite and non-time-definite logistics services operating within federal borders, utilizing road-dominant networks with hub-and-spoke sortation facilities processing up to 50,000 items per hour. Its primary commercial purpose is bridging inventory velocity with end-consumer accessibility across manufacturing, retail, and institutional supply chains. Standard Delivery occupies the volume base, while Same-Day Delivery captures premium margin pools in dense agglomerations. Express Courier differentiates through guaranteed morning delivery windows for healthcare and financial document flows.
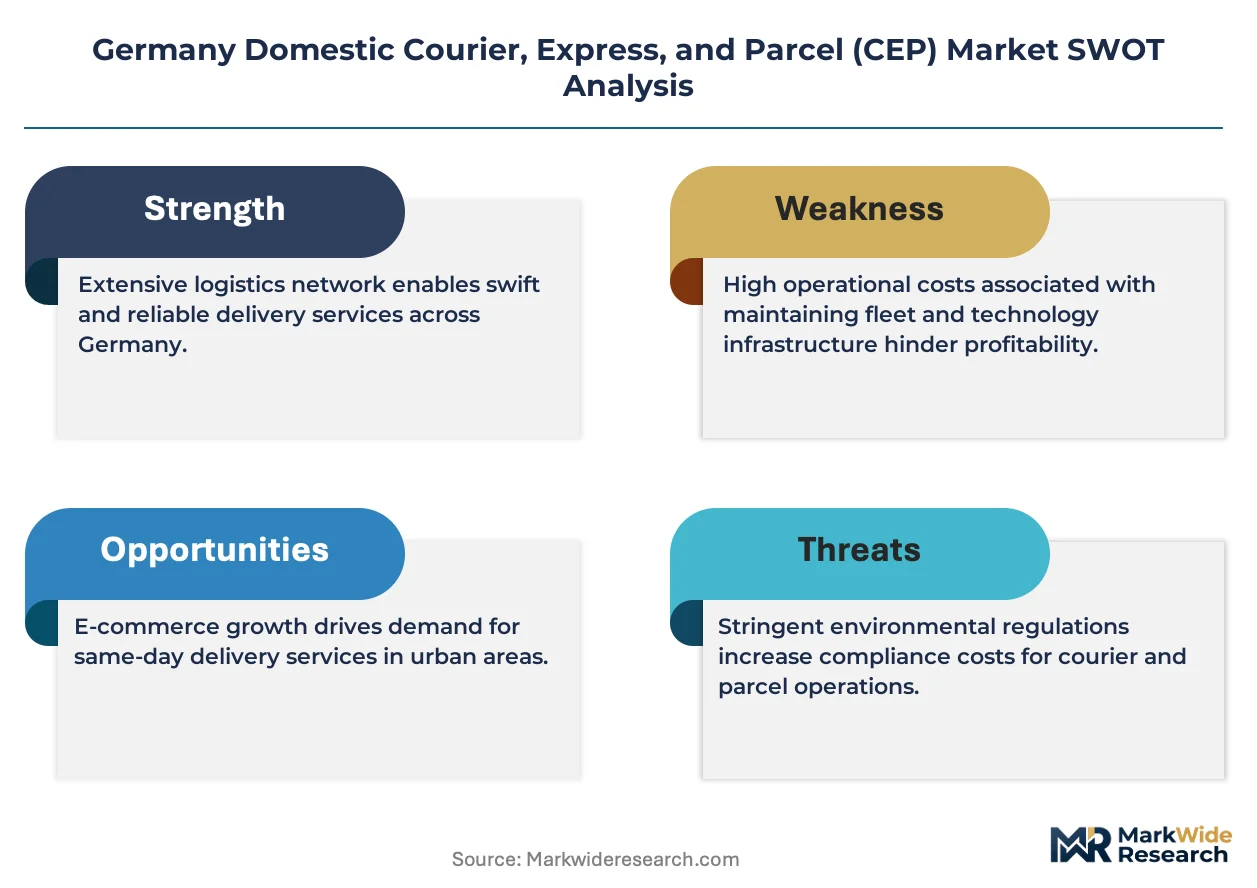
KBA vehicle-type approval and EU Green Deal emissions benchmarks shape fleet procurement decisions, compelling operators to electrify urban delivery vehicles. The German Packaging Act mandates recyclability standards that increase operational compliance costs per shipment. Stakeholders must weigh capital allocation between automated sortation and electric fleet conversion as regulatory thresholds tighten.
Market Dynamics
The EU Green Deal is forcing parcel carriers to accelerate fleet electrification ahead of binding emissions thresholds, while automated sortation investments compress per-unit handling costs across hub-and-spoke networks.
Growth Catalysts
- E-commerce fulfillment velocity:Urban agglomerations in Berlin, Hamburg, and Munich generate concentrated same-day delivery demand that justifies micro-fulfillment node deployment.
- KBA vehicle-type approval pathways:Streamlined certification for electric light commercial vehicles accelerates fleet turnover timelines for last-mile operators.
- German Packaging Act recyclability mandates:Standardized material specifications reduce packaging complexity for cross-carrier consolidation, lowering compliance coordination costs.
Market Restraints
- Lithium-ion battery supply concentration:Cell production bottlenecks in East Asian manufacturing corridors create procurement delays for electric van conversions.
- Last-mile labor cost rigidity:Collective bargaining agreements in German logistics limit flexible staffing models during demand spikes.
- Hub real estate scarcity:Zoning restrictions in metropolitan peripheries constrain automated sortation facility expansion.
Strategic Opportunities
- Rural route electrification:Battery range improvements now enable zero-emission service to secondary cities beyond Berlin-Hamburg-Munich corridors.
- Healthcare specimen logistics:Temperature-controlled express courier services for biopharma clinical trials remain underpenetrated relative to general parcel volumes.
- Carbon accounting integration:CSRD disclosure requirements create demand for shipment-level emissions tracking as a premium service tier.
Industry Challenges
- Automated sortation technician scarcity:Maintenance of high-throughput hub systems requires electromechanical specialists in short supply across German labor markets.
- Legacy IT stack integration:Real-time route optimization platforms must interface with decades-old warehouse management systems still prevalent in mid-tier logistics operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Domestic Courier, Express, and Parcel (CEP) Market |
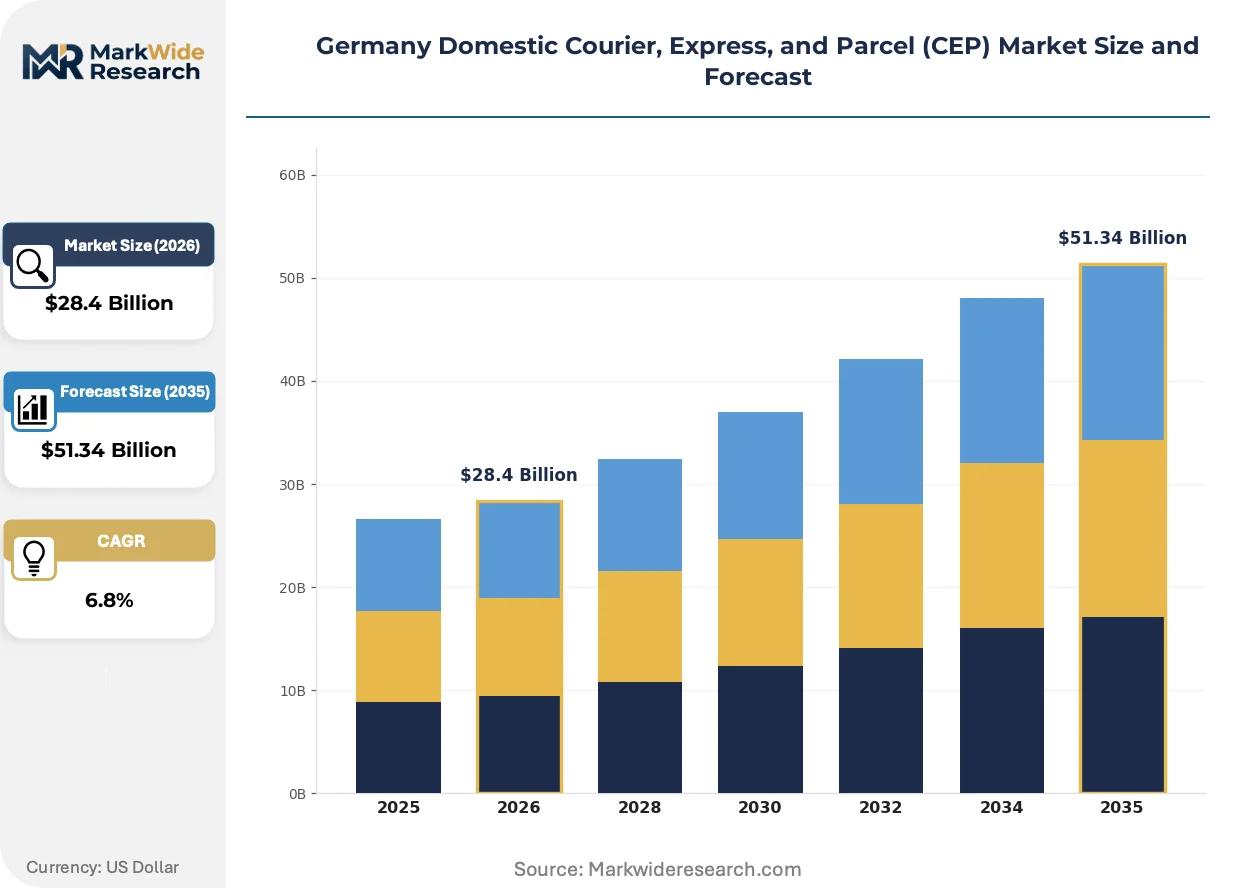
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $51.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Standard Delivery, Same-Day Delivery, Next-Day Delivery, Express Courier Customer Type: Retail, E-commerce, Healthcare, Government Delivery Mode: Road, Air, Rail, Multi-Modal Package Type: Document, Parcel, Pallet, Freight |
| Companies Covered | Deutsche Post AG, DHL Group, DPD, Hermes Europe, General Logistics Systems (GLS), United Parcel Service (UPS), FedEx Express, DB Schenker, Amazon Logistics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Domestic Courier, Express, and Parcel (CEP) Market Trends and Innovations
Digital freight matching and predictive capacity allocation are compressing the planning horizon for parcel networks from days to hours, fundamentally altering asset utilization patterns.
Computer vision-based parcel dimensioning and weight verification is rendering obsolete manual cubing stations at sortation hubs. Third-party logistics providers serving mid-market e-commerce merchants are adopting these systems fastest, attracted by labor cost reductions. The technology is rendering obsolete traditional hub staffing models that relied on seasonal workforce scaling.
The EU Green Deal's 2035 zero-emission vehicle mandate for urban freight is compelling carriers to front-load electric fleet procurement. KBA approval timelines for new electric van models have shortened, but charging infrastructure gaps in secondary cities create operational friction. Express courier segments with fixed morning delivery windows face the tightest vehicle availability constraints.
Buyer procurement of courier services is fragmenting across dedicated fleet contracts, spot-market platforms, and integrated logistics subscriptions. E-commerce marketplaces are unbundling last-mile delivery from warehousing, creating direct relationships with parcel carriers that bypass traditional 3PL intermediaries. This pattern is most visible in Berlin's dense startup ecosystem, where direct carrier API integrations dominate platform logistics stacks.
Germany Domestic Courier, Express, and Parcel (CEP) Market Segmentation
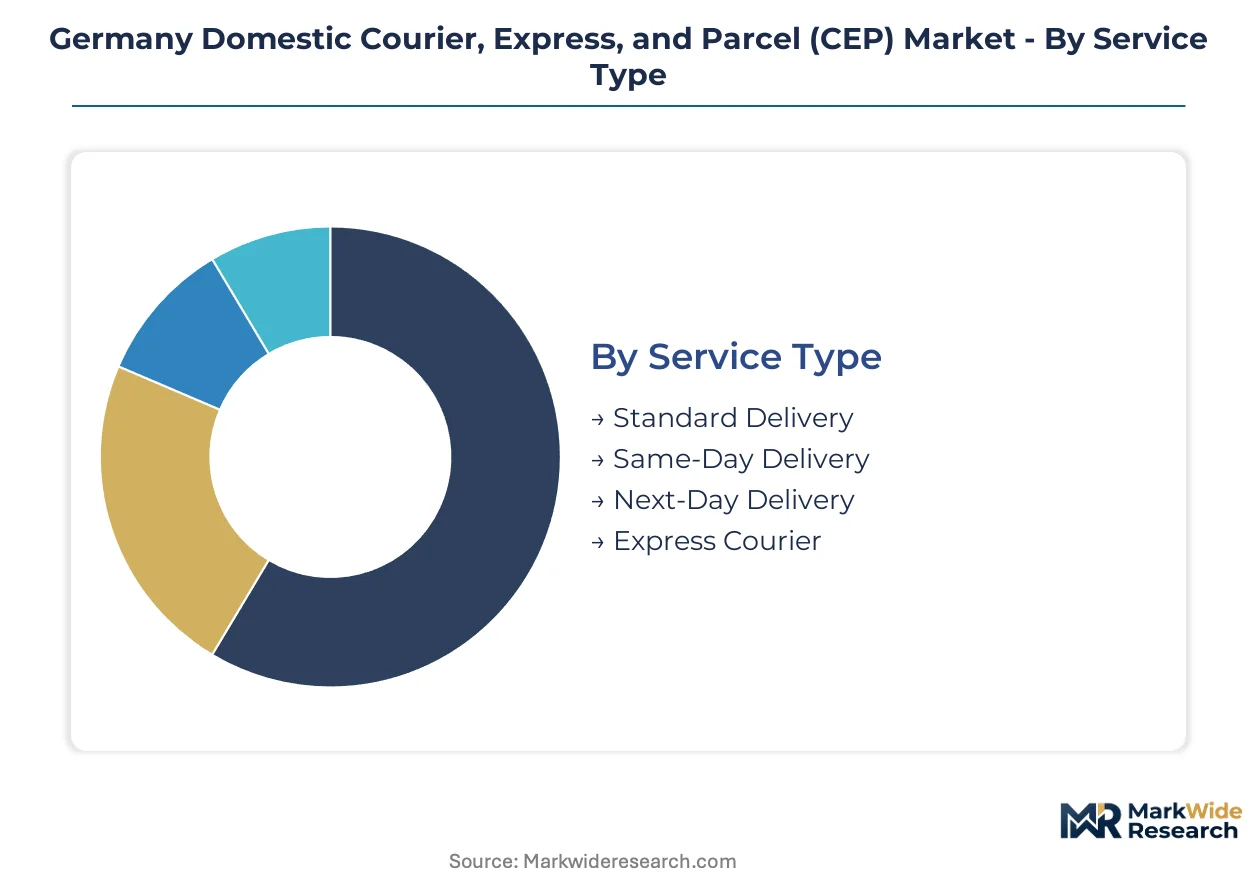
Service differentiation in the Germany Domestic CEP market determines capital allocation between automated hub infrastructure and last-mile density investments. Customer verticals dictate temperature control requirements and delivery window guarantees. Package characteristics shape vehicle fleet composition and sortation throughput design across federal logistics networks.
Service Type:
Velocity requirements span from non-time-definite ground transport to guaranteed morning delivery windows, creating distinct operational footprints and margin structures.
- Standard Delivery:Non-time-definite ground transport operates through hub-and-spoke networks with deferred delivery commitments. E-commerce fulfillment centers in the Ruhr Valley generate concentrated volume that justifies high-throughput automated sortation investments.
- Same-Day Delivery:Urban micro-fulfillment nodes position inventory within 15 kilometers of Berlin, Hamburg, and Munich endpoints. Premium pricing captures dense agglomeration demand while electric cargo bikes navigate congestion-charged city centers.
- Next-Day Delivery:Overnight hub processing enables morning delivery guarantees across secondary cities. Network design prioritizes line-haul efficiency over last-mile density.
- Express Courier:Dedicated vehicle assignments with real-time tracking serve healthcare specimen transport and financial document flows. KBA-approved electric vans meet EU Green Deal emissions thresholds for urban morning routes.
Established volume favors Standard Delivery; emerging adoption favors Same-Day Delivery.
Customer Type:
Vertical-specific compliance requirements reshape service level agreements and liability frameworks.
- Retail:Department store chains and specialty merchants demand flexible returns processing integrated with forward logistics. Seasonal volume spikes require surge capacity from collective bargaining-constrained workforces.
- E-commerce:Marketplace merchants drive API-native carrier integrations that bypass traditional 3PL relationships. Berlin's startup ecosystem concentrates platform-native logistics demand.
- Healthcare:Temperature-controlled transport for clinical trial specimens and pharmaceutical products commands specialized fleet equipment. German Packaging Act recyclability mandates complicate cold-chain insulation materials.
- Government:Tender-based procurement favors established operators with nationwide Packstation infrastructure. Document security protocols require chain-of-custody verification systems.
Margin compression hits Retail; contract stability favors Government.
Delivery Mode:
Modal selection balances speed requirements against EU Green Deal emissions compliance timelines.
- Road:Dominant mode for last-mile distribution with expanding electric light commercial vehicle deployment. KBA approval pathways have shortened for zero-emission van models.
- Air:Limited domestic application reserved for island territories and emergency medical logistics. High carbon intensity faces tightening CSRD disclosure scrutiny.
- Rail:Inter-city parcel consolidation between Cologne, Frankfurt, and Berlin reduces line-haul emissions. Infrastructure constraints limit terminal access for final-mile handoff.
- Multi-Modal:Rail-road combinations optimize long-distance efficiency with flexible last-mile completion. Coordination complexity increases transit time variability.
Road maintains volume dominance; rail electrification offers the steepest emissions reduction trajectory.
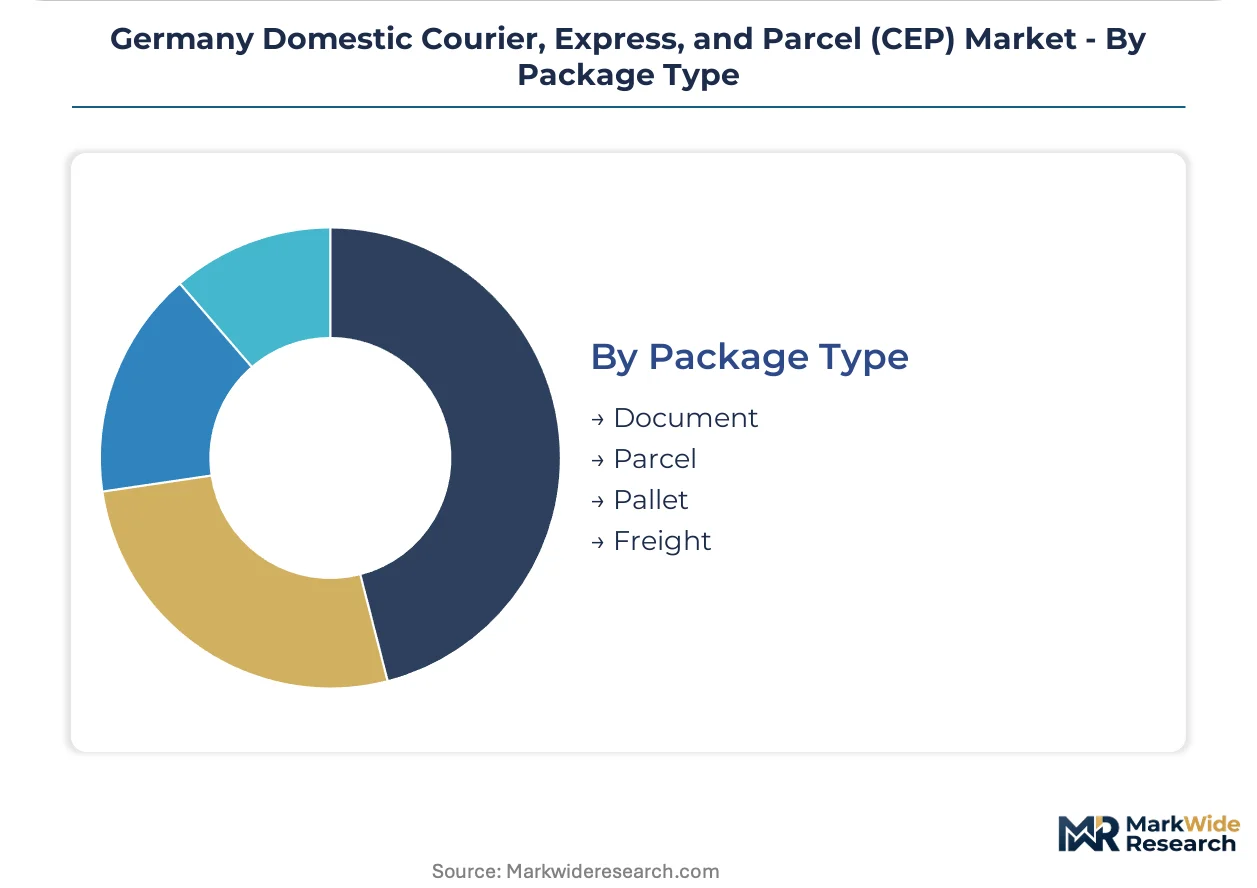
Package Type:
Physical characteristics determine sortation system design and vehicle payload optimization.
- Document:Lightweight envelopes enable high-density delivery rounds with minimal dimensional weight penalties. Digital displacement is compressing volumes in financial and legal verticals.
- Parcel:Standardized dimensions facilitate automated dimensioning and weight verification through computer vision systems. E-commerce growth sustains volume expansion.
- Pallet:Business-to-business freight requires dedicated vehicle fleets with lift-gate equipment. Manufacturing supply chains in Baden-Württemberg generate consistent demand.
- Freight:Project logistics and irregular dimensions demand specialized handling equipment and route planning. Cross-border consolidation into Eastern European corridors competes with domestic capacity allocation.
Parcel automation investment outpaces Document decline; Freight specialization commands premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German CEP operators channel cross-border volumes through the Netherlands and Belgium into UK and French consumer markets, while eastward flows serve Polish and Czech industrial corridors.
Bavaria
Munich's dense startup ecosystem and automotive supply chains generate premium same-day delivery demand for precision components. KBA vehicle-type approval pathways accelerate electric van deployment across the southern federal state. The Munich-Regensburg corridor hosts micro-fulfillment nodes serving Nuremberg manufacturing clusters with sub-two-hour delivery windows.
North Rhine-Westphalia
Ruhr Valley e-commerce fulfillment centers produce concentrated parcel volumes that justify high-throughput automated sortation investments. The German Packaging Act mandates recyclability standards that increase per-shipment compliance costs for Düsseldorf-based operators. Cologne-Dortmund rail terminals enable inter-city parcel consolidation reducing line-haul emissions across the Rhine-Ruhr metropolitan region.
Baden-Württemberg
Stuttgart's machinery and automotive sectors drive palletized freight demand for just-in-time manufacturing supply chains. EU Green Deal emissions benchmarks compel fleet electrification for urban delivery routes serving Mannheim chemical corridors. The Karlsruhe-Freiburg agglomeration anchors cross-border parcel consolidation into Eastern European markets through Basel rail connections.
Berlin-Brandenburg
Capital region e-commerce platforms concentrate same-day delivery demand within the S-Bahn ring and Potsdam periphery. KBA approval timelines for electric light commercial vehicles have shortened, though charging infrastructure gaps in Brandenburg exurbs create operational friction. Spreewald logistics parks host automated sortation facilities processing up to 50,000 items per hour for nationwide distribution.
Hamburg
Port city container throughput generates substantial air and sea freight intermodal handoffs for express courier networks. The EU Green Deal's 2035 zero-emission mandate accelerates electric cargo bike deployment across Hamburg's congestion-charged city center. Altona and Harburg districts concentrate last-mile micro-fulfillment nodes serving northern German secondary cities through overnight line-haul connections.
Germany Domestic Courier, Express, and Parcel (CEP) Market Competitive Landscape
On the supply side, the industry is consolidated around integrated postal incumbents and parcel specialists competing through network density and regulatory compliance capabilities. Three strategic archetypes dominate: nationwide postal operators with Packstation infrastructure, express specialists with guaranteed morning delivery windows, and platform-integrated last-mile providers. Competitive positioning hinges on automated sortation capacity expansion and electric fleet conversion timelines ahead of binding emissions thresholds.
Within the integrated postal tier, Deutsche Post AG and DHL Group exemplify network-scale operators leveraging hub-and-spoke density. Parcel specialists DPD occupy positions anchored through urban micro-fulfillment node deployment. Among cross-border consolidators, General Logistics Systems (GLS) represents the Eastern European corridor focus archetype.
| Leading Market Players |
|---|
| Deutsche Post AG |
| DHL Group |
| DPD |
| Hermes Europe |
| General Logistics Systems (GLS) |
| United Parcel Service (UPS) |
| FedEx Express |
| DB Schenker |
| Amazon Logistics |
| Others |
Pricing and Supply Chain Analysis
East Asian lithium-ion cell production concentration feeds directly into German electric van conversion costs, compressing margin pools for last-mile operators while EU Green Deal compliance deadlines harden. Battery procurement bottlenecks reshape where pricing power accumulates across express and standard delivery tiers.
Pricing Analysis
Legacy diesel fleet pricing diverges from next-generation electric van economics across service tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by delivery velocity and emissions compliance certification. Cost compression in standard delivery is intensifying because automated sortation investments amortize across higher volumes. E-commerce marketplace merchants exhibit highest price sensitivity, while healthcare specimen logistics buyers accept premium positioning for temperature guarantee and chain-of-custody verification.
Supply Chain Analysis
Tariff exposure between China and Germany dominates component procurement risk for electric light commercial vehicle fleets. Cell production draws from China, South Korea, and Japan, while power electronics and thermal management systems rest on Taiwanese semiconductor foundries. Single-source vulnerability concentrates in cathode active material supply. Distribution runs through hub-and-spoke sortation facilities with final-mile handoff via franchised depots and company-operated micro-fulfillment nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon accounting services and shipment-level emissions tracking represent a recurring-revenue layer expanding faster than parcel volume growth itself. The attach rate for sustainability-linked reporting tools is outpacing core logistics contract expansion.
For Market Incumbents: Harden automated sortation capacity in Ruhr Valley and Berlin-Brandenburg corridors against DPD's micro-fulfillment node encroachment. Secure captive supply of KBA-approved electric van allocations ahead of 2035 zero-emission mandates. Vertical integration into charging infrastructure partnerships reduces operational friction in secondary city exurbs.
For New Entrants and Emerging Players: Establish a beachhead in healthcare specimen logistics where temperature-controlled express courier capacity remains underpenetrated relative to general parcel volumes. Target Baden-Württemberg pharmaceutical corridors and Bavarian clinical trial hubs. Lead with API-native carrier integrations that bypass legacy 3PL relationships dominating Berlin's startup ecosystem.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated hub infrastructure and electric fleet conversion programs. Favor acquisition targets with established Packstation density and KBA certification pathways already secured. Watch lithium-ion cell supply contract durations as the inflection indicator for margin sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Sortation Facility Expansion | High-throughput hub investments in Ruhr Valley compress per-unit handling costs for e-commerce volumes. |
| Electric Fleet Conversion Program | KBA-approved van procurement ahead of EU Green Deal deadlines secures urban route operating rights. |
| Micro-Fulfillment Node Deployment | Urban density investments in Berlin, Hamburg, and Munich enable same-day delivery premium capture. |
| Carbon Accounting Service Launch | CSRD-compliant shipment-level emissions tracking creates recurring revenue attachment to core logistics contracts. |
| Healthcare Logistics Certification | Temperature-controlled express courier credentials unlock biopharma clinical trial specimen transport contracts. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with logistics operations directors, fleet procurement managers, e-commerce platform supply chain leads, and KBA certification specialists; and secondary validation against Bundesnetzagentur regulatory filings, KBA vehicle approval databases, EU Green Deal implementation trackers, and customs trade statistics for electric commercial vehicle imports. Bottom-up parcel volume modeling and top-down CEP market sizing were triangulated for consistency.
Forecast inputs include service type velocity requirements, customer vertical compliance specifications, delivery mode emissions trajectories, and package type sortation throughput design across the projection horizon. Segmentation dimensions modeled encompass service tier, customer vertical, delivery mode, and package physical characteristics. CAGRs were derived from historical volume trends adjusted for e-commerce penetration curves and regulatory compliance cost step-changes. Electric van adoption timelines and automated sortation capital deployment schedules served as primary forecast inputs.
Sensitivities concentrate around lithium-ion cell supply contract renegotiations and KBA approval timeline extensions for new electric van models. Forecasts reflect assumptions about EU Green Deal implementation pacing and German Packaging Act recyclability cost pass-through. Macroeconomic contraction, regulatory enforcement deviation, or battery technology substitution would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Global Load Planning Services and Solutions Market
Logistics and Shipping
Express Delivery Market
Logistics and Shipping
Japan Dangerous Goods Logistics Market
Logistics and Shipping
Saudi Arabia Third-Party Logistics (3PL) Market
Logistics and Shipping
APAC Contract Logistics Market
Logistics and Shipping
France Cold Chain Logistics Market
Logistics and Shipping
United Arab Emirates (UAE) Third-Party Logistics (3PL) Market
Logistics and Shipping
Brazil Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Italy Cold Chain Logistics Market
Logistics and Shipping
Shipping Container Market
Logistics and Shipping
Sweden Freight and Logistics Market
Logistics and Shipping
GCC Automotive Logistics Market
Logistics and Shipping
Asia Pacific Sea Freight Forwarding Market
Logistics and Shipping
India Contract Logistics Market
Logistics and Shipping
Egypt Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Asia-Pacific Container Drayage Market