
 Fine Art Logistics Market | 2026-2036
Fine Art Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Fine Art Logistics Market Analysis
Climate-controlled subscription services for recurring exhibition cycles is shifting how logistics contracts are structured. Crozier Fine Arts leverages its museum network across North America to sustain long-term client relationships. Crown Fine Art anchors European high-value transport through specialized temperature and humidity protocols. Momart competes on installation capabilities, controlling end-to-end exhibition build-outs for institutional clients.
Fine art logistics encompasses the specialized handling, transport, storage, and installation of cultural assets requiring environmental stabilization between 18-22°C and 45-55% relative humidity, with vibration monitoring below 0.5g during transit. Transport services dominate contract value due to the capital intensity of dedicated climate vehicles and air-ride suspension fleets. Insurance solutions represent the fastest-growing margin pool as underwriters develop parametric coverage tied to real-time sensor data. Galleries and museums anchor client-type demand, though private collector segments are expanding through fractional ownership platforms.
The EU Green Deal's F-Gas Regulation is phasing down hydrofluorocarbon use in transport refrigeration, forcing fleet retrofits across European operators. US DOT hazmat classifications and TSA cargo screening requirements shape cross-border air freight protocols for traveling exhibitions. Stakeholders must monitor how digital condition monitoring and blockchain provenance tracking reshape service differentiation and liability structures.
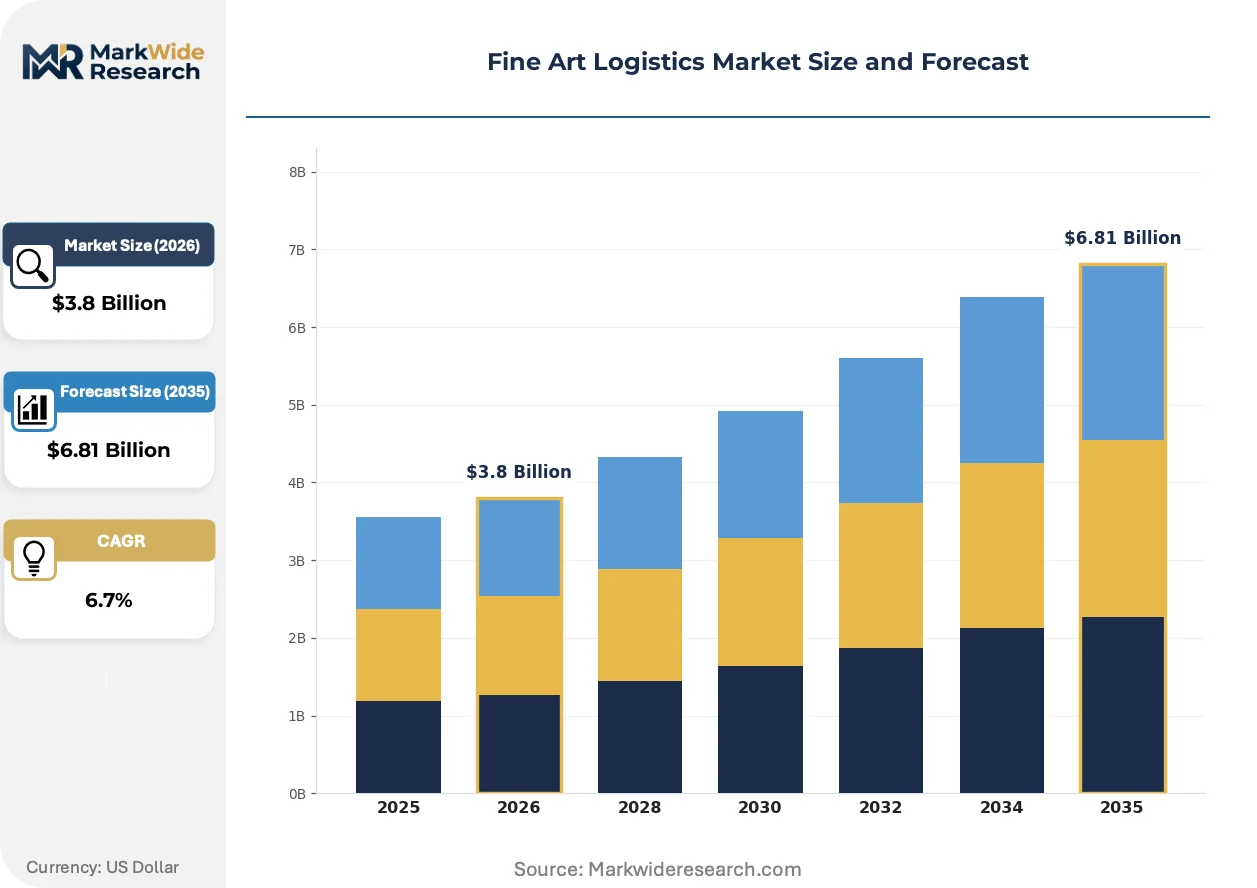
Market Dynamics
Climate-controlled subscription services for recurring exhibition cycles are restructuring contract economics across the fine art logistics sector, compressing traditional spot-rate pricing models into long-term service agreements.
Growth Catalysts
- EU Green Deal F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants is forcing fleet modernizations that improve energy efficiency and reduce operating costs for compliant operators.
- Museum international loan programs:Expanding exhibition calendars at major institutions are generating predictable demand for specialized transport and installation services.
- Parametric insurance products:Real-time sensor data integration is enabling underwriters to price risk more precisely, expanding coverage availability for high-value movements.
Market Restraints
- Specialized vehicle capital intensity:Air-ride suspension fleets and climate-control systems require substantial upfront investment with extended depreciation cycles.
- Qualified handler scarcity:Certified art handlers with conservation training represent a bottleneck in labor supply across major logistics hubs.
- Cross-border regulatory friction:US DOT hazmat classifications and TSA cargo screening create procedural delays for traveling exhibitions entering North American airspace.
Strategic Opportunities
- Fractional ownership platforms:Private collector segments are accessing museum-grade logistics through shared-asset models previously reserved for institutional clients.
- Blockchain provenance integration:Immutable chain-of-custody records are reducing title disputes and accelerating insurance underwriting for secondary market transactions.
- India's cultural infrastructure expansion:New museum construction and private gallery formation are creating first-mover advantages for operators establishing climate-controlled facilities.
Industry Challenges
- Conservation-grade technician recruitment:The intersection of art history knowledge and logistics operations expertise remains difficult to staff at scale.
- Legacy condition monitoring integration:Analog documentation systems at smaller institutions resist digitization, complicating end-to-end shipment visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fine Art Logistics Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transport, Packing, Installation, Insurance Client Type: Galleries, Museums, Collectors, Dealers Solution: Temperature Control, Security Systems, Tracking Software, Inventory Management Delivery Mode: Air Freight, Sea Freight, Ground Transport, Courier |
| Companies Covered | Crozier Fine Arts, Crown Fine Art, DHL Group, Masterpiece International, Momart, DB Schenker, Gander & White, Cadogan Tate, Hasenkamp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fine Art Logistics Market Emerging Trajectories
Digital condition monitoring and automated environmental controls are compressing the acceptable variance in transit protocols, raising baseline service expectations across buyer segments.
IoT-enabled vibration and climate sensors are expanding into standard service tiers, transmitting real-time data on temperature, humidity, and shock events to centralized monitoring platforms. Mid-sized galleries are adopting these systems as contract requirements from institutional lenders tighten. This capability diffusion is expanding into competitive differentiation for regional operators seeking to displace established incumbents on service transparency.
The EU F-Gas Regulation is mandating refrigerant phase-down schedules that accelerate fleet replacement timelines across European operators. Specialized art vehicle manufacturers are responding with CO2-based climate systems that eliminate synthetic refrigerants entirely. German and French logistics providers face the most compressed compliance deadlines given their concentration of cross-border exhibition traffic.
Institutional procurement patterns are consolidating around multi-year framework agreements that bundle transport, storage, and installation services under unified performance metrics. Museums are displacing transactional spot contracts with subscription structures that guarantee capacity during peak exhibition seasons. This shift is most pronounced in North American and Western European markets where lender liability requirements have standardized.
Fine Art Logistics Market Segmentation
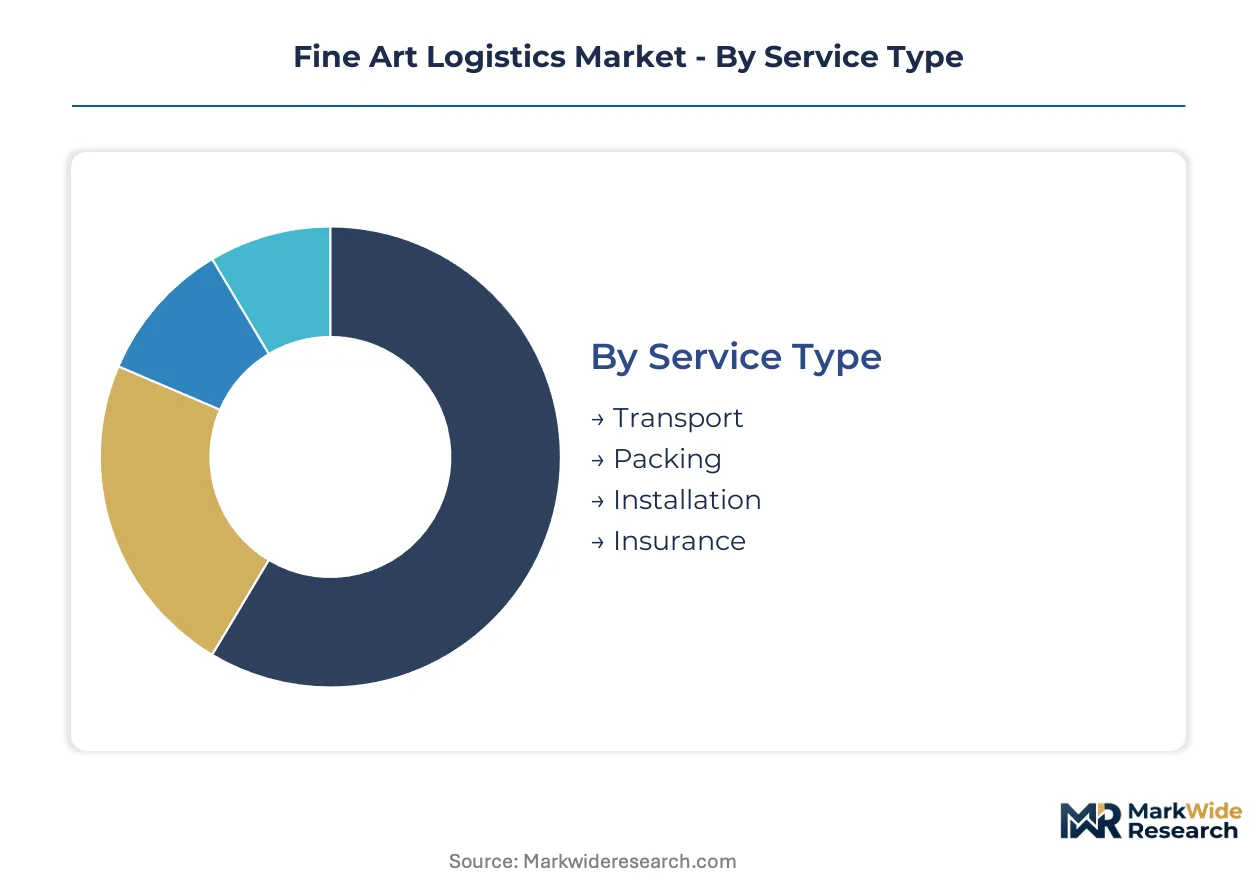
Segmentation in fine art logistics determines contract structure, capital deployment, and margin capture. Service intensity varies dramatically across client types, while environmental control requirements differentiate solution tiers.
Service Type:
Customization intensity spans from commoditized packing to highly engineered climate transport protocols.
- Transport:Dedicated climate vehicles with air-ride suspension and 18-22°C stabilization command premium contract values. Demand concentrates in Germany and the United States where major auction houses and museum consortiums anchor high-value cross-border movements.
- Installation:End-to-end exhibition build-outs require conservation-trained technicians and specialized rigging equipment. Museums in North America and Western Europe are consolidating procurement around multi-year framework agreements that bundle installation with transport services.
- Packing:Crating solutions range from standard foam-core enclosures to museum-grade vapor-barrier systems with shock-absorbent interiors.
- Insurance:Parametric coverage products tied to real-time sensor data are expanding availability for high-value movements.
Most installed capacity flows through Transport. Expansion is steepest in Insurance.
Client Type:
Volume concentration sits with institutional buyers, though private market participation is diversifying revenue pools.
- Museums:International loan programs generate predictable, recurring demand with stringent lender liability requirements. These clients are displacing spot contracts with subscription structures that guarantee capacity during peak exhibition seasons.
- Galleries:Mid-sized commercial operators are adopting IoT-enabled monitoring systems as contract requirements from institutional lenders tighten.
- Collectors:Fractional ownership platforms are opening museum-grade logistics access to private individuals previously excluded from specialized service tiers.
- Dealers:Secondary market transactions require rapid, flexible response times with blockchain provenance integration reducing title dispute delays.
Museums absorb the largest share of contract value. Collectors are gaining share fastest through platform-enabled access.
Solution:
Technology differentiation separates baseline compliance from competitive advantage in environmental stewardship.
- Temperature Control:CO2-based climate systems are eliminating synthetic refrigerants in response to EU F-Gas Regulation mandates. German and French operators face compressed compliance deadlines given cross-border exhibition traffic concentration.
- Tracking Software:IoT-enabled vibration and climate sensors transmitting real-time data are becoming standard service tier expectations.
- Security Systems:GPS monitoring, tamper-evident seals, and armed escort protocols protect ultra-high-value movements.
- Inventory Management:Digital condition documentation is replacing analog systems at smaller institutions, though legacy integration remains challenging.
Temperature Control commands the highest capital intensity. Tracking Software is climbing the fastest as transparency requirements harden.
Delivery Mode:
Speed-cost trade-offs align with object value, exhibition deadlines, and geographic constraints.
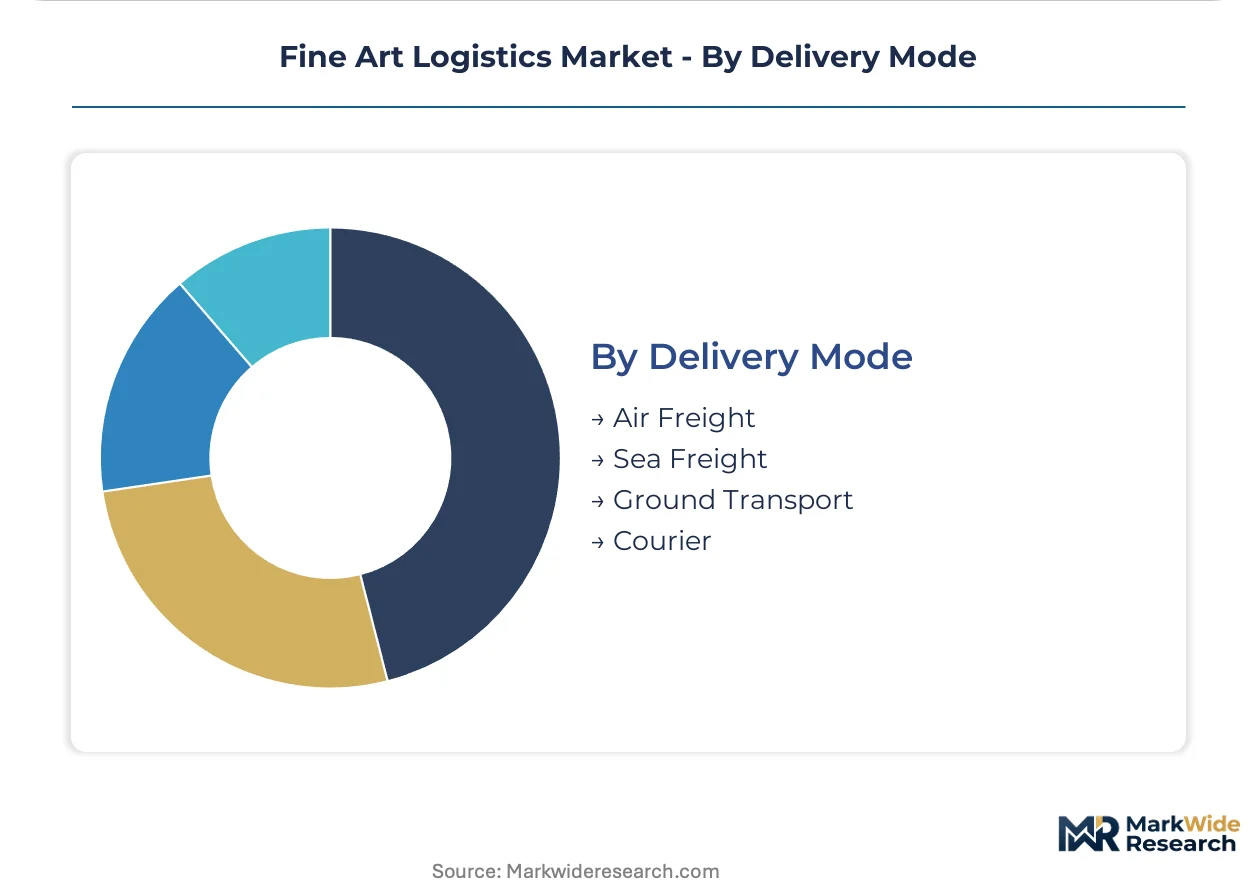
- Ground Transport:Specialized art vehicles with air-ride suspension dominate regional movements within Europe and North America. EU Green Deal energy efficiency requirements are tightening fleet specifications.
- Air Freight:Cross-border exhibition traffic relies on TSA cargo screening protocols and hazmat classifications that create procedural delays for traveling exhibitions entering North American airspace.
- Sea Freight:Containerized climate solutions serve permanent collection relocations and long-term loans where speed is secondary to cost control.
- Courier:Hand-carry protocols protect ultra-high-value objects requiring continuous chain-of-custody documentation.
Ground Transport carries the highest volume. Air Freight is expanding most quickly as international loan programs accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's auction house concentration generates higher per-shipment values than the United States, though American museum networks sustain greater exhibition loan volumes overall. National regulatory frameworks and cultural infrastructure investments are reshaping logistics demand patterns across key markets.
Germany
Major auction houses and private collectors anchor high-value cross-border movements between Berlin, Munich, and Cologne. The EU Green Deal's F-Gas Regulation is forcing fleet retrofits with CO2-based climate systems for specialized art vehicles. Frankfurt and Hamburg logistics clusters face compressed compliance deadlines given their concentration of international exhibition traffic.
United States
Museum consortiums in New York, Washington DC, and Los Angeles generate predictable demand for recurring exhibition cycles. US DOT hazmat classifications and TSA cargo screening requirements create procedural delays for traveling exhibitions entering North American airspace. The Northeast corridor sustains the densest concentration of climate-controlled storage facilities serving institutional lenders.
United Kingdom
London's secondary market dealers and private galleries drive rapid-response logistics requirements with flexible scheduling demands. Brexit-related customs friction has complicated EU-UK art movements, prompting operators to establish dual-hub structures. The Thames Valley cluster houses specialized crating and conservation facilities serving international auction houses.
France
Paris-based institutional lenders and the Grand Palais exhibition program sustain premium service tier demand throughout the year. French operators face accelerated F-Gas Regulation phase-down schedules alongside German counterparts. The Île-de-France region concentrates both museum-grade storage and specialized art handling training programs.
India
New museum construction in Mumbai and Delhi and private gallery formation are creating first-mover advantages for operators establishing climate-controlled facilities. The country's national cultural infrastructure regulator is tightening environmental standards for cultural asset storage. The Mumbai-Pune corridor is emerging as the primary logistics hub for inbound international loan exhibitions.
Fine Art Logistics Market Vendor Landscape
Top-tier vendors anchor museum and auction house relationships, while mid-tier specialists compete on regional density and installation capabilities. The vendor base stratifies across integrated logistics conglomerates with fine art divisions and pure-play art specialists. Three archetypes dominate: climate-technology leaders, installation-service consolidators, and insurance-integrated operators. Capacity expansion and multi-year framework agreement procurement are displacing transactional spot contracts as the primary competitive battleground.
Within the pure-play specialist tier, Crozier Fine Arts and Crown Fine Art exemplify divergent geographic anchoring strategies, while Momart occupies a position emphasizing end-to-end exhibition build-out capabilities. These operators represent the consolidation pressure facing smaller regional handlers as institutional procurement patterns harden around unified performance metrics and guaranteed capacity commitments.
| Leading Market Players |
|---|
| Crozier Fine Arts |
| Crown Fine Art |
| DHL Group |
| Masterpiece International |
| Momart |
| DB Schenker |
| Gander & White |
| Cadogan Tate |
| Hasenkamp |
| Others |
Supply Flow & Price Mechanics
Horizontal integration across climate-vehicle fleets and specialized handling networks anchors pricing power for tier-one operators while compressing margins for asset-light competitors dependent on third-party capacity. German and French logistics clusters leverage captive CO2-based refrigeration systems to command premium contract tiers under tightening EU F-Gas Regulation deadlines.
Pricing Analysis
Capacity additions in Germany and the United States are reshaping price floors for climate-controlled transport as fleet modernization cycles accelerate. Subscription-based framework agreements dominate institutional procurement, with price differentiation resting on real-time sensor integration and conservation-grade handler certification. Cost compression in standard service tiers is intensifying because mid-sized galleries are adopting IoT monitoring as baseline requirements. Private collectors through fractional ownership platforms demonstrate highest price sensitivity, while museum consortiums prioritize guaranteed capacity over rate negotiation.
Supply Chain Analysis
Direct-to-institution channels handle recurring exhibition demand from museum consortiums and auction houses, bypassing intermediary brokers. Supply concentrates in Germany, the United States, and France where specialized air-ride suspension manufacturing and conservation training programs cluster. Fleet operations draw from aluminum alloy fabrications, precision climate-control compressors, and conservation-grade crating materials. Single-source vulnerability in qualified art handler labor pools threatens capacity expansion timelines. Distribution runs through dedicated contract logistics networks rather than shared freight platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fine art logistics market functions as a stable compounder anchored by irreversible expansion of international museum loan programs and tightening environmental compliance that favors capital-rich incumbents.
For Market Incumbents: To counter margin erosion from IoT-enabled regional competitors, deepen captive maintenance capabilities for climate-vehicle fleets and secure multi-year framework agreements with Grand Palais and Smithsonian-tier institutions before procurement windows close. Certification investment in EU Green Deal-compliant CO2 refrigeration systems locks in compliant capacity. For New Entrants and Emerging Players: Blockchain-enabled provenance tracking offers a technology-first wedge into secondary market dealer segments where title verification delays create service gaps. India's Mumbai-Pune corridor presents the most penetrable geography given new museum construction and absent established climate-controlled infrastructure. Target rapid-response installation services for private galleries as the go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for regional installation specialists because institutional procurement consolidation is displacing fragmented spot-contract vendors. Five-to-ten year viability favors operators with unified transport-storage-installation capabilities and conservation-trained technician benches. Watch F-Gas Regulation enforcement intensity as the inflection signal for stranded-asset risk in legacy refrigerant fleets.| Strategic Initiative | Industry Significance |
|---|---|
| CO2 Fleet Modernization | Eliminates synthetic refrigerant exposure under EU F-Gas Regulation phase-down mandates. |
| Conservation Handler Training Program | Addresses qualified technician scarcity bottlenecking capacity expansion in Frankfurt and Hamburg clusters. |
| Blockchain Provenance Integration | Reduces title dispute delays accelerating insurance underwriting for secondary market transactions. |
| Multi-Year Framework Agreement | Guarantees capacity allocation during peak exhibition seasons displacing transactional spot contracts. |
| India Climate Facility Buildout | Captures first-mover advantage in Mumbai-Pune corridor before national environmental standards tighten. |
Methodological Framework
Multiple input streams — primary interviews with museum registrars, auction house logistics directors, and fine art insurance underwriters; secondary validation through EU regulatory filings, customs trade data, and institutional procurement records; plus specialized vehicle manufacturer technical disclosures — were reconciled through bottom-up service-line modeling and top-down market sizing triangulation.
Historical revenue patterns were cross-referenced against panel input from conservation technicians and climate-system engineers to build projection scenarios across the analysis window. Segmentation dimensions modeled include service type intensity, client institutional versus private status, solution technology tier, and delivery mode speed-cost positioning. CAGRs were derived from fitted growth curves calibrated to exhibition loan volume trajectories and fleet replacement cycle timing.
The model holds under stable regulatory enforcement timelines and continued museum capital expenditure commitment; deviation in F-Gas Regulation acceleration or international loan program retrenchment would shift capacity utilization assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Russia Courier Service Market
Logistics and Shipping
Germany Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Japan Logistics Market
Logistics and Shipping
Intra-Asia Freight Forwarding Market
Logistics and Shipping
Inbound Logistics Market
Logistics and Shipping
Slovakia Freight and Logistics Market
Logistics and Shipping
India E-Commerce Logistics Market
Logistics and Shipping
Russia Freight and Logistics Market
Logistics and Shipping
Europe Contract Logistics Market
Logistics and Shipping
Europe Sea Freight Forwarding Market
Logistics and Shipping
Myanmar Freight and Logistics Market
Logistics and Shipping
North America Shipping Agency Market
Logistics and Shipping
GCC Event Logistics Market
Logistics and Shipping
Peru Logistics Market
Logistics and Shipping
Europe Full Container Load (FCL) Market
Logistics and Shipping
Netherlands Cold Chain Logistics Market