
 Sweden Freight and Logistics Market | 2026-2036
Sweden Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden Freight and Logistics Market Analytics
Last-mile delivery revenue is rewriting margin allocation across Swedish logistics networks. PostNord AB leverages its nationwide parcel locker infrastructure to dominate domestic e-commerce fulfillment. DSV A/S anchors its Nordic hub operations through the Copenhagen-Malmö corridor, capturing cross-border pharmaceutical and automotive flows. Green Cargo AB specializes in rail freight electrification, sustaining competitive positioning on Stockholm-Gothenburg routes where shippers prioritize emission reductions.
Freight and logistics encompasses the physical movement, storage, and information management of goods across road, rail, air, and sea modalities, typically measured by ton-kilometers and container throughput, with systems integrating real-time tracking and automated handling to synchronize supply chains. Road freight maintains the largest volume share in Sweden yet faces margin compression from fuel taxation and driver shortages, while rail freight gains structural advantage from electrified track access and carbon pricing differentials. Warehouse automation within the technology dimension concentrates investment near the Stockholm logistics cluster, where labor costs and throughput requirements justify robotic sorting and autonomous vehicle deployment.
The Swedish Transport Agency enforces EU Mobility Package driving-time regulations that constrain long-haul trucking capacity and redirect investment toward rail interoperability. BIS-aligned vehicle certification standards for electric freight trucks, combined with national carbon dioxide taxation administered by the Swedish Environmental Protection Agency, accelerate fleet turnover decisions among domestic carriers. Stakeholders must weigh electrification capex against evolving EU ETS scope expansion and potential road pricing reforms before committing to terminal infrastructure.
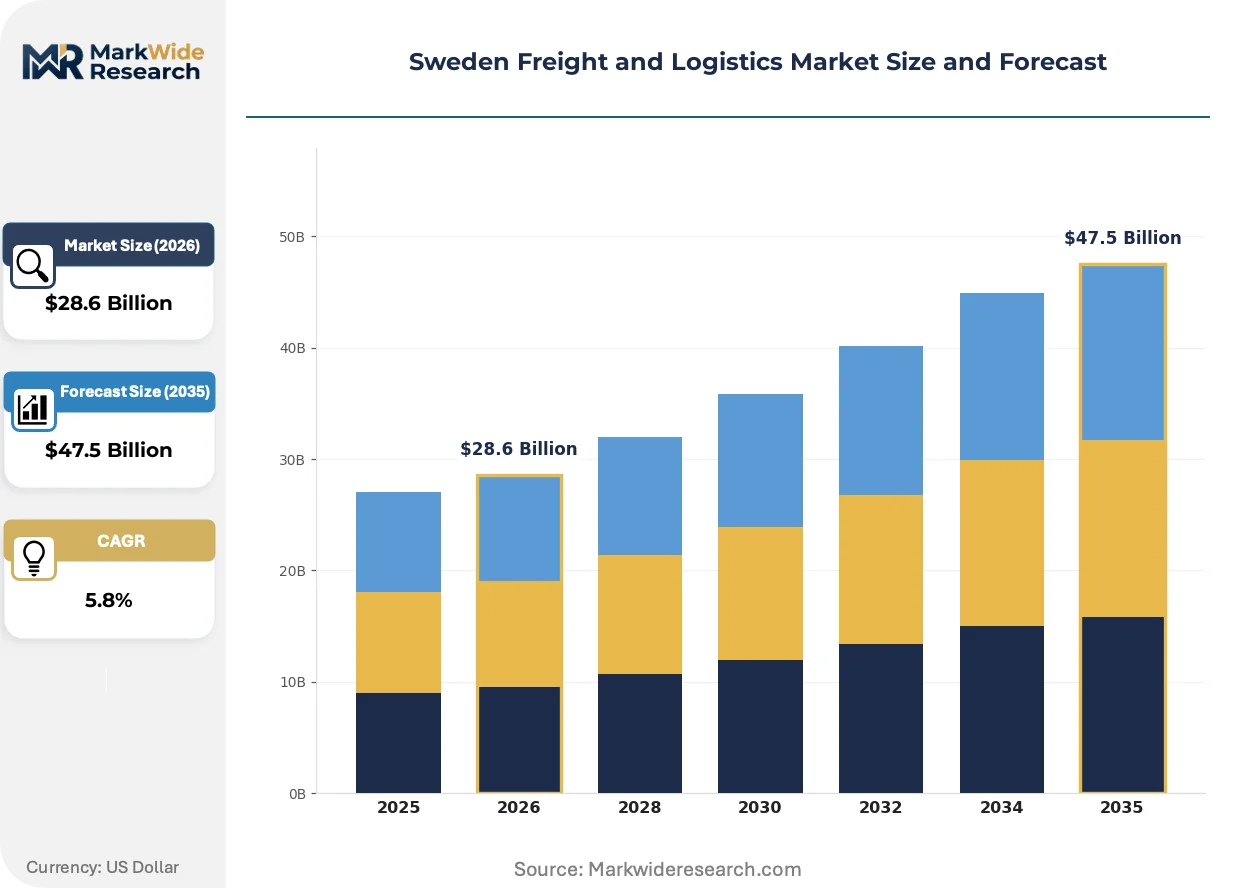
Market Dynamics
EU Green Deal emissions targets are compressing road freight margins while electrified rail corridors capture modal shift from carbon-intensive trucking across Swedish supply chains.
Growth Catalysts
- EU Mobility Package enforcement:The Swedish Transport Agency's strict driving-time regulations constrain long-haul trucking capacity, redirecting freight volumes toward rail interoperability investments.
- E-commerce fulfillment infrastructure:Parcel locker networks and automated sorting hubs concentrate investment around Stockholm, Gothenburg, and Malmö logistics clusters.
- Carbon pricing differentials:Swedish Environmental Protection Agency carbon dioxide taxation accelerates fleet electrification decisions among domestic carriers serving emission-sensitive shippers.
Market Restraints
- Driver shortage compression:Long-haul trucking faces structural capacity constraints as demographic shifts reduce qualified commercial driver availability.
- Electrification capex burden:Battery-electric freight trucks require terminal charging infrastructure investment that smaller carriers cannot finance.
- Rail network concentration:Green Cargo AB's dominance on Stockholm-Gothenburg electrified routes limits competitive alternatives for carbon-conscious shippers.
Strategic Opportunities
- Øresund corridor integration:Copenhagen-Malmö multimodal infrastructure offers underutilized cross-border pharmaceutical and automotive freight capacity.
- Warehouse automation convergence:Robotic sorting and autonomous vehicle deployment cluster near Stockholm where labor costs justify capital intensity.
- EU ETS scope expansion:Pending inclusion of road transport emissions creates regulatory tailwind for rail freight operators with verified carbon reduction credentials.
Industry Challenges
- Telematics integration complexity:Legacy fleet management systems resist real-time tracking synchronization with automated handling equipment.
- BIS-aligned certification timelines:Electric freight truck type approval delays fleet turnover schedules for carriers awaiting vehicle certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden Freight and Logistics Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Road Freight, Rail Freight, Air Freight, Sea Freight Technology: Telematics, Warehouse Automation, RFID, Blockchain End User: Retail, Manufacturing, Automotive, Pharmaceuticals Distribution Channel: Direct Shipping, Third-Party Logistics, Freight Forwarding, E-commerce |
| Companies Covered | PostNord AB, Kuehne+Nagel, Deutsche Post DHL Group, GEODIS, Green Cargo AB, DSV A/S, DB Schenker, FedEx, A.P. Moller - Maersk, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden Freight and Logistics Market Evolving Landscape
Swedish logistics networks are restructuring around emission verification systems and automated handling technologies that compress throughput costs while satisfying regulatory compliance requirements.
Autonomous mobile robots in warehouse environments are migrating from pilot installations to scaled deployment. Swedish third-party logistics providers near Stockholm logistics clusters adopt robotic sorting systems to offset wage inflation. This technology compression enables 24-hour throughput without shift labor penalties.
EU Green Deal Fit for 55 package mandates progressive emission reductions across member state transport sectors. Swedish national carbon dioxide taxation administered by the Swedish Environmental Protection Agency tightens faster than EU minimums. Domestic carriers serving retail and pharmaceutical verticals accelerate fleet electrification to avoid tax liability accumulation.
Shippers now require emission disclosure documentation as a procurement gate. Contract logistics agreements increasingly specify verified carbon intensity per ton-kilometer. Food and beverage manufacturers in southern Sweden lead this specification shift, disqualifying road carriers without telematics-tracked emission data.
Sweden Freight and Logistics Market Segmentation
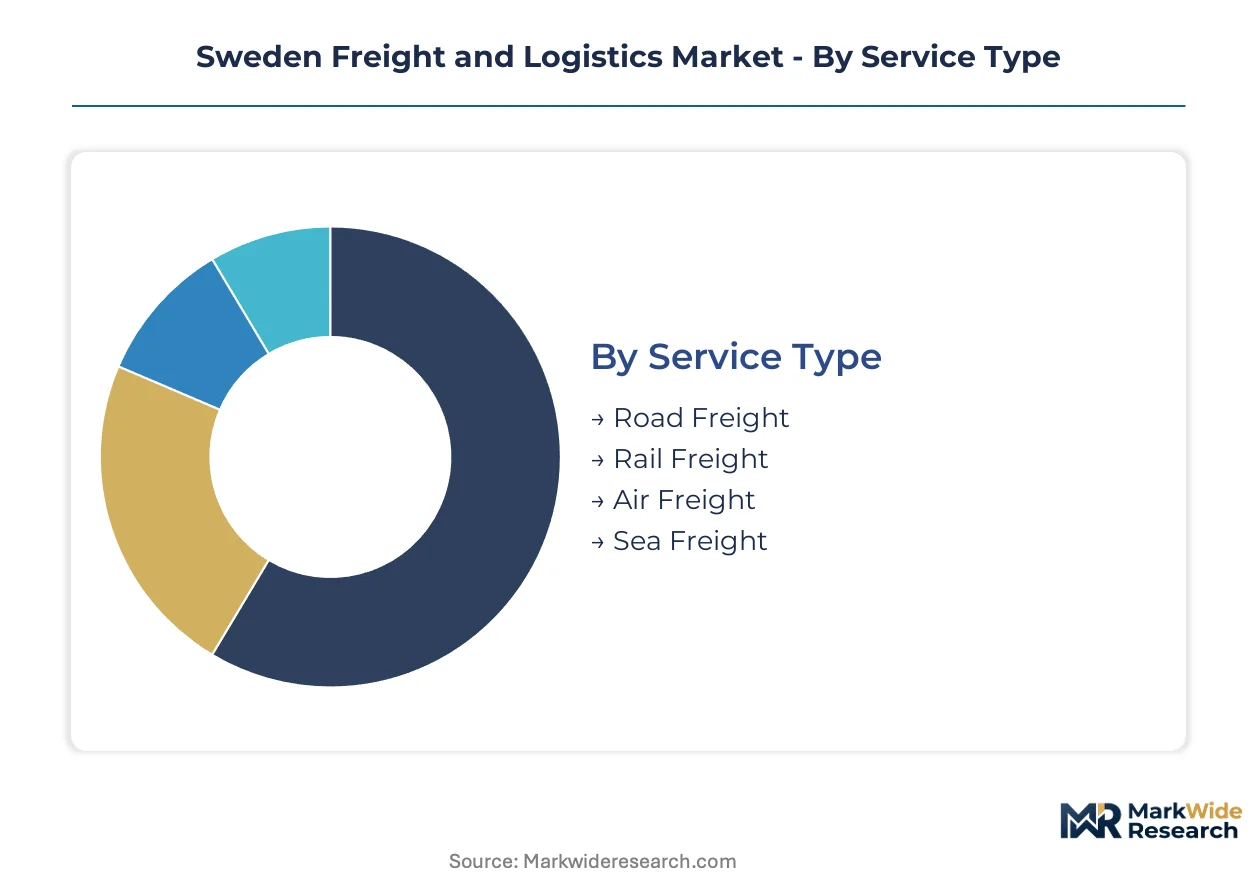
Modal choice and technology deployment determine cost structures across Swedish freight networks. Service differentiation, automation intensity, and end-use specifications each create distinct competitive arenas with diverging margin profiles and capital requirements.
Service Type:
Modal selection captures the fundamental cost-versus-speed trade-off that shippers navigate across Swedish supply chains.
- Road Freight:Flexible routing across Sweden's highway network enables door-to-door delivery without intermodal transfers. Retail replenishment and just-in-time manufacturing flows concentrate demand on Stockholm-Gothenburg corridors where EU Mobility Package driving-time regulations constrain capacity expansion.
- Rail Freight:Electrified track infrastructure delivers verified emission reductions per ton-kilometer for carbon-accounted supply chains. Green Cargo AB dominates Stockholm-Gothenburg routes where pharmaceutical and automotive shippers prioritize Scope 3 compliance over transit speed.
- Air Freight:Time-critical pharmaceutical and high-value electronics shipments utilize Arlanda and Landvetter cargo terminals. Niche positioning reflects premium pricing tolerance for temperature-controlled and security-intensive cargo categories.
- Sea Freight:Container throughput concentrates at Gothenburg port for intercontinental import-export flows. Deep-water access and rail connectivity position the terminal for Scandinavian distribution hub functions.
Road Freight commands the established base. The steepest expansion runs through Rail Freight.
Technology:
Technology adoption depth separates capital-intensive operators from asset-light competitors across Swedish logistics clusters.
- Telematics:Real-time fleet tracking systems enable dynamic route optimization and emission verification documentation. Swedish Transport Agency enforcement of EU Mobility Package regulations accelerates installation mandates for cross-border trucking operators.
- Warehouse Automation:Robotic sorting and autonomous mobile robots compress labor costs in high-throughput facilities. Stockholm logistics clusters justify capital intensity where wage inflation and 24-hour operational requirements converge.
- RFID:Automated inventory tracking reduces handling errors in retail and pharmaceutical distribution centers. Deployment concentrates in sectors where traceability requirements exceed barcode system capabilities.
- Blockchain:Distributed ledger applications secure documentation chains for pharmaceutical cold chain and customs clearance processes. Pilot implementations focus on cross-border Øresund corridor freight where multiple jurisdictional handoffs create verification friction.
Warehouse Automation commands the established base. Telematics gains share fastest as regulatory compliance tightens.
End User:
End-use specifications dictate service level requirements and emission disclosure intensity across Swedish contract logistics.
- Retail:Omnichannel fulfillment networks require parcel locker density and same-day delivery radius coverage. PostNord AB infrastructure investments concentrate around Stockholm, Gothenburg, and Malmö urban zones where e-commerce penetration drives volume concentration.
- Manufacturing:Just-in-sequence delivery schedules synchronize inbound component flows with production line timing. Automotive and electronics producers in western Sweden prioritize reliability metrics over pure cost minimization.
- Automotive:Finished vehicle logistics and component supply chains utilize specialized equipment for high-value cargo handling. Electrification transition shifts component sourcing patterns toward battery supply chain corridors.
- Pharmaceuticals:Temperature-controlled distribution and serialization compliance dominate service specifications. Swedish Environmental Protection Agency carbon taxation accelerates demand for verified cold chain emission documentation.
Retail commands the established base. Pharmaceuticals climbs the fastest on compliance-driven outsourcing.
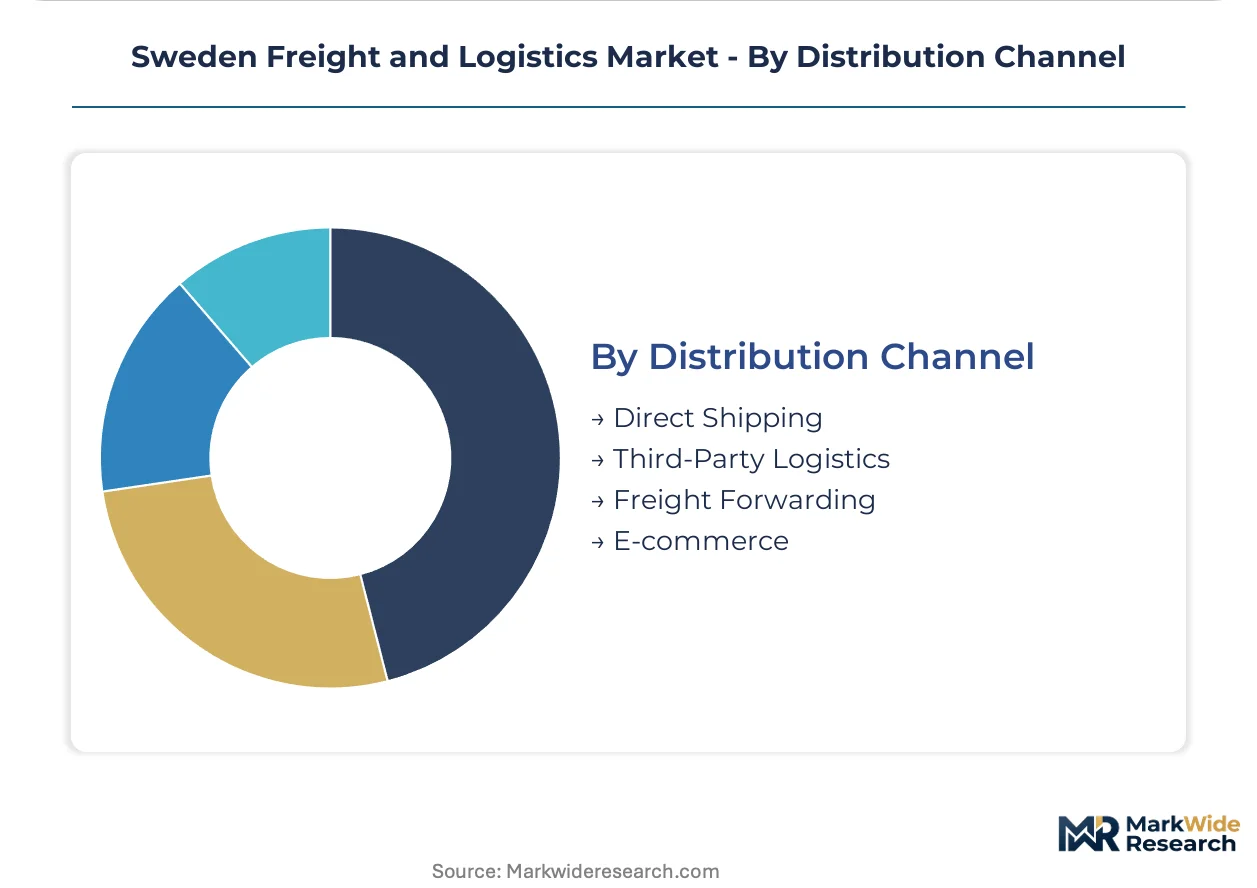
Distribution Channel:
Channel structure determines asset ownership patterns and working capital intensity across Swedish freight intermediation.
- Direct Shipping:Shipper-controlled fleets serve dedicated routes with captive capacity utilization. Large manufacturing verticals in southern Sweden maintain in-house road freight operations where volume density justifies asset ownership.
- Third-Party Logistics:Outsourced warehouse and transportation management enables variable cost scaling. DSV A/S Nordic hub operations capture cross-border pharmaceutical and automotive flows through Copenhagen-Malmø corridor infrastructure.
- Freight Forwarding:Intermodal coordination and customs brokerage services aggregate fragmented shipper demand. Consolidation economics favor mid-sized Swedish exporters lacking direct carrier negotiation scale.
- E-commerce:Parcel locker networks and last-mile density investments dominate fulfillment infrastructure. PostNord AB nationwide locker deployment creates barrier-to-entry for competing last-mile providers.
Third-Party Logistics commands the established base. E-commerce shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shippers in southern Sweden exhibit the highest price elasticity for emission-verified freight, while pharmaceutical manufacturers in Stockholm accept premium pricing for cold chain compliance.
Stockholm
E-commerce fulfillment demand and omnichannel retail distribution dominate freight volumes in the capital region. Swedish Transport Agency enforcement of EU Mobility Package driving-time regulations constrains long-haul trucking capacity expansion. The Stockholm logistics cluster concentrates warehouse automation investment where robotic sorting systems offset wage inflation and enable 24-hour throughput.
Gothenburg
Automotive manufacturing supply chains and intercontinental container imports generate substantial freight demand through western Sweden's primary port. Swedish Environmental Protection Agency carbon dioxide taxation accelerates demand for verified emission documentation among export-oriented shippers. The Gothenburg port terminal leverages deep-water access and rail connectivity to function as a Scandinavian distribution hub for manufacturing verticals.
Malmö
Cross-border pharmaceutical flows and automotive component trade utilize the Øresund corridor's multimodal infrastructure connecting to Copenhagen. EU Green Deal Fit for 55 package mandates compress margins for road freight while electrified rail corridors capture modal shift. The Copenhagen-Malmö logistics zone serves as the critical gateway for Scandinavian trade flows accessing continental European markets.
Linköping-Norrköping Corridor
Manufacturing just-in-sequence delivery requirements and food processing distribution sustain freight demand in the southern central region. National carbon pricing administered by the Swedish Environmental Protection Agency drives fleet electrification decisions among regional carriers. The Linköping-Norrköping industrial zone anchors specialized temperature-controlled distribution for food and beverage manufacturers with emission disclosure requirements.
Sweden Freight and Logistics Market Competitive Landscape
Capability concentration sits with integrated rail-road operators; scale advantage sits with international freight forwarding networks. The Sweden freight and logistics market structures around three tiers: domestic parcel specialists with locker infrastructure, Nordic hub operators with cross-border consolidation expertise, and global integrators with intercontinental reach. Dominant competitive moves include terminal infrastructure investment along electrified corridors and strategic partnerships for last-mile density expansion.
Within the domestic specialist tier, PostNord AB and Green Cargo AB exemplify divergent capability emphases. PostNord AB represents the parcel locker density archetype that creates barrier-to-entry for competing last-mile providers. Green Cargo AB occupies a position as the electrified rail freight specialist on Stockholm-Gothenburg corridors. Among international forwarders, DSV A/S anchors Nordic hub operations through Copenhagen-Malmö corridor infrastructure.
| Leading Market Players |
|---|
| PostNord AB |
| Kuehne+Nagel |
| Deutsche Post DHL Group |
| GEODIS |
| Green Cargo AB |
| DSV A/S |
| DB Schenker |
| FedEx |
| A.P. Moller - Maersk |
| Others |
Value Network & Pricing Analysis
German automotive component suppliers and Chinese electric drivetrain manufacturers anchor upstream concentration in Swedish freight networks, directing margin pools toward last-mile integrators with parcel locker density and rail operators with verified emission credentials.
Pricing Analysis
After-sales service contracts and extended logistics agreements drive lifetime value for Swedish third-party logistics providers. Contract-based long-term offtake structures dominate enterprise relationships, with price differentiation hinging on emission verification grade and geographic delivery radius. Pricing pressure stems from EU Green Deal compliance costs compressing road freight margins, while pharmaceutical shippers exhibit lowest price sensitivity due to cold chain compliance requirements.
Supply Chain Analysis
Supplier-financing facilities and extended payment terms from German chassis manufacturers and Chinese battery suppliers sustain working capital for Swedish fleet operators. Component sourcing draws from Germany, China, and Poland for electric freight vehicle assembly. Single-source vulnerability concentrates in battery cell supply, while distribution runs through Stockholm-Gothenburg-Malmö logistics clusters with Øresund corridor cross-border connectivity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
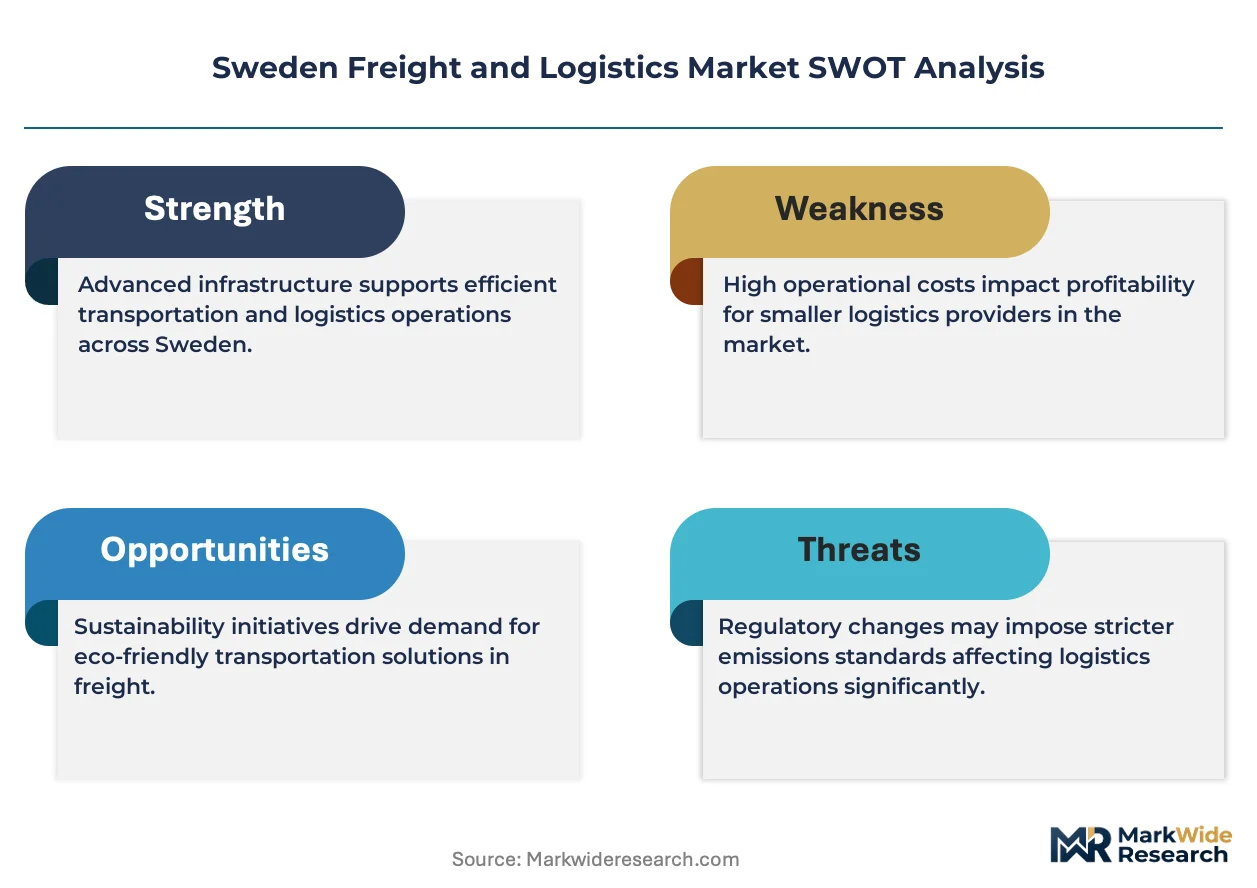
Swedish freight and logistics functions as a high-growth disruption where EU ETS scope expansion and warehouse automation convergence create structural inflection points for capital deployment and competitive repositioning.
For Market Incumbents: Insulate terminal infrastructure investments along Stockholm-Gothenburg electrified corridors against margin compression from carbon taxation. Prioritize backward integration into parcel locker networks to defend density advantages against emerging last-mile specialists. Certification investment in BIS-aligned electric vehicle standards protects fleet turnover timelines from regulatory delay risk. For New Entrants and Emerging Players: Build out temperature-controlled pharmaceutical distribution capacity in the Linköping-Norrköping corridor where emission disclosure requirements outpace incumbent service levels. Target food and beverage manufacturers with verified cold chain documentation as the most penetrable segment. Go-to-market positioning centers on telematics-integrated emission tracking as a procurement gate enabler. For Investors and Strategic Acquirers: Capital is best deployed toward electrified rail-road operators with Scope 3 compliance credentials and warehouse automation specialists serving Stockholm logistics clusters. Long-term viability across the analysis window favors assets with regulatory tailwinds from EU ETS expansion. The signal to watch is Swedish Transport Agency enforcement intensity on EU Mobility Package driving-time regulations as a capacity constraint indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Electrified Corridor Infrastructure Investment | Green Cargo AB's Stockholm-Gothenburg route expansion captures carbon-accounted pharmaceutical flows. |
| Parcel Locker Network Density Expansion | PostNord AB's nationwide deployment creates barrier-to-entry against competing last-mile providers. |
| Telematics Integration Partnership | Real-time emission verification satisfies Swedish Environmental Protection Agency documentation requirements. |
| Warehouse Automation Scale-Up | Robotic sorting deployment near Stockholm offsets wage inflation and enables 24-hour throughput. |
| Øresund Corridor Multimodal Agreement | Copenhagen-Malmö infrastructure access unlocks cross-border pharmaceutical and automotive consolidation economics. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet operations directors, warehouse automation engineers, pharmaceutical logistics managers, and rail corridor planners. Secondary validation incorporated Swedish Transport Agency regulatory filings, EU ETS scope expansion documentation, customs trade data through Gothenburg port authorities, and SEC disclosures from listed Nordic logistics operators. Bottom-up segment sizing and top-down macroeconomic calibration ensured triangulation integrity.
Calibration against historical ton-kilometer growth patterns and modal shift trajectories anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, technology deployment depth, end-use vertical specifications, and regional logistics cluster concentration. CAGRs were derived from elasticity-adjusted volume projections incorporating fleet electrification capex cycles and carbon pricing differential assumptions.
Stress conditions across EU ETS implementation timelines, battery supply disruption scenarios, and driver shortage intensification were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory enforcement consistency and technology adoption curves. Macroeconomic contraction, accelerated road pricing reforms, or breakthrough autonomous vehicle deployment would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Airfreight Forwarding Market
Logistics and Shipping
Chile Freight and Logistics Market
Logistics and Shipping
Inbound Logistics Market
Logistics and Shipping
Chemical Tanker Shipping Market
Logistics and Shipping
France Last Mile Delivery Market
Logistics and Shipping
Latin America Fourth Party Logistics (4PL) Market
Logistics and Shipping
Vietnam Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
ASEAN Warehousing and Distribution Logistics Market
Logistics and Shipping
Italy Courier Market
Logistics and Shipping
New Zealand Freight and Logistics Market
Logistics and Shipping
On-Demand Logistics Market
Logistics and Shipping
Autonomous Last Mile Delivery Market
Logistics and Shipping
Oman Third-Party Logistics (3PL) Market
Logistics and Shipping
Repositioning and Offloading Market
Logistics and Shipping
United Kingdom Freight and Logistics Market
Logistics and Shipping
Cross-Border Logistics Services Market