
 Car Carrier Market | 2026-2036
Car Carrier Market Size, Share, and Industry Trends Forecast 2026-2036
Car Carrier Market Intelligence
A consolidation among large-scale vehicle distributors and dealership networks is realigning service provider relationships. This shift favors carriers with extensive national coverage. Montway Auto Transport leverages a vast network to serve this concentrated customer base. In contrast, uShip operates an online platform connecting carriers with a more fragmented base of individual movers and small businesses.
A car carrier is a specialized vehicle or vessel designed for transporting passenger vehicles. These carriers, such as multi-car trucks, often feature hydraulic ramps and adjustable decks to maximize load capacity while ensuring vehicle security. The primary purpose is the efficient movement of automobiles from production sites to dealerships. Roll-on Roll-off vessels and multi-car trucks dominate the transport type segment, while vehicle distributors represent the largest customer type.
Operational standards are shaped by entities like the US Department of Transportation and the European Agreement concerning the International Carriage of Dangerous Goods by Road (ADR). These regulations govern driver hours, vehicle weight limits, and the transport of electric vehicles, impacting logistics planning. Compliance with ISO quality management standards also influences carrier selection by major automakers. Carrier choice will hinge on demonstrated adherence to emissions standards and EV handling certifications.
Market Dynamics
The global transition to electric vehicles (EVs) is the central structural force shaping the car carrier market. This shift imposes new logistical complexities and stringent regulatory requirements related to battery transport, fundamentally altering carrier operational standards and investment priorities.
Growth Catalysts
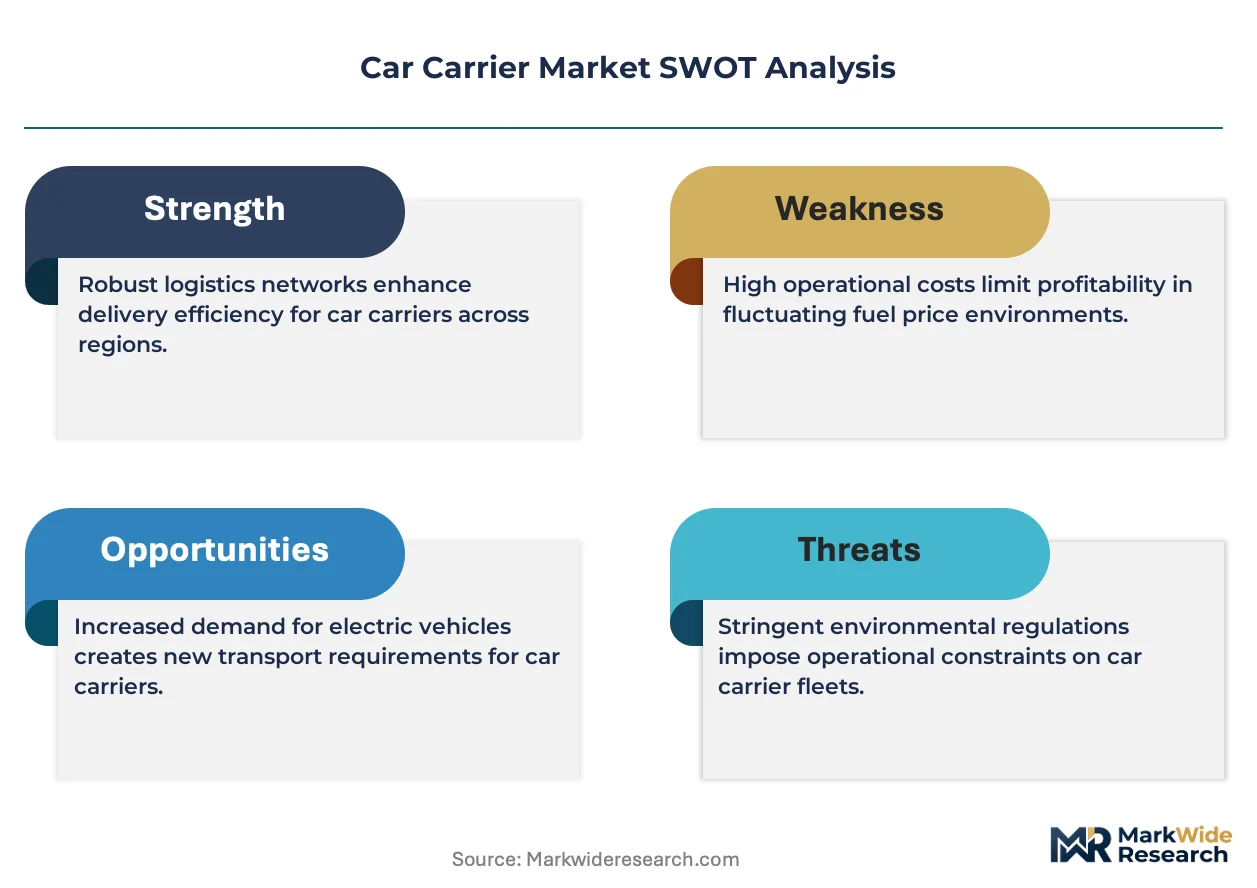
- Expanding EV Production:The rising manufacturing output of electric vehicles necessitates specialized logistics services. Carriers must adhere to battery transport regulations, such as the EU's ADR framework, to handle these vehicles, creating demand for certified providers.
- Automotive Export Growth:China's expanding role as a major vehicle exporter, particularly to markets in Europe and Southeast Asia, drives sustained volume for both Roll-on/Roll-off (Ro-Ro) vessels and terrestrial multi-car haulers.
- Dealer Network Consolidation:The trend of large automotive dealership groups acquiring smaller entities favors carriers with extensive national or regional coverage. These consolidated buyers prefer single-source logistics partners capable of serving a broad geographic footprint.
Market Restraints
- Persistent Driver Shortages:A chronic lack of qualified commercial truck drivers, especially in North America and Europe, inflates labor costs for carriers. This scarcity directly constrains fleet capacity and limits the ability to meet peak demand surges.
- Fuel Price Volatility:Unpredictable fluctuations in diesel and marine fuel prices directly impact carrier operating margins. This instability poses a significant financial risk, particularly for smaller operators lacking sophisticated fuel hedging strategies or surcharge mechanisms.
- Infrastructure Bottlenecks:Congestion at major ports and inadequate road infrastructure in key trade corridors create significant delays. These bottlenecks disrupt tightly scheduled delivery timelines and increase overall transit costs for vehicle distributors.
Strategic Opportunities
- Specialized EV Logistics Services:Developing certified handling procedures and dedicated fleets for electric vehicles presents a high-margin opportunity. This includes services for battery state-of-charge management and compliance with transport rules like those from the US EPA.
- Digital Freight Matching Platforms:The adoption of digital brokerage platforms allows carriers to optimize routing, reduce empty miles, and improve asset utilization. This technology offers small and mid-sized carriers better access to a fragmented customer base.
- South American Market Development:Growing automotive production in countries like Brazil and Mexico offers an underpenetrated market for specialized car carrier services. Cross-border logistics between these manufacturing hubs and consumer markets is a key growth area.
Industry Challenges
- Emissions Standards Compliance:Adhering to evolving emissions regulations, such as the EU's Euro standards or the EPA's GHG rules, requires significant capital investment in new, compliant trucks, which strains fleet modernization budgets.
- High Capital Investment:The substantial cost of acquiring and maintaining specialized assets like multi-level car haulers and Ro-Ro vessels creates a high barrier to entry and pressures the financial resources of existing operators.
- EV Handling Certification:A skills gap exists for safely handling electric vehicles, particularly concerning lithium-ion battery fire risks. Carriers face the challenge of investing in new training and certification programs for drivers and terminal staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Carrier Market |
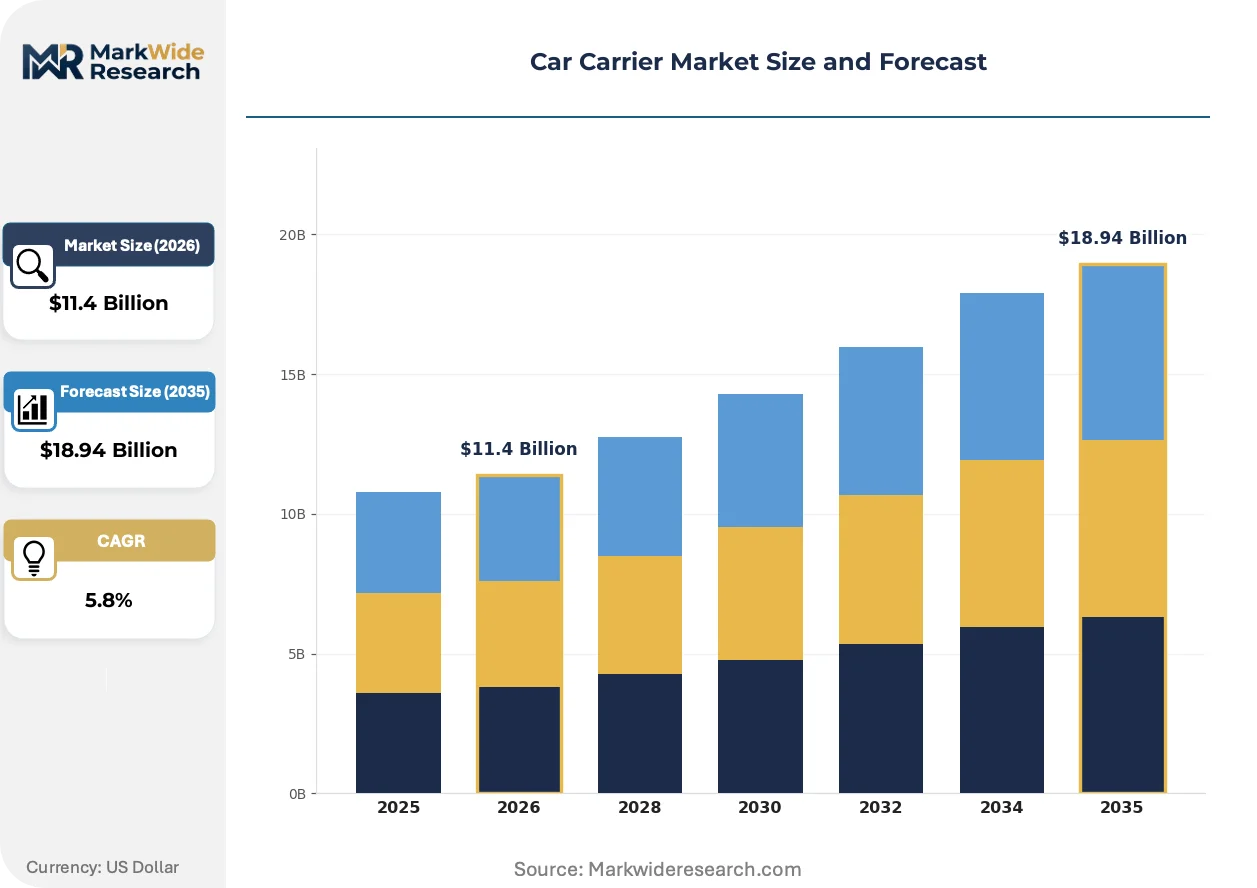
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $18.94 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Transport Type: Roll-on Roll-off, Flatbed Truck, Enclosed Trailer, Rail Freight, Sea Freight Load Capacity: Single Car, Multi-Car, Heavy Load, Light Load, Modular Load Customer Type: Vehicle Distributors, Leasing Companies, Dealerships, Vehicle Assemblers, Exporters Distribution Channel: Direct Sales, Fleet Management, Third-Party Logistics, Online Platforms, Auctions |
| Companies Covered | SGT Auto Transport, Sherpa Auto Transport, Navi Auto Transport, Ship A Car Direct, Mercury Auto Transport, Montway Auto Transport, AmeriFreight, uShip, Nexus Auto Transport, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Carrier Market Strategic Shifts & Innovations
The evolution toward digitally integrated and sustainable logistics is fundamentally altering car carrier operations. This transformation is driven by advancements in fleet management technology, stricter environmental mandates, and changing procurement behaviors among vehicle distributors and shippers.
Telematics and onboard diagnostics systems represent a critical technological layer, providing real-time data on vehicle location, driver performance, and powertrain health. Large-scale vehicle distributors and fleet operators are rapidly adopting these systems to gain visibility into their supply chains. This data-driven capability is converging with AI-powered route optimization software to dynamically adjust schedules, minimize fuel consumption, and enable predictive maintenance, thereby improving overall asset efficiency.
Regulatory frameworks are tightening around the transport of alternative fuel vehicles. The European Agreement concerning the International Carriage of Dangerous Goods by Road (ADR) now includes specific provisions for lithium-ion batteries. This rule forces carriers to implement specialized handling, labeling, and training protocols for electric vehicles. The finished vehicle logistics segment is most affected, compelling operators to invest in ADR compliance to serve automakers in the European market.
A notable behavioral shift is occurring as shippers move from fixed, long-term contracts toward more flexible, on-demand logistics procurement. This change disrupts the traditional model where automakers relied on a small group of preferred carriers for dedicated capacity. This dynamic is most prominent in the North American market, where digital freight platforms enable shippers to access a broader, more fragmented carrier base for single or low-volume vehicle movements.
Car Carrier Market Segmentation
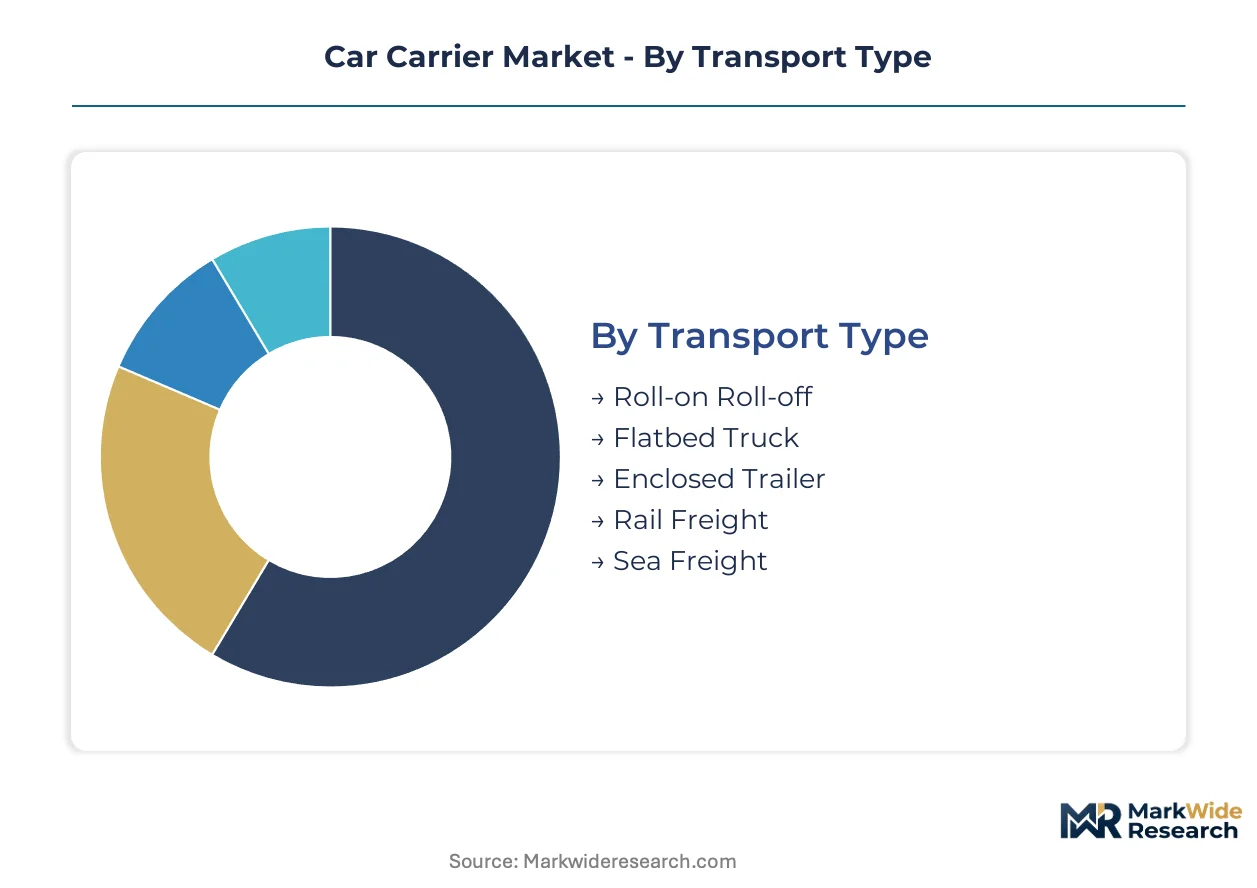
The car carrier market's segmentation provides a detailed lens into the diverse operational requirements and distinct customer needs across the vehicle logistics ecosystem. Understanding these segments is crucial for carriers to align their specialized services and asset investments with prevailing demand patterns.
Transport Type:
The car carrier market's transport type segmentation reflects ongoing investments in specialized vehicle fleets and infrastructure upgrades.
- Roll-on Roll-off:These specialized vessels efficiently move large volumes of finished vehicles across oceans. Demand concentrates in global trade lanes, particularly between Asian manufacturing hubs and European consumer markets.
- Multi-Car Truck:Multi-car trucks, often featuring hydraulic ramps and adjustable decks, optimize terrestrial vehicle movement. Consolidation among dealership networks in the US drives demand for these high-capacity overland solutions.
- Flatbed Truck:Standard flatbed trucks provide flexible transport for various vehicle types, often for shorter distances or specialized loads.
- Enclosed Trailer:Enclosed trailers offer enhanced protection for luxury or classic vehicles, ensuring pristine delivery conditions.
- Rail Freight:Rail transport moves high volumes of vehicles over long distances, connecting major production centers to distribution hubs in countries like Canada.
- Sea Freight:This category includes various non-RoRo vessel types for international vehicle shipments, supporting global automotive supply chains, often for containerized or project cargo.
Roll-on Roll-off sits at the top of the volume ranking, with Enclosed Trailer climbing the fastest.
Load Capacity:
Load capacity segmentation reveals how carriers adapt their assets to varying vehicle sizes and shipment volumes.
- Multi-Car:Multi-car carriers, including specialized trucks and railcars, transport multiple vehicles simultaneously. Demand is driven by large-scale dealership deliveries and factory-to-port movements in countries like Germany.
- Heavy Load:Heavy load carriers manage oversized or specialized vehicles like trucks and construction equipment. Regulations in the United States often influence the design and operation of these heavy transport units.
- Single Car:Single car transport caters to individual vehicle movements, often for luxury cars or personal relocations.
- Light Load:Light load capacity focuses on smaller passenger vehicles or motorcycles, optimizing fuel efficiency for lighter hauls.
- Modular Load:Modular load systems allow flexible configuration of carrier space, accommodating diverse vehicle dimensions efficiently.
Multi-Car transport represents the largest segment by volume, while Modular Load capacity offers increasing flexibility for diverse vehicle types.
Customer Type:
Customer type segmentation highlights the distinct procurement behaviors and service expectations of various automotive industry stakeholders.
- Vehicle Distributors:These large entities manage the flow of new vehicles from manufacturers to dealership networks. Their consolidated purchasing power in the US influences carrier selection and service level agreements.
- Vehicle Assemblers:Automakers rely on car carriers to move finished vehicles from assembly plants to distribution centers or ports. Production shifts in Mexico directly impact demand from this customer group.
- Leasing Companies:Leasing companies require efficient transport for vehicle fleet rotations and end-of-lease returns.
- Dealerships:Individual dealerships utilize carriers for inventory replenishment and inter-dealership transfers.
- Exporters:Exporters coordinate international vehicle shipments, navigating complex customs and logistics requirements.
Vehicle Distributors account for the largest share of transport demand, with Exporters showing significant growth due to global trade expansion.
Distribution Channel:
Distribution channel segmentation outlines the various pathways through which car carrier services are procured and managed.
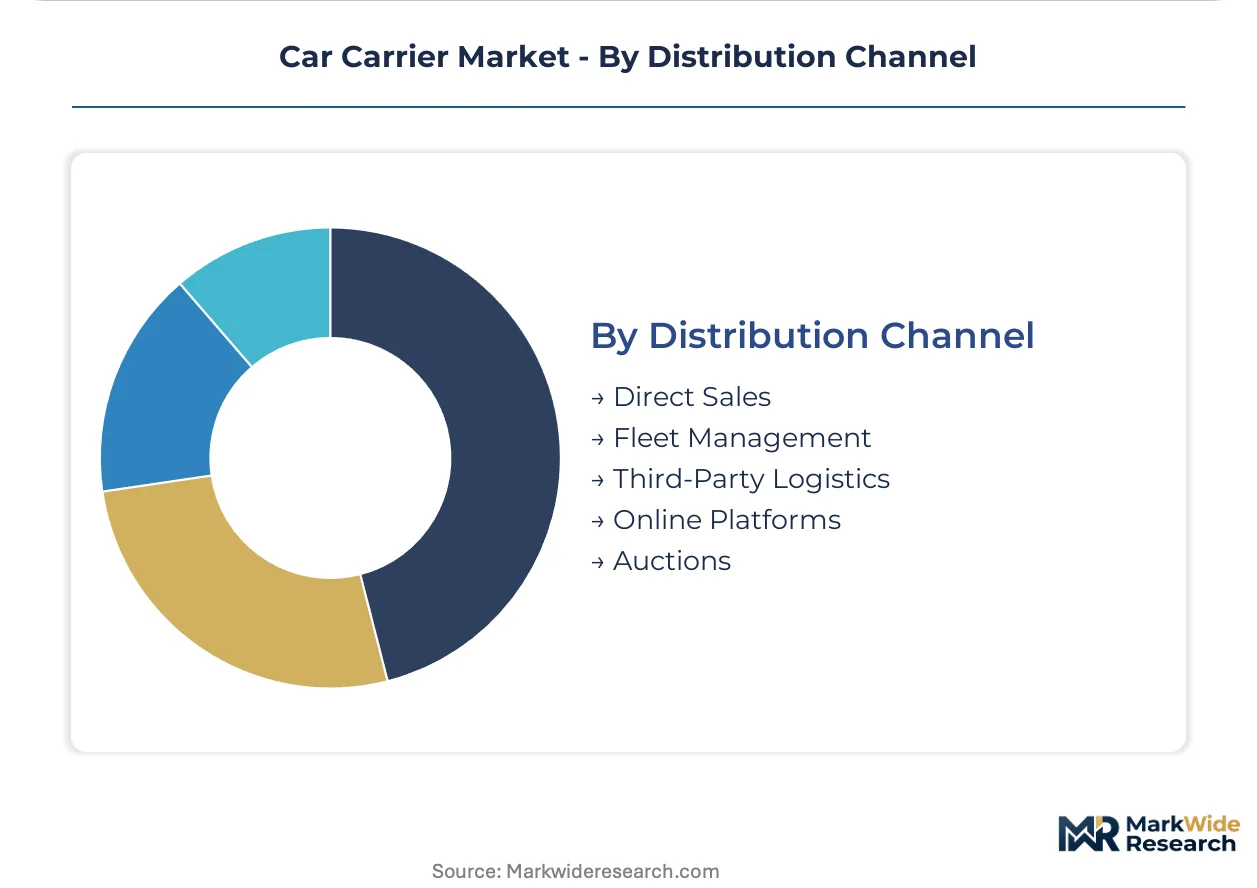
- Third-Party Logistics:3PL providers manage complex logistics operations, integrating car transport into broader supply chain solutions. Automakers in Europe increasingly rely on these specialists for efficiency.
- Online Platforms:Digital brokerage platforms connect shippers directly with available carriers, optimizing route efficiency and asset utilization. This channel is gaining traction for fragmented demand in Canada.
- Direct Sales:Direct sales involve direct contracting between large shippers and car carrier companies for dedicated services.
- Fleet Management:Fleet management services oversee the transport needs for corporate or rental car fleets, ensuring timely vehicle movements.
- Auctions:Car auctions generate demand for transport services to move purchased vehicles to new owners or dealerships.
Third-Party Logistics dominates the channel landscape for large-scale operations, while Online Platforms are rapidly expanding their reach among smaller shippers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's expanding automotive export activities fuel significant demand for car carrier services, contrasting with the United States where dealership network consolidation drives demand for extensive national coverage. Global vehicle logistics operations are adapting to diverse market dynamics shaped by local regulations and industrial concentration. This regional variation influences carrier investment in specialized fleets and digital platforms.
China
China's expanding automotive production, particularly for electric vehicles, generates substantial demand for both domestic and international car transport. The Ministry of Ecology and Environment (MEE) regulations on vehicle emissions and transport safety influence carrier operational standards. Major ports like Shanghai and Tianjin serve as critical hubs for Roll-on/Roll-off vessel movements to European and Southeast Asian markets.
Germany
Germany's robust automotive manufacturing sector, including a strong EV production base, creates consistent demand for multi-car transport to dealerships across Europe. The European Agreement concerning the International Carriage of Dangerous Goods by Road (ADR) dictates stringent battery transport regulations for EV logistics. The Stuttgart region, home to major automakers, requires efficient finished vehicle logistics to distribution centers.
United States
The United States car carrier market is characterized by significant demand from consolidated vehicle distributors and a growing need for EV logistics. The US Department of Transportation (DOT) regulates driver hours and vehicle weight limits, impacting fleet operations. Major automotive distribution centers in states like Michigan and California concentrate inbound and outbound vehicle movements.
Mexico
Mexico's role as a major automotive production hub, with significant exports to North American markets, drives demand for cross-border car carrier services. The Mexican Secretariat of Communications and Transportation (SCT) oversees transport regulations and infrastructure development. Manufacturing clusters in states like Nuevo León and Guanajuato require high-volume transport solutions to ports and border crossings.
Canada
Canada's car carrier market sees demand from a fragmented base of individual movers and a growing reliance on digital freight platforms. Transport Canada regulations govern vehicle safety standards and cross-provincial transport. The Greater Toronto Area, a major population and distribution center, generates consistent demand for both inter-provincial and cross-border vehicle movements.
Car Carrier Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a dynamic market structure. The car carrier market exhibits a tiered competitive landscape, with large carriers offering extensive national coverage alongside niche players serving specific segments. Strategic archetypes include asset-heavy fleet operators, technology-driven brokerage platforms, and specialized EV logistics providers. Dominant competitive moves involve geographic expansion and technology integration to optimize asset utilization.
Specialists in digital freight matching platforms, such as uShip, exemplify the technology-driven segment, connecting a fragmented customer base with carriers. Montway Auto Transport, operating a vast network, represents large-scale carriers with extensive national coverage, serving consolidated vehicle distributors. SGT Auto Transport occupies a position among the established asset-light brokers, facilitating diverse vehicle movements across the United States.
| Leading Market Players |
|---|
| SGT Auto Transport |
| Sherpa Auto Transport |
| Navi Auto Transport |
| Ship A Car Direct |
| Mercury Auto Transport |
| Montway Auto Transport |
| AmeriFreight |
| uShip |
| Nexus Auto Transport |
| Others |
Cost & Logistics Intelligence
The specialized EV handling certification divergence creates distinct pricing tiers and mandates specific supply chain configurations for compliant carriers. This certification directly influences service rates and the investment required for specialized equipment and training.
Pricing Analysis
Capacity additions in China are reshaping price floors for high-volume Roll-on/Roll-off vessel movements. The dominant pricing model involves contract-based long-term offtake for major vehicle distributors, while transactional spot rates serve fragmented demand. Price differentiation stems from specialized EV handling certification levels and the complexity of cross-border logistics. Individual movers accessing online platforms exhibit the highest price sensitivity, contrasting with large vehicle distributors who prioritize service reliability despite fuel price volatility.
Supply Chain Analysis
Dual-sourcing requirements for specialized Roll-on/Roll-off vessel capacity mitigate risk for major automakers. Supply chain concentration centers on manufacturing hubs in China, Germany, and Mexico, which rely on stable access to diesel and marine fuels. Infrastructure bottlenecks at major ports and key trade corridors present a significant structural risk. Distribution runs through third-party logistics providers and direct contracts with large vehicle distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The car carrier market functions as a stable compounder, driven by the sustained global expansion of automotive production and export activities. This consistent volume underpins predictable, long-term growth for specialized logistics providers.
For Market Incumbents: Extend national coverage and invest in EV handling certifications to defend market share against emerging digital platforms. Consolidate relationships with large vehicle distributors by offering integrated logistics solutions across diverse geographies. This strategy addresses the threat of fragmented digital freight platforms and leverages technology integration for optimized asset utilization. Incumbents should prioritize compliance with regulations like the EU's ADR framework.
For New Entrants and Emerging Players: Online digital freight matching platforms offer a direct route to fragmented customer bases. Target specialized EV logistics services, particularly for new EV production in countries like Mexico. The individual movers and small businesses segment remains highly penetrable through efficient digital brokerage. Offer certified EV transport solutions with transparent pricing to gain market traction.
For Investors and Strategic Acquirers: Consolidation pressure builds where extensive national coverage and specialized asset bases are critical for profitability. The market offers long-term viability due to sustained demand for specialized vehicle transport. Target mid-sized carriers with strong regional networks or proven EV handling expertise, particularly those compliant with ADR or US EPA battery transport rules. Regulatory harmonization for EV transport standards across major trade blocs is a signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in EV Fleet Modernization | Ensures compliance with emissions standards and specialized EV handling certifications. |
| Expand Digital Freight Matching Capabilities | Optimizes routing, reduces empty miles, and improves asset utilization for carriers. |
| Develop South American Market Presence | Captures growing automotive production volumes in countries like Brazil and Mexico. |
| Pursue Strategic Partnerships with 3PLs | Integrates car transport into broader supply chain solutions for automakers in Europe. |
| Implement Advanced Telematics and AI for Operations | Provides real-time data for predictive maintenance and dynamic route optimization, enhancing efficiency. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region. This approach combined in-depth primary interviews with vehicle distributors, fleet operators, logistics managers, and regulatory compliance officers, validated by extensive secondary research. Secondary sources included US DOT reports, EU ADR framework documents, automotive production databases, and port authority statistics. Bottom-up data aggregation and top-down market sizing provided robust triangulation.
Market dimensions were modeled at granular levels across transport type, load capacity, customer type, and distribution channel. The analytical framework involved quantitative modeling across the projection horizon, incorporating vehicle propulsion type as a key dimension. Compound annual growth rates were derived from historical growth patterns and future demand projections. Global EV production forecasts and automotive export volumes served as critical inputs.
The model assumes a particular technology adoption path; alternative pathways for autonomous trucking would alter the outlook. Forecasts reflect current regulatory frameworks and expected economic conditions. Deviation in geopolitical trade policies would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Europe less-Than Container Load Market
Logistics and Shipping
Liquid Chemical Tanker Shipping Market
Logistics and Shipping
Nordics Freight and Logistics Market
Logistics and Shipping
Sweden Courier, Express, and Parcel Market
Logistics and Shipping
Asean Freight and Logistics Market
Logistics and Shipping
North America Refrigerated Container Shipping Market
Logistics and Shipping
GCC Automotive Logistics Market
Logistics and Shipping
China less than-Truck-Load (LTL) Market
Logistics and Shipping
Hong Kong Container Transshipment Market
Logistics and Shipping
Saudi Arabia Freight and Logistics Market
Logistics and Shipping
GCC Air Freight and Logistics Market
Logistics and Shipping
Repositioning and Offloading Market
Logistics and Shipping
Italy Courier Market
Logistics and Shipping
Cargo Shipping Market
Logistics and Shipping
Indonesia Freight and Logistics Market
Logistics and Shipping
Fine Art Logistics Market