
 Mainframe Market | 2026-2036
Mainframe Market Size, Share, and Industry Trends Forecast 2026-2036
Mainframe Market Intelligence
Modular hardware bundling with integrated software layers is restructuring buyer choice in the mainframe ecosystem. IBM Corporation leverages its zSystems architecture to sustain technology leadership in encrypted transaction processing. Kyndryl anchors the aftermarket through its infrastructure management and managed services portfolio. HCLTech competes via specialized mainframe modernization labs that extend legacy codebases into API-accessible environments.
A mainframe denotes a high-performance, fault-tolerant computer system engineered for simultaneous transactional throughput exceeding tens of thousands of operations per second, typically employing redundant processor complexes and hardware-level encryption for mission-critical workloads. Enterprise systems remain the dominant product configuration, though hybrid systems connecting on-premises cores to cloud orchestration layers capture the fastest expansion trajectory as banks pursue incremental modernization without full rip-and-replace programs. Transaction processing applications command the largest installed base, while analytics workloads represent the emerging margin pool as financial institutions deploy machine learning inference directly on resident data volumes.
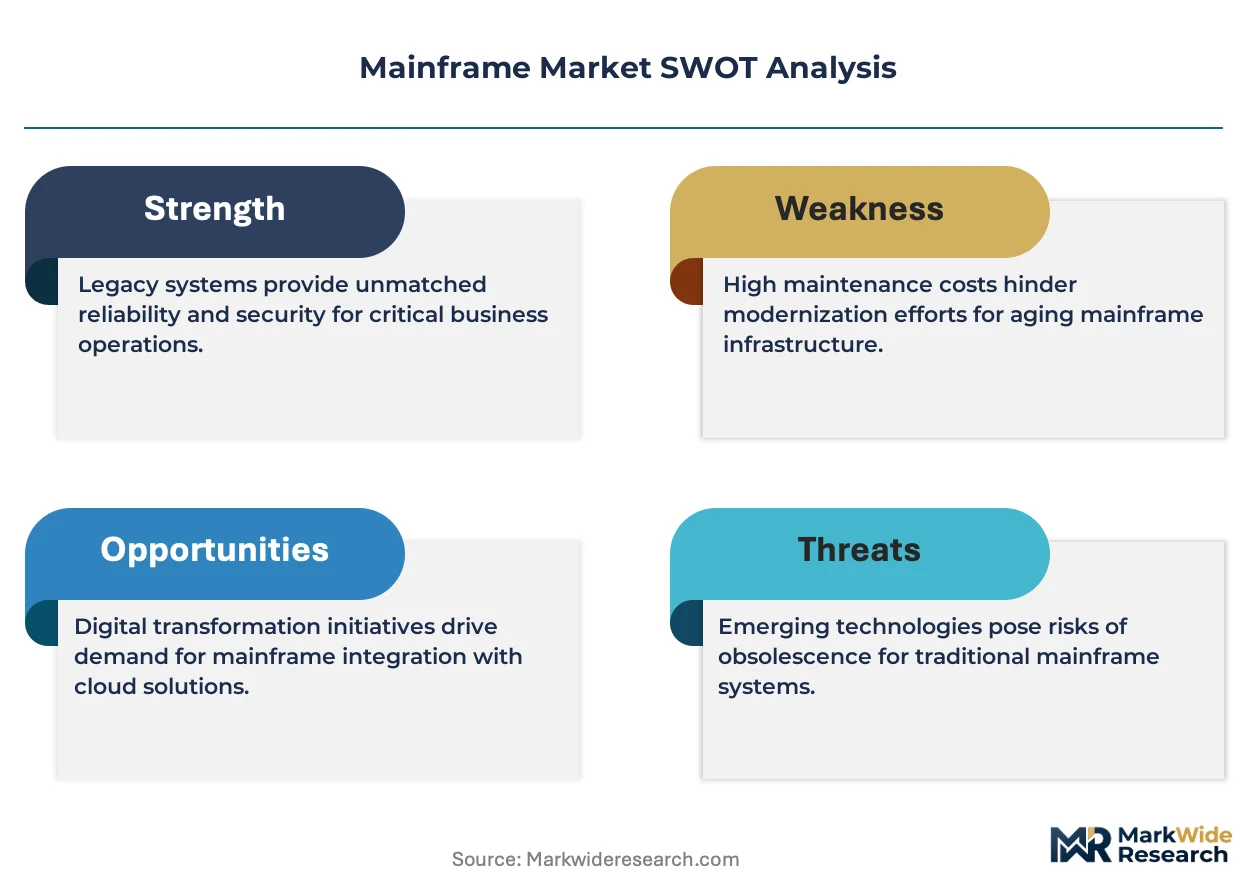
Financial regulators including the Federal Reserve, the European Banking Authority, and Japan's Financial Services Agency impose operational resilience mandates that directly sustain mainframe refresh cycles through strict uptime and auditability requirements. NIST frameworks and the EU's Digital Operational Resilience Act shape product standards by mandating encryption strength, access logging, and disaster recovery protocols that incumbent architectures satisfy more readily than distributed alternatives. Stakeholders must monitor whether central bank digital currency pilots will force architectural decisions that favor or displace traditional mainframe settlement engines.
Market Dynamics
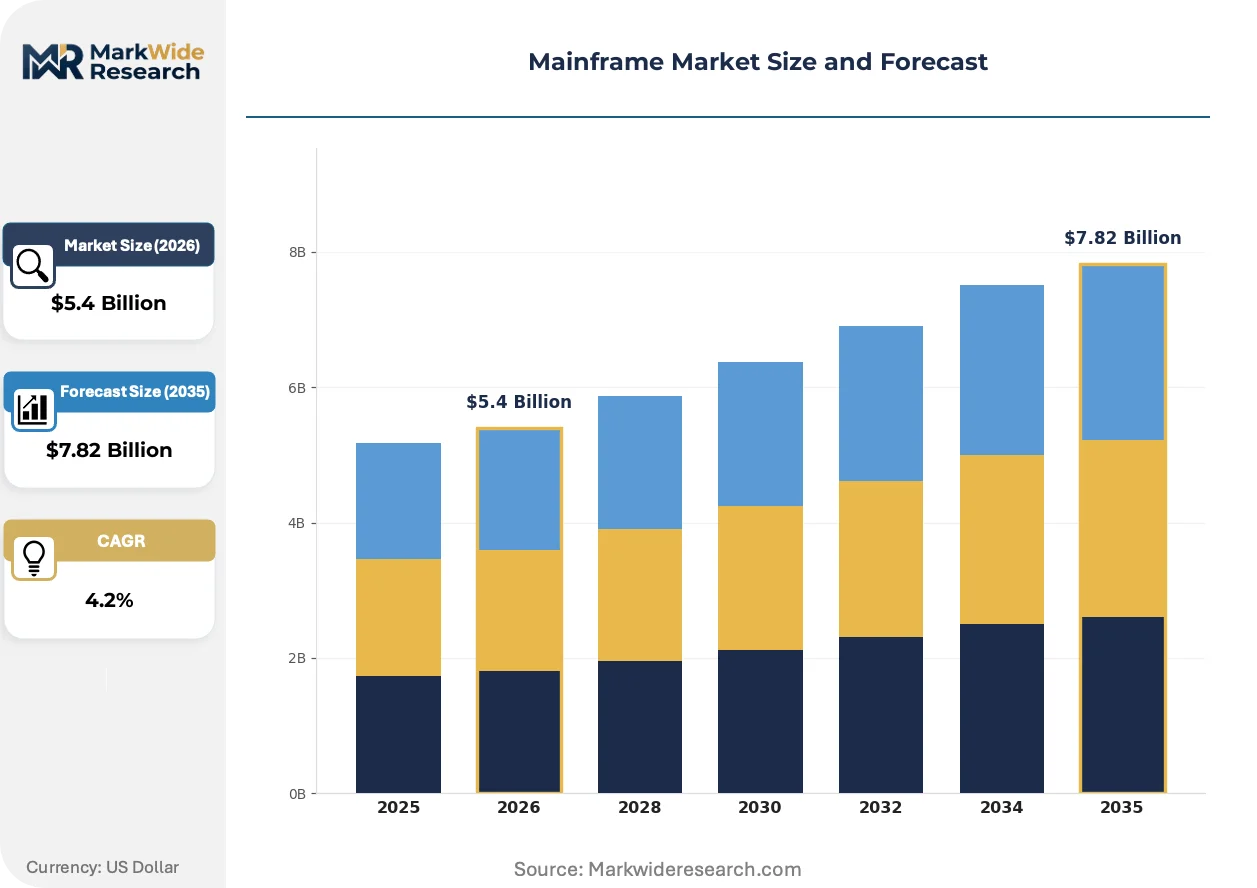
Financial regulators in the United States, European Union, and Japan are mandating operational resilience standards that preserve mainframe refresh cycles through strict uptime and auditability requirements, creating structural demand insulation against distributed alternatives.
Growth Catalysts
- NIST Cybersecurity Framework:United States federal agencies require hardware-level encryption and access logging that incumbent mainframe architectures satisfy more readily than cloud-native alternatives.
- High-volume transaction processing:Financial services institutions in Germany and Japan continue expanding mainframe capacity for core banking infrastructure modernization without full system replacement.
- EU Digital Operational Resilience Act:European Banking Authority mandates directly sustain hardware refresh cycles through disaster recovery protocol requirements that favor fault-tolerant redundant processor complexes.
Market Restraints
- Specialized workforce scarcity:COBOL and assembly language expertise concentrates among aging demographics in the United States and Japan, constraining operational scaling.
- Input cost concentration:Advanced semiconductor packaging for zSystems-class processors depends on TSMC and Samsung foundry capacity in Taiwan and South Korea.
- Cloud substitution pressure:Distributed ledger infrastructure and containerized settlement engines present viable alternatives for lower-latency workloads.
Strategic Opportunities
- India's banking modernization:Reserve Bank of India guidelines for payment system resilience create procurement windows for hybrid mainframe-cloud configurations in Mumbai and Bangalore.
- Machine learning inference on resident data:Analytics workloads directly on encrypted mainframe volumes unlock margin pools in fraud detection and real-time risk scoring.
- API-accessible legacy codebases:Specialized modernization labs convert monolithic transaction processing into microservices-accessible environments without full migration.
Industry Challenges
- Integration complexity:Hybrid systems connecting on-premises cores to cloud orchestration layers require middleware expertise that sits outside traditional mainframe operations.
- Compliance timeline compression:Central bank digital currency pilots in multiple jurisdictions force architectural decisions before settlement engine specifications stabilize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mainframe Market |
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $7.82 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enterprise Systems, Cloud Models, Hybrid Systems, Virtualized Servers Application: Transaction Processing, Data Storage, Batch Processing, Analytics End User: Financial Services, Healthcare Institutions, Government Agencies, Retail Outlets Service Type: Consulting, Maintenance, Integration, Support Services |
| Companies Covered | Capgemini, TCS, IBM Corporation, Wipro, Cognizant, Kyndryl, Accenture, HCLTech, DXC Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mainframe Market Strategic Shifts & Innovations
Encrypted processor complexes and hardware security modules are reshaping competitive positioning in mission-critical infrastructure. Three developments warrant particular attention.
Confidential computing architectures using trusted execution environments are decentralizing security boundaries within mainframe estates. Large German retail banks are deploying these modules for customer data processing. The technology is decentralizing risk isolation from perimeter defenses toward chip-level enclaves.
The EU's Digital Operational Resilience Act imposes third-party risk management obligations on critical technology suppliers. Financial institutions must now audit subprocessor resilience throughout their hardware supply chains. German and French banking consortia are consolidating vendor qualification programs in response.
Consumption-based capacity licensing is replacing perpetual hardware purchases among North American insurance carriers. Kyndryl and IBM are unbundling infrastructure management from capital acquisition. This shift is most visible in United States healthcare payers modernizing claims processing without upfront datacenter investment.
Mainframe Market Segmentation
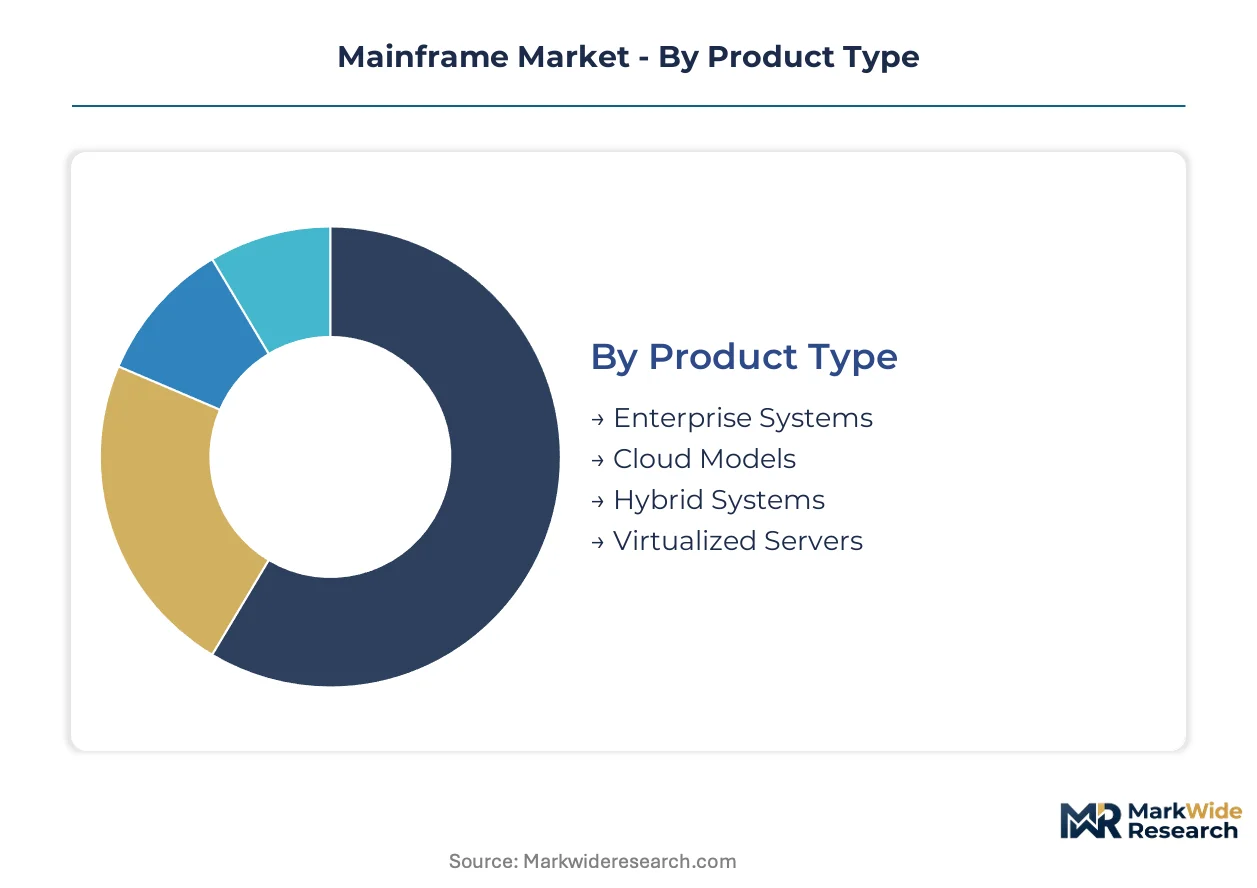
Mainframe procurement decisions pivot on workload criticality, regulatory exposure, and modernization trajectory. Buyers segment investments across hardware configurations, application layers, and service dependencies to balance risk containment against incremental cloud adoption.
Product Type:
Capital intensity and fault-tolerance requirements drive buyer selection across deployment architectures.
- Enterprise Systems:High-performance redundant processor complexes with hardware-level encryption serve core banking and settlement engines. Financial services institutions in the United States and Japan expand capacity for high-volume transaction processing under Federal Reserve and Financial Services Agency uptime mandates.
- Hybrid Systems:Configurations connecting on-premises cores to cloud orchestration layers enable incremental modernization without full rip-and-replace programs. German retail banks deploy these for customer data processing while maintaining resident compliance with EU Digital Operational Resilience Act protocols.
- Cloud Models:Consumption-based capacity licensing unbundles infrastructure management from capital acquisition.
- Virtualized Servers:Software-defined partitioning extends legacy hardware utilization through logical workload isolation.
Enterprise Systems leads on scale; Hybrid Systems leads on momentum.
Application:
Workload economics separate mission-critical operations from analytical margin pools.
- Transaction Processing:Simultaneous throughput exceeding tens of thousands of operations per second defines this category's technical specification. Core banking infrastructure in Germany and Japan depends on these applications for real-time settlement under strict auditability requirements.
- Analytics:Machine learning inference deployed directly on encrypted resident data volumes unlocks fraud detection and real-time risk scoring capabilities. Financial institutions pursue this layer for emerging margin pools without data egress.
- Data Storage:Hardware security modules protect persistent archives for regulated retention periods.
- Batch Processing:Overnight settlement and reconciliation workloads utilize spare capacity windows.
Transaction Processing commands installed base; Analytics climbs the fastest.
End User:
Regulatory pressure intensity varies sharply across sectoral risk profiles.
- Financial Services:Banks, insurers, and payment processors face operational resilience mandates from the Federal Reserve, European Banking Authority, and Japan's Financial Services Agency that directly sustain hardware refresh cycles.
- Government Agencies:NIST cybersecurity frameworks require hardware-level encryption and access logging that incumbent architectures satisfy.
- Healthcare Institutions:HIPAA compliance drives protected health information processing on fault-tolerant platforms.
- Retail Outlets:High-volume payment processing during peak demand windows creates seasonal capacity requirements.
Financial Services dominates procurement volume; Government Agencies show steadiest replacement cadence.
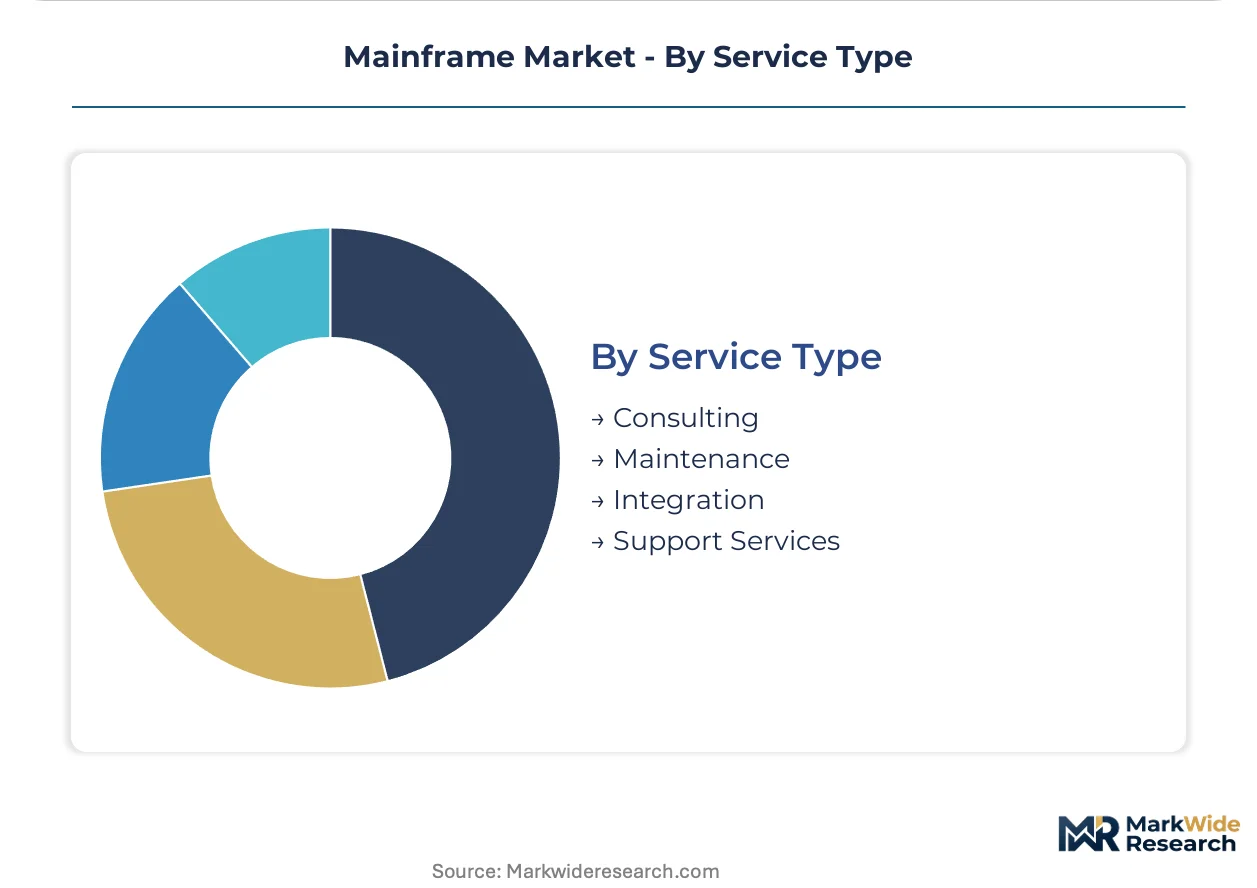
Service Type:
Skill scarcity shapes outsourcing depth across the operational lifecycle.
- Maintenance:COBOL and assembly language expertise concentrates among aging demographics in the United States and Japan, constraining in-house operational scaling and driving third-party dependency.
- Integration:Middleware expertise connecting on-premises cores to cloud orchestration layers sits outside traditional mainframe operations, creating specialized procurement.
- Consulting:Modernization labs convert monolithic codebases into API-accessible environments.
- Support Services:Tiered response commitments align with regulatory uptime requirements.
Maintenance captures largest service spend; Integration gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mainframe computing emerged from IBM's development laboratories in New York during the 1960s, establishing architectural foundations that financial institutions worldwide still depend upon for mission-critical transaction processing.
United States
Federal Reserve operational resilience mandates and NIST cybersecurity frameworks drive sustained hardware refresh cycles among domestic banks and insurers. The Federal Reserve Board enforces strict uptime requirements that favor fault-tolerant redundant processor complexes. New York and Charlotte banking clusters concentrate procurement for core settlement engines and high-volume payment processing infrastructure.
Germany
Deutsche Bundesbank oversight and retail banking consolidation sustain enterprise system deployments across Frankfurt and Munich financial centers. The EU Digital Operational Resilience Act imposes disaster recovery protocols that directly benefit incumbent mainframe architectures. Bavarian and North Rhine-Westphalian banking consortia are consolidating vendor qualification programs in response to third-party risk management obligations.
Japan
Financial Services Agency mandates preserve mainframe capacity expansion for real-time settlement and core banking modernization. METI industrial policy supports domestic technology sovereignty in critical financial infrastructure. Tokyo and Osaka metropolitan banking clusters maintain the densest concentration of COBOL-dependent transaction processing systems in the Asia-Pacific region.
India
Reserve Bank of India payment system resilience guidelines create procurement windows for hybrid mainframe-cloud configurations. RBI operational mandates for scheduled commercial banks drive infrastructure investment in Mumbai and Bangalore technology centers. Domestic IT services providers leverage specialized modernization labs to convert legacy codebases for API accessibility.
Mainframe Market Key Industry Players
Premium-margin players sit above commodity-margin players across service integration depth and specialized workforce access. The vendor base clusters around three strategic tiers: full-stack technology providers with proprietary hardware architectures, infrastructure management specialists with managed services portfolios, and IT services firms with dedicated modernization capabilities. Dominant competitive moves include strategic partnerships bundling hardware with software layers and portfolio diversification into hybrid cloud orchestration services.
Within the infrastructure management tier, Kyndryl and HCLTech occupy positions shaped by aftermarket service dependencies and specialized labor scarcity. IBM Corporation anchors the premium tier through zSystems architecture control. These three entities exemplify how competitive positioning flows from technology ownership depth versus services scale.
| Leading Market Players |
|---|
| Capgemini |
| TCS |
| IBM Corporation |
| Wipro |
| Cognizant |
| Kyndryl |
| Accenture |
| HCLTech |
| DXC Technology |
| Others |
Cost & Logistics Intelligence
Certification-grade bifurcation between NIST-compliant encrypted processor complexes and standard enterprise configurations shapes both procurement premiums and foundry allocation priorities across United States federal and commercial buyer segments.
Pricing Analysis
Consumption-based capacity licensing unbundles infrastructure management from capital acquisition across North American insurance carriers and healthcare payers. Price differentiation hinges on hardware-level encryption certification and disaster recovery protocol tiering. Cost compression in mid-market enterprise systems intensifies as Indian IT services providers expand API-accessible modernization offerings. Federal agencies demonstrate lowest price sensitivity due to NIST cybersecurity framework mandates; retail banking consortia in Germany exhibit highest sensitivity amid EU Digital Operational Resilience Act compliance timelines.
Supply Chain Analysis
Domestic-content mandates under Japan's METI industrial policy and United States federal procurement guidelines are reshaping semiconductor packaging sourcing for zSystems-class processors. Advanced processor fabrication draws from Taiwan and South Korea foundry capacity. Supply chain risk centers on single-source vulnerability for EUV lithography equipment. Distribution runs through direct OEM relationships with financial institutions and government agencies, supplemented by Kyndryl-managed infrastructure services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mainframe procurement constitutes a late-cycle quality story as financial regulators in the United States, European Union, and Japan mandate operational resilience specifications that favor fault-tolerant redundant processor complexes over distributed alternatives.
For Market Incumbents: Hedge against COBOL workforce attrition through captive training partnerships with Indian technical institutes and accelerated API-accessible modernization tooling. Secure foundry allocation commitments for encrypted processor complexes amid TSMC and Samsung capacity constraints. Prioritize certification maintenance for NIST and EU Digital Operational Resilience Act compliance tiers. For New Entrants and Emerging Players: Launch via managed services partnerships targeting India's Reserve Bank of India-mandated payment system resilience upgrades in Mumbai and Bangalore. Penetrate the hybrid mainframe-cloud integration segment where middleware expertise scarcity creates procurement windows. Position around machine learning inference on resident data volumes for fraud detection applications. For Investors and Strategic Acquirers: Consolidation pressure builds where specialized modernization lab capabilities concentrate among aging demographics in the United States and Japan. Five-to-ten year viability favors infrastructure management specialists with captive COBOL and assembly language workforces. Monitor central bank digital currency pilot specifications as architectural inflection signal for settlement engine displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Cloud Integration Partnership | Enables German retail banks to maintain EU Digital Operational Resilience Act compliance while modernizing incrementally. |
| API-Accessible Modernization Lab Acquisition | Secures scarce COBOL expertise for converting monolithic transaction processing into microservices environments. |
| Consumption-Based Licensing Expansion | Aligns with United States healthcare payer preferences for claims processing without upfront datacenter investment. |
| Confidential Computing Architecture Deployment | Addresses EU third-party risk management obligations through chip-level enclave security for customer data processing. |
| India Market Entry via RBI Compliance Services | Captures Reserve Bank of India payment system resilience procurement windows in Mumbai and Bangalore technology centers. |
Research Approach
Bottom-up financial services workload modeling reconciled against top-down semiconductor foundry capacity tracking forms the analytical core. Primary interviews with mainframe operations directors, regulatory compliance officers at Federal Reserve-supervised institutions, infrastructure procurement managers, and managed services executives combined with secondary validation against SEC 10-K filings, NIST framework documentation, EU Digital Operational Resilience Act regulatory texts, and Reserve Bank of India circulars. Supply-side data from TSMC and Samsung foundry disclosures triangulate against demand signals from banking technology spend surveys.
Input-output matrices map transaction processing volume, analytics workload intensity, and hybrid system adoption across enterprise system, hybrid system, cloud model, and virtualized server configurations. Segmentation dimensions include product architecture, application workload, end-user regulatory exposure, and service dependency depth. CAGRs derive from installed base refresh cycles, central bank digital currency pilot timelines, and workforce demographic projections. Forecast inputs incorporate NIST framework revision schedules and EU third-party risk management audit frequencies.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated distributed ledger settlement adoption or TSMC foundry disruption scenarios. Assumptions reflect current regulatory enforcement postures and technology sovereignty policy trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Mainframe Computers Market
Others
Snus Market
Others
Cloud Digital Video Recorder Market
Others
Smart Home Gateways Market
Others
Brazil Cane Sugar Market
Others
Solar Lighting Tower Market
Others
Rugged Tablet Market
Others
Middle East and Africa Home Care Packaging Market
Others
Global Military Wearable Sensors Market
Others
Global Pumpkin Candles Market
Others
Nyerereite Market
Others
Global Hardware As a Service (Haas) Market
Others
Radar Speed Signs Market
Others
North America Compressor Oil Market
Others
Iran Commercial Vehicles Lubricants Market
Others
Security Bottles Market