
 Brazil Cane Sugar Market | 2026-2036
Brazil Cane Sugar Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Cane Sugar Market Outlook
Mechanized harvesting technician shortages across São Paulo state is unwinding crushing capacity utilization at several major mill groups. Raízen leverages its integrated logistics network to sustain ethanol-sugar arbitrage flexibility across multiple biorefineries. Copersucar anchors export origination through Santos port terminal control, while São Martinho dominates high-yield agricultural land allocation in the Ribeirão Preto cluster.
Brazil cane sugar denotes sucrose extracted from Saccharum officinarum stalks with polarization exceeding 99 degrees for refined grades, produced via tandem milling, juice clarification, evaporation, and crystallization sequences primarily for caloric sweetening and fermentation feedstock. Raw sugar shipments hold the largest export volume pool, though organic sugar commands premium positioning in European and North American specialty channels. Liquid sugar adoption is accelerating among beverage industry bottlers seeking process simplification, while biofuel producers concentrate demand for VHP raw sugar as fermentation substrate under Brazil's escalating ethanol mandate.
ANVISA governs food-grade sugar purity standards and additive restrictions, while the National Biofuels Policy (RenovaBio) administered by ANP shapes carbon credit obligations that redirect mill output toward anhydrous ethanol. BIS-equivalent INMETRO certification requirements for export-bound organic sugar add compliance layers for international market access. Stakeholders must monitor RenovaBio carbon credit pricing volatility and Center-South rainfall patterns to calibrate crush mix decisions before each harvest cycle.
Market Dynamics
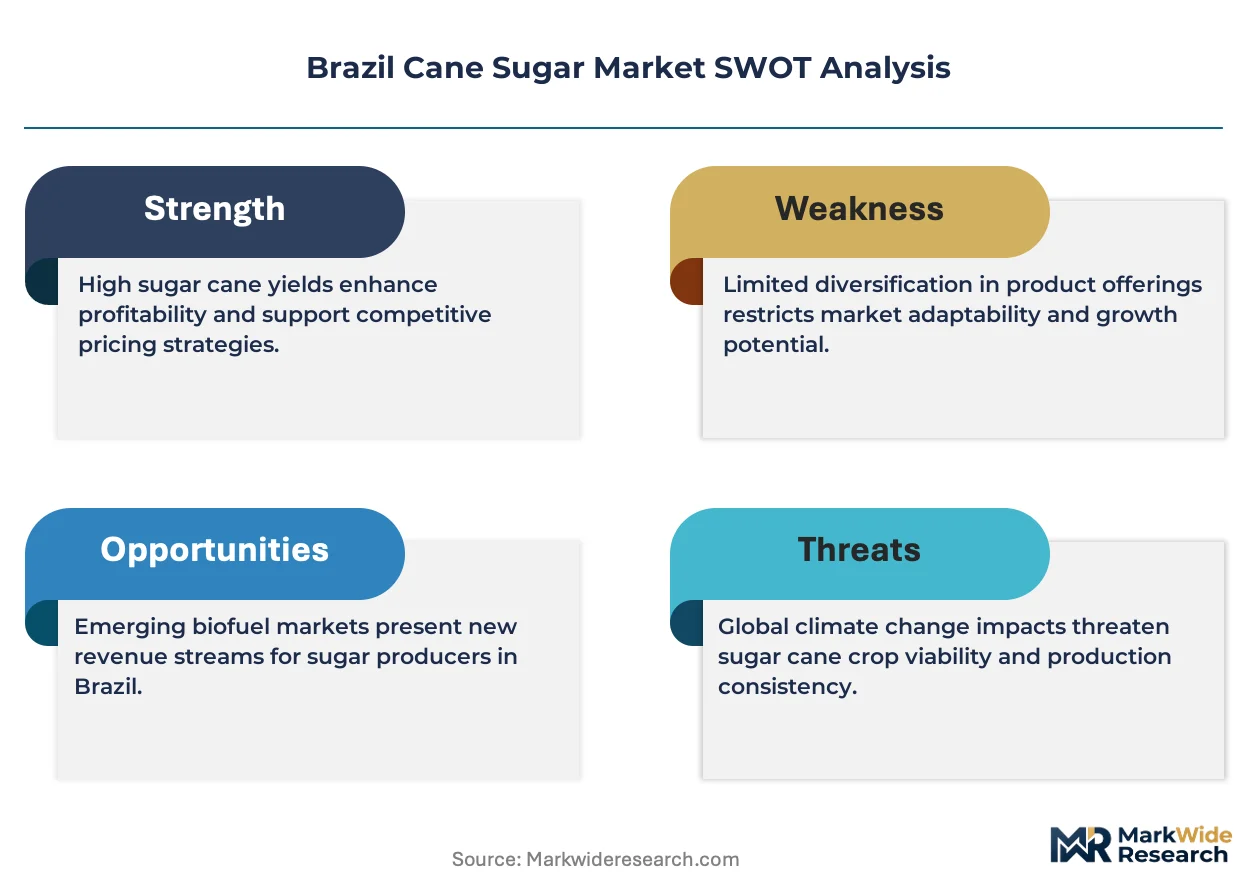
Brazil's cane sugar sector faces a structural pivot as RenovaBio carbon intensity requirements redirect mill capacity toward ethanol fermentation, compressing crystal sugar availability while biofuel offtake absorbs VHP raw sugar streams.
Growth Catalysts
- RenovaBio Carbon Credit Framework:ANP-administered decarbonization credits reward mills producing low-carbon ethanol, incentivizing crush mix reallocation toward fermentation feedstock and tightening refined sugar supply.
- Liquid Sugar Adoption:Beverage bottlers in São Paulo and Minas Gerais states are converting to liquid sucrose to eliminate crystallization steps, pulling demand from traditional crystal formats.
- Organic Certification Premiums:INMETRO-equivalent standards for EU and North American export channels command price premiums that justify segregated processing lines at Center-South mills.
Market Restraints
- Mechanized Harvesting Labor Scarcity:São Paulo state technician shortages are unwinding crushing capacity utilization gains across the Ribeirão Preto and Piracicaba clusters.
- Fertilizer Input Cost Volatility:Potash and urea price swings tied to Black Sea supply disruptions compress agricultural margins for independent growers in Goiás and Mato Grosso do Sul.
- Port Terminal Concentration:Santos port congestion and terminal control concentration create export origination bottlenecks during peak harvest windows.
Strategic Opportunities
- Northeast Brazil Expansion:Underpenetrated Alagoas and Pernambuco cane belts offer yield improvement potential through irrigation infrastructure and varietal substitution programs.
- Bioplastics Feedstock Pivot:Polyhydroxyalkanoate and polyethylene furanoate producers are piloting VHP sugar streams as fermentation substrates for biodegradable packaging materials.
- Carbon-Negative Ethanol Certification:Mills integrating biomass power generation and carbon capture can access premium offtake contracts under emerging EU border adjustment mechanisms.
Industry Challenges
- Precision Agriculture Specialist Shortage:Variable-rate application and telemetry system operators are scarce across São Paulo's mechanized harvest zones, limiting yield optimization.
- Organic Conversion Capex Burden:Segregated processing equipment, buffer zones, and certification audit trails require capital deployment that stretches independent mill balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Cane Sugar Market |
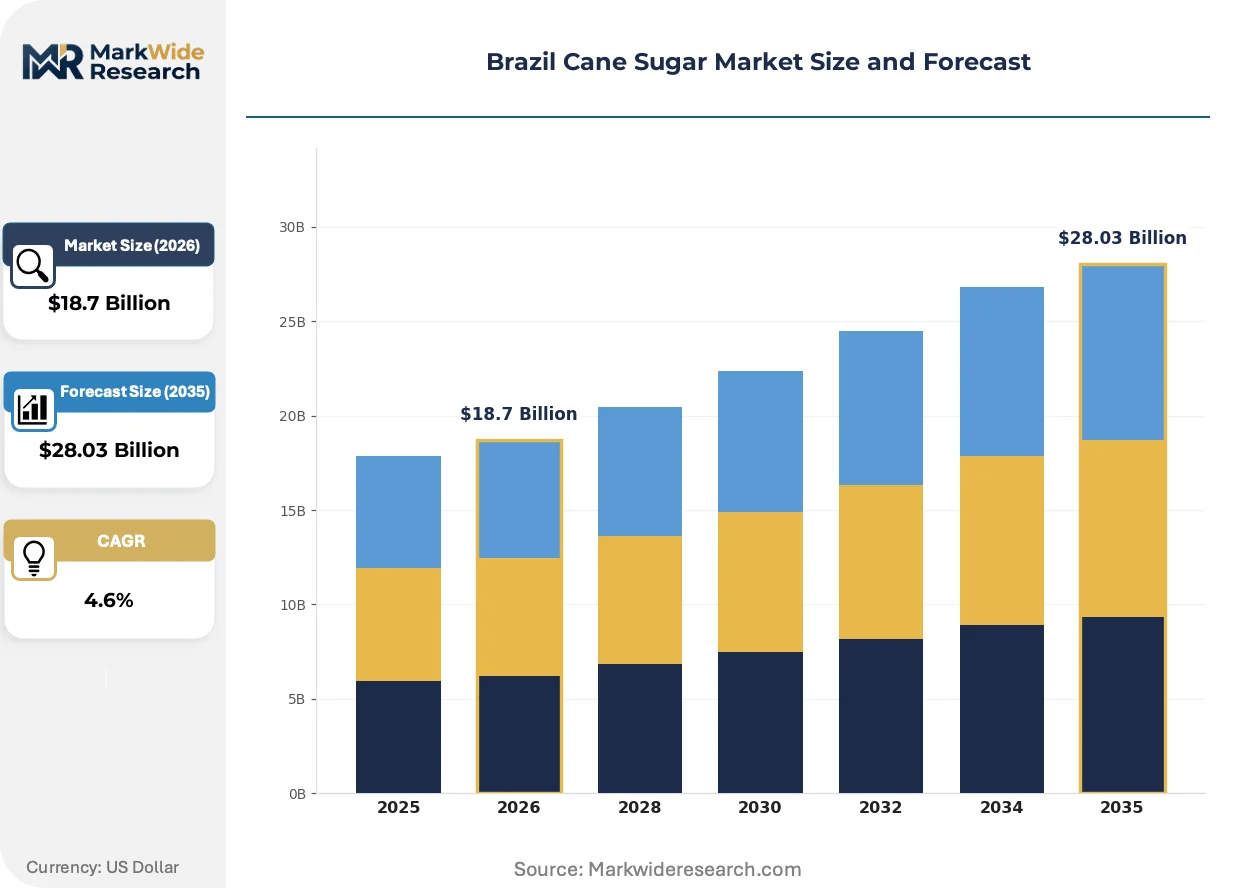
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Sugar, Refined Sugar, Liquid Sugar, Organic Sugar End User: Food Industry, Beverage Industry, Pharmaceutical Industry, Biofuel Producers Distribution Channel: Direct Sales, Wholesalers, Retailers, E-commerce Application: Sweeteners, Fermentation, Food Preservation, Sugar Substitutes |
| Companies Covered | Tereos Internacional, Atvos Agroindustrial, Copersucar, Grupo Virgolino de Oliveira, Usina Coruripe, Raízen, Biosev, Cosan, São Martinho, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Cane Sugar Market Strategic Shifts
Digital agriculture platforms and fermentation biotechnology are compressing operational timelines while regulatory carbon accounting redefines product-mix economics across Brazil's Center-South belt.
Near-infrared spectroscopy coupled with machine vision is miniaturizing real-time brix measurement during cane delivery, allowing mills to optimize payment formulas and crush sequencing. Major groups in São Paulo state are deploying portable units at receiving yards, compressing laboratory turnaround from hours to minutes and reducing payment disputes with grower cooperatives.
ANVISA's updated food-grade additive restrictions are tightening impurity thresholds for refined sugar destined for infant formula and pharmaceutical applications. Mills serving these channels are investing in additional clarification and ion exchange stages, with certification timelines extending six to nine months for first-time entrants.
Consolidated beverage bottlers are compressing supplier rosters and demanding integrated liquid sugar and logistics packages rather than commodity crystal procurement. This concentration is visible in Minas Gerais and Rio de Janeiro state bottling corridors, where long-term tolling agreements are displacing spot market transactions and requiring mills to invest in dedicated tanker fleets.
Brazil Cane Sugar Market Segmentation
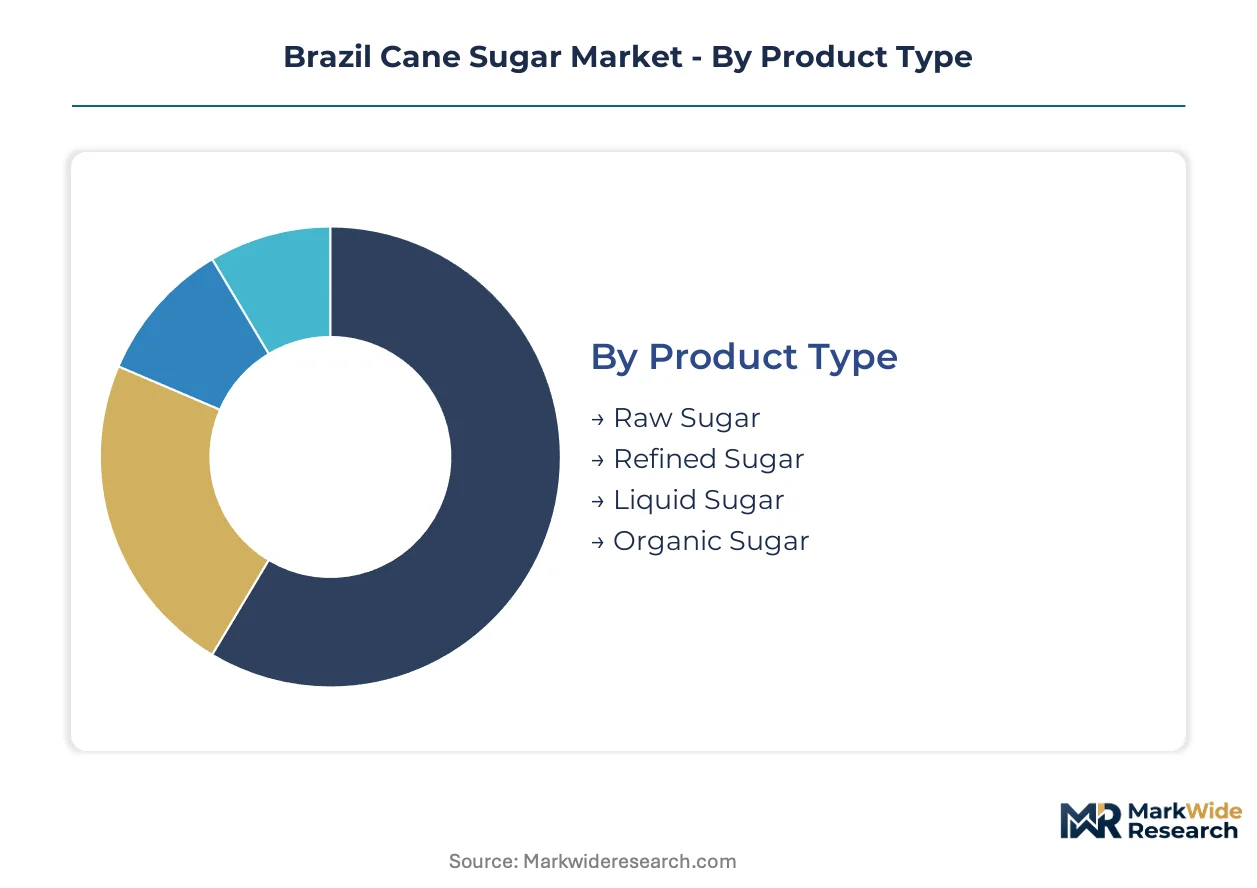
Brazil's cane sugar market segments reflect divergent margin profiles and channel economics across the Center-South belt. Product format and end-use application determine whether mills capture value through Santos port terminals, direct industrial contracts, or retail distribution networks.
Product Type:
Channel-mix patterns vary sharply across product formats, with export-bound raw sugar flowing through Santos port terminals while liquid and organic grades require dedicated logistics infrastructure.
- Raw Sugar:VHP polarization grades (99.2-99.7 degrees) dominate Santos port export volumes under long-term offtake contracts with international traders. Biofuel producers under RenovaBio carbon credit obligations are absorbing expanding VHP streams for fermentation feedstock, tightening availability for crystal sugar refiners.
- Refined Sugar:ICUMSA 45 and lower specifications serve ANVISA-regulated food-grade channels including infant formula and pharmaceutical applications. Mills serving these segments invest in additional ion exchange clarification stages with certification timelines extending six to nine months for first-time entrants.
- Liquid Sugar:Inverted sucrose solutions eliminate crystallization steps for beverage bottlers in São Paulo and Minas Gerais states.
- Organic Sugar:INMETRO-equivalent certification for EU and North American export channels commands price premiums that justify segregated processing lines.
By volume, Raw Sugar leads. By growth pace, Liquid Sugar is expanding most quickly as bottlers convert from crystal formats.
End User:
Cost tier differentiation separates commodity offtakers from premium-channel buyers, with biofuel and pharmaceutical segments commanding distinct margin structures.
- Food Industry:Confectionery and bakery manufacturers in São Paulo state represent the largest volume sink for standard crystal sugar, though procurement is consolidating toward integrated liquid sugar and logistics packages.
- Beverage Industry:Consolidated bottlers in Minas Gerais and Rio de Janeiro corridors are compressing supplier rosters and demanding tolling agreements that displace spot market transactions.
- Pharmaceutical Industry:ANVISA's tightened impurity thresholds for excipient-grade sucrose restrict eligible mill suppliers.
- Biofuel Producers:RenovaBio carbon intensity requirements redirect mill capacity toward ethanol fermentation, absorbing VHP raw sugar streams that previously supplied crystal refiners.
By volume, Food Industry leads. By margin expansion, Biofuel Producers are gaining share fastest as carbon credit economics reshape crush mix decisions.
Distribution Channel:
Supply concentration determines channel leverage, with major mill groups bypassing intermediaries for industrial accounts while fragmented growers depend on wholesaler networks.
- Direct Sales:Long-term supply agreements link Center-South mill groups directly to multinational beverage bottlers and biofuel producers, locking in crush volumes before harvest windows.
- Wholesalers:Independent growers in Goiás and Mato Grosso do Sul rely on regional distributors to aggregate output for export origination.
- Retailers:Supermarket and convenience store channels for packaged crystal sugar face margin compression from private label expansion.
- E-commerce:Specialty organic and fair-trade certifications find niche demand through direct-to-consumer platforms serving European and North American buyers.
By volume, Direct Sales leads. By channel development investment, E-commerce shows the steepest expansion trajectory as specialty sugar producers build export customer bases.
Application:
Application maturity separates commodity sweetening from value-added fermentation and preservation uses, with technology barriers determining competitive entry.
- Sweeteners:Caloric sweetening for food and beverage manufacturing remains the baseline volume application, though demand is fragmenting across crystal, liquid, and specialty formats.
- Fermentation:Ethanol production under RenovaBio mandates and emerging bioplastics feedstock trials are redirecting VHP sugar streams from export markets to domestic bioindustrial use.
- Food Preservation:Curing and osmotic stabilization applications in processed meat and fruit sectors demand specific sucrose purity grades.
- Sugar Substitutes:High-intensity sweetener blending and reduced-calorie formulation R&D creates demand for specialized sucrose fractions.
By volume, Sweeteners leads. By technology intensity, Fermentation is climbing the fastest as carbon-negative ethanol certification opens premium offtake contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Center-South states consume cane sugar predominantly for ethanol fermentation under RenovaBio mandates, while Northeast regions maintain stronger crystal sugar orientation for coastal food processing. São Paulo's industrial corridor absorbs the largest volume of liquid sugar for beverage manufacturing. Regional crush mix decisions diverge sharply based on proximity to Santos export terminals versus domestic biofuel offtake infrastructure.
São Paulo
RenovaBio carbon credit pricing governs crush allocation across the Ribeirão Preto and Piracicaba clusters. ANVISA food-grade certification requirements restrict mill participation in pharmaceutical-grade channels. Raízen's integrated logistics network spans multiple biorefineries in the state's northern cane belt.
Minas Gerais
Beverage bottlers in the Triângulo Mineiro and Belo Horizonte corridors drive liquid sugar demand through tolling agreements. State environmental licensing for new mill capacity faces extended review timelines. Atvos Agroindustrial operates crushing assets in the Uberaba cane district.
Goiás
Independent growers supply VHP raw sugar to Center-South mill groups under contract farming arrangements. Fertilizer input cost volatility compresses agricultural margins across the Rio Verde valley. Terminal access constraints force reliance on truck haulage to São Paulo state export facilities.
Alagoas
Irrigation infrastructure investments and varietal substitution programs target yield improvement in underpenetrated coastal cane zones. Federal agricultural credit lines through Banco do Nordeste support mechanization adoption. Coruripe maintains crushing operations in the Maceió sugarcane district.
Paraná
Southern cane belt mills balance domestic crystal sugar supply with ethanol production for regional fuel distributors. INMETRO-equivalent organic certification requirements shape export-oriented investment decisions. Biosev operates processing capacity in the northern Paraná cane zone.
Brazil Cane Sugar Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with ownership concentration highest among diversified agroindustrial conglomerates. The top tier controls Santos port terminal access and captive logistics networks, while mid-scale operators compete on crush flexibility and specialty certification. Three archetypes dominate: vertically integrated biorefinery operators, export-origination specialists with terminal control, and organic-certified niche producers. Competitive moves center on backward integration into agricultural land and strategic partnerships with carbon credit aggregators.
Within the integrated biorefinery tier, Raízen and Cosan exemplify scale-driven positioning through multi-asset logistics coordination. Copersucar anchors the export-origination specialist archetype through Santos port infrastructure control. São Martinho occupies a position among agricultural land specialists with concentrated holdings in high-yield Ribeirão Preto cluster zones. Tereos Internacional represents European-origin conglomerate structure with Brazilian operational footprint.
| Leading Market Players |
|---|
| Tereos Internacional |
| Atvos Agroindustrial |
| Copersucar |
| Grupo Virgolino de Oliveira |
| Usina Coruripe |
| Raízen |
| Biosev |
| Cosan |
| São Martinho |
| Others |
Value Chain & Pricing Dynamics
Forty-five to sixty days of cane inventory at Center-South mills compresses pricing leverage toward harvest-season buyers while Santos port terminal queues extending three weeks amplify spot-market volatility for export-bound VHP grades. This lead-time compression binds agricultural input costs to ocean freight scheduling in ways that favor integrated biorefineries with captive logistics over independent growers dependent on third-party haulage.
Pricing Analysis
Long-term offtake contracts governing Santos port export volumes anchor pricing stability for VHP raw sugar, while spot-market transactions for pharmaceutical-grade ICUMSA 45 reflect ANVISA certification premiums and ion exchange clarification costs. Price differentiation separates INMETRO-equivalent organic certifications commanding specialty premiums from standard crystal grades facing beverage bottler procurement consolidation. Pricing pressure intensifies as RenovaBio carbon credit economics redirect mill capacity toward ethanol fermentation, tightening refined sugar supply and elevating input-cost pass-through demands. Food industry manufacturers exhibit highest price sensitivity due to thin confectionery margins, while biofuel producers under ANP mandates absorb cost volatility through carbon credit revenue offsets.
Supply Chain Analysis
Brazil and India anchor global cane sugar production, with Center-South mills drawing from São Paulo and Minas Gerais agricultural zones while Uttar Pradesh and Maharashtra cane belts feed Asian refiners. Raw material dependencies center on potash and urea fertilizers subject to Black Sea supply disruptions, harvest labor availability, and varietal seedstock quality. Supply chain risk concentrates at Santos port terminal bottlenecks during peak harvest windows, where queue congestion and control concentration create single-point vulnerability for export origination. Distribution runs through direct mill-to-bottler tolling agreements for liquid sugar, Santos port terminals for raw sugar export, and regional wholesaler networks for independent grower aggregation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-intensity sweetener blending and reduced-calorie formulation R&D threatens caloric sweetener volume retention, forcing cane sugar incumbents to defend fermentation feedstock positioning against synthetic biology substitutes.
For Market Incumbents: Fortify crush-mix flexibility through backward integration into agricultural land and strategic partnerships with carbon credit aggregators under ANP administration. Secure ANVISA pharmaceutical-grade certification to access infant formula and excipient channels with six-to-nine-month entry barriers. Defend against precision fermentation substitutes by anchoring VHP supply relationships with bioplastics producers piloting polyhydroxyalkanoate feedstock streams. For New Entrants and Emerging Players: Differentiate on INMETRO-equivalent organic certification for European and North American specialty channels where segregated processing justifies price premiums. Target underpenetrated Alagoas and Pernambuco cane belts through irrigation infrastructure investments and Banco do Nordeste mechanization credit lines. Pursue direct-to-consumer e-commerce positioning for fair-trade and carbon-negative ethanol certification narratives. For Investors and Strategic Acquirers: Long-term, this sits as a carbon-accounting arbitrage play because RenovaBio credit pricing volatility and EU border adjustment mechanisms will revalue low-carbon ethanol assets independently of commodity sugar cycles. Acquisition focus should center on mills integrating biomass power generation with Santos port terminal access or captive agricultural land positions in high-yield Ribeirão Preto cluster zones. Monitor ANP carbon credit auction clearing prices as the signal for crush-mix reallocation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| RenovaBio Carbon Credit Optimization | ANP-administered decarbonization credits reward low-carbon ethanol production, redirecting mill output from crystal sugar. |
| Liquid Sugar Infrastructure Investment | Dedicated tanker fleets and tolling agreements lock in beverage bottler demand across Minas Gerais and Rio de Janeiro corridors. |
| Organic Certification Segregation | INMETRO-equivalent standards command price premiums justifying separate processing lines for EU and North American export channels. |
| Northeast Brazil Irrigation Expansion | Federal credit lines through Banco do Nordeste support yield improvement in Alagoas and Pernambuco coastal cane zones. |
| Bioplastics Feedstock Partnerships | Polyhydroxyalkanoate producers pilot VHP sugar streams for biodegradable packaging materials, opening fermentation demand beyond ethanol. |
Study Parameters
Initial hypotheses were tested against primary input from mill operations directors, agricultural cooperative managers, ANP regulatory affairs specialists, and Santos port terminal logistics coordinators, then refined through secondary validation against ANVISA food-grade additive filings, ANP RenovaBio carbon credit auction records, and INMETRO organic certification audit trails. Bottom-up crush volume estimates from Center-South state agricultural departments were triangulated with top-down export origination data from customs declarations.
Variance decomposition across the projection horizon isolates demand drivers by product format, end-use application, and distribution channel concentration. Segmentation modeling incorporated polarization grade tiers, ANVISA regulatory pathways, RenovaBio carbon intensity obligations, and regional crush mix decisions across São Paulo, Minas Gerais, Goiás, and Northeast belt states. CAGRs were derived from elasticity-adjusted volume projections calibrated to historical crush allocation shifts between ethanol fermentation and crystal sugar production.
Material uncertainties — Center-South rainfall pattern volatility, potash and urea price swings tied to Black Sea supply disruptions, and ANP carbon credit pricing regime changes — sit outside the modeled envelope and could materially revise trajectory assumptions. Forecasts reflect documented assumptions regarding RenovaBio mandate enforcement continuity and Santos port infrastructure expansion timelines. Recalibration cycles align with material shifts in ANP regulatory guidance and EU border adjustment mechanism implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Military Apparel Market
Others
UAE Location-Based Services Market
Others
Vegan Confectionery Market
Others
South America Halal Food and Beverages Market
Others
Digital Media Adaptor (DMA) Market
Others
Halogen Free Flame Retardant Bopet Films Market
Others
Global Mica Market
Others
Brown Ht Market
Others
Mini Personal Computer Market
Others
Global Active Speaker Market
Others
North America Astrology Market
Others
Bimodal Identity Management Solutions Market
Others
ASEAN Smart Homes Market
Others
Fresh Apples Market
Others
Hydrostatic Testing Market
Others
Propanil Market