
 North America Compressor Oil Market | 2026-2036
North America Compressor Oil Market Size, Share, and Industry Trends Forecast 2026-2036
North America Compressor Oil Market Insights
Modular service bundling is recalibrating how buyers procure compressor oils across North America. ExxonMobil leverages its integrated base oil and additive supply chain to control cost positions in synthetic formulations. Shell competes through technology leadership in gas-to-liquid process oils that extend drain intervals for industrial compressors. Chevron anchors its position with strong distribution density across the US Midwest manufacturing belt.
Compressor oil is a formulated lubricant designed to reduce friction, dissipate heat, and seal clearances in positive displacement and dynamic compressors, typically containing anti-wear additives, oxidation inhibitors, and foam suppressants in viscosity grades ranging from ISO 32 to 100. Its primary purpose is to protect compressor internals from wear and deposit formation while maintaining thermal stability under continuous high-pressure operation. Synthetic oil formulations command the deepest margin pools as end users prioritize extended drain intervals and energy efficiency in industrial automation applications. Mineral oil retains volume leadership in cost-sensitive construction equipment where shorter service cycles prevail. The refrigeration application segment is gaining structural importance as EPA phase-down rules for high-GWP refrigerants force lubricant reformulation for compatibility with lower-flammability alternatives.
EPA regulations under Section 608 and the Clean Air Act shape refrigerant-containing compressor oil management, while OSHA standards govern workplace exposure limits during oil change operations in industrial settings. The US Department of Energy efficiency mandates for compressed air systems indirectly steer demand toward advanced synthetic formulations that reduce energy consumption. Stakeholders must monitor how state-level low-carbon fuel standards in California and Oregon propagate into lubricant carbon intensity reporting requirements.
Market Dynamics
EPA refrigerant phase-down mandates under Section 608 are forcing lubricant reformulation across the North American compressor oil landscape, creating immediate technical displacement pressure on legacy mineral formulations while opening formulation windows for synthetic alternatives.
Growth Catalysts
- Petrochemical capacity expansion:Downstream processing buildouts along the Texas Gulf Coast are pulling industrial-grade synthetic compressor oils into new installation and maintenance cycles.
- Section 608 compliance deadlines:EPA refrigerant management rules are accelerating replacement demand for oils compatible with lower-GWP refrigerant alternatives in commercial cooling systems.
- Great Lakes manufacturing retrofit wave:Aging compressed air infrastructure across Ohio, Michigan, and Illinois industrial corridors is generating sustained demand for advanced lubricant formulations with extended drain intervals.
Market Restraints
- Group III base oil supply concentration:Synthetic formulation feedstocks remain concentrated among a narrow set of North American refiners, creating input cost volatility exposure.
- Mineral oil price anchoring:Cost-sensitive construction equipment operators continue to specify conventional formulations, compressing premium synthetic penetration in outdoor mobile applications.
- Refrigerant-lubricant compatibility testing:Extended certification timelines for new refrigerant-oil pairings under ASHRAE protocols delay product commercialization cycles.
Strategic Opportunities
- Mexico manufacturing integration:Nearshoring momentum across automotive and appliance production in Querétaro and Nuevo León is expanding addressable demand for industrial compressor lubricants.
- Energy-as-a-service models:Compressed air system performance contracts are bundling lubricant supply into outcome-based agreements, creating captive demand channels.
- California low-carbon fuel standards:State-level carbon intensity reporting requirements are creating preference premiums for lubricants with documented supply chain emissions profiles.
Industry Challenges
- Refrigerant chemistry expertise gap:Field service technicians lack training on new lower-flammability refrigerant properties and corresponding lubricant handling protocols.
- Legacy system integration complexity:Synthetic oil conversions in aged compressor fleets require extensive system flushing and seal compatibility verification, extending sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Compressor Oil Market |
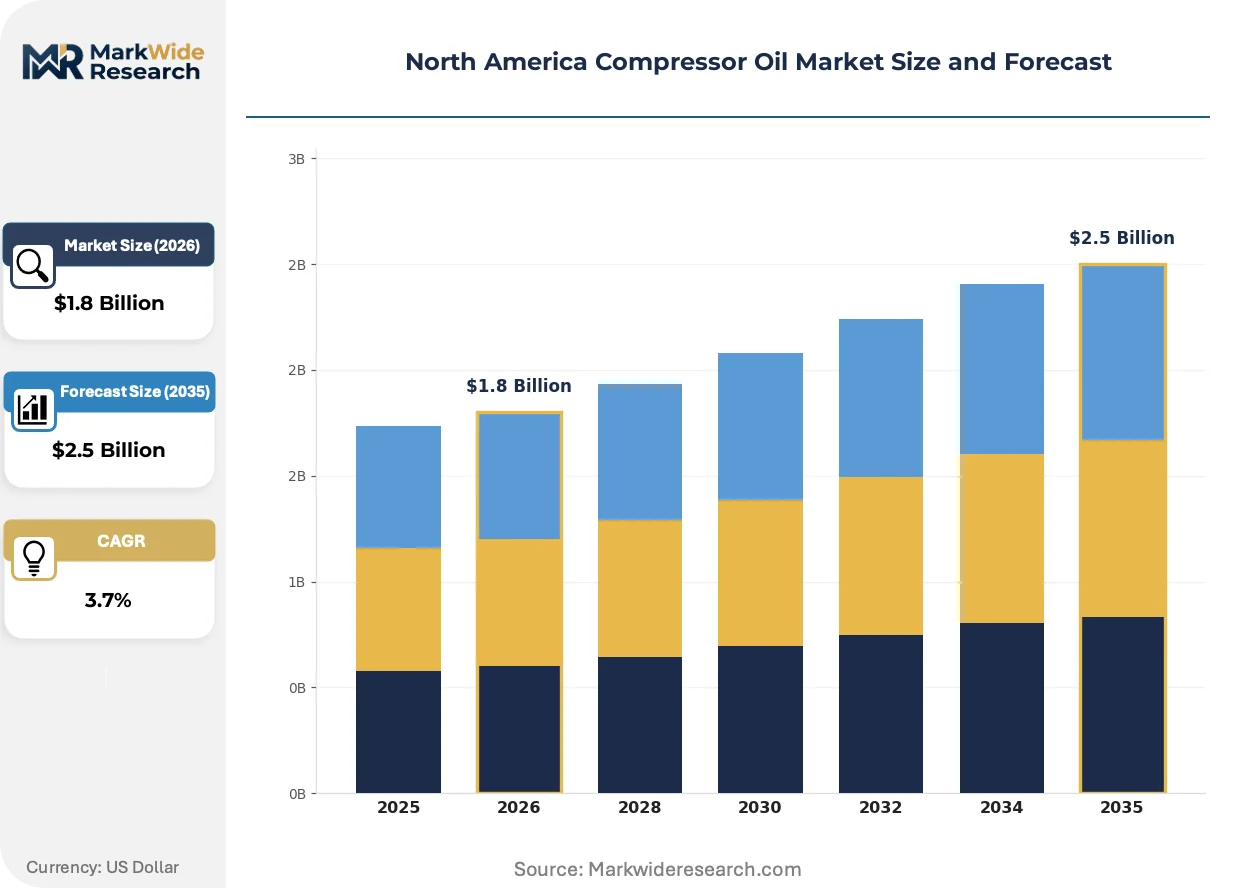
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Oil, Synthetic Oil, Semi-Synthetic Oil, Biodegradable Oil End User: Manufacturing, Automotive, Construction, Marine Application: Refrigeration, Air Conditioning, Industrial Automation, Vacuum Systems Distribution Channel: Online Retail, Direct Sales, Wholesale, Specialty Stores |
| Companies Covered | ExxonMobil, Shell, Chevron, TotalEnergies, FUCHS, Phillips 66, Quaker Houghton, Valvoline, BP, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Compressor Oil Market Trends and Innovations
Synthetic formulation technology is actively fragmenting competitive advantage across the North American compressor oil market, with performance differentiation increasingly tied to additive chemistry rather than base oil sourcing alone.
Polyalkylene glycol (PAG) and polyol ester (POE) synthetic base stocks are decentralizing the technical center of gravity in refrigeration compressor lubrication. Commercial HVAC contractors and industrial cold chain operators are adopting these formulations at accelerating rates as R-410A and R-134a phase-downs advance. The shift is decentralizing procurement authority from traditional petroleum distributors toward specialty chemical suppliers with refrigerant-specific formulation expertise.
EPA's updated Section 608 regulations and the AIM Act refrigerant phase-down schedule are compressing formulation development timelines. Equipment manufacturers must now certify lubricant compatibility across multiple refrigerant alternatives simultaneously, forcing closer technical collaboration between compressor OEMs and lubricant formulators. The commercial refrigeration segment is responding fastest, with supermarket chains and cold storage operators demanding pre-certified oil-refrigerant packages to minimize compliance risk.
Integrated fluid management programs are displacing transactional lubricant purchasing across Midwest manufacturing belts. Automotive suppliers and metal fabricators are contracting directly with lubricant providers for scheduled analysis, filtration, and replacement services, bypassing traditional industrial distributor networks. The Ohio-Indiana-Michigan manufacturing corridor shows the deepest penetration of this model, where compressed air system uptime guarantees increasingly include lubricant condition monitoring.
North America Compressor Oil Market Segmentation
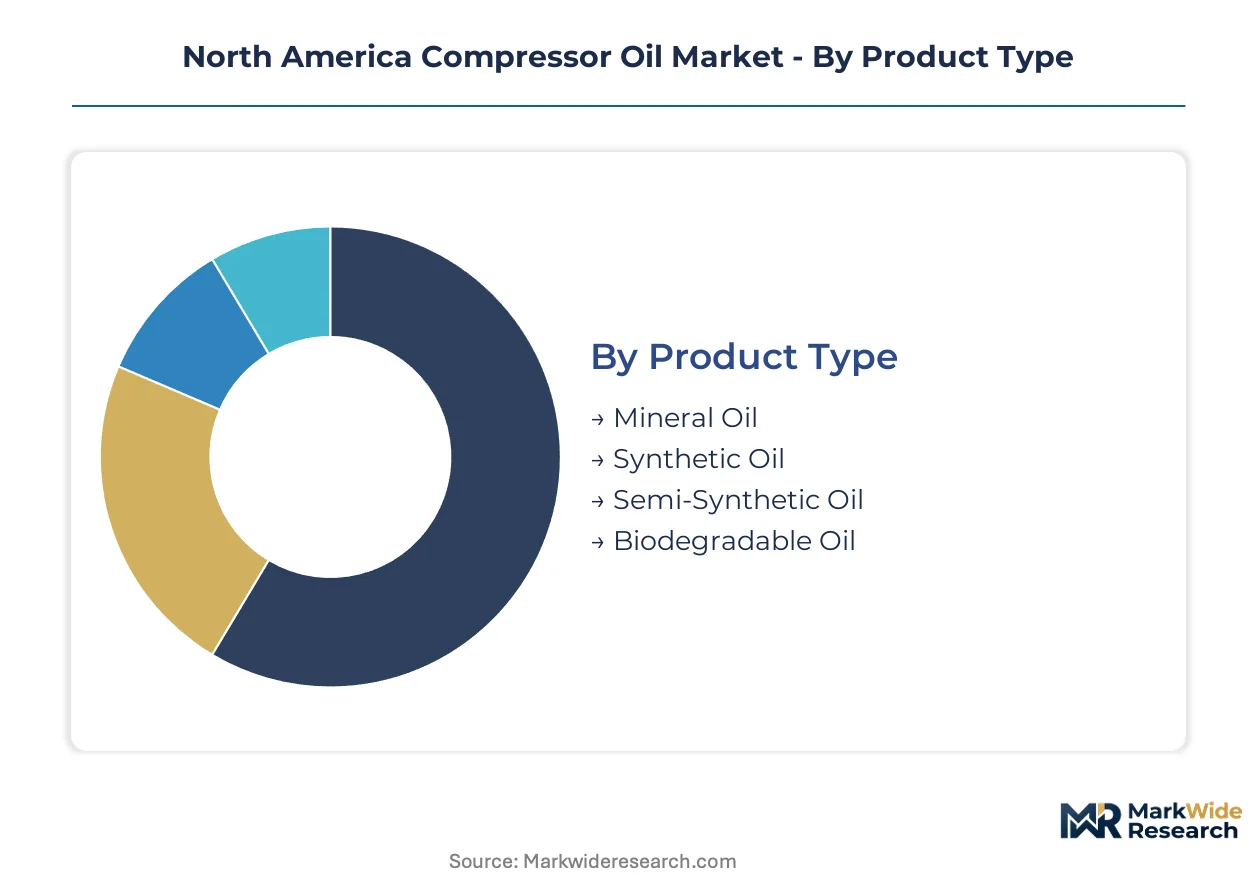
Compressor oil segmentation in North America reflects divergent buyer priorities across cost sensitivity, regulatory exposure, and operational intensity. Procurement patterns split sharply between facilities seeking extended drain intervals and those prioritizing lowest unit cost per liter.
Product Type:
Cost tier fundamentally separates buyers in this category, with premium synthetics commanding specification authority at energy-intensive operations while mineral oils retain volume leadership in price-driven segments.
- Mineral Oil:Refined petroleum distillates with additive packages for oxidation resistance and foam control. Demand concentrates in Texas construction equipment fleets and Great Lakes metal fabrication shops where shorter service intervals and lower per-unit cost override efficiency premiums. EPA refrigerant compatibility requirements are beginning to displace mineral formulations in commercial cooling applications.
- Synthetic Oil:Formulations built on Group III, IV, or V base stocks with engineered viscosity stability across temperature extremes. Petrochemical processors along the US Gulf Coast specify these for continuous-duty centrifugal compressors where unplanned downtime exceeds lubricant cost premiums by orders of magnitude. California manufacturing facilities increasingly require documented carbon intensity profiles for synthetic procurement.
- Semi-Synthetic Oil:Blended base stocks balancing mineral cost structure with synthetic performance extension.
- Biodegradable Oil:Vegetable-derived or synthetic ester formulations for environmentally sensitive applications.
Mineral oil leads volumes today; synthetic oil is gaining share fastest.
End User:
Application intensity and compressor duty cycles create distinct formulation requirements across buyer segments.
- Manufacturing:Automotive stamping plants and appliance assembly lines in Ohio, Michigan, and Indiana operate extensive compressed air networks. These facilities are converting to synthetic formulations under integrated fluid management contracts that bundle oil analysis, filtration, and scheduled replacement.
- Automotive:Vehicle assembly and component manufacturing in Mexico's Bajío region and southeastern US states.
- Construction:Mobile compressors for pneumatic tools and shotcrete application in infrastructure projects.
- Marine:Shipboard refrigeration and auxiliary compressed air systems.
Manufacturing dominates current demand; automotive end-use is expanding most quickly.
Application:
Regulatory exposure intensity separates applications, with refrigerant-phase-down compliance creating urgent reformulation demand in cooling systems.
- Refrigeration:Cold chain logistics and supermarket systems face EPA Section 608 mandates for lower-GWP refrigerant adoption. Lubricant formulators must certify polyol ester and PAG compatibility with R-448A, R-449A, and other alternatives, compressing product development timelines and favoring suppliers with refrigerant-specific technical capabilities.
- Air Conditioning:Commercial building HVAC systems in Texas, Florida, and California.
- Industrial Automation:Robotics and precision assembly requiring contaminant-free compressed air.
- Vacuum Systems:Semiconductor manufacturing and pharmaceutical processing.
Industrial automation leads volumes today; refrigeration is climbing the fastest.
Distribution Channel:
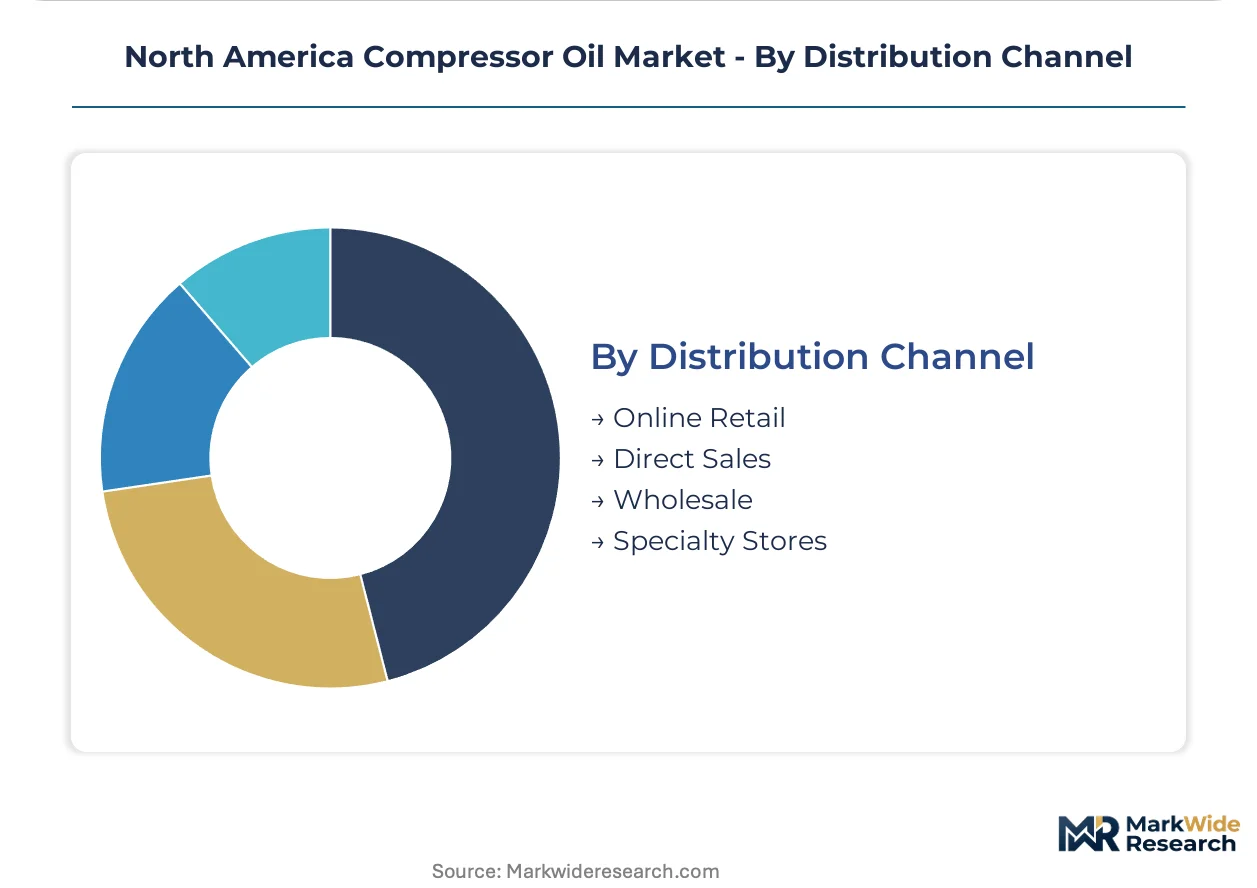
Buyer scale and technical service requirements determine channel selection, with large consumers bypassing traditional distribution.
- Direct Sales:National accounts and multi-site manufacturers negotiate direct supply agreements with formulators. These contracts increasingly incorporate performance guarantees and condition monitoring services, displacing transactional purchasing across the Midwest manufacturing belt.
- Online Retail:Small maintenance shops and independent contractors.
- Wholesale:Industrial distributors serving regional manufacturing clusters.
- Specialty Stores:Refrigeration and HVAC-focused suppliers with refrigerant handling expertise.
Wholesale leads volumes today; direct sales is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American compressor oil industry traces its modern scale to post-war industrialization along the Great Lakes and Gulf Coast, where petrochemical complexes and automotive manufacturing established the region's lubricant formulation infrastructure. This historical foundation now shapes demand concentration across three distinct national markets.
United States
EPA Section 608 refrigerant phase-down rules and DOE compressed air efficiency mandates are accelerating synthetic formulation adoption across Texas petrochemical corridors and Midwest manufacturing belts. The Ohio-Indiana-Michigan automotive stamping cluster operates extensive compressed air networks converting to integrated fluid management contracts. California's low-carbon fuel standards are creating preference premiums for lubricants with documented supply chain emissions profiles.
Canada
Ontario's automotive parts manufacturing and Alberta's oil sands processing drive industrial compressor oil demand with distinct regional specifications. Health Canada and Environment and Climate Change Canada administer refrigerant management rules aligned with Montreal Protocol commitments. The Toronto-Windsor manufacturing corridor shows deepening penetration of condition-monitoring service contracts bundling lubricant supply with uptime guarantees.
Mexico
Nearshoring momentum across Querétaro and Nuevo León automotive and appliance production is expanding addressable demand for industrial compressor lubricants. Mexican environmental regulations under SEMARNAT are tightening refrigerant handling protocols for commercial cooling systems. The Bajío region's manufacturing parks are specifying synthetic formulations for new compressed air infrastructure serving export-oriented assembly operations.
North America Compressor Oil Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation technology and service integration capabilities. The North American compressor oil market exhibits tiered concentration with integrated petroleum majors controlling synthetic base oil supply chains while specialty chemical suppliers capture refrigerant-specific formulation niches. Three strategic archetypes dominate: vertically integrated petroleum majors with captive base oil production, specialty lubricant formulators with refrigerant chemistry expertise, and regional distributors bundling technical services. Competitive dynamics center on backward integration into additive chemistry and forward integration into fluid management programs.
Within the integrated petroleum major tier, ExxonMobil and Shell exemplify archetypes of supply chain control and process technology leadership respectively. Chevron anchors a position through distribution density. These three occupy the premium formulation segment where extended drain intervals and energy efficiency specifications command margin premiums over commodity mineral alternatives.
| Leading Market Players |
|---|
| ExxonMobil |
| Shell |
| Chevron |
| TotalEnergies |
| FUCHS |
| Phillips 66 |
| Quaker Houghton |
| Valvoline |
| BP |
| Others |
Pricing and Supply Chain Analysis
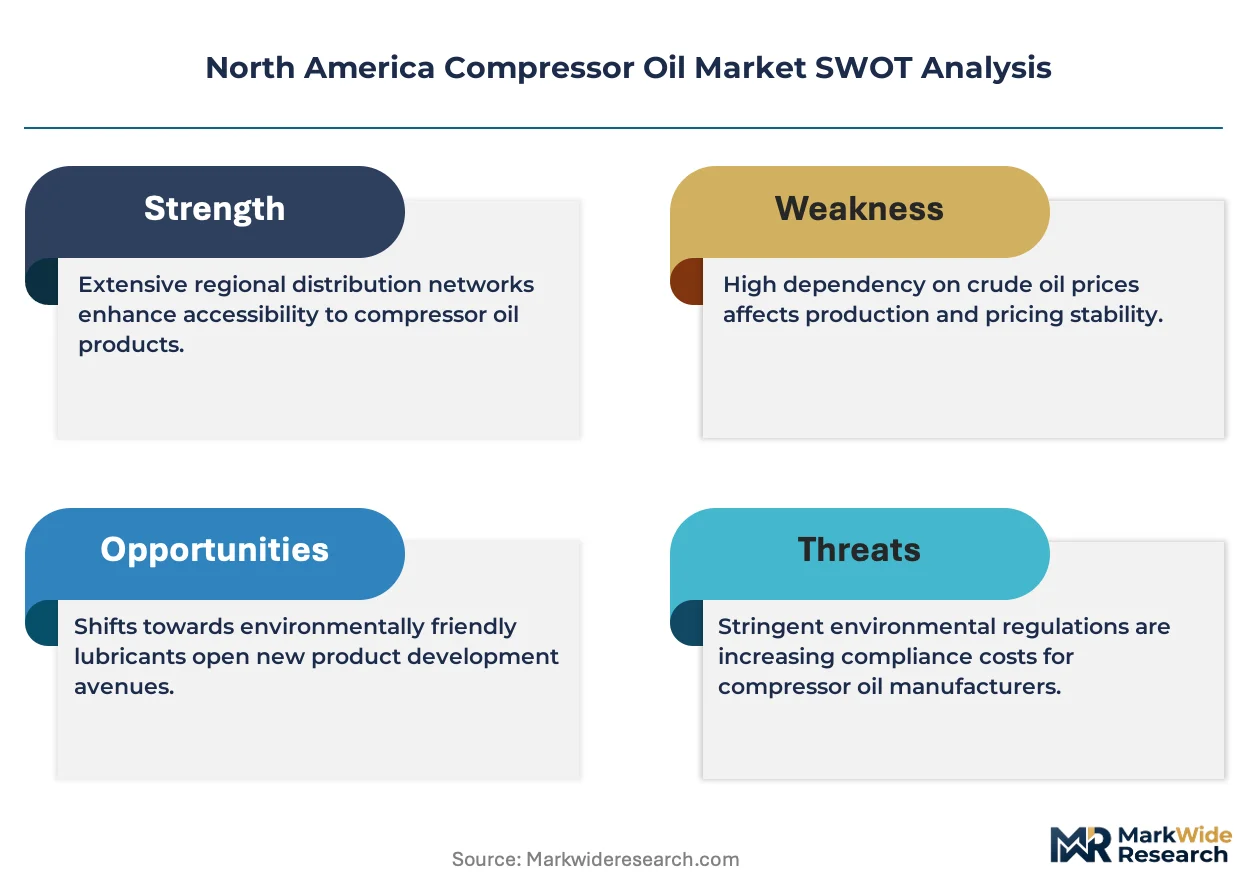
Group III base oil feedstock costs cascade through synthetic compressor oil pricing tiers, with narrow North American refiner concentration amplifying volatility exposure for formulators serving Texas petrochemical corridors and Midwest manufacturing belts.
Pricing Analysis
Three-tier pricing structure across premium synthetic, semi-synthetic, and mineral economy levels separates buyers by drain interval requirements and energy efficiency priorities. Price differentiation hinges on ISO viscosity grade certification and bundled fluid management service inclusion. Cost compression in mineral formulations intensifies because construction equipment operators prioritize lowest per-liter cost over performance premiums. Small independent contractors exhibit highest price sensitivity; Gulf Coast petrochemical processors show least.
Supply Chain Analysis
Dual-sourcing requirements from major compressor OEMs and national account manufacturers mandate multi-refiner qualification for Group III, IV, and V base stocks. Supply concentrates in United States Gulf Coast refineries, Canadian oil sands upgraders, and South Korean Group III exporters. Formulation draws from polyalphaolefin, polyalkylene glycol, and polyol ester chemistries alongside additive packages. Single-source vulnerability persists in specialized refrigerant-compatible esters. Distribution runs through integrated petroleum majors, regional industrial distributors, and direct national account contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in synthetic formulation tiers as EPA refrigerant phase-downs force technical displacement of mineral alternatives and service bundling captures lifecycle value.
For Market Incumbents: Hedge refrigerant chemistry expertise gaps by acquiring specialty ester formulators with ASHRAE certification capabilities before R-448A and R-449A compatibility windows close. Deepen backward integration into additive chemistry to defend margin positions against feedstock volatility from concentrated Group III suppliers. Channel control through integrated fluid management contracts across the Ohio-Indiana-Michigan corridor locks out distributor competition.
For New Entrants and Emerging Players: E-commerce platforms serving independent HVAC contractors and small maintenance shops offer lowest barrier entry with refrigerant-specific technical content marketing. White-space targets include biodegradable compressor oils for California low-carbon fuel standard compliance and Mexico Bajío region nearshoring demand. Specialty chemical suppliers with PAG and POE formulation expertise can bypass petroleum distributor networks entirely.
For Investors and Strategic Acquirers: Consolidation pressure builds where refrigerant-lubricant compatibility certification timelines compress product development cycles and favor scaled R&D operations. Long-term viability favors formulators with captive base oil supply and documented carbon intensity profiles. Acquisition target archetype: regional specialty lubricant players with SEMARNAT-registered products for Mexico manufacturing integration. Watch EPA Section 608 enforcement intensity as inflection indicator for synthetic conversion velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Chemistry | Captures margin pool from concentrated specialty chemical suppliers serving synthetic formulations. |
| Refrigerant Compatibility Certification Program | Accelerates ASHRAE-compliant product launches ahead of R-410A phase-down deadlines. |
| Integrated Fluid Management Contract Expansion | Locks Midwest automotive stamping plants into scheduled analysis and replacement services. |
| Mexico Manufacturing Footprint Establishment | Positions supply adjacent to Querétaro and Nuevo León nearshoring momentum. |
| Carbon Intensity Documentation System | Qualifies synthetic formulations for California low-carbon fuel standard preference premiums. |
Research Methodology
Direct dialogue with compressor OEM technical directors, petrochemical plant maintenance managers, HVAC contractor purchasing leads, and industrial lubricant distribution executives grounded qualitative findings. Secondary validation drew from EPA Section 608 regulatory filings, DOE compressed air efficiency program data, ASHRAE refrigerant-lubricant compatibility standards, and customs trade records for base oil imports. Bottom-up and top-down triangulation cross-checked volume estimates against refinery capacity disclosures and end-use equipment installation trends.
Bottom-up modeling built from segment-level demand drivers across product type, end user, application, and distribution channel dimensions. Top-down constraints applied macroeconomic indicators and energy price assumptions across the analysis window. CAGRs derived from fitted growth curves weighted by regulatory phase-down schedules and manufacturing capital expenditure pipelines. Industry-specific inputs included refrigerant transition timelines and petrochemical capacity buildout permits.
The model assumes a particular technology adoption path; alternative pathways for lower-flammability refrigerant chemistry would alter the outlook for polyol ester demand trajectories. Forecasts reflect assumptions about EPA enforcement consistency and nearshoring momentum sustainability. Deviation in Group III base oil refinery utilization rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Middle East and Africa Home Care Packaging Market
Others
Italy Feed Additives Market
Others
Global Smart Home Installation Service Market
Others
Sunflower Husk Pellets Market
Others
Global ESD Protection Devices Market
Others
Storm Surge Barriers Market
Others
Asia-Pacific B2B Legal Services Market
Others
Solar Panel Testers Market
Others
Smart Home Controller Market
Others
United States Cigarette Market
Others
Residential Electrical Conduit Market
Others
Europe Video Encoder Market
Others
Tunnel Lighting Market
Others
Singapore Retail Market
Others
Cloud Advertising Market
Others
Global Maritime Freight Transport Market