
 Security Bottles Market | 2026-2036
Security Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Security Bottles Market Analytics
Pharmaceutical wholesale distribution is fragmenting as direct-to-pharmacy channels and specialty drug logistics networks multiply across North America and Europe. Amcor Plc leverages its global manufacturing footprint to supply multi-layer barrier bottles for oncology and biologic therapies. Gerresheimer AG anchors high-value glass security bottle production for European injectable markets, while Berry Global Group, Inc. competes aggressively in plastic child-resistant closures through automated molding scale.
Security bottles are engineered containers incorporating child-resistant closures, tamper-evident seals, and barrier materials to prevent unauthorized access, contamination, or diversion of regulated contents. Polypropylene formulations with ethylene vinyl alcohol coextrusion achieve oxygen transmission rates below 0.1 cc per day, preserving oxidation-sensitive pharmaceuticals across extended supply chains. Child-resistant closures dominate unit volume in prescription drug packaging, though tamper-evident segments command premium pricing due to forensic traceability requirements. Multi-use bottles with locking mechanisms are gaining share in institutional pharmacy settings where dose verification protocols necessitate repeated controlled access.
FDA 21 CFR Part 310.3 child-resistant packaging standards and EMA Annex 1 sterile manufacturing guidelines jointly dictate material selection and closure validation protocols for pharmaceutical security bottles. EPA regulations on recycled content thresholds are pressuring converters to certify post-consumer polyethylene streams without compromising barrier integrity. Stakeholders must monitor evolving state-level pharmaceutical stewardship laws in California and New York, where extended producer responsibility frameworks may impose bottle take-back obligations independent of federal requirements.
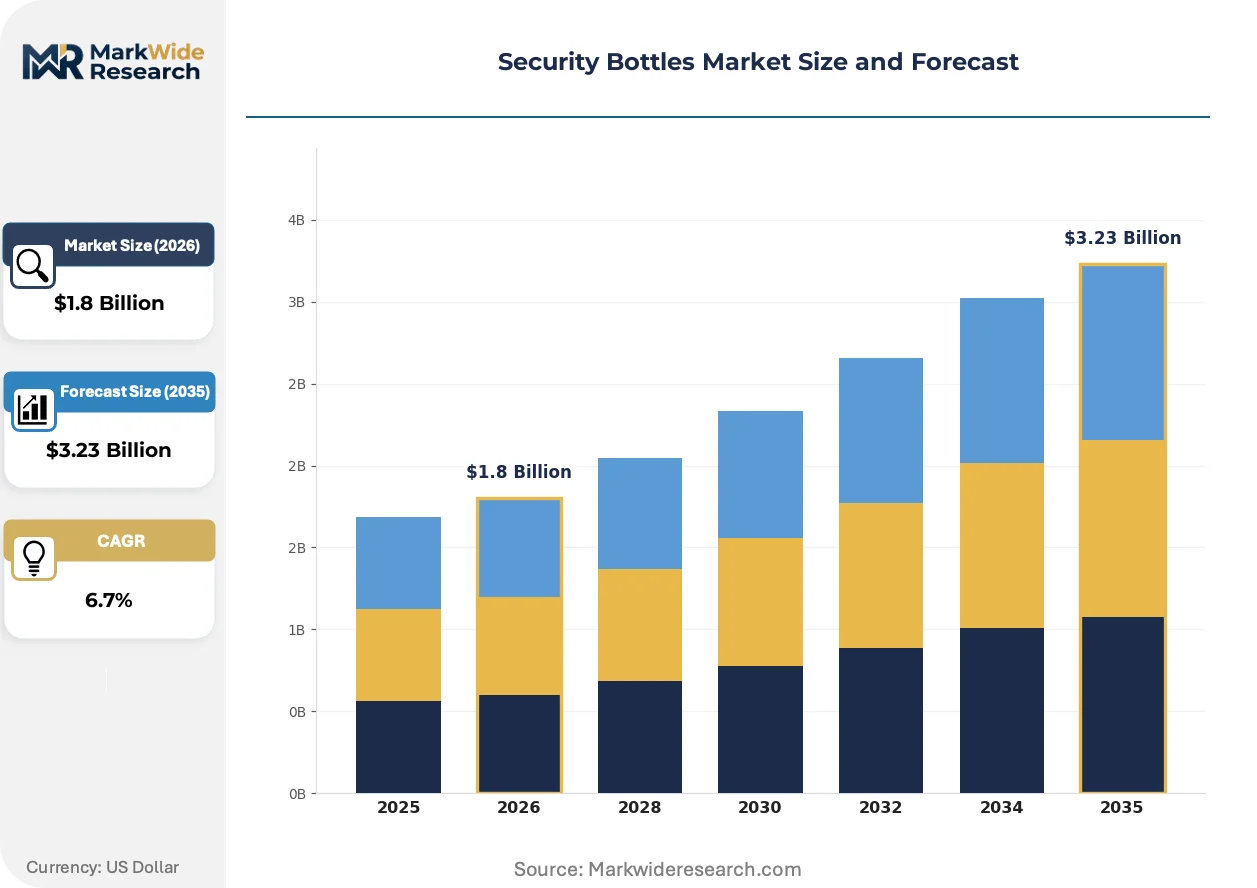
Market Dynamics
Pharmaceutical packaging procurement is fragmenting as specialty drug distributors and direct-to-pharmacy networks bypass traditional wholesale channels, forcing converters to reconfigure fulfillment systems for smaller batch sizes and faster turnaround cycles.
Growth Catalysts
- FDA 21 CFR Part 310.3 Mandates:US prescription drug packaging must incorporate child-resistant closures, creating baseline demand across oral solid and liquid formulations.
- Oncology Biologics Expansion:Temperature-sensitive monoclonal antibody therapies require multi-layer barrier bottles with ethylene vinyl oxygen barriers below 0.1 cc per day.
- EMA Annex 1 Sterile Manufacturing Guidelines:European injectable producers are upgrading to tamper-evident glass and polymer containers with validated closure integrity testing.
Market Restraints
- Post-Consumer Recycled Content Certification:EPA thresholds for recycled polyethylene streams create validation bottlenecks without guaranteed barrier performance equivalence.
- Specialty Resin Supply Concentration:Ethylene vinyl alcohol copolymer production clusters in Northeast Asia, exposing converters to freight cost volatility and extended lead times.
- Glass-to-Plastic Substitution Limits:High-pH biologic formulations still require borosilicate glass due to polymer degradation risks in extended shelf-life scenarios.
Strategic Opportunities
- Extended Producer Responsibility Frameworks:California and New York pharmaceutical stewardship laws may impose bottle take-back obligations, creating reverse logistics service revenue pools.
- Institutional Pharmacy Locking Mechanisms:Multi-use bottles with programmable access controls address hospital dose-verification protocols and controlled substance tracking requirements.
- Smart Closure Integration:Near-field communication chips embedded in child-resistant caps enable digital adherence monitoring for value-based care contracts.
Industry Challenges
- Barrier Validation Timeline Compression:Accelerated FDA generic drug approvals demand faster extractables and leachables testing without compromising protocol rigor.
- Automation Integration Complexity:Legacy pharmaceutical filling lines require retrofitting for new closure geometries, extending qualification periods and capital deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Security Bottles Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Child Resistant, Tamper Evident, Single-Use, Multi-Use Material: Glass, Plastic, Polypropylene, Polyethylene End User: Pharmaceuticals, Nutraceuticals, Cosmetics, Household Products Closure Type: Screw Cap, Flip Top, Dropper, Locking Mechanism |
| Companies Covered | Amcor Plc, Gerresheimer AG, Graham Packaging Company, Berry Global Group, Inc., West Pharmaceutical Services, Inc., Stevanato Group S.p.A., AptarGroup, Inc., SGD Pharma S.A.S, ALPLA Werke Alwin Lehner GmbH & Co KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Security Bottles Market Evolving Landscape
Material science convergence with digital authentication technologies is redefining security bottle value propositions, shifting competitive differentiation from physical barrier properties to integrated supply chain traceability and patient engagement capabilities.
Coextruded polypropylene-ethylene vinyl alcohol barrier structures are collapsing the performance gap between plastic and glass containers for oxidation-sensitive liquid formulations. Oncology and biologic therapy packagers in Germany and the United States are qualifying these multi-layer bottles for 24-month shelf-life claims previously reserved for amber glass. The technology is collapsing premium pricing power in high-barrier segments as commodity resin converters achieve specialty performance tiers.
EMA Annex 1 sterile manufacturing guidelines and FDA container closure integrity guidance are converging to mandate probabilistic leak detection methods over traditional dye ingress testing. European injectable producers face capital equipment upgrades for vacuum decay and high-voltage leak detection systems. Parenteral packaging lines in Switzerland and Germany are prioritizing inline testing integration to avoid batch release delays.
Hospital and long-term care pharmacy buyers are consolidating procurement through group purchasing organizations with standardized specification requirements. Specialty drug distributors are disintermediating traditional wholesale relationships to capture packaging specification influence. The concentration of buying power is most visible in United States health system networks, where formulary committees now mandate specific closure torque ranges and tamper-evident break forces across therapeutic categories.
Security Bottles Market Segmentation
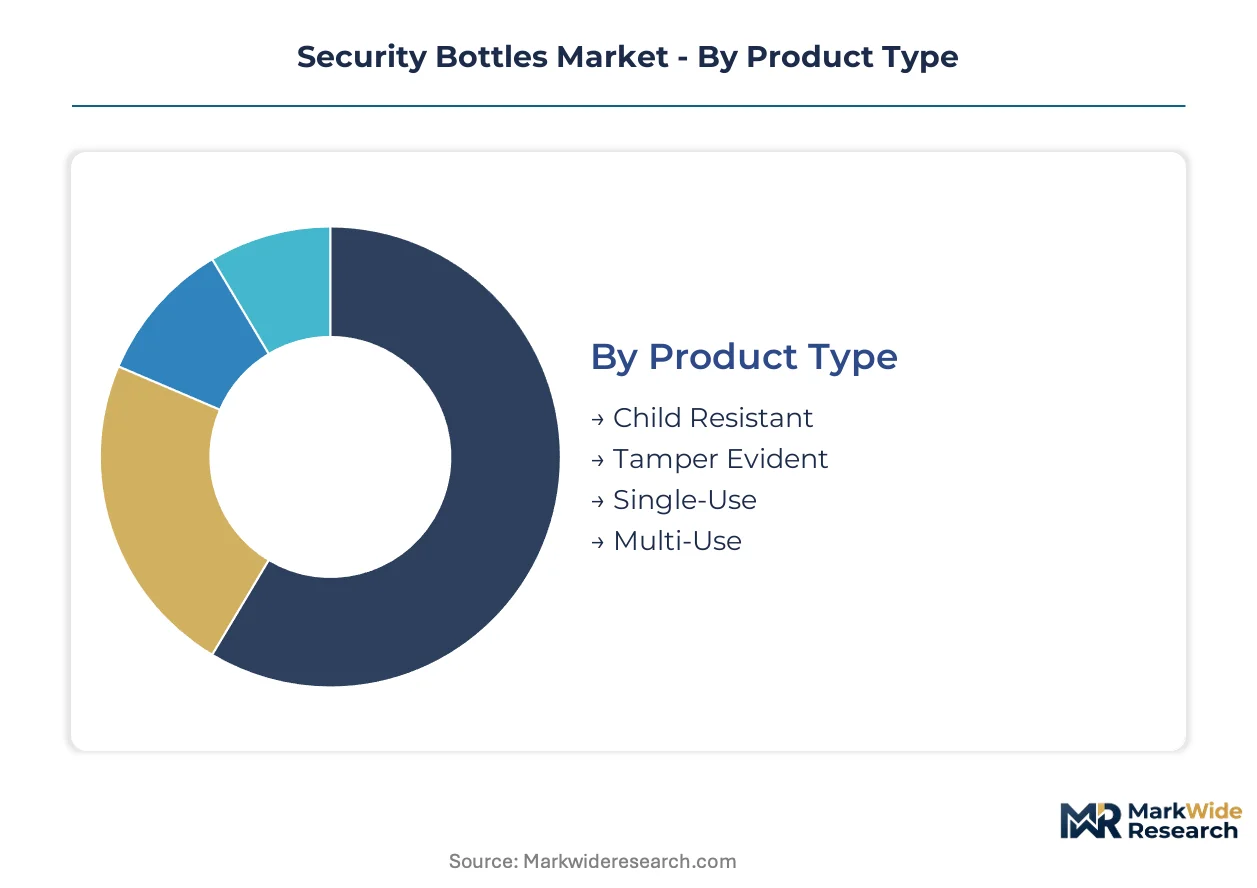
Security bottle procurement decisions cascade through multiple technical dimensions, each imposing distinct validation protocols and supply chain configurations. Material-barrier compatibility and closure-access mechanisms determine regulatory pathway complexity and manufacturing capital intensity across pharmaceutical and consumer applications.
Product Type:
After-sales service intensity varies sharply across product categories, with multi-use bottles requiring field calibration support and replacement component logistics while single-use formats minimize ongoing manufacturer obligations.
- Child Resistant:These closures integrate push-and-turn or squeeze-and-turn mechanisms meeting FDA 21 CFR Part 310.3 torque specifications. US prescription oral solid dose manufacturers mandate this format across pediatric and geriatric therapeutic categories, with validation testing consuming 12-16 weeks per SKU.
- Tamper Evident:Break-away bands, shrink sleeves, and induction seals provide forensic evidence of container compromise. European injectable producers under EMA Annex 1 guidelines prioritize this segment for biologic therapies, commanding premium pricing due to batch-level traceability requirements.
- Single-Use:Disposable bottles with bonded closures eliminate recontamination risks in hospital pharmacy compounding.
- Multi-Use:Locking mechanisms with programmable access controls serve institutional dose-verification protocols.
Child Resistant holds the largest share; momentum sits with Tamper Evident as biologics expand.
Material:
Cost tier stratification separates commodity resin converters from specialty barrier material suppliers, with glass and coextruded polymers occupying premium positions above standard polyethylene.
- Glass:Borosilicate and amber glass containers deliver inert surfaces for high-pH biologics and oxidation-sensitive formulations. German and Swiss injectable producers retain glass specifications for 24-month shelf-life claims where polymer degradation risks persist.
- Polypropylene:Coextruded grades with ethylene vinyl alcohol achieve oxygen transmission below 0.1 cc per day. US oncology packagers are qualifying these structures for temperature-sensitive monoclonal antibody therapies previously reserved for glass.
- Plastic:General-purpose polymers serve over-the-counter and nutraceutical applications with moderate barrier requirements.
- Polyethylene:HDPE and LDPE formulations dominate high-volume liquid prescription dispensing due to molding efficiency and closure compatibility.
Polyethylene holds the largest share; Polypropylene is climbing the fastest as barrier technology advances.
End User:
Application-driven specification divergence separates pharmaceutical-grade validation requirements from cosmetic and household product standards, with nutraceuticals occupying an intermediate compliance tier.
- Pharmaceuticals:FDA and EMA mandates enforce extractables and leachables testing, child-resistant closure validation, and container closure integrity verification. US generic drug manufacturers face compressed approval timelines demanding faster qualification protocols.
- Nutraceuticals:Dietary supplement packagers adopt pharmaceutical-grade security features preemptively to secure retail shelf placement in US health system networks and German pharmacy chains.
- Cosmetics:Premium skincare brands deploy tamper-evident seals to signal product authenticity against diversion and counterfeiting.
- Household Products:Cleaning chemical producers incorporate child-resistant closures under Consumer Product Safety Commission guidelines for caustic formulations.
Pharmaceuticals holds the largest share; Nutraceuticals is gaining share fastest as supplement regulation tightens.
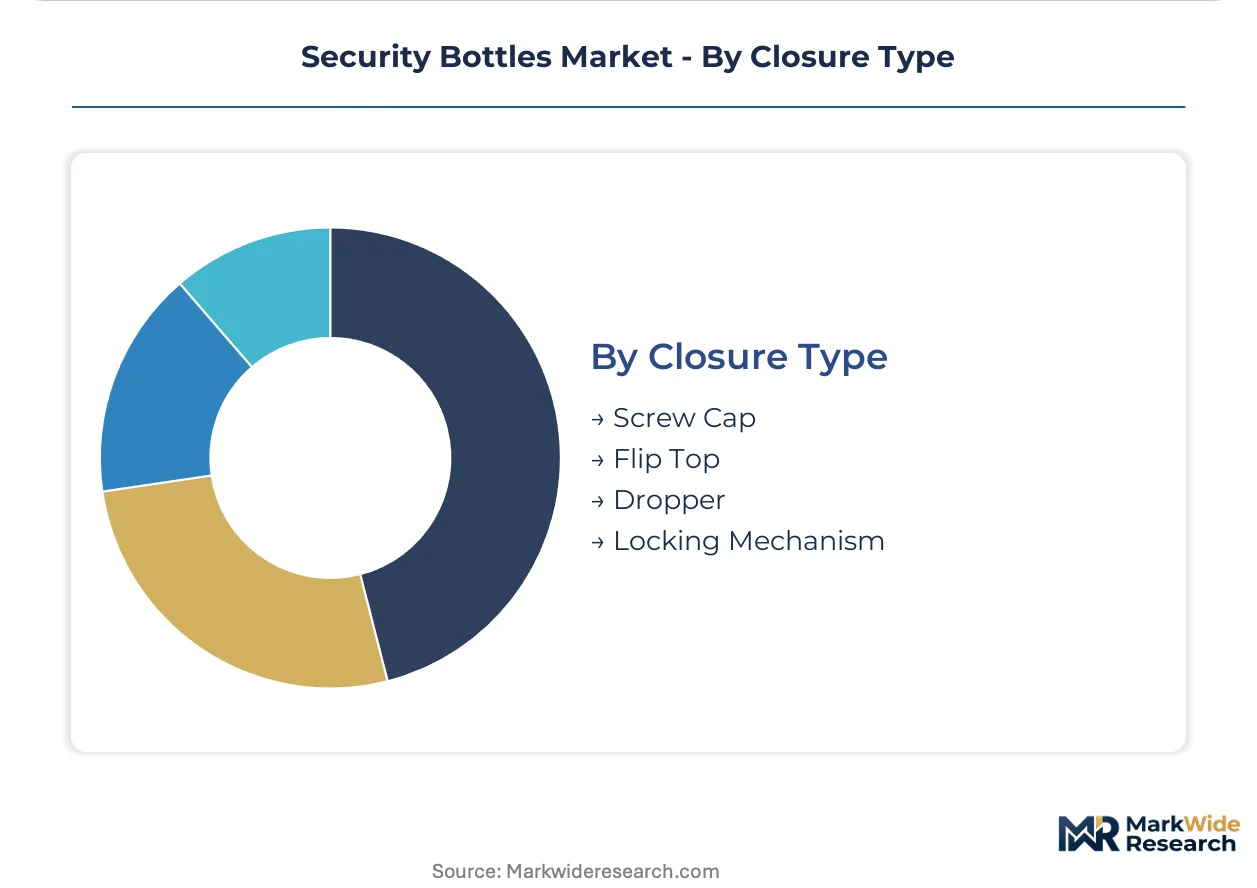
Closure Type:
Volume concentration favors screw cap formats across oral solid dose applications, while specialty mechanisms capture margin in controlled substance and institutional pharmacy segments.
- Screw Cap:Standard threaded closures with child-resistant liners dominate prescription bottle unit volume. Automated capping lines in US and Chinese pharmaceutical facilities achieve throughputs exceeding 300 bottles per minute with this format.
- Locking Mechanism:Programmable electronic and mechanical locks address hospital controlled substance tracking and dose-verification protocols. German long-term care pharmacy networks are consolidating procurement through group purchasing organizations specifying torque ranges and break forces for this category.
- Flip Top:Hinged lids with snap closures serve over-the-counter liquid formulations requiring frequent access.
- Dropper:Calibrated glass and polymer pipettes integrate with tamper-evident collars for ophthalmic and pediatric liquid dosing.
Screw Cap holds the largest share; Locking Mechanism shows the steepest expansion trajectory as institutional protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Swiss injectable packaging clusters where EMA Annex 1 compliance costs create entry barriers, while Chinese converters compete on polyethylene volume with thinner margins. Regulatory stringency and healthcare infrastructure investments drive procurement decisions across the United States, Germany, and China.
United States
FDA 21 CFR Part 310.3 mandates child-resistant closures across prescription oral solid and liquid formulations, creating baseline demand validation. Generic drug manufacturers face compressed approval timelines that demand faster extractables and leachables testing protocols. New Jersey and Pennsylvania pharmaceutical corridors host automated capping lines exceeding 300 bottles per minute for screw-cap formats.
Germany
EMA Annex 1 sterile manufacturing guidelines enforce tamper-evident container specifications for biologic therapies with premium pricing power. Long-term care pharmacy networks consolidate procurement through group purchasing organizations with standardized torque ranges. Bavarian and Baden-Württemberg packaging clusters specialize in high-barrier coextruded polypropylene for oncology applications.
China
NMPA pharmaceutical packaging standards align with international barrier performance benchmarks for export-oriented manufacturers. Domestic nutraceutical demand accelerates adoption of pharmaceutical-grade security features for retail shelf placement. Yangtze River Delta converters scale polyethylene molding capacity for high-volume liquid prescription dispensing.
Switzerland
Swissmedic injectable regulations preserve borosilicate glass specifications for 24-month shelf-life biologics where polymer degradation risks persist. Parenteral packaging lines prioritize inline vacuum decay testing to avoid batch release delays. Basel and Zurich pharmaceutical clusters anchor European high-value glass security bottle production.
India
CDSCO pharmaceutical packaging guidelines tighten extractables testing requirements for export markets. Domestic generic drug manufacturers upgrade child-resistant closure capabilities to secure US and European supply contracts. Maharashtra and Gujarat pharmaceutical corridors expand polyethylene and polypropylene molding capacity for liquid formulations.
Security Bottles Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in materials and closure mechanisms. The vendor base stratifies between global converters with multi-continent manufacturing footprints and regional specialists serving niche barrier or glass segments. Three archetypes dominate: integrated packaging platforms, high-barrier material specialists, and precision closure engineers. Competitive moves center on automated molding scale investments and EMA Annex 1 validation service bundling.
Within the integrated platform tier, Amcor Plc and Berry Global Group, Inc. occupy positions spanning multi-layer barrier bottles and child-resistant closure systems. Gerresheimer AG anchors the high-value glass segment for European injectable markets, representing the precision pharmaceutical packaging archetype where validated closure integrity commands premium positioning.
| Leading Market Players |
|---|
| Amcor Plc |
| Gerresheimer AG |
| Graham Packaging Company |
| Berry Global Group, Inc. |
| West Pharmaceutical Services, Inc. |
| Stevanato Group S.p.A. |
| AptarGroup, Inc. |
| SGD Pharma S.A.S |
| ALPLA Werke Alwin Lehner GmbH & Co KG |
| Others |
Value Network & Pricing Analysis
Ethylene vinyl alcohol supply concentration in Northeast Asia determines both pricing tier spreads and supply chain shape, forcing converters to absorb freight volatility or qualify alternative barrier resins at lower performance tiers. FDA and EMA validation requirements for child-resistant and tamper-evident formats create fixed compliance costs that compress margins at volume-driven polyethylene converters while preserving premium positioning for glass and coextruded polypropylene specialists.
Pricing Analysis
The customization-premium spread separates standard screw-cap polyethylene bottles from configured-to-order multi-layer barrier formats with validated closure integrity documentation. Pricing stratifies across premium, standard, and economy tiers based on barrier performance certification and after-sales validation support intensity. Cost compression in high-volume oral solid dose segments is intensifying as Chinese converters expand automated molding capacity. Generic drug manufacturers exhibit highest price sensitivity; biologic packagers for oncology therapies show lowest sensitivity due to shelf-life failure costs.
Supply Chain Analysis
Supplier-financing facilities with 90-120 day terms have become standard for polyethylene and polypropylene converters serving US pharmaceutical distributors. Manufacturing gravity centers on China, Germany, and the United States, with Swiss and Indian specialists anchoring high-value glass and closure validation segments. Raw material flows draw from Saudi Arabian and US Gulf Coast ethylene feedstock, Northeast Asian ethylene vinyl alcohol copolymer, and German borosilicate glass. Single-source vulnerability sits with specialty oxygen barrier resin supply. Distribution runs through direct-to-pharmacy networks and group purchasing organizations consolidating procurement leverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Security bottle markets increasingly reward service-attach revenue streams, with EMA Annex 1 validation consulting and extractables testing protocols expanding faster than commodity bottle unit sales. After-sales calibration support for multi-use locking mechanisms and digital adherence monitoring integration represent recurring revenue layers outpacing hardware growth.
For Market Incumbents: Build regulatory validation moats through captive EMA Annex 1 certification laboratories and FDA extractables testing protocols. Expand backward integration into ethylene vinyl alcohol compounding to secure barrier resin supply against Northeast Asian freight volatility. Deepen channel control by embedding field service engineers within group purchasing organization specification committees. Threat of disintermediation by direct-to-pharmacy networks demands faster batch turnaround capabilities. For New Entrants and Emerging Players: Pursue institutional pharmacy locking mechanism segments where programmable access controls remain underpenetrated relative to oral solid dose child-resistant formats. Target German long-term care pharmacy networks consolidating procurement through standardized torque specifications. White-space exists in smart closure integration with near-field communication chips for adherence monitoring. Go-to-market angle: bundle hardware with digital platform licensing for hospital dose-verification protocols. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision closure engineers with validated pharmaceutical-grade manufacturing footprints. Long-term viability hinges on regulatory certification asset durability and service revenue attach rates. Acquisition archetype: mid-cap specialists with EMA Annex 1 sterile manufacturing validation and existing group purchasing organization contracts. Signal to watch: California and New York extended producer responsibility framework implementation accelerating bottle take-back obligation monetization.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Annex 1 Validation Service Bundling | Captures premium positioning in European biologic injectable packaging through certified sterile manufacturing compliance. |
| Smart Closure Integration | Enables digital adherence monitoring partnerships with value-based care contracts and hospital pharmacy networks. |
| Backward Integration into Barrier Resins | Secures oxygen transmission performance below 0.1 cc per day without Northeast Asian supply concentration exposure. |
| Extended Producer Responsibility Infrastructure | Positions for California and New York pharmaceutical stewardship law compliance through reverse logistics capabilities. |
| Automated Molding Scale Investment | Achieves throughputs exceeding 300 bottles per minute for screw-cap formats serving generic drug manufacturers. |
Research Methodology
A standing panel of pharmaceutical packaging procurement directors, regulatory affairs leads at converters, group purchasing organization formulary managers, and hospital pharmacy operations heads provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation against FDA 21 CFR filings, EMA Annex 1 guidance documents, EPA recycled content certifications, and state-level pharmaceutical stewardship legislation. Bottom-up volume modeling triangulated against top-down value estimates from trade data and industry association reports.
Scenario-bracketing framed analytical outputs across the projection horizon, with segmentation dimensions spanning product type, material barrier tier, closure mechanism, and end-use regulatory intensity. CAGRs derived from regression analysis of historical shipment data and forward-looking procurement survey responses. Forecast inputs incorporated oncology biologics pipeline expansion rates and generic drug approval timeline compression effects.
Macroeconomic conditions sit as an overlay; deviation in resin feedstock pricing, freight rates, or healthcare reimbursement policy would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory timeline stability and barrier technology substitution rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Snus Market
Others
North America Industrial Wearable Devices Market
Others
Automatic Barriers and Bollards Market
Others
Reef Aquarium Market
Others
Pin Mills Market
Others
Performance Testing Tools Market
Others
Europe Astrology Market
Others
High Frequency Vibrator Market
Others
India Home Automation Market
Others
Pollen Allergy Market
Others
North America Thermoformed Plastics Market
Others
Asia Pacific Cloud Infrastructure Testing Services Market
Others
Grna Market
Others
Smart-Connected Power Plug Socket Market
Others
Radiation Detection Monitoring and Safety Market
Others
Quadrant Scale Market