
 Mainframe Computers Market | 2026-2036
Mainframe Computers Market Size, Share, and Industry Trends Forecast 2026-2036
Mainframe Computers Market Insights
Banking sector demand is consolidating around mainframe modernization programs as financial institutions replace aging IBM zSystems while maintaining COBOL-dependent core applications. IBM sustains technology leadership through its z16 architecture with on-chip AI inferencing capabilities. Fujitsu differentiates via its BS2000 SE series targeting European public sector and banking clients. Broadcom extends software monetization across installed bases after acquiring mainframe tooling portfolios.
Mainframe computers are large-scale, high-availability server systems engineered for parallel transaction processing, featuring redundant hardware architectures, hardware-based encryption, and sub-millisecond I/O response times designed for mission-critical batch and online workloads. High-end systems dominate absolute revenue contribution due to million-dollar-plus unit pricing and multi-year service attach rates. Cloud-based deployment models represent the fastest-expanding configuration as enterprises adopt hybrid architectures linking on-premises zSystems with AWS, Azure, and IBM Cloud endpoints. Entry-level segments face margin compression from converged infrastructure alternatives and x86-based distributed systems.
US financial institutions navigate FFIEC examination standards and SEC cybersecurity disclosure rules that mandate resilient core processing infrastructure. European operators confront EBA operational resilience requirements and GDPR data localization constraints that favor on-premises or sovereign cloud mainframe configurations. Japanese banking regulators through FSA guidelines enforce end-of-life system migration timelines that accelerate replacement demand. Stakeholders must weigh hardware refresh cycles against software emulation paths as chip architecture transitions and energy efficiency mandates reshape total cost of ownership calculations.
Market Dynamics
Mainframe infrastructure decisions pivot on the tension between hardware refresh imperatives and software-defined abstraction layers. IBM's z16 architecture with on-chip AI inferencing and Fujitsu's BS2000 SE series create divergent modernization paths for financial institutions weighing total cost of ownership against regulatory compliance deadlines.
Growth Catalysts
- EU AI Act compliance mandates:European banking regulators require algorithmic transparency for credit-scoring systems, driving demand for mainframes with integrated AI governance and audit-ready transaction logs.
- COBOL application persistence:Core banking systems retain billions of lines of mission-critical COBOL code that resist cloud-native refactoring, preserving mainframe dependency for transaction integrity.
- Hardware-based encryption acceleration:On-chip cryptographic processors in modern zSystems satisfy FFIEC and EBA operational resilience requirements without performance degradation.
Market Restraints
- Specialized engineering talent scarcity:Universities have ceased COBOL and mainframe systems curricula, shrinking the labor pool for platform maintenance and modernization.
- Power and cooling cost escalation:Data center energy efficiency mandates in Germany and Japan impose carbon-adjusted operating cost penalties on legacy mainframe footprints.
- x86 cluster substitution:Distributed PostgreSQL and Kubernetes orchestration layers now handle mid-tier transaction volumes at fractionally lower capital intensity.
Strategic Opportunities
- Hybrid cloud orchestration layers:Mainframe-as-a-service integrations with AWS, Azure, and IBM Cloud endpoints enable workload portability without core system displacement.
- Indian banking modernization wave:RBI-mandated digital payment infrastructure upgrades create replacement demand among public sector banks with 1970s-era installed bases.
- Quantum-safe cryptography migration:NIST post-quantum standards adoption positions mainframe vendors to capture security refresh cycles ahead of 2030 compliance deadlines.
Industry Challenges
- Platform engineering skill attrition:Retirement waves among z/OS and BS2000 systems programmers outpace knowledge transfer to cloud-native DevOps teams.
- Multi-generational hardware interoperability:Peripheral device compatibility across three-decade system generations complicates phased modernization roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mainframe Computers Market |
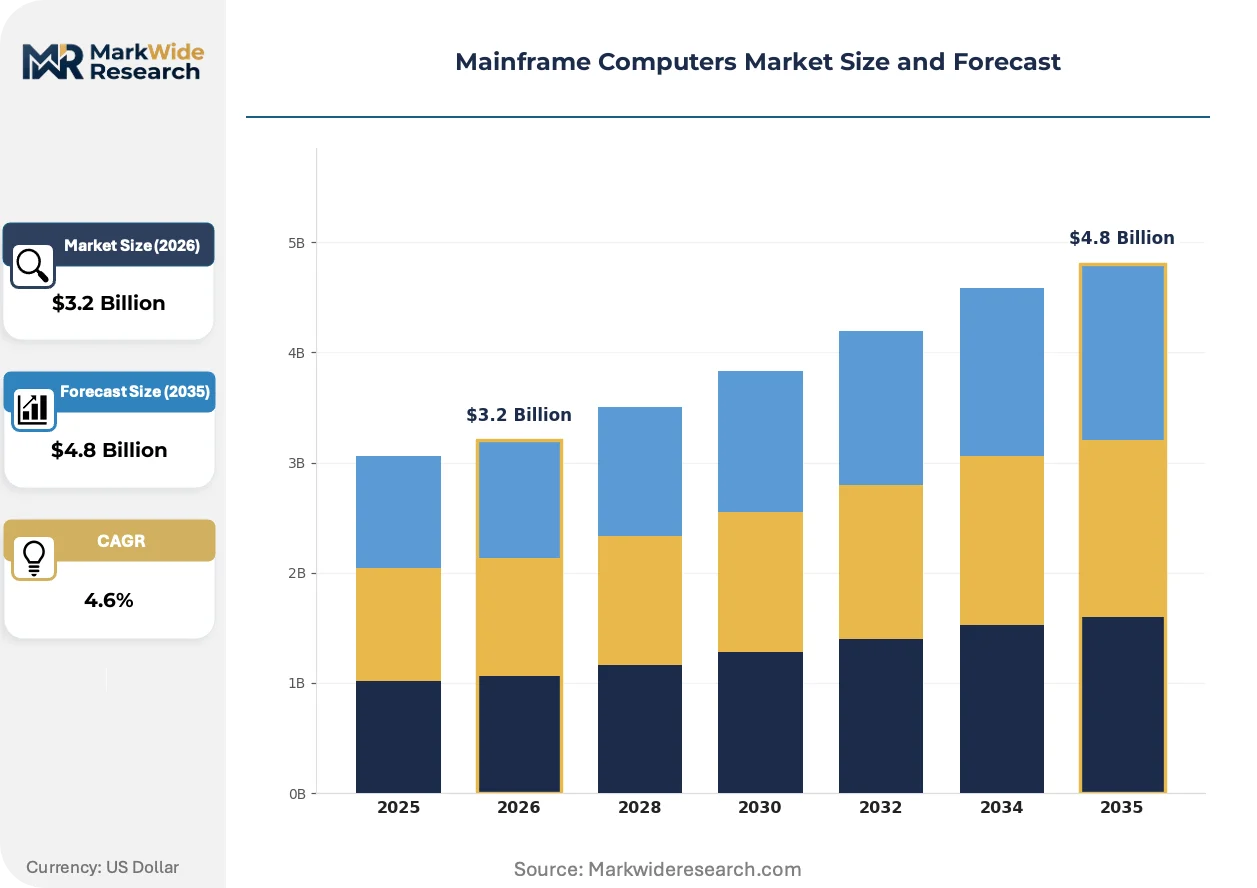
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $4.8 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Entry-Level, Mid-Range, High-End, Specialty Deployment Model: On-Premises, Virtualized, Hybrid, Cloud-Based Application: Transaction Processing, Data Warehousing, Analytics, Batch Processing End User: Government, Banking, Insurance, Telecommunications |
| Companies Covered | IBM, Unisys, Fujitsu, Hitachi, Atos, Broadcom, BMC Software, Dell Technologies, DXC Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mainframe Computers Market Trends and Innovations
Mainframe architecture is fragmenting into composable subsystems that decouple compute, memory, and I/O scaling from monolithic chassis constraints. This decomposition enables workload-specific configurations while preserving binary compatibility for legacy applications.
Containerized middleware stacks are modularizing traditional mainframe software delivery. Red Hat OpenShift on IBM zSystems allows financial services firms to deploy cloud-native microservices alongside CICS transaction monitors. German automotive banks and Japanese regional lenders pilot these hybrid runtimes to accelerate DevOps velocity without core system replacement. The approach is modularizing vendor lock-in assumptions by standardizing on Kubernetes control planes.
EU AI Act algorithmic accountability requirements are reshaping procurement specifications for credit-scoring and fraud-detection infrastructure. Article 10 mandates demand explainable AI with full audit trails, favoring mainframe platforms with integrated governance tooling over black-box cloud alternatives. French and Dutch banking supervisors now examine model lineage documentation during operational resilience assessments, pushing institutions toward on-premises inference engines with hardware-rooted trust chains.
Consumption-based capacity licensing is displacing perpetual entitlement models across installed bases. Broadcom's subscription pricing for mainframe software portfolios shifts capital expenditure to operational budgets, aligning vendor revenue with actual MIPS utilization. US credit unions and German Sparkassen increasingly favor this elasticity for seasonal payment processing peaks, though long-term total cost projections remain contested between procurement and infrastructure teams.
Mainframe Computers Market Segmentation
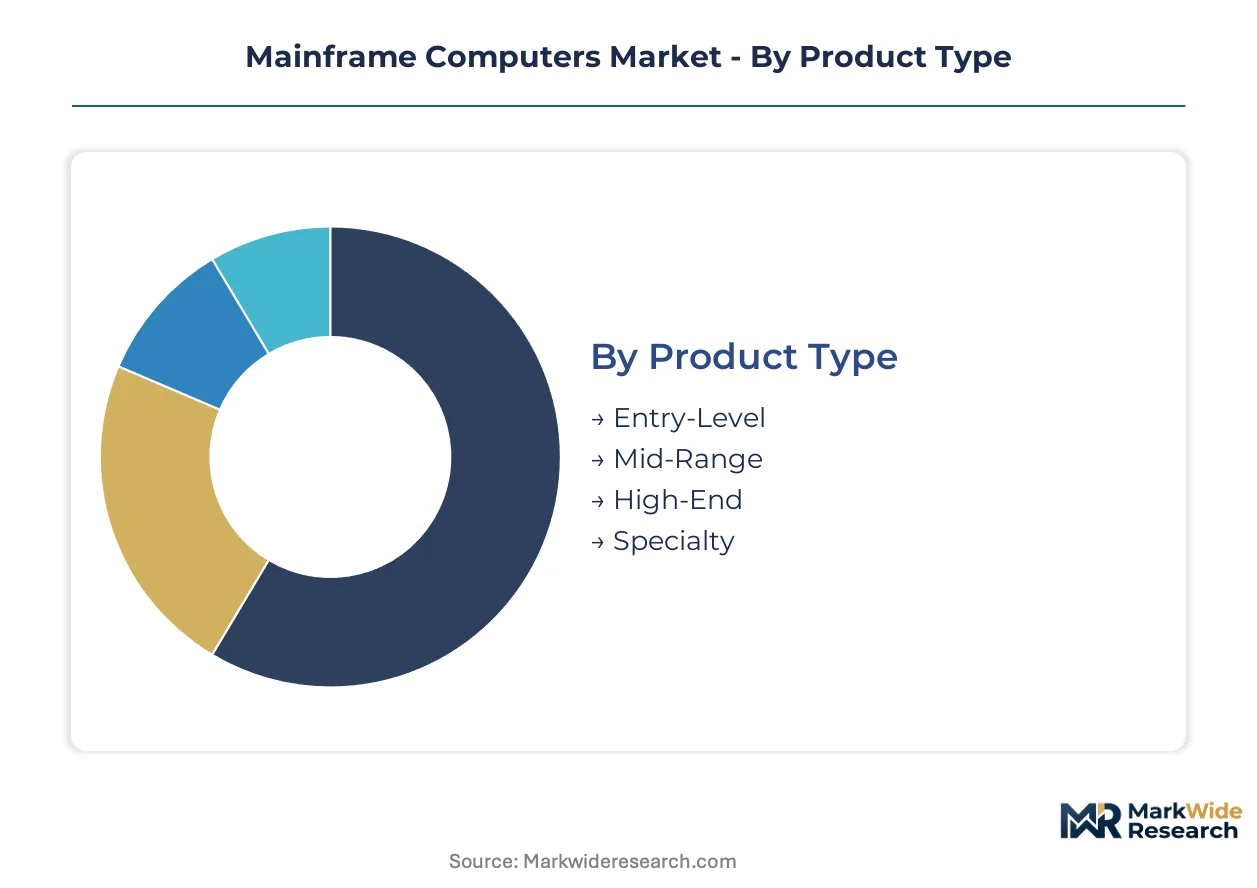
Mainframe segmentation reveals how workload characteristics and infrastructure maturity drive purchasing patterns. Procurement teams balance transaction volume requirements against data sovereignty mandates when selecting across product tiers and deployment configurations.
Product Type:
Entry-level systems serve discrete departmental workloads while high-end configurations anchor enterprise-wide core banking platforms.
- Entry-Level:Compact chassis designs target departmental transaction processing with sub-500 MIPS capacity. German Sparkassen and Japanese regional credit associations deploy these for branch-level payment authorization, constrained by power efficiency mandates in both jurisdictions.
- High-End:Million-dollar-plus systems feature redundant processor books and hardware-based encryption engines. US money-center banks and Indian public sector banks under RBI modernization directives represent concentrated demand for z16-class installations supporting billions of daily transactions.
- Mid-Range:Balanced compute-I/O configurations for mid-tier financial institutions transitioning from legacy z14 platforms.
- Specialty:Purpose-built variants with enhanced cryptographic modules for defense and intelligence agency workloads.
High-End leads volumes today; Cloud-integrated configurations are gaining share fastest.
Deployment Model:
Deployment choices reflect regulatory jurisdiction data localization requirements and capital expenditure flexibility preferences.
- Cloud-Based:Mainframe-as-a-service offerings through IBM Cloud and partner hyperscalers enable consumption-based capacity scaling. French banking groups under EU AI Act algorithmic accountability mandates favor these configurations for audit-ready infrastructure documentation.
- Hybrid:On-premises zSystems linked to AWS and Azure endpoints support burst workload portability. Japanese megabanks pilot these architectures under FSA cloud guidance frameworks for non-core application tiering.
- On-Premises:Traditional data center installations satisfying HIPAA and GDPR sovereignty requirements for primary transaction processing.
- Virtualized:Software-defined partitions enabling workload isolation across shared physical infrastructure.
On-Premises retains dominant installed base; Cloud-Based deployment climbs the fastest among new procurement decisions.
Application:
Application segmentation tracks how mainframe workloads partition between real-time transactional and analytical processing domains.
- Transaction Processing:CICS and IMS-based online systems handling payment authorization, securities settlement, and ATM networks. Core banking modernization in India and Brazil sustains replacement demand for COBOL-dependent OLTP platforms.
- Batch Processing:Nightly settlement runs, regulatory reporting, and end-of-period financial closes. German universal banks maintain these workloads for EBA stress test data compilation.
- Data Warehousing:Db2 and IMS hierarchical databases supporting longitudinal customer analytics.
- Analytics:zIIP-enabled inference engines for fraud detection and credit scoring under EU AI Act explainability requirements.
Transaction Processing commands absolute workload share; Analytics shows steepest expansion trajectory.
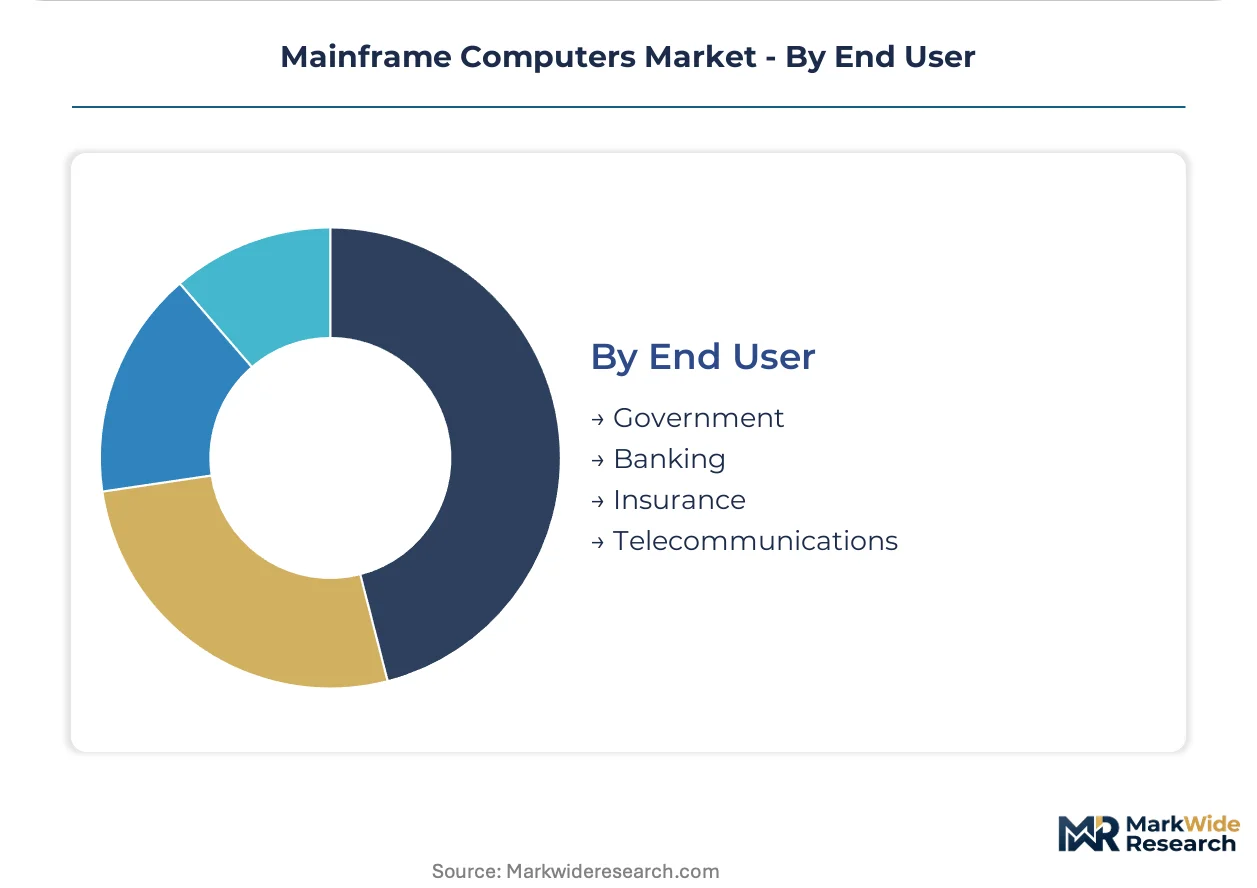
End User:
End-user segmentation reflects sector-specific regulatory intensity and legacy system replacement cycles.
- Banking:Universal banks, payment processors, and central securities depositories constitute the foundational demand base. US institutions navigate FFIEC examination standards while European operators confront EBA operational resilience deadlines.
- Government:Tax administration, social security, and defense agencies with multi-decade system longevity requirements. Japanese municipal governments and Indian state-level revenue departments represent active replacement markets.
- Insurance:Life and property-casualty carriers with actuarial batch processing and policy administration workloads.
- Telecommunications:Billing and customer care platforms for national operators with subscriber bases exceeding fifty million.
Banking dominates procurement volumes; Government vertical shows fastest policy-driven replacement activity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping mainframe procurement patterns as financial institutions migrate workloads toward jurisdictions with clearer data sovereignty frameworks and lower compliance friction. Cost-of-compliance gaps between the United States, Germany, and Japan are accelerating replacement cycles in markets with explicit operational resilience mandates.
United States
Money-center banks in New York and Chicago drive z16-class installations to satisfy FFIEC examination standards for core processing resilience. The SEC's cybersecurity disclosure rules mandate resilient infrastructure documentation, pushing institutions toward hardware-refresh programs rather than emulation paths. Texas data centers host expanding mainframe footprints as energy costs and tax incentives attract secondary site consolidation.
Germany
Sparkassen and universal banks in Frankfurt and Munich confront EBA operational resilience deadlines alongside GDPR data localization constraints that favor on-premises configurations. The EU AI Act's algorithmic transparency requirements for credit-scoring systems are steering procurement toward integrated AI governance platforms. Baden-Württemberg automotive banks pilot hybrid cloud orchestration layers to maintain audit-ready transaction logs.
Japan
Megabanks in Tokyo and Osaka navigate FSA guidelines enforcing end-of-life system migration timelines that compress replacement windows. Hardware-based encryption acceleration satisfies domestic financial regulator expectations for sub-millisecond payment authorization security. Nagoya regional credit associations deploy entry-level systems for branch-level transaction processing under municipal energy efficiency mandates.
India
Public sector banks in Mumbai and Delhi face RBI-mandated digital payment infrastructure upgrades that expose 1970s-era installed bases to modernization pressure. Data localization requirements under domestic privacy frameworks favor sovereign cloud mainframe configurations for core banking platforms. Bangalore technology centers are emerging as hybrid integration hubs linking on-premises zSystems to hyperscaler endpoints.
United Kingdom
Clearing banks in London balance post-Brexit regulatory divergence with continued EBA-aligned operational resilience expectations for euro-denominated transaction processing. The Prudential Regulation Authority's operational continuity requirements sustain demand for high-availability mainframe configurations in the City and Canary Wharf. Edinburgh financial services clusters are evaluating containerized middleware stacks to accelerate DevOps velocity without core displacement.
Mainframe Computers Market Competitive Landscape
Portfolio consolidation through targeted software acquisitions dominates the current landscape as vendors seek recurring revenue attach rates across installed bases. The vendor structure concentrates around three strategic archetypes: full-stack hardware-software integrators, specialized software monetizers, and regional platform specialists. Technology licensing agreements and consumption-based pricing transitions represent the dominant competitive vectors reshaping customer relationships.
Within the full-stack integrator tier, IBM and Fujitsu exemplify divergent modernization philosophies for financial institutions weighing total cost of ownership. IBM occupies a position anchored in zSystems architecture with on-chip AI inferencing capabilities, while Fujitsu represents European public sector and banking specialization through its BS2000 SE series. Broadcom sits within the software monetization archetype, extending subscription pricing across mainframe tooling portfolios acquired through prior consolidation waves.
| Leading Market Players |
|---|
| IBM |
| Unisys |
| Fujitsu |
| Hitachi |
| Atos |
| Broadcom |
| BMC Software |
| Dell Technologies |
| DXC Technology |
| Others |
Pricing and Supply Chain Analysis
High-end z16-class installations and entry-level departmental systems diverge sharply in procurement economics, with million-dollar-plus configurations commanding multi-year service attach rates while compact chassis face margin compression from converged infrastructure alternatives. This bifurcation concentrates supply chain leverage among full-stack integrators for premium tiers while commoditized segments draw from distributed x86 component ecosystems.
Pricing Analysis
Distributor margins for mainframe software portfolios typically run 15-25 percent, with direct-to-OEM hardware arrangements commanding steeper discounts for volume commitments. Subscription-based capacity licensing is displacing perpetual entitlements across installed bases, shifting capital expenditure to operational budgets aligned with actual MIPS utilization. Price differentiation rests on encryption certification tiers and after-sales service bundling rather than raw compute specifications. Cost compression in entry-level segments is intensifying because German and Japanese energy efficiency mandates impose carbon-adjusted operating penalties. Regional credit associations and departmental users exhibit highest price sensitivity, while money-center banks under FFIEC examination standards prioritize resilience over unit economics.
Supply Chain Analysis
Freight costs for mainframe chassis and processor books remain modest relative to unit value, though specialized cooling infrastructure and raised-floor data center construction create significant logistics complexity for site deliveries. Component manufacturing concentrates in the United States, Japan, and Germany, with custom processor fabrication anchored in IBM's New York facilities and Fujitsu's Kawasaki operations. Raw material dependencies include high-purity silicon wafers, advanced ceramic substrates for multi-chip modules, and specialized alloy heat spreaders. Single-source vulnerability for proprietary processor architectures represents the dominant structural risk. Distribution runs through direct vendor sales organizations and certified systems integrators serving financial services verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mainframe infrastructure functions as a stable compounder where regulatory compliance mandates create predictable replacement cycles across banking and government verticals. The analysis frames steady growth driven by operational resilience requirements that resist cloud-native displacement.
For Market Incumbents: Anticipate retirement waves among z/OS and BS2000 systems programmers by accelerating automated tooling deployment and knowledge-capture platforms. Defensive consolidation around software monetization portfolios captures recurring revenue attach rates as hardware refresh cycles lengthen. Capacity addition in Indian public sector banks under RBI modernization directives secures replacement demand against x86 cluster substitution threats. For New Entrants and Emerging Players: Capture white-space opportunity in containerized middleware orchestration layers that modularize traditional mainframe software delivery. The most penetrable segment lies among German automotive banks and Japanese regional lenders piloting hybrid runtimes to accelerate DevOps velocity. A go-to-market angle anchored in EU AI Act algorithmic accountability tooling addresses explainable AI mandates with hardware-rooted trust chains. For Investors and Strategic Acquirers: Consolidation pressure builds where software tooling portfolios fragment across legacy installed bases and subscription pricing transitions create recurring revenue visibility. Long-term viability over a five-to-ten year window favors vendors with hybrid cloud integration capabilities that preserve binary compatibility for COBOL-dependent workloads. Acquisition target archetypes include specialized mainframe DevOps tooling firms and regional systems integrators with banking sector relationships. The signal to watch is quantum-safe cryptography migration timelines ahead of NIST post-quantum standards adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Cloud Integration | Links on-premises zSystems to AWS, Azure, and IBM Cloud endpoints for workload portability. |
| AI Governance Platform Development | Satisfies EU AI Act Article 10 mandates for explainable credit-scoring with audit-ready transaction logs. |
| Subscription Pricing Transition | Aligns vendor revenue with actual MIPS utilization across US credit unions and German Sparkassen. |
| Quantum-Safe Cryptography Migration | Positions vendors to capture security refresh cycles ahead of NIST post-quantum compliance deadlines. |
| Containerized Middleware Deployment | Enables Red Hat OpenShift on IBM zSystems for cloud-native microservices alongside CICS monitors. |
Research Methodology
Coverage spans the United States, Germany, Japan, India, and the United Kingdom, with primary inputs from each regional banking hub. The analysis combines structured interviews with mainframe systems architects, data center infrastructure directors, regulatory compliance officers, and financial services procurement leads with secondary validation from SEC filings, EBA operational resilience guidelines, FSA cloud guidance frameworks, and RBI circulars on digital payment infrastructure. Bottom-up triangulation across hardware shipment data and top-down reconciliation against installed base estimates ensures cross-verified outputs.
Granularity-level modeling disaggregates the analysis window by product tier, deployment configuration, application workload, and end-user vertical, with additional dimensioning across regional regulatory clusters and MIPS capacity bands. CAGRs derive from logistic growth curve fitting anchored to replacement cycle timing and compliance deadline clustering. Industry-specific forecast inputs include COBOL application persistence rates and energy efficiency mandate enforcement trajectories in Germany and Japan.
Chip architecture transition timelines, regulatory enforcement variance across jurisdictions, and talent pool attrition rates are the dominant revision risks to modeled projections. Forecasts reflect assumptions about sustained regulatory pressure for on-premises transaction processing sovereignty. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Griffin Beaker Market
Others
Folding Screen Mobile Phone Market
Others
Port Replicator Market
Others
Paper Shredder Market
Others
Global Contactless Biometrics Technology Market
Others
Digital Audio Decoders Market
Others
Smart Home Technologies Market
Others
Coloring Apps Market
Others
Medical Simulation Market
Others
Construction Wearables Market
Others
Global Electronic Filters Market
Others
Digital LUX Meter Market
Others
UK 3D Printing Construction Market
Others
Asia-Pacific Legal Services Market
Others
Photo Booth/Kiosk Market
Others
Middle East and Africa Induced Pluripotent Stem Cells (Ipscs) Market