
 Cloud Digital Video Recorder Market | 2026-2036
Cloud Digital Video Recorder Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Digital Video Recorder Market Outlook
Enterprise video archiving is restructuring how organizations approach content retention and retrieval. Comcast Corporation leverages its cable infrastructure to dominate hybrid cloud DVR deployments for media workflows. Google LLC anchors its position through deep API integration with YouTube's live streaming backend. Amazon Web Services competes aggressively on storage density pricing for long-form archived footage.
A Cloud Digital Video Recorder is a network-hosted system that ingests, stores, and replays video content via remote server infrastructure, typically employing H.265/HEVC compression and redundant object storage architectures to ensure sub-second seek latency across distributed edge nodes. Its primary commercial purpose is to replace on-premises tape and disk-based recording with elastic, remotely accessible retention for broadcast, surveillance, and enterprise communications. Public cloud deployments capture the bulk of current revenue as media companies prioritize OpEx flexibility over capital-intensive private infrastructure. On-demand content segments within the content type dimension generate disproportionate margin pools due to higher per-gigabyte monetization through subscription and advertising models.
FCC guidelines in the United States govern signal carriage obligations that directly shape cloud DVR feature sets, while GDPR and the EU AI Act in Europe impose strict data localization and automated content analysis constraints on cross-border video storage. Japan's METI promotes cloud migration through standards harmonization that eases vendor certification for foreign platform providers. Stakeholders must monitor evolving encryption mandates and territorial licensing frameworks as these regulations increasingly determine which deployment models gain operational clearance in priority markets.
Market Dynamics
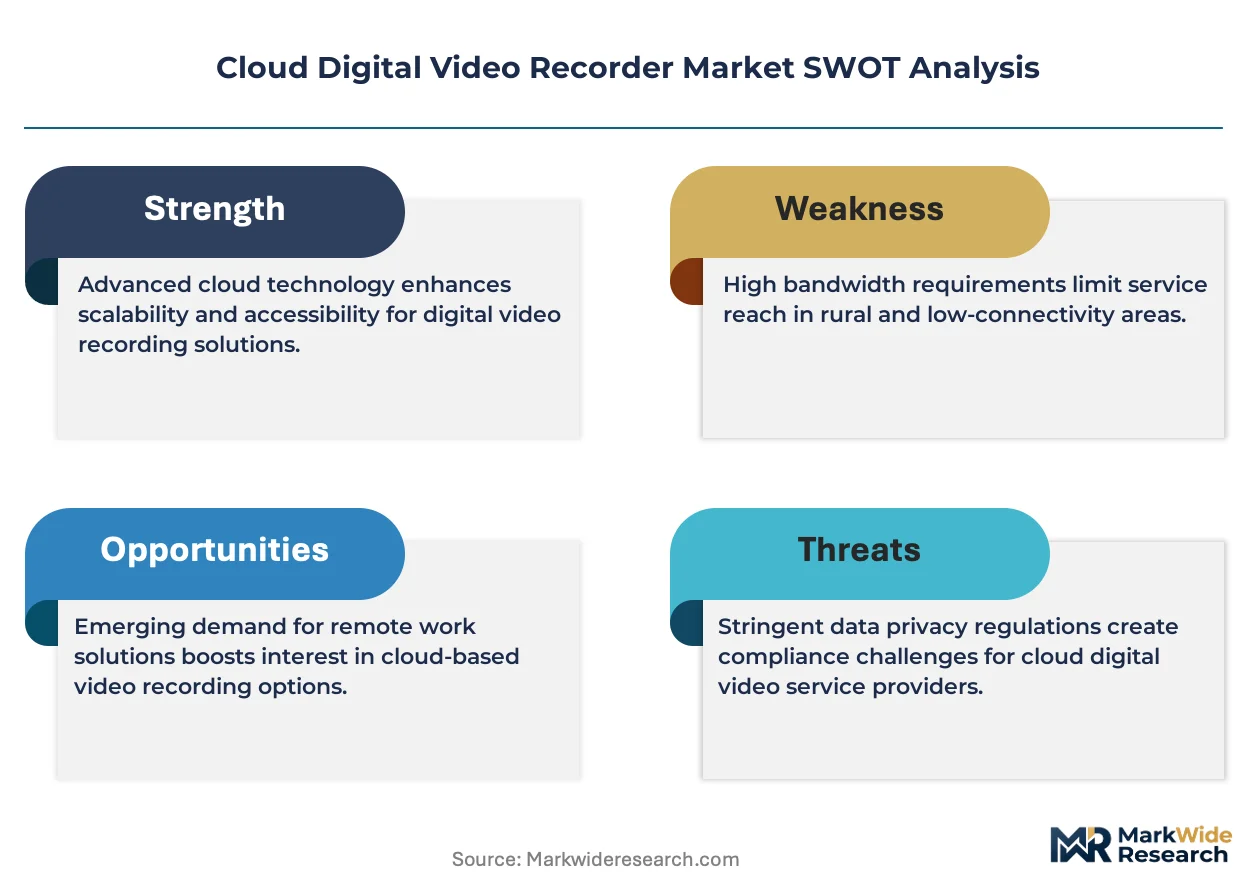
Enterprise migration from tape-based archives to elastic cloud storage is compressing procurement cycles and forcing vendors to reprice per-gigabyte retention around GDPR compliance costs rather than raw infrastructure economics.
Growth Catalysts
- EU AI Act compliance mandates:Automated content analysis requirements in Europe are accelerating demand for cloud DVR platforms with embedded metadata tagging and territorial data localization.
- H.265/HEVC compression maturation:Broadcasters in Germany and Japan are replacing MPEG-2 infrastructure to reduce bandwidth costs for 4K live streaming workflows.
- Surveillance retention mandates:Corporate security departments face extended video archiving requirements, pulling cloud DVR capacity into enterprise IT procurement frameworks.
Market Restraints
- Cross-border data friction:GDPR territorial licensing constraints block seamless replication of archived content between EU and non-EU cloud regions, fragmenting vendor operational scale.
- Edge node capex concentration:Sub-second seek latency requirements force providers to over-provision distributed storage in expensive metropolitan colocation facilities.
- Quantum encryption uncertainty:Long-form archival customers hesitate on 10-year retention contracts due to unresolved post-quantum cryptographic standardization timelines.
Strategic Opportunities
- India enterprise communications:TRAI cloud migration incentives and underpenetrated SME video conferencing archives offer first-mover positioning for compliant platform entrants.
- Healthcare diagnostic imaging convergence:Cloud DVR architectures are absorbing DICOM-compliant medical video streams, opening adjacent revenue pools beyond broadcast and surveillance.
- Subscription unbundling:Tiered retention pricing is displacing flat-rate enterprise contracts, enabling margin capture from high-velocity news and sports content producers.
Industry Challenges
- Legacy tape migration complexity:Petabyte-scale broadcast archives require specialized ingest pipelines that cloud DVR vendors must build as custom professional services rather than standardized SaaS.
- Multi-cloud orchestration talent scarcity:Engineering teams capable of optimizing storage tiering across AWS, Azure, and Google Cloud simultaneously command premium compensation, compressing vendor gross margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Digital Video Recorder Market |
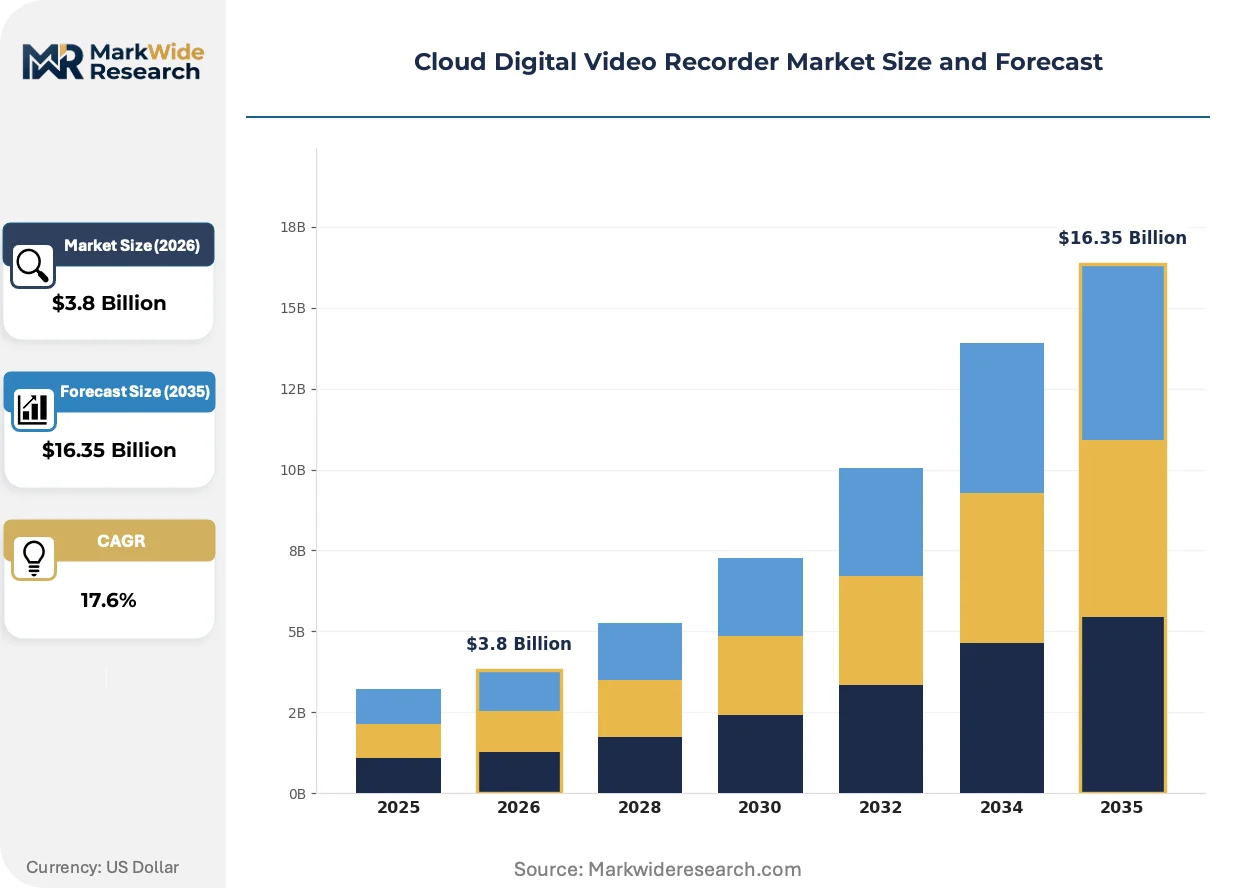
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $16.35 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud End User: Media Companies, Educational Institutions, Corporate Sector, Healthcare Facilities Content Type: Live Streaming, On-Demand Content, Recorded Footage, Archived Video Integration Level: API Integrations, SDK Support, Third-Party Services, Custom Solutions |
| Companies Covered | Comcast Corporation, AT&T Inc., Verizon Communications Inc., EchoStar Corp., Cisco Systems Inc., Google LLC, Amazon Web Services, TiVo Corporation, Synamedia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Digital Video Recorder Market Strategic Shifts
Compression efficiency gains and sovereignty-driven data localization are forcing platform architects to redesign storage hierarchies around regulatory boundaries rather than pure latency optimization.
AI-powered content indexing is electrifying archive searchability by automatically generating scene-level metadata during ingestion. Media companies in the United States are deploying these tools for rapid clipping of live sports broadcasts into social-optimized segments. The technology is compressing editorial turnaround from hours to minutes, reshaping monetization velocity for rights holders.
GDPR Article 17 right-to-erasure enforcement is mandating granular deletion capabilities within cloud DVR platforms that traditional broadcast infrastructure never required. Vendors must now engineer segment-level purge functions without corrupting adjacent archived content. European media enterprises are absorbing 15-20% storage overhead penalties to maintain compliant audit trails.
Consumption patterns among enterprise buyers are fragmenting procurement authority between CIO-led IT departments and CMO-led content operations teams. Cloud DVR vendors now face dual stakeholder sales cycles with conflicting technical requirements: IT demands encryption key custody while marketing prioritizes API flexibility for creative tool integration. This bifurcation is most pronounced in Japan, where METI standards harmonization has accelerated vendor certification but not simplified internal enterprise decision-making.
Cloud Digital Video Recorder Market Segmentation
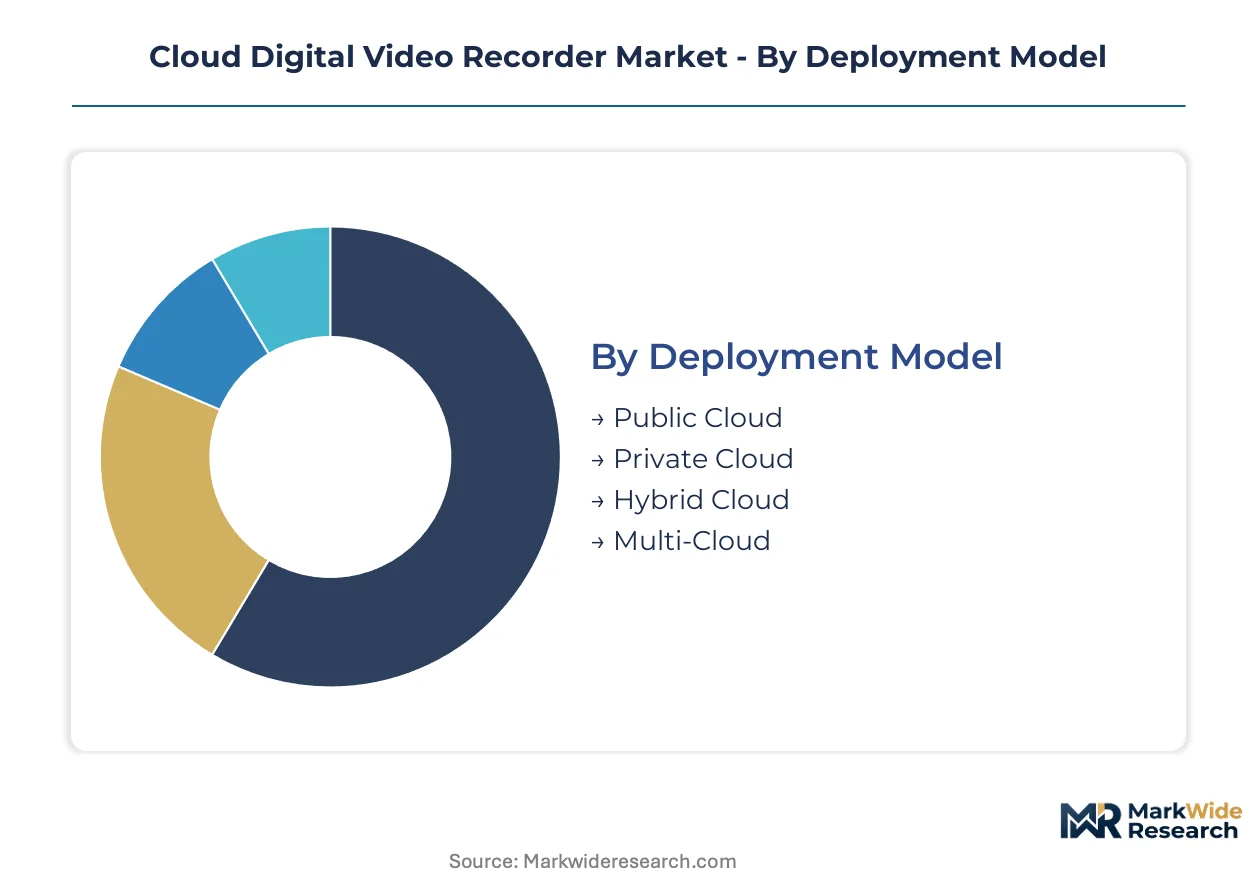
Cloud DVR procurement patterns diverge sharply across deployment models and integration requirements, with GDPR compliance costs and H.265 compression maturation driving divergent buyer priorities. Understanding these segment boundaries clarifies where platform vendors must engineer specialized capabilities versus standardized offerings.
Deployment Model:
Buyer risk tolerance and data sovereignty obligations determine deployment selection more than raw infrastructure economics.
- Public Cloud:Shared infrastructure delivers elastic capacity with OpEx pricing, attracting media companies prioritizing rapid scaling for live sports broadcasts. Demand concentrates in the United States where FCC signal carriage rules align with commercial cloud availability zones.
- Private Cloud:Dedicated tenant environments enforce territorial data boundaries required by GDPR Article 44 cross-border transfer restrictions. Healthcare facilities in Germany specify these deployments for diagnostic imaging archives subject to EU AI Act automated analysis constraints.
- Hybrid Cloud:Split architectures retain hot content at edge nodes while archiving cold footage to centralized pools. Corporate security departments leverage this model to balance sub-second surveillance retrieval against decade-long retention mandates.
- Multi-Cloud:Orchestrated replication across AWS, Azure, and Google Cloud mitigates vendor lock-in for enterprise buyers negotiating storage tiering contracts. Japan's METI standards harmonization has accelerated certification of foreign providers enabling this approach.
Volume sits with Public Cloud; growth tilts toward Hybrid Cloud as sovereignty requirements harden.
End User:
Procurement authority fragmentation between IT and content operations teams reshapes vendor sales cycles across buyer categories.
- Media Companies:Broadcasters and streaming platforms demand API flexibility for creative tool integration alongside encryption key custody for rights-protected content. These buyers generate the highest per-gigabyte monetization through advertising and subscription models.
- Corporate Sector:Enterprise security departments absorb cloud DVR capacity into IT procurement frameworks, prioritizing metadata tagging for automated incident review. Extended retention mandates from insurers are pulling budget from on-premises tape systems.
- Educational Institutions:Universities require lecture capture with searchable transcripts, driving demand for AI-powered content indexing during ingestion. Budget constraints favor multi-year archive contracts with predictable egress pricing.
- Healthcare Facilities:DICOM-compliant video streams from surgical suites and diagnostic equipment are converging with cloud DVR architectures. METI standards in Japan have eased vendor certification for medical device integration.
Revenue concentrates with Media Companies; expansion accelerates fastest in Healthcare Facilities as diagnostic imaging requirements converge.
Content Type:
Monetization velocity and compression efficiency requirements segment buyer technical specifications.
- On-Demand Content:Pre-produced libraries generate disproportionate margin pools through subscription bundling and targeted advertising insertion. Germany's broadcasters are migrating MPEG-2 catalogs to H.265 to reduce bandwidth costs for 4K delivery.
- Live Streaming:Real-time ingestion with sub-second latency demands edge node concentration in metropolitan colocation facilities. Sports rights holders in the United States deploy AI clipping tools to compress editorial turnaround for social distribution.
- Recorded Footage:Surveillance and corporate communications archives prioritize storage density pricing over retrieval speed. GDPR Article 17 erasure mandates require segment-level purge capabilities without adjacent content corruption.
- Archived Video:Petabyte-scale broadcast libraries necessitate specialized ingest pipelines as custom professional services rather than standardized SaaS. Quantum encryption uncertainty stalls 10-year retention contract commitments.
Margin pools concentrate in On-Demand Content; technical innovation focuses on Live Streaming workflows.
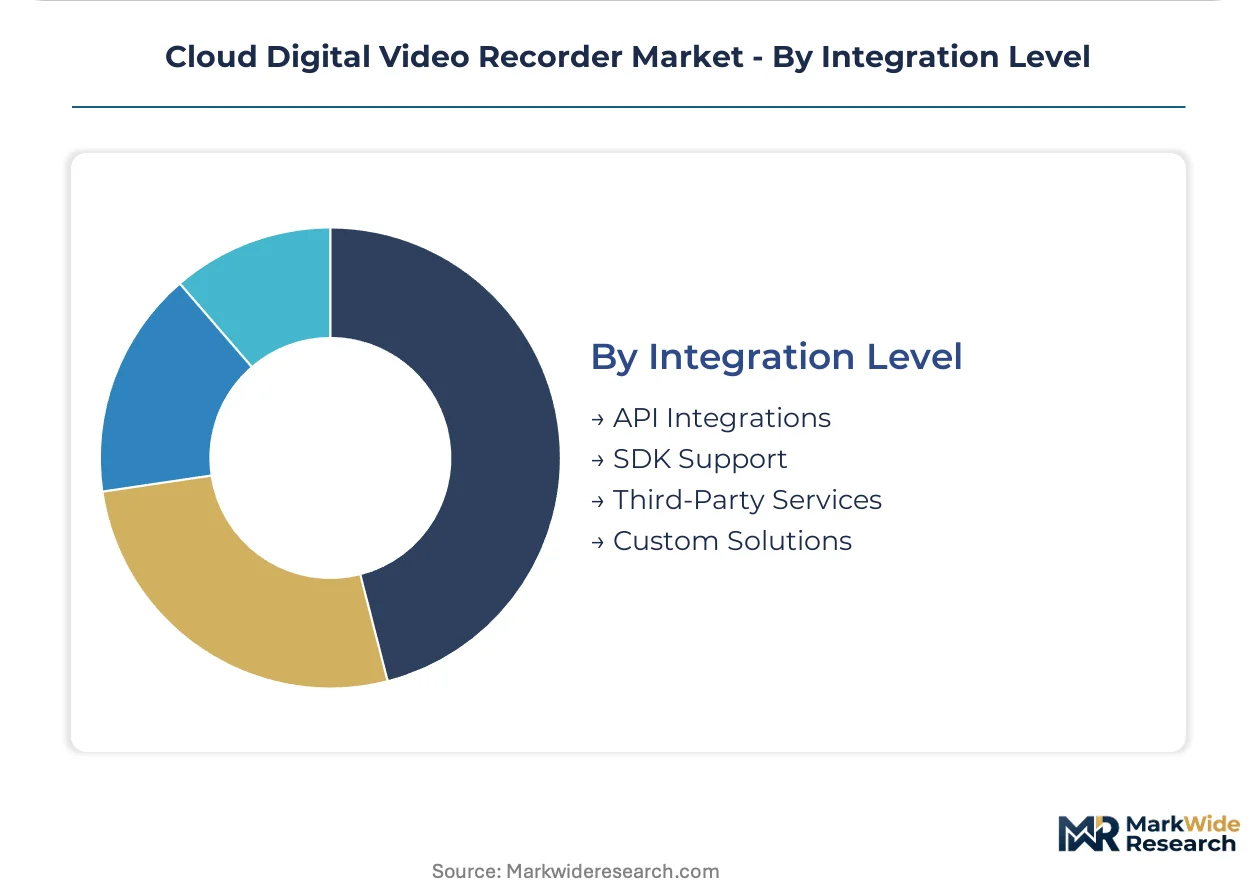
Integration Level:
Engineering team capabilities and existing software investments determine integration depth preferences.
- API Integrations:RESTful endpoints enable connectivity with YouTube, Vimeo, and proprietary content management systems. Google LLC anchors platform positioning through deep backend integration with live streaming infrastructure.
- SDK Support:Native client libraries accelerate embedded player development for iOS, Android, and smart TV applications. Educational institutions leverage these toolkits for custom lecture capture interfaces.
- Third-Party Services:Pre-built connectors for Adobe Creative Cloud, Salesforce, and ServiceNow reduce implementation timelines. Corporate buyers prioritize these when procurement authority sits with CMO-led operations teams.
- Custom Solutions:Bespoke engineering addresses legacy tape migration complexity and specialized compliance workflows. Vendors price these engagements as professional services with margin compression from multi-cloud orchestration talent scarcity.
Deployment volume favors API Integrations; SDK Support climbs fastest as mobile-first consumption patterns harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Shenzhen and Dubai Internet City concentrate cloud infrastructure investment through tax holidays and data center land grants. These zones attract hyperscaler partnerships that anchor regional cloud DVR capacity expansion. Regulatory harmonization programs accelerate vendor certification timelines.
United States
FCC signal carriage obligations drive hybrid cloud DVR deployments for broadcast workflows. The IRA's clean energy credits reduce power costs for hyperscale data centers in Northern Virginia. Dallas-Fort Worth hosts edge node concentration for sub-second latency sports streaming.
Germany
GDPR Article 44 cross-border transfer restrictions mandate private cloud architectures for healthcare diagnostic imaging. The EU AI Act's automated content analysis rules reshape metadata tagging requirements. Munich's media cluster absorbs H.265 compression upgrades for 4K broadcast migration.
Japan
METI standards harmonization eases foreign vendor certification for enterprise video conferencing archives. The country's national pharmaceutical regulator extends retention mandates for surgical suite recordings. Tokyo-Osaka corridor concentrates multi-cloud orchestration talent for storage tiering optimization.
India
TRAI cloud migration incentives pull SME video conferencing archives toward compliant platform entrants. BIS certification requirements for data localization reshape vendor partnership structures. Bangalore's technology cluster absorbs AI-powered content indexing deployments for educational lecture capture.
United Kingdom
Post-Brexit data adequacy negotiations fragment cross-border replication architectures with EU cloud regions. The country's national pharmaceutical regulator enforces diagnostic imaging retention standards converging with cloud DVR specifications. London's broadcast district anchors subscription unbundling experiments for tiered retention pricing.
Cloud Digital Video Recorder Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with hyperscalers dominating public cloud volume while systems integrators capture hybrid deployment professional services. The vendor base concentrates around three strategic archetypes: cable infrastructure operators leveraging last-mile networks, cloud-native platforms competing on API depth, and broadcast technology incumbents with legacy tape migration expertise. Competitive moves center on multi-cloud orchestration partnerships and sovereignty-compliant data center joint ventures.
Among cable infrastructure operators, Comcast Corporation and EchoStar Corp. occupy positions anchored in subscriber-facing video service bundling. Google LLC and Amazon Web Services exemplify the cloud-native archetype through deep platform integration and storage density pricing. Cisco Systems Inc. sits within the broadcast technology tier, representing legacy enterprise networking convergence with video archiving workflows.
| Leading Market Players |
|---|
| Comcast Corporation |
| AT&T Inc. |
| Verizon Communications Inc. |
| EchoStar Corp. |
| Cisco Systems Inc. |
| Google LLC |
| Amazon Web Services |
| TiVo Corporation |
| Synamedia |
| Others |
Value Chain & Pricing Dynamics
DRAM spot price indices cascade through server infrastructure procurement, compressing margin pools for cloud DVR vendors who must absorb memory cost volatility while maintaining flat-rate enterprise contracts across GDPR-compliant storage tiers.
Pricing Analysis
Short lead-time premiums for H.265/HEVC encoder hardware separate urgent broadcast upgrades from standard procurement cycles. Three-tier pricing structure across premium, standard, and economy levels stratifies by encryption key custody depth and API integration complexity. Price differentiation centers on territorial data localization certification, with GDPR Article 44 compliant private cloud deployments commanding substantial uplifts over shared infrastructure. Cost compression in public cloud storage tiers is intensifying because hyperscalers are reprising per-gigabyte rates around energy density improvements in Northern Virginia data centers. Corporate security departments exhibit highest price sensitivity due to extended retention mandates stretching IT procurement frameworks, while media companies prioritize API flexibility over unit economics.
Supply Chain Analysis
Returns and refurbishment flows for edge node servers concentrate in Taiwan and South Korea, where original equipment manufacturers maintain captive remanufacturing facilities for hyperscaler account servicing. Component sourcing draws from Chinese rare earth processing for magnetic storage substrates, Japanese precision optics for encoder modules, and German industrial controls for automated tiering systems. Single-source vulnerability in H.265/HEVC codec licensing from patent pool administrators creates royalty rate uncertainty for platform vendors. Distribution runs through direct hyperscaler partnerships for public cloud capacity, systems integrator channels for hybrid deployments, and value-added resellers for healthcare and education verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over encoder hardware supply and edge node real estate determines pricing power. Backward integration into H.265/HEVC silicon design represents the decisive upstream lever separating margin leaders from commodity storage providers.
For Market Incumbents: Cement hybrid cloud dominance through exclusive edge node leases in Dallas-Fort Worth and Tokyo-Osaka corridors, blocking entrant access to sub-second latency sports streaming workflows. Deepen API integration moats with YouTube and Vimeo backend systems to raise switching costs for media company accounts. Multi-cloud orchestration talent scarcity threatens operational scale; acquire specialized engineering teams in Bangalore and Munich before compensation inflation erodes gross margins.
For New Entrants and Emerging Players: The premium-to-economy pricing gap in Indian SME video conferencing archives offers immediate white-space capture under TRAI cloud migration incentives. Target healthcare diagnostic imaging convergence in Germany where GDPR Article 44 restrictions disqualify incumbent public cloud architectures. Pursue SDK-first go-to-market positioning for educational lecture capture in Japan, leveraging METI standards harmonization to bypass certification barriers that slow hyperscaler entry.
For Investors and Strategic Acquirers: Distressed-cycle entries favor broadcast technology incumbents with legacy tape migration expertise in the United States, where petabyte-scale ingest pipelines require professional services capabilities no cloud-native platform has replicated. Long-term viability over the next decade hinges on quantum-encryption-ready archival infrastructure as post-quantum standardization resolves. Monitor EU AI Act enforcement patterns for automated content analysis mandates as the inflection signal determining which metadata-tagging platforms achieve regulatory clearance.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Cloud Orchestration Partnership | Storage tiering optimization across AWS, Azure, and Google Cloud mitigates vendor lock-in for enterprise procurement. |
| Sovereignty-Compliant Data Center Joint Venture | German private cloud deployments satisfy GDPR Article 44 cross-border transfer restrictions for healthcare imaging archives. |
| AI-Powered Content Indexing Acquisition | Scene-level metadata generation during ingestion compresses editorial turnaround for US sports rights holders. |
| Edge Node Concentration Expansion | Metropolitan colocation facilities in Dallas-Fort Worth enable sub-second latency for live streaming workflows. |
| Legacy Tape Migration Service Buildout | Petabyte-scale broadcast archives require specialized ingest pipelines as custom professional services engagements. |
Study Parameters
Independent corroboration across cloud infrastructure executives, broadcast technology procurement leads, enterprise IT security officers, and healthcare biomedical engineers underwrites the qualitative findings. Primary interviews with hyperscaler storage product managers, systems integrator solution architects, and educational technology directors combined with secondary validation from SEC hyperscaler capex disclosures, FCC signal carriage rulemakings, and EMA regulatory guidance. Bottom-up triangulation across deployment model adoption curves and top-down cross-checks against territorial data localization expenditure patterns anchored volume and value estimates.
Rate-of-change decomposition across the analysis window isolated compression efficiency gains, sovereignty-driven infrastructure repricing, and AI indexing penetration as discrete growth drivers. Segmentation dimensions modeled include deployment model, end user vertical, content type monetization velocity, and integration complexity tier. CAGRs derived from logistic diffusion curves fitted to early-adopter penetration benchmarks in the United States, Germany, and Japan. Forecast inputs incorporated H.265/HEVC encoder shipment trajectories and GDPR enforcement cost absorption rates reported by European media enterprises.
Inputs from hyperscaler financial disclosures and regulatory filing databases were available through the study window; gaps in private cloud pricing transparency for healthcare diagnostic imaging introduce uncertainty bands around German market estimates. Forecasts reflect documented assumptions regarding EU AI Act implementation timelines and post-quantum cryptographic standardization progress. Practitioners should monitor TRAI cloud migration incentive disbursement rates and METI foreign vendor certification velocity for early signals of geographic demand shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Wood Stoves Market
Others
Pollen Allergy Market
Others
Calendered Polyvinyl Chloride Flexible Films Market
Others
Embedded Computer Market
Others
Massive Machine Type Communication in Healthcare Market
Others
Global Virtual Keyboard Market
Others
Global Car Wax Market
Others
Middle East Location-Based Services Market
Others
Digital Mortgage Software Market
Others
India 3D Printing Construction Market
Others
Snus Market
Others
Global Military and Aerospace Sensors Market
Others
China Smart Home Market
Others
Software Synthesizers Market
Others
Propanil Market
Others
Manometers Market