
 Iran Commercial Vehicles Lubricants Market | 2026-2036
Iran Commercial Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Iran Commercial Vehicles Lubricants Market Foresight
The gap between API CK-4 synthetic formulations and mineral-based CI-4 products is consolidating as fleet procurement teams tighten total cost of ownership calculations. Iranol Oil Company leverages captive refinery access to anchor its position in base oil supply. Sepahan Oil Company competes through specialized distribution networks serving provincial transport cooperatives. FUCHS differentiates by concentrating on hydraulic oil specifications for construction-linked commercial fleets.
Iran commercial vehicles lubricants comprise formulated oils and functional fluids engineered with viscosity grades typically spanning SAE 15W-40 to 10W-30, incorporating detergent-dispersant packages to manage soot loading in diesel combustion environments. These products reduce friction wear, extend drain intervals, and protect after-treatment systems in high-utilization powertrains. Engine oil holds the dominant volume position given mandatory crankcase replenishment cycles across heavy-duty truck applications. Transmission fluid represents the fastest-growing category as automated manual transmissions penetrate Iranian bus and long-haul segments. Gear oil maintains stable demand tied to differential and axle service intervals in vocational vehicle pools.
The National Iranian Oil Refining and Distribution Company enforces domestic blending standards that shape product formulation requirements for local manufacturers. Iran's national standards body aligns lubricant specifications with regional thermal operating conditions and sulfur-content diesel fuel profiles. Stakeholders must monitor how sanctions-evading import channels affect additive package availability and whether domestic base oil output can match fleet operator expectations for extended drain intervals.
Market Dynamics
Fleet operators across Iran's Tehran-Mashhad logistics corridor are recalibrating lubricant procurement around total cost of ownership metrics as domestic base oil quality improves and drain interval expectations lengthen.
Growth Catalysts
- API CK-4 formulation mandates:The National Iranian Oil Refining and Distribution Company's updated blending standards are pulling fleet operators toward higher-performance synthetics that protect after-treatment systems in modern diesel powertrains.
- Tehran-Mashhad corridor density:Heavy-duty truck concentration along this 900-kilometer route generates concentrated bulk demand for engine oil replenishment cycles.
- Automated manual transmission penetration:Iranian bus and long-haul segments are expanding transmission fluid volumes as AMT hardware displaces conventional manual gearboxes.
Market Restraints
- Additive package import dependency:Sanctions-evading channels constrain detergent-dispersant availability, forcing blenders to reformulate around supply interruptions.
- Sulfur-content diesel incompatibility:High-sulfur domestic fuel accelerates lubricant degradation, compressing effective drain intervals below synthetic oil theoretical limits.
- Base oil quality variance:Inconsistent Group II output from Iranian refineries limits extended-drain product consistency for premium fleet contracts.
Strategic Opportunities
- Khorasan province logistics expansion:Mashhad-centered distribution cooperatives present underpenetrated channels for specialized hydraulic oil servicing construction-linked commercial fleets.
- Group III base oil investment:Captive refinery upgrades would enable domestic synthetic formulation matching regional thermal operating conditions without import exposure.
- Bus fleet electrification preparation:Hybrid powertrain lubrication requirements create white space for thermal management fluid development ahead of Tehran municipal procurement cycles.
Industry Challenges
- Blending technician certification gaps:Shortage of personnel trained in API/ACEA specification alignment limits quality assurance throughput at provincial facilities.
- Legacy fleet compatibility testing:Reformulated products require extensive field validation against pre-2010 engine hardware before fleet-wide deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iran Commercial Vehicles Lubricants Market |
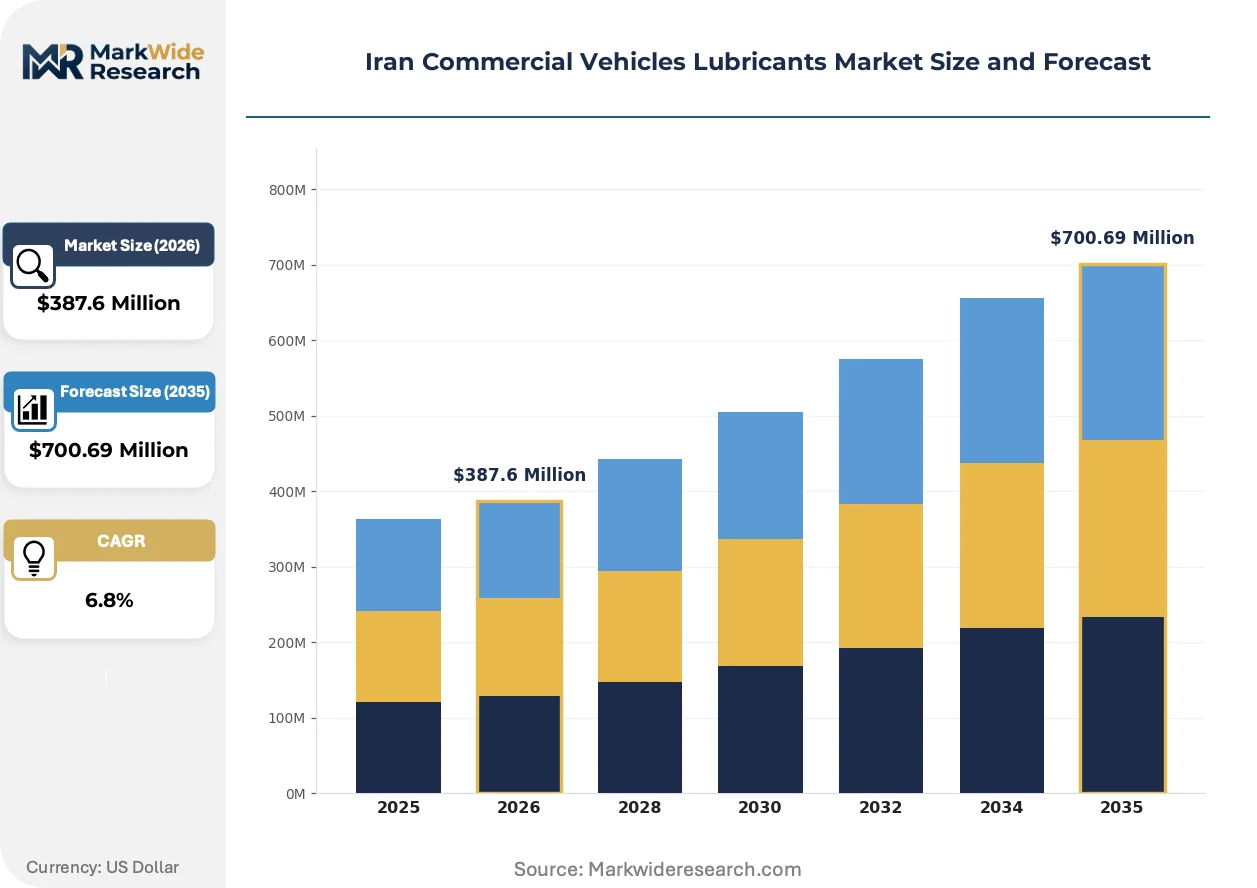
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Gear Oil, Transmission Fluid, Hydraulic Oil End User: Trucking Companies, Logistics Firms, Fleet Operators, Public Transport Vehicle Type: Heavy-Duty Trucks, Buses, Vans, Light Commercial Vehicles Application: Engine Performance, Fuel Efficiency, Wear Protection, Emission Control |
| Companies Covered | Iranol Oil Company, LIQUI MOLY, Sepahan Oil Company, AZAR RAVAN SAZ (Petronol), FUCHS, Pars Oil Company, Behran Oil Company, Ghatran Kaveh Motor Oil Co, Pardis Engine Oil Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iran Commercial Vehicles Lubricants Market Shifts & Advancements
Synthetic formulation advancement is compressing the performance gap between premium and mid-tier lubricants, while procurement digitization and regulatory alignment reshape how products reach fleet operators.
Group III base oil production is overtaking Group II as the domestic refinery upgrade priority. The National Iranian Oil Refining and Distribution Company has directed capacity expansion toward higher viscosity index feedstocks. This shift enables domestic blenders to formulate synthetic-grade products without additive package penalties from import dependency.
REACH-aligned additive disclosure requirements are influencing Iranian export-oriented lubricant specifications even absent direct EU market access. Domestic standards bodies are incorporating contaminant threshold language compatible with European registration protocols. This regulatory convergence primarily affects hydraulic oil categories destined for construction equipment OEM supply chains.
Volume-based procurement contracts are displacing spot purchasing among Tehran-based fleet operators. Large transport cooperatives are consolidating lubricant buying through annual framework agreements with fixed pricing bands. This pattern concentrates most visibly in heavy-duty trucking segments serving the Imam Khomeini Port-Tehran container corridor.
Iran Commercial Vehicles Lubricants Market Segmentation
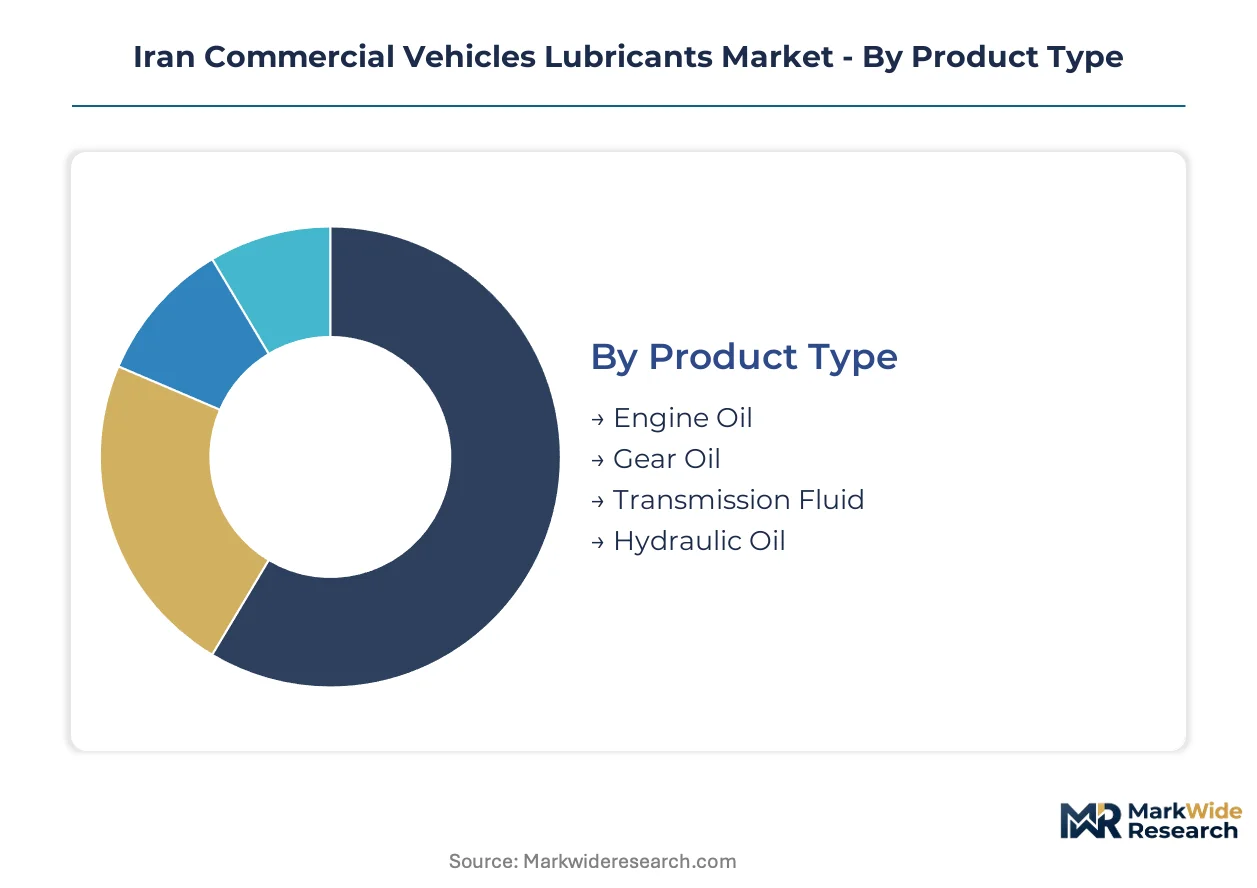
Segmentation in Iran's commercial vehicles lubricants market reveals how formulation requirements diverge across duty cycles and procurement channels. Fleet operators select products based on drain interval economics, hardware compatibility, and refinery proximity rather than brand preference alone.
Product Type:
Capital intensity varies sharply across product categories, with synthetic engine oil requiring the heaviest upfront investment in Group III base oil infrastructure and additive package sourcing.
- Engine Oil:Formulated with detergent-dispersant packages managing soot loading in diesel combustion, this category dominates procurement volumes along the Tehran-Mashhad corridor where heavy-duty truck density mandates frequent crankcase replenishment. Fleet operators calculate total cost of ownership around drain interval extension, though high-sulfur domestic fuel compresses effective service life below synthetic theoretical limits.
- Transmission Fluid:Specialized formulations for automated manual transmissions are gaining share fastest as Iranian bus and long-haul segments upgrade hardware. The shift from conventional manual gearboxes creates specification complexity around friction modification and thermal stability requirements.
- Gear Oil:Axle and differential lubrication maintains stable demand tied to vocational vehicle service intervals, with viscosity grades selected for load-bearing capacity in construction-linked fleets.
- Hydraulic Oil:Construction equipment and material handling applications drive specification requirements around anti-wear additive packages and oxidation resistance under high-pressure cycling.
Most installed capacity flows through Engine Oil. Expansion is steepest in Transmission Fluid.
End User:
Procurement scale determines segment economics, with large fleet operators commanding volume-based pricing frameworks unavailable to fragmented buyers.
- Trucking Companies:Long-haul operators along the Imam Khomeini Port-Tehran container corridor consolidate lubricant buying through annual framework agreements with fixed pricing bands, prioritizing drain interval extension over unit cost minimization.
- Fleet Operators:Multi-vehicle maintenance pools across provincial transport cooperatives balance synthetic formulation benefits against base oil quality variance from Iranian refineries, creating specification segmentation between premium and mid-tier contracts.
- Logistics Firms:Third-party operators serving Tehran-Mashhad freight corridors face sulfur-content diesel incompatibility that accelerates lubricant degradation and compresses effective service intervals.
- Public Transport:Municipal bus procurement cycles in Tehran are beginning to specify hybrid powertrain lubrication requirements ahead of electrification transitions, creating white space for thermal management fluid development.
Volume concentrates with Fleet Operators. Procurement sophistication is climbing fastest among Trucking Companies.
Vehicle Type:
Duty cycle severity drives formulation specification, with continuous highway operation demanding different additive packages than stop-start urban service.
- Heavy-Duty Trucks:High-utilization powertrains along Iran's primary logistics corridors generate concentrated bulk demand for API CK-4 synthetic formulations protecting after-treatment systems, though domestic Group II output inconsistency limits extended-drain product reliability.
- Buses:Urban and intercity segments are expanding transmission fluid volumes through automated manual transmission penetration, with thermal management requirements intensifying under Iranian summer operating conditions.
- Light Commercial Vehicles:Distributed last-mile delivery fleets across provincial centers favor mineral-based CI-4 products where procurement teams prioritize acquisition cost over total cost of ownership calculations.
- Vans:Small commercial operators in urban Tehran-Mashadh service corridors represent fragmented demand with limited negotiating leverage on volume-based contract terms.
Hardware population skews toward Heavy-Duty Trucks. Specification upgrading is most rapid in Buses.
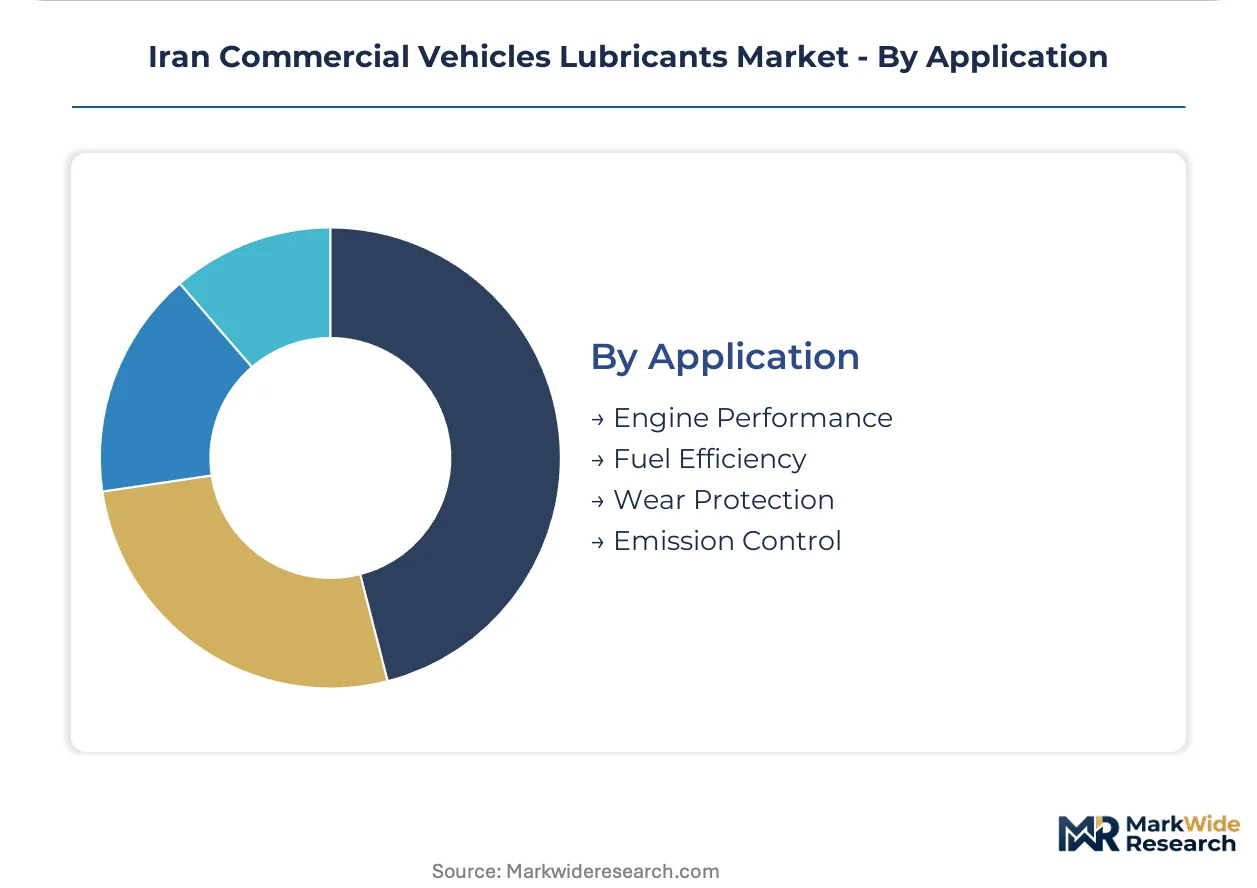
Application:
Performance claims align with regulatory pressure points, with emission control formulations responding to National Iranian Oil Refining and Distribution Company blending standard updates.
- Engine Performance:Friction reduction and power retention specifications dominate crankcase product positioning, with viscosity grade selection spanning SAE 15W-40 to 10W-30 based on regional thermal operating conditions.
- Wear Protection:Anti-wear additive packages address high-load conditions in differential and axle applications, with field validation requirements extending deployment timelines for reformulated products against pre-2010 engine hardware.
- Fuel Efficiency:Low-viscosity formulations targeting consumption reduction face adoption constraints from legacy fleet compatibility concerns and technician certification gaps at provincial blending facilities.
- Emission Control:After-treatment system protection requirements are pulling fleet operators toward higher-performance synthetics under updated National Iranian Oil Refining and Distribution Company standards, though additive package import dependency through sanctions-evading channels constrains consistent supply.
Current formulation investment concentrates on Engine Performance. Regulatory pull is strongest in Emission Control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled blending technicians cluster around Tehran's refinery complexes, anchoring formulation expertise in the capital region while provincial distribution networks extend toward eastern logistics corridors.
Tehran Province
Heavy-duty truck fleet operators concentrate along the Imam Khomeini Port container corridor, generating concentrated bulk procurement volumes. The National Iranian Oil Refining and Distribution Company enforces updated API CK-4 blending standards that pull procurement toward synthetic formulations. Karaj industrial zones host captive refinery infrastructure supplying base oil feedstocks to metropolitan blenders.
Khorasan Razavi Province
Mashhad-centered transport cooperatives manage long-haul replenishment cycles across the 900-kilometer Tehran-Mashhad freight route. Provincial logistics expansion creates underpenetrated channels for hydraulic oil servicing construction-linked commercial fleets. Mashhad distribution hubs coordinate bulk engine oil deliveries to corridor-based trucking terminals.
Isfahan Province
Specialized distribution networks serve provincial transport cooperatives balancing synthetic formulation benefits against base oil quality variance. The National Iranian Oil Refining and Distribution Company's standards shape local blending requirements for regional manufacturers. Isfahan industrial clusters support mid-tier lubricant production for fragmented light commercial vehicle operators.
Khuzestan Province
Port-linked logistics firms face sulfur-content diesel incompatibility that accelerates lubricant degradation and compresses effective drain intervals. Imam Khomeini Port throughput drives container corridor freight density requiring frequent crankcase replenishment. Ahvaz-based fleet operators negotiate volume-based procurement contracts with fixed pricing bands.
East Azerbaijan Province
Northwestern transport corridors connect to regional trade routes, generating stable demand for gear oil in vocational vehicle pools. Provincial blending facilities face technician certification gaps that limit quality assurance throughput. Tabriz industrial zones maintain legacy fleet compatibility testing protocols for pre-2010 engine hardware validation.
Iran Commercial Vehicles Lubricants Market Competitive Landscape
Capital-heavy producers with captive refinery access compete with asset-light distributors relying on third-party base oil sourcing and import-dependent additive packages. Market structure consolidates around three strategic tiers: integrated refinery-blenders controlling upstream feedstocks, specialized provincial distributors serving transport cooperatives, and foreign formulation specialists targeting specification-driven niches. Dominant competitive moves include backward integration into Group III base oil production and annual framework contracting with large fleet operators.
Within the integrated refinery tier, Iranol Oil Company anchors domestic base oil supply through captive refinery infrastructure, while Sepahan Oil Company exemplifies specialized distribution network architecture serving provincial transport cooperatives. FUCHS occupies a position among specification-focused foreign operators concentrating on hydraulic oil categories for construction-linked commercial fleets. These three archetypes represent the competitive spectrum from upstream control through channel specialization to niche technical positioning.
| Leading Market Players |
|---|
| Iranol Oil Company |
| LIQUI MOLY |
| Sepahan Oil Company |
| AZAR RAVAN SAZ (Petronol) |
| FUCHS |
| Pars Oil Company |
| Behran Oil Company |
| Ghatran Kaveh Motor Oil Co |
| Pardis Engine Oil Company |
| Others |
Supply & Pricing Matrix
Captive refinery integration by Iranol Oil Company and Sepahan Oil Company anchors domestic base oil supply while compressing procurement costs for fleet operators negotiating annual framework agreements along the Tehran-Mashhad corridor.
Pricing Analysis
Bundled technical service contracts dominate premium synthetic formulations, while unbundled spot purchasing persists for mineral-based CI-4 products serving fragmented light commercial vehicle operators. Three-tier pricing structure across premium API CK-4 synthetics, mid-tier Group II blends, and economy mineral grades differentiates on drain interval guarantees and after-treatment system compatibility. Pricing pressure stems from additive package import dependency through sanctions-evading channels, forcing blenders to absorb margin compression or reformulate specifications. Fleet operators demonstrate lowest price sensitivity, while provincial transport cooperatives exhibit highest sensitivity to unit acquisition costs.
Supply Chain Analysis
Blending technician availability constraints in East Azerbaijan and Khorasan Razavi provinces limit quality assurance throughput at provincial facilities serving construction-linked commercial fleets. Base oil supply concentrates in Iran's domestic refinery network, with Group II and emerging Group III output from Tehran and Isfahan complexes, while detergent-dispersant additive packages draw from China and India through transshipment routes. Single-source vulnerability around API-licensed additive masterbatches creates formulation disruption risk during trade channel interruptions. Distribution runs through Mashhad-centered cooperatives for eastern corridor replenishment and direct refinery offtake for Tehran metropolitan fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Iran's commercial vehicles lubricants market rests on domestic Group III base oil investment reducing import exposure and enabling premium synthetic formulation at mid-tier price positioning.
For Market Incumbents: Acquire captive additive blending capability to secure detergent-dispersant supply continuity against sanctions-channel volatility. Iranol Oil Company should expand Group III base oil capacity at Karaj refinery complexes to match fleet operator expectations for extended drain intervals. Defensive positioning requires locking annual framework agreements with Tehran-Mashhad corridor operators before provincial distributors consolidate buying power. For New Entrants and Emerging Players: Fragmented van operators in urban Tehran-Mashadh service corridors represent an underserved buyer archetype lacking volume leverage for synthetic formulation access. White space exists in hybrid powertrain thermal management fluids ahead of Tehran municipal bus electrification procurement cycles. Construction-linked hydraulic oil specifications in Khorasan province expansion zones offer penetrable entry with specialized anti-wear additive positioning. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier provincial distributors because transport cooperative consolidation creates scale advantages in bulk procurement negotiations. Long-term viability hinges on domestic refinery upgrade completion and API CK-4 formulation mandate enforcement breadth. Acquisition targets should demonstrate captive base oil access or specialized channel control in underpenetrated logistics corridors. The signal to watch is National Iranian Oil Refining and Distribution Company blending standard revision timing affecting synthetic product mandate scope.| Strategic Initiative | Industry Significance |
|---|---|
| Group III Base Oil Investment | Captive refinery upgrades enable synthetic formulation matching regional thermal conditions without import exposure. |
| Annual Framework Contracting | Fixed pricing bands with Tehran-Mashhad corridor operators secure volume commitment against spot market volatility. |
| Hybrid Powertrain Fluid Development | Thermal management specifications for Tehran municipal bus procurement create pre-electrification white space. |
| Provincial Distribution Network Expansion | Mashhad-centered cooperatives in Khorasan province offer underpenetrated channels for construction fleet hydraulic oil. |
| API CK-4 Certification Investment | Alignment with National Iranian Oil Refining and Distribution Company standards protects after-treatment system positioning. |
Research Methodology
Multiple input streams — fleet operator procurement interviews, refinery technical assessments, and trade channel documentation — were reconciled to construct demand and supply estimates. Primary engagement with lubricant procurement managers at Tehran-Mashhad corridor trucking companies, blending facility technical directors at provincial cooperatives, and National Iranian Oil Refining and Distribution Company regulatory affairs contacts provided operational validation. Secondary sources included Iranian customs records for additive package import flows, base oil production disclosures from refinery operators, and API licensing databases for formulation certification status. Bottom-up fleet operator demand modeling and top-down refinery capacity analysis were triangulated against corridor freight density estimates.
Data-stream reconciliation across product type, end user category, vehicle class, and application segments generated volume and value outputs throughout the forecast period. CAGRs were derived from segment-level growth rate differentials weighted by base year share and projected corridor expansion intensity. Industry-specific inputs incorporated automated manual transmission penetration rates in Iranian bus segments, sulfur-content diesel fuel degradation coefficients affecting drain interval economics, and Group III base oil capacity expansion timelines at domestic refineries.
Inputs from refinery operators and fleet procurement contacts were available through the study window; gaps in sanctions-channel additive package volume data introduce uncertainty bands around synthetic formulation supply assumptions. Forecasts reflect documented assumptions regarding National Iranian Oil Refining and Distribution Company standard enforcement timing and domestic base oil quality consistency. Material deviation in blending technician certification progress or additive import channel stability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Hardwood Market
Others
Europe Refrigerated Display Cases Market
Others
Global Electroshock Weapons Market
Others
Vo5g Market
Others
North America Video Conferencing Hardware Market
Others
South America Automotive LED Lighting Market
Others
Architectural Fabrics Market
Others
North America IT Device Market
Others
Smart Home Platforms Market
Others
Italy Smart Home Market
Others
Global Healthcare/Medical Simulation Market
Others
Latin America Automotive HVAC Market
Others
Global Cigarette Packaging Market
Others
Floor Cleaning and Mopping Machine Market
Others
Ammeters Market
Others
AI in Precision Medicine Market