
 Solar Lighting Tower Market | 2026-2036
Solar Lighting Tower Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Lighting Tower Market Insights
Construction rental fleets is consolidating demand for emission-free illumination across North American and Australian jobsites. Atlas Copco AB leverages its portable compressor distribution network to cross-sell solar lighting towers into existing contractor relationships. Wacker Neuson SE anchors its position through dedicated R&D spending on battery-integrated mast systems for European roadwork specifications. Aggreko PLC competes by bundling solar towers within its broader off-grid power rental portfolio for remote mining camps.
A solar lighting tower is a self-contained, mobile or stationary illumination system combining photovoltaic panels, battery storage, and high-efficiency LED arrays on an elevating mast, typically delivering 4,000–12,000 lumens for 8–24 hours without grid connection or fuel resupply. The unit serves construction, mining, emergency response, and event staging where diesel generator noise, emissions, or fuel logistics prove prohibitive. Hybrid towers that pair solar-battery cores with small backup generators currently capture the widest addressable market by bridging reliability gaps in high-latitude winter operations. LED technology dominates the luminaire segment due to its 50,000-hour lifespan and minimal draw on battery capacity, while modular tower architectures gain traction among rental houses seeking field-serviceable component swaps.
The US EPA enforces Tier 4 Final emissions standards that elevate diesel generator operating costs and effectively subsidize solar alternatives through compliance penalties. Australia's Clean Energy Regulator administers carbon credit schemes that reward mining operators for displacing diesel lighting with renewable substitutes. The EU F-Gas Regulation and associated CE machinery directives constrain refrigerant-based cooling in conventional generator sets, indirectly favoring passively cooled solar-battery designs. Stakeholders must track how national renewable procurement mandates and diesel bans at urban construction sites reshape fleet replacement cycles and rental rate structures.
Market Dynamics
Construction rental fleets are displacing owned diesel-lighting assets faster than any other buyer category, compressing replacement cycles from seven-year depreciation schedules to three-year technology refresh mandates.
Growth Catalysts
- EPA Tier 4 Final compliance costs:Diesel generator operators face elevated maintenance and exhaust after-treatment expenses that widen the total-cost-of-ownership gap against solar-battery alternatives.
- Australian Clean Energy Regulator carbon credits:Mining operators earn verified emission reductions for displacing diesel lighting, creating direct revenue streams that offset capital outlays.
- LED-lithium convergence:Solid-state luminaires with 50,000-hour lifespans and dense battery packs now deliver 12,000 lumens through winter nights without fuel logistics.
Market Restraints
- Polysilicon and lithium price volatility:Input cost swings of 40-60% on photovoltaic wafers and battery cells destabilize manufacturer margin planning and rental rate-setting.
- High-latitude winter insufficiency:Solar yield below 2 peak sun hours daily in Nordic and Alaskan winters forces hybrid backup generator retention, erasing full emission elimination claims.
- EU F-Gas refrigerant constraints:Conventional diesel generator cooling system redesigns absorb engineering resources that otherwise migrate to pure solar-battery development.
Strategic Opportunities
- Indonesian archipelago infrastructure:Island-hopping construction and disaster response operations lack grid access and diesel resupply chains, creating captive demand for self-contained illumination.
- Hybrid-to-pure solar transition pathways:Rental houses can segment fleets by latitude, deploying all-solar towers in equatorial zones while retaining generator backup for temperate contracts.
- CE machinery directive safety harmonization:Unified mast stability and electrical isolation standards reduce country-specific certification burdens for European cross-border rental operations.
Industry Challenges
- Field technician battery-safety certification:Thermal runaway response protocols and high-voltage DC isolation procedures require specialized training that rental fleet maintenance teams currently lack.
- Legacy diesel fleet stranded asset risk:Accelerated write-downs on conventional lighting towers compress balance sheet capacity for solar replacement capex.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Lighting Tower Market |
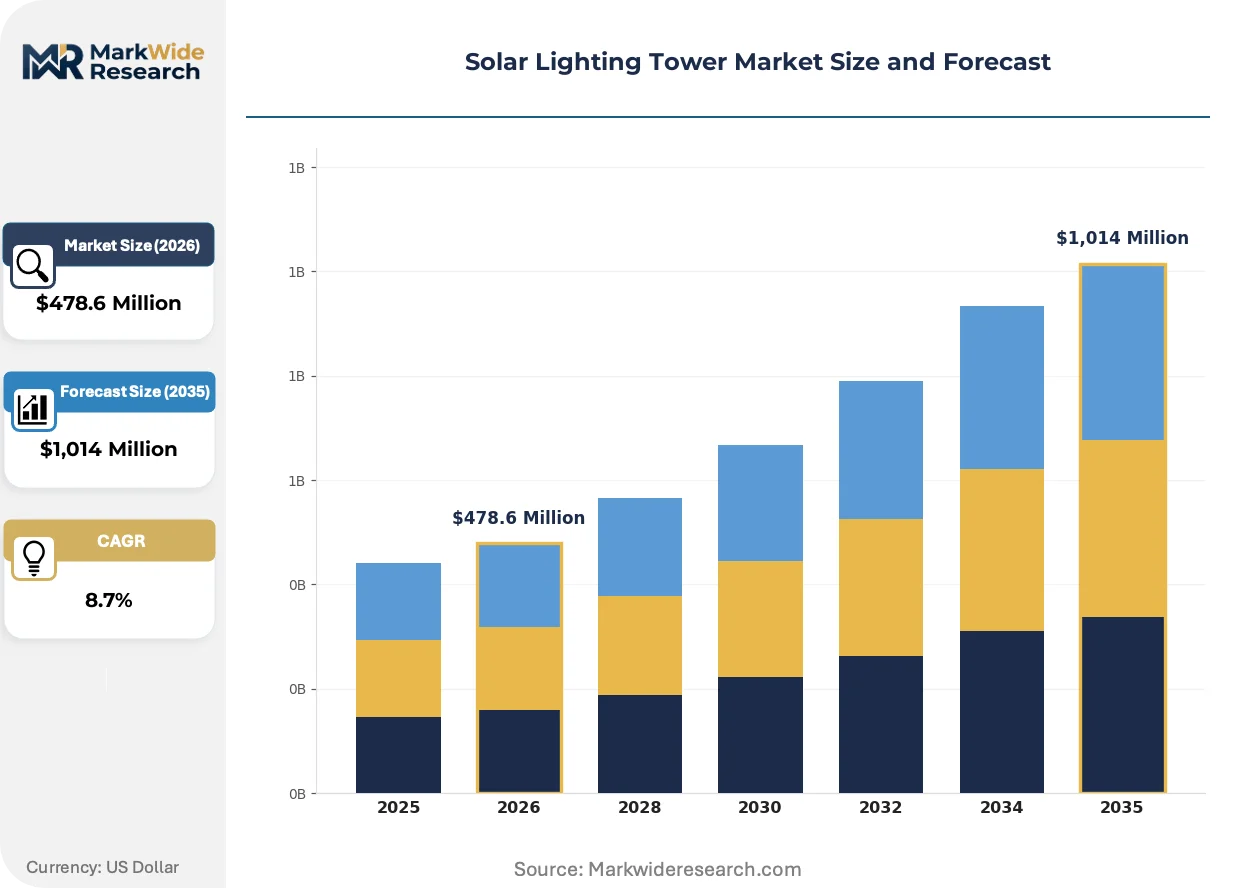
| Market Size in 2026 | $478.6 Million |
| Market Size in 2035 | $1,014 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
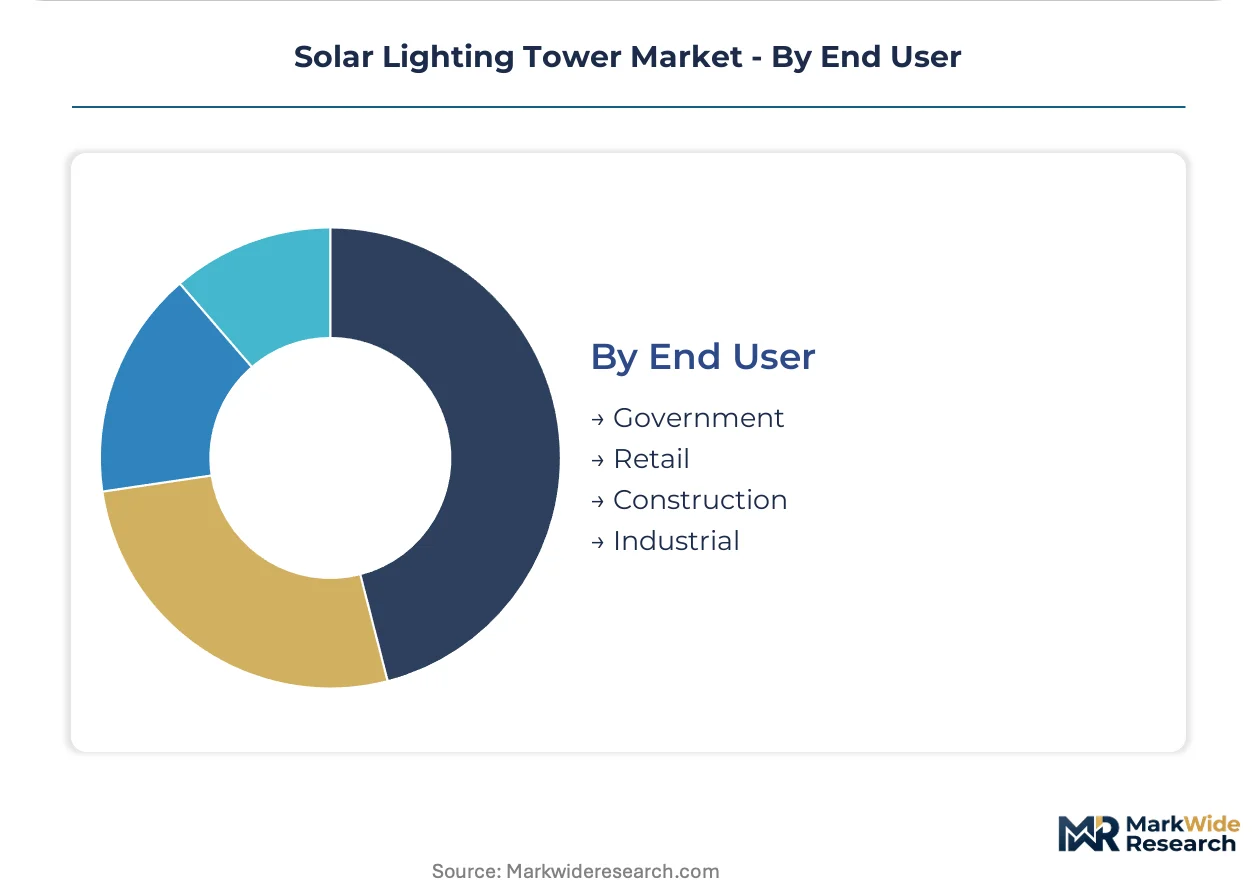
| Segmentation | Product Type: Portable Towers, Fixed Towers, Hybrid Towers, Modular Towers Application: Construction Sites, Mining Operations, Emergency Services, Event Lighting Technology: LED, Solar Photovoltaic, Battery Storage, Hybrid Systems End User: Government, Retail, Construction, Industrial |
| Companies Covered | Atlas Copco AB, BIGLUX, Aggreko PLC, OPTRAFFIC, Tower Light SRL, Wacker Neuson SE, Allmand Brothers Inc., Wanco Inc., Generac Power Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Lighting Tower Market Trends and Innovations
Modular component architectures and predictive battery management systems are compressing field service intervals and extending asset utilization rates in remote deployment scenarios.
Lithium iron phosphate (LiFePO4) battery chemistry is rewriting reliability expectations for solar lighting towers operating in temperature extremes. Mining contractors in Western Australia and Chilean Atacama operations now specify this chemistry exclusively for 40°C ambient performance. The technology is compressing warranty claim rates and enabling multi-shift continuous operation that lead-acid and diesel alternatives cannot match.
The EU F-Gas Regulation and associated CE machinery directives are constraining refrigerant-based cooling in conventional generator sets. This regulatory pressure indirectly favors passively cooled solar-battery designs that eliminate compressor maintenance and leak detection obligations. Roadwork contractors in Germany and France now face accelerated depreciation schedules on diesel assets that cannot achieve refrigerant compliance.
Rental fleet operators are unbundling after-sales service from equipment procurement, preferring per-lumen-hour performance contracts with manufacturer uptime guarantees. This model transfers battery degradation and LED replacement risk to OEMs while locking in multi-year revenue visibility. The shift is most visible in Australian mining camps and North American highway maintenance contracts where downtime penalties exceed equipment lease rates.
Solar Lighting Tower Market Segmentation
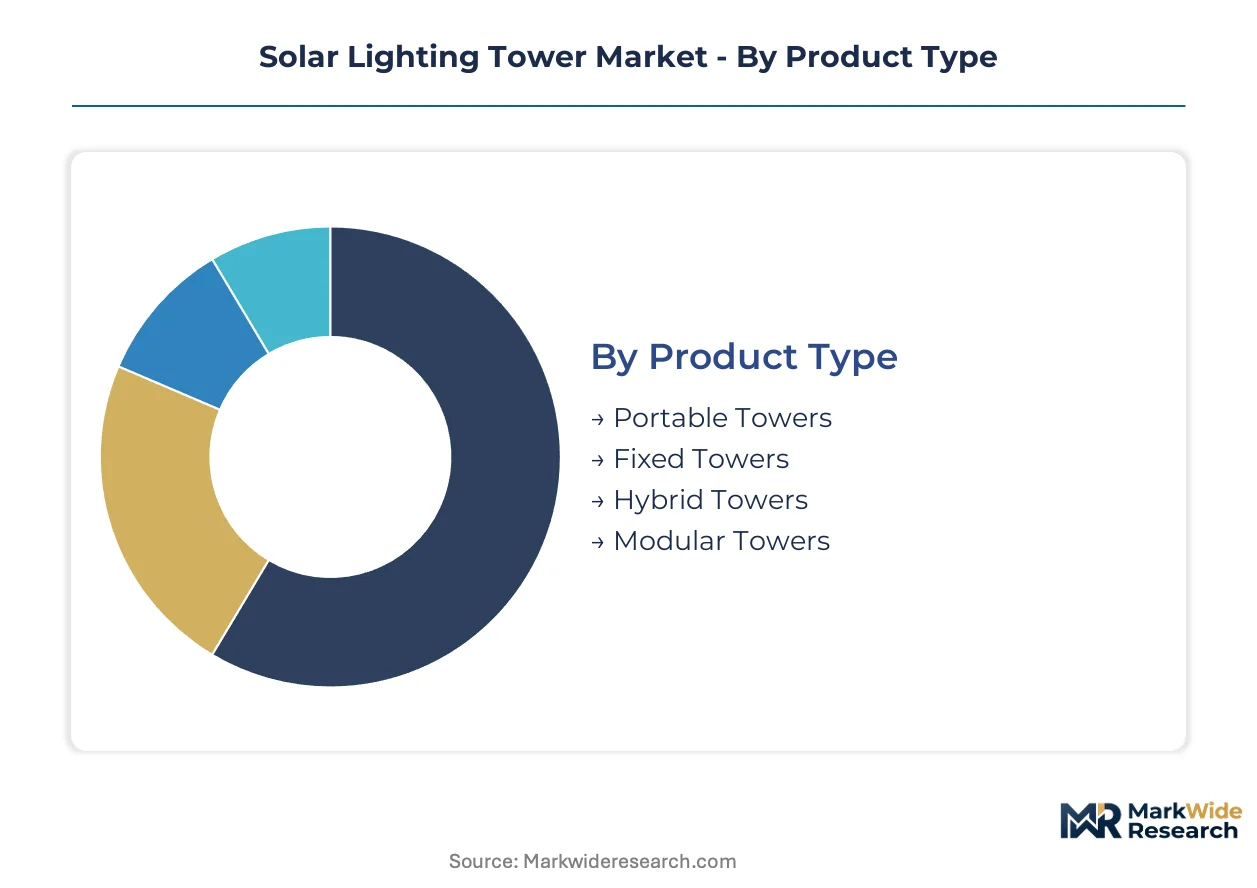
Segmentation in solar lighting towers reveals how procurement criteria diverge between rental fleet operators seeking modularity and mining contractors demanding all-weather reliability. Understanding these fault lines allows manufacturers to align R&D spending with segments where battery chemistry and mast engineering create defensible differentiation.
Product Type:
Rental houses prioritize transportability and field serviceability when selecting tower architectures, driving divergence between mobile and stationary designs.
- Portable Towers:Trailer-mounted units with collapsible masts and forklift pockets dominate North American highway maintenance contracts where rapid site relocation is mandatory. Fleet operators in Texas and California specify these for multi-project rotation schedules.
- Fixed Towers:Permanent installations with poured concrete foundations anchor remote mining camps in Western Australia where decade-long operational horizons justify civil works investment.
- Hybrid Towers:Solar-battery cores with small diesel backup generators bridge reliability gaps in high-latitude winter operations where insufficiency drops below 2 peak sun hours.
- Modular Towers:Field-swappable component architectures enable rental houses to isolate battery, panel, or LED failures without OEM technician dispatch.
Hybrid towers lead on scale; modular towers lead on momentum.
Application:
Site conditions and regulatory exposure determine whether buyers prioritize emission elimination, noise reduction, or fuel logistics elimination.
- Construction Sites:Urban diesel bans in German and French municipalities accelerate displacement of conventional generator lighting for roadwork and building foundations.
- Mining Operations:Australian Clean Energy Regulator carbon credit schemes create direct revenue streams for operators displacing diesel lighting in Pilbara and Bowen Basin extraction zones.
- Emergency Services:Rapid deployment requirements favor self-contained units with pre-charged battery reserves for disaster response where grid restoration lags.
- Event Lighting:Noise-sensitive outdoor venues specify silent operation for multi-day festivals where generator hum disrupts neighboring residential zones.
Construction sites lead on scale; mining operations lead on momentum.
Technology:
Component convergence between solid-state lighting and lithium storage is compressing system footprints while extending autonomous runtime.
- LED:Solid-state luminaires with 50,000-hour lifespans and minimal thermal signature dominate all new tower specifications, rendering metal halide obsolete.
- Solar Photovoltaic:Monocrystalline panel arrays with anti-soil coatings maintain yield in dusty mining environments where cleaning access is limited.
- Battery Storage:Lithium iron phosphate chemistry is displacing lead-acid in Australian and Chilean desert operations where 40°C ambient temperatures degrade conventional electrochemistry.
- Hybrid Systems:Integrated generator backup retains market presence in Nordic and Alaskan markets where winter insufficiency forces fossil fuel bridging.
LED leads on scale; battery storage leads on momentum.
End User:
Procurement authority and total-cost-of-ownership horizons separate public sector tender processes from private fleet investment cycles.
- Government:Municipal highway departments and federal land management agencies specify domestic content requirements and extended warranty terms in public tenders.
- Retail:Big-box construction rental chains consolidate national fleet purchasing, extracting volume discounts and manufacturer uptime guarantees.
- Construction:General contractors operating under EPA Tier 4 Final compliance pressure accelerate replacement of owned diesel assets with rental solar alternatives.
- Industrial:Mining conglomerates and oilfield services operators integrate lighting towers into broader off-grid power procurement frameworks.
Construction leads on scale; government leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting solar lighting tower procurement toward jurisdictions where carbon credit schemes and diesel compliance penalties create the widest cost-of-ownership gaps. Manufacturers now site assembly capacity to minimize cross-border certification burdens while exploiting localized incentive structures.
United States
Construction rental fleets in Texas and California are compressing replacement cycles from seven-year depreciation to three-year technology refreshes. The EPA's Tier 4 Final emissions standards elevate diesel generator maintenance costs and exhaust after-treatment expenses. Highway maintenance contractors in the Permian Basin and Central Valley now specify trailer-mounted portable towers for multi-project rotation schedules.
Australia
Mining operators in the Pilbara and Bowen Basin earn verified emission reductions through the Clean Energy Regulator's carbon credit schemes. Western Australia's off-grid power mandates for remote extraction sites eliminate diesel lighting alternatives. Fixed towers with poured concrete foundations anchor decade-long operational horizons at camp installations where civil works investment is justified.
Germany
Roadwork contractors face accelerated depreciation schedules on diesel assets that cannot achieve EU F-Gas refrigerant compliance. The CE machinery directive's mast stability and electrical isolation standards reduce certification burdens for cross-border rental operations. Bavarian and North Rhine-Westphalian municipal highway departments specify domestic content requirements in public tenders.
Chile
Atacama mining operations specify lithium iron phosphate battery chemistry exclusively for 40°C ambient performance. The country's renewable energy procurement mandates for extractive industries displace diesel lighting alternatives. Antofagasta and Calama industrial clusters now demand multi-shift continuous operation that lead-acid and diesel alternatives cannot match.
Indonesia
Island-hopping infrastructure construction and disaster response operations lack grid access and diesel resupply chains. Archipelago geography creates captive demand for self-contained illumination systems. Javanese and Sumatran contractors now prioritize rapid deployment units with pre-charged battery reserves where maritime logistics complicate fuel delivery.
Solar Lighting Tower Market Competitive Landscape
Strategic partnerships dominate the current landscape as manufacturers seek to bundle solar towers within broader off-grid power rental portfolios. The vendor base stratifies across three tiers: diversified industrial conglomerates with portable equipment distribution networks, specialized lighting tower fabricators with dedicated mast engineering capabilities, and regional rental operators with captive fleet deployment expertise. Competitive positioning hinges on cross-selling leverage, battery-integrated R&D spending, and field-serviceable modular architectures. M&A activity and technology licensing agreements represent the dominant competitive moves as players seek geographic coverage and component supply security.
Within the diversified industrial tier, Atlas Copco AB and Wacker Neuson SE exemplify archetypes that leverage existing portable equipment distribution networks to anchor positions in contractor relationships. Aggreko PLC occupies a position representing the rental-house bundling model, integrating solar towers within broader off-grid power portfolios. Among specialized fabricators, Tower Light SRL and BIGLUX represent European and Asian engineering-focused competitors respectively. The competitive terrain rewards players who can transfer battery degradation and LED replacement risk to OEMs through per-lumen-hour performance contracts with uptime guarantees.
| Leading Market Players |
|---|
| Atlas Copco AB |
| BIGLUX |
| Aggreko PLC |
| OPTRAFFIC |
| Tower Light SRL |
| Wacker Neuson SE |
| Allmand Brothers Inc. |
| Wanco Inc. |
| Generac Power Systems Inc. |
| Others |
Pricing and Supply Chain Analysis
Polysilicon wafer and lithium carbonate costs cascade through three distinct pricing tiers before reaching rental fleet operators, with Australian mining contractors absorbing premium markups for LiFePO4-certified systems while North American highway maintenance buyers negotiate volume discounts on trailer-mounted portable units.
Pricing Analysis
Distributor margins of 18-25% separate OEM factory gates from end-user invoices across the solar lighting tower channel. Three-tier pricing structure across premium, standard, and economy levels reflects battery chemistry grade, mast height certification, and after-sales service bundling. Cost compression in the standard tier is intensifying because Chinese panel manufacturers are flooding mid-range specifications. Construction rental chains exhibit highest price sensitivity, demanding per-lumen-hour performance contracts that transfer degradation risk upstream.
Supply Chain Analysis
Domestic-content mandates in the United States, Germany, and Australia are fragmenting component sourcing away from concentrated Asian manufacturing hubs. Photovoltaic wafers draw from Chinese and Malaysian foundries, LiFePO4 cells rest on South Korean and Taiwanese cathode production, and LED arrays hinge on Shenzhen packaging clusters. Single-source vulnerability in refined lithium hydroxide creates exposure to export licensing disruptions. Distribution runs through national rental house networks rather than direct OEM-to-site logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in solar lighting towers rests on lithium iron phosphate cost curves flattening faster than lead-acid replacement cycles compress, while premium-tier buyers in Australian mining and Chilean desert operations absorb 15-20% markups for 40°C thermal performance guarantees.
For Market Incumbents: Anchor defensive positioning through backward integration into LiFePO4 cell supply and captive mast engineering capacity in Western Australia. Battery thermal runaway liability and emerging Chinese tower fabricators threaten installed base maintenance revenue. Certification investment in EU CE machinery directive compliance creates switching costs against rental house procurement teams. For New Entrants and Emerging Players: Battery management system IP with predictive degradation algorithms offers the most penetrable wedge for Indonesian archipelago contractors lacking field technician networks. Island-hopping infrastructure and disaster response operations present white-space demand with minimal incumbent rental presence. Direct-to-municipal tender positioning bypasses consolidated national rental chain gatekeepers. For Investors and Strategic Acquirers: Consolidation pressure builds where regional rental operators lack capital to refresh diesel fleets under EPA Tier 4 Final compliance deadlines. Five-to-ten year viability favors specialized fabricators with dedicated mast engineering over diversified industrial conglomerates cross-selling from compressor portfolios. Watch Australian Clean Energy Regulator carbon credit price floors as inflection signal for mining procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| LiFePO4 Battery Supply Agreement | Locks in cathode capacity from South Korean suppliers for Australian mining fleet deployments. |
| CE Machinery Directive Certification | Opens cross-border rental mobility between German and French municipal highway contracts. |
| Modular Component Architecture Launch | Enables Texas rental houses to execute field swaps without OEM technician dispatch. |
| Per-Lumen-Hour Performance Contract | Transfers LED degradation and battery replacement risk from Pilbara miners to OEM balance sheets. |
| Indonesian Distribution Partnership | Establishes local service presence for Javanese island-hopping construction logistics. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with rental fleet procurement directors, mining camp power engineers, municipal highway maintenance supervisors, and solar tower OEM product managers with secondary validation against EPA Tier 4 Final filings, Australian Clean Energy Regulator carbon credit registries, EU F-Gas Regulation implementation guidance, and customs data on photovoltaic wafer trade flows. Bottom-up unit economics and top-down market sizing triangulated to convergence.
Historical reference periods anchored the projection horizon through verified replacement cycle compression in North American rental fleets and Australian diesel displacement mandates. Segmentation dimensions spanned product architecture, application environment, battery chemistry tier, and end-user procurement authority. CAGRs derived from logistic adoption curves fitted to early-mover mining operator data and late-majority municipal tender patterns. Forecast inputs incorporated polysilicon price volatility bands and lithium carbonate supply elasticity assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Australian carbon credit scheme modifications, EU F-Gas refrigerant constraint enforcement intensity, and Chinese photovoltaic export licensing shifts. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Europe Indoor LBS Market
Others
Global Electronic Filters Market
Others
Cryogenic Storage Tanks Market
Others
Hypersensitivity Market
Others
Global Car Wax Market
Others
Duckweed Market
Others
Profiling Floats Market
Others
US Automotive LED Lighting Market
Others
Human Enhancement Technology Market
Others
Three Proofing Rugged Tablet Market
Others
Global Optical Coordinate Measuring Machine Market
Others
Thermal Energy Flow Metering Solutions Market
Others
Conditional Access System (CAS) Market
Others
Europe Medical Simulation Market
Others
Augmented Reality (AR) in Manufacturing Market
Others
North America Micro Market