
 Spinal Imaging Market | 2026-2036
Spinal Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Spinal Imaging Market Intelligence
Artificial intelligence integration in diagnostic radiology is narrowing the gap between image acquisition and actionable clinical interpretation. GE HealthCare leverages embedded AI algorithms to automate vertebral segmentation and anomaly detection across its CT and MRI platforms. Siemens Healthineers anchors its competitive stance through high-field MRI systems optimized for spine-specific coil arrays and motion correction protocols. Koninklijke Philips differentiates via integrated informatics that connect imaging data to surgical navigation ecosystems.
Spinal imaging encompasses the acquisition, reconstruction, and interpretation of anatomical and pathological visual data from the vertebral column, spinal cord, and adjacent neural structures using ionizing and non-ionizing energy modalities, with spatial resolution thresholds typically ranging from sub-millimeter for CT to sub-millimeter isotropic for high-field MRI. Its primary commercial purpose is to enable definitive diagnosis of trauma, degenerative conditions, neoplasms, and post-surgical complications while guiding interventional and operative decision-making. MRI systems command the premium equipment tier due to superior soft-tissue contrast for neural element assessment, while CT scanners retain dominance in trauma settings where speed and bone detail outweigh radiation exposure concerns. Digital radiography occupies the high-volume, lower-margin baseline for initial screening and longitudinal monitoring of spinal alignment disorders.
FDA premarket notification requirements under 21 CFR Part 892 govern diagnostic imaging device safety and effectiveness, while ISO 13485 quality management standards shape manufacturer operational compliance across production and post-market surveillance activities. The Centers for Medicare & Medicaid Services reimbursement frameworks directly influence hospital capital allocation cycles for imaging equipment replacement and technology upgrades. Stakeholders must monitor evolving AI diagnostic coding and coverage determinations that will reshape return-on-investment calculations for advanced system deployments.
Market Dynamics
AI-assisted diagnostic software is compressing the interval between image acquisition and surgical decision-making, forcing equipment manufacturers to embed algorithmic interpretation layers directly into imaging platforms rather than treating analytics as aftermarket add-ons.
Growth Catalysts
- CMS Reimbursement Frameworks:Medicare coverage determinations for AI-enhanced spinal imaging are accelerating hospital capital allocation toward equipment replacement cycles in the United States.
- Orthopedic Clinic Expansion:Ambulatory surgical centers are installing advanced MRI and CT modalities to capture outpatient spine procedures migrating from inpatient settings.
- FDA 510(k) Pathways:Streamlined premarket notification processes for software-as-a-medical-device are reducing time-to-market for automated vertebral segmentation tools.
Market Restraints
- Helium Supply Concentration:Superconducting MRI systems depend on helium cryogen sourced primarily from Qatar and the United States, exposing manufacturers to price volatility and export restriction risks.
- Radiation Exposure Protocols:CT spine protocols face intensifying scrutiny under ALARA principles and institutional review board mandates, limiting repeat scanning frequency in trauma surveillance.
- Specialized Coil Manufacturing:Spine-specific phased-array coils require precision RF engineering concentrated among Japanese and German component suppliers, creating single-source vulnerabilities.
Strategic Opportunities
- India Diagnostic Infrastructure:Government PLI scheme incentives for medical device manufacturing are attracting MRI and CT assembly investments to serve underpenetrated tier-2 and tier-3 hospital networks.
- Intraoperative Imaging Convergence:Integration of 3D C-arm fluoroscopy with surgical navigation systems is creating new product categories for real-time spinal instrumentation verification.
- EU AI Act Compliance:Early alignment with high-risk AI system documentation requirements positions vendors for preferential procurement in European hospital systems.
Industry Challenges
- Radiologist-AI Collaboration Models:Training workflows that preserve diagnostic accountability while delegating segmentation tasks to algorithms remain institutionally unresolved.
- Multi-Vendor PACS Integration:Legacy picture archiving systems from GE, Siemens, and Philips employ proprietary DICOM implementations that obstruct seamless AI plugin deployment.
- Post-Market Surveillance Burden:ISO 13485-compliant vigilance systems for algorithm updates require continuous performance monitoring that strains quality assurance staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spinal Imaging Market |
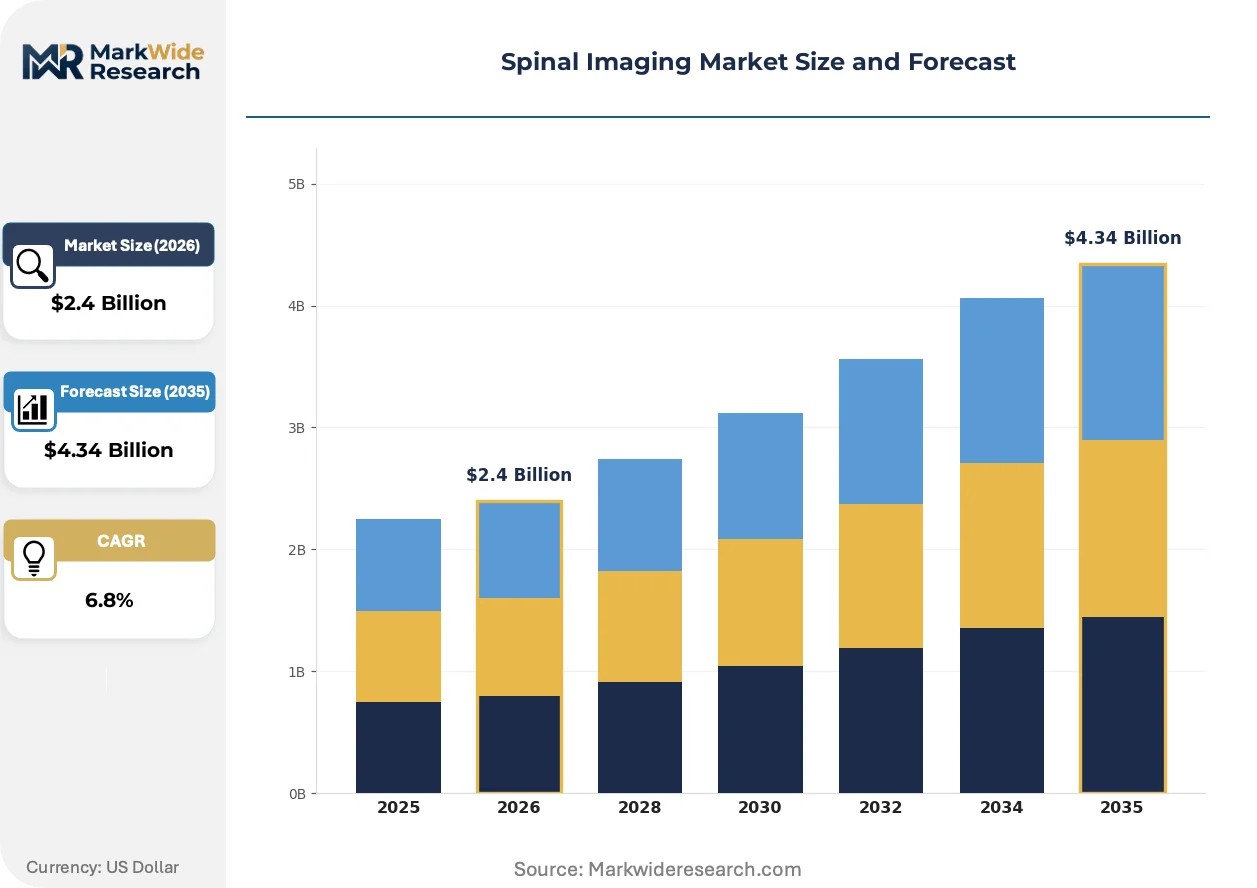
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CT Scanners, MRI Systems, X-ray Systems, Ultrasound Devices End User: Hospitals, Orthopedic Clinics, Neurology Centers, Diagnostic Imaging Centers Technology: 3D Imaging, Ultrasonography, Digital Radiography, Fluoroscopy Application: Trauma Assessment, Degenerative Disc Disease, Spinal Tumors, Postoperative Evaluation |
| Companies Covered | GE HealthCare, Siemens Healthineers, Koninklijke Philips, Canon Medical Systems, Medtronic, FUJIFILM, Hitachi, Shimadzu, Esaote, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spinal Imaging Market Strategic Shifts & Innovations
Computational methods are displacing manual measurement protocols across the spinal imaging value chain, from automated Cobb angle calculation in scoliosis assessment to predictive modeling of adjacent segment disease after fusion surgery.
Photon-counting CT detectors are digitizing spectral tissue characterization at dose levels approaching conventional CT, enabling simultaneous bone mineral density quantification and implant metal artifact reduction. Academic medical centers in Germany and South Korea are piloting these systems for complex revision spine surgery planning. The technology is digitizing the trade-off between diagnostic information density and radiation exposure that has constrained CT spine protocols for decades.
The EU Medical Device Regulation is tightening clinical evidence requirements for imaging software, mandating prospective validation studies that extend regulatory timelines by 18-24 months compared to predecessor directives. Manufacturers are restructuring quality management systems to accommodate notified body scrutiny of machine learning training datasets. High-risk classification for AI-assisted diagnostic tools is concentrating compliance investment among firms with established European regulatory affairs capabilities.
Hospital procurement committees are unbundling equipment acquisition from multi-year service contracts, compressing vendor switching cycles and exposing installed base vulnerabilities. Independent service organizations are capturing maintenance revenue previously held by original equipment manufacturers through third-party parts sourcing and remote diagnostics. This pattern is most pronounced in the United States, where health system consolidation has centralized purchasing authority and standardized equipment specifications across regional networks.
Spinal Imaging Market Segmentation
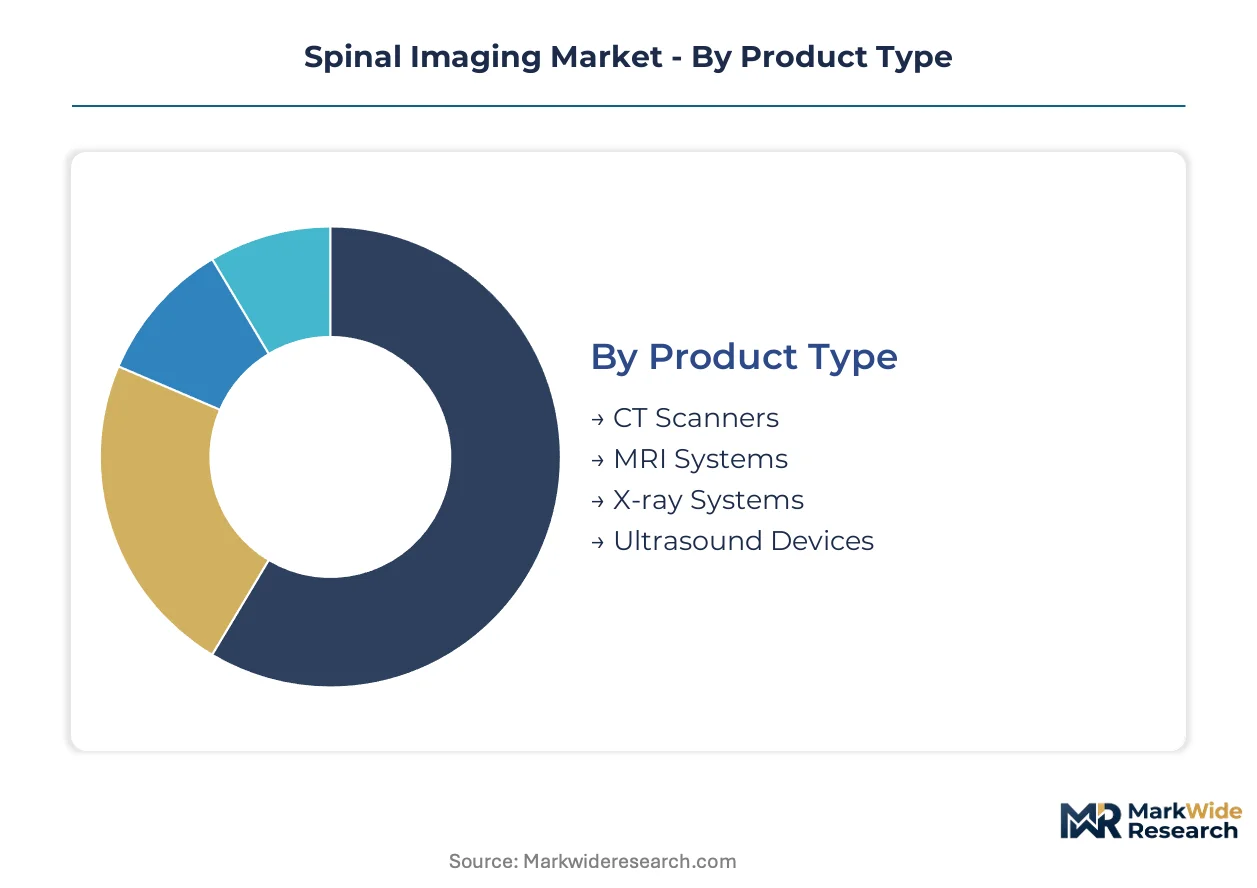
Spinal imaging segmentation reflects divergent clinical workflows across emergency, surgical, and outpatient settings. Equipment specifications and reimbursement pathways vary sharply by care site, driving distinct procurement patterns across health system tiers.
Product Type:
Mature modalities dominate installed base economics while emerging platforms capture replacement cycles through AI integration and spectral imaging advances.
- CT Scanners:Helium-cooled rotating anode tubes and multi-detector arrays deliver sub-millimeter spatial resolution for trauma protocols. Emergency departments in the United States prioritize 256-slice systems for whole-spine trauma surveys under ALARA constraints.
- MRI Systems:Superconducting 1.5T and 3T platforms with spine-specific phased-array coils enable neural element visualization without ionizing radiation. Orthopedic clinics in Germany and Japan are deploying compact 1.5T systems for outpatient spine surgery planning.
- X-ray Systems:Digital radiography with automated stitching algorithms supports scoliosis monitoring and postoperative alignment checks.
- Ultrasound Devices:Portable systems with linear high-frequency transducers enable intraoperative pedicle screw guidance and soft-tissue navigation.
CT Scanners retain volume leadership across trauma settings; MRI Systems hold the steepest expansion curve in ambulatory surgical center deployments.
End User:
Procurement authority concentrates at health system level for hospitals while orthopedic clinics exercise independent equipment decisions.
- Hospitals:Integrated delivery networks in the United States consolidate imaging capital decisions across emergency, inpatient, and surgical service lines under centralized value analysis committees.
- Orthopedic Clinics:Ambulatory surgical centers in Texas and Florida are installing intraoperative CT and 3D C-arm systems to capture spinal fusion procedures migrating from hospital outpatient departments.
- Neurology Centers:Academic medical centers in South Korea deploy high-field MRI for intraoperative functional mapping during spinal cord tumor resections.
- Diagnostic Imaging Centers:Independent facilities in India leverage government PLI scheme incentives to deploy CT and MRI capacity in tier-2 cities.
Hospitals command the largest equipment budgets; Orthopedic Clinics are gaining share fastest as procedure volume shifts to outpatient settings.
Technology:
Digital acquisition methods are displacing analog workflows while 3D reconstruction capabilities reshape surgical planning economics.
- 3D Imaging:Cone-beam CT and volumetric reconstruction algorithms enable preoperative templating for spinal instrumentation with screw trajectory optimization.
- Ultrasonography:High-frequency linear probes with bone-enhancement algorithms support real-time guidance for neuraxial anesthesia and intraoperative screw placement verification.
- Digital Radiography:Flat-panel detectors with automated exposure control replace computed radiography cassettes in high-volume screening workflows.
- Fluoroscopy:Pulsed and low-dose protocols with last-image-hold reduce radiation exposure during interventional spine procedures.
Digital Radiography sustains the highest scan volume; 3D Imaging commands the fastest technology refresh rates.
Application:
Clinical urgency and reimbursement intensity vary across acute trauma, chronic degenerative conditions, and surveillance protocols.
- Trauma Assessment:Whole-spine CT protocols with sagittal and coronal reconstructions detect occult fractures and ligamentous injuries in multitrauma patients. Level I trauma centers mandate sub-30-minute scan-to-interpretation intervals.
- Degenerative Disc Disease:MRI with T2-weighted sequences and axial loaded positioning visualizes neural foraminal stenosis and disc herniation severity for surgical candidacy determination.
- Spinal Tumors:Contrast-enhanced MRI with diffusion-weighted imaging characterizes vertebral metastases and primary spinal cord neoplasms for biopsy planning and treatment response monitoring.
- Postoperative Evaluation:CT with metal artifact reduction algorithms assesses fusion mass maturation and hardware position following instrumented spinal surgery.
Trauma Assessment drives the highest emergency department scan volume; Degenerative Disc Disease generates the most elective surgical planning studies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export high-field MRI systems to United States hospital networks, while Japanese component suppliers ship precision RF coils to assembly facilities across Asia and Europe.
United States
Hospital consolidation and outpatient imaging center expansion drive equipment replacement cycles in Texas and Florida. CMS reimbursement frameworks for AI-enhanced spinal imaging accelerate capital allocation toward advanced CT and MRI platforms. The Greater Boston corridor hosts academic medical centers piloting photon-counting CT for complex revision spine surgery.
Germany
Academic medical centers in Munich and Heidelberg deploy high-field MRI systems for intraoperative functional mapping during spinal cord tumor resections. The EU Medical Device Regulation mandates prospective validation studies extending regulatory timelines for imaging software. Baden-Württemberg concentrates precision engineering firms supplying spine-specific phased-array coil components.
Japan
Orthopedic clinics in Tokyo and Osaka install compact 1.5T MRI systems for outpatient spine surgery planning. METI industrial policy supports domestic manufacturing of superconducting magnet components for export markets. The Nagoya industrial corridor hosts specialized suppliers of precision RF engineering for MRI coil arrays.
India
Government PLI scheme incentives attract MRI and CT assembly investments to serve underpenetrated tier-2 and tier-3 hospital networks. CDSCO regulatory pathways streamline medical device import substitution programs. The Maharashtra-Gujarat industrial belt concentrates emerging diagnostic imaging center expansion in Mumbai and Ahmedabad.
South Korea
Academic medical centers in Seoul deploy high-field MRI for intraoperative spinal cord tumor resections. MFDS accelerated review pathways support domestic manufacturers developing AI-assisted diagnostic software. The Busan-Ulsan manufacturing corridor supplies precision components to regional imaging equipment assemblers.
Spinal Imaging Market Key Industry Players
Channel-controlling players compete with product-specialist players across three distinct tiers. Consolidated original equipment manufacturers anchor the premium segment through integrated hardware-software platforms, while mid-scale regional fabricators capture replacement cycles via third-party service contracts. Strategic archetypes span full-stack imaging conglomerates, specialized coil engineering houses, and independent software vendors. Dominant competitive moves include backward integration into precision component manufacturing and geographic expansion through distributor acquisition in emerging diagnostic markets.
Among diversified health technology conglomerates, GE HealthCare, Siemens Healthineers, and Koninklijke Philips occupy positions exemplifying the full-stack archetype. These entities represent channel-controlling structures through embedded AI algorithms, high-field MRI optimization, and integrated informatics connecting imaging data to surgical navigation ecosystems. Their positioning reflects consolidated installed base economics and multi-year service contract retention across United States hospital networks and European academic medical centers.
| Leading Market Players |
|---|
| GE HealthCare |
| Siemens Healthineers |
| Koninklijke Philips |
| Canon Medical Systems |
| Medtronic |
| FUJIFILM |
| Hitachi |
| Shimadzu |
| Esaote |
| Others |
Cost & Logistics Intelligence
Overcapacity in Chinese CT scanner assembly lines compresses margin structures for mid-tier manufacturers while simultaneously creating procurement leverage for United States health systems negotiating multi-year equipment contracts. This utilization asymmetry between Asian production hubs and North American buyer concentration shapes supplier pricing discipline and inventory posture across the spinal imaging value chain.
Pricing Analysis
Next-generation photon-counting CT systems command premium positioning against conventional energy-integrating detectors and legacy 128-slice platforms. Pricing stratifies across premium, standard, and economy tiers based on field strength gradients for MRI and detector row counts for CT, with FDA 510(k) clearance status serving as a secondary price escalator. Cost compression in the standard tier is intensifying because third-party service organizations are capturing maintenance revenue previously held by original equipment manufacturers. Ambulatory surgical centers exhibit the highest price sensitivity due to capital constraints and shorter equipment depreciation schedules, while academic medical centers prioritize performance specifications over unit economics.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for superconducting magnet components and precision RF coil assemblies. Manufacturing gravity centers on Germany for high-field MRI systems, Japan for spine-specific phased-array coils, and the United States for helium cryogen distribution infrastructure. Component sourcing draws from Qatar for helium supply, Japanese precision engineering firms for RF arrays, and German specialty steel producers for gradient coil housings. Single-source vulnerability concentrates in helium refining capacity, where export restrictions from Qatar and the United States create supply interruption exposure. Distribution runs through original equipment manufacturer direct sales forces for hospital networks and specialized imaging distributors for orthopedic clinic segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI-assisted diagnostic software is compressing the interval between image acquisition and surgical decision-making, creating a regulatory and technological inflection that rewards first movers in algorithmic integration. This disruption dynamic favors participants who can bridge hardware-software convergence faster than traditional equipment replacement cycles.
For Market Incumbents: Harden installed base retention by embedding AI algorithms directly into imaging platforms rather than treating analytics as aftermarket add-ons, neutralizing independent software vendors seeking API access. Pursue backward integration into precision RF coil manufacturing to reduce dependence on Japanese and German component suppliers. Prioritize multi-year service contract structures that lock in maintenance revenue against third-party service organization encroachment.
For New Entrants and Emerging Players: Establish a beachhead in tier-2 and tier-3 Indian hospital networks where government PLI scheme incentives are attracting assembly investments and procurement committees lack incumbent loyalty. Target the intraoperative imaging convergence segment, where integration of 3D C-arm fluoroscopy with surgical navigation systems creates new product categories without requiring full MRI or CT platform development. Lead with software-as-a-medical-device regulatory pathways rather than hardware certification to accelerate time-to-revenue.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among independent service organizations capturing maintenance contracts from aging installed bases of GE, Siemens, and Philips systems. Long-term viability in this market hinges on regulatory compliance capabilities for EU AI Act and FDA software-as-a-medical-device pathways, making European regulatory affairs infrastructure a scarce asset. The signal to watch is CMS reimbursement determinations for AI-enhanced spinal imaging, which will reshape capital allocation cycles and equipment replacement timing across United States hospital networks.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Algorithm Integration | Embedded vertebral segmentation in CT and MRI platforms compresses diagnostic interpretation timelines for United States hospitals. |
| Helium Supply Diversification | Alternative cryogen technologies reduce exposure to Qatar and United States export restriction risks for superconducting MRI systems. |
| Orthopedic Clinic Partnership | Direct equipment placement in Texas and Florida ambulatory surgical centers captures spinal fusion procedure migration from hospitals. |
| EU AI Act Compliance Investment | Early alignment with high-risk AI system documentation requirements positions vendors for preferential procurement in German and French hospital systems. |
| Photon-Counting CT Development | Spectral tissue characterization at reduced dose levels enables bone mineral density quantification for complex revision spine surgery planning. |
Research Approach
Operator-level perspectives from hospital purchasing committee members, biomedical engineers at academic medical centers, GPO contracts managers, and orthopedic clinic administrators anchored the qualitative base for this analysis. Primary interview data combined with secondary validation from FDA 510(k) premarket notification databases, CMS Medicare coverage determinations, ISO 13485 quality management audit records, and hospital procurement databases. Bottom-up equipment shipment tracking and top-down health system capital expenditure analysis provided triangulation across quantitative estimates.
Scenario-bracketing around helium supply disruption, CMS reimbursement acceleration, and AI diagnostic coding adoption shaped the projection framework across the analysis window. Segmentation dimensions modeled include product type, end user category, technology generation, and clinical application urgency. CAGRs were derived from installed base replacement cycle analysis and procedure volume migration patterns between inpatient and outpatient settings. Forecast inputs incorporated health system consolidation trends in the United States and PLI scheme incentive utilization rates in India.
Stress conditions across helium price volatility, FDA software clearance timelines, and orthopedic clinic capital availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding reimbursement pathway evolution and regulatory harmonization between FDA and EU MDR frameworks. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
India Ultrasound Devices Market
Medical Imaging
Spain Mammography Market
Medical Imaging
3D Imaging Surgical Solution Market
Medical Imaging
Panoramic and Cephalometric Radiography Systems Market
Medical Imaging
Mexico Digital Radiology Market
Medical Imaging
Australia Digital X-Ray Market
Medical Imaging
Canada Nuclear Medicine Market
Medical Imaging
Fluoroscopy Market
Medical Imaging
Global Medical Cameras Market
Medical Imaging
Retinal Imaging Devices Market
Medical Imaging
Global Veterinary CT Scanner Market
Medical Imaging
Global Image-Guided Radiation Therapy (IGRT) Market
Medical Imaging
Spain Computed Tomography Market
Medical Imaging
Brazil Digital Radiology Market
Medical Imaging
Global Mobile Medical Imaging Services Market
Medical Imaging
Medical Holography Market