
 Image Guided Systems Market | 2026-2036
Image Guided Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Image Guided Systems Market Foresight
Hospital procurement channels for capital imaging equipment is tilting toward bundled service contracts and long-term equipment partnerships. Siemens Healthineers leverages its installed base of angiography suites to sustain recurring revenue streams across European hospital networks. Medtronic anchors its position through deep integration of navigation platforms with spine and cranial surgical workflows. Koninklijke Philips N.V. competes by concentrating on hybrid operating room configurations that merge diagnostic imaging with therapeutic intervention.
Image guided systems comprise integrated hardware-software platforms that merge real-time anatomical visualization with instrument tracking, typically achieving sub-millimeter spatial accuracy through electromagnetic or optical localization. These systems enable surgeons to navigate complex anatomy without open exposure, reducing operative time and tissue disruption. CT scanner deployments dominate hospital capital budgets among product types, while optical coherence tomography represents the fastest-expanding technology segment driven by ophthalmologic and intravascular applications. Neurology applications command premium pricing due to the precision requirements of functional neurosurgery, whereas orthopedics offers volume scale through joint replacement navigation.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and commercial launch sequencing for manufacturers. Japan's PMDA and China's NMPA impose additional localization testing that filters market entrants without regional regulatory infrastructure. Stakeholders must monitor reimbursement code evolution for image-guided procedures across Medicare, national health services, and private payers to anticipate demand inflection points.
Market Dynamics
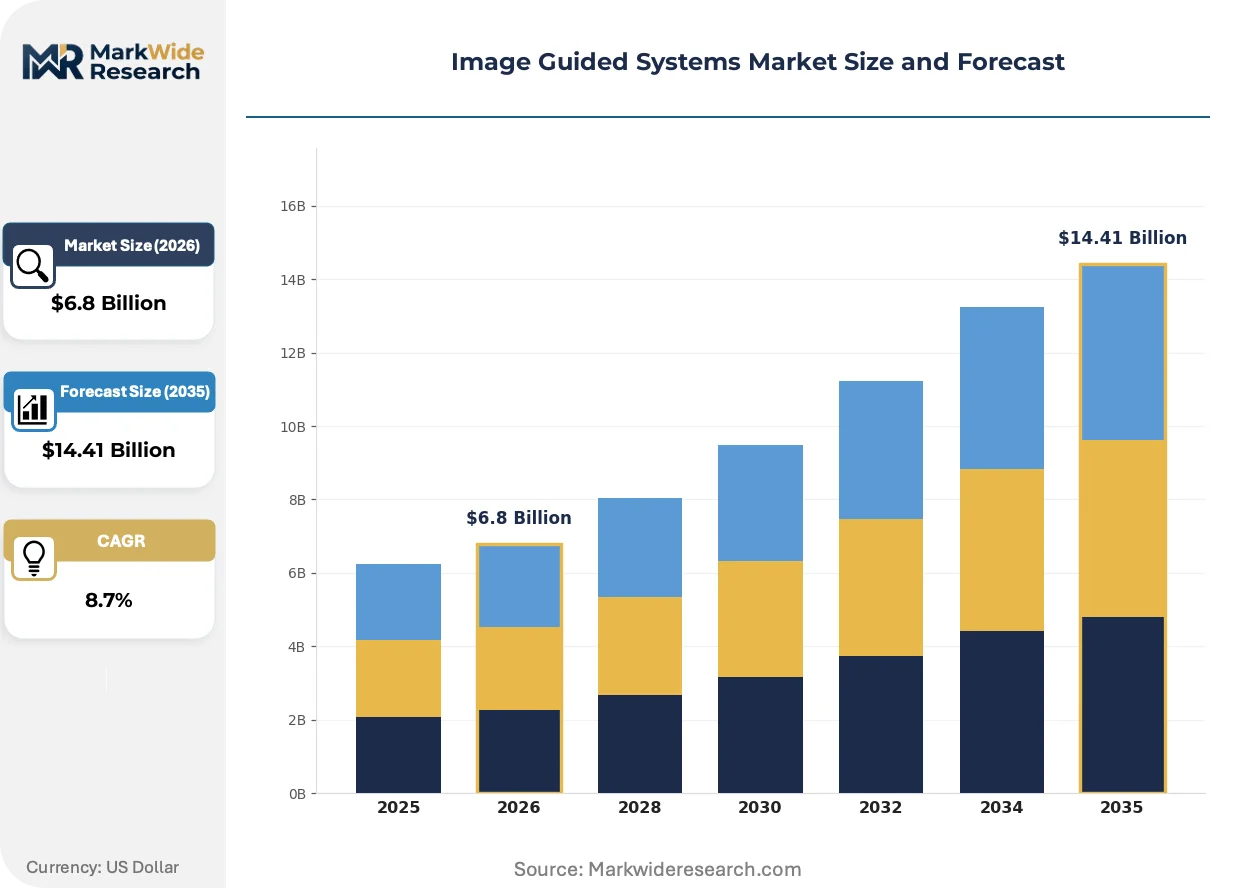
Hospital capital equipment procurement is consolidating around multi-year service partnerships that bundle hardware, software maintenance, and clinical training, compressing vendor margins while locking in installed base protection for incumbent platform providers.
Growth Catalysts
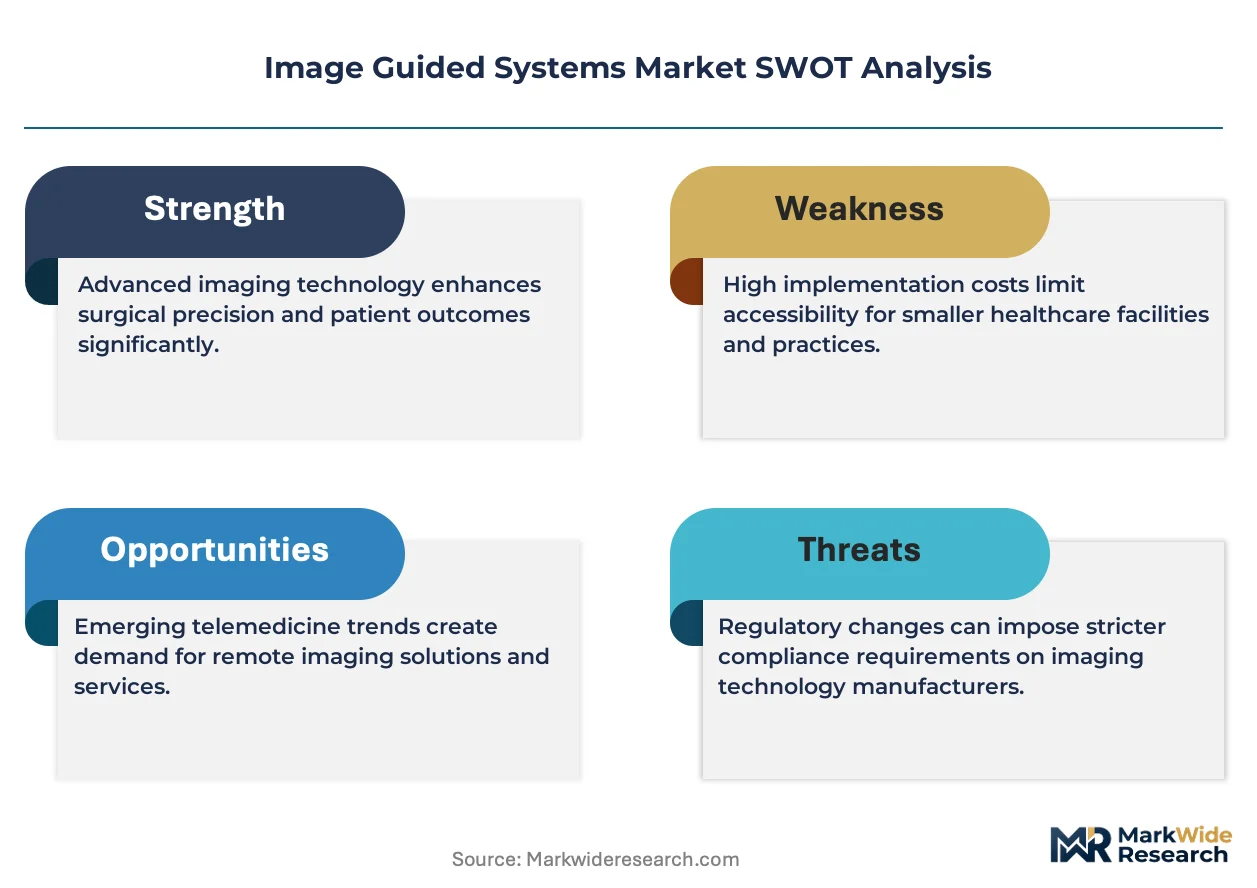
- EU MDR conformity assessment pathways:Strengthened post-market surveillance requirements under the Medical Device Regulation are filtering out marginal competitors and concentrating demand among established CE-marked platform vendors with robust quality management systems.
- Hybrid operating room infrastructure:Academic medical centers in Germany and the United States are retrofitting surgical suites with integrated imaging-navigation systems to enable single-session diagnosis-to-treatment workflows for complex cranial and spinal procedures.
- Optical coherence tomography:Intravascular and ophthalmologic applications are expanding the addressable procedure volume beyond traditional CT-guided navigation, with sub-millimeter resolution enabling microsurgical interventions previously requiring open exposure.
Market Restraints
- Superconducting magnet supply concentration:Liquid helium dependency and specialized magnet manufacturing capacity in Japan and Germany create input bottlenecks for high-field intraoperative MRI systems, extending delivery timelines to 18-24 months.
- FDA 510(k) clearance friction:Enhanced scrutiny of predicate device equivalence for software-as-medical-device navigation algorithms is lengthening premarket notification review cycles and delaying commercial launches for algorithm-dependent platforms.
- Fluoroscopy dose accumulation:Radiation exposure concerns in pediatric and repeat-procedure populations are limiting application expansion in orthopedics, where alternative navigation modalities carry higher capital cost per procedure.
Strategic Opportunities
- Japan PMDA localization requirements:Mandatory domestic clinical testing and Japanese-language labeling create defensive moats for vendors with established Tokyo or Osaka regulatory infrastructure, filtering direct import competition.
- Augmented reality-optical convergence:Head-mounted displays with integrated instrument tracking are enabling surgeon-agnostic navigation assistance in community hospitals lacking dedicated neurosurgical or orthopedic navigation specialists.
- China NMPA innovation fast-track:Priority review pathways for domestically manufactured Class III devices with novel clinical indications are incentivizing joint ventures with local imaging equipment producers for regional market access.
Industry Challenges
- Electromagnetic interference engineering:Operating room density of RF-emitting devices from anesthesia monitors to surgical robots requires specialized shielding design and site-specific validation, extending installation commissioning timelines.
- Cross-modality registration accuracy:Preoperative CT-to-intraoperative ultrasound or MRI alignment errors in deformable tissue environments demand continuous algorithm refinement and clinical workflow adaptation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Image Guided Systems Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluoroscopy Systems, MRI Systems, Ultrasound Equipment, CT Scanners Technology: Computed Tomography, Magnetic Resonance Imaging, Ultrasound, Optical Coherence Tomography Application: Cardiology, Oncology, Orthopedics, Neurology End User: Hospitals, Clinics, Diagnostic Centers, Research Institutions |
| Companies Covered | Medtronic, Siemens Healthineers, Koninklijke Philips N.V., GE Healthcare, Stryker, Brainlab AG, Analogic Corporation, Varian Medical Systems, Inc., Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Image Guided Systems Market Shifts & Advancements
Navigation platform architecture is converging toward open-application ecosystems that decouple hardware instrumentation from proprietary software stacks, enabling third-party algorithm deployment and challenging traditional bundled pricing models.
Intraoperative cone-beam CT is collapsing the spatial and temporal gap between diagnostic imaging and surgical intervention, enabling real-time anatomical verification without patient transport. Orthopedic and trauma centers in the United States are deploying these systems for complex pelvic and spinal fixation procedures. The technology is collapsing revenue per procedure for standalone diagnostic CT while capturing premium reimbursement for image-guided surgical codes.
EU MDR technical documentation requirements for software lifecycle processes are forcing navigation platform vendors to restructure quality management systems around IEC 62304 medical device software standards. Manufacturers with legacy predicate devices face substantial retrospective clinical evidence generation costs. The spine navigation segment is responding with controlled rollout strategies prioritizing European markets with established notified body relationships.
Academic medical center procurement committees are consolidating vendor relationships through enterprise-wide capital equipment frameworks that span diagnostic imaging, surgical navigation, and post-acute monitoring. Equipment distributors with localized clinical engineering capabilities are displacing direct manufacturer sales teams in secondary and tertiary hospital markets. Germany's university hospital procurement consortia exemplify this concentration, with three purchasing alliances controlling access to over sixty percent of hybrid operating room installations.
Image Guided Systems Market Segmentation
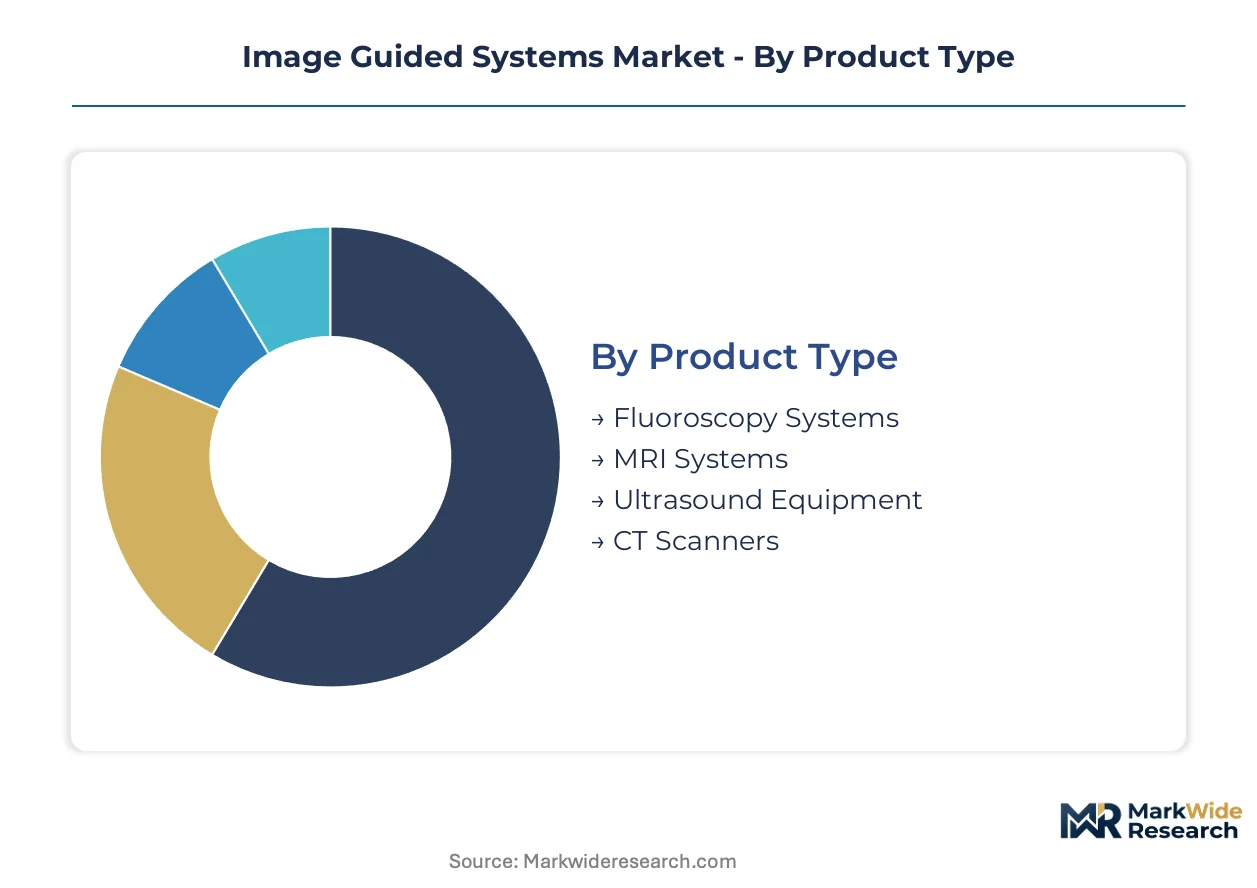
Segmentation in image guided systems reveals distinct procurement cycles and margin profiles across hardware platforms, imaging modalities, clinical applications, and facility types. Understanding these divides enables vendors to align R&D investment with replacement timelines and reimbursement trajectories.
Product Type:
Replacement cycles vary dramatically across modalities, with portable C-arms turning over every 5-7 years while fixed-room MRI suites operate for 12-15 years before decommissioning.
- CT Scanners:High-throughput diagnostic platforms with sub-millimeter slice resolution dominate hospital capital budgets and hybrid operating room installations. Demand concentrates in Germany and the United States where academic medical centers anchor multi-million dollar procurement frameworks for intraoperative cone-beam configurations.
- MRI Systems:Superconducting magnet-based platforms achieve superior soft-tissue contrast for neurosurgical and orthopedic navigation. Liquid helium supply constraints from Japanese and German magnet manufacturers extend delivery timelines to 18-24 months, filtering demand toward established vendors with captive supply agreements.
- Fluoroscopy Systems:Real-time X-ray guidance for interventional cardiology and trauma surgery with lower capital cost per unit.
- Ultrasound Equipment:Portable and cart-based systems enabling point-of-care guidance without ionizing radiation exposure.
CT scanners anchor the volume base while MRI systems gain share at the steepest rate among high-field intraoperative configurations.
Technology:
Cost tier stratification separates premium diagnostic modalities from emerging optical technologies disrupting microsurgical applications.
- Computed Tomography:X-ray-based volumetric reconstruction enabling bone and soft-tissue visualization with sub-millimeter spatial accuracy. Orthopedic and trauma centers in the United States deploy intraoperative cone-beam variants for real-time anatomical verification during complex spinal fixation.
- Optical Coherence Tomography:Near-infrared interferometry achieves cellular-level resolution for ophthalmologic and intravascular applications. Sub-millimeter imaging capability enables microsurgical interventions previously requiring open exposure, expanding addressable procedure volume beyond traditional navigation markets.
- Magnetic Resonance Imaging:Magnetic field-based soft-tissue contrast without ionizing radiation, essential for functional neurosurgery and pediatric applications.
- Ultrasound:Acoustic-wave real-time imaging with lowest cost per procedure and zero radiation burden.
Computed tomography commands the largest installed base while optical coherence tomography climbs fastest among emerging navigation modalities.
Application:
Procedure volume and pricing power diverge sharply between high-acuity functional interventions and routine joint replacement workflows.
- Neurology:Functional neurosurgery and deep brain stimulation demand sub-millimeter accuracy for electrode placement and tumor resection. Premium pricing reflects precision requirements and malpractice exposure, with academic medical centers in Japan and Germany representing concentrated demand for navigation-integrated platforms.
- Orthopedics:Joint replacement and spinal fixation navigation offers volume scale through standardized procedural protocols. Community hospitals across the United States adopt these systems to reduce revision rates and align with bundled payment incentives for episode-of-care cost control.
- Cardiology:Electrophysiology and structural heart interventions requiring real-time fluoroscopic or intracardiac echocardiographic guidance.
- Oncology:Biopsy guidance and tumor ablation leveraging cross-modal registration between preoperative planning and intraoperative verification.
Orthopedics anchors the procedure volume base while neurology captures the steepest pricing premium per navigation case.
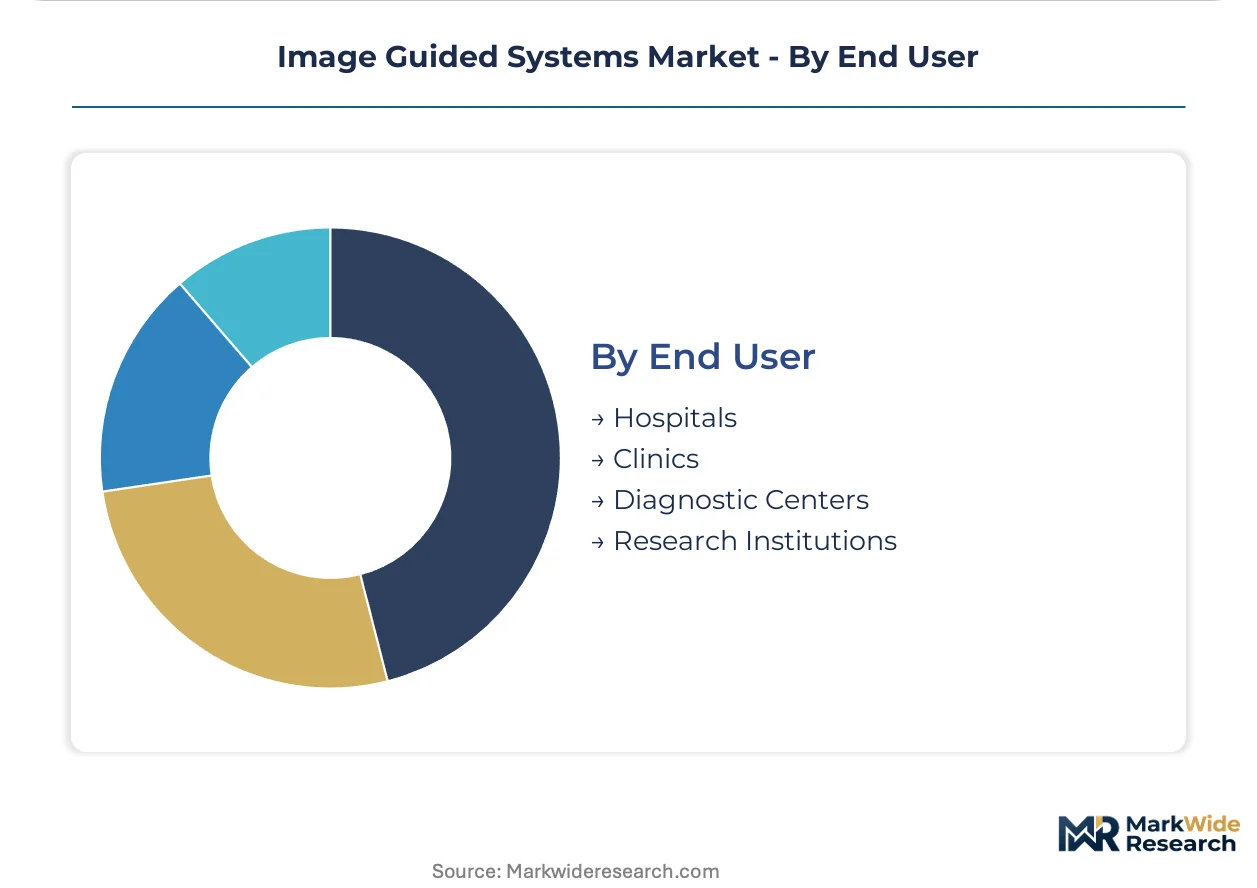
End User:
Customer type determines procurement authority, with centralized hospital systems negotiating enterprise frameworks while independent clinics prioritize lease-based access models.
- Hospitals:Integrated delivery networks and academic medical centers command capital budgets exceeding individual diagnostic centers by an order of magnitude. Germany's university hospital procurement consortia exemplify concentration, with three purchasing alliances controlling access to over sixty percent of hybrid operating room installations.
- Diagnostic Centers:Outpatient imaging facilities focus on throughput optimization and rapid patient turnover for reimbursed screening procedures.
- Clinics:Ambulatory surgical centers adopting leased or refurbished navigation platforms for specific high-volume orthopedic procedures.
- Research Institutions:Preclinical and clinical trial sites requiring experimental imaging configurations with regulatory flexibility for investigational device protocols.
Hospitals anchor capital equipment demand while diagnostic centers expand most quickly among outpatient navigation service providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German university hospitals negotiate hybrid operating room installations at pricing premiums unavailable to Latin American purchasers, where refurbished C-arm imports dominate capital procurement.
United States
Academic medical centers in Boston and Houston drive demand for intraoperative cone-beam CT configurations. FDA 510(k) clearance timelines for navigation software now exceed fourteen months. The Texas Medical Center anchors multi-hospital procurement consortia consolidating vendor relationships.
Germany
Three purchasing alliances control sixty percent of hybrid operating room installations across university hospital networks. EU MDR conformity assessments filter demand toward established CE-marked platform vendors. Bavarian medical device clusters around Munich supply electromagnetic tracking components.
Japan
PMDA localization requirements mandate domestic clinical testing and Japanese-language labeling for Class III navigation devices. Tokyo academic centers concentrate functional neurosurgery demand for sub-millimeter accuracy systems. Osaka-based magnet manufacturers face liquid helium supply constraints extending MRI delivery timelines.
China
NMPA priority review pathways incentivize joint ventures with domestic imaging equipment producers. Yangtze River Delta hospitals retrofit surgical suites with navigation-integrated platforms. Shanghai medical device parks host regulatory infrastructure for innovation fast-track submissions.
United Kingdom
NHS England procurement frameworks bundle hardware, software maintenance, and clinical training into multi-year service partnerships. London teaching hospitals anchor demand for augmented reality-optical convergence systems. Oxford-Cambridge corridor research institutions pilot investigational device protocols.
Image Guided Systems Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying tracking sensors, electromagnetic coils, and optical arrays. The vendor base concentrates around three multinational conglomerates with captive installed bases, while mid-tier navigation software houses compete on algorithmic registration accuracy. Two strategic archetypes dominate: diversified imaging conglomerates leveraging angiography suite footprints, and surgical workflow specialists integrating navigation with instrument delivery. Competitive moves center on multi-year service partnership expansion and open-application ecosystem development challenging proprietary software stacks.
Among diversified imaging conglomerates, Siemens Healthineers and Koninklijke Philips N.V. exemplify platform integrators capitalizing on hybrid operating room configurations. Medtronic occupies a distinct position anchoring navigation platforms to spine and cranial surgical workflows. These three entities represent divergent strategic postures: German-engineered system bundling, Dutch diagnostic-therapeutic convergence, and Irish-American surgical instrument integration.
| Leading Market Players |
|---|
| Medtronic |
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| GE Healthcare |
| Stryker |
| Brainlab AG |
| Analogic Corporation |
| Varian Medical Systems, Inc. |
| Olympus Corporation |
| Others |
Supply & Pricing Matrix
Munich's Bavarian medical device cluster anchors electromagnetic tracking component production, with capacity constraints at specialized coil manufacturers translating directly into pricing premiums for configured-to-order navigation platforms. Academic medical centers in Germany and the United States absorb these premiums through multi-year service partnerships, while secondary hospitals face compressed margins on standard configurations.
Pricing Analysis
Configured-to-order pricing for hybrid operating room installations commands substantial premiums over standard C-arm configurations, with customization depth and after-sales service bundling as the primary differentiation drivers. Three-tier pricing structure across premium, standard, and economy levels stratifies the market, with premium tiers capturing academic medical center procurement and economy tiers serving refurbished equipment channels. Cost compression in the standard tier is intensifying because of consolidated hospital purchasing alliances negotiating enterprise-wide frameworks. Community hospitals and ambulatory surgical centers exhibit the highest price sensitivity, whereas integrated delivery networks with captive capital budgets demonstrate the least.
Supply Chain Analysis
Superconducting magnet feedstock draws from concentrated manufacturing capacity in Japan and Germany, with liquid helium supply chains tethered to Qatar and the United States. Electromagnetic tracking coils, optical sensor arrays, and specialized RF shielding materials represent critical component dependencies. Single-source vulnerability in liquid helium refining creates structural risk for high-field intraoperative MRI system delivery timelines. Distribution runs through authorized equipment distributors with localized clinical engineering capabilities, displacing direct manufacturer sales teams in secondary markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent navigation platform vendors face substitution pressure from augmented reality head-mounted displays enabling surgeon-agnostic navigation assistance without proprietary hardware stacks. Defense against this threat requires strategic repositioning around data moats and workflow integration depth.
For Market Incumbents: Build installed base data moats by deepening algorithmic registration accuracy in deformable tissue environments, creating switching costs that AR-native entrants cannot replicate. Anchor position through backward integration into electromagnetic tracking component production, securing captive supply from Munich and Osaka manufacturing clusters. Prioritize FDA 510(k) clearance pipeline investment to maintain predicate device advantages against software-as-medical-device challengers.
For New Entrants and Emerging Players: Mid-market community hospitals in the United States represent the most penetrable entry point, lacking dedicated neurosurgical navigation specialists and receptive to leased platform models. Optical coherence tomography modules for ophthalmologic applications offer white-space expansion beyond saturated CT-guided navigation markets. Pursue go-to-market alignment with equipment distributors possessing localized clinical engineering capabilities rather than direct sales force buildout.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because EU MDR conformity assessment requirements are filtering marginal competitors and concentrating demand among established CE-marked platform vendors with robust quality management systems. Target acquisition candidates with established notified body relationships and retrospective clinical evidence packages for legacy predicate devices. Monitor reimbursement code evolution for image-guided procedures across Medicare and national health services as the critical inflection signal for demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation requirements filter demand toward established vendors with notified body relationships. |
| Hospital System Partnership | Germany's university hospital procurement consortia control access to over sixty percent of hybrid operating room installations. |
| Software Companion Development | Open-application ecosystems decouple hardware instrumentation from proprietary stacks, challenging bundled pricing models. |
| Reimbursement Strategy | Medicare and private payer code evolution for image-guided procedures determines demand inflection timing. |
| FDA Submission | Enhanced scrutiny of predicate device equivalence for navigation algorithms lengthens premarket notification review cycles. |
Research Methodology
Initial hypotheses were tested against primary input from hospital purchasing committee chairs, biomedical engineers, GPO contracts managers, and navigation platform clinical specialists and refined through secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare reimbursement code updates. Bottom-up segmentation modeling triangulated with top-down market sizing approaches.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, imaging modality, clinical application, and facility tier. CAGRs were derived from procedure volume trajectories and capital equipment replacement cycle analysis, incorporating inputs from superconducting magnet delivery timelines and reimbursement code adoption curves.
Stress conditions across liquid helium supply disruptions, FDA clearance timeline extensions, and EU MDR retrospective clinical evidence costs were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding hospital capital budget trajectories and regulatory pathway evolution. Cross-checking against hospital procurement database benchmarks and notified body approval timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global Artificial Intelligence in MRI Market
Medical Imaging
China Mammography Market
Medical Imaging
Global Colposcopy Market
Medical Imaging
Retinal Imaging Devices Market
Medical Imaging
US Magnetic Resonance Imaging Coils Market
Medical Imaging
South America CT Market
Medical Imaging
Global Super Resolution Microscopes Market
Medical Imaging
Germany Digital Pathology Market
Medical Imaging
Ultrasound Consoles and Transducers Market
Medical Imaging
US Medical Imaging Market
Medical Imaging
Cone Beam Computed Tomography (CBCT) System Market
Medical Imaging
X-Ray Flat Panel Detectors Market
Medical Imaging
AI-Enabled Diagnostic Imaging Market
Medical Imaging
United States Digital X-Ray Devices Market
Medical Imaging
Industrial Radiography Market
Medical Imaging
Radiology Services Market