
 Global Sodium Chlorate Market | 2026-2036
Global Sodium Chlorate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sodium Chlorate Market Foresight
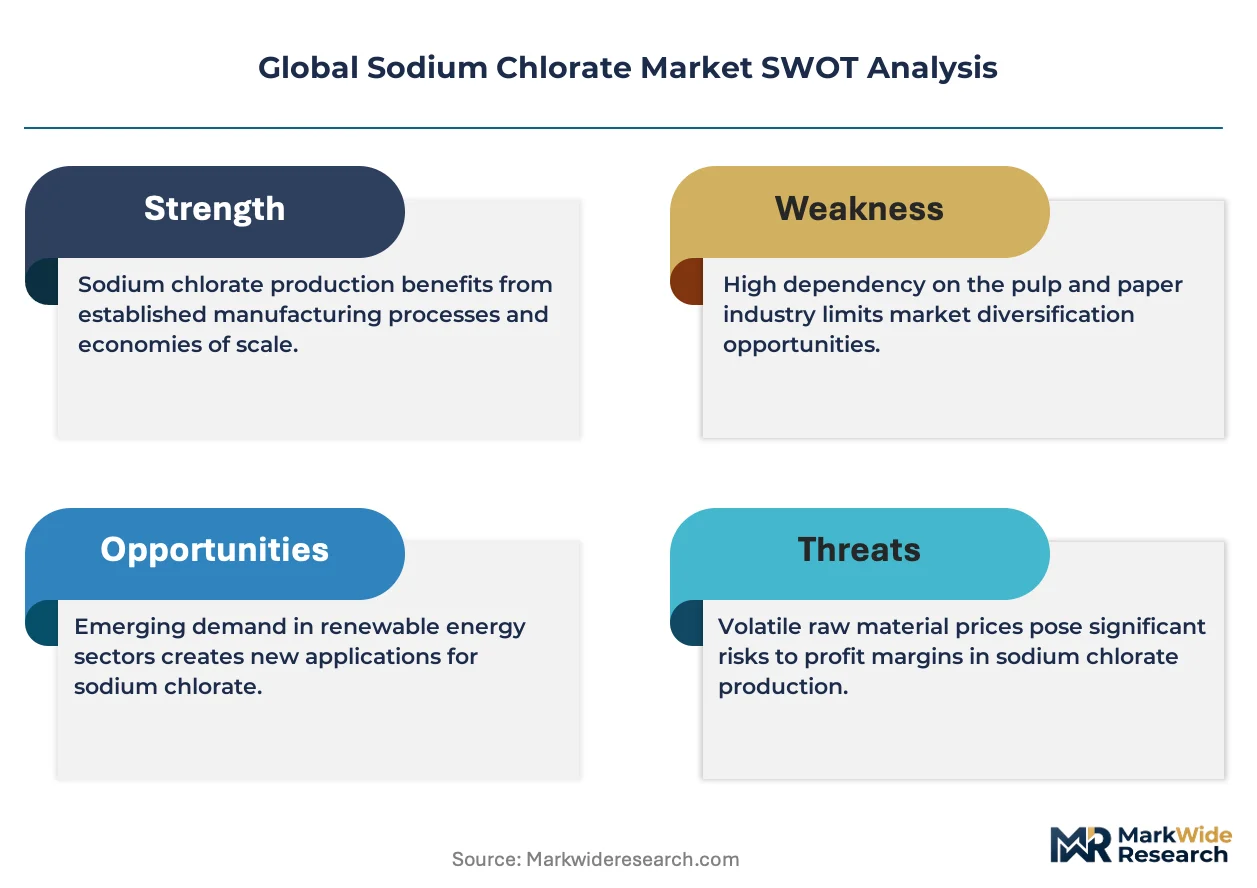
Canadian electrochemical production capacity is shifting toward higher-purity outputs as environmental permitting tightens around the Great Lakes basin. ERCO Worldwide leverages its integrated chlor-alkali infrastructure to sustain cost leadership across North American pulp mill supply chains. Kemira anchors its competitive position through specialized logistics networks serving Scandinavian paper producers. Nouryon differentiates via membrane-cell technology leadership that reduces energy intensity in sodium chlorate crystallization.
Sodium chlorate is an inorganic salt produced through electrolysis of sodium chloride brine in undivided cells, yielding white crystalline solids with strong oxidizing properties used primarily as a chlorine dioxide precursor for pulp delignification. Industrial grade material dominates volume flows due to established specifications for bleaching applications, while technical grade formulations command premium positioning in herbicide intermediate production where impurity thresholds are stricter. Pulp mills represent the most concentrated end user segment, though water treatment plants represent an expanding demand pocket as municipal disinfection protocols evolve.
EPA effluent guidelines under the Clean Water Act constrain discharge profiles from US-based electrochemical facilities, while REACH registration requirements in Europe mandate comprehensive toxicity documentation for sodium chlorate imports. Brazil's ANVISA and China's MEE enforce divergent purity standards that fragment product certification obligations across export destinations. Stakeholders must monitor regulatory divergence between jurisdictions to align capacity investments with emerging compliance thresholds and end-user specification migrations.
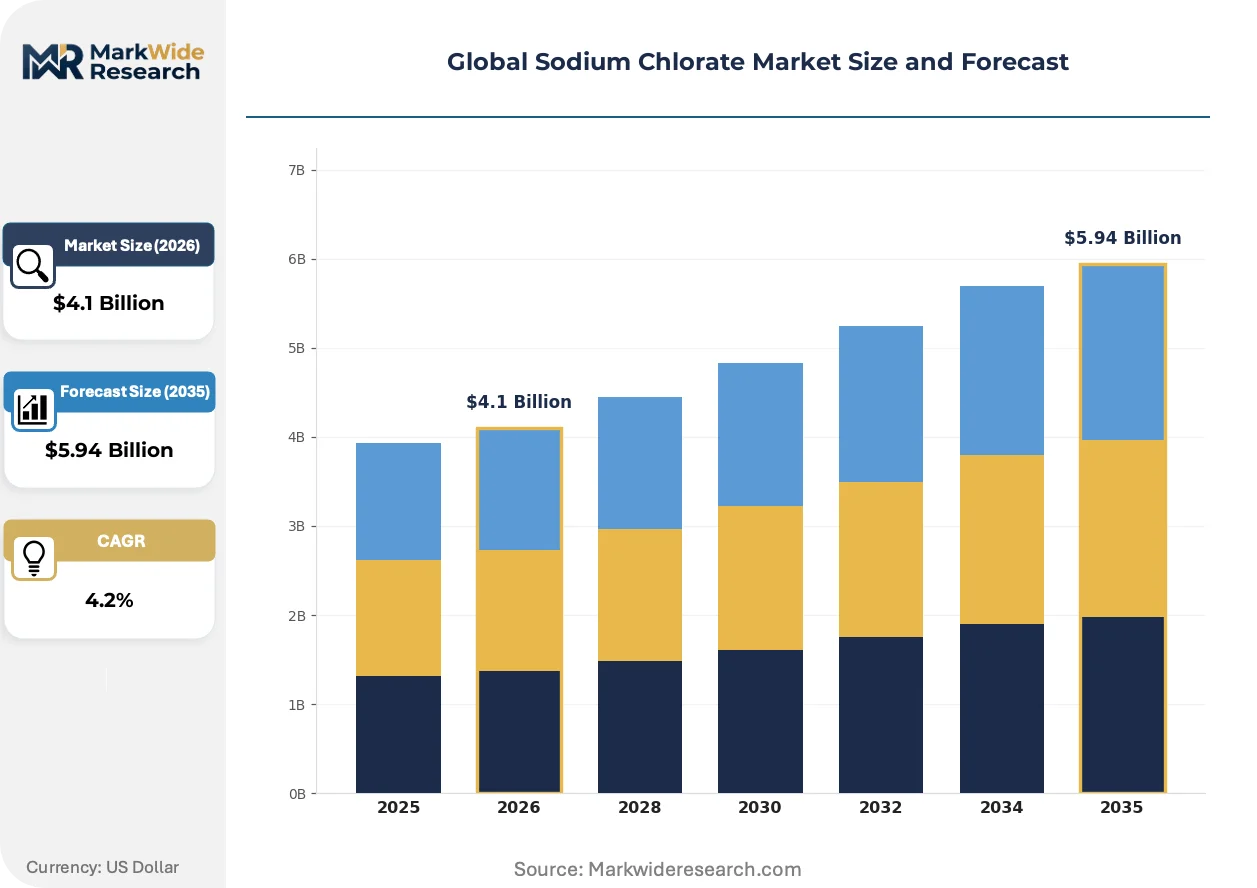
Market Dynamics
Electrochemical capacity concentration around the Great Lakes basin is reshaping supply security calculations as EPA effluent guidelines tighten discharge permitting timelines and force crystallization technology upgrades.
Growth Catalysts
- Pulp export expansion:Brazil's cellulose sector is scaling bleaching chemical demand as export terminal capacity doubles at Santos port facilities.
- EU F-Gas Regulation:Phasedown of fluorinated gases is redirecting paper mill disinvestment toward chlorine dioxide precursor chemistry.
- Membrane-cell advancement:Energy intensity reductions in electrochemical production are compressing unit economics for high-purity crystalline outputs.
Market Restraints
- Brine supply volatility:Sodium chloride feedstock costs fluctuate with winter road-salt demand cycles and mining logistics constraints.
- Great Lakes concentration risk:Canadian and US electrochemical clusters face simultaneous environmental permitting delays that bottleneck regional supply.
- Peracetic acid substitution:Food-contact paper segments are piloting alternative delignification chemistries that bypass chlorine dioxide generation entirely.
Strategic Opportunities
- Water treatment underpenetration:Municipal disinfection protocols in India and Southeast Asian megacities remain below chlorate adoption thresholds.
- Herbicide intermediate premiumization:Technical-grade specifications for agricultural chemical synthesis command pricing spreads over industrial material.
- Green hydrogen co-location:Chlor-alkali plant retrofits for electrolyzer integration create stranded chlorate capacity repurposing potential.
Industry Challenges
- Electrochemical engineering talent scarcity:Undivided cell design expertise is concentrating among retiring cohorts at legacy Canadian producers.
- Multi-jurisdiction certification timelines:REACH registration, ANVISA approval, and MEE compliance documentation create staggered market entry costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sodium Chlorate Market |
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $5.94 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Grade, Industrial Grade, Technical Grade, Food Grade, Pharmaceutical Grade Application: Pulp & Paper Bleaching, Herbicides Production, Water Treatment, Dye Industry, Explosives Manufacturing, Chemical Synthesis End User: Pulp Mills, Chemical Manufacturers, Agriculture Firms, Water Treatment Plants, Textile Dyeing Units, Mining Companies Packaging Type: Big Bags, Jumbo Bags, Drums, Bulk Containers, Fiber Drums, Cardboard Boxes |
| Companies Covered | ERCO Worldwide, Nouryon, Kemira, Arkema S.A., Eka Chemicals, Inner Mongolia Lantai Industry Co., Ltd., Shree Chlorates, Chemtrade Electrochem Inc., China First Chemical Holdings Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sodium Chlorate Market Shifts & Advancements
Membrane-cell technology diffusion and regulatory chemistry substitution mandates are compressing legacy production economics while opening specialty-grade positioning for electrochemical producers with purification capabilities.
Advanced membrane electrolysis is modularizing sodium chlorate crystallization workflows. Scandinavian pulp mills are adopting skid-mounted generation units that co-locate chlorine dioxide precursor production with bleaching lines. This distributed architecture is modularizing supply chain risk away from bulk chemical transport toward captive electrochemical capacity.
REACH registration requirements are mandating comprehensive toxicity dossiers for sodium chlorate imports into European Union member states. ECHA substance evaluation timelines are extending certification cycles and favoring incumbent registrants with existing data packages. Specialty chemical distributors are consolidating import permits to amortize compliance costs across larger volume bases.
Municipal procurement offices are unbundling chemical supply from equipment service contracts in water treatment applications. Traditional bundled vendors face disintermediation as direct material sourcing through regional chemical distributors accelerates. Brazilian state water utilities are pioneering this separation to improve transparency in disinfection chemical expenditure audits.
Global Sodium Chlorate Market Segmentation
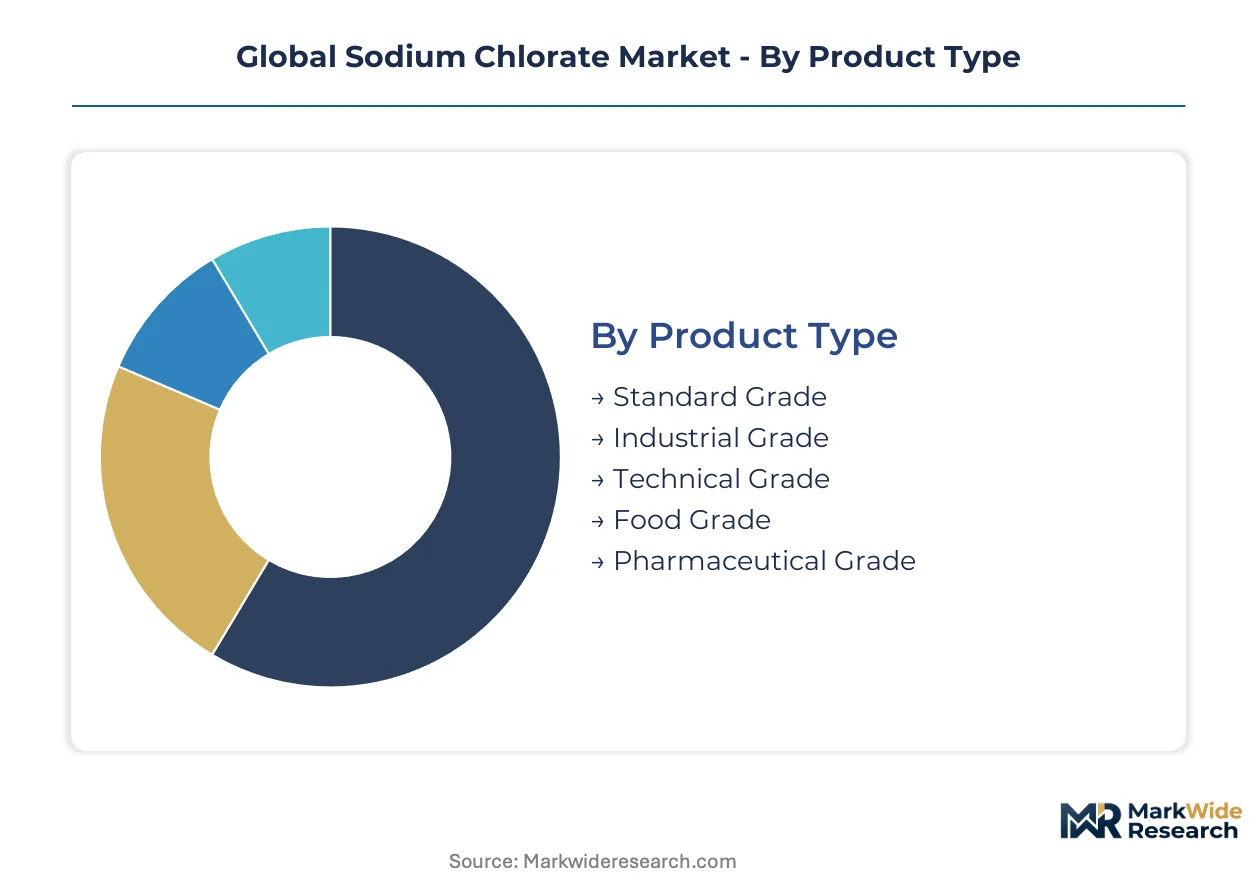
Segmentation in sodium chlorate markets reveals how capital intensity, regulatory thresholds, and logistics requirements fragment production economics across purity grades and packaging formats. Electrochemical producers must align crystallization investments with end-user specification bands to avoid stranded capacity.
Product Type:
Capital intensity concentrates in membrane-cell retrofits and multi-stage purification trains that separate commodity outputs from premium grades.
- Standard Grade:Baseline crystalline material meeting minimum oxidizing potency thresholds for bulk chlorine dioxide generation. Pulp mills in Brazil absorb this volume as Santos port expansion doubles cellulose export terminal capacity.
- Industrial Grade:Intermediate purity band with controlled moisture content and particle size distribution for automated handling systems. Canadian Great Lakes basin producers dominate this tier as EPA effluent guidelines force crystallization technology upgrades that incidentally improve grade consistency.
- Technical Grade:Stricter impurity limits for herbicide intermediate synthesis where trace metal contamination degrades downstream agricultural chemical performance.
- Food Grade:Compliance with food-contact migration limits required in specialized packaging sterilization applications.
- Pharmaceutical Grade:Highest purity tier with comprehensive heavy metal and microbial specification documentation for API synthesis.
Industrial grade absorbs the bulk of installed capacity; technical grade is expanding most quickly as agricultural chemical intermediate demand intensifies.
Application:
Volume concentration follows pulp sector capital cycles, while smaller applications command margin premiums through specification complexity.
- Pulp & Paper Bleaching:Chlorine dioxide precursor consumption for lignin removal in kraft pulping sequences. Scandinavian mills are adopting skid-mounted generation units that co-locate precursor production with bleaching lines, modularizing supply chain risk away from bulk transport.
- Herbicides Production:Technical-grade sodium chlorate serves as oxidation feedstock for glyphosate and paraquat synthesis intermediates. Brazil's expanding soy and corn cultivation belts are driving ANVISA-compliant import volume as domestic agrochemical formulation capacity scales.
- Water Treatment:Municipal disinfection protocols in Indian and Southeast Asian megacities remain below chlorate adoption thresholds despite pilot programs in state water utilities.
- Dye Industry:Oxidizing agent for vat dye synthesis and textile bleaching sequences in South Asian manufacturing clusters.
- Explosives Manufacturing:Controlled decomposition properties for blasting agent formulation in regulated mining jurisdictions.
- Chemical Synthesis:Broad oxidation chemistry applications across specialty chemical production.
Pulp bleaching commands the dominant volume position; water treatment is gaining share fastest as municipal procurement unbundles chemical supply from equipment service contracts.
End User:
Procurement scale and specification discipline separate concentrated industrial buyers from fragmented specialty consumers.
- Pulp Mills:Integrated bleaching chemical consumers with captive chlorine dioxide generation or bulk precursor supply contracts. Brazilian cellulose exporters are consolidating supplier relationships as port capacity expansion synchronizes with pulp line commissioning schedules.
- Chemical Manufacturers:Diversified oxidation chemistry users spanning herbicide, dye, and specialty intermediate production with variable purity requirements.
- Agriculture Firms:Direct procurement of technical-grade material for on-site herbicide synthesis or toll manufacturing arrangements.
- Water Treatment Plants:Municipal and industrial disinfection facilities with emerging chlorate adoption in developing megacity markets.
- Textile Dyeing Units:Regional manufacturing clusters in South Asia with seasonal demand patterns tied to fashion industry procurement cycles.
- Mining Companies:Explosives formulation consumers in regulated jurisdictions with strict precursor tracking requirements.
Pulp mills anchor procurement volume; water treatment plants are climbing the fastest as Brazilian state utilities pioneer direct material sourcing transparency.
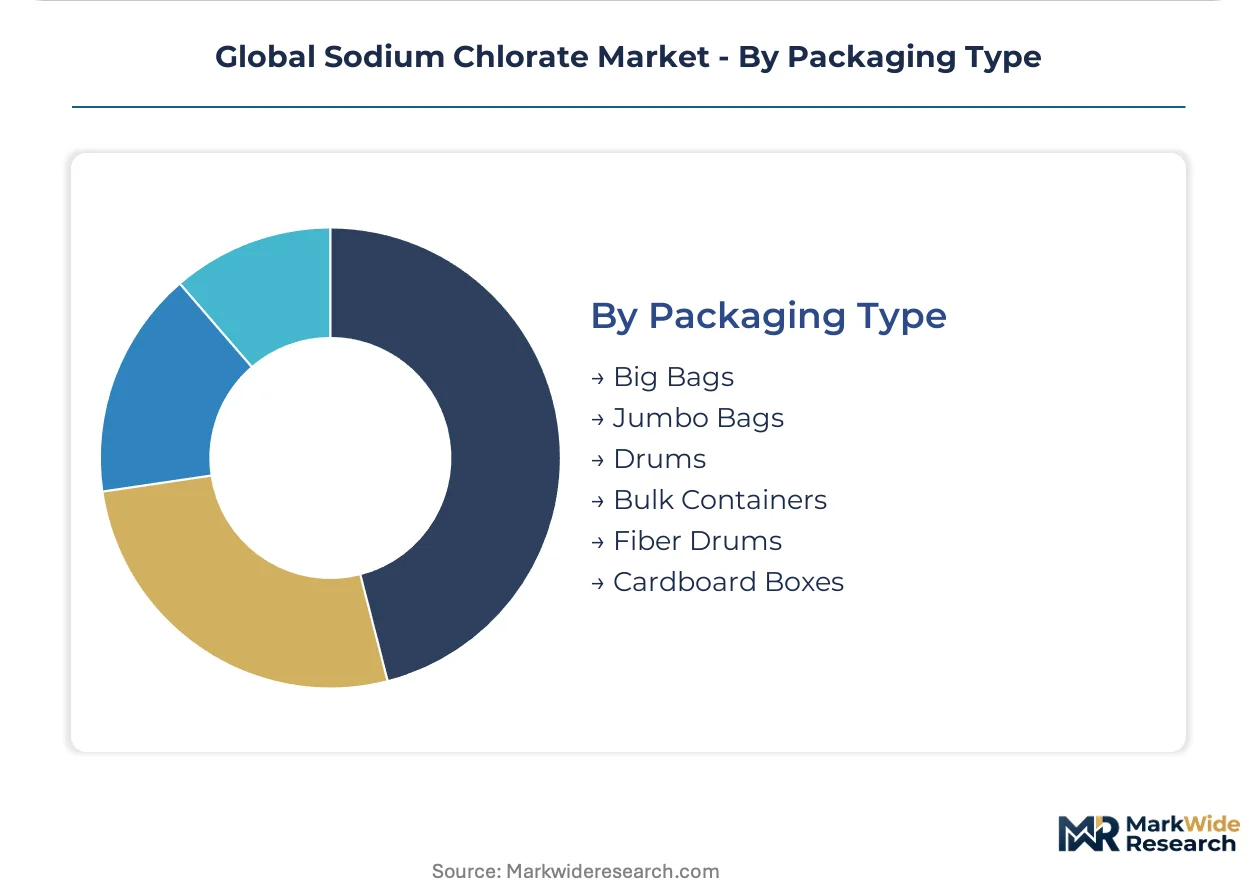
Packaging Type:
Logistics economics and handling automation requirements segment containerization choices across customer scale and geographic concentration.
- Big Bags:Intermediate bulk containers for mid-scale industrial consumers with forklift handling infrastructure.
- Jumbo Bags:Maximum single-unit payloads for high-volume pulp mill delivery minimizing per-ton handling costs.
- Drums:Standard steel containment for technical-grade material requiring moisture exclusion during extended storage.
- Bulk Containers:Returnable intermediate bulk systems for closed-loop supply chains between integrated producers and large consumers.
- Fiber Drums:Lightweight alternative for food-grade and pharmaceutical-grade shipments with reduced tare weight.
- Cardboard Boxes:Small-package format for laboratory and pilot-scale chemical synthesis applications.
Jumbo bags move the greatest tonnage; fiber drums are expanding most quickly as pharmaceutical-grade specification volumes accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sodium chloride brine deposits around the Great Lakes basin anchor North American electrochemical capacity, while Brazilian pulp export terminals and Scandinavian paper clusters shape demand geography across three continents.
United States
EPA effluent guidelines under the Clean Water Act constrain discharge profiles from electrochemical facilities in the Great Lakes region. Pulp mills in the Southeast absorb industrial-grade volumes as regional bleaching capacity expands. Wisconsin and Ohio host concentrated chlor-alkali infrastructure that supplies precursor chemicals to paper producers.
Canada
Great Lakes basin producers face tightening environmental permitting timelines that force crystallization technology upgrades. ERCO Worldwide leverages integrated infrastructure across Ontario and Quebec to sustain cost leadership. The Niagara region anchors electrochemical clusters serving North American pulp mill supply chains.
Brazil
ANVISA enforces purity standards that fragment product certification obligations for imported sodium chlorate. Santos port terminal expansion doubles cellulose export capacity and synchronizes bleaching chemical demand. São Paulo state pulp producers consolidate supplier relationships as domestic chemical synthesis requirements intensify.
Sweden
EU F-Gas Regulation phasedown redirects paper mill investment toward chlorine dioxide precursor chemistry. Kemira anchors competitive positioning through specialized logistics networks serving Scandinavian producers. Skid-mounted generation units are modularizing supply chain risk away from bulk transport toward captive electrochemical capacity.
China
MEE enforces divergent purity standards that complicate export certification timelines for domestic producers. Inner Mongolia and Shandong provinces host electrochemical capacity serving both domestic pulp mills and agricultural chemical intermediate demand. Technical-grade specifications for herbicide synthesis command premium positioning in coastal manufacturing clusters.
Global Sodium Chlorate Market Competitive Landscape
Global majors compete with regional champions across electrochemical infrastructure and logistics specialization dimensions. The vendor base stratifies into membrane-cell technology leaders, integrated chlor-alkali operators, and regional distribution specialists. Three archetypes dominate: scale-driven bulk producers, premium-grade purification specialists, and captive pulp mill suppliers. Capacity expansion and strategic partnerships constitute the dominant competitive moves as environmental permitting tightens.
Within the integrated infrastructure tier, ERCO Worldwide and Nouryon exemplify archetypes built on captive brine supply and membrane-cell advancement. Kemira occupies a position representing logistics-specialized regional champions. Arkema S.A. anchors the European premium-grade segment. Inner Mongolia Lantai Industry Co., Ltd. and China First Chemical Holdings Limited sit within the scale-driven Chinese producer category. Shree Chlorates and Chemtrade Electrochem Inc. represent mid-cap specialists with concentrated geographic footprints.
| Leading Market Players |
|---|
| ERCO Worldwide |
| Nouryon |
| Kemira |
| Arkema S.A. |
| Eka Chemicals |
| Inner Mongolia Lantai Industry Co., Ltd. |
| Shree Chlorates |
| Chemtrade Electrochem Inc. |
| China First Chemical Holdings Limited |
| Others |
Supply & Pricing Matrix
Captive brine-to-crystalline integration around the Great Lakes basin anchors both supply security and pricing leverage for North American electrochemical producers. ERCO Worldwide and Nouryon leverage this backward control over sodium chloride feedstock to buffer margin compression from energy cost volatility, while Brazilian pulp mills absorb premium freight costs for import-dependent supply.
Pricing Analysis
Equipment-service unbundling in municipal water treatment is stripping away historical pricing premiums that bundled vendors captured through long-term maintenance contracts. Three-tier pricing structure across technical, industrial, and standard grades separates herbicide intermediate producers from pulp mill bulk buyers, with certification-grade spreads widening as ANVISA and REACH documentation burdens concentrate among incumbent registrants. Cost compression in industrial-grade material is intensifying because membrane-cell technology diffusion compresses unit economics for crystalline outputs. Pulp mills exhibit highest price sensitivity due to volume concentration and contract renegotiation leverage, while pharmaceutical-grade buyers accept premium positioning for heavy metal documentation.
Supply Chain Analysis
Returnable bulk container loops between Canadian Great Lakes producers and Midwestern pulp mills minimize packaging waste and handling costs through closed-logistics coordination. Electrochemical capacity clusters in Canada, the United States, and Brazil, with Chinese producers in Inner Mongolia and Shandong serving domestic agricultural chemical synthesis. Sodium chlorate production draws from sodium chloride brine, electricity-intensive electrolysis infrastructure, and crystallization purification trains. Single-source vulnerability concentrates in Great Lakes basin permitting delays that bottleneck regional supply simultaneously. Distribution runs through integrated chlor-alkali operators with captive rail and barge networks, supplemented by regional chemical distributors consolidating import permits for REACH compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Environmental permitting consolidation is forcing sub-scale electrochemical operators toward acquisition or exit as EPA effluent guidelines and crystallization upgrade costs concentrate capacity among integrated infrastructure holders.
For Market Incumbents: Acquire stranded membrane-cell capacity in Ontario and Quebec to consolidate Great Lakes basin supply positioning before permitting timelines extend further. Deepen backward integration into captive brine supply to buffer sodium chloride feedstock volatility from winter road-salt demand cycles. Defend against peracetic acid substitution threats by embedding chlorine dioxide precursor generation directly into pulp mill bleaching lines through skid-mounted unit deployment. For New Entrants and Emerging Players: The premium-to-economy price gap in technical-grade material offers entry positioning for purification-specialist operators targeting Brazilian agrochemical intermediate demand. Water treatment applications in Indian and Southeast Asian megacities remain below chlorate adoption thresholds, presenting white-space expansion for regional chemical distributors unbundling procurement from equipment service. Pursue toll manufacturing arrangements with established ANVISA registrants to bypass staggered certification timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated chlor-alkali majors seeking membrane-cell technology capabilities and captive pulp mill supply relationships. Long-term viability favors producers with dual-use electrochemical infrastructure adaptable to green hydrogen electrolyzer retrofit. Monitor Brazilian pulp export terminal capacity utilization at Santos port as inflection indicator for bleaching chemical demand cyclicality.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane-Cell Capacity Retrofit | Energy intensity reductions compress unit economics for ERCO Worldwide and Nouryon crystallization outputs. |
| Backward Integration into Brine Supply | Captive sodium chloride sourcing buffers Canadian producers from winter road-salt demand price spikes. |
| Long-term Supply Agreement | Brazilian pulp mills lock in chlorine dioxide precursor volumes ahead of Santos port expansion completion. |
| Green Hydrogen Co-location | Chlor-alkali plant electrolyzer retrofits create stranded chlorate capacity repurposing potential for European producers. |
| Joint Venture | Regional distributors consolidate REACH import permits to amortize ECHA toxicity documentation costs across volume bases. |
Research Methodology
Multi-period observation of electrochemical capacity utilization, pulp mill bleaching chemical procurement cycles, and municipal water treatment disinfection protocol adoption anchored the trend analysis, supplemented by interviews with plant managers at Great Lakes basin facilities, procurement leads at Brazilian cellulose exporters, distribution channel partners handling ANVISA-compliant imports, and technical R&D directors advancing membrane-cell designs. Secondary validation drew from customs and trade data, American Chemistry Council and Cefic sector reports, SEC 10-K filings of listed chemical producers, and EPA effluent guideline documentation. Bottom-up crystallization capacity modeling triangulated against top-down pulp sector chemical intensity benchmarks.
Input-output matrices mapped sodium chloride brine throughput to crystalline output yields across grade-tier, end-use industry, packaging format, and regional production hub dimensions. CAGRs were derived from segmented demand elasticity modeling and capacity expansion pipeline tracking throughout the forecast period. Industry-specific forecast inputs included Brazilian pulp export terminal commissioning schedules and EU F-Gas Regulation phasedown implementation trajectories.
Inputs from electrochemical facility operators and pulp mill procurement officers were available through the study window; gaps in real-time membrane-cell technology cost curves introduce uncertainty bands around energy intensity reduction projections. Practitioners should monitor EPA permitting timeline extensions and Brazilian ANVISA certification backlog developments for early signals of supply constraint emergence.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Bio-Succinic Acid Market
Bulk Chemicals
North America Vinyl Chloride Monomer Market
Bulk Chemicals
Sodium Hypophosphite Market
Bulk Chemicals
Global 2-Methylpropene Market
Bulk Chemicals
Soda Ash Market
Bulk Chemicals
Lithium Benzoate Market
Bulk Chemicals
Tributyl Citrate Market
Bulk Chemicals
Isoprene Market
Bulk Chemicals
Global Benzaldehyde Market
Bulk Chemicals
Vinyl Cyclohexane Market
Bulk Chemicals
United States Calcium Carbonate Market
Bulk Chemicals
Caprylic Acid Market
Bulk Chemicals
India Carbon Black Market
Bulk Chemicals
North America Caustic Potash Market
Bulk Chemicals
Lithium Nitrate Market
Bulk Chemicals
Global Sodium Hydrosulfite Market