
 Asia-Pacific Carbon Black Market | 2026-2036
Asia-Pacific Carbon Black Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Carbon Black Market Analysis
Multi-source procurement from regional furnace operators is expanding as tire makers reduce dependence on single-country supply after recent freight disruptions. Birla Carbon leverages integrated feedstock refining across Indian and Thai facilities to sustain cost-advantaged output for Southeast Asian tire plants. Cabot Corporation anchors its position through specialty-grade capacity in China, while Jiangxi Black Cat Carbon Black dominates domestic furnace black volume with reactor upgrades that lower emission intensity.
Carbon black is a colloidal carbon material produced by incomplete combustion or thermal decomposition of hydrocarbons, with primary particle sizes ranging from 10 to 500 nanometers and surface areas between 20 and 150 square meters per gram; it functions as a reinforcing filler, pigment, and conductivity additive across industrial formulations. The reinforcing grade segment occupies the largest volume share given its irreplaceable role in tire tread and carcass compounds, while specialty carbon black leads margin pools due to stringent purity requirements in coatings and electronics applications. Synthetic carbon black competes with natural alternatives on cost and consistency, though furnace process advances are narrowing the performance gap in high-durability rubber goods.
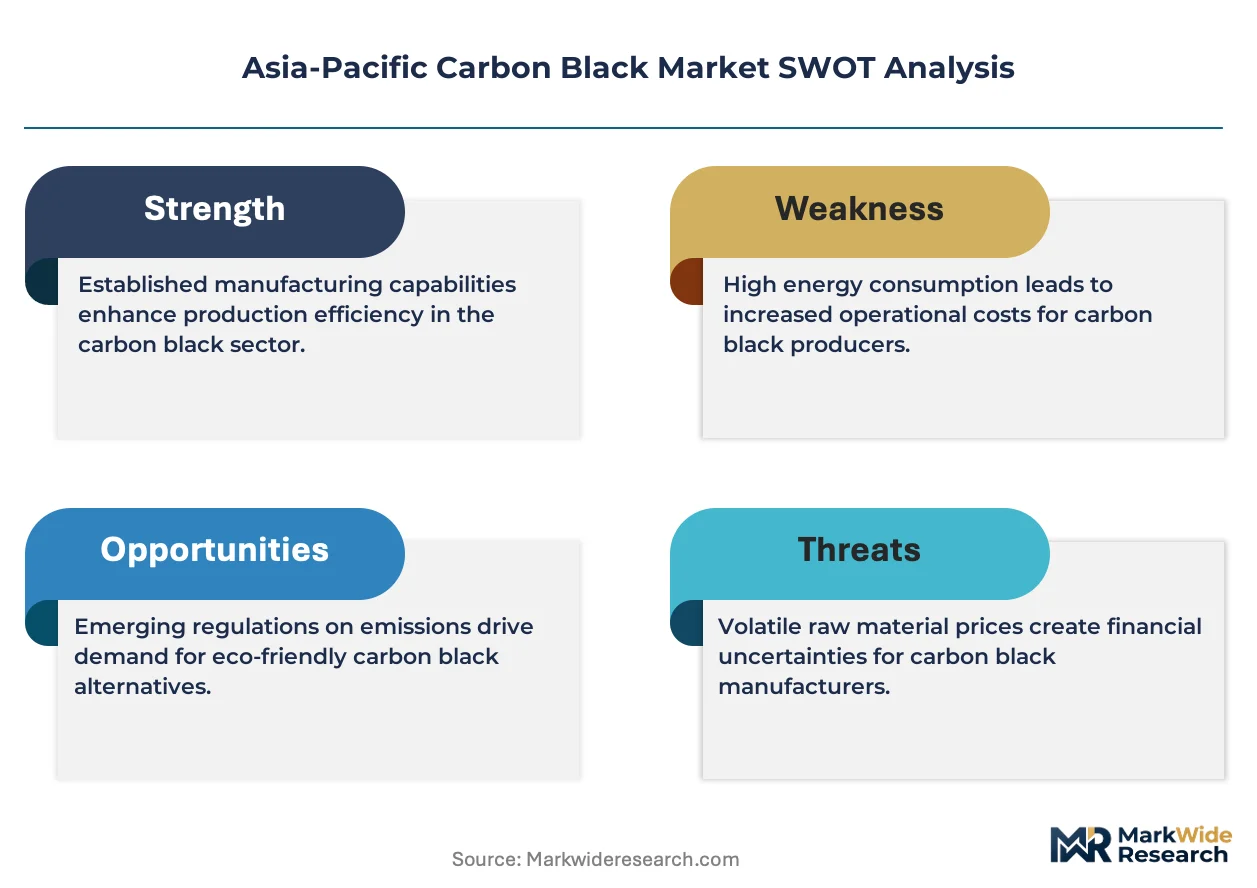
China's MEE enforces GB emission standards that compel reactor retrofits or shutdowns at smaller furnace operators, while India's CEA mandates energy-efficiency audits that favor larger producers with captive power integration. Japan's METI promotes JIS-certified low-PAH grades for consumer-goods contact applications, creating tiered market access by certification level. Stakeholders must monitor how feedstock cost volatility interacts with carbon-border adjustments to determine whether regional capacity expansion or import substitution offers superior returns.
Market Dynamics
China's MEE emission benchmarks are compressing furnace black capacity and redirecting capital toward cleaner reactor technologies, tightening supply availability while specialty-grade production expands in response to tire OEM procurement consolidation.
Growth Catalysts
- Tire OEM procurement consolidation:Southeast Asian tire manufacturers are expanding long-term supply agreements with integrated carbon black-rubber clusters in Shandong and Jiangsu provinces to secure reinforcing grade volumes for automotive supply chains.
- MEE dual carbon enforcement:China's Ministry of Ecology and Environment is accelerating reactor retrofits at furnace operators, creating tiered capacity access that favors producers with emission-compliant infrastructure.
- Specialty grade purity requirements:Electronics and coatings applications are pulling high-surface-area furnace blacks with stringent PAH controls, expanding margin pools beyond commodity reinforcing segments.
Market Restraints
- Feedstock cost volatility:Carbon black producers face margin compression from fluctuating heavy residual oil and coal tar prices, with limited pass-through mechanisms in annual tire supply contracts.
- Supply concentration in eastern China:Overreliance on Shandong and Jiangsu production clusters exposes buyers to simultaneous disruption risks from regional environmental enforcement actions or logistics bottlenecks.
- Natural carbon black substitution:Certain rubber goods applications are testing furnace black alternatives derived from renewable feedstocks, though performance consistency gaps persist in high-durability compounds.
Strategic Opportunities
- India CEA energy-efficiency mandates:India's Central Electricity Authority audits favor larger producers with captive power integration, creating expansion incentives for integrated furnace operators with grid-independent energy systems.
- Japan METI low-PAH certification:JIS-certified grades for consumer goods contact applications command premium positioning in food packaging and personal care rubber components across developed Asia-Pacific markets.
- Thailand-Indonesia tire hub proximity:Southeast Asian production clusters offer logistics-advantaged supply positions for regional tire plants reducing dependence on single-country sourcing after recent freight disruptions.
Industry Challenges
- Reactor engineering talent scarcity:Furnace black producers struggle to recruit process engineers capable of optimizing emission-compliant reactor designs while maintaining throughput targets.
- Certification timeline compression:Japan's JIS and China's GB standard evolution requires simultaneous compliance tracking across multiple jurisdictions, extending product qualification cycles for multi-market suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Carbon Black Market |
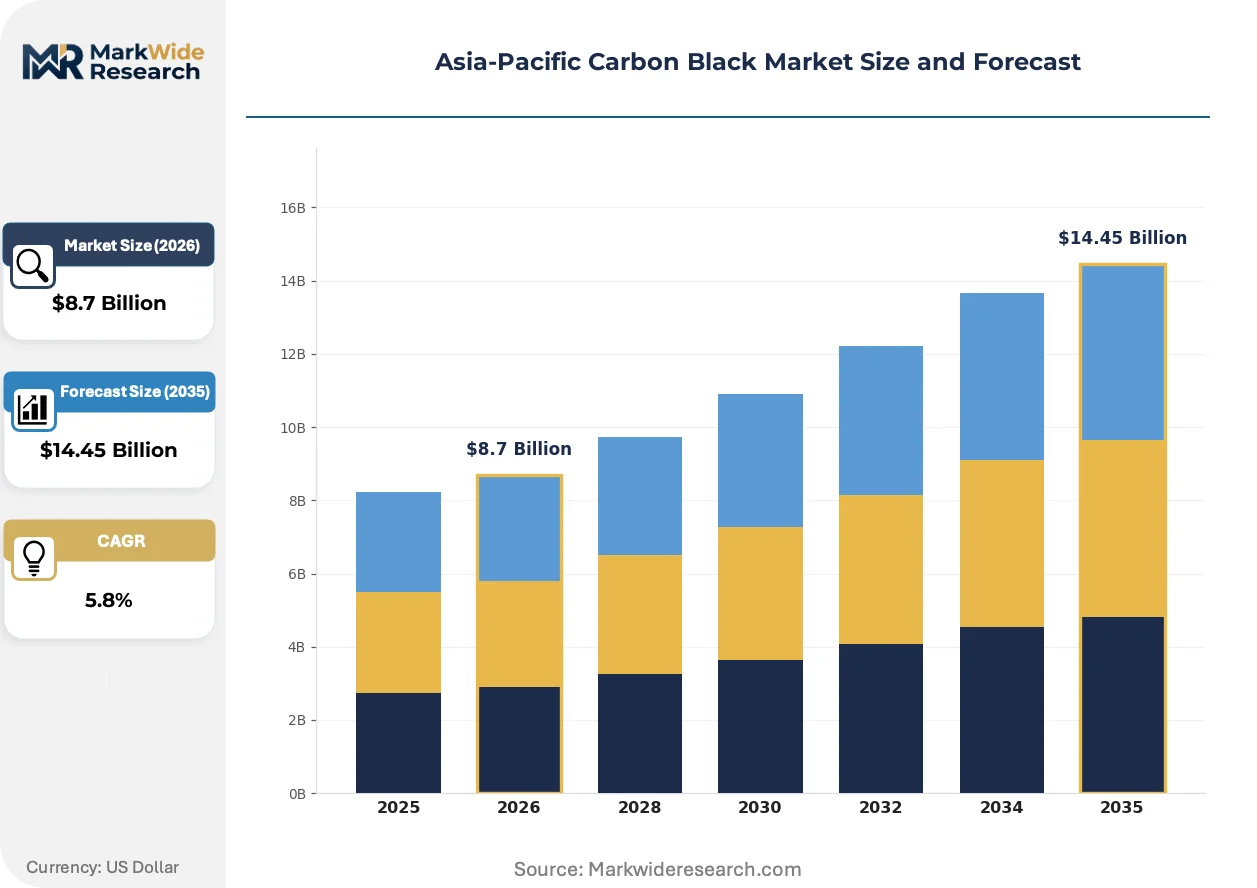
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Reinforcing, Specialty End User: Tires, Coatings, Plastics, Inks Distribution Channel: Direct Sales, Online Retail, Distributors, Agents Application: Automotive Manufacturing, Industrial Rubber, Consumer Goods, Construction |
| Companies Covered | Birla Carbon, Cabot Corporation, Tokai Carbon Co., Ltd., Orion Engineered Carbons, Phillips Carbon Black Limited, Jiangxi Black Cat Carbon Black Co., Ltd., OCI Company Ltd., International CSRC Investments Holdings Co Ltd, Longxing Chemical, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Carbon Black Market Emerging Trajectories
Process intensification and emission control convergence are reconfiguring competitive advantage in Asia-Pacific carbon black production, with technology differentiation increasingly separating compliant capacity from stranded assets.
Plasma-assisted furnace technology is unifying emission reduction with yield optimization in next-generation reactor designs. Specialty carbon black producers in China and Japan are piloting these systems to meet MEE benchmarks without throughput sacrifice. The technology is compressing the cost gap between low-emission and conventional furnace output, reshaping investment priorities for capacity expansion.
Japan's METI is tightening JIS standards for polycyclic aromatic hydrocarbon content in carbon blacks used in consumer goods contact applications. The regulation is forcing reformulation in food packaging seals, toy rubber components, and personal care applicators. Domestic producers are accelerating low-PAH grade certification while importers face extended testing timelines at designated conformity assessment bodies.
Tire manufacturers are consolidating supplier panels around integrated carbon black-rubber compounders capable of delivering pre-dispersed masterbatch rather than raw furnace black. This procurement compression is disintermediating standalone carbon black distributors in Thailand and Indonesia. The shift is most visible among Japanese and Korean tire OEMs with Southeast Asian production bases seeking logistics simplification and quality traceability.
Asia-Pacific Carbon Black Market Segmentation
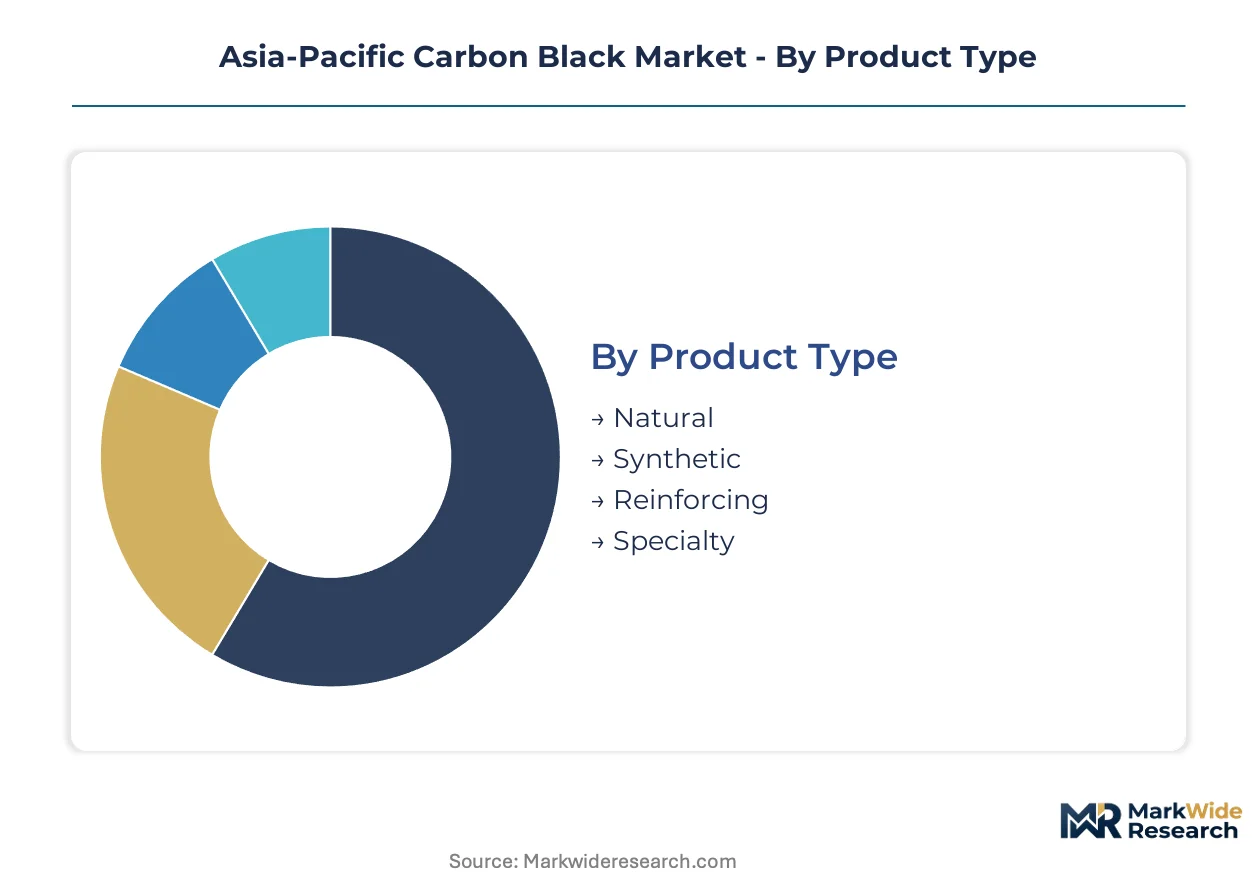
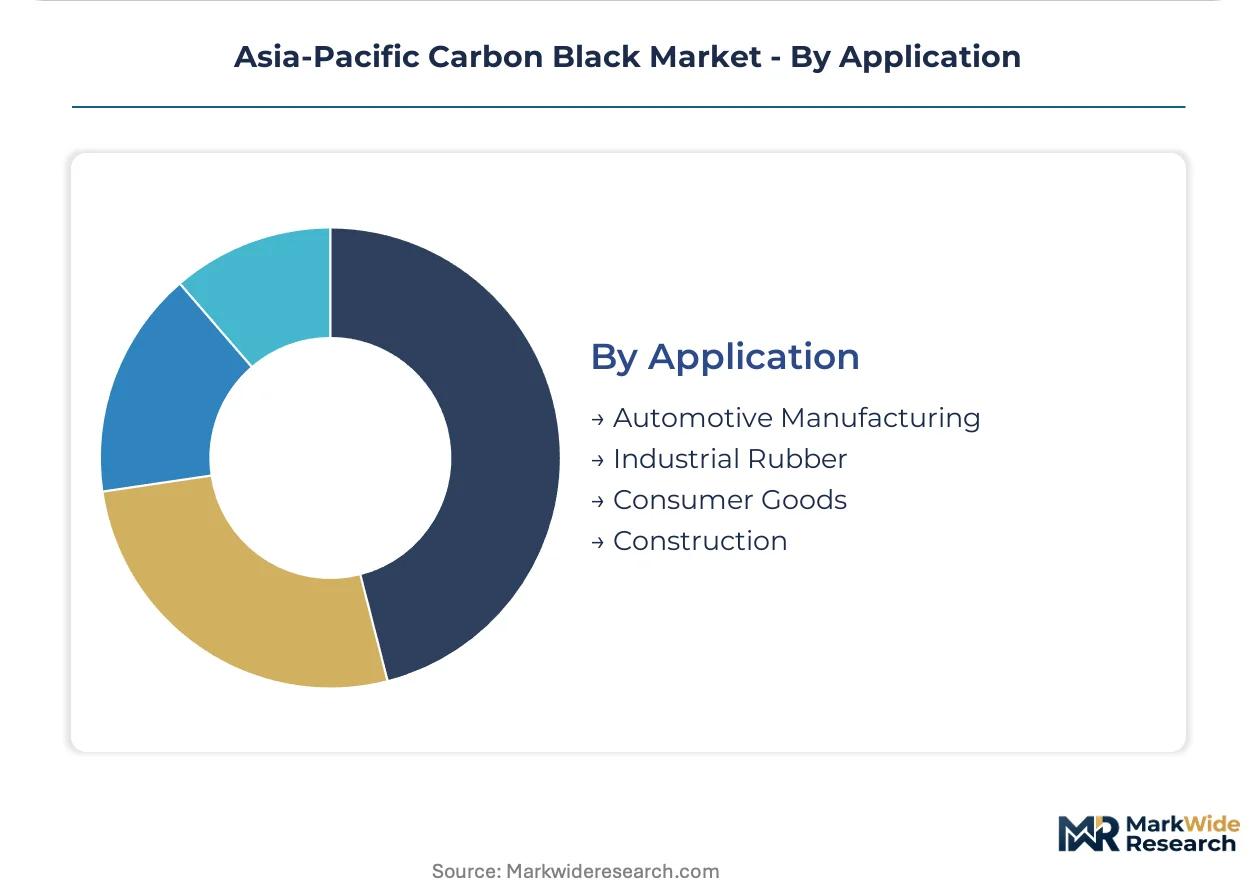
Segmentation in the Asia-Pacific carbon black market determines which producers access tiered procurement channels and which face exclusion from automotive OEM supply chains. Certification requirements, feedstock integration, and end-use purity standards create distinct competitive boundaries across each dimension.
Product Type:
Japan's METI JIS certification and China's GB standards impose divergent purity burdens across product categories, with specialty grades requiring the most extensive documentation for consumer goods contact applications.
- Reinforcing:Furnace black with primary particle sizes of 20-50 nanometers and surface areas of 70-150 square meters per gram delivers tensile strength to tire tread and carcass compounds. Procurement concentrates at integrated carbon black-rubber clusters in Shandong and Jiangsu provinces serving Southeast Asian tire OEMs expanding long-term supply agreements.
- Specialty:High-purity furnace blacks with stringent PAH controls below 10 parts per million serve electronics, coatings, and food-contact rubber applications. Demand pulls toward JIS-certified grades in Japan and low-emission reactor output in China as METI and MEE standards tighten simultaneously.
- Natural:Derived from renewable feedstocks including plant biomass and agricultural residues, competing on sustainability credentials rather than performance parity.
- Synthetic:Petroleum and coal tar-derived furnace black dominating volume production through conventional reactor technology, facing emission compliance pressure from MEE enforcement.
Leading the category by volume: Reinforcing. Growing fastest: Specialty.
End User:
Cost tier stratification separates commodity procurement from premium-grade contracting, with tire makers optimizing freight and inventory while coatings buyers absorb purity premiums.
- Tires:Automotive OEM supply chains in Thailand and Indonesia consolidate procurement around pre-dispersed masterbatch from integrated compounders rather than raw furnace black, disintermediating standalone distributors.
- Coatings:High-surface-area furnace blacks with color consistency and UV stability requirements command margin premiums in automotive and industrial finishes.
- Plastics:Conductivity and pigment applications in electronics housings and packaging compounds.
- Inks:Publication and packaging gravure formulations requiring specific particle size distributions.
Dominating procurement scale: Tires. Expanding most quickly: Coatings.
Distribution Channel:
Customer type determines channel selection, with integrated tire manufacturers bypassing intermediaries while smaller compounders rely on distributor inventory buffers.
- Direct Sales:Long-term supply agreements between furnace operators and automotive OEM tire plants, particularly Japanese and Korean producers with Southeast Asian manufacturing bases seeking logistics simplification.
- Distributors:Inventory-holding intermediaries serving smaller rubber compounders and coatings formulators with fragmented order patterns.
- Agents:Commission-based representatives facilitating cross-border procurement for buyers lacking direct supplier relationships.
- Online Retail:Digital platforms for small-volume specialty grade orders and sample procurement.
Capturing majority volume: Direct Sales. Facing displacement pressure: Distributors.
Application:
Supply concentration in eastern China exposes each application segment to simultaneous disruption from regional environmental enforcement actions.
- Automotive Manufacturing:Tire and rubber component production driving reinforcing grade consumption, with procurement consolidating around emission-compliant Shandong and Jiangsu producers.
- Industrial Rubber:Conveyor belts, hoses, and seals requiring durability performance where furnace black maintains cost advantage over natural alternatives.
- Consumer Goods:Food packaging seals, toy components, and personal care applicators subject to Japan's tightening JIS PAH standards and extended import testing timelines.
- Construction:Roofing membranes, sealants, and infrastructure rubber goods with moderate purity requirements.
Commanding largest share: Automotive Manufacturing. Facing steepest certification escalation: Consumer Goods.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coal tar and petroleum residue availability in eastern China anchors carbon black feedstock procurement across Asia-Pacific, with reactor capacity clustering in provinces with integrated refinery access.
China
Tire OEMs from Thailand and Indonesia source reinforcing grades through long-term contracts with Shandong and Jiangsu producers. MEE emission benchmarks under dual carbon goals are forcing reactor retrofits at smaller furnace operators, compressing compliant capacity. Qingdao and Zibo industrial corridors concentrate integrated carbon black-rubber compounding facilities serving export markets.
India
Domestic tire manufacturers are expanding procurement from regional furnace operators to reduce single-country supply dependence. CEA energy-efficiency audits favor larger producers with captive power integration, creating expansion incentives for integrated operators. Gujarat and Maharashtra industrial belts host furnace capacity with grid-independent energy systems qualifying for preferential regulatory treatment.
Japan
Electronics and coatings formulators are pulling high-purity furnace blacks with stringent PAH controls below 10 parts per million. METI JIS certification requirements for consumer goods contact applications are forcing reformulation in food packaging seals and toy rubber components. Osaka and Nagoya manufacturing clusters concentrate specialty-grade production with extended testing timelines at designated conformity assessment bodies.
South Korea
Automotive OEM supply chains are consolidating supplier panels around integrated compounders capable of delivering pre-dispersed masterbatch. MFDS alignment with international purity standards is elevating documentation burdens for imported furnace blacks. Ulsan and Yeosu petrochemical complexes anchor carbon black production with downstream rubber integration for tire and industrial goods manufacturing.
Thailand
Southeast Asian tire plants are reducing freight exposure through proximity sourcing from regional furnace operators after recent logistics disruptions. BOI investment promotion incentives support carbon black-rubber cluster development for automotive supply chain localization. Rayong and Map Ta Phut industrial zones concentrate downstream tire manufacturing driving reinforcing grade consumption.
Asia-Pacific Carbon Black Market Vendor Landscape
Capacity expansion dominates the current landscape as emission-compliant reactor upgrades separate viable producers from stranded assets. The vendor base concentrates around integrated petrochemical conglomerates with captive feedstock refining, mid-scale regional specialists with geographic proximity advantages, and diversified chemical groups with cross-selling capabilities into rubber compounding. M&A activity targets distressed furnace operators in eastern China facing MEE compliance deadlines, while strategic partnerships between tire OEMs and compounders disintermediate traditional distribution channels.
Among integrated multinational operators, Birla Carbon and Cabot Corporation exemplify the feedstock-integrated archetype with refining capabilities across multiple jurisdictions. Jiangxi Black Cat Carbon Black Co., Ltd. anchors the domestic Chinese tier through reactor upgrades lowering emission intensity. These three occupy positions across the spectrum from global supply chain integration to regional compliance-led capacity renewal, with their respective structures reflecting divergent strategic responses to tightening environmental enforcement and procurement consolidation among tire manufacturers.
| Leading Market Players |
|---|
| Birla Carbon |
| Cabot Corporation |
| Tokai Carbon Co., Ltd. |
| Orion Engineered Carbons |
| Phillips Carbon Black Limited |
| Jiangxi Black Cat Carbon Black Co., Ltd. |
| OCI Company Ltd. |
| International CSRC Investments Holdings Co Ltd |
| Longxing Chemical |
| Others |
Supply Flow & Price Mechanics
China's MEE dual carbon enforcement gates both qualified supply access and premium-tier pricing eligibility, compressing furnace black capacity at non-compliant operators while JIS-certified specialty grades command structural premiums in Japan's consumer goods contact applications.
Pricing Analysis
Technical service bundling separates contract structures, with integrated compounders including pre-dispersed masterbatch formulation support while standalone furnace operators price raw carbon black unbundled. Three-tier pricing structure across JIS-certified premium, MEE-compliant standard, and non-compliant economy grades reflects certification investment differentials. Pricing pressure stems from heavy residual oil cost volatility with limited annual contract pass-through mechanisms. Small rubber compounders exhibit highest price sensitivity, while automotive OEMs absorb premiums for emission-compliant supply security.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale tire manufacturer demand through long-term offtake agreements with Shandong and Jiangsu integrated clusters, while distributor networks serve fragmented coatings and plastics formulators. Feedstock procurement draws from petroleum residue refining in China, coal tar distillation in India, and imported heavy oil in Southeast Asia. Single-source vulnerability concentrates in eastern China's reactor corridor exposed to simultaneous MEE enforcement actions. Distribution runs through compounder-integrated masterbatch delivery for tire OEMs and regional distributor inventory buffers for specialty grade buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where China's MEE emission benchmarks construct a barrier-to-entry moat favoring reactor retrofit-capable incumbents over stranded smaller furnace operators.
For Market Incumbents: Hedge feedstock exposure through backward integration into captive petroleum residue refining or coal tar distillation to buffer heavy oil price volatility. Accelerate plasma-assisted reactor deployments ahead of MEE compliance deadlines to capture tiered capacity access while specialty grade competitors face extended JIS certification timelines in Japan. For New Entrants and Emerging Players: E-procurement platforms for small-volume specialty grade sampling offer low-friction market entry without distributor relationship burdens. Target India's CEA-favored captive power integrated capacity expansion in Gujarat and Maharashtra, where energy-efficiency audits create regulatory preference for greenfield entrants with grid-independent systems. For Investors and Strategic Acquirers: Distressed reactor asset sales in eastern China are the leading indicator that MEE enforcement is compressing viable supply faster than compliant capacity expansion. Position for five-to-ten year holding periods around integrated compounders with tire OEM masterbatch contracts, monitoring MEE shutdown announcements as inflection signals for supply-constrained pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Reactor Retrofit and Emission Compliance | MEE-compliant furnace upgrades separate viable capacity from stranded assets in Shandong and Jiangsu corridors. |
| Backward Integration into Feedstock Refining | Captive petroleum residue processing buffers margin compression from heavy oil spot market volatility. |
| Pre-dispersed Masterbatch Capacity Addition | Tire OEM procurement consolidation favors integrated compounders over standalone carbon black distributors in Thailand. |
| JIS Low-PAH Certification Investment | METI tightening creates premium positioning in food packaging seals and toy rubber components across Japan. |
| Southeast Asian Production Cluster Development | BOI incentives in Rayong and Map Ta Phut reduce freight exposure for regional tire plants post-logistics disruptions. |
Methodological Framework
Trade databases, SEC filings from carbon black producers, and MEE regulatory enforcement records formed the secondary backbone, cross-referenced with primary interviews across plant managers at furnace operators, procurement leads at Thai and Indonesian tire OEMs, technical R&D directors at specialty grade compounders, and distribution channel partners serving coatings formulators. Bottom-up capacity modeling triangulated against top-down tire industry consumption estimates.
Bottom-up segmentation analysis modeled reinforcing versus specialty grade splits, furnace versus natural feedstock origins, and direct sales versus distributor channel shares across the projection horizon. CAGRs derived from production capacity expansion schedules correlated with automotive OEM tire demand forecasts and MEE compliance timeline assumptions. Feedstock cost curves and carbon border adjustment scenarios informed pricing trajectory sensitivity analysis.
The model holds under sustained MEE enforcement intensity and stable tire OEM procurement consolidation; deviation in feedstock price volatility spikes or JIS certification timeline extensions would shift capacity utilization and margin distribution assumptions. Periodic stress-testing of base assumptions against regulatory announcement flows and reactor engineering talent availability is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Ammonium Carbonate Market
Bulk Chemicals
Phthalic Anhydride Market
Bulk Chemicals
Picric Acid Market
Bulk Chemicals
Methyl Cyclohexane Market
Bulk Chemicals
North America Sodium Chlorate Market
Bulk Chemicals
Middle East Ammonia Market
Bulk Chemicals
Lithium Bromide Market
Bulk Chemicals
North America Lactic Acid Market
Bulk Chemicals
US Hydrochloric Acid Market
Bulk Chemicals
Ethylene Oxide Market
Bulk Chemicals
Asia-Pacific Bitumen Market
Bulk Chemicals
Bulk Liquid Containers Market
Bulk Chemicals
North America Glycerol Market
Bulk Chemicals
Natural Thickener Market
Bulk Chemicals
Europe Lipids Market
Bulk Chemicals
Heavy Alkyl Benzenes Market