
 Citrate Market | 2026-2036
Citrate Market Size, Share, and Industry Trends Forecast 2026-2036
Citrate Market Outlook
Long-term supply contracts for pharmaceutical-grade citrate is restructuring how buyers secure volume commitments across multi-year horizons. Jungbunzlauer Suisse AG leverages its Swiss fermentation facilities to sustain premium-grade output for European drug manufacturers. Cargill anchors North American supply through corn-derived feedstock integration, while Gadot Biochemical Industries specializes in Dead Sea-sourced mineral citrates for regional pharmaceutical clients.
Citrates are salts and esters of citric acid, typically produced via fermentation of carbohydrate substrates followed by chemical neutralization, with specifications varying by pH buffering capacity and chelating strength for industrial applications. Sodium citrate dominates food preservation buffers where pH control extends shelf stability in processed proteins and dairy systems. Calcium citrate represents the fastest-expanding product type within pharmaceutical applications, as tablet and capsule formulators favor its bioavailability in mineral supplements over carbonate alternatives.
The US FDA and EPA jointly govern citrate purity thresholds for food contact and drinking water treatment applications, while REACH registration requirements in Europe mandate full toxicological dossiers for imported citrate salts. China's SAMR enforces GB standards for food additive citrates that diverge from Codex Alimentarius specifications, creating compliance complexity for multinational suppliers. Stakeholders must monitor evolving pharmaceutical excipient monographs and regional carbon-intensity regulations that could reshape fermentation-based production economics.
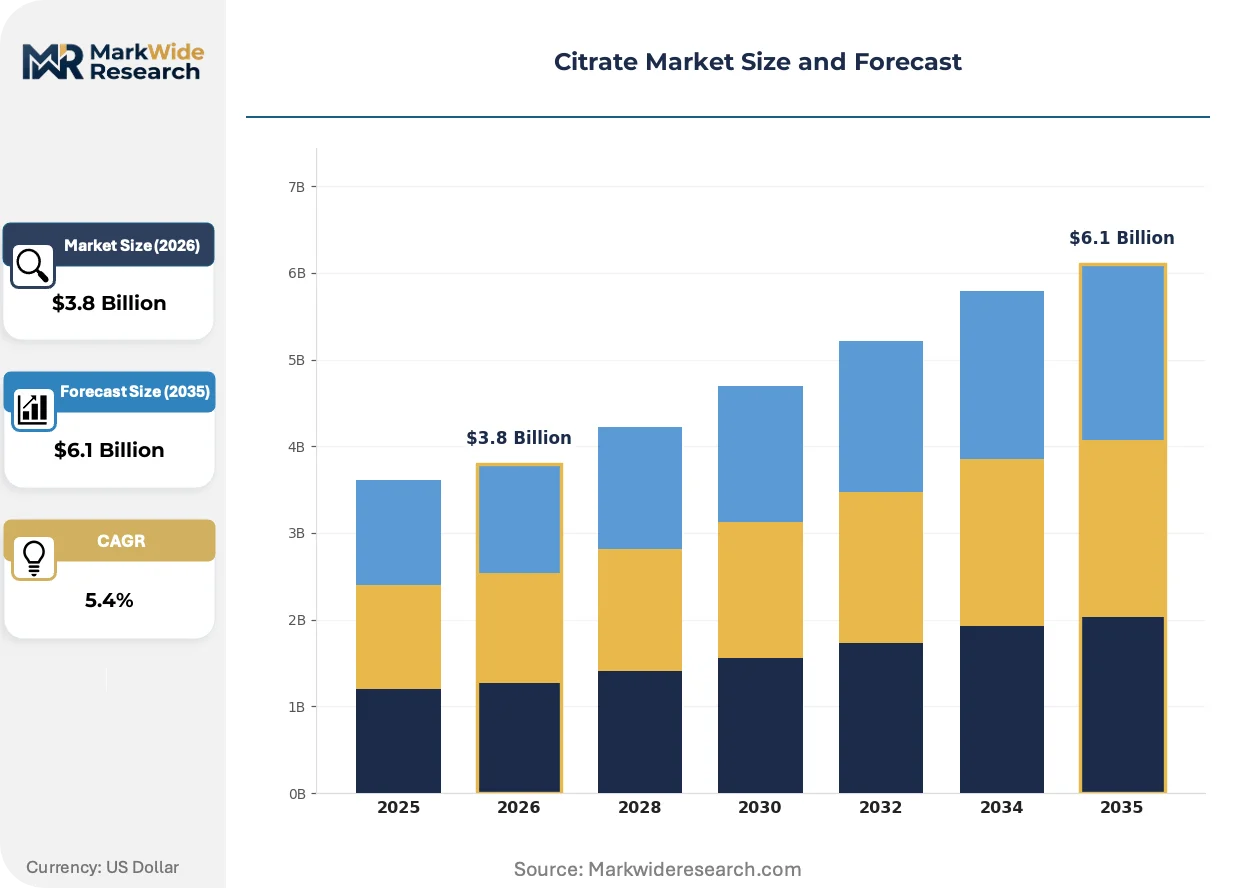
Market Dynamics
Pharmaceutical formulators are restructuring citrate procurement around multi-year volume commitments as biologic drug pipelines expand, tightening the link between fermentation capacity and drug stabilization chemistry.
Growth Catalysts
- Biologic drug stabilization protocols:mRNA and monoclonal antibody manufacturers are embedding citrate buffers into formulation stability studies, creating dedicated demand corridors for pharmaceutical-grade material.
- REACH purity escalation:Europe's tightening thresholds for food-grade citrate imports are forcing upstream purification investments that cascade into higher-grade output availability.
- China fermentation scale:Bulk citric acid production concentrates in Shandong province, where integrated glucose-to-citrate processing yields cost structures that feed global downstream salt production.
Market Restraints
- Molasses and corn feedstock volatility:Fermentation economics swing with agricultural commodity cycles, compressing margins for non-integrated producers during sucrose price spikes.
- Shandong supply concentration:Three integrated fermentation clusters control the majority of global citric acid precursor output, creating geographic vulnerability to regional energy or environmental enforcement actions.
- Carbonate substitution in antacids:Calcium carbonate retains cost advantage in over-the-counter mineral supplements, limiting citrate penetration in price-sensitive consumer health segments.
Strategic Opportunities
- India pharmaceutical excipient certification:CDSCO's expanding monograph recognition for citrate salts in domestic drug manufacturing creates import substitution potential for local fermentation investments.
- Cell-cultured meat pH buffering:Growth medium formulators are testing citrate systems for bioreactor pH control, opening novel demand from alternative protein startups.
- EU Green Deal carbon accounting:Fermentation-based citrate production with verified low-carbon intensity feedstocks qualifies for preferential procurement in European food and pharmaceutical supply chains.
Industry Challenges
- Pharmaceutical GMP compliance timelines:Excipient manufacturers face 18-24 month certification cycles for IPEC-PQG standards, delaying revenue recognition on capacity investments.
- Chelation chemistry integration:Industrial cleaning and water treatment formulators require application-specific citrate blends, demanding technical service capabilities that stretch mid-tier suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Citrate Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Citrate, Potassium Citrate, Calcium Citrate, Citric Acid Application: Food Preservation, Pharmaceuticals, Cosmetic Formulation, Water Treatment End User: Food & Beverage Industry, Healthcare Providers, Personal Care Manufacturers, Agricultural Sector Delivery Mode: Liquid, Powder, Granular, Tablet |
| Companies Covered | Jungbunzlauer Suisse AG, Archer Daniels Midland, Cargill, Gadot Biochemical Industries, Tate & Lyle, BASF SE, DSM, Citribel NV, RZBC Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Citrate Market Strategic Shifts
Continuous fermentation and downstream membrane filtration are compressing unit economics for pharmaceutical-grade citrate, while regulatory carbon accounting is rewiring feedstock sourcing decisions across European supply chains.
Membrane-based continuous fermentation is consolidating citric acid production into fewer, larger-scale facilities with integrated purification trains. Biopharmaceutical excipient buyers are qualifying these outputs for buffer applications at accelerated rates. The technology is consolidating competitive position around capital-intensive fermentation engineering rather than batch-process scale.
REACH registration requirements for imported citrate salts now mandate full toxicological dossiers covering reproductive and aquatic toxicity endpoints. European food and pharmaceutical manufacturers are narrowing supplier pools to those with completed registrations. The policy is compressing import flexibility and rewarding early-registrant fermentation groups with locked customer relationships.
Long-term offtake contracts with fixed-volume escalators are displacing spot-market purchasing for pharmaceutical-grade material. Biologic drug manufacturers are embedding citrate suppliers into multi-year stability programs, trading price flexibility for supply security. The shift is most visible in North American and European contract manufacturing networks where pipeline visibility supports commitment structures.
Citrate Market Segmentation
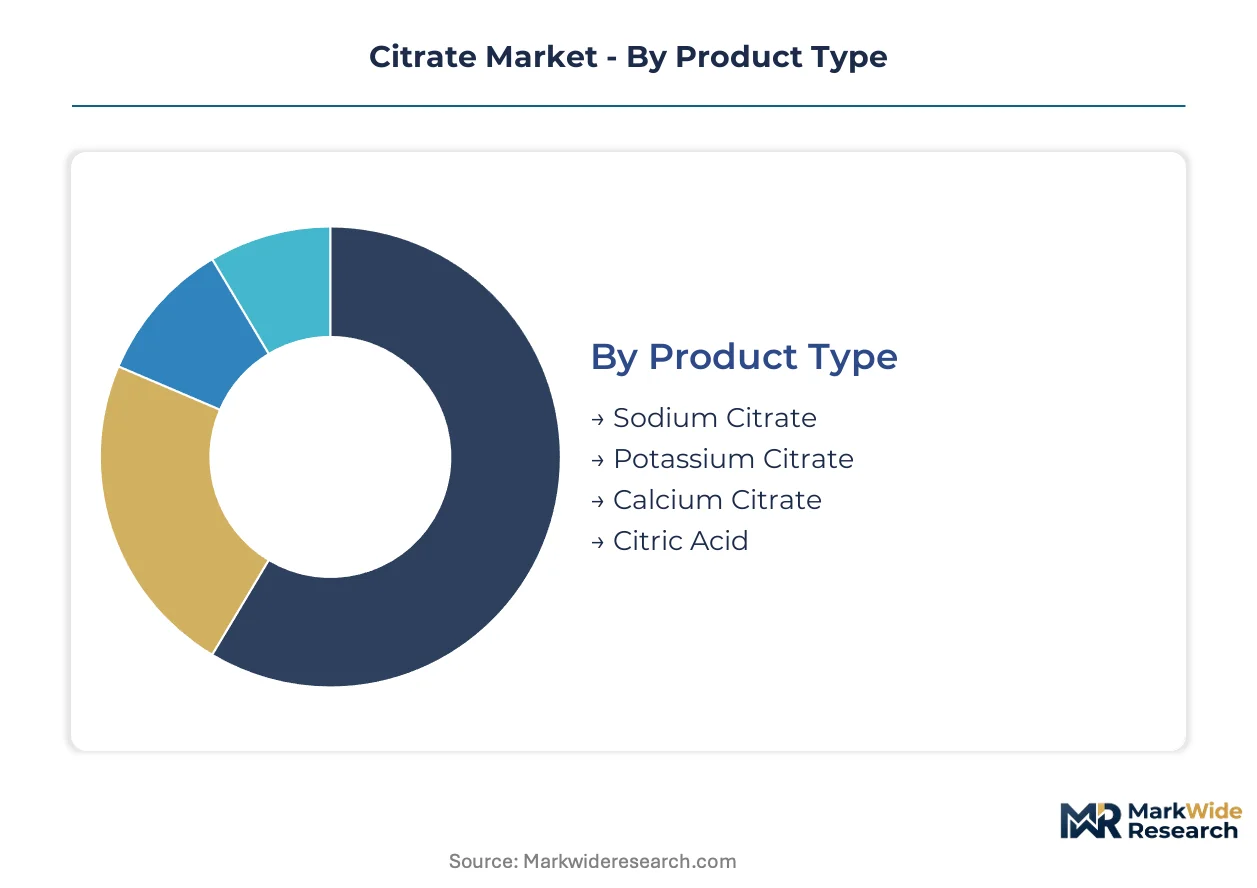
Citrate chemistry fragments across specification grades that determine fermentation investment recovery. Each segment carries distinct purity thresholds, certification burdens, and customer switching costs that reshape competitive entry barriers.
Product Type:
Supply concentration clusters around fermentation facilities with integrated neutralization trains, locking cost structures to carbohydrate feedstock access.
- Sodium Citrate:The trisodium salt delivers precise pH buffering across 6.0-8.0 ranges, making it indispensable for processed meat emulsions and dairy stabilization. European food manufacturers under EFSA oversight specify low-arsenic grades that strain purification economics for non-integrated producers.
- Calcium Citrate:This mineral salt achieves superior bioavailability in tablet matrices compared to carbonate alternatives, driving pharmaceutical formulator preference for osteoporosis and antacid applications. CDSCO's expanding excipient monographs in India are accelerating regional qualification timelines for this grade.
- Potassium Citrate:Renal care formulators embed this salt in alkalinization therapies where sodium load contraindications apply.
- Citric Acid:The precursor acid feeds downstream salt production and direct beverage acidification, with Shandong province fermentation clusters supplying bulk volume to global processors.
Sodium citrate absorbs the bulk of installed capacity; calcium citrate is expanding most quickly.
Application:
Cost tier stratification separates commodity-grade from pharmaceutical-certified material, with margin spreads widening on certification depth.
- Food Preservation:pH control extends shelf stability in processed proteins and dairy systems, where SAMR's GB standards in China diverge from Codex Alimentarius specifications and force dual-track compliance investments.
- Pharmaceuticals:mRNA and monoclonal antibody manufacturers embed citrate buffers into formulation stability studies, creating dedicated demand corridors for IPEC-PQG certified material with 18-24 month qualification cycles.
- Cosmetic Formulation:Chelating properties stabilize emulsions against metal-catalyzed oxidation in premium skincare.
- Water Treatment:Scale inhibition and metal sequestration applications in industrial cooling systems favor lower-purity, cost-optimized grades.
Food preservation commands the largest volume flows; pharmaceuticals capture the steepest margin expansion.
End User:
Customer type determines contract structure, with biopharmaceutical buyers demanding multi-year offtake commitments that displace spot purchasing.
- Food & Beverage Industry:Processors of carbonated drinks, processed meats, and dairy derivatives specify citrate grades based on regional additive codes, with REACH-registered suppliers locking preferred vendor status in European procurement.
- Healthcare Providers:Hospital pharmacy and dialysis unit procurement of potassium citrate for renal alkalinization operates through group purchasing organizations with consolidated supplier panels.
- Personal Care Manufacturers:Cosmetic formulators source chelating-grade material for antioxidant stabilization in premium product lines.
- Agricultural Sector:Micronutrient delivery and feed acidification applications tolerate lower purity thresholds than pharmaceutical or food grades.
Food and beverage channels move the highest tonnage; healthcare providers are consolidating procurement around fewer qualified suppliers.
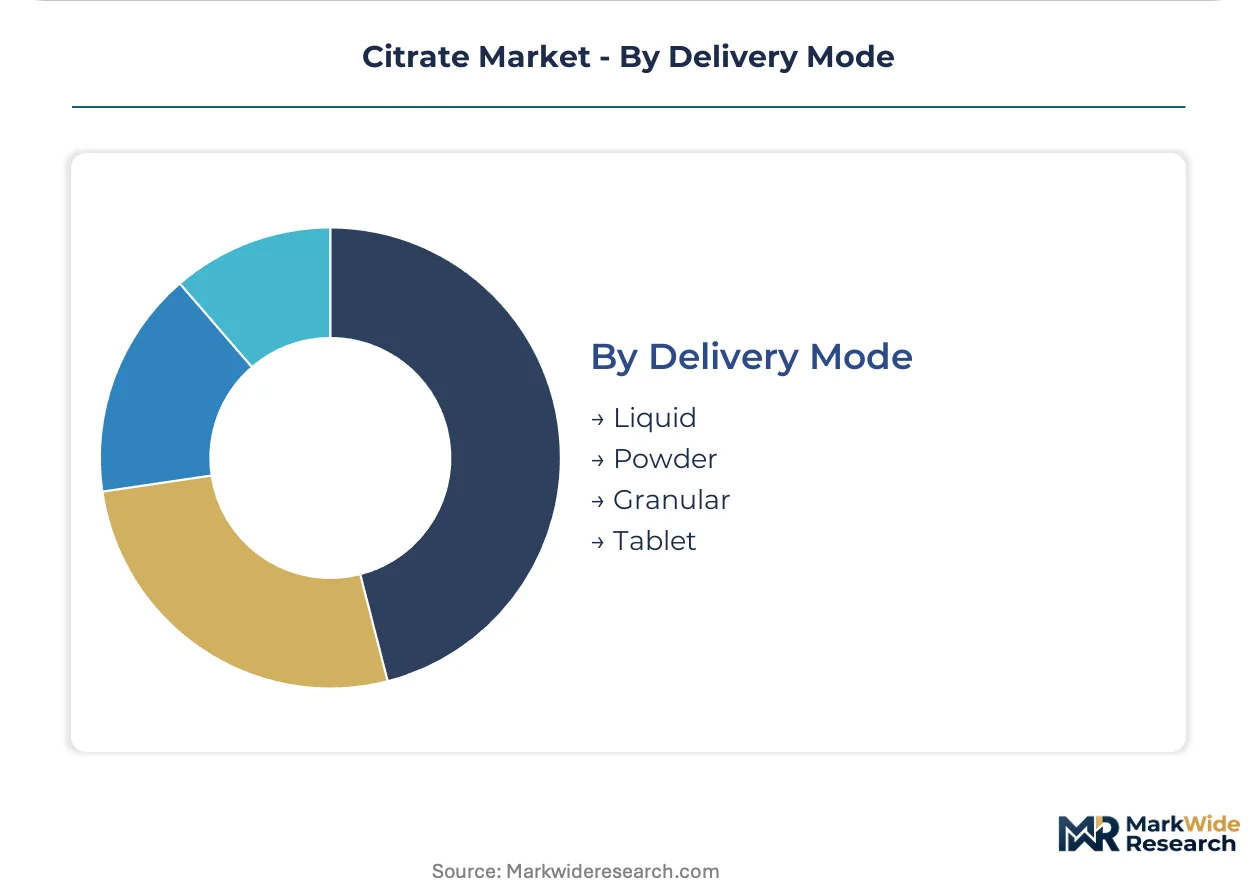
Delivery Mode:
Volume economics favor bulk liquid and powder formats for industrial accounts, while tablet and granular forms serve dispersed retail and clinical endpoints.
- Liquid:Ready-to-use solutions eliminate dissolution steps in beverage manufacturing and industrial water treatment, with tanker delivery optimizing logistics for high-volume processors.
- Powder:Free-flowing crystalline material serves food compounding and pharmaceutical granulation with flexible dosing precision.
- Granular:Low-dust handling characteristics suit automated feeding systems in meat processing and dairy operations.
- Tablet:Unit-dose convenience targets clinical and direct-consumer mineral supplementation with compressed calcium and potassium citrate formulations.
Powder and liquid formats dominate industrial procurement; tablet delivery is gaining share in direct-to-consumer mineral supplements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation capacity clusters in Shandong province while pharmaceutical-grade consumption concentrates in North American and European drug manufacturing corridors. This production-consumption divide shapes trade flows and regulatory compliance investments across national boundaries.
China
Shandong province hosts integrated glucose-to-citrate fermentation clusters that supply bulk acid to global salt processors. SAMR enforces GB standards for food additive citrates that diverge from Codex Alimentarius specifications, forcing multinational suppliers into dual-track compliance. RZBC Group anchors production in Jining city, feeding downstream pharmaceutical and food-grade refinement in Europe and North America.
United States
mRNA vaccine manufacturers and monoclonal antibody formulators drive pharmaceutical-grade citrate demand through multi-year stability programs. The FDA governs excipient purity thresholds jointly with EPA oversight for drinking water treatment applications. Cargill leverages corn-derived feedstock integration across Midwest processing facilities to supply North American drug manufacturers.
Germany
REACH registration requirements mandate full toxicological dossiers for imported citrate salts, compressing supplier flexibility. EFSA oversight of food-grade material tightens arsenic thresholds beyond global baselines. Jungbunzlauer Suisse AG serves German drug manufacturers from Swiss fermentation facilities, qualifying outputs for IPEC-PQG certified pharmaceutical applications.
India
CDSCO's expanding excipient monographs for citrate salts in domestic drug manufacturing create import substitution potential for local fermentation investments. FSSAI governs food-grade specifications with evolving alignment to Codex standards. Maharashtra and Gujarat pharmaceutical clusters are accelerating qualification timelines for calcium citrate in tablet and capsule formulations.
Switzerland
Swissmedic pharmaceutical regulations enforce excipient certification standards that cascade into supplier selection across adjacent European markets. Jungbunzlauer Suisse AG operates fermentation facilities that supply premium-grade material to drug manufacturers in Germany, France, and Italy. Basel and Zurich anchor pharmaceutical procurement networks with consolidated supplier panels for buffer applications.
Citrate Market Competitive Environment
Capital-heavy fermentation operators compete with asset-light specialty salt processors across tiered supply relationships. Three integrated Shandong clusters control bulk citric acid precursor output, while European and North American refiners specialize in pharmaceutical-grade purification. Strategic archetypes separate feedstock-integrated fermenters, Dead Sea mineral extractors, and excipient-certified refiners. Capacity expansion and long-term offtake contracting dominate competitive positioning as biologic drug pipelines multiply buffer demand.
Among fermentation-integrated multinationals, Jungbunzlauer Suisse AG, Cargill, and RZBC Group occupy positions spanning the value chain from carbohydrate feedstock to pharmaceutical certification. Jungbunzlauer exemplifies the European premium-grade archetype with Swiss-based fermentation and REACH-registered outputs. Cargill represents North American feedstock integration through corn-derived processing networks. RZBC Group anchors the China-based bulk supply position with Shandong province concentration. These three patterns illustrate how geographic feedstock access and regulatory certification depth stratify competitive standing.
| Leading Market Players |
|---|
| Jungbunzlauer Suisse AG |
| Archer Daniels Midland |
| Cargill |
| Gadot Biochemical Industries |
| Tate & Lyle |
| BASF SE |
| DSM |
| Citribel NV |
| RZBC Group |
| Others |
Value Chain & Pricing Dynamics
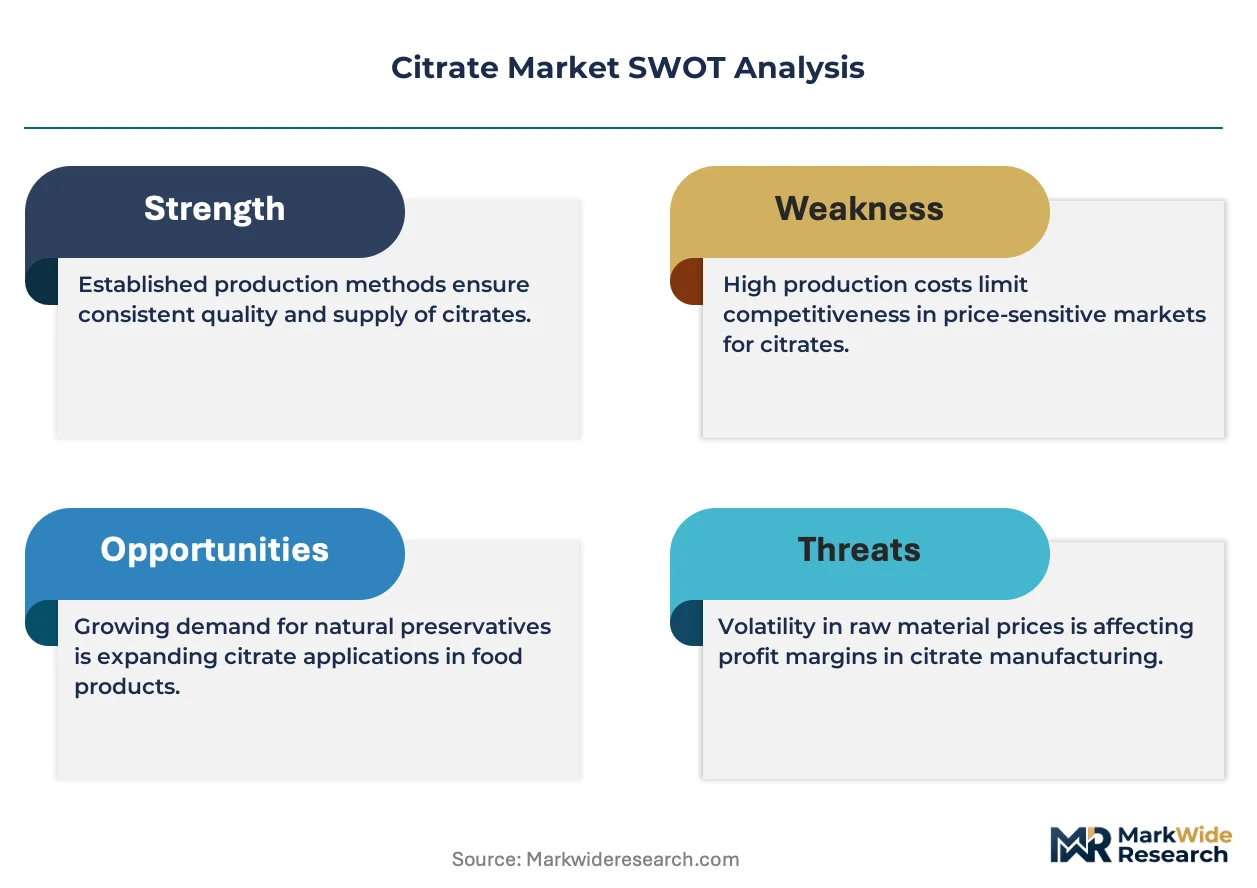
Feedstock-integrated fermentation in Shandong province anchors both supply security and pricing power for bulk citric acid precursors, while pharmaceutical-grade refiners in Europe and North America command premium spreads through certification depth and multi-year offtake structures.
Pricing Analysis
Margin tightening in pharmaceutical-grade material reflects REACH-registered supply scarcity and 18-24 month IPEC-PQG qualification cycles that lock buyer relationships. Three-tier pricing structure across pharmaceutical-certified, food-grade, and industrial-grade levels separates premium fermentation outputs from commodity salt processing. Price differentiation traces to purity thresholds and toxicological dossier completeness under ECHA oversight. Food and beverage processors show highest price sensitivity, while mRNA manufacturers absorb premiums for supply security.
Supply Chain Analysis
Ocean freight rates from Qingdao port to Rotterdam and Houston significantly shape landed costs for Shandong-sourced bulk acid. Supply concentrates in China, with secondary fermentation capacity in the United States and Switzerland. Raw material flows draw from corn and molasses carbohydrate streams, with sulfuric acid and sodium hydroxide for neutralization. Single-source vulnerability clusters around Shandong energy enforcement actions or environmental shutdowns. Distribution runs through integrated refiners serving pharmaceutical formulators under long-term contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where control over fermentation capacity and downstream pharmaceutical certification determines competitive survival. Players are pursuing captive supply of carbohydrate feedstocks to compress unit economics.
For Market Incumbents: Acquire fermentation capacity in Shandong or Jining clusters to secure precursor supply against environmental enforcement volatility. Lock multi-year offtake contracts with mRNA and monoclonal antibody manufacturers before CDSCO expands domestic Indian excipient production. Invest in membrane-based continuous fermentation to consolidate cost position against batch-process competitors.
For New Entrants and Emerging Players: Begin with CDSCO-registered calcium citrate production for Maharashtra and Gujarat pharmaceutical clusters, where import substitution demand is accelerating. Target cell-cultured meat pH buffering applications as novel demand corridors with lower certification barriers than pharmaceutical grades. Pursue joint development agreements with alternative protein startups testing citrate growth media.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to fermentation-integrated multinationals seeking REACH-registered European assets. Long-term viability favors operators with verified low-carbon intensity feedstocks qualifying for EU Green Deal preferential procurement. Watch for SAMR alignment of GB standards to Codex specifications as inflection signal for Chinese import competitiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Feedstock | Cargill's Midwest processing secures carbohydrate supply against molasses price volatility. |
| REACH Registration Completion | Jungbunzlauer's toxicological dossiers lock preferred vendor status under ECHA mandates. |
| Long-term Supply Agreement | Multi-year stability programs embed citrate suppliers into biologic drug pipelines. |
| Continuous Fermentation Scale-Up | Membrane filtration consolidation compresses unit economics for pharmaceutical-grade output. |
| Joint Venture in Shandong Cluster | RZBC Group partnerships access integrated glucose-to-citrate processing infrastructure. |
Study Parameters
Multi-period observation of fermentation capacity utilization, REACH registration timelines, and pharmaceutical excipient qualification cycles anchored the trend analysis, supplemented by interviews with plant managers at citric acid facilities, procurement leads at biologic drug manufacturers, technical R&D directors at buffer formulators, and distribution channel partners in European food additive supply. Secondary validation drew from ECHA registration databases, FDA drug master file submissions, SAMR GB standard publications, and customs trade data. Bottom-up capacity modeling and top-down demand triangulation from mRNA pipeline disclosures were cross-referenced.
Segment-weighting approaches applied differential growth assumptions across pharmaceutical-grade, food-grade, and industrial-grade tiers, with additional modeling for calcium citrate tablet formulations and sodium citrate liquid delivery modes. CAGRs were derived from regression analysis of historical price-volume relationships and forward projection of biologic drug approval trajectories. Feedstock cost indices and carbon intensity verification protocols under EU Green Deal frameworks served as industry-specific forecast inputs throughout the projection horizon.
Underlying measurement precision varies by segment; pharmaceutical-grade demand carries tighter precision than emerging cell-cultured meat applications. Forecasts reflect assumptions about CDSCO monograph expansion pace and Shandong environmental enforcement intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Potassium Methylate Market
Functional Chemicals
Heptanoic Acid Market
Functional Chemicals
L-Citrulline Market
Functional Chemicals
Global Glutamic Acid Market
Functional Chemicals
Urea Formaldehyde Market
Functional Chemicals
Global Adiponitrile Market
Functional Chemicals
Global Peptide Synthesis Market
Functional Chemicals
Thymolphthalein Market
Functional Chemicals
Serine Amino Acid Market
Functional Chemicals
L-Alanyl-L-Glutamine Market
Functional Chemicals
Sodium Citrate Market
Functional Chemicals
Asparagine Market
Functional Chemicals
Isophthaloyl Chloride Market
Functional Chemicals
L-Cysteine Market
Functional Chemicals
Europe Formic Acid Market
Functional Chemicals
Sodium Lauroyl Glutamate Market