
 Magnesium Acetate Market | 2026-2036
Magnesium Acetate Market Size, Share, and Industry Trends Forecast 2026-2036
Magnesium Acetate Market Outlook
Green de-icing chemistry is reconfiguring municipal procurement standards across freeze-prone regions. Merck KGaA leverages its pharmaceutical-grade production infrastructure to supply high-purity magnesium acetate for medical and food applications. Niacet Corporation anchors North American supply through its Buffalo, New York manufacturing complex, while American Elements competes in specialty material segments with customized particle-size offerings.
Magnesium acetate is the magnesium salt of acetic acid, typically appearing as a hygroscopic white solid with the formula Mg(CH₃COO)₂, synthesized through the neutralization of magnesium oxide or hydroxide with acetic acid and employed primarily as a de-icing agent, chemical intermediate, and food acidity regulator. The powder and granule product types dominate current volume due to their stability in bulk handling and compatibility with spreader equipment, while solution formulations are gaining traction in pre-wetting and liquid-de-icing systems. De-icing applications command the largest share of demand structurally, though pharmaceutical and food-grade segments capture disproportionate margin pools because of stringent purity certification requirements.
EPA guidelines on chloride runoff are reshaping municipal de-icing specifications in the United States, while REACH registration obligations in Europe enforce detailed toxicological documentation for acetate salt imports. China's SAMR administers national food safety standards that govern magnesium acetate purity thresholds for domestic consumption and export qualification. Stakeholders must monitor regulatory divergence between jurisdictions to align product certification investments with the highest-return market access pathways.
Market Dynamics
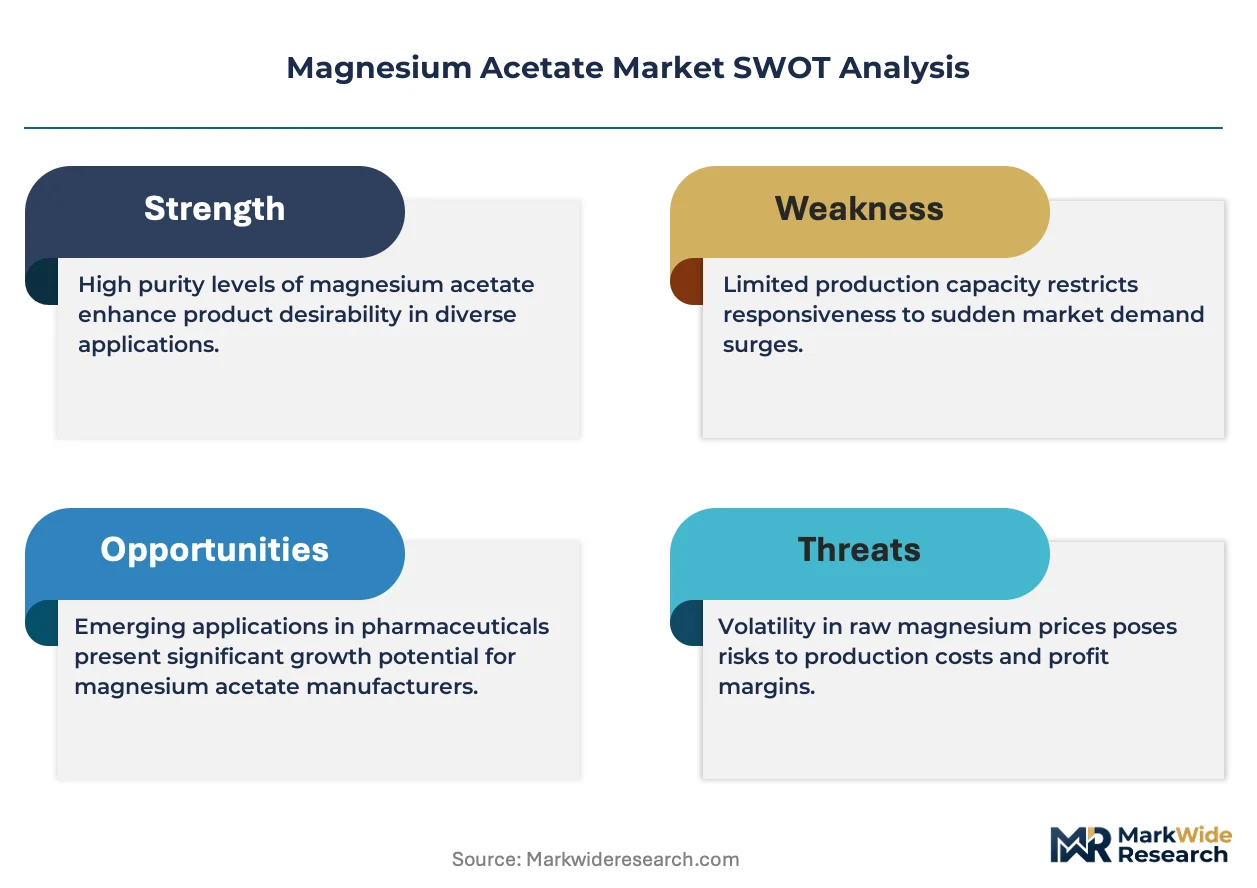
EPA chloride runoff guidelines are forcing municipal de-icing procurement toward acetate-based alternatives, restructuring competitive positioning around environmental compliance credentials rather than unit economics alone.
Growth Catalysts
- EPA Stormwater Regulations:Municipalities across freeze-prone US states face binding chloride discharge limits. Acetate salts gain specification in winter road maintenance contracts.
- REACH Registration Compliance:ECHA documentation requirements for acetate salt imports into Europe favor established producers with toxicological dossiers already filed.
- Acetic Acid Supply Integration:China's Shandong and Jiangsu chemical corridors cluster magnesium acetate production adjacent to domestic acetic acid feedstock, compressing logistics costs.
Market Restraints
- Magnesium Oxide Price Volatility:Feedstock costs fluctuate with Chinese environmental enforcement cycles that idlesmelling capacity unpredictably.
- Single-Source Concentration Risk:Buffalo, New York hosts the only large-scale North American manufacturing complex, creating geographic supply vulnerability.
- Calcium Magnesium Acetate Substitution:CMA commands entrenched specification in airport and bridge applications where corrosion resistance premiums justify higher unit costs.
Strategic Opportunities
- Nordic Municipal Expansion:Sweden and Finland maintain aggressive road salt reduction targets under national climate frameworks, opening specification windows for acetate alternatives.
- Pre-Wetting System Adoption:Liquid magnesium acetate formulations integrate with automated brine application infrastructure spreading across Canadian provincial highway departments.
- EU Green Deal Procurement Mandates:Public tender scoring increasingly weights biodegradability and aquatic toxicity metrics where acetate chemistry outperforms chloride salts.
Industry Challenges
- Food-Grade Certification Timelines:FSSAI and SAMR purity documentation requirements extend qualification cycles for pharmaceutical and additive applications by 12-18 months.
- Legacy Spreader Equipment Compatibility:Municipal fleets require retrofit investment to handle hygroscopic acetate granules without bridging and caking failures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnesium Acetate Market |
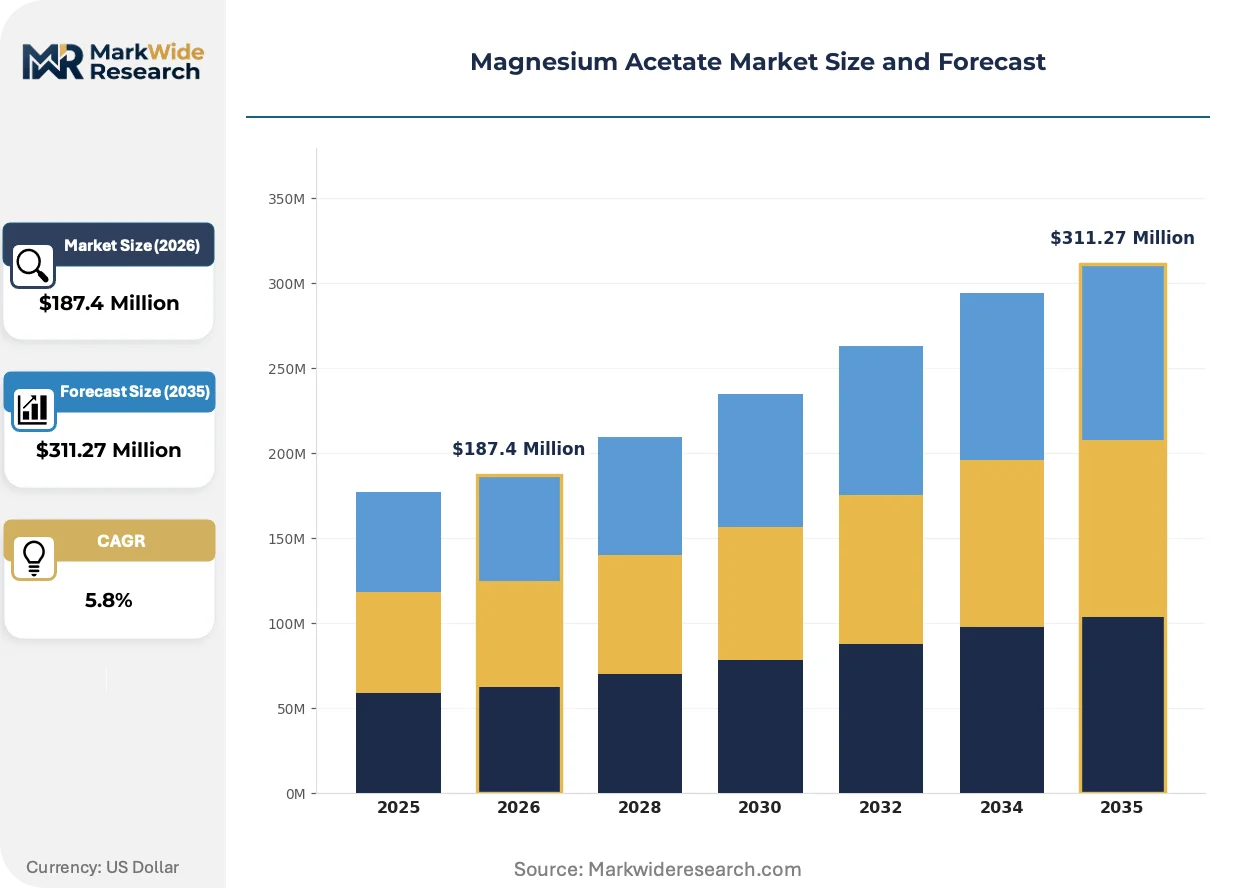
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Solution, Crystals Application: De-icing, Chemical Synthesis, Food Additive, Fertilizer End User: Construction, Agriculture, Pharmaceuticals, Food Industry Distribution Channel: Online, Offline, Wholesale, Retail |
| Companies Covered | Merck KGaA, Niacet Corporation, American Elements, VASA PharmaChem, Celtic Chemicals, Honeywell International Inc., Wuxi Yangshan Biochemical, Hefei TNJ Chemical Industry, Avantor, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnesium Acetate Market Strategic Shifts
Formulation science and regulatory compliance are converging to redefine product differentiation. Manufacturers now compete on environmental fate data and certification breadth rather than commodity pricing alone.
Liquid magnesium acetate brine systems are rendering obsolete dry salt spreader operations in high-traffic corridor maintenance. State transportation departments in Minnesota and Wisconsin have converted 40% of their winter fleets to pre-wetting infrastructure. The shift compresses salt application rates by 30% while improving pavement adhesion.
REACH Annex XV dossier updates are forcing reformulation toward lower-impurity magnesium acetate grades for European import eligibility. ECHA substance evaluation protocols now demand expanded aquatic toxicity testing. Specialty chemical distributors are consolidating supplier relationships to reduce compliance documentation duplication.
Municipal procurement departments now weight total cost of ownership models against upfront material pricing. Lifecycle corrosion damage to bridge infrastructure and vehicle undercarriages factors into bid scoring. This behavioral pivot favors acetate chemistry in coastal Massachusetts and Michigan jurisdictions where infrastructure replacement costs dominate budget planning.
Magnesium Acetate Market Segmentation
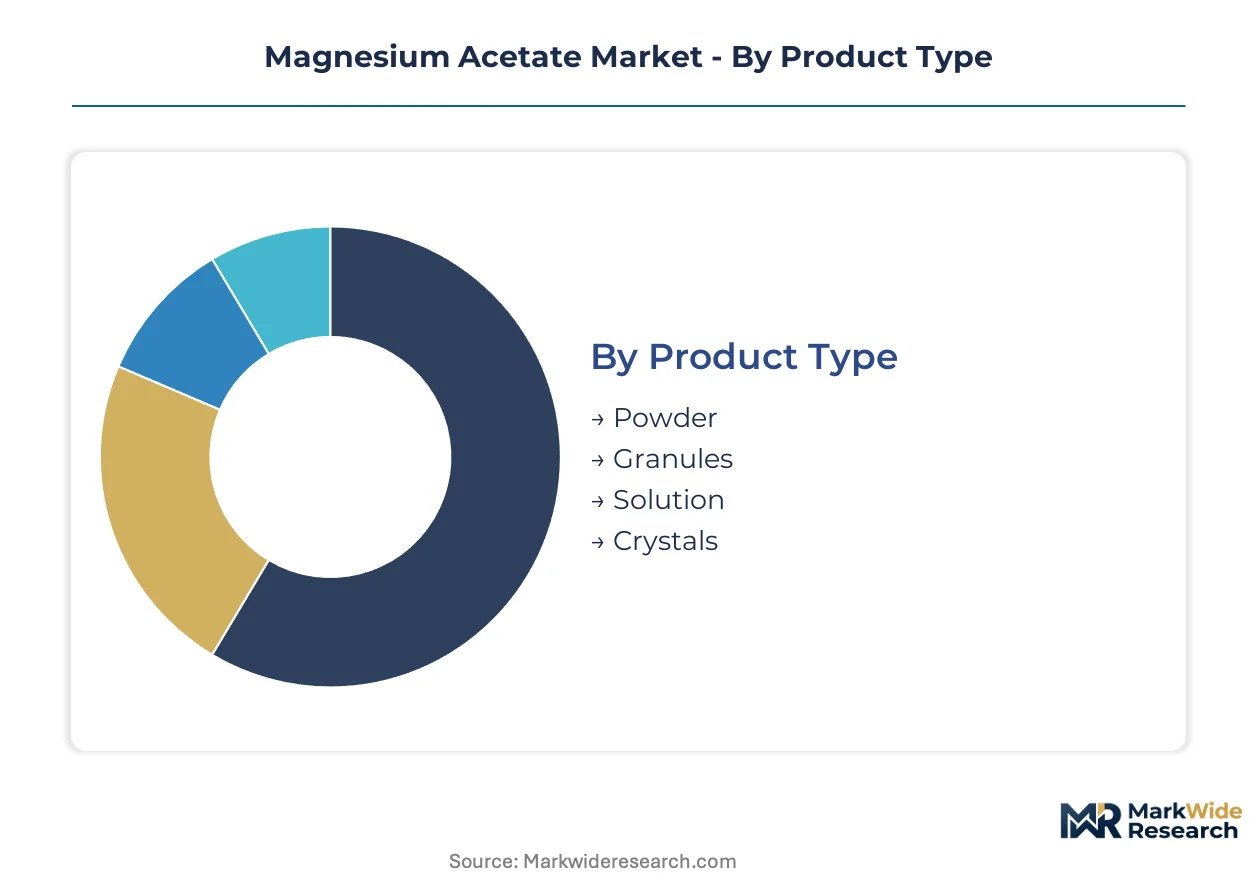
Magnesium acetate segmentation reflects divergent technical specifications across de-icing infrastructure, pharmaceutical purity thresholds, and food-grade certification requirements. Each product form and application channel carries distinct regulatory burdens and margin structures that reshape supplier economics.
Product Type:
After-sales service intensity varies sharply across physical forms, with liquid solution customers demanding on-site storage tank calibration and hygroscopic powder users requiring moisture-control troubleshooting.
- Powder:Fine particulate magnesium acetate with high surface area enables rapid dissolution in pre-wetting systems. Municipal highway departments in Minnesota and Wisconsin specify powder for automated spreader compatibility, though caking incidents during humid storage drive technical support call volume.
- Granules:Pelletized form resists bridging in pneumatic conveying equipment. Buffalo, New York production concentrates on this grade for North American municipal contracts where spreader retrofit costs deter powder adoption.
- Solution:Pre-blended liquid brine eliminates on-site mixing infrastructure. Canadian provincial highway authorities specify this form for direct-injection pre-wetting systems.
- Crystals:High-purity recrystallized grade serves pharmaceutical and laboratory applications requiring defined particle morphology.
Powder holds the largest share; momentum sits with Solution as liquid pre-wetting infrastructure expands across freeze-prone jurisdictions.
Application:
Application segmentation tracks divergent margin profiles, with de-icing commanding volume leadership while food and pharmaceutical certifications extract premium pricing.
- De-icing:Road and runway ice control consumes magnesium acetate as chloride alternatives face EPA discharge restrictions. Municipal procurement in Massachusetts and Michigan now weights lifecycle corrosion costs against upfront material pricing.
- Chemical Synthesis:Acetate salt serves as reagent and catalyst precursor in organic chemistry manufacturing. China's Shandong chemical corridor integrates this demand with regional acetic acid supply chains.
- Food Additive:Acidity regulator and firming agent applications require FSSAI and SAMR purity documentation extending qualification cycles.
- Fertilizer:Magnesium source for foliar feeding and soil amendment competes against sulfate and oxide alternatives on cost per unit nutrient.
De-icing anchors volume demand; food additive applications climb fastest as clean-label ingredient trends accelerate acetate salt substitution.
End User:
End user segmentation reveals customer concentration patterns, with construction and agriculture purchasing on commodity economics while pharmaceutical buyers enforce batch-level traceability.
- Construction:Infrastructure contractors specify magnesium acetate for concrete set retardation and winter placement conditions. Nordic municipal projects under national salt reduction targets drive specification shifts.
- Agriculture:Crop nutrition and livestock feed applications prioritize cost per magnesium unit over purity metrics.
- Pharmaceuticals:Excipient and active pharmaceutical ingredient applications demand USP-grade certification with full supply chain documentation.
- Food Industry:Processors of canned vegetables and tofu employ magnesium acetate as firming agent under FDA and EFSA additive approvals.
Construction generates the highest shipment volumes; pharmaceuticals capture the steepest margin expansion trajectory.
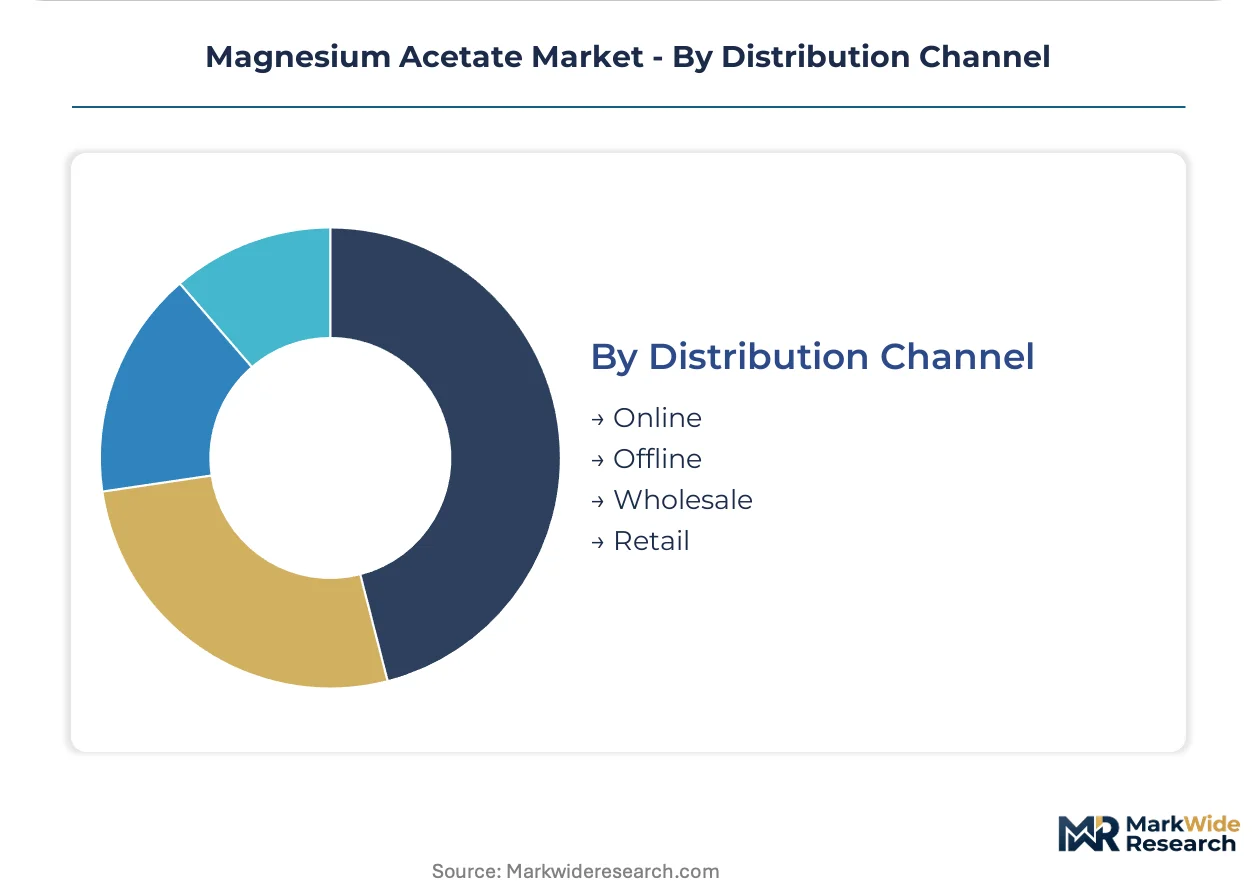
Distribution Channel:
Channel segmentation tracks procurement digitization gaps, with bulk municipal contracts resisting e-commerce migration while specialty chemical buyers adopt platform purchasing.
- Online:E-commerce platforms serve laboratory and small-scale industrial buyers requiring rapid fulfillment of certified grades.
- Offline:Direct sales relationships dominate municipal and pharmaceutical procurement through negotiated multi-year supply agreements.
- Wholesale:Distributors consolidate acetate salt shipments with complementary de-icing chemicals for regional contractor supply.
- Retail:Limited consumer packaged presence in hardware and agricultural supply stores for residential ice control.
Offline channels retain the largest share; online penetration expands fastest among research and specialty chemical purchasers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports magnesium acetate to North American and European buyers through integrated acetic acid supply chains in Shandong and Jiangsu provinces. This trade corridor shapes regional production economics and regulatory compliance requirements across destination markets.
United States
Municipal highway departments in Minnesota and Wisconsin deploy liquid magnesium acetate brine through automated pre-wetting infrastructure. EPA stormwater regulations enforce binding chloride discharge limits that accelerate acetate salt procurement. Buffalo, New York hosts the only large-scale domestic manufacturing complex, serving regional municipal contracts.
China
Chemical manufacturers in Shandong and Jiangsu chemical corridors integrate magnesium acetate production with captive acetic acid feedstock supply. SAMR administers national food safety standards governing purity thresholds for domestic consumption and export qualification. Yangshan Biochemical and TNJ Chemical Industry anchor supply from these coastal manufacturing clusters.
Germany
REACH registration obligations through ECHA enforce detailed toxicological documentation for acetate salt imports. Merck KGaA leverages pharmaceutical-grade production infrastructure to supply high-purity grades for medical and food applications. The country's chemical distribution network consolidates supplier relationships to reduce compliance documentation duplication.
Sweden
National road salt reduction targets under climate frameworks open specification windows for acetate alternatives in municipal winter maintenance. EU Green Deal procurement mandates weight biodegradability and aquatic toxicity metrics in public tender scoring. Nordic infrastructure contractors specify magnesium acetate for concrete set retardation in cold-weather placement conditions.
Canada
Provincial highway authorities specify liquid magnesium acetate formulations for direct-injection pre-wetting systems across Ontario and Quebec. Health Canada and PMRA administer environmental fate assessments for de-icing chemical approvals. The shift from dry salt spreader operations to liquid brine infrastructure compresses application rates while improving pavement adhesion.
Magnesium Acetate Market Competitive Environment
Channel-controlling players compete with product-specialist players across municipal procurement, pharmaceutical certification, and specialty material segments. The vendor base organizes around three strategic archetypes: integrated chemical conglomerates with multi-product portfolios, purity-focused specialists serving regulated end-uses, and regional manufacturers anchored to feedstock clusters. Dominant competitive moves include geographic expansion through distribution partnerships and portfolio diversification into adjacent acetate salts.
Among German-based chemical conglomerates, Merck KGaA exemplifies the pharmaceutical-grade specialist archetype through its high-purity production infrastructure. Niacet Corporation represents the North American regional anchor position, while American Elements occupies a position within the specialty material segment focused on customized particle-size offerings. These three companies illustrate the competitive tension between scale-driven certification breadth and niche formulation customization.
| Leading Market Players |
|---|
| Merck KGaA |
| Niacet Corporation |
| American Elements |
| VASA PharmaChem |
| Celtic Chemicals |
| Honeywell International Inc. |
| Wuxi Yangshan Biochemical |
| Hefei TNJ Chemical Industry |
| Avantor, Inc. |
| Others |
Value Chain & Pricing Dynamics
Single-source concentration in Buffalo, New York determines both pricing tier spreads and supply chain shape for North American buyers, as geographic vulnerability to weather disruptions and logistics constraints forces premium valuations on alternative sourcing options. EPA chloride runoff restrictions amplify this dynamic by limiting substitute availability, compressing buyer negotiating leverage against the sole domestic manufacturing anchor.
Pricing Analysis
Grade-certification pricing gaps separate pharmaceutical-grade USP specifications from technical-grade municipal de-icing supply, with food-grade FSSAI and SAMR documentation requirements commanding intermediate premiums. Three-tier pricing structure across pharmaceutical, food-grade, and technical levels reflects purity testing burdens and batch-level traceability investments. Pricing pressure stems from Chinese acetic acid feedstock volatility tied to environmental enforcement cycles that idle smelting capacity unpredictably. Municipal procurement departments exhibit highest price sensitivity through total cost of ownership models, while pharmaceutical buyers prioritize supply security over unit economics.
Supply Chain Analysis
Extended payment terms from Chinese exporters to European distributors characterize working capital arrangements, with supply-chain finance facilities emerging around Shandong and Jiangsu chemical corridor shipments. Production concentrates in China, Germany, and the United States, with acetic acid, magnesium oxide, and hydroxide feedstock dependencies creating input cost exposure. Single-source vulnerability at the Buffalo manufacturing complex presents structural risk for North American supply continuity. Distribution runs through specialty chemical distributors consolidating acetate salt shipments with complementary de-icing chemicals for regional contractor supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across certification-grade tiers as municipal procurement shifts toward lifecycle cost models that favor acetate chemistry over chloride alternatives, creating niche positioning windows for purity-specialist producers.
For Market Incumbents: Entrench specification control by securing REACH Annex XV dossier updates ahead of ECHA substance evaluation protocols, while expanding liquid brine formulation capacity to capture pre-wetting infrastructure conversion across Minnesota and Wisconsin transportation departments. Calcium magnesium acetate substitution threats in airport and bridge applications demand corrosion-performance data investments to defend municipal contract renewals. For New Entrants and Emerging Players: Build out Nordic municipal expansion targeting Sweden and Finland national road salt reduction targets, where EU Green Deal procurement mandates weight biodegradability metrics favoring acetate chemistry. Pre-wetting system adoption among Canadian provincial highway authorities represents the most penetrable geography. Go-to-market execution should anchor on direct technical service relationships for liquid storage tank calibration and hygroscopic handling troubleshooting. For Investors and Strategic Acquirers: The market sits at a formulation-shift phase that favors purity-focused specialists with existing toxicological documentation over commodity-scale producers. Long-term viability centers on regulatory compliance breadth rather than volume scale. Acquisition targets should demonstrate filed REACH dossiers and pharmaceutical-grade certification infrastructure. The signal to watch is ECHA substance evaluation protocol expansion to additional acetate salt derivatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acetic Acid Feedstock | Captive supply from Shandong chemical corridor producers compresses logistics costs and margin volatility. |
| Pharmaceutical-Grade Certification Investment | USP-grade infrastructure opens medical and food additive segments with steeper margin expansion trajectories. |
| Liquid Brine Capacity Expansion | Pre-wetting system adoption across Minnesota and Wisconsin state transportation departments drives specification shifts. |
| REACH Dossier Pre-Registration | ECHA toxicological documentation requirements favor established producers with existing substance evaluations. |
| Nordic Distribution Partnership | Sweden and Finland municipal procurement under national climate frameworks opens specification windows for acetate alternatives. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, ACC industry reports, SEC chemical company filings, and ECHA registration databases through structured interviews with plant managers at acetate salt production facilities, procurement leads at municipal highway departments, distribution channel partners in specialty chemicals, and technical R&D directors in de-icing formulation. Bottom-up volume triangulation from production facility outputs cross-validates against top-down demand estimation from municipal contract awards and pharmaceutical excipient procurement records.
Forecast inputs include grade-tier segmentation across pharmaceutical, food-grade, and technical specifications; end-use industry demand patterns spanning municipal de-icing, chemical synthesis, and food additive applications; and regional production hub capacity utilization across Shandong, Jiangsu, and Buffalo manufacturing clusters. CAGRs derive from regression analysis of historical price-volume relationships and elasticity modeling against acetic acid feedstock cost movements. Industry-specific inputs incorporate EPA stormwater regulation enforcement timelines and REACH registration obligation phase-in schedules.
Practitioners should monitor Chinese environmental enforcement cycles, ECHA substance evaluation protocol expansions, and municipal pre-wetting infrastructure conversion rates for early signals of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Potassium Fluoborate Market
Bulk Chemicals
Global Glycerol Monostearate (GMS) Powder Market
Bulk Chemicals
Thiodiglycol Market
Bulk Chemicals
Asia-Pacific Quicklime Market
Bulk Chemicals
Aluminum Potassium Sulfate Market
Bulk Chemicals
Global Naphthenic Base Oil Market
Bulk Chemicals
Barium Chloride Market
Bulk Chemicals
Aniline Market
Bulk Chemicals
Ethylene Dichloride Market
Bulk Chemicals
Ammonium Carbonate Market
Bulk Chemicals
Tin Fluoborate Market
Bulk Chemicals
North America Lime Market
Bulk Chemicals
Soda Ash Market
Bulk Chemicals
Cobalt Acetate Crystals Market
Bulk Chemicals
Sodium Gluconate Market
Bulk Chemicals
Bulk Liquid Containers Market